
 Resin Dispersion Market | 2026-2036
Resin Dispersion Market Size, Share, and Industry Trends Forecast 2026-2036
Resin Dispersion Market Analytics
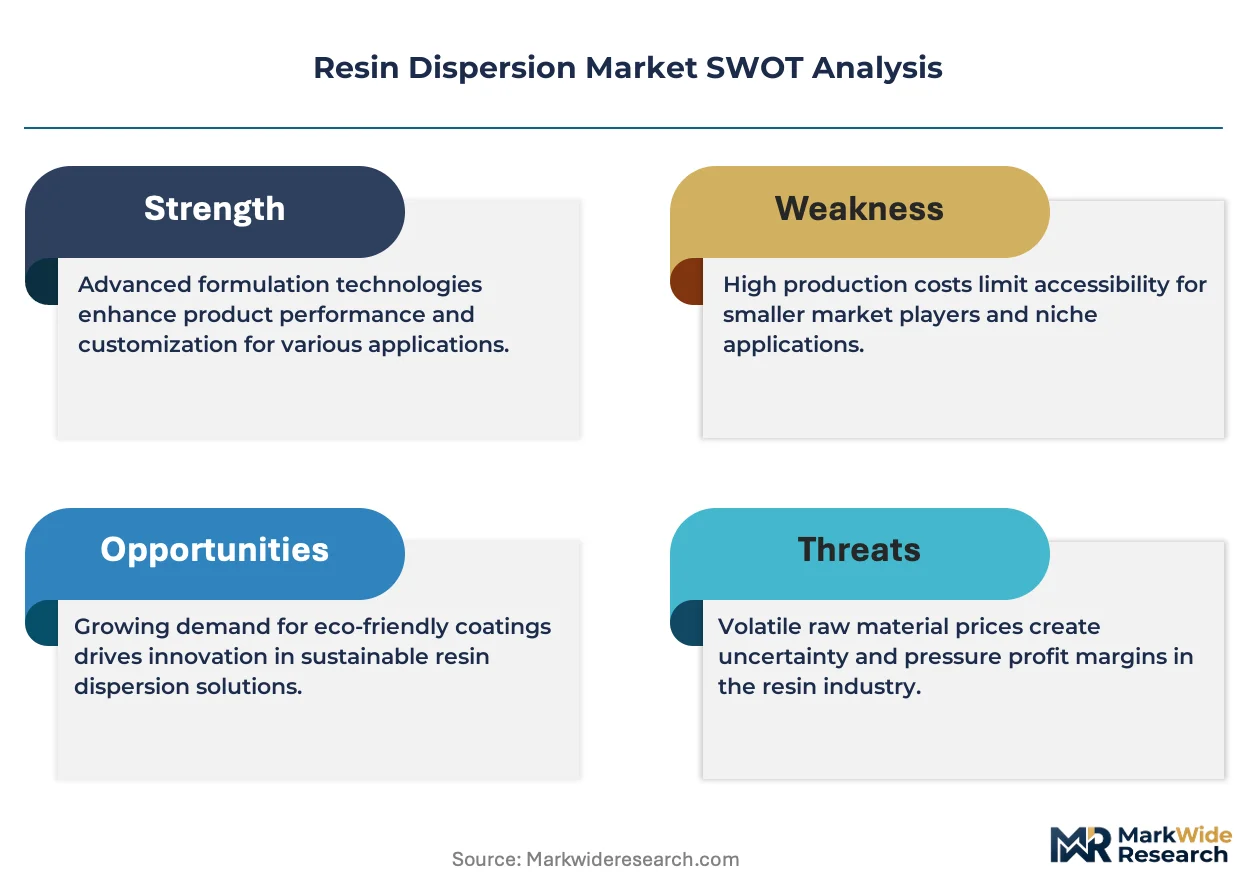
A widening capital-intensity divergence between integrated petrochemical giants and specialty chemical operators is unwinding competitive stability in resin dispersion supply. BASF SE leverages its Ludwigshafen Verbund site to sustain captive acrylic acid supply for dispersion back-integration. Dow Chemical Company anchors North American ethylene-based dispersion feedstock through its Gulf Coast infrastructure. Arkema competes via specialty polyamide dispersions for high-performance coatings in European automotive lines.
Resin dispersion denotes a colloidal system of polymer particles suspended in a continuous liquid phase, typically 40-60% solids content, manufactured through emulsion polymerization or mechanical dispersion processes to deliver film-forming binders for surface protection and adhesion. Aqueous dispersions lead volume owing to VOC compliance mandates, while UV-cure dispersions represent the fastest-expanding technology segment driven by energy-cured industrial coatings demand. Solvent-based dispersions retain margin pools in aerospace and marine applications where waterborne chemistry fails performance thresholds.
EPA emission standards and EU REACH chemical registration requirements shape product reformulation cycles, forcing dispersion producers to eliminate legacy solvents and disclose full substance toxicity profiles. FDA food-contact regulations and BIS certification in India further segment market access by application purity grade. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned R&D allocation across dispersion portfolios.
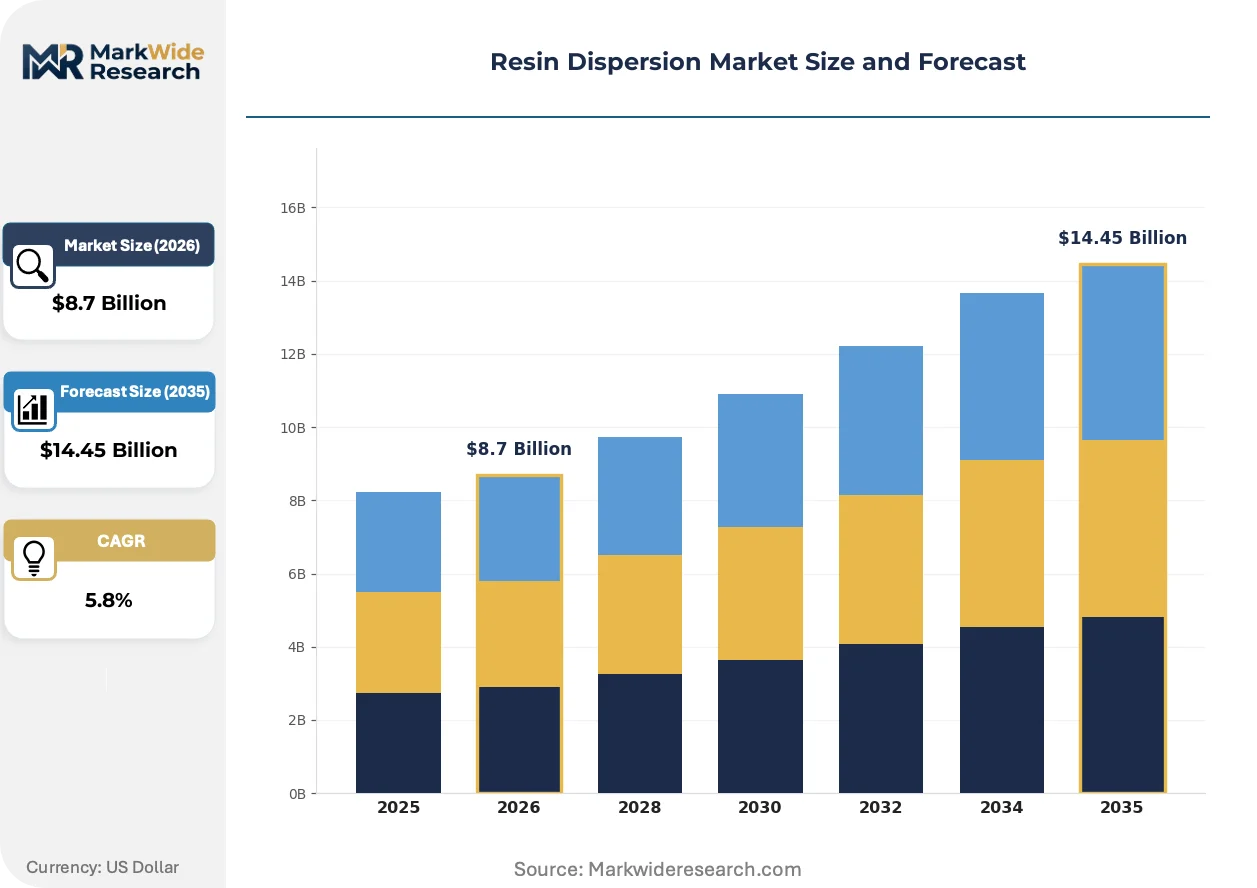
Market Dynamics
Aqueous dispersion chemistry is compressing solvent-based alternatives as EPA and EU REACH frameworks tighten VOC emission thresholds, forcing reformulation cycles across coatings, adhesives, and sealant portfolios.
Growth Catalysts
- EU REACH chemical registration:Mandatory disclosure of substance toxicity profiles accelerates phase-out of legacy solvent systems in European industrial coatings.
- Automotive OEM specification shifts:Waterborne basecoat and clearcoat mandates from German and Japanese vehicle manufacturers concentrate procurement of low-VOC dispersions.
- UV-cure dispersion technology:Energy-cured industrial coatings for wood and plastic substrates expand addressable applications beyond conventional thermal drying constraints.
Market Restraints
- Propylene and acrylic acid feedstock volatility:Petrochemical input cost swings compress margin stability for non-integrated dispersion compounders lacking captive monomer supply.
- Technical performance ceilings in marine coatings:Waterborne chemistry fails corrosion resistance and immersion durability thresholds required for ship hull and offshore platform applications.
- Substitution by powder coatings:Zero-VOC powder systems capture metal finishing segments where substrate geometry permits electrostatic application.
Strategic Opportunities
- India BIS certification pathways:Domestic purity-grade standards for food-contact and toy coatings create first-mover positioning for compliant aqueous dispersion suppliers.
- Bio-based dispersion feedstocks:Integration of renewable acrylic acid and vegetable-oil-derived polyols aligns with EU Green Deal carbon intensity benchmarks.
- Digital color-matching platforms:Cloud-based spectrophotometry and automated tinting systems displace traditional distributor technical service relationships in architectural coatings channels.
Industry Challenges
- Emulsion polymerization process control:Narrow particle size distribution requirements demand specialized chemical engineering talent scarce outside established production clusters.
- Multi-jurisdiction certification timelines:Sequential FDA, EPA, and EU EFSA food-contact approvals extend product launch cycles by 18-36 months.
- Legacy solvent system integration:Coatings manufacturers face capital-intensive line conversions and waste-handling infrastructure upgrades to accommodate aqueous dispersion rheology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resin Dispersion Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aqueous Dispersion, Solvent-based Dispersion, UV-cure Dispersion, High Solid Dispersion End Use Industry: Automotive, Coatings, Construction, Textiles Application: Adhesives, Paints, Inks, Sealants Technology: Dispersion Technologies, Nanodispersion, Emulsion Polymerization, Colloidal Dispersion |
| Companies Covered | BASF SE, Evonik Industries, Dow Chemical Company, Covestro AG, Huntsman, SABIC, Arkema, Royal DSM, Allnex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resin Dispersion Market Evolving Landscape
Hybrid cure mechanisms and bio-attributed feedstocks are fragmenting traditional technology categories, while regulatory stringency compresses reformulation windows from years to months.
Self-crosslinking acrylic dispersions are displacing two-component polyurethane systems in automotive refinish and industrial maintenance coatings. Tier-1 automotive suppliers in Germany and Japan specify these materials for repair network compliance with VOC limits. The technology is displacing isocyanate-based hardener supply chains and associated hazardous material handling infrastructure.
EU F-Gas Regulation phase-down mandates accelerate hydrofluoroolefin propellant substitution in aerosol-dispersed coatings, pressuring dispersion formulators to re-engineer sprayable viscosity and atomization profiles. Aerosol packagers in France and Italy face compressed transition timelines through 2030. The regulation forces disclosure of fluorinated gas content across supply tiers previously exempt from substance tracking.
Direct procurement from dispersion manufacturers is consolidating distributor influence in North American architectural coatings. Large painting contractors and property management groups negotiate volume agreements bypassing traditional regional distribution. The pattern concentrates most visibly in Texas and Florida metropolitan construction corridors where project scale permits tank-wagon delivery economics.
Resin Dispersion Market Segmentation
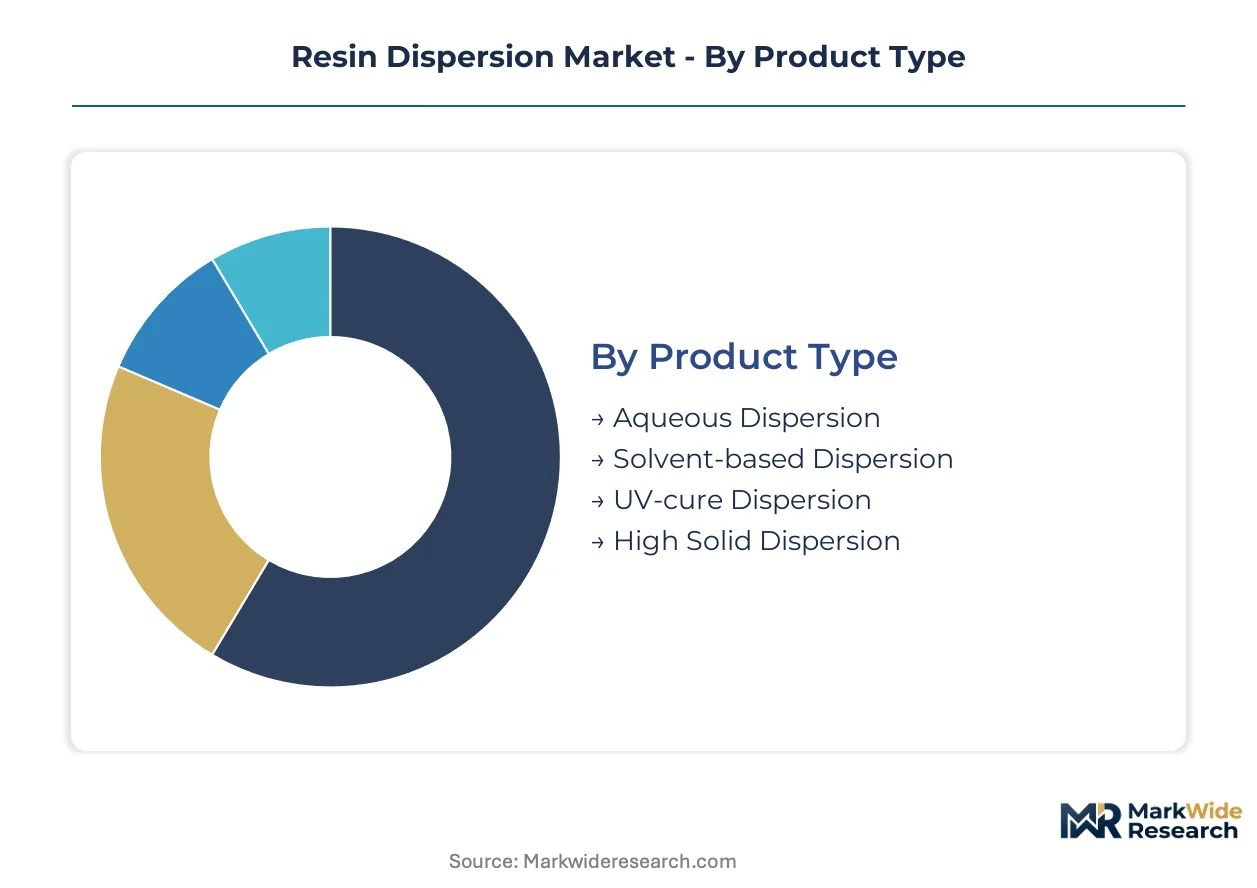
Segmentation in resin dispersions reveals how chemistry choices lock suppliers into distinct regulatory exposure and customer switching costs. Product type and end-use combinations determine which producers capture value from VOC compliance mandates versus performance-critical niches where solvent systems retain defensibility.
Product Type:
Substitution pressure from powder coatings and UV-cure alternatives is fragmenting volume concentration across chemistry platforms, with waterborne systems facing the most aggressive regulatory tailwinds.
- Aqueous Dispersion:Polymer particles suspended in water at 40-60% solids, stabilized by surfactant systems for film formation without organic co-solvents. Automotive OEMs in Germany specify these for basecoat and clearcoat applications under EU REACH VOC limits. EPA emission thresholds in the US are compressing solvent-based alternatives in industrial maintenance coatings.
- Solvent-based Dispersion:Polymer solutions in hydrocarbon or oxygenated solvents delivering superior substrate wetting and corrosion resistance. Marine coatings for ship hulls and offshore platforms in Norway and South Korea retain this chemistry where waterborne systems fail immersion durability standards.
- UV-cure Dispersion:Photoinitiator-functionalized oligomers curing via ultraviolet exposure, eliminating thermal drying energy costs. Energy-cured industrial wood and plastic coatings in Italy and Japan are expanding addressable applications beyond conventional drying constraints.
- High Solid Dispersion:Concentrated polymer systems at 65-80% solids reducing transport costs and application passes. Aerospace primers in France and California utilize these for weight-critical coating specifications.
Aqueous dispersion anchors the volume base while UV-cure dispersion gains share at the steepest rate.
End Use Industry:
Cost tier stratification separates specification-driven automotive procurement from price-sensitive construction applications, with coatings manufacturers serving multiple verticals facing conflicting margin pressures.
- Automotive:OEM and refinish coatings demanding exacting color match, weathering resistance, and repair network compliance. Waterborne basecoat mandates from German and Japanese vehicle manufacturers concentrate procurement of low-VOC dispersions in Stuttgart and Nagoya production corridors.
- Coatings:Architectural, industrial, and protective coatings representing the broadest application canvas. Direct procurement from dispersion manufacturers is consolidating distributor influence in Texas and Florida metropolitan construction markets.
- Construction:Adhesives, sealants, and waterproofing membranes for commercial and residential building envelopes. BIS certification requirements in India are creating first-mover positioning for compliant aqueous dispersion suppliers in food-contact and toy coating segments.
- Textiles:Fabric coatings and nonwoven binders requiring soft hand and wash durability. Technical textile producers in Belgium and North Carolina specify acrylic and polyurethane dispersions for automotive interior and medical applications.
Coatings commands the largest revenue pool while automotive delivers the highest specification premiums.
Application:
Application viscosity and film thickness requirements segment dispersion rheology design, with thin-film applications demanding tighter particle size control than bulk sealant formulations.
- Adhesives:Pressure-sensitive and structural bonding formulations requiring tack, creep resistance, and substrate compatibility. Packaging adhesive compounders in Wisconsin and Bavaria are reformulating around EU REACH substance restrictions on legacy tackifier systems.
- Paints:Decorative and protective film-forming systems spanning architectural, industrial, and automotive refinish end uses. Digital color-matching platforms in North America are displacing traditional distributor technical service relationships.
- Inks:Graphic arts and packaging print formulations demanding pigment wetting, gloss, and rub resistance. Flexographic ink producers in Illinois and Ontario are migrating to aqueous dispersions for food-contact compliance under FDA regulations.
- Sealants:Elongation and recovery-focused formulations for joint filling and weatherproofing. Construction sealant manufacturers in Florida and Queensland specify high-solid polyurethane dispersions for movement accommodation in high-humidity climates.
Paints generates the highest absolute volume while adhesives is climbing the fastest on packaging sustainability mandates.
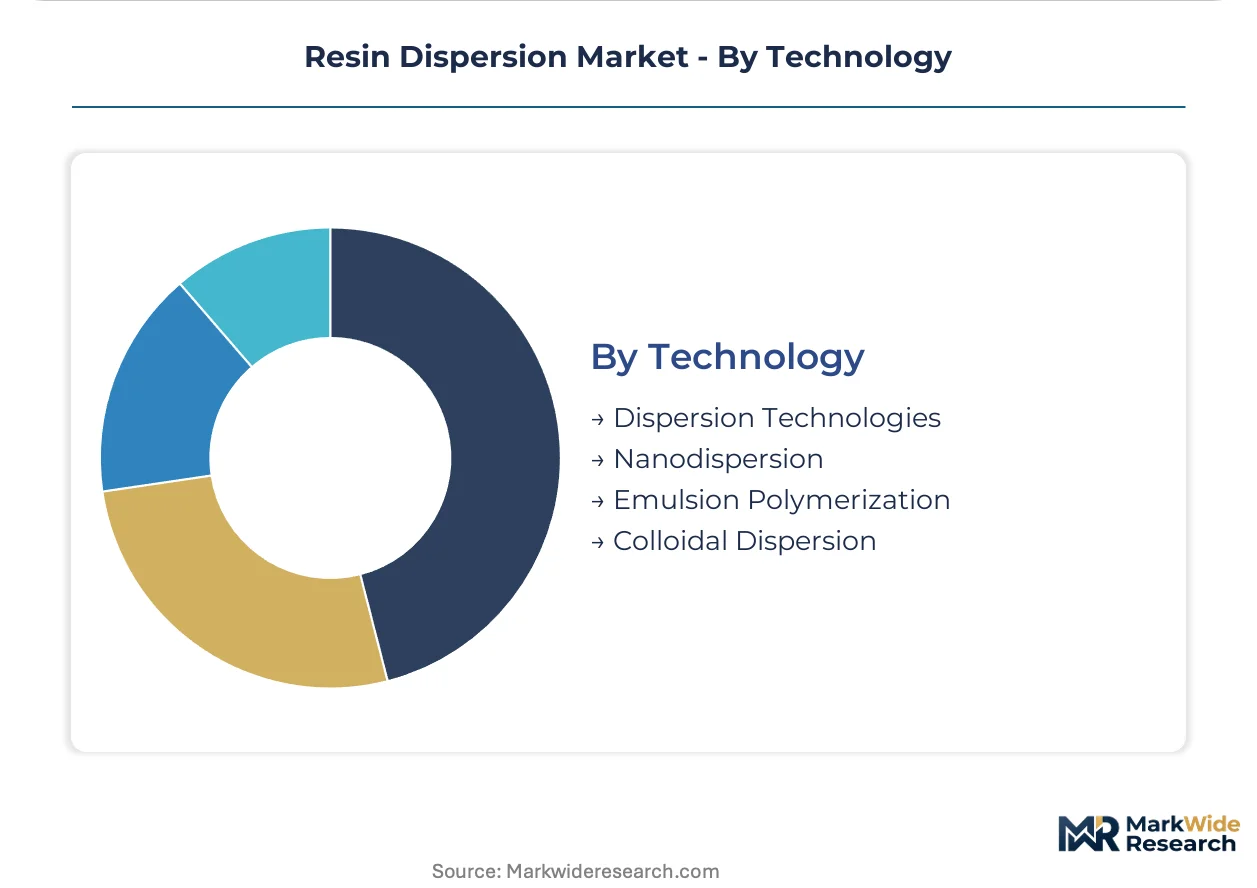
Technology:
Process maturity and capital intensity separate established emulsion polymerization capacity from emerging nanodispersion platforms requiring specialized engineering talent.
- Dispersion Technologies:Conventional mechanical and chemical dispersion methods for polymer particle stabilization. Standard production equipment dominates volume manufacturing in established chemical clusters.
- Nanodispersion:Sub-100 nanometer particle systems delivering optical clarity and enhanced mechanical properties. Optical coating applications in Japan and Switzerland are driving capacity investment for display and lens applications.
- Emulsion Polymerization:Free-radical polymerization in aqueous surfactant micelles producing controlled particle size distributions. BASF SE leverages Ludwigshafen Verbund integration for captive acrylic acid supply to this platform.
- Colloidal Dispersion:Electrostatically stabilized particle systems for specialty coating and electronic applications. Semiconductor CMP slurry producers in Taiwan and Arizona utilize these for wafer planarization.
Emulsion polymerization anchors installed capacity while nanodispersion is expanding most quickly on optical and electronic coating demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia exhibit acute price sensitivity on standard-grade aqueous dispersions, while German and Japanese automotive OEMs absorb specification premiums for low-VOC refinish systems without volume elasticity.
Germany
Automotive OEM waterborne basecoat mandates from Stuttgart manufacturers drive specification-grade dispersion procurement. EU REACH chemical registration requirements force full substance toxicity disclosure across supply tiers. The Ludwigshafen Verbund cluster anchors integrated acrylic acid production for captive dispersion back-integration.
United States
Industrial maintenance coatings reformulation accelerates as EPA emission thresholds compress solvent-based alternatives. FDA food-contact regulations segment market access by application purity grade. Texas and Florida metropolitan construction corridors concentrate direct procurement from dispersion manufacturers bypassing traditional distribution.
China
Packaging adhesive compounders migrate to aqueous systems for export compliance with EU and US food-contact standards. MIIT industrial standards and dual carbon goals pressure domestic producers toward low-emission chemistry platforms. The Yangtze River Delta cluster houses emulsion polymerization capacity serving electronics and automotive export manufacturing.
India
BIS certification requirements for food-contact and toy coatings create first-mover positioning for compliant aqueous dispersion suppliers. The PLI scheme for specialty chemicals incentivizes domestic manufacturing investment. Maharashtra and Gujarat industrial corridors concentrate construction adhesive and sealant formulation activity for infrastructure build-out.
Japan
Automotive refinish networks in Nagoya and Tokyo metropolitan areas specify self-crosslinking acrylic dispersions for VOC limit compliance. METI energy efficiency standards accelerate UV-cure dispersion adoption in industrial wood coatings. Kanto region technical textile producers specify polyurethane dispersions for automotive interior applications.
Resin Dispersion Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward integration into petrochemical feedstocks separating margin-stable compounders from price-takers on acrylic acid and propylene derivatives. The structure concentrates capacity in Ludwigshafen, Freeport, and Antwerp chemical clusters where Verbund economics and Gulf Coast ethylene infrastructure anchor supply security. Three archetypes populate the competitive map: integrated petrochemical giants with captive monomer supply, European specialty chemical operators with automotive specification relationships, and Asian regional compounders serving price-sensitive construction markets. Dominant competitive moves include capacity expansion in high-growth Asian markets and strategic partnerships for bio-based feedstock sourcing under EU Green Deal benchmarks.
Among integrated petrochemical operators, BASF SE and Dow Chemical Company exemplify the backward-integrated archetype with captive acrylic acid and ethylene-based feedstock control. Covestro AG occupies a position within the European specialty tier, representing the polyurethane dispersion specialists serving automotive OEM specification channels. These three anchors demonstrate how geographic clustering and feedstock integration separate margin-stable leaders from non-integrated compounders exposed to petrochemical input volatility.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries |
| Dow Chemical Company |
| Covestro AG |
| Huntsman |
| SABIC |
| Arkema |
| Royal DSM |
| Allnex |
| Others |
Value Network & Pricing Analysis
EU REACH chemical registration gates both supplier qualification and price differentiation simultaneously, forcing dispersion producers to absorb compliance costs that stratify procurement tiers across automotive OEMs and construction compounders. The Ludwigshafen Verbund cluster and Gulf Coast ethylene infrastructure anchor supply security, while non-integrated compounders face margin compression from petrochemical input volatility.
Pricing Analysis
After-sales technical service contracts and color-matching support drive lifetime value in specification-grade dispersions. Three-tier pricing structure across premium, standard, and economy levels separates automotive OEM-compliant grades from construction-grade volumes. Price differentiation rests on certification grade and captive monomer supply. Cost compression in standard-grade aqueous dispersions is intensifying because Indian and Southeast Asian buyers exhibit acute price sensitivity. Construction adhesive compounders in price-sensitive markets resist specification premiums, while German automotive OEMs absorb higher costs without volume elasticity.
Supply Chain Analysis
Germany, the United States, and China anchor acrylic acid and ethylene-based dispersion feedstock production. The supply chain draws from propylene derivatives, surfactant stabilizers, and photoinitiator chemicals. Single-source vulnerability concentrates in Ludwigshafen and Freeport chemical clusters where Verbund economics dominate. Distribution runs through direct procurement from integrated manufacturers to large coatings compounders, bypassing traditional regional distributors in Texas and Florida metropolitan construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized emulsion polymerization engineering talent sits outside established production clusters, creating a capability scarcity that constrains capacity expansion and fragments competitive positioning. This gap separates margin-stable integrated producers from non-integrated compounders exposed to feedstock volatility and technical talent shortages.
For Market Incumbents: Fortify captive acrylic acid supply through Ludwigshafen Verbund integration or Gulf Coast ethylene infrastructure to defend against propylene price volatility. Expand capacity in Maharashtra and Gujarat industrial corridors to capture PLI scheme incentives for specialty chemicals. Invest in BIS certification pathways for food-contact and toy coating segments to lock in first-mover positioning before domestic compounders scale compliance capabilities. For New Entrants and Emerging Players: Digital color-matching platforms represent a service-layer gap where incumbents under-serve painting contractors and property management groups in North American architectural coatings. Target direct procurement relationships in Texas and Florida metropolitan construction corridors where tank-wagon delivery economics displace distributor influence. Build cloud-based spectrophotometry capabilities to bypass traditional technical service relationships and capture specification-driven procurement. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down mandates through 2030 reshape the acquisition landscape by pressuring aerosol packagers to re-engineer sprayable viscosity profiles. Target European specialty chemical operators with automotive OEM specification relationships and polyurethane dispersion expertise. Watch hydrofluoroolefin propellant substitution timelines as the signal indicating which formulators will capture compressed transition demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | BASF SE leverages Ludwigshafen Verbund to neutralize propylene feedstock volatility. |
| Bio-based Feedstock Sourcing Partnership | Renewable acrylic acid integration aligns with EU Green Deal carbon intensity benchmarks. |
| India BIS Certification Investment | First-mover positioning captures food-contact and toy coating compliance requirements. |
| UV-cure Dispersion Capacity Expansion | Energy-cured industrial coatings demand accelerates beyond conventional thermal drying constraints. |
| Direct Procurement Channel Development | Tank-wagon delivery economics displace traditional distributors in Texas and Florida corridors. |
Research Methodology
Operator-level perspectives from dispersion plant managers, automotive OEM procurement leads, coatings compounder technical directors, and distribution channel partners anchored the qualitative base. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings for petrochemical feedstock disclosures. Bottom-up volume modeling and top-down value triangulation cross-checked segment assumptions across the analysis window.
Sensitivity analysis tested forecast robustness against propylene price volatility scenarios and regulatory acceleration pathways. The analytical framework modeled segmentation across chemistry platform, end-use industry, application viscosity, and regional production hub. CAGRs were derived from installed capacity utilization trends and OEM specification shift timelines. Forecast inputs incorporated EU REACH registration deadlines and EPA emission threshold compliance curves.
Forecasts assume regulatory continuity in EU REACH, EPA emission standards, and India BIS certification regimes; material policy shifts would require re-modeling substance disclosure timelines and food-contact approval pathways. Recalibration cycles align with material shifts in automotive OEM waterborne mandates, feedstock price volatility spikes, and aerosol propellant substitution deadlines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Blow Molding Resins Market
Polymers & Resins
Hydrophobic Interaction Chromatography Resins Market
Polymers & Resins
Bio-Based Polyvinyl Chloride Market
Polymers & Resins
Medical Polyoxymethylene (POM) Market
Polymers & Resins
North America Plastic Compounding Market
Polymers & Resins
Global Polyethylene (PE) Foam Market
Polymers & Resins
France Engineering Plastics Market
Polymers & Resins
Thermosetting Plastics Market
Polymers & Resins
Styrenic Block Copolymer (SBC) Market
Polymers & Resins
Molding and Trim Materials Market
Polymers & Resins
Conditioning Polymers Market
Polymers & Resins
Bio-Based Polypropylene Market
Polymers & Resins
North America Fluoropolymer Market
Polymers & Resins
Polypropylene Filler Sheet Market
Polymers & Resins
Canada Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Thermoplastic Polyolefin Market