
 Poland Third Party Logistics (3PL) Market | 2026-2036
Poland Third Party Logistics (3PL) Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Third Party Logistics (3PL) Market Analytics
Software-defined warehouse management is consolidating control over inventory visibility across Polish distribution networks. Kuehne + Nagel leverages its Baltic Sea corridor connections to anchor pharmaceutical cold chain operations from Gdańsk. DHL Supply Chain sustains automated fulfillment scale for e-commerce clients near Warsaw. Raben competes through its dense domestic road network covering secondary cities.
Third party logistics encompasses outsourced supply chain management where providers coordinate transportation, warehousing, and value-added services through integrated information systems, typically operating warehouse management platforms with real-time inventory tracking and route optimization algorithms. The service type dimension shows transportation and warehousing capturing established volume pools while freight forwarding margins tighten from fuel cost pass-through volatility. End user segmentation reveals e-commerce and pharmaceuticals as the fastest-expanding demand verticals, with automotive retaining stable contract tenure but slower growth.
Poland's national road transport regulator enforces EU Mobility Package driving-time rules and cabotage restrictions that elevate fleet compliance costs for 3PL operators. The Polish Centre for EU Transport Projects coordinates infrastructure funding that expands multimodal terminal capacity along the TEN-T corridors. Stakeholders must monitor how EU emissions trading system extension to road transport reshapes fleet investment decisions.
Market Dynamics
EU Mobility Package enforcement is compressing fleet utilization rates for Polish road carriers while simultaneously accelerating warehouse automation investments as labor substitution hedges. The regulatory shock is rewriting capital allocation priorities across the sector.
Growth Catalysts
- E-commerce fulfillment density:Parcel volumes through Polish distribution hubs are pulling automated sortation capacity into secondary cities. Warehouse operators are expanding footprint to capture last-mile consolidation economies.
- EU Green Deal fleet mandates:Alternative fuel infrastructure subsidies are lowering electric truck total-cost-of-ownership thresholds. Carriers with early battery-electric deployments are securing preferential shipper contracts.
- REACH compliance outsourcing:Chemical manufacturers are transferring hazardous materials handling liability to certified 3PL operators. Specialized storage certification is creating service differentiation.
Market Restraints
- Driver wage compression:EU Mobility Package rest-period rules are reducing effective driving hours per shift. Fleet operators face fixed cost absorption without proportional rate recovery mechanisms.
- Warehousing land scarcity:Industrial zoned plots around Warsaw and Łódź are concentrating in speculative hands. Greenfield development timelines are extending beyond 18 months.
- Rail gauge incompatibility:Polish broad-gauge connections to CIS markets require transshipment at border terminals. Intermodal cost advantages dissipate on eastbound corridors.
Strategic Opportunities
- Pharmaceutical cold chain expansion:Temperature-controlled GDP certification gaps exist in the Podkarpackie region. Operators with validated warehouse infrastructure can capture generic drug distribution contracts.
- CSRD reporting services:Scope 3 emissions disclosure mandates are creating demand for supply chain carbon accounting. 3PL providers with integrated telematics can bundle visibility-as-a-service.
- Cross-dock automation:Robotics-as-a-service models are lowering barrier-to-entry for mid-market freight consolidators. Polish manufacturing exporters represent underpenetrated demand.
Industry Challenges
- WMS integration complexity:Shipper ERP systems require custom API development for real-time inventory synchronization. Project timelines are extending due to middleware scarcity.
- ADR certification bottlenecks:Dangerous goods safety adviser training capacity is constrained. Fleet expansion into chemical logistics faces 6-month compliance delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Third Party Logistics (3PL) Market |
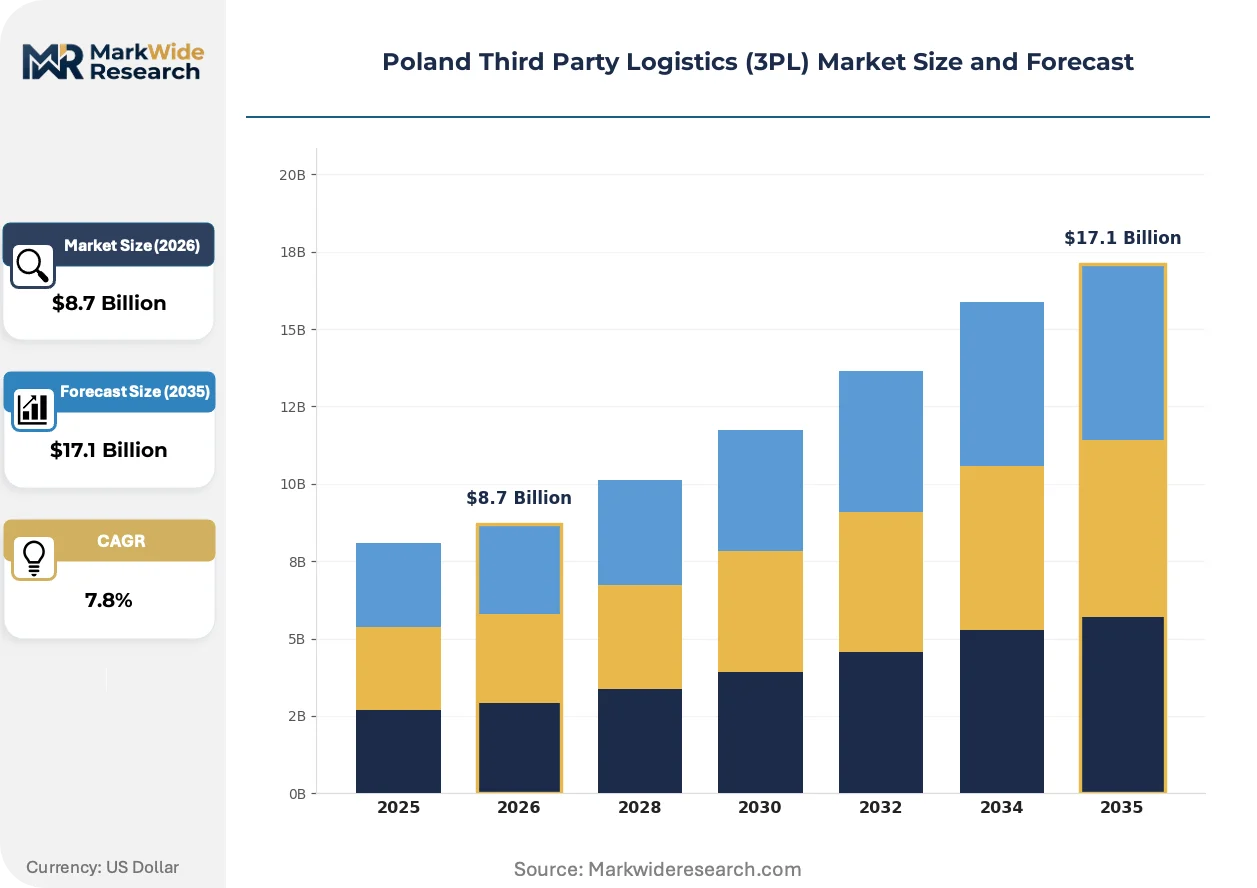
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Custom Brokerage End User: E-commerce, Retail, Automotive, Pharmaceuticals Technology: Automated Solutions, IoT Integration, Cloud Computing, Data Analytics Delivery Mode: Road, Rail, Air, Sea |
| Companies Covered | Kuehne + Nagel, Ekol Logistics, CEVA Logistics, ID Logistics, Geodis, DHL Supply Chain, Raben, Omnipack, DSV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Third Party Logistics (3PL) Market Evolving Landscape
Digital freight matching platforms are compressing spot market transaction friction while warehouse robotics are extending operating hours. The convergence is redrawing competitive boundaries between asset-heavy and technology-native operators.
Autonomous mobile robots (AMRs) with vision-guided navigation are rewriting fulfillment labor economics in Polish e-commerce warehouses. Retailers with seasonal demand volatility are deploying AMR fleets on 36-month operating leases rather than capital purchases. The technology is compressing break-even thresholds for mid-scale distribution centers.
EU Mobility Package cabotage restrictions are fragmenting cross-border fleet deployment strategies. Polish carriers are re-registering subsidiaries in neighboring member states to preserve route flexibility. The regulation is elevating compliance overhead for operators dependent on irregular route networks.
Shippers are unbundling transportation management from warehousing contracts to optimize rate benchmarking frequency. Automotive manufacturers near Katowice are splitting 3PL relationships between dedicated fleet operators and multi-user warehouse providers. The procurement model is visible across Silesian manufacturing clusters seeking cost transparency.
Poland Third Party Logistics (3PL) Market Segmentation
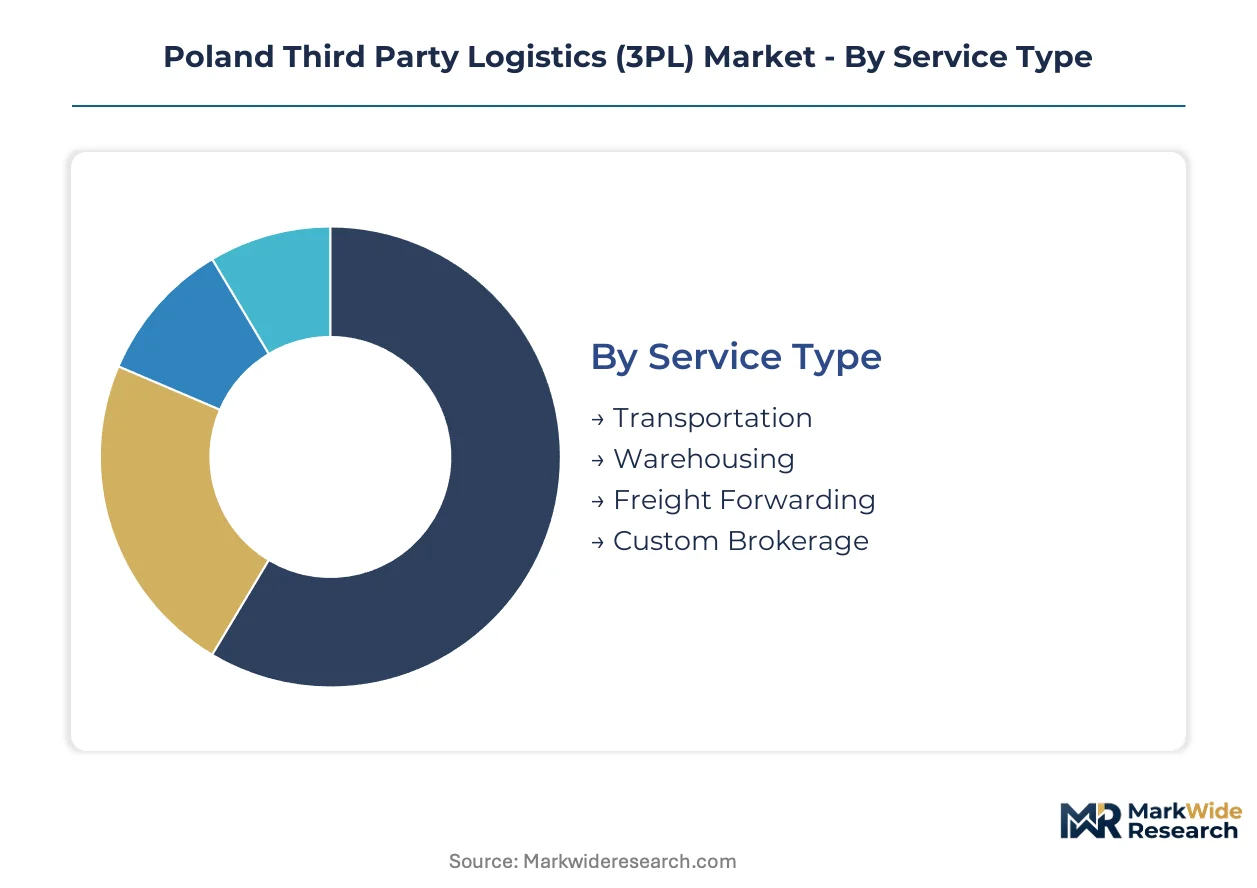
Service configuration in Poland's 3PL sector determines capital deployment cycles and contract tenure structures. Segment boundaries are blurring as integrated providers bundle transportation with warehouse management platforms to lock in multi-year agreements.
Service Type:
Warehouse automation and fleet electrification are driving divergent capital intensity profiles across service lines, with cold storage infrastructure commanding the highest upfront investment per square meter.
- Transportation:Road freight dominates contract volumes, with EU Mobility Package compliance costs accelerating fleet renewal cycles. Silesian automotive manufacturers are consolidating dedicated fleet contracts to secure capacity through the TEN-T corridors.
- Warehousing:Automated storage and retrieval systems require substantial capital commitment, particularly for temperature-controlled GDP-certified facilities. E-commerce fulfillment centers near Warsaw are absorbing speculative industrial land at premium rates.
- Freight Forwarding:Margin pressure from fuel volatility and spot market fragmentation is compressing brokerage economics. Polish exporters to CIS markets rely on forwarders to navigate gauge breaks at Brest-Małaszewicze.
- Custom Brokerage:Post-Brexit customs complexity and EU import control system upgrades are elevating compliance advisory demand. Electronics manufacturers near Poznań are outsourcing documentation to specialized brokers.
Most installed capacity flows through Warehousing. Expansion is steepest in Transportation as fleet electrification mandates reshape procurement.
End User:
Contract structures vary sharply by vertical, with automotive demanding dedicated asset commitments while e-commerce tolerates multi-user facility sharing.
- E-commerce:Seasonal demand volatility is driving flexible warehousing contracts with robotics-as-a-service clauses. Parcel volumes through Łódź distribution hubs are pulling automated sortation into secondary cities.
- Automotive:Just-in-sequence delivery requirements lock providers into long-term dedicated fleet and warehouse investments. Katowice-area manufacturers are splitting contracts between transport specialists and warehouse operators for cost transparency.
- Retail:Omnichannel fulfillment is collapsing traditional wholesale and direct-to-consumer logistics boundaries. Grocery chains are deploying micro-fulfillment centers in Warsaw suburbs.
- Pharmaceuticals:GDP temperature validation and serialization tracking impose certification overhead that filters out mid-tier competitors. Generic drug distributors are seeking validated cold chain capacity in Podkarpackie.
Automotive commands the longest contract tenures. E-commerce is gaining share fastest as marketplace sellers outsource fulfillment infrastructure.
Technology:
Technology adoption curves separate asset-heavy incumbents from platform-native competitors, with integration costs determining deployment speed.
- Automated Solutions:Autonomous mobile robots with vision-guided navigation are compressing fulfillment labor economics in e-commerce warehouses. Retailers are deploying AMR fleets on operating leases rather than capital purchases.
- IoT Integration:Telematics-enabled fleet monitoring supports EU Mobility Package driving-time compliance while generating carbon accounting data for CSRD disclosures. Carriers with integrated sensor networks are bundling visibility-as-a-service.
- Cloud Computing:Warehouse management system migration to SaaS models is reducing IT infrastructure capital for mid-market operators. API standardization remains uneven across shipper ERP environments.
- Data Analytics:Predictive demand forecasting is optimizing inventory positioning for seasonal retail clients. Route optimization algorithms are reducing empty kilometers for road carriers.
Cloud Computing carries the lowest barrier to entry. Automated Solutions show the steepest expansion trajectory as labor substitution economics improve.
Delivery Mode:
Modal choice reflects cargo value density and time sensitivity, with infrastructure gaps forcing transshipment on eastbound corridors.
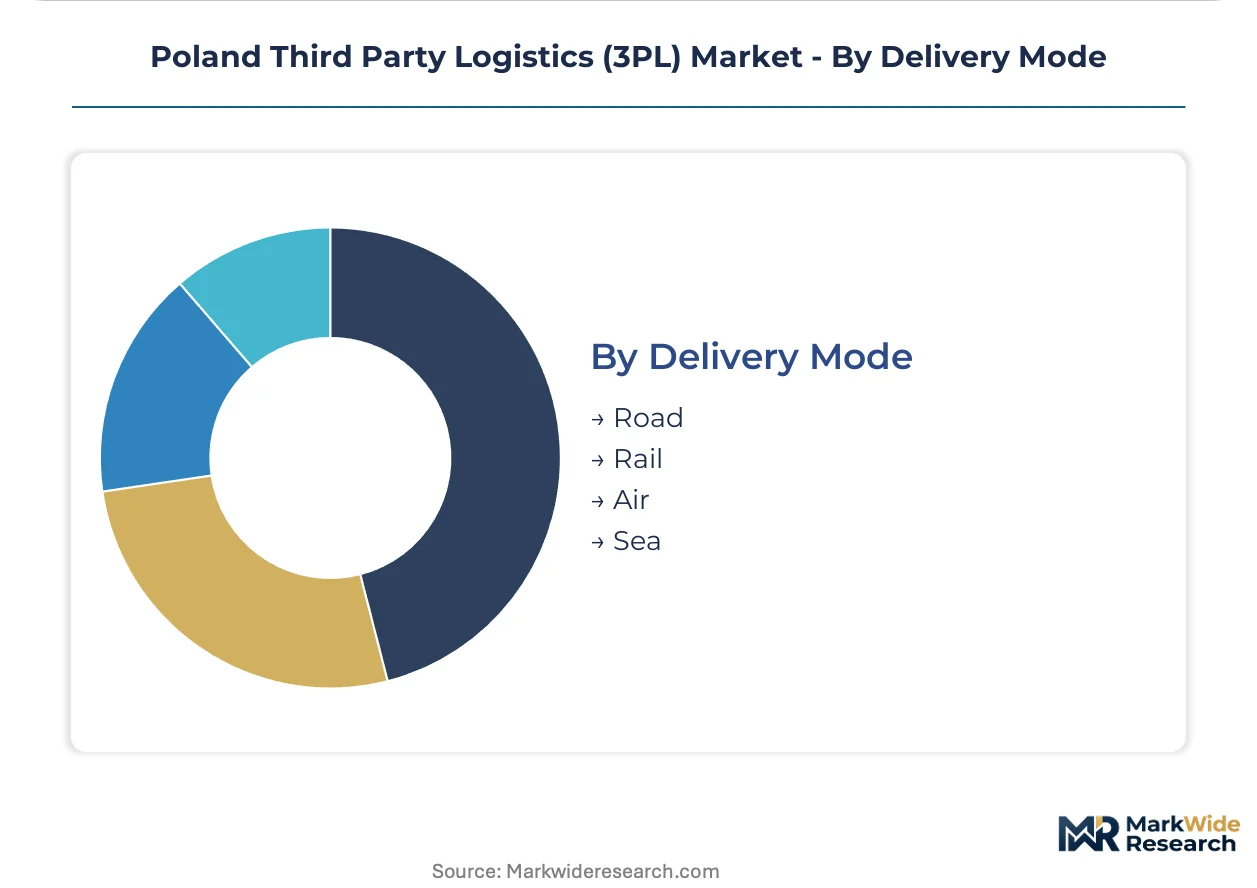
- Road:EU Mobility Package driving-time rules and cabotage restrictions are fragmenting cross-border fleet deployment. Polish carriers are re-registering subsidiaries in neighboring member states to preserve route flexibility.
- Rail:Broad-gauge connections to CIS markets require transshipment at Małaszewicze, dissipating intermodal cost advantages on eastbound routes. TEN-T corridor investments are expanding multimodal terminal capacity.
- Air:Pharmaceutical cold chain and high-value electronics shipments concentrate at Warsaw Chopin cargo terminals. Express operators are securing dedicated freighter capacity for e-commerce peak seasons.
- Sea:Baltic Sea feeder services through Gdańsk and Gdynia anchor pharmaceutical cold chain operations for Nordic markets. Container terminal automation is reducing vessel turnaround times.
Road retains dominant volume share. Rail is climbing the fastest as EU Green Deal subsidies lower electric locomotive operating costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's logistics density exceeds Poland's by a factor of three, yet Polish warehouse rents remain 40 percent lower than Frankfurt or Hamburg corridors, drawing cross-border fulfillment investment from DACH-region retailers.
Silesian Voivodeship
Automotive just-in-sequence delivery contracts from Katowice-area manufacturers anchor dedicated fleet investments. The Polish Centre for EU Transport Projects coordinates TEN-T corridor funding that expands multimodal terminal capacity. Gliwice and Zabrze industrial zones concentrate contract logistics facilities serving German OEM supply chains.
Greater Poland Voivodeship
Electronics manufacturing clusters near Poznań generate high-velocity warehousing demand for component sequencing. REACH compliance outsourcing from chemical processors elevates certified hazardous materials handling requirements. Konin and Kalisz secondary cities attract automated fulfillment footprint as Warsaw land scarcity intensifies.
Masovian Voivodeship
E-commerce parcel volumes through Warsaw distribution hubs pull automated sortation into suburban corridors. EU Mobility Package driving-time rules compress fleet utilization rates for road carriers headquartered in the capital region. Radom and Płock satellite cities absorb overflow warehousing demand from core Warsaw industrial zones.
Pomeranian Voivodeship
Pharmaceutical cold chain operations concentrate at Gdańsk port terminals serving Nordic markets. The EU Green Deal fleet mandates accelerate electric truck deployment along Baltic Sea feeder routes. Gdynia container terminal automation reduces vessel turnaround times for intra-European shipping loops.
Łódź Voivodeship
Central geographic positioning supports national distribution hub strategies for omnichannel retailers. Rail gauge incompatibility at Brest-Małaszewicze dissipates intermodal cost advantages on eastbound CIS corridors. Pabianice and Stryków logistics parks capture last-mile consolidation economies from e-commerce marketplace sellers.
Poland Third Party Logistics (3PL) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated global operators commanding automotive and pharmaceutical verticals while domestic road carriers retain fragmented e-commerce last-mile contracts. The market structures around three tiers: asset-heavy multinationals with Baltic Sea corridor dominance, mid-scale Polish operators with dense secondary-city road networks, and technology-native entrants deploying robotics-as-a-service models. Strategic moves concentrate on warehouse automation partnerships and fleet electrification pre-commitments to secure EU Green Deal subsidy capture.
Among integrated global providers, Kuehne + Nagel and DHL Supply Chain exemplify the asset-heavy archetype with established pharmaceutical cold chain infrastructure, while Raben represents the domestic density model through its Polish road network coverage. These three anchors illustrate how capital deployment cycles diverge between multinational platform investments and regional fleet specialization.
| Leading Market Players |
|---|
| Kuehne + Nagel |
| Ekol Logistics |
| CEVA Logistics |
| ID Logistics |
| Geodis |
| DHL Supply Chain |
| Raben |
| Omnipack |
| DSV |
| Others |
Value Network & Pricing Analysis
Warehouse automation investments across Polish logistics corridors are compressing labor cost structures while concentrating operational scale in fewer facilities. This capital shift simultaneously elevates fixed cost absorption requirements and rewards operators with speculative land positions near Warsaw and Łódź.
Pricing Analysis
Capacity additions in Greater Poland and Silesian voivodeships are reshaping price floors for automated warehousing contracts. Three-tier pricing structure across GDP-certified cold storage, standard automated facilities, and conventional ambient warehousing reflects certification investment differentials. Cost compression in ambient warehousing intensifies because speculative land acquisition has compressed development timelines. E-commerce marketplace sellers exhibit highest price sensitivity, while pharmaceutical manufacturers accept premium tiers for validated cold chain assurance.
Supply Chain Analysis
Regional distribution centers around Warsaw, Łódź, and Katowice anchor hub-and-spoke patterns radiating toward secondary cities and cross-border corridors. Germany, the Netherlands, and the Czech Republic feed capital equipment and fleet technology into Polish operations. Polish 3PL providers draw from EU Green Deal subsidy programs, Baltic Sea port infrastructure, and TEN-T corridor investments. Single-source vulnerability concentrates in electric truck battery supply chains. Distribution runs through multimodal terminals at Małaszewicze and Gdańsk port complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Poland's 3PL sector rests on warehouse automation economics displacing labor-intensive fulfillment models. Fleet electrification pre-commitments unlock EU Green Deal subsidies that lower total cost of ownership thresholds.
For Market Incumbents: Extend automation partnerships with robotics-as-a-service providers to deflect capital intensity from balance sheets. Consolidate speculative land positions near Warsaw before greenfield development timelines extend beyond viable contract windows. Technology-native entrants with AMR deployment capabilities threaten mid-scale operators lacking integration expertise. For New Entrants and Emerging Players: The price-point gap between premium GDP-certified cold storage and economy-tier ambient warehousing offers entry latitude for mid-market consolidators. Podkarpackie region pharmaceutical cold chain capacity represents the most penetrable vertical. Target cross-dock automation for Polish manufacturing exporters using robotics-as-a-service financing structures. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic road carriers with dense secondary-city networks but limited warehouse automation exposure. Long-term viability hinges on EU Mobility Package compliance cost absorption and fleet electrification timing. Watch EU emissions trading system extension to road transport as the inflection signal for accelerated fleet replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Warehouse Automation Partnership | AMR operating leases reduce capital barriers for mid-scale Polish distributors. |
| Fleet Electrification Pre-commitment | Early battery-electric deployments secure EU Green Deal subsidy capture. |
| Speculative Land Acquisition | Industrial zoned plots near Warsaw command scarcity premiums as development timelines extend. |
| GDP Certification Investment | Validated cold chain infrastructure filters competitors from generic drug distribution. |
| Cross-Border Subsidiary Registration | EU Mobility Package cabotage restrictions elevate compliance overhead for single-entity operators. |
Research Methodology
Direct dialogue with fleet operations directors, warehouse automation engineers, pharmaceutical supply chain managers, and customs brokerage specialists grounded qualitative assessment. Secondary validation drew from EU Mobility Package regulatory filings, Polish Centre for EU Transport Projects infrastructure disclosures, TEN-T corridor investment databases, and Baltic Sea port authority statistics. Bottom-up service segment sizing and top-down macroeconomic triangulation converged on volume and value estimates.
Segment-level projections across service type, end user vertical, technology adoption tier, and delivery mode dimensions were generated through the analytical framework. CAGRs were derived from regression analysis against EU Green Deal implementation timelines and e-commerce parcel volume trajectories. Fleet electrification cost curves and warehouse automation penetration rates served as primary forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for autonomous mobile robot deployment would alter the outlook. Forecasts reflect documented assumptions regarding EU Mobility Package enforcement intensity and subsidy program continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Italy Cold Chain Logistics Market
Logistics and Shipping
Shipping Container Market
Logistics and Shipping
Inland Container Depot and Dry Port Market
Logistics and Shipping
Event Logistics Market
Logistics and Shipping
Smart Shipping Containers Market
Logistics and Shipping
North America Refrigerated Container Shipping Market
Logistics and Shipping
Malaysia Road Freight Transport Market
Logistics and Shipping
GCC Air Freight and Logistics Market
Logistics and Shipping
Germany Freight and Logistics Market
Logistics and Shipping
Qatar Third-Party Logistics (3PL) Market
Logistics and Shipping
United States FTL Freight Brokerage Market
Logistics and Shipping
Oman Third-Party Logistics (3PL) Market
Logistics and Shipping
Europe Chemical Logistics Market
Logistics and Shipping
GCC Air Freight Transport Market
Logistics and Shipping
United Arab Emirates (UAE) Third-Party Logistics (3PL) Market
Logistics and Shipping
Europe Full Container Load (FCL) Market