
 GCC Air Freight and Logistics Market | 2026-2036
GCC Air Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Air Freight and Logistics Market Insights
The GCC air freight and logistics sector is restructuring around a sharp divergence between premium temperature-controlled pharma corridors and commoditized general cargo lanes. Emirates SkyCargo leverages its Dubai hub infrastructure to dominate perishable and pharmaceutical verticals. Aramex competes through last-mile density across secondary Gulf cities. Agility anchors its position via integrated warehousing and customs brokerage networks spanning Kuwait, Saudi Arabia, and the UAE.
Air freight and logistics encompasses the coordinated movement of goods via aircraft, supported by ground handling, customs facilitation, and multimodal interconnectivity, with critical performance parameters including transit-time reliability, payload optimization, and cold-chain integrity for temperature-sensitive commodities. Express delivery commands premium pricing through time-definite guarantees, while standard freight occupies volume-driven lanes with thinner margins. Pharmaceutical end users generate the fastest-growing demand segment as Gulf health authorities tighten Good Distribution Practice compliance. Warehouse management systems and automated sorting technologies concentrate investment as operators seek throughput gains amid labor scarcity.
GACA in Saudi Arabia, the UAE's General Civil Aviation Authority (GCAA), and Qatar's Civil Aviation Authority collectively enforce safety, security, and environmental standards that shape fleet modernization and facility certification requirements across the region. These regulators mandate phased adoption of advance cargo information systems and screening protocols that raise operational barriers for non-compliant operators. Stakeholders must monitor evolving national aviation strategies as each Gulf state pursues hub differentiation rather than coordinated capacity planning.
Market Dynamics
Pharmaceutical cold-chain compliance mandates from GACA, GCAA, and Qatar's Civil Aviation Authority are forcing capital redeployment toward temperature-certified infrastructure across Gulf hubs. This regulatory pressure concentrates investment in automated warehouse systems and real-time cargo monitoring.
Growth Catalysts
- SFDA Pharmaceutical Distribution Rules:Saudi Arabia's tightened Good Distribution Practice requirements are pulling specialized cold-chain infrastructure investment into Riyadh and Jeddah cargo zones.
- Biologics Manufacturing Clustering:Gulf health authorities are licensing advanced therapy production facilities that require time-definite temperature-controlled logistics.
- Blockchain-Enabled Documentation:Dubai's customs authority is piloting distributed ledger systems that compress cargo clearance cycles at Al Maktoum International Airport.
Market Restraints
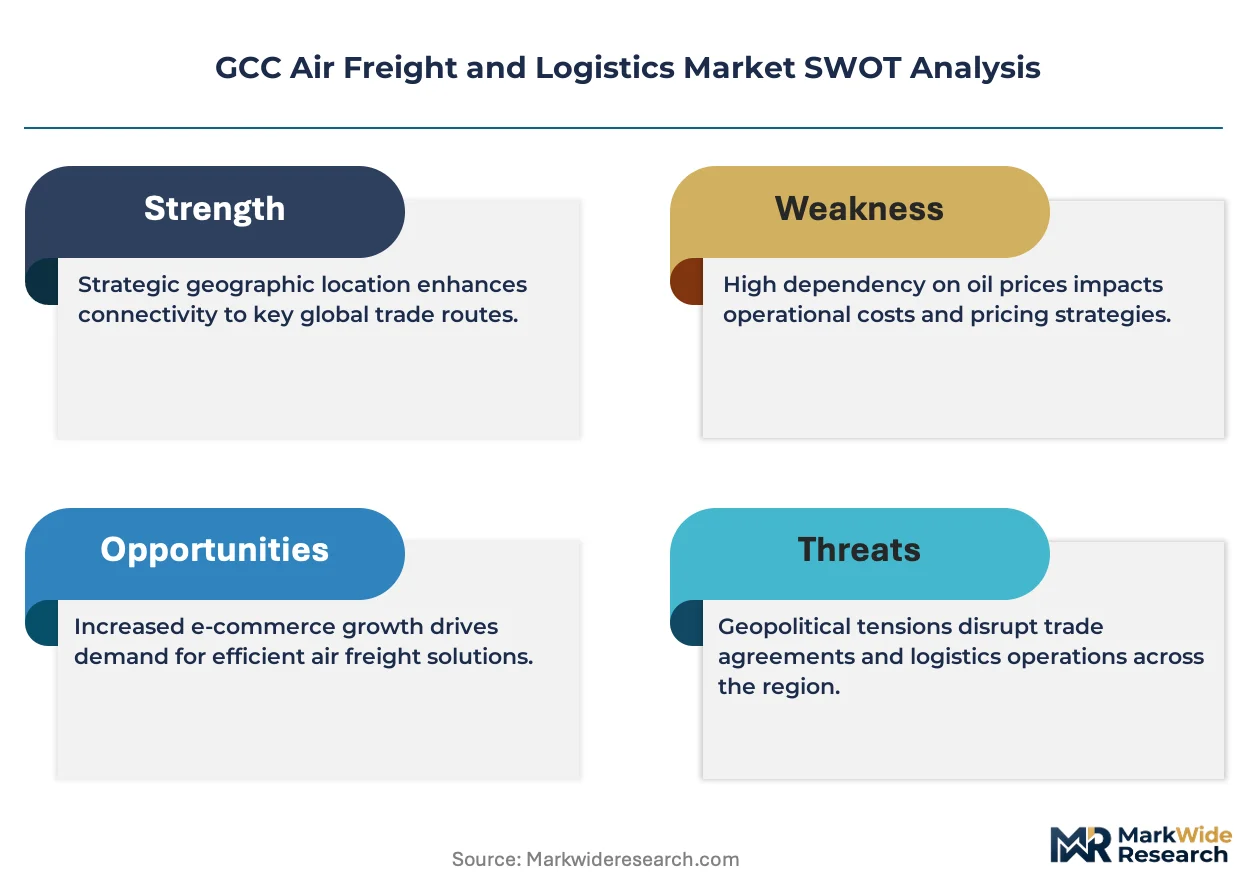
- Aviation Fuel Cost Volatility:Jet fuel price swings compress margins on standard freight lanes where fuel surcharges cannot be fully passed through to price-sensitive shippers.
- Ground Handling Concentration:Dubai and Doha together control the majority of certified cool-dock capacity, creating chokepoint risk for temperature-sensitive cargo.
- Dual-Use Screening Requirements:Advance cargo information mandates from Gulf aviation authorities extend processing timelines for non-compliant operators.
Strategic Opportunities
- Oman Salalah Free Zone:Underdeveloped transshipment infrastructure offers first-mover positioning for operators establishing East Africa-Gulf-Asia triangular routing.
- Cell and Gene Therapy Logistics:Cryogenic chain requirements for CAR-T therapies represent a premium service tier with limited incumbent specialization.
- Kuwait Customs Modernization:Planned single-window clearance systems will reduce dwell times for cross-border e-commerce parcels entering the northern Gulf.
Industry Challenges
- Certified Workforce Scarcity:IATA CEIV Pharma and Fresh accreditation programs face insufficient candidate pipelines across Saudi Arabia and the UAE.
- Legacy Warehouse Management Integration:Automated sortation systems require costly retrofitting of existing bonded facilities in secondary Gulf cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Air Freight and Logistics Market |
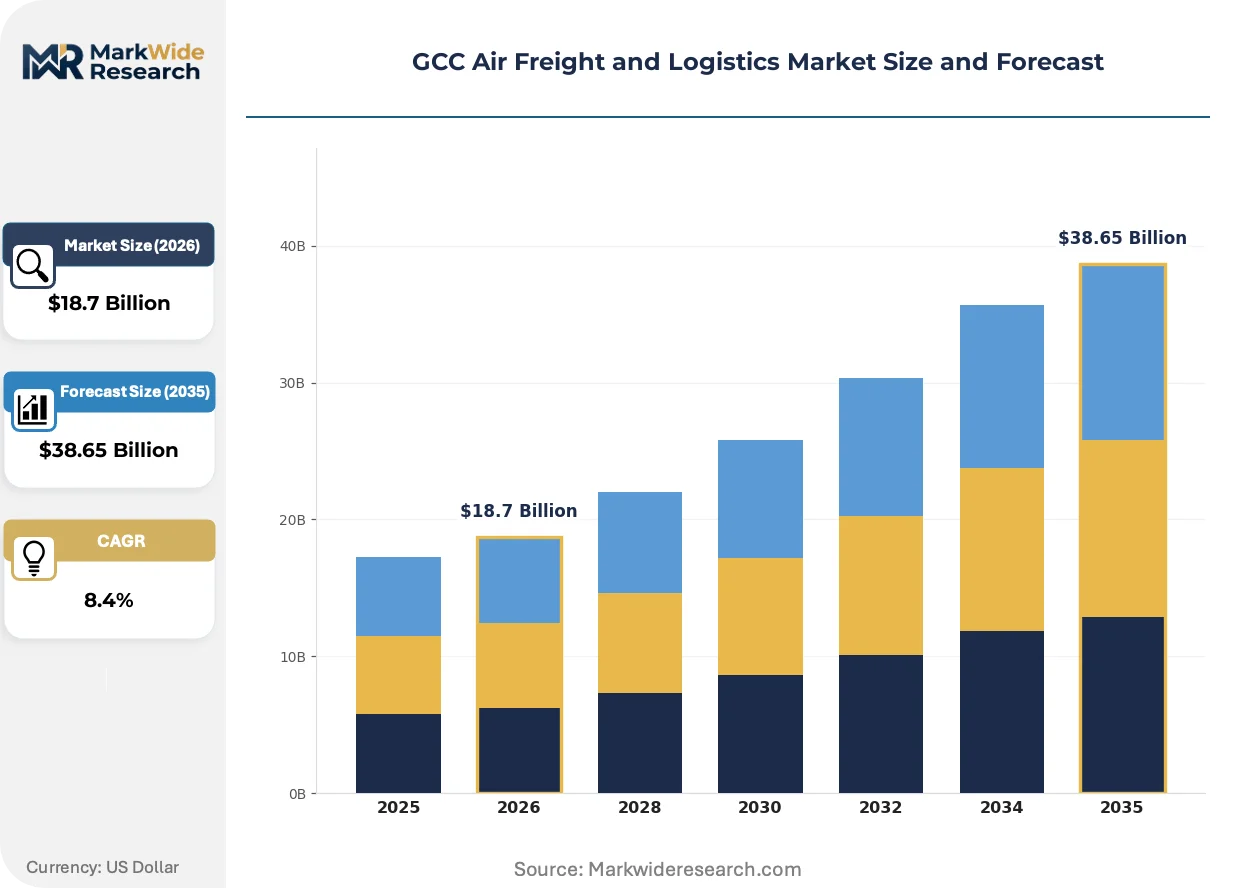
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express Delivery, Standard Freight, Charter Services, Cargo Handling End User: Aerospace, Pharmaceuticals, Retail, Automotive Technology: Warehouse Management Systems, Tracking Solutions, Automated Sorting, RFID Cargo Type: Perishable Goods, Electronics, Industrial Equipment, Live Animals |
| Companies Covered | Emirates SkyCargo, Qatar Airways Cargo, Saudia Cargo, Etihad Cargo, Jazeera Airways Cargo, DHL, FedEx, Aramex, Agility, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Air Freight and Logistics Market Trends and Innovations
Digital cargo ecosystems and autonomous ground handling equipment are compressing traditional operational timelines across Gulf aviation hubs. Operators are racing to deploy connected infrastructure before regulatory mandates harden compliance deadlines.
Autonomous guided vehicles in cargo terminals are automating pallet movement between aircraft stands and cool storage facilities. Emirates SkyCargo and ground handlers at Dubai South are deploying these systems to reduce tarmac exposure for temperature-sensitive shipments. The technology is automating labor-intensive material handling steps that previously created bottlenecks during peak pharmaceutical export windows.
GACA's phased advance cargo information requirements are mandating pre-departure data submission for all freight entering Saudi airspace. Carriers must integrate screening protocols with Saudi customs systems or face load rejection at origin stations. Pharmaceutical exporters are responding by front-loading documentation preparation and contracting dedicated compliance staff.
E-commerce shippers are consolidating purchase orders into scheduled block space agreements rather than spot-buying capacity. This procurement compression favors integrated logistics providers with guaranteed lift contracts across Emirates, Qatar Airways, and Saudia cargo divisions. The shift is most visible in UAE-based fashion and electronics verticals serving Saudi consumer markets.
GCC Air Freight and Logistics Market Segmentation
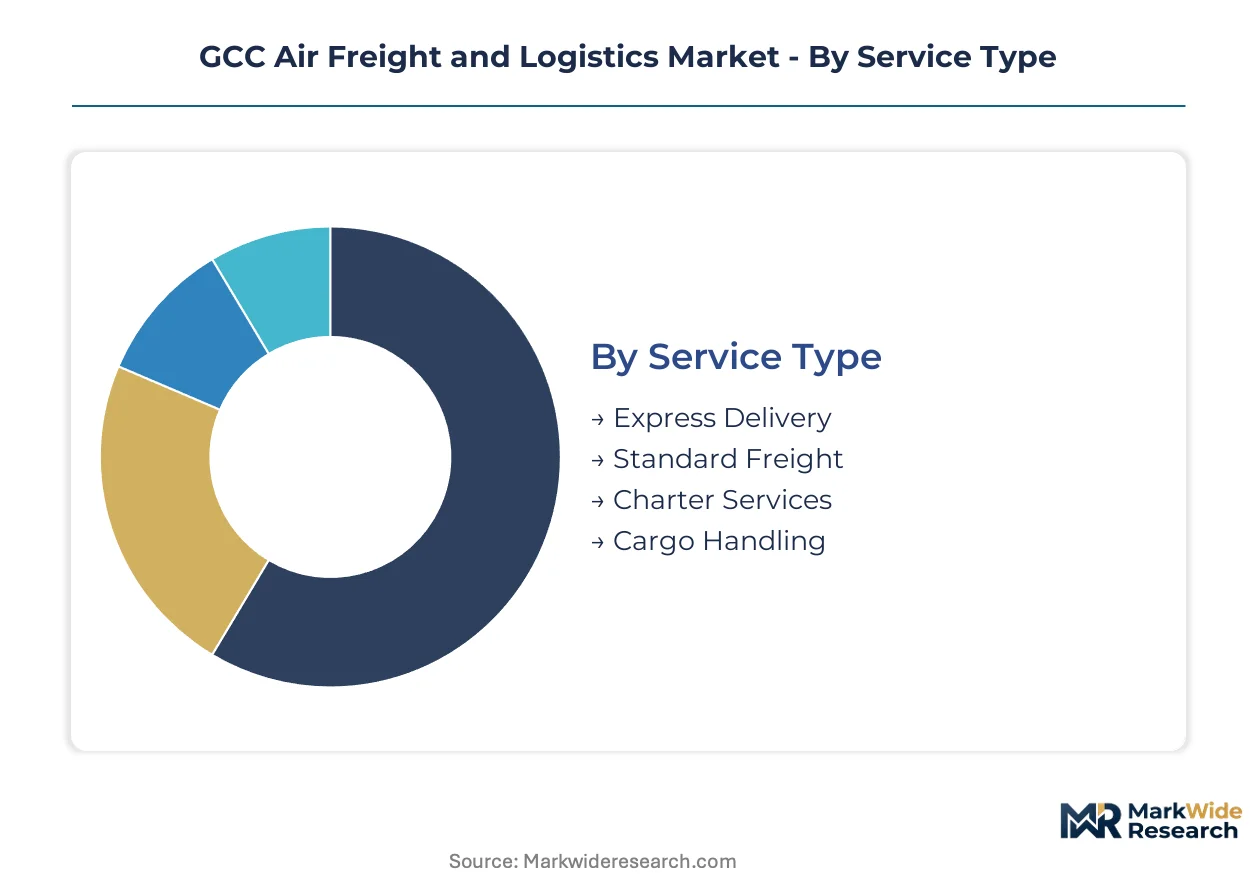
Segmentation in GCC air freight reveals how regulatory certification requirements fragment service tiers. Operators must align capital deployment with the specific compliance burdens each segment carries across Saudi, Emirati, and Qatari jurisdictions.
Service Type:
Certification intensity varies sharply across service tiers, with temperature-controlled express corridors requiring CEIV Pharma accreditation from IATA while standard freight operates under baseline aviation security protocols.
- Express Delivery:Time-definite guarantees with dedicated aircraft capacity and bonded last-mile networks. Pharmaceutical exporters in Dubai's Jebel Ali Free Zone contract these services for Saudi SFDA-regulated cold-chain distribution.
- Standard Freight:Consolidated belly-hold capacity on scheduled passenger routes. Thin margins here concentrate volume around Dubai and Doha hubs where ground handling scale offsets fuel cost volatility.
- Charter Services:Project cargo and emergency response lift. Oilfield equipment movements from Kuwait to Saudi Arabia's Eastern Province dominate this tier.
- Cargo Handling:Ground-based sorting, build-up, and break-down operations. GACA mandates advance cargo information integration for handlers operating in Riyadh and Jeddah airports.
Leading the category by volume: Standard Freight. Growing fastest: Express Delivery.
End User:
Application-specific logistics requirements determine which Gulf hubs capture demand, with pharmaceutical corridors commanding premium infrastructure investment.
- Aerospace:Just-in-time component delivery for MRO facilities. Dubai's proximity to Emirates Engineering drives AOG parts consolidation.
- Pharmaceuticals:Temperature-validated lanes with continuous monitoring. Saudi SFDA and UAE MOHAP enforce GDP compliance that restricts qualified providers.
- Retail:Seasonal surge capacity for fashion and electronics. E-commerce platforms in Riyadh and Jeddah pull dedicated charter capacity during peak windows.
- Automotive:Knock-down kit movements and finished vehicle logistics. Jebel Ali serves as consolidation point for GCC distribution.
Pharmaceuticals commands the steepest infrastructure investment. Retail generates the highest shipment frequency.
Technology:
Capital deployment into digital infrastructure separates integrated operators from commodity handlers across the Gulf.
- Warehouse Management Systems:Real-time inventory orchestration across bonded facilities. Agility and Aramex deploy these systems to manage multi-country customs compliance.
- Tracking Solutions:GPS and sensor-based shipment visibility. Pharmaceutical lanes require temperature-logging integration with airline cargo systems.
- Automated Sorting:High-speed parcel handling with OCR address recognition. Dubai South's Al Maktoum cargo terminal deploys this for e-commerce throughput.
- RFID:Contactless cargo identification for security screening. GACA mandates phased adoption for Saudi import cargo.
Warehouse Management Systems anchor the largest installed base. Automated Sorting claims the fastest replacement cycle.
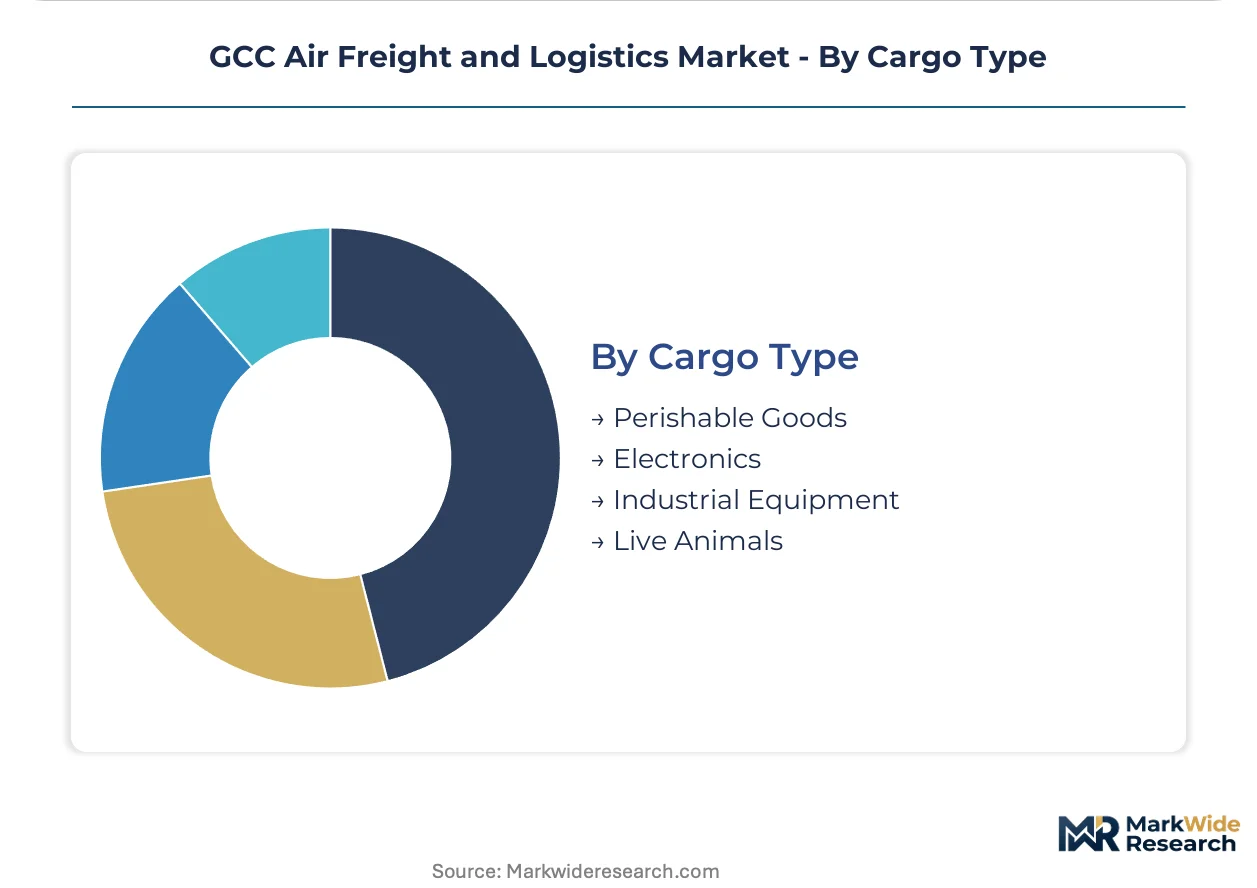
Cargo Type:
Physical handling requirements dictate facility specialization, with temperature-sensitive categories driving certified cool-dock construction.
- Perishable Goods:Fresh produce and floral products requiring 2-8°C or 15-25°C chains. Emirates SkyCargo dominates via Dubai's perishable handling center.
- Electronics:High-value consumer devices with security-sensitive handling. Saudi retail demand pulls these shipments through Riyadh's cargo terminals.
- Industrial Equipment:Project cargo and oilfield machinery. Kuwait and Qatar serve as origination points for Saudi Arabia's construction sector.
- Live Animals:Equine and breeding stock movements with veterinary certification. Doha and Dubai host dedicated animal handling facilities.
Perishable Goods leads in certified infrastructure allocation. Electronics generates the highest revenue per kilogram.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai anchors Gulf air freight capacity through Al Maktoum International Airport's phased expansion, while Saudi Arabia's GACA mandates are redrawing regulatory compliance boundaries across the peninsula.
United Arab Emirates
Pharmaceutical cold-chain exports and e-commerce fulfillment drive volume through Dubai South's cargo terminals. MOHAP enforces GDP compliance that restricts qualified logistics providers. Jebel Ali Free Zone concentrates bonded warehousing investment from integrated operators seeking Saudi market access.
Saudi Arabia
Domestic retail expansion and biologics manufacturing clustering pull specialized freight infrastructure toward Riyadh and Jeddah. GACA's advance cargo information mandates require pre-departure data submission for all inbound freight. King Abdulaziz International Airport's cargo zone is absorbing temperature-certified warehouse construction.
Qatar
Perishable re-exports and equine logistics sustain niche premium corridors through Hamad International Airport. Qatar's Civil Aviation Authority mandates phased screening protocol upgrades that raise handler certification requirements. Doha's dedicated animal handling facilities support breeding stock movements across the Gulf.
Kuwait
Oilfield equipment project cargo and cross-border e-commerce parcels generate mixed freight demand through Kuwait International Airport. Planned single-window customs clearance systems will reduce dwell times for northern Gulf distribution. Agility's integrated warehousing network anchors bonded capacity near the airport perimeter.
Oman
Underdeveloped transshipment infrastructure offers positioning for East Africa-Gulf-Asia triangular routing. Salalah Free Zone's port-airport corridor remains below capacity relative to Dubai and Doha hubs. Muscat International Airport's cargo terminal is attracting regional operators seeking alternative chokepoint bypass.
GCC Air Freight and Logistics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification intensity, with CEIV Pharma-accredited operators commanding rate premiums over standard freight handlers. The market structures around hub-controlled ground handling scale rather than dispersed point-to-point networks. Three archetypes dominate: integrated flag carriers with captive freighter fleets, global express networks with last-mile density, and regional logistics platforms with customs brokerage integration. Competitive moves concentrate on cool-dock capacity expansion and blockchain-enabled documentation partnerships with Gulf aviation authorities.
Within the flag carrier tier, Emirates SkyCargo and Qatar Airways Cargo exemplify hub-and-spoke models built around Dubai and Doha infrastructure concentration. Aramex occupies a position among regional platforms combining express delivery density with customs brokerage networks across secondary Gulf cities. These three anchors illustrate how certification barriers and facility scale separate premium service tiers from commodity freight handlers competing on thin margins.
| Leading Market Players |
|---|
| Emirates SkyCargo |
| Qatar Airways Cargo |
| Saudia Cargo |
| Etihad Cargo |
| Jazeera Airways Cargo |
| DHL |
| FedEx |
| Aramex |
| Agility |
| Others |
Pricing and Supply Chain Analysis
IATA CEIV Pharma-certified workforce concentration across the UAE and Saudi Arabia widens labor-cost differentials between premium temperature-controlled corridors and commoditized general cargo lanes. Pricing-tier spreads reflect this certification scarcity, with compliant operators capturing rate premiums while non-certified handlers compete on thinner margins in standard freight segments.
Pricing Analysis
Throughput guarantees anchor value-based pricing for pharmaceutical express services, with Emirates SkyCargo and Qatar Airways Cargo commanding premiums tied to temperature-validated delivery windows. Three-tier pricing structure across CEIV-accredited premium, standard GDP-compliant, and baseline security tiers separates qualified cold-chain providers from commodity handlers. Cost compression in standard belly-hold freight is intensifying because fuel surcharge pass-through remains incomplete on price-sensitive retail lanes. E-commerce consolidators exhibit highest price sensitivity, while biologics manufacturers accept premium rates for time-definite cryogenic logistics.
Supply Chain Analysis
Single-source vulnerability sits with Dubai and Doha controlling the majority of certified cool-dock capacity across the GCC. Pharmaceutical cold-chain infrastructure draws from German temperature-control equipment suppliers, Korean sensor manufacturers, and UAE-based ground handling operators. Regulatory restriction risk looms as GACA, GCAA, and Qatar's Civil Aviation Authority mandate phased screening protocol upgrades that disqualify non-compliant handlers. Distribution runs through hub-and-spoke networks anchored at Al Maktoum International Airport and Hamad International Airport, with bonded last-mile legs extending into Saudi Arabia's secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where Saudi Arabia's SFDA Good Distribution Practice requirements erect a barrier-to-entry moat favoring operators with pre-existing CEIV Pharma accreditation and integrated customs brokerage capabilities.
For Market Incumbents: To counter margin erosion in standard freight lanes, deepen backward integration into captive cool-storage construction at King Abdulaziz International Airport and Riyadh cargo zones. Prioritize blockchain-enabled documentation partnerships with GACA to compress clearance cycles and lock in pharmaceutical shipper loyalty before compliance deadlines harden. For New Entrants and Emerging Players: Launch via scheduled block space agreements with Oman Air and Jazeera Airways Cargo to access underpenetrated Salalah and Kuwait corridors without direct hub competition. Target cell and gene therapy logistics as the most penetrable premium tier, where cryogenic chain requirements and limited incumbent specialization create first-mover positioning for IATA CEIV Pharma-certified entrants. For Investors and Strategic Acquirers: Re-rating potential sits with mid-sized regional logistics platforms possessing customs brokerage integration and multi-country warehousing networks, given Kuwait's planned single-window clearance systems and Saudi domestic retail expansion. Monitor CEIV Fresh accreditation completion rates across Saudi Arabia and the UAE as the signal to watch for inflection in perishable corridor profitability.| Strategic Initiative | Industry Significance |
|---|---|
| CEIV Pharma Accreditation Expansion | GACA mandates are disqualifying non-certified handlers from Saudi pharmaceutical corridors. |
| Automated Cool-Dock Construction | Emirates SkyCargo deployment at Dubai South reduces tarmac exposure for temperature-sensitive shipments. |
| Blockchain Documentation Partnership | Dubai customs authority pilots compress clearance cycles for pharmaceutical exporters in Jebel Ali Free Zone. |
| East Africa-Gulf-Asia Routing | Salalah Free Zone positioning captures triangular transshipment bypassing Dubai chokepoints. |
| Single-Window Customs Integration | Kuwait's planned system reduces dwell times for cross-border e-commerce parcels entering northern Gulf markets. |
Research Methodology
GACA regulatory filings, IATA cargo statistics, and SFDA distribution rule updates formed the secondary backbone, cross-referenced with primary interviews involving cargo terminal operations managers, pharmaceutical logistics directors, airline network planners, and customs brokerage specialists. Bottom-up triangulation across carrier capacity disclosures and top-down validation through Gulf aviation authority infrastructure reports anchored market sizing.
Historical trendline analysis of pharmaceutical cold-chain volume growth and e-commerce parcel throughput informed projection modeling across service type, end user, technology, and cargo type segmentation dimensions. CAGRs were derived from regression analysis of certified infrastructure deployment rates and regulatory compliance phase-in schedules, with biologics manufacturing clustering and advance cargo information mandate timelines as key forecast inputs.
Fuel cost volatility, regulatory deadline acceleration, and workforce certification pipeline gaps are the dominant revision risks that could compress or extend projected growth trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
United States Apparel Logistics Market
Logistics and Shipping
South America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Air Cargo Container Market
Logistics and Shipping
Global 5PL Solutions Market
Logistics and Shipping
Hungary Third Party Logistics (3PL) Market
Logistics and Shipping
Timber Logistics Market
Logistics and Shipping
Romania Freight and Logistics Market
Logistics and Shipping
Germany Freight and Logistics Market
Logistics and Shipping
Global Air Cargo and Freight Logistics Market
Logistics and Shipping
Japan Third-Party Logistics (3PL) Market
Logistics and Shipping
United Arab Emirates Freight and Logistics Market
Logistics and Shipping
Egypt Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Germany Last Mile Delivery Market
Logistics and Shipping
Tank Container Shipping Market
Logistics and Shipping
On-Demand Logistics Market
Logistics and Shipping
Turkey Cold Chain Logistics Market