
 Event Logistics Market | 2026-2036
Event Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Event Logistics Market Analysis
Market Context
Germany's exhibition hall expansion across Berlin, Hamburg, and Cologne is narrowing the gap between peak demand periods and available venue capacity. Freeman leverages its integrated fabrication and logistics network to control end-to-end event build-outs across North American trade show circuits. GES sustains geographic dominance through proprietary digital asset management platforms that streamline booth transportation and on-site installation workflows. GPJ specializes in experiential brand activations, differentiating through technology leadership in augmented reality staging and modular scenic construction.
Technical Definition and Structural Segments
Event logistics encompasses the procurement, transportation, warehousing, installation, and dismantling of temporary physical assets—including modular exhibits, staging systems, lighting rigs, and catering infrastructure—required to execute live gatherings at defined venues within constrained time windows. The discipline demands precision scheduling measured in four-hour installation windows and real-time coordination across multiple subcontractor tiers to meet fixed opening times. Transportation and venue management services capture the dominant margin pools due to their capital-intensive nature and limited supplier substitution, while audio-visual services represent the fastest-growing segment as hybrid delivery models require simultaneous physical and digital production capabilities. Corporate clients anchor volume demand through recurring trade show and conference programs, whereas the outsourced delivery model is displacing in-house event teams as organizations prioritize variable cost structures over fixed event departments.
Regulatory Frame and Forward-Looking Close
The EU's F-Gas Regulation restricts fluorinated greenhouse gases in temporary cooling and refrigeration units deployed for outdoor festivals and catering operations, while Germany's KBA enforces commercial vehicle emission standards for freight movements into city-center exhibition grounds during restricted hours. OSHA in the United States mandates fall protection and load-bearing certification for rigging crews assembling temporary overhead structures in convention centers. Stakeholders must monitor how CSRD-aligned carbon accounting requirements will reshape supplier selection criteria for temporary structure providers and freight carriers serving major exhibition venues.
Market Dynamics
Hybrid delivery mandates from corporate conference planners are compressing installation windows and forcing logistics providers to synchronize physical venue build-outs with real-time virtual streaming infrastructure across multiple subcontractor tiers.
Growth Catalysts
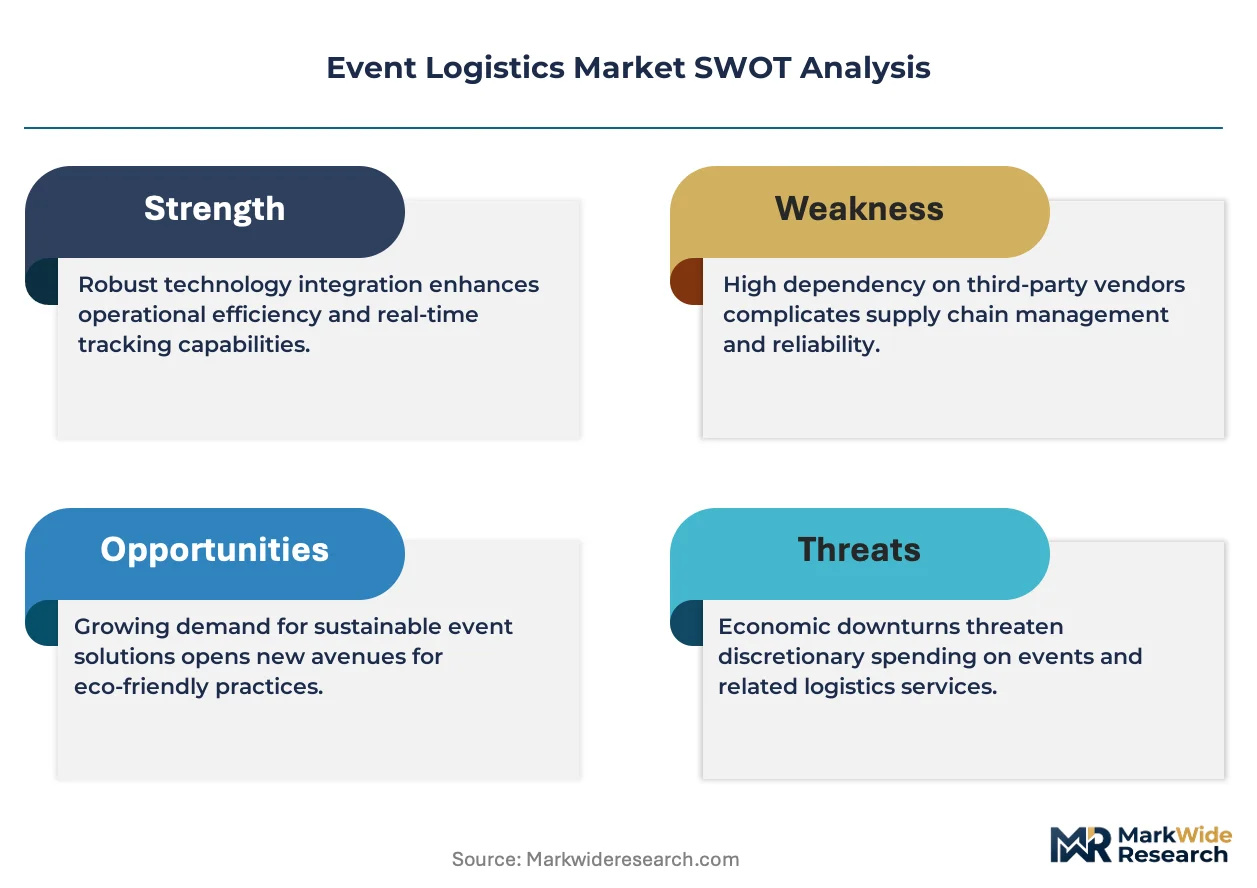
- EU CSRD carbon disclosure:Sustainability reporting mandates for temporary structures and freight movements are creating competitive differentiation for providers with verified emissions tracking systems.
- Exhibition hall expansion:Germany's venue capacity growth across Berlin, Hamburg, and Cologne is extending the tradeshow calendar and generating year-round logistics demand.
- Modular scenic systems:Reusable aluminum frame construction is reducing material waste and accelerating booth installation cycles for recurring corporate programs.
Market Restraints
- Freight emission standards:Germany's KBA enforces strict commercial vehicle limits for city-center exhibition ground access during restricted hours, constraining delivery scheduling flexibility.
- Specialized rigging labor:Certified load-bearing crew scarcity limits rapid scaling for simultaneous mega-events in dense metropolitan clusters.
- Fluorinated gas restrictions:The EU's F-Gas Regulation bans specific refrigerants in temporary cooling units, forcing equipment fleet replacement for outdoor festival catering operations.
Strategic Opportunities
- Digital asset platforms:Proprietary booth transportation and installation workflow systems offer margin expansion through reduced on-site coordination labor.
- AR staging integration:Augmented reality scenic elements are opening premium service tiers for brand activation budgets seeking experiential differentiation.
- Carbon accounting services:CSRD-aligned supplier verification tools represent a new revenue stream for logistics providers serving ESG-mandated corporate clients.
Industry Challenges
- Four-hour installation windows:Precision scheduling demands real-time coordination across multiple subcontractor tiers with zero tolerance for delay.
- Fall protection compliance:OSHA-mandated rigging crew certification timelines extend workforce deployment lead times for US convention center events.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Event Logistics Market |
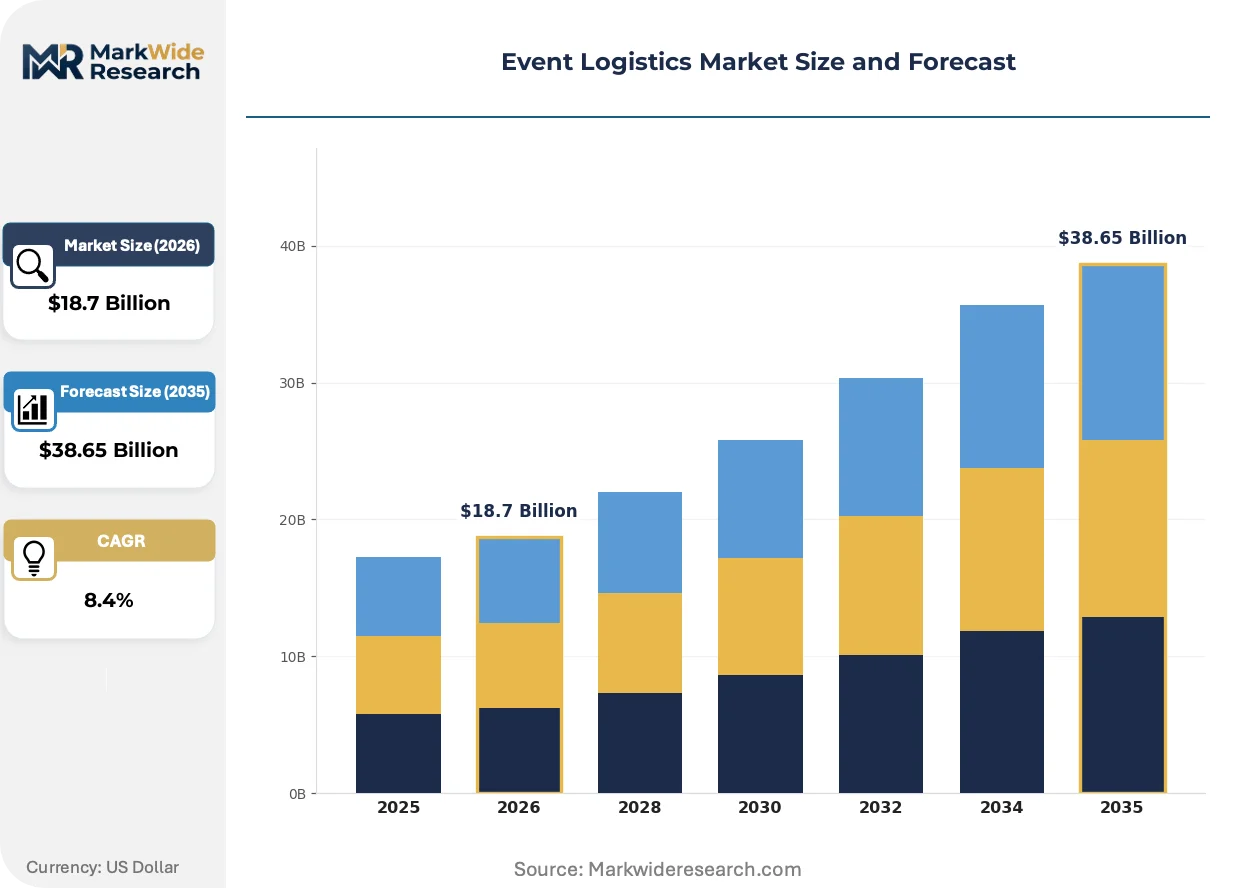
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Venue Management, Catering, Audio-Visual Services Event Type: Conferences, Trade Shows, Festivals, Weddings Client Type: Corporates, Non-Profits, Government, Individuals Delivery Model: On-Site, Hybrid, Virtual, Outsourced |
| Companies Covered | CPG Agency, GES, GoGather, Destination Concepts, GPJ, Freeman, Event Logistics, TK Events, Jack Morton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Event Logistics Market Emerging Trajectories
Event logistics is converging with digital production capabilities as hybrid delivery models become standard, while regulatory pressure on temporary structure emissions reshapes supplier selection criteria.
Reusable modular aluminum framing is migrating from niche sustainability programs to mainstream corporate trade show specifications. Fortune 500 exhibitors now mandate recyclable booth construction for recurring annual programs. This shift is compressing material procurement cycles and reducing landfill disposal costs for logistics providers managing end-to-end build-outs.
The EU's F-Gas Regulation is phasing down hydrofluorocarbon use in temporary refrigeration and cooling equipment deployed for outdoor festivals. Equipment rental fleets face accelerated replacement schedules to maintain compliance. German logistics providers serving Munich's Oktoberfest-scale events are retrofitting cold chain assets with natural refrigerant alternatives.
Corporate event teams are consolidating vendor relationships around integrated fabrication-logistics providers capable of single-contract accountability. Procurement departments are eliminating fragmented subcontractor management in favor of turnkey build-out partners. This concentration is most visible in North American tech sector conference circuits where speed-to-execution outweighs cost minimization.
Event Logistics Market Segmentation
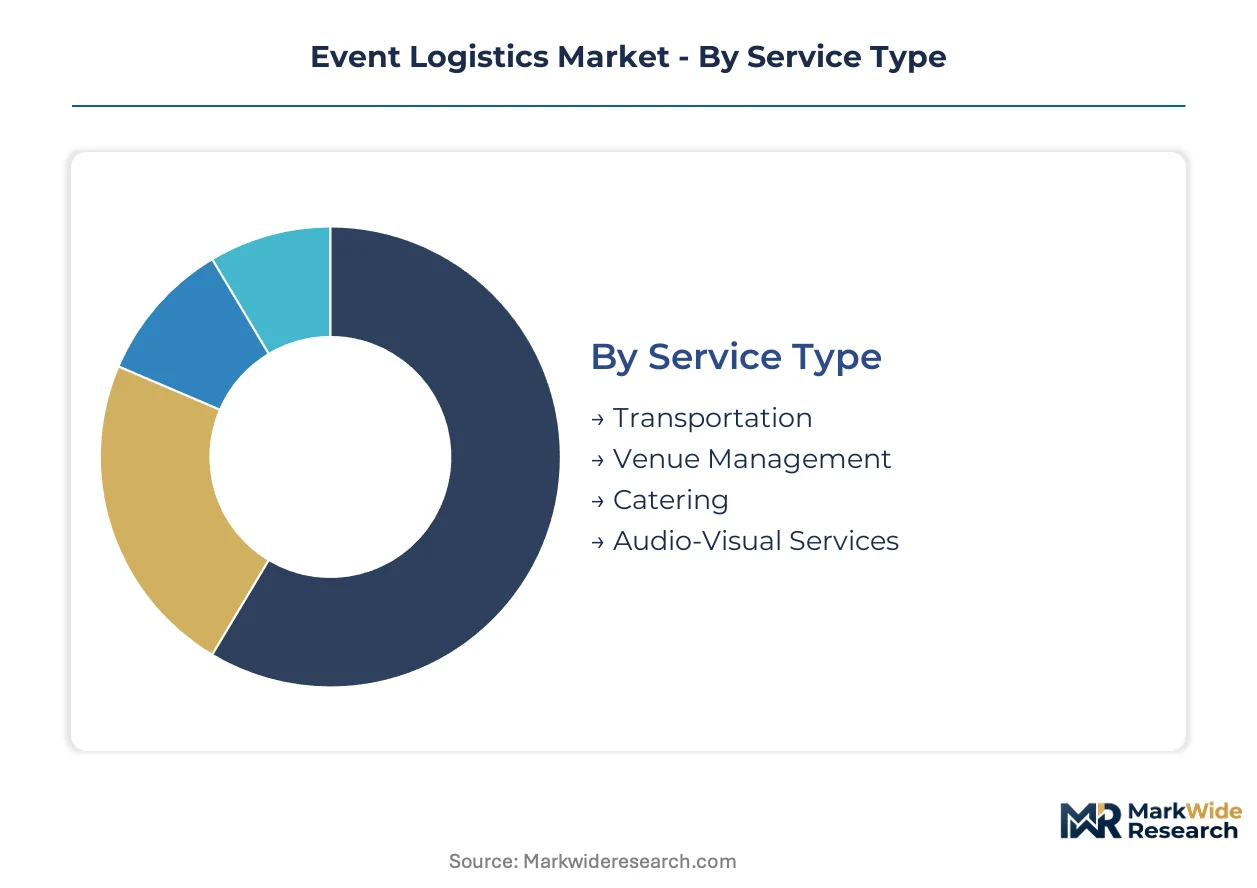
Event logistics segmentation reveals distinct margin profiles and operational constraints across service tiers. Each dimension exposes different competitive dynamics, from capital-intensive transportation fleets to labor-scarce rigging crews.
Service Type:
Cost tier stratification separates capital-heavy infrastructure services from variable-cost labor specialties.
- Transportation:Heavy-haul trucking and specialized freight coordination for oversized exhibit components and modular structures. Fleet ownership and KBA emission compliance in Germany anchor competitive positioning for city-center exhibition ground access.
- Venue Management:End-to-end coordination of installation windows, subcontractor scheduling, and on-site asset flow control. Precision four-hour build-out mandates from Messe Frankfurt and Messe München compress coordination tolerances to near-zero.
- Catering:Temporary food service infrastructure including refrigeration, mobile kitchens, and waste removal.
- Audio-Visual Services:Hybrid streaming infrastructure and physical staging systems.
Transportation and venue management command the established base. The steepest expansion runs through audio-visual services.
Event Type:
Application context determines asset reusability and scheduling predictability across the calendar.
- Conferences:Recurring corporate programs with standardized booth specifications and compressed turnaround cycles. Berlin and Hamburg venue expansions are extending annual conference density.
- Trade Shows:Large-format exhibition builds requiring simultaneous multi-booth coordination. CSRD-aligned carbon accounting is reshaping material procurement for recurring programs.
- Festivals:Outdoor temporary infrastructure with seasonal demand spikes.
- Weddings:Fragmented individual bookings with high customization requirements.
Conferences anchor volume stability. Festivals show the most volatile demand amplitude.
Client Type:
Customer sophistication and procurement scale separate enterprise programs from discretionary spending.
- Corporates:Fortune 500 recurring trade show commitments with ESG-mandated supplier vetting. CSRD disclosure requirements are forcing verified emissions tracking across temporary structure providers.
- Non-Profits:Budget-constrained programs prioritizing cost minimization over service integration.
- Government:Compliance-heavy procurement with extended vendor qualification timelines.
- Individuals:One-time events with price sensitivity and low switching costs.
Corporates dominate contract value concentration. Non-profits exhibit the highest price elasticity.
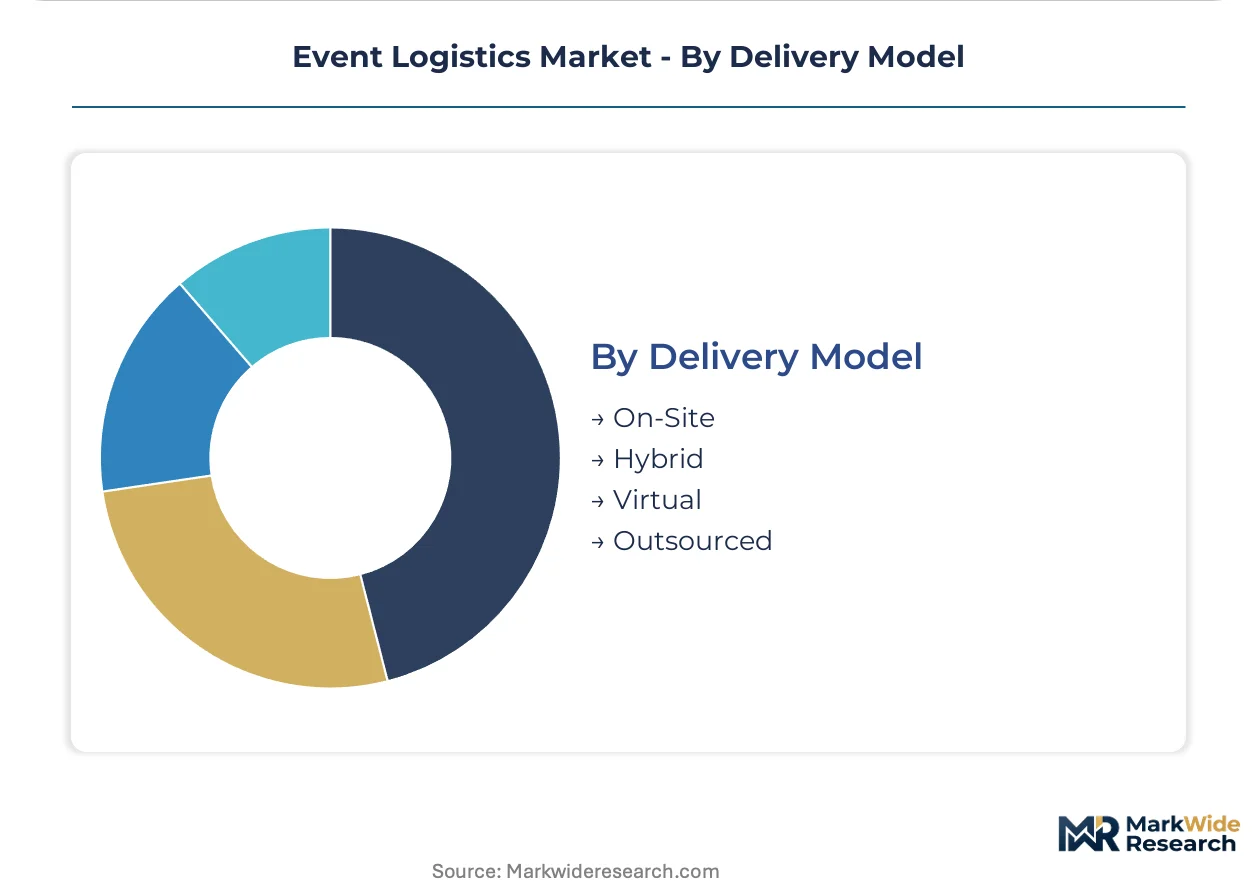
Delivery Model:
Maturity of execution format defines technical capability requirements and margin structure.
- On-Site:Traditional physical venue coordination with established subcontractor networks. OSHA fall protection mandates extend rigging crew deployment lead times for US convention centers.
- Hybrid:Simultaneous physical build-out and virtual streaming infrastructure. Corporate planners now mandate this as default for major conference programs.
- Virtual:Digital-only production with minimal logistics touchpoints.
- Outsourced:Turnkey accountability displacing fragmented in-house event teams.
On-site retains volume dominance. Hybrid delivery is climbing the fastest as corporate standard-of-care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German logistics providers anchor the largest share of exhibition infrastructure contracts, with Messe Frankfurt and Messe München generating concentrated demand for precision-scheduled venue build-outs. Supply-side capacity clusters around these dense metropolitan exhibition ecosystems, compressing subcontractor coordination windows to four-hour installation mandates.
United States
Corporate conference circuits in Las Vegas, Chicago, and Orlando drive recurring demand for hybrid delivery infrastructure. OSHA mandates fall protection certification for rigging crews assembling temporary overhead structures in convention centers. Freeman leverages integrated fabrication networks across North American trade show circuits.
Germany
Berlin, Hamburg, and Cologne venue expansions extend the tradeshow calendar into year-round logistics cycles. KBA enforces commercial vehicle emission standards for freight movements into city-center exhibition grounds during restricted hours. Messe Frankfurt anchors Europe's densest exhibition ecosystem with compressed installation tolerances.
United Kingdom
London's ExCeL and NEC Birmingham anchor corporate event demand for modular scenic construction. CSRD-aligned carbon accounting requirements reshape supplier vetting for temporary structure providers. Integrated logistics-fabrication providers consolidate vendor relationships in the tech sector conference circuit.
United Arab Emirates
Dubai World Trade Centre and Abu Dhabi National Exhibition Centre drive mega-event infrastructure demand for simultaneous physical and digital production. MOHAP oversees health and safety compliance for temporary catering operations at outdoor festivals. Expo City Dubai sustains post-2020 legacy demand for turnkey build-out accountability.
Japan
Tokyo Big Sight and Osaka International Exhibition Center anchor demand for precision-scheduled booth installation workflows. METI promotes modular aluminum framing adoption to reduce material waste in recurring corporate programs. Japanese logistics providers integrate digital asset management platforms for real-time subcontractor coordination.
Event Logistics Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in fabrication and rigging subcontracts. The vendor base stratifies between capital-heavy transportation fleet operators and labor-scarce certified rigging crews. Three archetypes dominate: integrated fabrication-logistics providers, digital workflow platform operators, and experiential technology specialists. Competitive moves concentrate on M&A for geographic footprint expansion and strategic partnerships for hybrid delivery capability.
Among North American integrated providers, Freeman and GES exemplify the platform integrator archetype, while GPJ occupies a position within the experiential technology tier. Freeman represents the fabrication-logistics convergence model through end-to-end build-out accountability. GES anchors the digital workflow specialization through proprietary asset management systems. GPJ exemplifies technology-led differentiation in augmented reality staging and modular scenic construction.
| Leading Market Players |
|---|
| CPG Agency |
| GES |
| GoGather |
| Destination Concepts |
| GPJ |
| Freeman |
| Event Logistics |
| TK Events |
| Jack Morton |
| Others |
Supply Flow & Price Mechanics
Messe Frankfurt's heavy-haul freight corridor into central Germany compresses logistics cost differentials between integrated providers and fragmented subcontractor networks, while EU CSRD disclosure mandates are forcing price stratification between verified emissions-tracked suppliers and uncertified competitors.
Pricing Analysis
The EU's F-Gas Regulation dictates the pricing tier structure for temporary refrigeration equipment deployed at outdoor festivals, separating natural refrigerant-compliant fleets from legacy hydrofluorocarbon assets facing accelerated replacement cycles. Project-based contracting dominates corporate conference programs, with price differentiation anchored in CSRD-aligned carbon accounting certification and modular aluminum framing reusability. Cost compression in standard-tier venue management services is intensifying as German exhibition hall expansion extends capacity availability and compresses peak-period premiums. Non-profit event organizers exhibit the highest price elasticity, while Fortune 500 corporate clients prioritize single-contract accountability over cost minimization.
Supply Chain Analysis
Aluminum extrusion feedstock for modular scenic systems draws from German, Chinese, and Norwegian smelter networks, with KBA emission-compliant trucking fleets and certified rigging labor pools representing the critical downstream bottlenecks. Specialized freight coordination for oversized exhibit components rests on heavy-haul trucking capacity concentrated in Germany, the United States, and the United Arab Emirates. Single-source vulnerability in certified load-bearing crew availability constrains rapid scaling for simultaneous mega-events in dense metropolitan clusters. Distribution runs through integrated fabrication-logistics providers capable of end-to-end build-out accountability, displacing fragmented subcontractor management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified rigging labor scarcity and KBA-compliant fleet limitations are constraining rapid capacity expansion, privileging providers with captive workforce development programs and verified emissions infrastructure over asset-light competitors.
For Market Incumbents: Pre-empt margin erosion in standard-tier venue management by consolidating subcontractor relationships into captive networks, while accelerating backward integration into modular aluminum fabrication to capture material reusability premiums. The threat of digital-native workflow platforms displacing legacy coordination systems demands proprietary asset management investment. CSRD-aligned carbon accounting certification represents the critical defensive lever for corporate contract retention. For New Entrants and Emerging Players: Establish a beachhead in carbon accounting services for ESG-mandated corporate clients, where supplier verification tools represent an underpenetrated white-space adjacent to core logistics execution. Target mid-tier conference circuits in expanded German venues where installation window compression exceeds incumbent coordination capacity. A SaaS-enabled workflow platform go-to-market angle bypasses capital-intensive fleet ownership requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated fabrication-logistics providers with proprietary digital asset management platforms, as hybrid delivery mandates consolidate vendor relationships around single-contract accountability. Long-term viability across the projection horizon rests on CSRD compliance infrastructure and AR staging capability. The inflection indicator to monitor is corporate procurement department consolidation of vendor panels, signaling accelerated market share concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Digital Asset Platform Development | Reduces on-site coordination labor for Messe Frankfurt's four-hour installation mandates. |
| Natural Refrigerant Fleet Retrofit | Maintains EU F-Gas Regulation compliance for Munich-scale outdoor festival catering operations. |
| CSRD-Aligned Carbon Accounting Service Launch | Captures new revenue from Fortune 500 ESG-mandated supplier vetting requirements. |
| Modular Aluminum Framing Backward Integration | Controls material reusability premiums for recurring corporate trade show programs. |
| Certified Rigging Workforce Development Program | Addresses OSHA-mandated crew scarcity constraining US convention center scaling. |
Methodological Framework
A standing panel of exhibition venue operations directors, corporate event procurement managers, certified rigging crew supervisors, and temporary structure fabrication specialists provided ongoing calibration against secondary validation from trade association filings, customs freight movement data, SEC disclosures by publicly listed logistics providers, and EU regulatory implementation guidance. Primary interviews with stakeholders across Germany, the United States, and the United Arab Emirates combined with bottom-up service tier volume estimates and top-down market sizing triangulation.
Scenario-bracketing around CSRD implementation pace, hybrid delivery adoption curves, and German venue expansion timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, event format, client sophistication tier, and delivery model maturity. CAGRs were derived from logistic curve fitting to technology adoption patterns and regulatory compliance cost trajectories, with specific inputs from aluminum framing reusability cycle data and certified labor pool growth projections.
Stress conditions across KBA emission standard enforcement intensity, rigging labor availability shocks, and corporate procurement consolidation velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation timelines and technology substitution rates. Cross-checking against exhibition industry trade association volume surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Asia Pacific Sea Freight Forwarding Market
Logistics and Shipping
China Project Logistics Market
Logistics and Shipping
United Arab Emirates Freight and Logistics Market
Logistics and Shipping
United Kingdom Cold Chain Logistics Market
Logistics and Shipping
Latin America Contract Logistics Market
Logistics and Shipping
United States Cold Chain Logistics Market
Logistics and Shipping
Asia-Pacific Last Mile Delivery Market
Logistics and Shipping
US Mexico Cross Border FTL Freight Transport Market
Logistics and Shipping
Tank Container Shipping Market
Logistics and Shipping
Cargo Transportation Market
Logistics and Shipping
Georgia Freight and Logistics Market
Logistics and Shipping
Control Towers Market
Logistics and Shipping
Sri Lanka Freight and Logistics Market
Logistics and Shipping
Netherlands Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
United States FTL Freight Brokerage Market
Logistics and Shipping
Flat Rack Containers Market