
 Europe Full Container Load (FCL) Market | 2026-2036
Europe Full Container Load (FCL) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Full Container Load (FCL) Market Foresight
Buyer concentration among large European retailers and automotive OEMs is hardening, pressuring mid-tier forwarders on volume commitments and rate negotiations. Maersk leverages its integrated ocean-to-door network to capture direct contracts with manufacturing shippers. DHL sustains dominance in customs brokerage and bonded warehousing across the EU internal market. Kuehne + Nagel International AG anchors its position through proprietary digital booking platforms that bypass traditional freight broker channels.
Full Container Load denotes exclusive use of an entire intermodal shipping container by a single shipper, typically involving twenty-foot equivalent unit (TEU) or forty-foot equivalent unit (FEU) containers sealed at origin and delivered unopened to destination. The Reefer Container segment is expanding fastest as pharmaceutical cold chains and fresh produce exporters demand precise temperature integrity from southern Europe to Nordic markets. The Freight Forwarding service type still commands the largest revenue pool, though margin compression from digital freight platforms is redirecting value toward customs clearance and value-added warehousing.
The EU Green Deal and F-Gas Regulation are reshaping reefer container specifications and inland haulage emissions standards, while ECHA chemical handling rules affect tank container certifications for hazardous cargo. EMA pharmaceutical transport guidelines and national food safety authorities enforce chain-of-custody documentation that elevates compliance costs for non-specialized carriers. Stakeholders must monitor how the EU Emissions Trading System extension to maritime shipping alters route economics and carrier alliance structures.
Market Dynamics
Carrier consolidation and the EU Green Deal's emissions trading extension to maritime shipping are compressing forwarder margins while forcing asset-light operators toward specialized value-added services.
Growth Catalysts
- EU Emissions Trading System expansion:Maritime inclusion under the EU ETS is accelerating fleet renewal investments and stimulating demand for verified low-carbon FCL services from sustainability-focused shippers.
- Automotive just-in-time restructuring:European OEMs are consolidating parts suppliers into sealed FCL circuits to reduce inventory carrying costs and protect against semiconductor supply volatility.
- Rhine-Ruhr logistics cluster densification:Germany's industrial heartland is attracting bonded warehousing investments that feed direct FCL injection into the Port of Rotterdam's deep-sea network.
Market Restraints
- Container manufacturing concentration:Chinese and South Korean producers control over 95% of global reefer box output, exposing European carriers to input cost volatility and extended order backlogs.
- REACH chemical documentation:ECHA's substance registration requirements create friction for tank container operators moving specialty chemicals across EU internal borders.
- Trucking capacity fragmentation:Driver shortages across Poland, Hungary, and Romania constrain inland haulage elasticity during seasonal demand spikes.
Strategic Opportunities
- Polish manufacturing corridor:Central European production relocation from Asia is generating new FCL origination volumes from the Łódź and Wrocław industrial zones.
- Digital freight platform integration:API-connected booking systems are converging with customs pre-clearance databases to compress port dwell times.
- F-Gas Regulation retrofit demand:Refrigerant phase-down mandates are creating replacement cycles for reefer container fleets serving Mediterranean produce exporters.
Industry Challenges
- Customs brokerage talent scarcity:Post-Brexit rules-of-origin complexity and ICS2 entry requirements have outpaced training pipeline capacity for specialized declarants.
- Reefer telematics integration:Legacy container fleets lack IoT sensor compatibility with emerging blockchain-based chain-of-custody verification systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Full Container Load (FCL) Market |
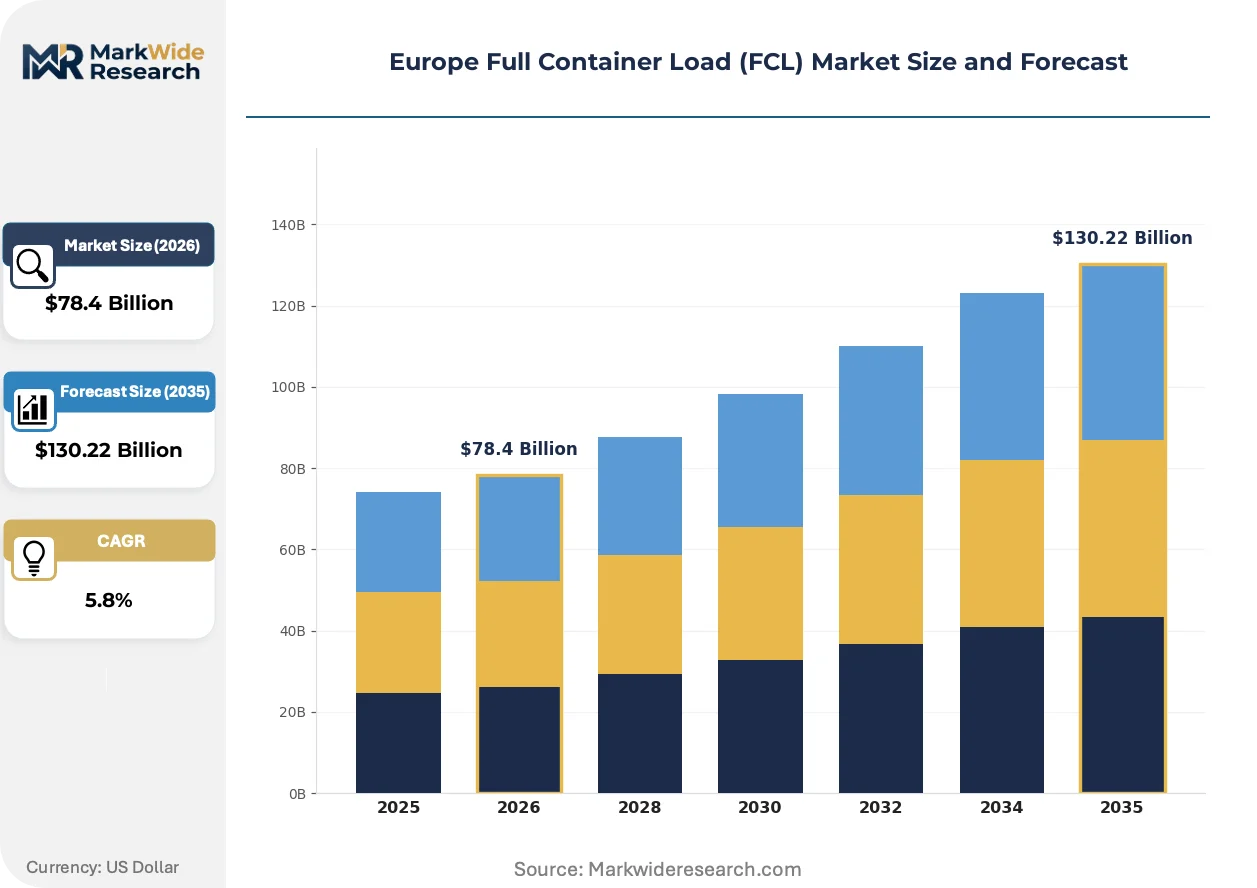
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $130.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Customs Clearance, Freight Forwarding End User: Manufacturers, Retailers, Wholesalers, E-commerce Container Type: Dry Container, Reefer Container, Tank Container, Flat Rack Distribution Channel: Direct Shipping, Third-Party Logistics, Freight Brokers, Others |
| Companies Covered | Kuehne + Nagel International AG, DHL, DB Schenker, DSV Global, Bolloré Logistics, Maersk, CMA CGM, Hapag-Lloyd, MSC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Full Container Load (FCL) Market Shifts & Advancements
Digital freight platforms and emissions verification systems are compressing traditional broker functions while elevating data transparency as a competitive differentiator across European trade corridors.
Blockchain-enabled bill-of-lading documentation is overtaking paper-based customs processes at major EU ports. Pharmaceutical and high-value electronics shippers in the Netherlands and Belgium are adopting smart-contract settlements to reduce documentary credit friction. This compression of settlement cycles is forcing traditional forwarders to absorb IT infrastructure costs or cede direct shipper relationships to integrated carriers.
The EU Green Deal's Fit for 55 package is tightening fuel standards for heavy-duty trucks serving maritime terminals. German and French haulage operators face mandatory fleet renewal timelines that favor electric and hydrogen tractor units for short-haul container drays. Reefer segments are responding with shore-power retrofit investments to eliminate auxiliary engine emissions during terminal dwell.
Direct contracting between manufacturing shippers and ocean carriers is displacing intermediary volume aggregation in major trade lanes. Automotive and retail buyers in Germany and Italy are leveraging tender platforms to secure multi-year FCL commitments at fixed rates. This behavioral shift concentrates negotiating leverage with volume holders and compresses spot market liquidity for smaller forwarders.
Europe Full Container Load (FCL) Market Segmentation
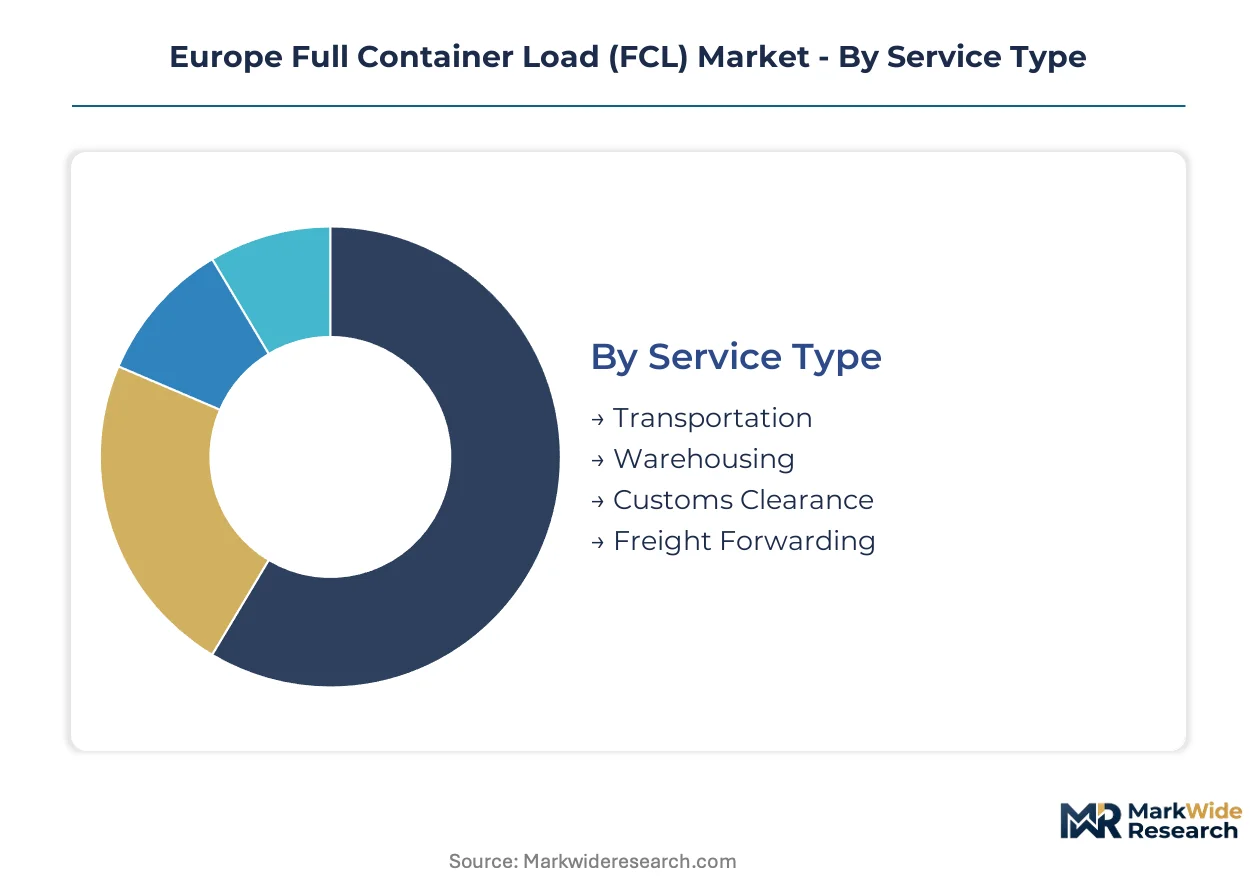
Segmentation reveals how service bundling, equipment specialization, and channel structure fragment competitive position across European trade corridors. Each dimension carries distinct margin profiles and regulatory exposure that shape carrier and forwarder strategy.
Service Type:
Supply concentration in integrated ocean-to-door networks is compressing standalone service margins and forcing specialization.
- Transportation:Ocean and intermodal haulage of sealed containers between maritime terminals and inland depots. Demand concentrates in Germany's Rhine-Ruhr corridor and Rotterdam hinterland, where automotive OEMs require synchronized arrival windows for just-in-time assembly lines.
- Warehousing:Bonded storage and cross-dock facilities for containerized inventory awaiting customs release or final distribution. E-commerce fulfillment centers in Belgium and the Netherlands are absorbing capacity fastest as direct-to-consumer models replace wholesale distribution.
- Customs Clearance:Documentation preparation and regulatory compliance for EU entry and internal border crossings. Post-Brexit rules-of-origin complexity and ICS2 requirements have elevated demand for specialized declarants at UK-facing ports.
- Freight Forwarding:End-to-end coordination of booking, documentation, and multimodal handoffs. Margin compression from digital platforms is redirecting value toward value-added services and captive customs brokerage.
Freight Forwarding absorbs the bulk of installed capacity; Warehousing is expanding most quickly.
End User:
Customer scale and procurement sophistication are polarizing service requirements between direct contracting and intermediary aggregation.
- Manufacturers:Industrial shippers moving raw materials, components, and finished goods through sealed FCL circuits. Automotive and machinery producers in Germany and Italy are consolidating supplier bases into dedicated container flows to reduce inventory carrying costs.
- Retailers:Large-format and specialty chains importing seasonal merchandise and private-label products. Sustainability mandates under the EU Green Deal are steering volume toward carriers with verified low-carbon service offerings.
- Wholesalers:Distributors aggregating fragmented supplier output into consolidated container loads. Polish and Czech distribution hubs are gaining share as manufacturing relocation from Asia generates new origination volumes.
- E-commerce:Platform operators and third-party sellers requiring rapid replenishment of fulfillment networks. Direct injection into parcel networks is bypassing traditional wholesale warehousing in the Netherlands and UK.
Manufacturers command the largest revenue pool; E-commerce is climbing the fastest.
Container Type:
Equipment specialization is concentrating investment around temperature integrity and hazardous cargo certification.
- Dry Container:Standard enclosed boxes for non-perishable general cargo, available in TEU and FEU specifications. Volume concentrates in consumer goods and machinery moving through Rotterdam and Hamburg terminals.
- Reefer Container:Temperature-controlled units with integrated refrigeration for pharmaceutical cold chains and fresh produce. Mediterranean exporters serving Nordic markets are driving replacement cycles under F-Gas Regulation refrigerant phase-down mandates.
- Tank Container:Stainless steel vessels for liquid chemicals, food-grade products, and gases. ECHA substance registration requirements create compliance friction for specialty chemical operators moving across EU internal borders.
- Flat Rack:Collapsible platforms with fixed or folding end walls for oversized and heavy cargo. Project cargo and machinery out-of-gauge movements absorb sporadic demand from German and Italian industrial zones.
Dry Container retains the dominant installed base; Reefer Container is gaining share fastest.
Distribution Channel:
Channel structure is bifurcating between direct shipper-carrier relationships and platform-mediated aggregation.
- Direct Shipping:Contractual arrangements between manufacturing shippers and ocean carriers without intermediary forwarders. Large German and Italian automotive and retail buyers are leveraging tender platforms to secure multi-year commitments at fixed rates.
- Third-Party Logistics:Integrated providers combining transportation, warehousing, and customs services under single accountability. DHL and Kuehne + Nagel sustain dominance through proprietary digital booking platforms and bonded warehousing networks.
- Freight Brokers:Intermediaries matching spot capacity with ad-hoc shipper demand. Digital freight platforms are compressing traditional broker margins by converging API-connected booking with customs pre-clearance databases.
- Others:Cooperative arrangements, consortium structures, and captive fleet operations serving affiliated corporate groups. Niche configurations persist in specialized chemical and pharmaceutical verticals.
Third-Party Logistics captures the dominant revenue share; Direct Shipping is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany's industrial heartland and the Netherlands' maritime gateway, with automotive OEMs and pharmaceutical cold chains driving volume commitments across Northern Europe's integrated logistics corridors.
Germany
Automotive manufacturers in Stuttgart and Munich are consolidating supplier bases into sealed FCL circuits to protect against semiconductor volatility. The EU Green Deal's Fit for 55 package mandates fleet renewal for heavy-duty trucks serving Hamburg and Bremerhaven terminals. The Rhine-Ruhr logistics cluster attracts bonded warehousing investments that feed direct container injection into Rotterdam's deep-sea network.
Netherlands
Pharmaceutical exporters in the Randstad region demand precise temperature integrity for Nordic market access, accelerating reefer container replacement cycles. EMA transport guidelines enforce chain-of-custody documentation that elevates compliance costs for non-specialized carriers. The Port of Rotterdam's hinterland expansion absorbs transshipment volumes from German industrial zones seeking alternative routing flexibility.
Poland
Central European production relocation from Asia generates new FCL origination volumes from Łódź and Wrocław industrial zones. National food safety authorities align with EU cold chain standards for Mediterranean produce re-exports. Trucking capacity constraints across the Polish corridor intensify during seasonal demand spikes, pressuring inland haulage elasticity.
Italy
Machinery producers in Lombardy and Emilia-Romagna leverage tender platforms to secure multi-year FCL commitments at fixed rates. REACH chemical documentation requirements create friction for specialty cargo moving across EU internal borders. Milan's logistics hub consolidates fragmented supplier output into dedicated container flows for German automotive buyers.
Belgium
E-commerce fulfillment centers in Antwerp and Liège absorb warehousing capacity fastest as direct-to-consumer models replace wholesale distribution. F-Gas Regulation refrigerant phase-down mandates drive reefer fleet retrofit demand for Mediterranean produce exporters. Brussels-based customs brokers face talent scarcity as post-Brexit rules-of-origin complexity outpaces training pipeline capacity.
Europe Full Container Load (FCL) Market Competitive Landscape
North Sea carriers anchor the premium tier; Central European forwarders hold specialized brokerage positions. The market presents a consolidated structure with integrated ocean-to-door networks compressing standalone service margins. Three archetypes dominate: asset-heavy ocean carriers with captive terminal access, digital-forward forwarders with proprietary booking platforms, and specialized customs brokers with bonded warehousing networks. Carrier consolidation and emissions trading system compliance are accelerating fleet renewal investments while forcing asset-light operators toward value-added services.
Within the integrated carrier tier, Maersk and CMA CGM exemplify ocean-to-door network operators that capture direct manufacturing shipper contracts. Among European forwarders, Kuehne + Nagel International AG and DHL occupy positions defined by customs brokerage dominance and digital platform integration. These players represent how proprietary technology and bonded warehousing networks sustain competitive differentiation against margin compression from API-connected freight platforms.
| Leading Market Players |
|---|
| Kuehne + Nagel International AG |
| DHL |
| DB Schenker |
| DSV Global |
| Bolloré Logistics |
| Maersk |
| CMA CGM |
| Hapag-Lloyd |
| MSC |
| Others |
Supply & Pricing Matrix
Shanghai Containerized Freight Index volatility cascades through European FCL markets, compressing margins for asset-light forwarders while integrated carriers leverage long-term contract structures to buffer spot rate exposure across premium, standard, and economy service tiers.
Pricing Analysis
Volume concentration among German automotive OEMs and Dutch retailers splits the market between fixed-rate multi-year contracts and volatile spot procurement. Contract pricing stratifies across premium, standard, and economy tiers based on cargo value density and customs complexity bundling. Cost compression in the spot tier is intensifying because digital freight platforms compress broker margins through API-driven rate transparency. Small Polish and Czech wholesalers exhibit highest price sensitivity, while pharmaceutical shippers in Belgium and the Netherlands prioritize temperature integrity over rate minimization.
Supply Chain Analysis
Freight cost inflation along Asia-Europe corridors and Baltic feeder routes feeds into landed cost structures for German machinery and Italian automotive components. Container manufacturing concentrates in China and South Korea, while reefer box assembly draws from Chinese and South Korean component ecosystems. European operators rest on stainless steel sheet, compressor units, and refrigerant gases as critical inputs. Single-source vulnerability in Chinese container production exposes carriers to order backlog risk. Distribution runs through Rotterdam and Hamburg deep-sea terminals into Rhine-Ruhr bonded warehousing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European FCL markets have become a vertical-integration race where captive control over customs brokerage networks and reefer maintenance infrastructure determines margin defense against platform disintermediation.
For Market Incumbents: Anticipate digital freight platform encroachment by consolidating proprietary booking systems with bonded warehousing assets in the Rhine-Ruhr corridor. Acquire specialized customs declarants in Belgium and the Netherlands to capture post-Brexit rules-of-origin complexity premiums. Secure long-term reefer fleet renewal contracts ahead of F-Gas Regulation phase-down deadlines. For New Entrants and Emerging Players: API-connected customs pre-clearance databases offer a technology-first wedge into forwarder-dominated documentation workflows. Target Polish manufacturing corridors around Łódź and Wrocław where production relocation from Asia generates origination volume without entrenched carrier relationships. Partner with Mediterranean produce exporters for reefer telematics retrofit demand under EU emissions standards. For Investors and Strategic Acquirers: Distressed-cycle entries favor asset-light customs brokerage specialists in Benelux with ICS2 compliance capabilities and trained declarants. Long-term viability hinges on regulatory complexity deepening faster than automation can displace specialized human expertise. Monitor EU ETS carbon price trajectories as the inflection signal for low-carbon service premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Reefer Fleet Retrofit Program | F-Gas Regulation compliance secures Mediterranean produce exporter contracts under ECHA refrigerant mandates. |
| Customs Brokerage Acquisition | Post-Brexit ICS2 complexity elevates specialized declarants above digital platform commoditization. |
| Direct Shipper Platform Integration | API-connected booking systems compress port dwell times at Rotterdam through pre-clearance database convergence. |
| Polish Corridor Capacity Expansion | Łódź and Wrocław industrial zones generate origination volumes from Asia manufacturing relocation. |
| Low-Carbon Service Certification | EU ETS maritime inclusion creates verified emissions service tier differentiation for sustainability-focused shippers. |
Research Methodology
Trade databases, customs flow records, and carrier financial disclosures formed the secondary backbone, cross-referenced with primary interviews involving freight forwarder operations directors, automotive OEM logistics managers, reefer fleet procurement leads, and customs brokerage principals. Bottom-up container volume data from Port of Rotterdam and Hamburg terminal operators was triangulated against top-down macro trade flow estimates across the analysis window.
Bottom-up modeling of TEU and FEU movements by container type, service tier, and end-use vertical converged with top-down GDP-trade elasticity benchmarks. Segmentation dimensions included service type, container equipment category, distribution channel structure, and regional logistics cluster density. CAGRs were derived from trend extrapolation of carrier fleet deployment schedules and manufacturing relocation patterns, incorporating EU ETS carbon price assumptions and F-Gas Regulation compliance cost curves as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged Asia-Europe freight rate volatility or accelerated EU Green Deal regulatory tightening. Forecasts reflect documented assumptions about manufacturing relocation velocity and carrier alliance stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
United States Courier, Express and Parcel (CEP) Market
Logistics and Shipping
United Arab Emirates Freight and Logistics Market
Logistics and Shipping
South Korea International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Europe Container Terminal Operations Market
Logistics and Shipping
Total Logistics Market
Logistics and Shipping
Russia Courier Service Market
Logistics and Shipping
Bangladesh Freight and Logistics Market
Logistics and Shipping
China Automotive Logistics Market
Logistics and Shipping
Freight Forwarding Market
Logistics and Shipping
Central and Eastern Europe Cold Chain Logistics Market
Logistics and Shipping
France Freight and Logistics Market
Logistics and Shipping
Italy Cold Chain Logistics Market
Logistics and Shipping
GCC Warehousing and Distribution Logistics Market
Logistics and Shipping
Courier, Express and Parcel Services Market
Logistics and Shipping
Global 5PL Solutions Market
Logistics and Shipping
Germany Freight Forwarding Market