
 Europe Chemical Logistics Market | 2026-2036
Europe Chemical Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Chemical Logistics Market Analysis
Specialized hazmat driver availability is rotating toward acute shortage across European chemical corridors, constraining fleet expansion and forcing wage premiums in Germany and the Netherlands. DHL leverages its pan-European dangerous goods certification network to sustain contract renewals with BASF and Lanxess manufacturing sites. Bertschi AG dominates intermodal tank container movements across the Rhine-Alpine corridor, while Den Hartogh specializes in liquid bulk distribution to Benelux petrochemical clusters.
Europe chemical logistics encompasses the specialized transportation, storage, and handling of hazardous and non-hazardous chemical products under ADR, RID, and IMDG protocols, requiring temperature-controlled environments, stainless steel tank specifications, and sealed containment systems to prevent contamination or environmental release. The primary purpose is maintaining product integrity and regulatory compliance through multimodal chains connecting chemical producers to downstream manufacturing. Transportation services command the largest value share due to fuel surcharges and driver scarcity, while warehousing of specialty chemicals generates superior margins from climate-controlled vault requirements. Organic chemicals movements by road remain the volume backbone, though polymers rail freight is gaining share on Rotterdam-Antwerp-Ghent lanes.
REACH enforcement by ECHA and the EU Green Deal's sustainable transport mandates are tightening emissions standards for chemical freight, while ADR 2023 revisions impose stricter tank inspection intervals that reshape fleet replacement cycles. Germany's KBA and France's ANSM coordinate cross-border hazmat permitting, adding administrative layers to international movements. Stakeholders must monitor battery-electric and hydrogen truck pilot viability for chemical haulage, as zero-emission corridors will determine terminal access rights and contract eligibility across the next planning cycle.
Market Dynamics
The EU Green Deal's sustainable transport mandates are forcing fleet operators to restructure diesel-dependent road haulage networks before zero-emission corridor deadlines take effect.
Growth Catalysts
- Specialty Chemicals Demand:Pharmaceutical manufacturers in Germany and Belgium are expanding active ingredient sourcing, requiring temperature-controlled stainless steel tank movements with full batch traceability.
- REACH Compliance Services:ECHA documentation requirements create recurring revenue streams for logistics providers offering substance volume tracking and safety data sheet management.
- Rhine-Alpine Rail Modernization:Infrastructure upgrades between Rotterdam and Basel enable intermodal polymer movements that bypass road weight restrictions and driver hour limits.
Market Restraints
- Driver Scarcity:ADR-certified hazmat operators concentrate in Germany and the Netherlands, creating wage inflation that compresses margins on standard chemical haulage contracts.
- Tank Inspection Cycles:ADR 2023 revisions mandate shortened inspection intervals for pressure vessels, accelerating capital replacement schedules for fleet operators.
- Electrification Cost Barrier:Battery-electric and hydrogen truck platforms require depot charging infrastructure investments that smaller carriers cannot finance without consolidation.
Strategic Opportunities
- Benelux Petrochemical Integration:Antwerp-Rotterdam-Ghent clusters seek synchronized warehousing and just-in-time delivery services for downstream polymer processors.
- Carbon Border Adjustment Mechanism:CBAM reporting requirements create demand for embedded emissions tracking services across chemical import supply chains.
- Hydrogen Corridor Pilots:EU Green Deal funding for zero-emission freight routes offers first-mover terminal access rights to early fleet adopters in the Rhine-Ruhr corridor.
Industry Challenges
- Multimodal Synchronization:Chemical parks require precise rail-road-barge handoffs where delays in one mode cascade through temperature-sensitive product chains.
- Cross-Border Permitting:Germany's KBA and France's ANSM maintain divergent hazmat documentation standards that complicate international driver assignments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Chemical Logistics Market |
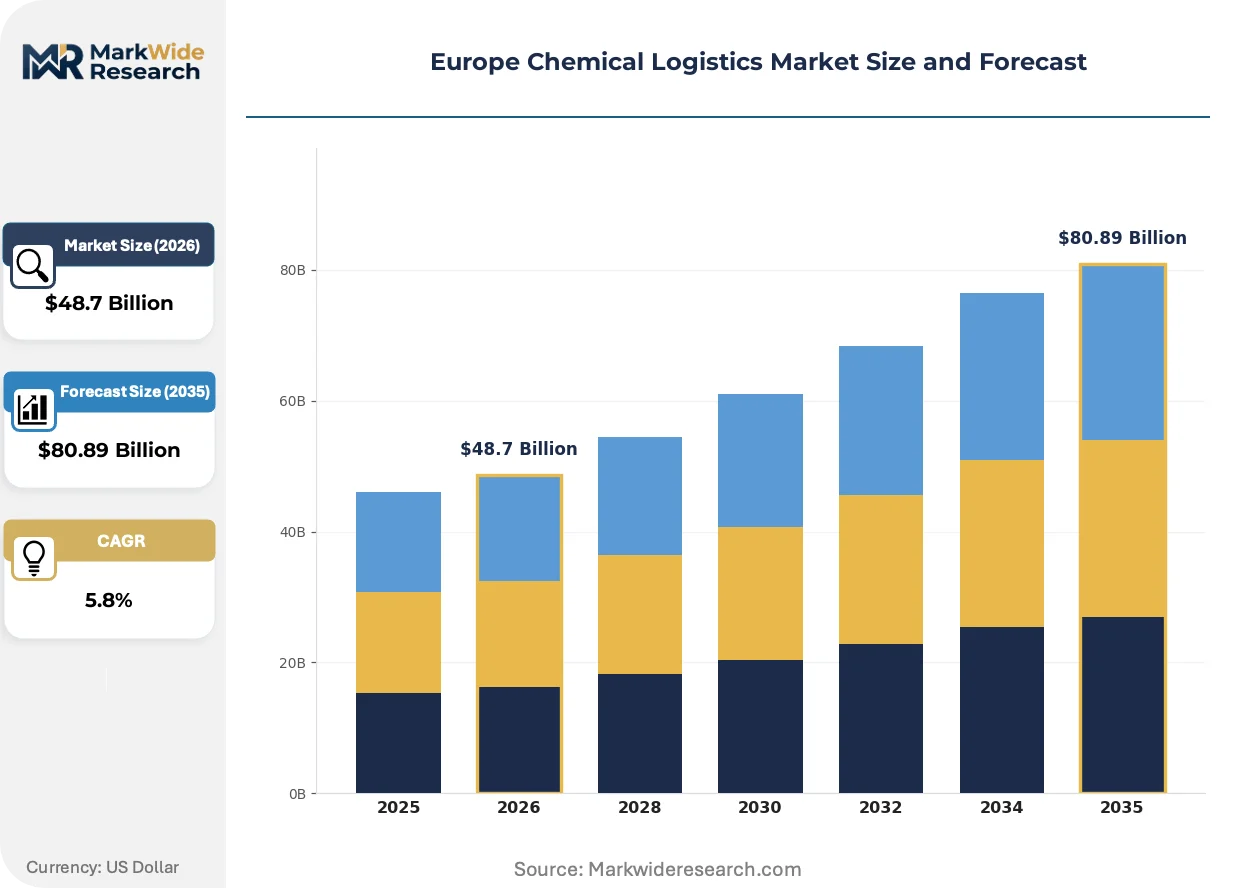
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Packaging, Distribution Material: Organic Chemicals, Inorganic Chemicals, Polymers, Specialty Chemicals End Use Industry: Pharmaceuticals, Agriculture, Paints & Coatings, Food & Beverage Delivery Mode: Road, Rail, Sea, Air |
| Companies Covered | DHL, DSV A/S, CEVA Logistics, XPO Logistics, Kuehne + Nagel, Bertschi AG, Den Hartogh, Hoyer, DB Schenker, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Chemical Logistics Market Emerging Trajectories
Digital freight platforms and alternative propulsion technologies are restructuring how chemical cargo moves across European corridors, with regulatory pressure accelerating adoption timelines beyond typical fleet replacement cycles.
Telematics-enabled tank monitoring is bifurcating the contract logistics market between premium providers offering real-time pressure and temperature visibility and commodity haulers competing on lane rates alone. BASF and Lanxess manufacturing sites now mandate sensor-equipped containers for high-value specialty chemicals. This technology compression is squeezing mid-tier operators who lack capital for connected fleet upgrades.
REACH enforcement by ECHA and the EU Green Deal's sustainable transport mandates are tightening emissions standards for chemical freight movements across member states. The F-Gas Regulation's phase-down schedules are pressuring refrigerated transport operators to retrofit or replace cooling units. Petrochemical clusters in Belgium and the Netherlands face the steepest compliance costs due to their reliance on temperature-controlled liquid bulk distribution.
Buyer consolidation among pharmaceutical manufacturers is compressing contract renewal cycles and demanding outcome-based logistics agreements with guaranteed temperature integrity. Traditional lane-rate bidding is giving way to total-cost-of-ownership evaluations that penalize temperature excursions. This procurement evolution is most visible in Germany, where Merck KGaA and Boehringer Ingelheim have consolidated chemical logistics spend under integrated tender structures.
Europe Chemical Logistics Market Segmentation
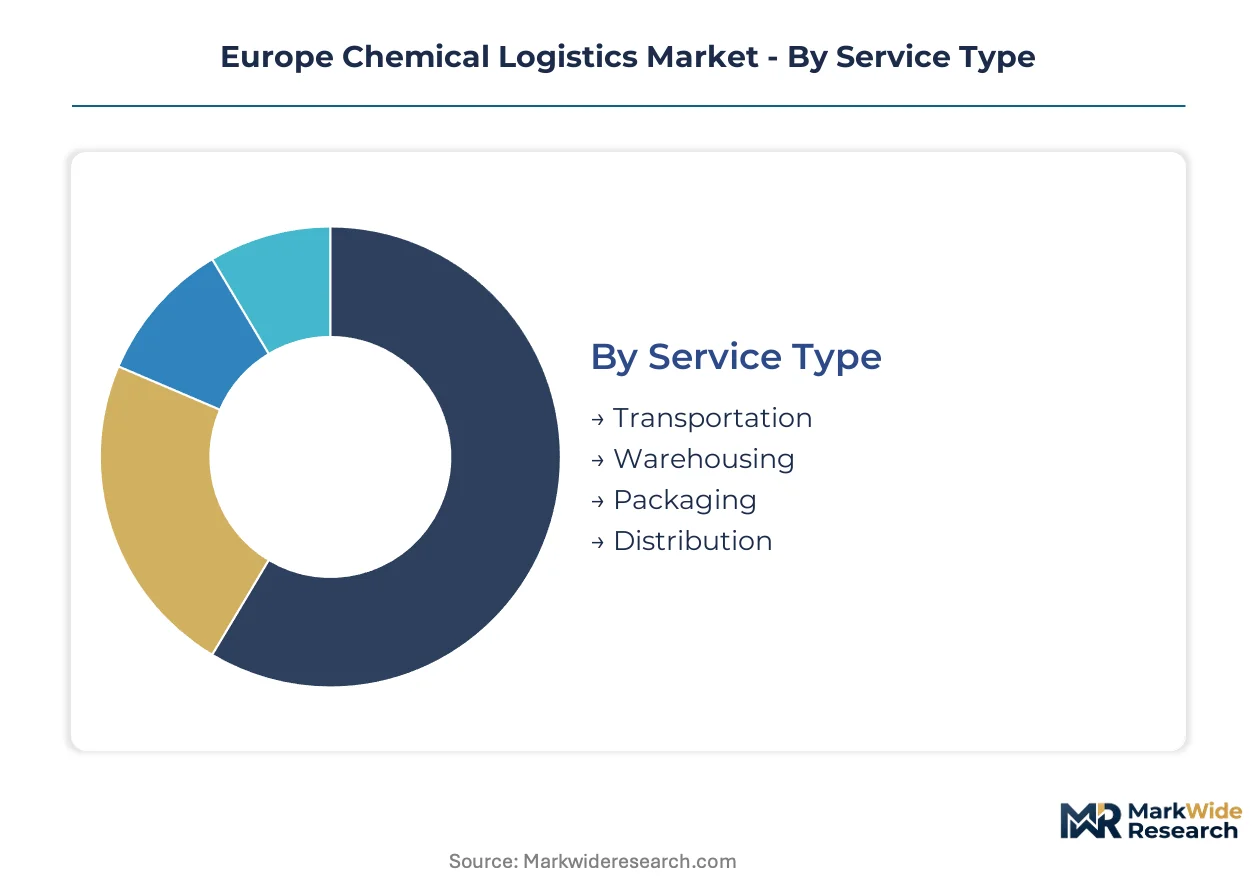
Chemical logistics segmentation reveals where capital deploys across temperature-sensitive supply chains. Margin pools concentrate in services requiring ADR certification and stainless steel containment, while material mix determines modal choice and regulatory burden.
Service Type:
Transportation commands the deepest margin pools due to fuel surcharges and specialized hazmat driver scarcity.
- Transportation:Road haulage of liquid bulk and temperature-controlled specialty chemicals generates premium rates from ADR-certified fleet requirements. Rhine-Ruhr chemical parks demand synchronized multimodal handoffs where delays cascade through batch-sensitive product chains.
- Warehousing:Climate-controlled vaults for pharmaceutical-grade chemicals produce superior margins from REACH documentation services and sealed containment infrastructure. Belgium and the Netherlands host concentrated demand from petrochemical clusters requiring just-in-time inventory positioning.
- Packaging:UN-certified drums and intermediate bulk containers for hazardous materials must comply with ADR pressure specifications. ECHA safety data sheet integration adds compliance layers to container selection.
- Distribution:Cross-border consolidation services face administrative friction from divergent KBA and ANSM hazmat permitting standards.
Transportation holds installed capacity. Warehousing is rotating up the share rankings.
Material:
Specialty chemicals concentrate value through temperature integrity requirements and batch traceability mandates.
- Organic Chemicals:Solvents and feedstock movements by road form the volume backbone across European corridors. Rotterdam-Antwerp lanes handle the densest flows for downstream polymer production.
- Inorganic Chemicals:Fertilizer and industrial salt distribution relies on rail-barge intermodal to bypass road weight restrictions. Rhine-Alpine modernization is expanding capacity for bulk mineral movements.
- Polymers:Pellet and resin freight is gaining modal share on dedicated rail corridors connecting Benelux production to German manufacturing. Temperature-controlled requirements are minimal, compressing margins versus liquid bulk.
- Specialty Chemicals:Active pharmaceutical ingredients and agrochemical intermediates require stainless steel tank specifications with full pressure and temperature telemetry. Merck KGaA and Boehringer Ingelheim mandate sensor-equipped containers for contract eligibility.
Organic chemicals holds installed capacity. Specialty chemicals is climbing the fastest.
End Use Industry:
Pharmaceutical procurement patterns are reshaping service specifications across all material categories.
- Pharmaceuticals:Active ingredient logistics demands continuous cold chain validation and REACH substance volume tracking. Germany and Belgium anchor demand from consolidated tender structures at major manufacturers.
- Agriculture:Seasonal fertilizer and pesticide distribution requires flexible fleet scaling around planting windows. Rail access to Black Sea port corridors is expanding for urea and ammonia movements.
- Paints & Coatings:Solvent-based product logistics faces F-Gas Regulation pressure on refrigerated transport units. Water-based formulation growth is reducing temperature control intensity.
- Food & Beverage:Food-grade chemical additives require segregated handling protocols and HACCP-aligned documentation. Benelux flavor and fragrance clusters generate concentrated demand.
Pharmaceuticals holds installed capacity. Food & Beverage is rotating up the share rankings.
Delivery Mode:
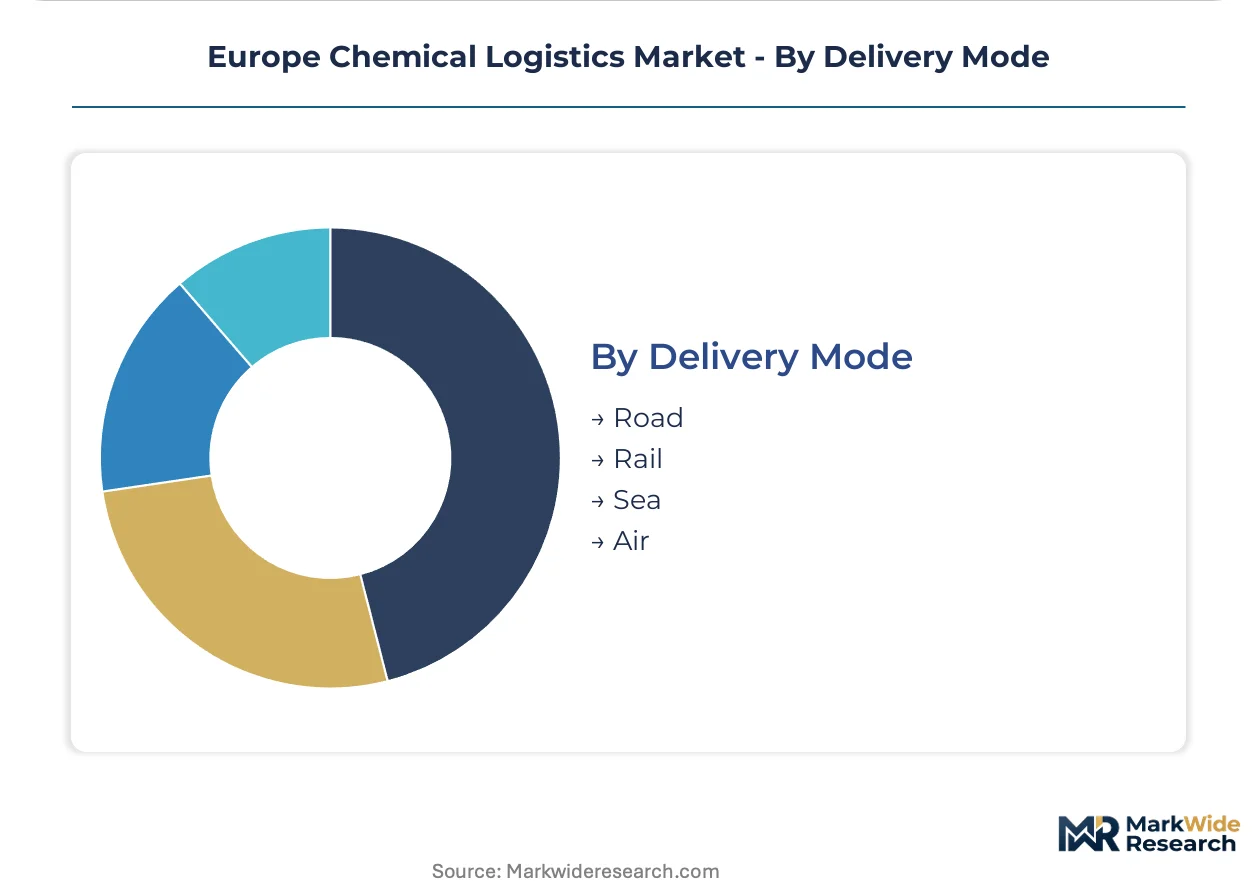
Road retains volume dominance while rail captures share on corridor modernization.
- Road:Flexible routing and door-to-door delivery sustain dominance for specialty chemicals and just-in-time pharmaceutical supply. Driver scarcity in Germany and the Netherlands is forcing wage premiums that compress margins.
- Rail:Bulk polymer and organic chemical movements benefit from Rotterdam-Basel infrastructure upgrades bypassing road restrictions. Intermodal tank container standardization is reducing transfer delays.
- Sea:Deep-sea liquid bulk and containerized chemicals concentrate at Rotterdam and Antwerp terminals. EU Green Deal emissions standards are pressuring vessel fuel transitions.
- Air:High-value pharmaceutical ingredients and emergency chemical shipments command extreme premiums for speed. Temperature excursion liability limits modal expansion.
Road holds installed capacity. Rail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing for ADR-certified hazmat movements while Poland absorbs cost-sensitive bulk chemical flows, creating a two-tier rate structure across European corridors.
Germany
Rhine-Ruhr chemical parks drive synchronized multimodal demand for specialty chemicals and pharmaceutical feedstocks. KBA enforces ADR 2023 tank inspection protocols that compress fleet replacement cycles. BASF's Ludwigshafen complex anchors liquid bulk logistics networks requiring stainless steel containment and full batch traceability.
Netherlands
Rotterdam-Antwerp petrochemical clusters generate dense polymer and organic chemical movements by rail and barge. EU Green Deal sustainable transport mandates accelerate zero-emission corridor pilots. The Port of Rotterdam's integrated tank terminals enable intermodal handoffs that bypass road weight restrictions.
Belgium
Antwerp-Ghent manufacturing zones concentrate demand for just-in-time polymer delivery and temperature-controlled pharmaceutical logistics. REACH compliance services create recurring revenue streams for providers offering substance volume tracking. Den Hartogh operates liquid bulk distribution networks serving Benelux downstream processors.
France
ANSM maintains hazmat documentation standards that diverge from German KBA protocols, adding administrative friction to cross-border driver assignments. Lyon and Paris pharmaceutical manufacturers expand active ingredient sourcing requiring cold chain validation. The F-Gas Regulation pressures refrigerated transport operators serving chemical corridors.
Switzerland
Basel's pharmaceutical and agrochemical headquarters demand precision logistics for high-value specialty chemicals with full pressure and temperature telemetry. Swissmedic alignment with EMA standards streamlines documentation for EU-border movements. Rhine-Alpine rail modernization connects Basel to Rotterdam terminals with expanded polymer capacity.
Europe Chemical Logistics Market Vendor Landscape
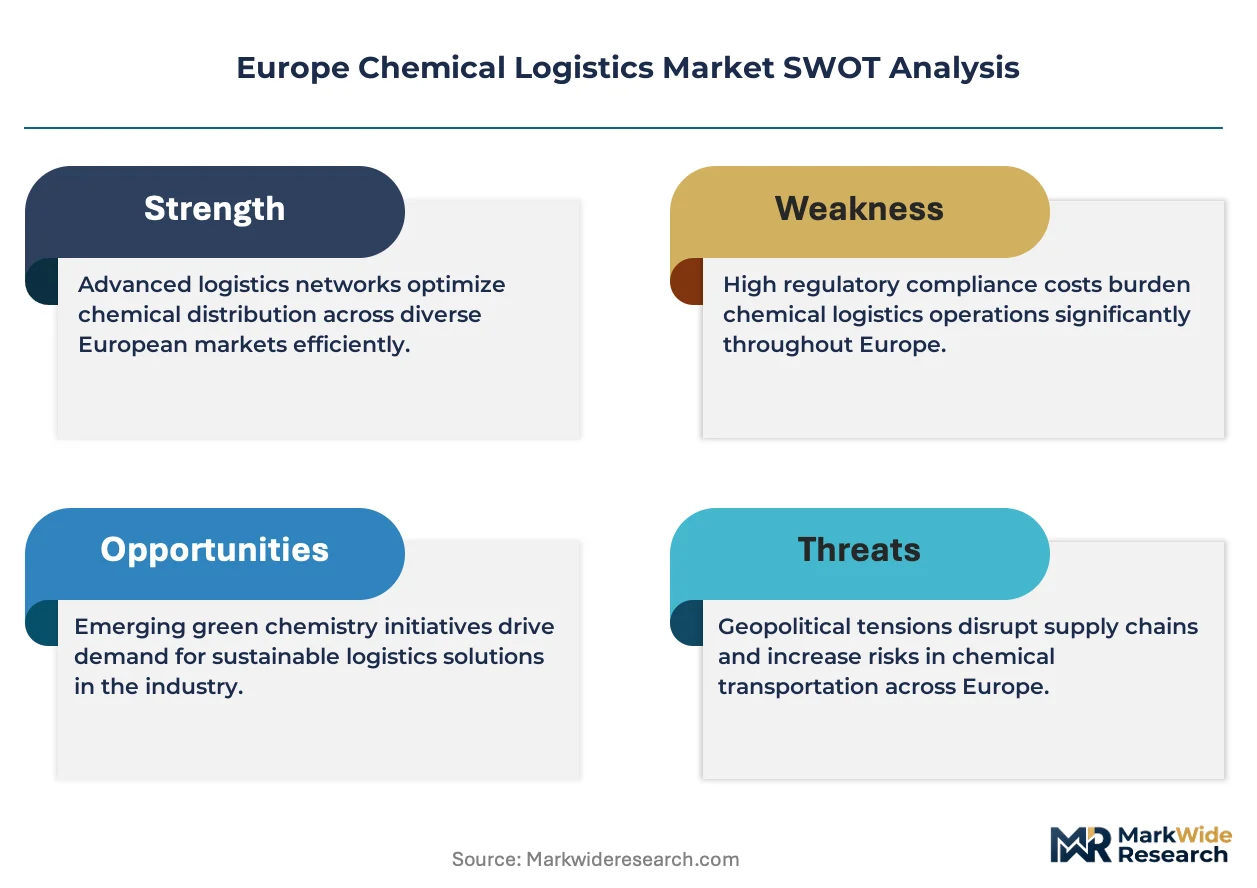
Technology leadership and cost leadership are held by different player archetypes across the European chemical logistics sector. Pan-European integrators with dangerous goods certification networks command premium contract terms from multinational chemical manufacturers. Regional tank container specialists and intermodal operators occupy distinct tiers based on corridor density and asset specificity. Consolidation pressure is intensifying as electrification costs force smaller carriers toward acquisition or alliance structures.
Among Germany-based logistics providers, DHL and DB Schenker exemplify the integrated network archetype with dangerous goods certification coverage spanning multiple manufacturing clusters. Bertschi AG represents the specialized intermodal segment with concentrated presence across Rhine-Alpine tank container movements. These three anchors illustrate how scale-driven certification breadth and corridor-specific asset density constitute alternative competitive positions in a market where ADR compliance and temperature integrity command pricing power.
| Leading Market Players |
|---|
| DHL |
| DSV A/S |
| CEVA Logistics |
| XPO Logistics |
| Kuehne + Nagel |
| Bertschi AG |
| Den Hartogh |
| Hoyer |
| DB Schenker |
| Others |
Supply Flow & Price Mechanics
Fleet scale economies in Germany and the Netherlands establish price floors across European chemical corridors, with larger ADR-certified operators capturing premium spreads while smaller carriers absorb cost compression from electrification mandates and driver wage inflation. Scale concentration in the Rhine-Ruhr corridor reinforces tiered pricing power, as integrated chemical parks demand synchronized multimodal handoffs that only capital-intensive networks can reliably deliver.
Pricing Analysis
Configured-to-order pricing for specialty chemical movements commands spreads of 40-60% above standard liquid bulk haulage, with stainless steel tank specifications and full temperature telemetry driving the premium tier. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and batch traceability intensity. Cost compression in standard chemical haulage is intensifying because ADR-certified driver scarcity forces wage premiums that erode margins on lane-rate contracts. Pharmaceutical manufacturers exhibit the lowest price sensitivity, prioritizing temperature integrity guarantees over per-kilometer rates, while commodity polymer processors remain highly price-sensitive and readily switch between road and rail modes.
Supply Chain Analysis
Germany and the Netherlands anchor liquid bulk chemical production and distribution, with Belgium serving as a critical consolidation node for Benelux petrochemical clusters. Raw material dependencies center on North Sea crude feedstocks, natural gas derivatives from Norwegian and Dutch fields, and imported specialty chemical precursors from Swiss and French manufacturing sites. Single-source vulnerability concentrates in ADR-certified driver pools, where Germany's KBA and France's ANSM maintain divergent hazmat permitting standards that restrict cross-border labor mobility. Distribution runs through Rotterdam-Antwerp terminal complexes, with intermodal tank container handoffs reducing road dependency for bulk polymer movements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's chemical logistics sector sits in early-cycle expansion, with EU Green Deal zero-emission corridor pilots creating first-mover terminal access rights that will reshape competitive positioning across the next fleet replacement cycle.
For Market Incumbents: Compound certification breadth across ECHA REACH documentation services and dangerous goods handling protocols to deepen switching costs among pharmaceutical manufacturers. Consolidate regional tank container fleets in the Rhine-Alpine corridor before electrification capital requirements force smaller competitors into distressed sales. Vertical integration into depot charging infrastructure for battery-electric and hydrogen truck pilots will secure zero-emission corridor eligibility as the EU Green Deal deadlines approach. For New Entrants and Emerging Players: Carbon Border Adjustment Mechanism embedded emissions tracking services represent a service-layer gap where incumbents under-serve chemical import supply chains. Target mid-tier polymer processors in Poland and Eastern Europe with cost-optimized intermodal solutions that bypass German driver scarcity. A go-to-market angle anchored in digital freight platforms with real-time tank telemetry can displace commodity haulers competing on lane rates alone. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among logistics providers offering REACH substance volume tracking and safety data sheet management services. Long-term viability across the next decade hinges on electrification readiness and corridor-specific asset density rather than geographic sprawl. Acquisition targets should prioritize regional tank container specialists with established Rhine-Alpine presence. The signal to watch is EU Green Deal funding disbursement velocity for hydrogen corridor pilots, which will determine which fleet operators secure terminal access rights before zero-emission mandates take effect.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Depot Charging Infrastructure | Secures zero-emission corridor eligibility under EU Green Deal terminal access rules. |
| REACH Compliance Service Expansion | Creates recurring revenue streams from ECHA substance volume tracking mandates. |
| Rhine-Alpine Rail Intermodal Investment | Bypasses German ADR driver scarcity and road weight restrictions for polymer movements. |
| Digital Freight Platform Deployment | Enables real-time temperature telemetry that pharmaceutical manufacturers now mandate. |
| Consolidation of Regional Tank Fleets | Builds scale economies before electrification capital barriers force smaller carrier exits. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with chemical plant managers, downstream pharmaceutical procurement leads, ADR-certified fleet operators, and intermodal terminal coordinators. Secondary validation drew from ECHA regulatory filings, Cefic chemical trade statistics, customs data on liquid bulk movements, and SEC disclosures from listed logistics providers. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the European chemical production base.
Across the analysis window, volume and value projections were derived from modeled segmentation across service type, material category, end-use industry, and delivery mode, with regional production hub intensity as an additional dimension. CAGRs were computed from historical trajectory analysis and forward-looking capacity utilization assumptions. Forecast inputs incorporated ADR 2023 tank inspection cycle impacts on fleet replacement schedules and EU Green Deal zero-emission corridor pilot timelines.
Material uncertainties — regulatory acceleration or delay in zero-emission mandates, abrupt shifts in ADR-certified driver availability, and Rhine water level volatility affecting barge capacity — sit outside the modeled envelope. Forecasts reflect assumptions about sustained pharmaceutical outsourcing trends and gradual electrification technology maturation. Recalibration cycles align with material shifts in ECHA enforcement intensity and EU Green Deal funding disbursement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
US Cross-Border Road Freight Transport Market
Logistics and Shipping
North America Sea Freight Forwarding Market
Logistics and Shipping
Vehicle Routing and Scheduling Market
Logistics and Shipping
Russia Freight and Logistics Market
Logistics and Shipping
Middle Mile Delivery Market
Logistics and Shipping
Netherlands Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Vietnam Express Delivery Services Market
Logistics and Shipping
Global Load Planning Services and Solutions Market
Logistics and Shipping
Asia-Pacific less-Than Container Load (LCL) Market
Logistics and Shipping
Peru Cold Chain Logistics Market
Logistics and Shipping
On-Demand Logistics Market
Logistics and Shipping
Philippines Freight and Logistics Market
Logistics and Shipping
Airfreight Forwarding Market
Logistics and Shipping
Germany Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Freight Brokerage Market
Logistics and Shipping
Real-Time Inventory-in-Transit Positioning Platforms Market