
 5G RAN Market | 2026-2036
5G RAN Market Size, Share, and Industry Trends Forecast 2026-2036
5G RAN Market Analysis
The direct-to-operator procurement channel is tilting toward multi-vendor Open RAN frameworks. Ericsson leverages its cloud-native portfolio to sustain European operator relationships. Huawei anchors Asian infrastructure rollouts despite geopolitical headwinds. Nokia competes through specialized massive MIMO radio units for dense urban environments.
5G Radio Access Network denotes the distributed base station architecture connecting user devices to core networks through gNodeB units operating across sub-6 GHz and mmWave spectrum bands, with beamforming and massive MIMO enabling gigabit throughput and sub-10 millisecond latency for industrial automation and immersive media. The deployment model dimension shows Cloud RAN capturing margin pools as operators virtualize baseband processing, while Open RAN disrupts incumbent hardware lock-in through standardized interfaces. Services revenue outpaces hardware growth as system integration complexity rises with multi-vendor interoperability requirements.
FCC spectrum auction rules and the EU 5G security toolbox constrain vendor selection for operators in North America and Europe, while India's TRAI mandates domestic sourcing thresholds for critical network elements. China's MIIT accelerates standalone 5G buildouts through coordinated spectrum allocation and infrastructure investment targets. Stakeholders must monitor Open RAN maturity timelines against operator capex cycles to calibrate portfolio bets between proprietary integrated stacks and disaggregated multi-vendor architectures.
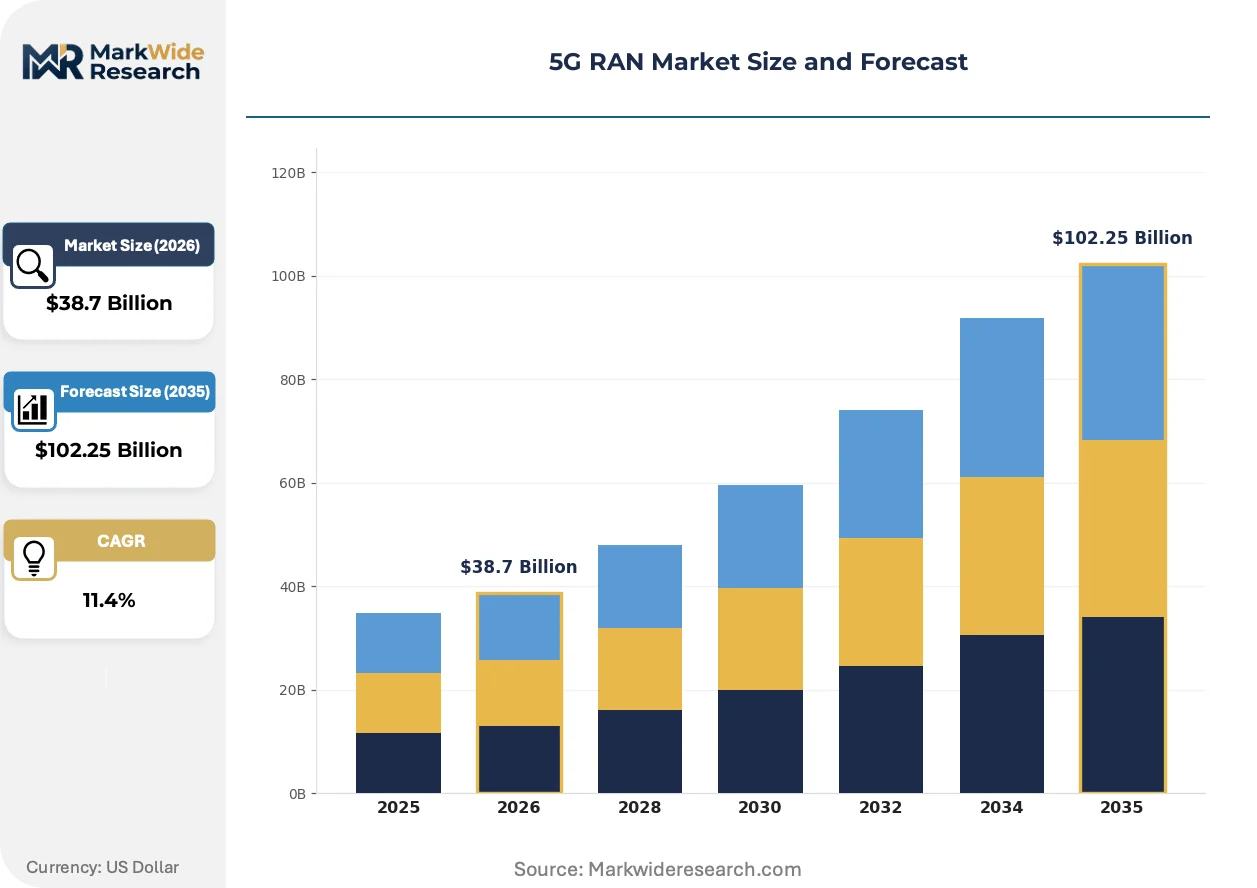
Market Dynamics
Cloud RAN virtualization is compressing proprietary hardware margins while Open RAN interoperability mandates from the FCC and EU's 5G security toolbox force vendor diversification across operator procurement cycles.
Growth Catalysts
- Smart manufacturing corridors:Germany's industrial automation belt demands sub-10 millisecond latency for robotic control systems, driving gNodeB density requirements in factory zones.
- EU 5G security toolbox:The framework's vendor diversification mandates accelerate multi-vendor Open RAN pilots among European operators seeking supply chain resilience.
- Massive MIMO beamforming:The technology enables gigabit throughput in dense urban environments, supporting immersive media and industrial automation use cases simultaneously.
Market Restraints
- mmWave propagation physics:Line-of-sight limitations and rain fade constrain outdoor coverage, restricting deployment to stadiums and fixed wireless access scenarios.
- Specialized RF engineering talent:Scarcity of engineers proficient in 3GPP Release 17 specifications and O-RAN Alliance interface standards extends integration timelines.
- Geopolitical vendor fragmentation:FCC spectrum auction rules and EU security certifications exclude certain Asian equipment suppliers from North American and European infrastructure bids.
Strategic Opportunities
- India's telecom infrastructure buildout:TRAI domestic sourcing thresholds for critical network elements create localized manufacturing partnerships for radio unit assembly.
- Standalone 5G core migration:Operators transitioning from non-standalone to standalone architectures require full stack replacement, opening systems integration service contracts.
- Private network slicing:Mining operations and port automation in South Korea's smart city clusters purchase dedicated spectrum blocks for mission-critical communications.
Industry Challenges
- Multi-vendor interoperability testing:O-RAN Alliance specification gaps between radio unit and distributed unit vendors delay field certification timelines.
- Legacy 4G infrastructure co-existence:Dynamic spectrum sharing complexity increases baseband processing overhead and power consumption at cell sites.
- Supply chain reconfiguration:Sub-6 GHz power amplifier component shortages from concentrated semiconductor foundry capacity extend radio unit lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G RAN Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Distributed RAN, Centralized RAN, Cloud RAN, Open RAN Industry Vertical: Telecommunications, Transportation, Healthcare, Manufacturing Component: Hardware, Software, Services, Infrastructure End User: Telecom Operators, Enterprises, Government, Others |
| Companies Covered | ZTE, T-Mobile US, Huawei, AT&T, Verizon, Ericsson, Samsung, CEVA, Nokia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G RAN Market Emerging Trajectories
Virtualization of baseband processing functions is redistributing value from proprietary hardware stacks toward software-defined orchestration layers and multi-vendor integration services.
Intelligent RAN automation is digitizing network optimization workflows previously requiring manual drive testing and parameter tuning. Tier-1 operators in South Korea deploy machine learning-based interference management across urban macro cells. The shift is digitizing operational expenditure structures and compressing mean-time-to-repair metrics for coverage anomalies.
The EU 5G security toolbox's vendor diversification requirements are fragmenting traditional single-supplier relationships. European operators must now certify secondary radio unit sources for critical infrastructure eligibility. German and French carriers accelerate parallel qualification programs for massive MIMO equipment ahead of auctioned spectrum deployment deadlines.
Direct-to-operator procurement is displacing systems integrator intermediaries in mature markets. North American carriers now contract specialized Open RAN software vendors for cloud-native stack components separately from radio hardware. The unbundling concentrates in markets where FCC rules have already forced vendor diversification through security certification requirements.
5G RAN Market Segmentation
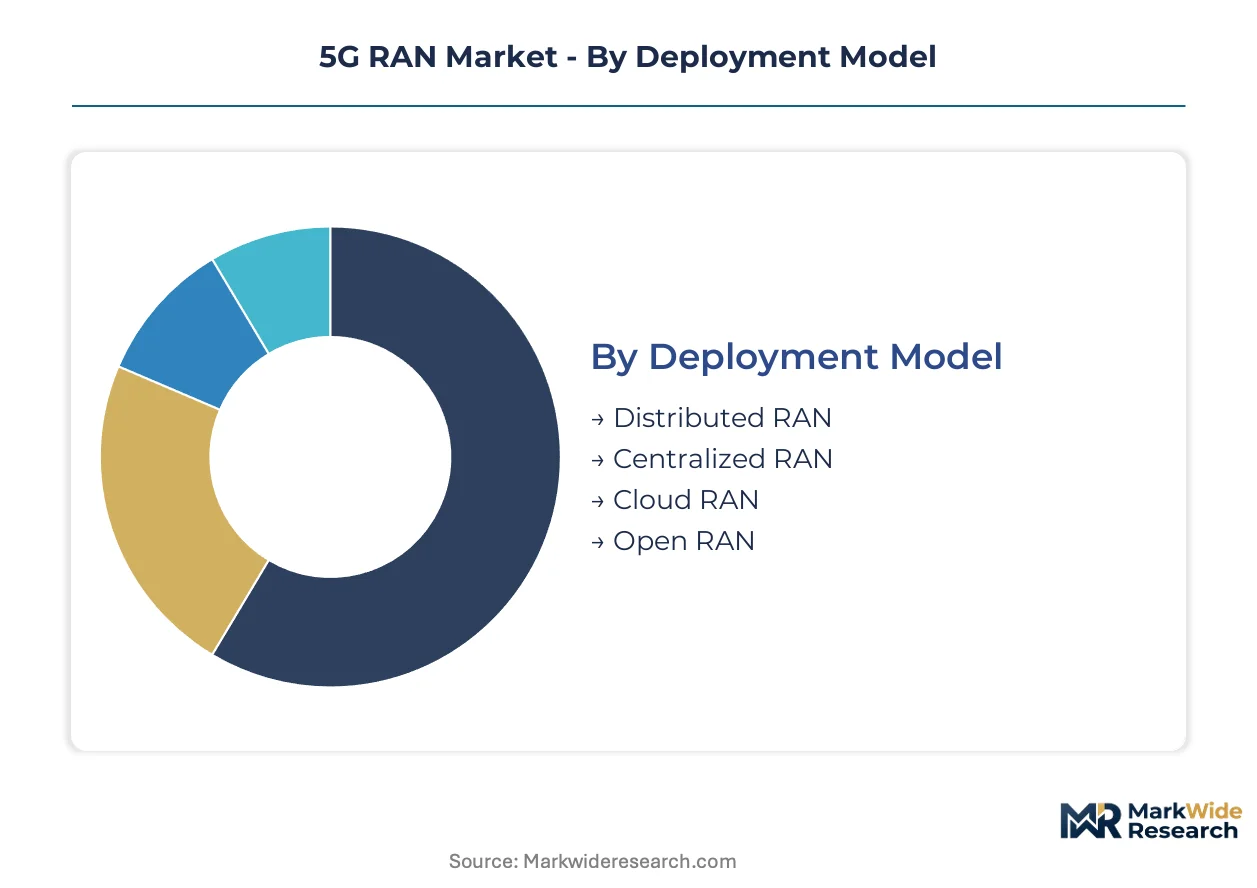
5G RAN market segmentation reveals distinct service intensity profiles across deployment architectures and customer types. Each category carries differentiated integration complexity, recurring revenue potential, and vendor relationship structures that shape commercial strategies.
Deployment Model:
After-sales service intensity varies dramatically across deployment architectures, with disaggregated models demanding continuous multi-vendor orchestration support while integrated stacks require less frequent but deeper specialist intervention.
- Cloud RAN:Virtualizes baseband processing functions onto commercial-off-the-shelf servers, shifting value toward software orchestration layers. Operators in Germany's industrial automation belt deploy Cloud RAN to achieve sub-10 millisecond latency for robotic control systems, requiring ongoing platform engineering support.
- Open RAN:Disaggregates radio units, distributed units, and centralized units through standardized O-RAN Alliance interfaces, mandating multi-vendor interoperability testing throughout operational life. South Korean smart city clusters pilot Open RAN to diversify supplier bases under vendor neutrality mandates, generating sustained systems integration service contracts.
- Distributed RAN:Maintains traditional baseband-radio co-location with proprietary interfaces, limiting service intensity to periodic hardware maintenance and software upgrades.
- Centralized RAN:Pools baseband resources across multiple cell sites through fronthaul concentration, requiring specialized transport network engineering support.
By volume, Distributed RAN leads among incumbent operators. By growth pace, Open RAN is gaining share fastest as regulatory diversification mandates expand.
Industry Vertical:
Application-specific performance requirements drive divergent procurement patterns across verticals, with manufacturing and transportation demanding deterministic latency guarantees that telecommunications and healthcare rarely require.
- Manufacturing:Smart factory deployments require guaranteed sub-10 millisecond latency for closed-loop robotic control and AGV coordination. Germany's automotive production corridors represent concentrated demand zones where private network slicing contracts bundle radio infrastructure with operational technology integration services.
- Telecommunications:Public mobile networks prioritize spectral efficiency and coverage density over deterministic performance, with India's infrastructure buildout zones driving volume procurement of massive MIMO equipment for subscriber capacity expansion.
- Transportation:Connected vehicle infrastructure and port automation systems demand high-reliability low-latency communications for safety-critical coordination.
- Healthcare:Remote surgery and patient monitoring applications require consistent quality-of-service guarantees with specialized security certifications.
Telecommunications generates the largest absolute revenue pool. Manufacturing demonstrates the steepest expansion trajectory as Industry 4.0 adoption accelerates.
Component:
Margin structures invert across the hardware-software-services spectrum, with proprietary radio units capturing upfront value while integration services extract recurring revenue over extended deployment lifecycles.
- Services:Systems integration, multi-vendor interoperability certification, and ongoing network optimization constitute the fastest-expanding revenue category. Complexity rises with Open RAN maturity timelines as operators navigate O-RAN Alliance specification gaps between radio unit and distributed unit vendors.
- Software:Cloud-native stack components including RAN intelligent controllers and orchestration platforms redistribute value from hardware toward programmable layers. North American carriers contract specialized vendors separately from radio hardware under FCC-mandated diversification frameworks.
- Hardware:Massive MIMO radio units, baseband processing equipment, and antenna systems face margin compression from virtualization trends.
- Infrastructure:Cell site construction, power systems, and transport backhaul represent capital-intensive foundation layers with limited differentiation.
Hardware dominates current procurement value. Services are climbing the fastest as multi-vendor architectures proliferate.
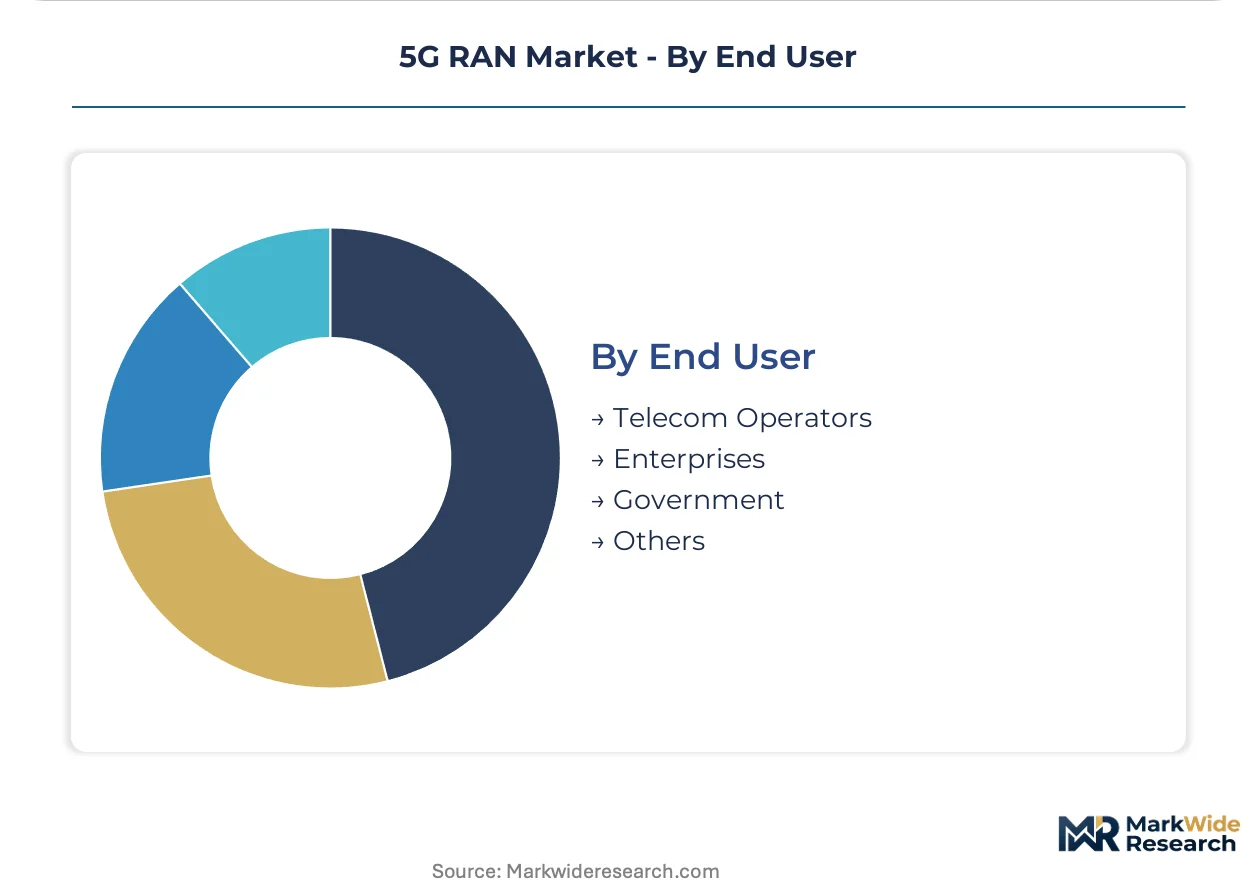
End User:
Customer type determines contract structures, with telecom operators favoring long-term managed service arrangements while enterprises increasingly procure dedicated private network slices.
- Telecom Operators:Public network deployers concentrate procurement volume through multi-year framework agreements with incumbent vendors. European operators accelerate parallel qualification programs for secondary radio unit sources under EU 5G security toolbox diversification requirements.
- Enterprises:Mining operations, port authorities, and industrial conglomerates purchase dedicated spectrum blocks for mission-critical communications. South Korea's smart city clusters lead enterprise adoption through coordinated private network slicing initiatives.
- Government:Defense and public safety networks impose stringent security certification requirements that constrain vendor eligibility.
- Others:Neutral host providers and venue owners deploy infrastructure for wholesale capacity arrangements.
Telecom Operators account for the dominant share of current deployments. Enterprises represent the most rapid growth channel as vertical-specific applications mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with German industrial automation deployers while Indian volume buyers extract procurement leverage through domestic sourcing mandates. Operators in Seoul and Stuttgart pay premiums for sub-10 millisecond latency guarantees. Volume discounts dominate procurement in Mumbai and Delhi infrastructure corridors.
Germany
Automotive production corridors in Bavaria and Baden-Württemberg drive dense gNodeB deployments for robotic control systems. The EU 5G security toolbox mandates vendor diversification for critical infrastructure eligibility. Stuttgart's smart factory clusters purchase private network slices with guaranteed latency specifications.
United States
FCC spectrum auction rules constrain vendor selection for national carriers seeking C-band and mmWave licenses. Verizon and AT&T accelerate standalone 5G core migration across urban markets. Dense urban environments in New York and Los Angeles deploy massive MIMO radio units for subscriber capacity.
India
TRAI domestic sourcing thresholds for critical network elements reshape procurement toward localized radio unit assembly. Reliance Jio and Bharti Airtel expand infrastructure buildout zones across Maharashtra and Gujarat. Mumbai and Delhi telecom corridors drive volume procurement of sub-6 GHz equipment.
South Korea
Smart city clusters in Seoul Capital Area and Busan-Ulsan purchase dedicated spectrum blocks for mission-critical communications. The government's private network slicing initiatives accelerate enterprise adoption beyond public mobile services. Daegu-Gyeongbuk industrial zones deploy intelligent RAN automation for manufacturing coordination.
China
MIIT accelerates standalone 5G buildouts through coordinated spectrum allocation and infrastructure investment targets. Yangtze River Delta manufacturing hubs deploy cloud-native RAN architectures for industrial automation. Shanghai and Shenzhen operators virtualize baseband processing onto commercial-off-the-shelf server infrastructure.
5G RAN Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the radio unit and semiconductor layers. The vendor base organizes around three strategic archetypes: integrated stack providers with cloud-native portfolios, disaggregated Open RAN specialists, and semiconductor IP licensors. Consolidation pressure intensifies as FCC and EU security certifications disqualify certain suppliers from Western infrastructure bids. Competitive moves center on multi-vendor interoperability certification programs and geographic pivoting toward unconstrained procurement markets.
Within the integrated platform tier, Ericsson and Nokia exemplify European operators' preferred vendor relationships under security toolbox diversification requirements. Huawei occupies a position anchoring Asian infrastructure rollouts despite Western market exclusions. Samsung sits within the diversified supplier base serving South Korean domestic carriers and select export markets. These three represent contrasting geographic positioning strategies amid regulatory fragmentation.
| Leading Market Players |
|---|
| ZTE |
| T-Mobile US |
| Huawei |
| AT&T |
| Verizon |
| Ericsson |
| Samsung |
| CEVA |
| Nokia |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's power amplifier foundries is compressing component pricing while simultaneously eroding supplier willingness to expand capacity for sub-6 GHz radio units, creating a feedback loop where procurement leverage concentrates with volume buyers in India's infrastructure buildout zones.
Pricing Analysis
Configured-to-order pricing for Cloud RAN orchestration platforms commands substantial premiums over standard massive MIMO radio unit catalogs. The dominant structure runs through project-based systems integration contracts bundling hardware, software, and multi-vendor interoperability certification. Price differentiation rests on O-RAN Alliance certification tier and vertical integration depth of the vendor stack. Cost compression in proprietary hardware tiers is intensifying because virtualization shifts value toward software layers. Telecom operators in Germany's industrial automation belt demonstrate the least price sensitivity due to latency guarantee requirements, while neutral host providers in dense urban markets exhibit acute sensitivity to per-unit radio costs.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for North American operators seeking C-band equipment. Geographic concentration centers on China for power amplifier semiconductors, South Korea for advanced antenna substrates, and Taiwan for baseband processing silicon. Raw material dependencies draw from gallium nitride wafers, high-frequency laminates, and precision RF connectors. Single-source vulnerability persists for O-RAN Alliance-compliant distributed unit chipsets. Distribution runs through direct-to-operator procurement channels displacing systems integrator intermediaries in markets where FCC security certification requirements have already forced vendor diversification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
5G RAN infrastructure sits in early-cycle expansion as standalone 5G core migration and private network slicing adoption accelerate deployment velocity beyond initial non-standalone coverage builds.
For Market Incumbents: Insulate proprietary hardware margins through accelerated Cloud RAN software portfolio development and selective backward integration into semiconductor IP licensing. The threat from disaggregated Open RAN specialists eroding integrated stack value requires defensive certification investment in O-RAN Alliance interoperability programs. Priority leverage rests on deepening relationships with European operators navigating EU 5G security toolbox diversification mandates through parallel qualification support for secondary radio unit sources. For New Entrants and Emerging Players: Pursue white-space opportunities in intelligent RAN automation software and multi-vendor systems integration services for South Korean smart city clusters. The most penetrable segment comprises specialized orchestration platforms for private network slicing contracts in mining and port automation verticals. A direct go-to-market angle targeting enterprise procurement officers outside traditional telecom operator channels bypasses incumbent vendor lock-in. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Open RAN software vendors with multi-year managed service contracts tied to interoperability certification obligations. Long-term viability over the next decade favors acquisition targets possessing O-RAN Alliance specification expertise and established operator relationships in regulatory-constrained Western markets. The critical inflection signal to monitor is Open RAN maturity timelines against operator capex cycle synchronization.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Stack Development | Virtualized baseband processing captures margin pools shifting from proprietary hardware toward software orchestration layers. |
| O-RAN Alliance Certification Investment | Interoperability qualification opens procurement access to European operators under EU 5G security toolbox diversification mandates. |
| Private Network Slicing Partnership | Enterprise spectrum purchases in South Korea's industrial zones generate dedicated infrastructure contracts beyond public mobile services. |
| Domestic Manufacturing Localization | TRAI sourcing thresholds in India compel radio unit assembly partnerships for critical network element eligibility. |
| Intelligent RAN Automation Platform | Machine learning-based interference management digitizes operational expenditure structures for Tier-1 operators in dense urban deployments. |
Methodological Framework
A spread of perspectives from network infrastructure procurement directors, radio unit engineering leads, systems integration project managers, and regulatory compliance officers converged on the working assumptions. Primary interviews combined with secondary validation from 3GPP release documentation, O-RAN Alliance interface specifications, FCC spectrum auction records, and EU 5G security toolbox implementation guidance. Bottom-up triangulation across deployment model segmentation and top-down cross-checks against operator capex disclosure patterns anchored the analytical framework.
Demand-supply balance dynamics shaped the forecast architecture across the analysis window. Segmentation dimensions modeled include deployment architecture, industry vertical application, component category, and end-user type. CAGRs derived from weighted operator deployment timelines, Open RAN maturity curve assumptions, and regional regulatory implementation pace. Industry-specific inputs incorporated gNodeB density requirements for sub-10 millisecond latency zones and domestic sourcing threshold compliance costs.
Sensitivities concentrate around O-RAN Alliance specification gap resolution timelines, semiconductor foundry capacity allocation shifts, and geopolitical vendor exclusion list expansions. Forecasts reflect documented assumptions subject to revision triggers in regulatory certification requirements and operator technology migration decisions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
United Kingdom Telecom Market
Telecommunications
Sri Lanka Telecom Tower Market
Telecommunications
Optical Network Terminal (ONT) Equipment Market
Telecommunications
Global LTE Market
Telecommunications
Asia Pacific Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Asia Pacific Telecom Expense Management Market
Telecommunications
Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Private Branch Exchange Market
Telecommunications
Germany Critical Communication Market
Telecommunications
Voice Over LTE (Volte) Market
Telecommunications
Czech Republic Telecom Market
Telecommunications
Japan 5G Small Cell Market
Telecommunications
Global Policy Management in Telecom Market
Telecommunications
Argentina ICT Market
Telecommunications
Singapore MVNO Market
Telecommunications
Italy Telecom Market