
 Global Telecom Analytics Market | 2026-2036
Global Telecom Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Telecom Analytics Market Foresight
The EU AI Act is shifting procurement criteria for telecom analytics platforms across European mobile network operators. Oracle Corporation leverages its cloud infrastructure stack to anchor large-scale churn prediction deployments for tier-one carriers. SAP SE differentiates through embedded revenue assurance modules that integrate directly with billing systems. IBM Corporation competes in the fraud analytics niche where real-time transaction scoring demands sub-millisecond latency.
Telecom analytics encompasses the computational processing of subscriber, network, and operational data to generate actionable intelligence for telecommunications providers. The discipline applies statistical modeling, machine learning inference, and streaming data architectures to monitor Quality of Service metrics, detect anomalous usage patterns, and optimize radio access network resource allocation. Customer analytics commands the largest current revenue pool as operators battle retention costs in saturated subscriber markets. Cloud-based deployment models represent the fastest-expanding structural category, displacing on-premises installations as hyperscale elasticity becomes essential for processing petabyte-scale call detail records and signaling traffic. Network analytics retains durable growth momentum where 5G standalone core deployments generate exponentially richer telemetry streams requiring real-time visualization.
The Federal Communications Commission in the United States enforces outage reporting mandates that compel operators to invest in predictive network analytics for infrastructure resilience. India's Telecom Regulatory Authority imposes quality-of-service benchmarks that drive demand for service quality analytics platforms capable of continuous compliance monitoring. The International Organization for Standardization publishes ISO/IEC 27001 frameworks that shape data governance requirements for subscriber analytics pipelines. Stakeholders must evaluate whether their analytics architectures can absorb forthcoming edge computing telemetry volumes without compromising latency thresholds for automated network remediation.
Market Dynamics
5G standalone core deployments are generating petabyte-scale telemetry streams that force mobile network operators to rebuild analytics architectures for real-time edge processing, compressing procurement cycles for cloud-native platforms.
Growth Catalysts
- EU AI Act transparency mandates:European operators must deploy explainable algorithms for automated network management, accelerating replacement of opaque legacy systems with auditable machine learning pipelines.
- India TRAI quality-of-service benchmarks:Continuous compliance monitoring requirements drive carrier investment in service quality analytics platforms that flag threshold breaches before penalties trigger.
- Edge computing telemetry proliferation:Radio access network densification multiplies sensor endpoints, creating demand for distributed analytics architectures that process data closer to generation points.
Market Restraints
- Specialized data engineering talent scarcity:Shortage of professionals combining telecommunications domain expertise with streaming data architecture skills inflates implementation timelines and service costs.
- Hyperscale cloud concentration risk:Dependence on three dominant infrastructure providers for elastic compute creates vendor lock-in exposure and limits negotiation leverage for tier-two carriers.
- Subscriber data localization requirements:India's data protection framework and similar national regimes fragment analytics workloads across jurisdictional boundaries, duplicating infrastructure spend.
Strategic Opportunities
- Brazilian 5G mid-band auction aftermath:New market entrants and incumbent Claro, TIM, and Vivo require churn prediction and revenue assurance analytics to compete in freshly liberalized spectrum allocations.
- ISO/IEC 27001 certification differentiation:Analytics vendors achieving information security management certification gain preferred vendor status with operators processing sensitive subscriber financial data.
- Digital twin convergence with network analytics:Integration of virtualized network replicas with real-time telemetry streams enables predictive maintenance before physical infrastructure degrades.
Industry Challenges
- Legacy billing system integration complexity:Revenue assurance analytics must interface with decades-old mainframe architectures, requiring costly middleware development and extended deployment phases.
- Sub-millisecond latency certification for fraud scoring:Real-time transaction validation demands specialized hardware acceleration that extends procurement and testing cycles beyond standard software deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Telecom Analytics Market |
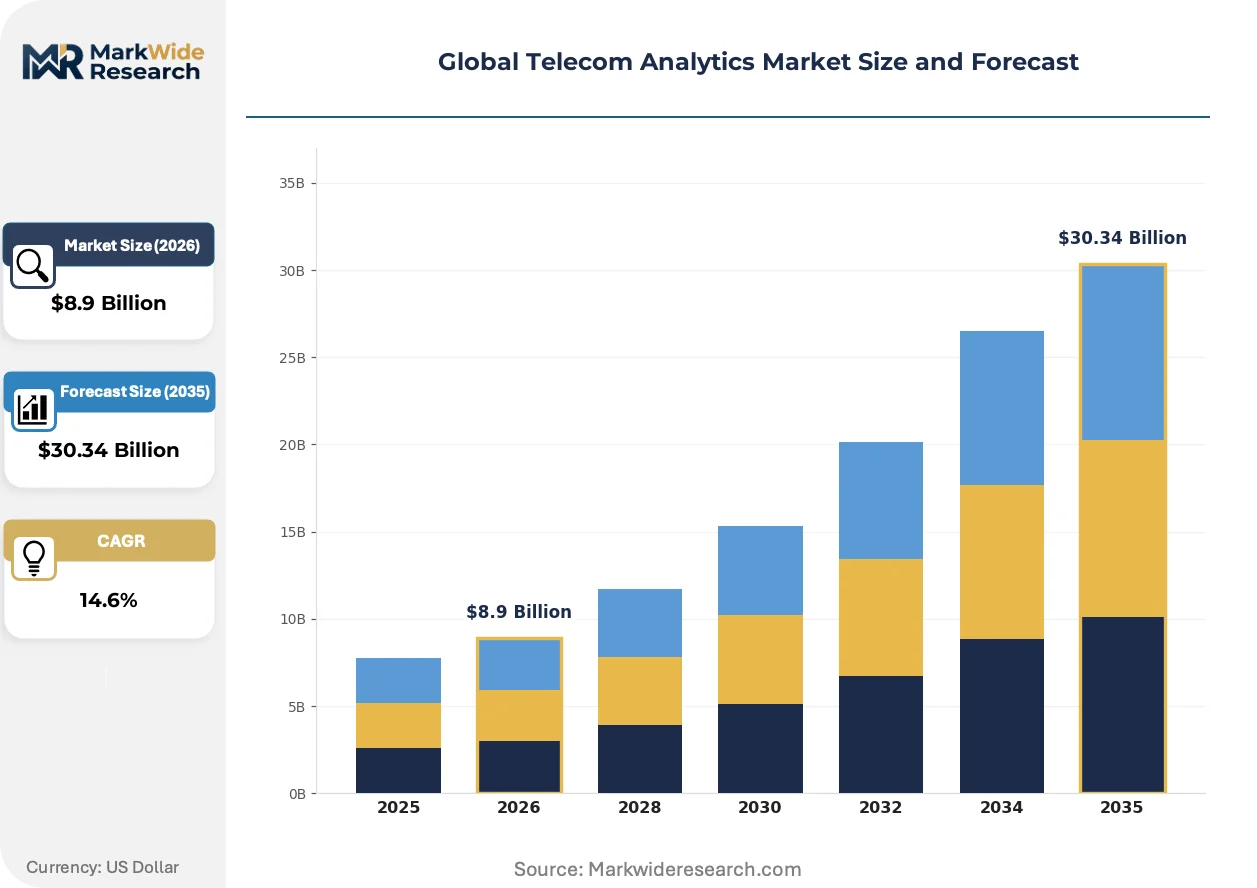
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $30.34 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Customer Analytics, Network Analytics, Fraud Analytics, Revenue Analytics, Service Quality Analytics Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services Use Case: Churn Prediction, Network Optimization, Customer Segmentation, Predictive Maintenance, Marketing Campaigns End User Type: Mobile Network Operators, Internet Service Providers, Infrastructure Vendors, Research Firms |
| Companies Covered | Oracle Corporation, IBM Corporation, SAP SE, Cisco Systems Inc., Accenture plc, Adobe Inc., Teradata Corporation, TIBCO Software Inc., Huawei Technologies Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Telecom Analytics Market Shifts & Advancements
Artificial intelligence inference is migrating from centralized data lakes toward radio access network edges, compressing response times for automated remediation while fragmenting vendor competitive positions between cloud-native and telco-optimized stacks.
Generative AI is automating root cause analysis in network operations centers, interpreting unstructured alarm logs and correlating anomalies across multi-vendor infrastructure. Tier-one carriers in Germany and South Korea are piloting these systems to reduce mean-time-to-resolution for cell site outages. The technology is automating tier-one support escalation decisions that previously required human engineering judgment.
The EU AI Act's risk classification framework is compelling European operators to document algorithmic decision pathways for credit scoring and service denial systems. This regulatory pressure is reshaping procurement specifications to prioritize interpretable models over black-box neural networks with marginal accuracy advantages. Network analytics vendors serving Deutsche Telekom, Orange, and Telefónica are accelerating explainable AI roadmaps to maintain eligibility.
Consumption patterns are shifting from perpetual software licenses toward usage-based analytics subscriptions tied to processed data volumes. Indian operators Reliance Jio and Bharti Airtel are negotiating contracts where fees scale with petabytes of call detail records ingested monthly rather than fixed seat counts. This model aligns vendor incentives with customer data growth trajectories while transferring infrastructure elasticity risk to platform providers.
Global Telecom Analytics Market Segmentation
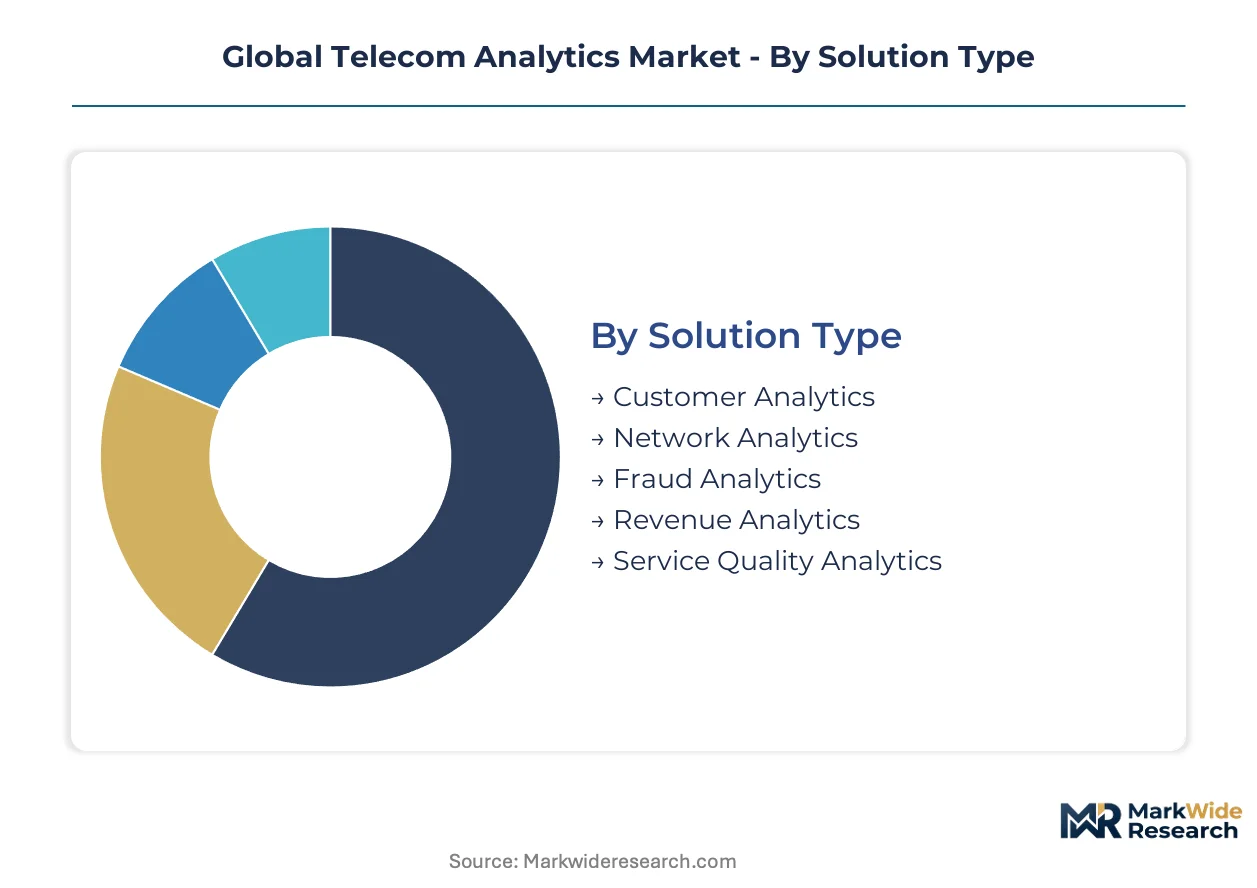
Telecom analytics procurement diverges sharply between volume-driven customer retention platforms and premium network intelligence systems. Operators allocate budgets across solution types, deployment architectures, use case priorities, and end-user categories based on infrastructure maturity and competitive pressure intensity.
Solution Type:
Customer analytics commands the largest revenue pool while network analytics captures the steepest expansion trajectory as 5G standalone cores proliferate.
- Customer Analytics:Subscriber behavior modeling platforms process call detail records, usage patterns, and billing histories to flag at-risk accounts. Indian carriers Reliance Jio and Bharti Airtel deploy these systems to combat churn in saturated metropolitan markets where acquisition costs exceed retention spend by multiples.
- Network Analytics:Real-time telemetry processing from radio access networks, core infrastructure, and transport layers enables automated resource allocation. European operators under EU AI Act mandates prioritize explainable algorithms for fault detection and self-healing orchestration.
- Fraud Analytics:Real-time transaction scoring identifies subscription fraud, international revenue share fraud, and SIM box bypass schemes.
- Revenue Analytics:Billing reconciliation and leakage detection systems interface with legacy mainframe architectures to capture unbilled usage.
- Service Quality Analytics:Continuous compliance monitoring platforms track TRAI-mandated quality-of-service thresholds in India and FCC outage reporting requirements in the United States.
Today's leader: Customer Analytics. Tomorrow's challenger: Network Analytics.
Deployment Model:
Cloud-native architectures displace on-premises installations as petabyte-scale call detail record processing demands hyperscale elasticity.
- On-Premises:Legacy installations persist where data localization mandates or security classifications prohibit external infrastructure. Tier-one carriers in regulated jurisdictions maintain captive data centers for subscriber financial records.
- Cloud-Based:Elastic compute and storage resources scale with signaling traffic volumes without capital-intensive hardware procurement. Indian operators negotiate usage-based contracts tied to monthly petabyte ingestion rather than fixed licensing.
- Hybrid:Sensitive subscriber data remains on-premises while compute-intensive model training leverages public cloud burst capacity.
- Managed Services:Outsourced platform operation transfers talent scarcity risk to vendors with specialized telecommunications data engineering expertise.
Cloud-Based deployments expand most quickly. Hybrid architectures retain durable relevance where sovereignty constraints bite hardest.
Use Case:
Churn prediction absorbs the largest implementation spend while predictive maintenance climbs fastest as 5G infrastructure densifies.
- Churn Prediction:Machine learning models score subscriber propensity to terminate service based on usage degradation, payment delays, and competitor switching signals. Mobile network operators in Brazil's freshly liberalized mid-band spectrum environment deploy these systems to defend subscriber bases against new market entrants.
- Network Optimization:Dynamic radio resource management algorithms balance load across cells based on real-time demand patterns and quality-of-service requirements.
- Customer Segmentation:Clustering algorithms group subscribers by value, behavior, and propensity for targeted tariff and service bundling.
- Predictive Maintenance:Equipment failure forecasting from sensor telemetry reduces mean-time-to-repair and capitalizes on digital twin convergence opportunities.
- Marketing Campaigns:Next-best-action engines personalize promotional offers across digital channels based on individual subscriber profiles.
Churn Prediction dominates current procurement. Predictive Maintenance represents the steepest growth vector through the forecast window.
End User Type:
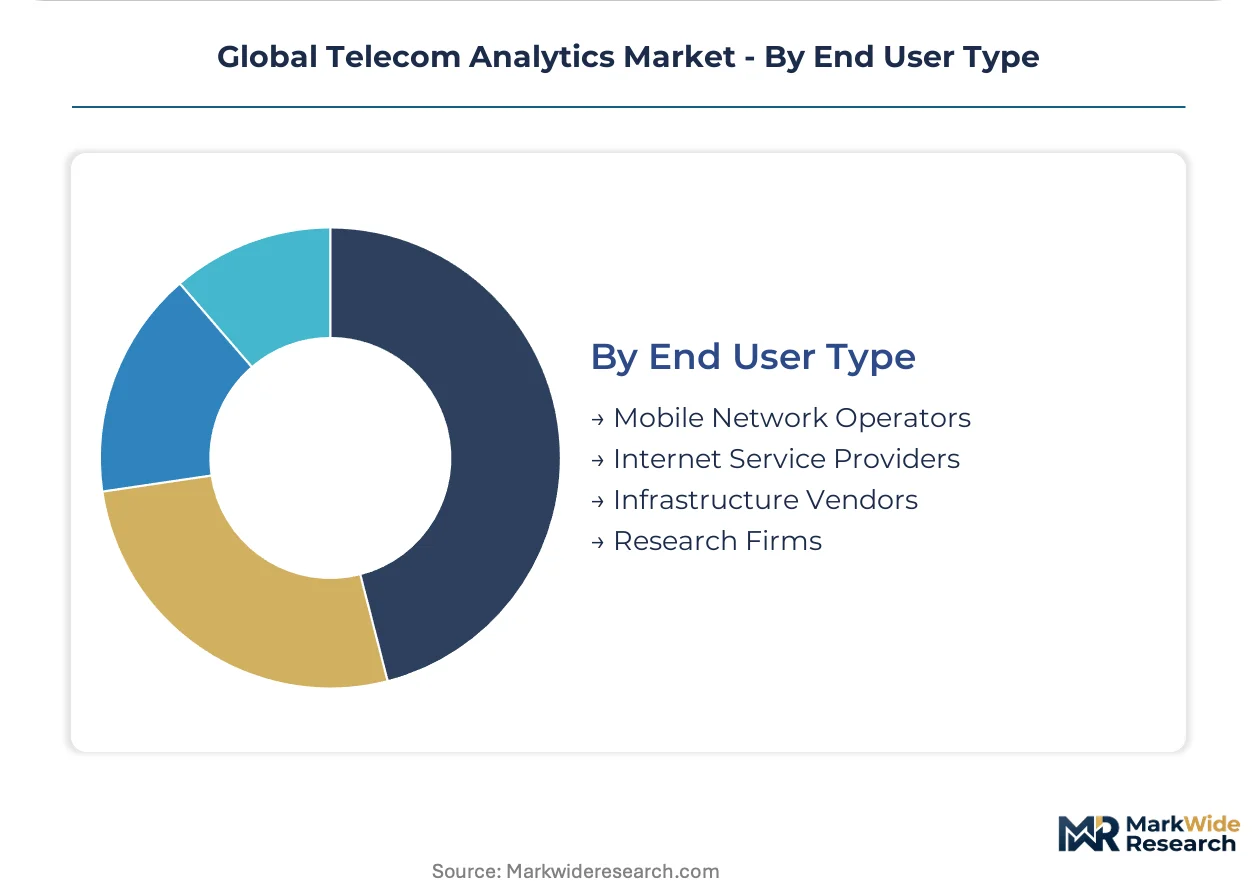
Mobile network operators concentrate demand while infrastructure vendors emerge as analytics consumers for product differentiation.
- Mobile Network Operators:Tier-one and tier-two carriers across India, Germany, South Korea, and Brazil represent the primary demand source. These entities procure across all solution types to combat subscriber erosion and optimize capital-intensive 5G deployments.
- Internet Service Providers:Fixed broadband providers apply customer analytics to reduce churn in fiber and cable markets where overbuild intensifies competition.
- Infrastructure Vendors:Equipment manufacturers embed analytics capabilities into base stations, core network functions, and orchestration platforms as competitive differentiators.
- Research Firms:Telecommunications consultancies and academic institutions license aggregated datasets for market intelligence and algorithm development.
Mobile Network Operators anchor volume today. Infrastructure Vendors constitute the ascending demand category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecom analytics originated in the United States during the 1990s deregulation wave, when AT&T and MCI deployed early churn prediction models to retain subscribers in newly competitive long-distance markets. This American foundation established the computational frameworks that later diffused to European and Asian carriers facing similar competitive pressures.
United States
FCC outage reporting mandates compel carriers to invest in predictive network analytics for infrastructure resilience. The Federal Communications Commission enforces strict reliability standards that drive continuous monitoring platform procurement. Silicon Valley clusters anchor cloud-native analytics development, with hyperscale providers offering elastic compute for petabyte-scale call detail record processing.
Germany
EU AI Act transparency requirements reshape procurement specifications for Deutsche Telekom and Vodafone Germany, prioritizing interpretable algorithms over black-box systems. The national regulator enforces algorithmic accountability standards for automated network management decisions. Berlin-Brandenburg and Munich-Stuttgart corridors concentrate vendor R&D facilities serving Central European carriers.
India
TRAI quality-of-service benchmarks drive Reliance Jio and Bharti Airtel to deploy predictive maintenance analytics across expanding 5G infrastructure. The Telecom Regulatory Authority imposes continuous compliance monitoring that flags threshold breaches before penalties trigger. Bangalore and Hyderabad anchor domestic analytics development centers, while Mumbai-Delhi corridors concentrate carrier headquarters procurement decisions.
Brazil
Fresh 5G mid-band auction outcomes compel Claro, TIM, and Vivo to deploy churn prediction and revenue assurance analytics for competitive positioning. ANVISA and national telecommunications regulators impose data governance frameworks shaping platform selection. São Paulo anchors Latin American carrier operations, with Rio de Janeiro corridor housing regional analytics vendor offices.
South Korea
SK Telecom and KT Corporation pioneer generative AI root cause analysis in network operations centers, reducing mean-time-to-resolution for cell site outages. MFDS and national ICT regulators enforce cybersecurity standards for subscriber data processing pipelines. Seoul Capital Area concentrates carrier headquarters and vendor partnerships, while Busan-Ulsan corridor hosts equipment manufacturing integration facilities.
Global Telecom Analytics Market Competitive Landscape
Capital-heavy cloud infrastructure providers compete with asset-light analytics specialists for carrier procurement contracts. The vendor landscape exhibits tiered consolidation, with three hyperscale platforms anchoring elastic compute offerings while dozens of niche players address specialized use cases. Strategic archetypes separate into full-stack cloud providers, embedded enterprise software vendors, and telecommunications-native specialists. Dominant competitive moves include strategic partnerships between carriers and hyperscalers, plus portfolio diversification into edge computing telemetry processing.
Within the embedded enterprise software tier, SAP SE and Oracle Corporation exemplify archetypes that leverage existing billing and ERP relationships to anchor analytics deployments. IBM Corporation occupies a position representing the telecommunications-native specialist approach, with historical strength in fraud detection latency requirements. These three entities anchor competitive positioning across distinct procurement vectors—enterprise integration, cloud infrastructure, and domain-specific performance—rather than competing directly on identical capability sets.
| Leading Market Players |
|---|
| Oracle Corporation |
| IBM Corporation |
| SAP SE |
| Cisco Systems Inc. |
| Accenture plc |
| Adobe Inc. |
| Teradata Corporation |
| TIBCO Software Inc. |
| Huawei Technologies Co. Ltd |
| Others |
Supply & Pricing Matrix
Tier-one mobile network operators in India and Germany concentrate procurement volumes, anchoring usage-based subscription contracts where fees scale with monthly petabyte ingestion rather than fixed seat licensing.
Pricing Analysis
Usage-based SaaS pricing with tiered elasticity thresholds dominates carrier procurement, separating premium cloud-native platforms with sub-millisecond latency guarantees from standard managed service bundles and economy-tier on-premises licenses. Price differentiation hinges on ISO/IEC 27001 certification status and hyperscale infrastructure integration depth. Cost compression in the economy tier is intensifying because Indian operators Reliance Jio and Bharti Airtel negotiate volume-scaled rates for call detail record processing. Tier-two carriers exhibit highest price sensitivity, while tier-one operators prioritize performance guarantees over per-unit cost.
Supply Chain Analysis
Refurbished server hardware flows from decommissioned on-premises carrier data centers into secondary markets across Southeast Asia, extending asset lifecycles for tier-two operators. Primary supply concentrates in the United States, Ireland, and Singapore where hyperscale cloud regions anchor elastic compute provisioning. Component dependencies include NVIDIA GPU accelerators for fraud scoring latency, Intel Xeon processors for general telemetry processing, and specialized FPGA modules for network function virtualization. Single-source vulnerability around AI training silicon creates procurement risk. Distribution runs through direct enterprise sales teams and systems integrators with telecommunications domain expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Telecom Analytics Market compounds steadily as 5G standalone core deployments generate inexhaustible telemetry volumes requiring continuous platform expansion.
For Market Incumbents: Hedge against hyperscale cloud concentration risk by cultivating multi-vendor infrastructure relationships and accelerating edge computing telemetry processing capabilities. Oracle Corporation and SAP SE should deepen certification investments in EU AI Act explainability standards to defend European carrier relationships against emerging cloud-native specialists. Channel control through embedded billing system integration remains a durable defensive moat. For New Entrants and Emerging Players: Enter via Brazil's freshly liberalized 5G mid-band environment where Claro, TIM, and Vivo require churn prediction analytics without legacy vendor lock-in. The most penetrable segment combines revenue assurance with legacy mainframe integration expertise, an area where talent scarcity has slowed incumbent response times. A go-to-market angle anchored in ISO/IEC 27001 certification accelerates trust-building with risk-conscious procurement committees. For Investors and Strategic Acquirers: Hyperscale cloud providers represent the most active acquirer in this space, seeking telecommunications-native AI engineering teams to complement infrastructure offerings. The market exhibits long-term viability through the 5G infrastructure replacement cycle and subsequent 6G planning phases. Acquisition targets should demonstrate sub-millisecond latency optimization expertise and established carrier reference contracts. Monitor EU AI Act enforcement actions against opaque algorithmic systems as an early signal of vendor displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Telemetry Integration | Radio access network densification demands distributed processing architectures that compress automated remediation response times. |
| Explainable AI Roadmap Acceleration | EU AI Act mandates from Deutsche Telekom and Orange procurement teams prioritize interpretable models over black-box neural networks. |
| Legacy Billing System Middleware Development | Revenue assurance analytics require costly interfaces with decades-old mainframe architectures at tier-one carriers. |
| ISO/IEC 27001 Certification Investment | Information security management certification gains preferred vendor status with operators processing sensitive subscriber financial data. |
| Generative AI Root Cause Analysis Deployment | SK Telecom and KT Corporation pilot systems that automate tier-one support escalation decisions in network operations centers. |
Research Methodology
Bottom-up mobile network operator deployment modeling reconciled against top-down cloud infrastructure capacity tracking forms the analytical core. Primary interviews with CTOs, network operations center directors, carrier procurement officers, and telecommunications data engineering specialists combined with secondary validation from TRAI compliance filings, FCC outage reports, hyperscaler capex disclosures, and ISO certification databases. Triangulation across these sources ensures segmentation integrity.
Input-output matrices map subscriber data volume growth, 5G infrastructure deployment trajectories, and regulatory compliance cost burdens across the projection horizon. Segmentation dimensions include solution type, deployment architecture, use case priority, and end-user category. CAGRs derive from curve-fitting historical adoption patterns against infrastructure investment cycles. Forecast inputs incorporate edge computing sensor endpoint proliferation rates and EU AI Act implementation timelines.
The model holds under stable regulatory enforcement intensity; deviation in TRAI penalty structures or FCC outage reporting mandates would shift carrier procurement priorities. Forecasts reflect documented assumptions about 5G standalone core adoption velocity and hyperscale cloud region expansion. Practitioners should monitor EU AI Act algorithmic transparency enforcement actions and Indian data localization rule refinements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Customer Identity Graph Drift Monitoring Market
Analytics
Patent Analytics Services Market
Analytics
France Contact Center Analytics Market
Analytics
Italy ICT Market
Analytics
Global Cognitive Analytics Market
Analytics
Tourism Industry Big Data Analytics Market
Analytics
Asia-Pacific HR Analytics Market
Analytics
Practice Analytics Market
Analytics
Content Intelligence Market
Analytics
Global Analytics Market
Analytics
Latin America Location Analytics Market
Analytics
Data Analytics in Telecom Market
Analytics
Global Business Intelligence (BI) Software Market
Analytics
Global Sales Performance Management Market
Analytics
South Korea Contact Center Analytics Market
Analytics
Israel Geospatial Analytics Market