
 Global Ip Multimedia Subsystem (Ims) Market | 2026-2036
Global Ip Multimedia Subsystem (Ims) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ip Multimedia Subsystem (Ims) Market Foresight
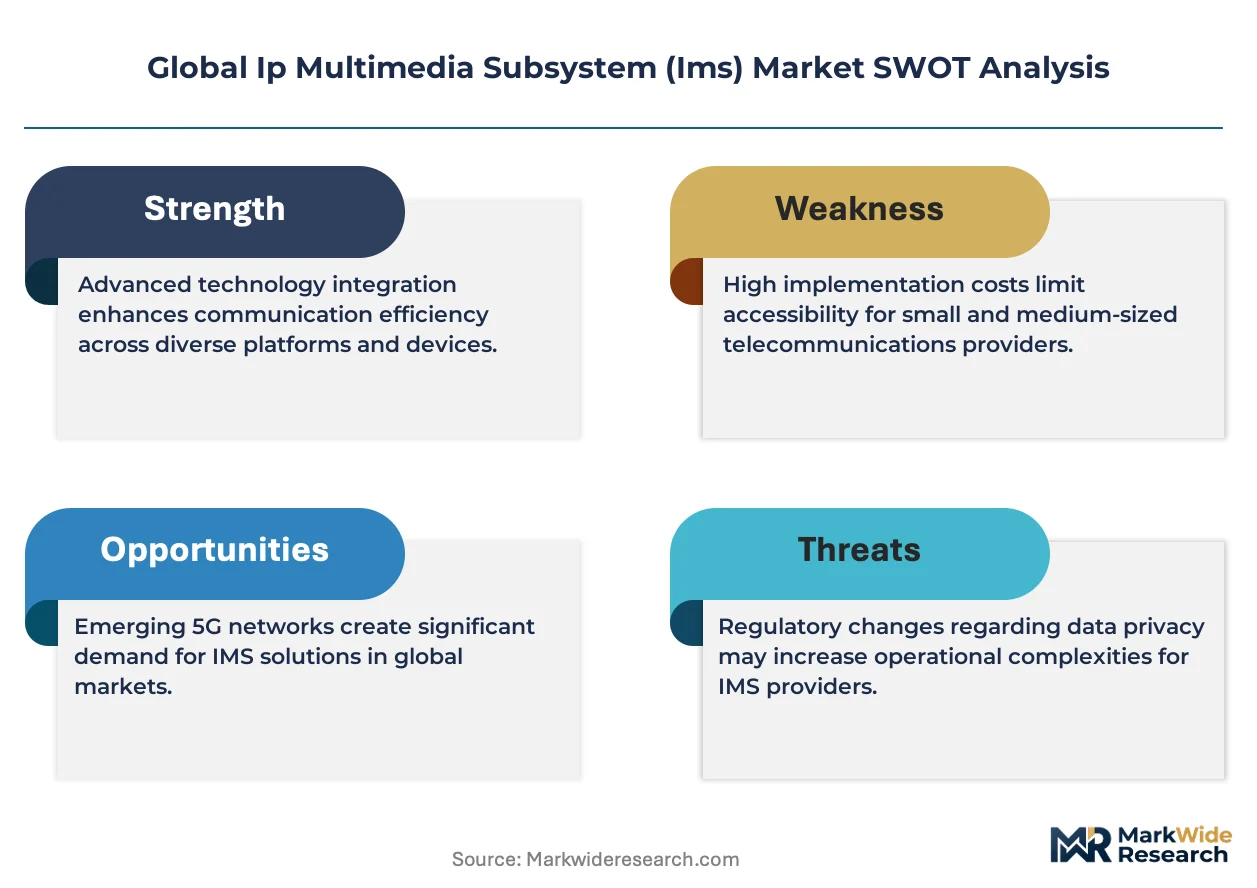
The EU AI Act is pivoting how network equipment vendors architect session border controllers and signaling gateways for European deployments. Ericsson leverages its end-to-end 5G core portfolio to sustain leadership in IMS infrastructure across Nordic markets. Huawei Technologies anchors its competitive position through deep vertical integration from silicon to software stacks. Nokia Corporation differentiates via cloud-native IMS deployments that target telecom operators migrating from hardware-centric architectures.
The IP Multimedia Subsystem constitutes a standardized architectural framework specified by 3GPP that enables packet-switched delivery of multimedia services over Internet Protocol networks, employing Session Initiation Protocol for session establishment and Diameter for policy control and charging interfaces. Its primary commercial purpose centers on unifying voice, video, and messaging services across heterogeneous access networks while enabling interworking with legacy circuit-switched domains. IMS Core deployments are capturing the dominant share of infrastructure spending as operators consolidate signaling and media planes onto virtualized platforms. Voice over LTE use cases are expanding fastest among mobile operators decommissioning 3G radio access networks. Wholesale Carriers represent a concentrated margin pool where interconnection and roaming hub consolidation is driving premium pricing for managed IMS transit services.
The FCC in the United States mandates intercarrier compensation reform that accelerates IP transition timelines for incumbent local exchange carriers. ETSI and 3GPP specifications govern European interoperability requirements that shape vendor certification cycles and operator procurement criteria. Japan's Ministry of Internal Affairs and Communications enforces numbering resource policies that directly influence IMS migration schedules for regional carriers. Stakeholders must monitor spectrum refarming announcements and standalone 5G core mandates as deterministic signals for IMS replacement capex cycles.
Market Dynamics
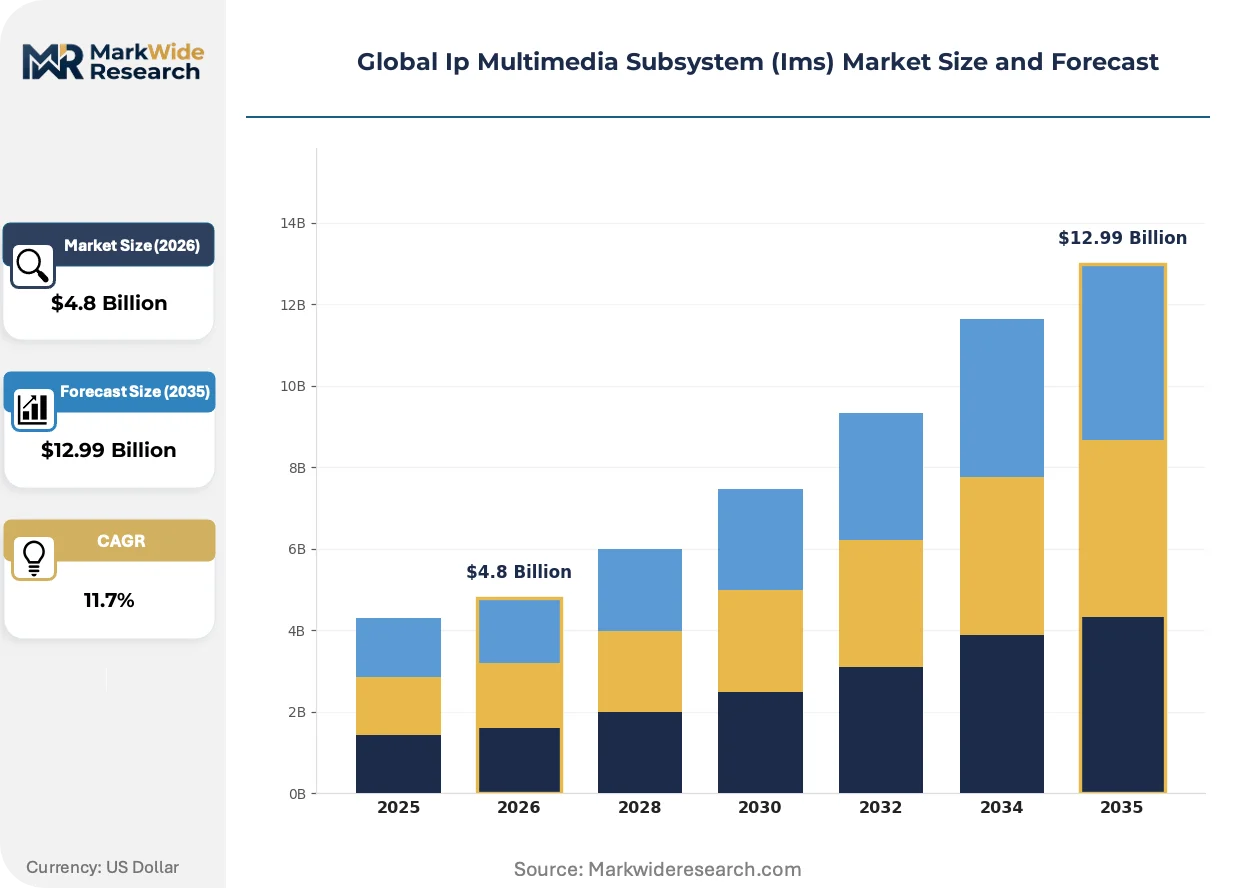
The migration from circuit-switched voice to all-IP architectures is compressing replacement cycles for core network infrastructure as mobile operators face mandatory 3G shutdown deadlines and 5G standalone core mandates across multiple regulatory jurisdictions.
Growth Catalysts
- 3GPP Release 17 specifications:Enhanced IMS procedures for 5G voice continuity are accelerating operator migration timelines in markets where spectrum refarming deadlines have been announced.
- Voice over New Radio (VoNR):5G standalone deployments require native IMS voice support, creating incremental infrastructure demand as operators bypass interim non-standalone configurations.
- Japan numbering resource policies:The Ministry of Internal Affairs and Communications has tied numbering portability to IMS compliance, forcing regional carriers to accelerate core modernization.
Market Restraints
- Silicon supply concentration:Merchant silicon for packet processing in session border controllers remains concentrated among a limited set of foundry sources, creating procurement bottlenecks.
- Legacy interworking complexity:SS7-to-SIP translation requirements for PSTN interconnection impose ongoing operational overhead that slows pure-IP transition economics.
- Skilled systems integration labor:The specialized engineering talent required for multi-vendor IMS core deployments commands premium rates that extend project timelines.
Strategic Opportunities
- India rural broadband expansion:The BharatNet initiative and associated USO fund disbursements are creating addressable demand for IMS-based voice services in previously unserved districts.
- Network exposure function convergence:The integration of IMS with 5G network exposure platforms enables API monetization for third-party voice and messaging applications.
- FCC intercarrier compensation reform:IP transition mandates for incumbent local exchange carriers are opening replacement procurement windows for next-generation core infrastructure.
Industry Challenges
- Multi-vendor interoperability certification:The 3GPP compliance testing required for mixed-vendor IMS deployments extends deployment timelines and increases integration risk.
- PSTN sunset coordination:Synchronized decommissioning of legacy circuit-switched infrastructure across interconnected carriers requires complex operational orchestration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ip Multimedia Subsystem (Ims) Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CS Core, IMS Core, Telecom Applications, Network Interfaces Technology: Session Initiation Protocol, Diameter Protocol, SIP-T, SIP-I, SIGTRAN Use Case: Voice over LTE, Video Calling, Messaging Services, Conferencing Solutions Customer Type: Mobile Network Operators, Fixed Network Operators, Wholesale Carriers, Government Communication Providers |
| Companies Covered | Ericsson, Huawei Technologies, Nokia Corporation, Cisco Systems, ZTE Corporation, IBM Corporation, Oracle Corporation, Samsung Electronics, NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ip Multimedia Subsystem (Ims) Market Shifts & Advancements
Artificial intelligence is penetrating network operations centers, automating fault correlation and capacity forecasting in ways that reshape how carriers manage IMS core availability. This technological infusion is compressing mean-time-to-repair metrics and altering staffing models across tier-one operators.
Cloud-native IMS functions deployed as containerized microservices are automating elastic scaling of signaling plane capacity during peak traffic events. Mobile Network Operators in South Korea and the United States are adopting these architectures to eliminate overprovisioning of fixed-capacity hardware. The shift is automating capital efficiency in core network planning and reducing stranded asset risk.
The EU AI Act is imposing algorithmic transparency requirements on automated network management systems deployed in European Union member states. Equipment vendors must now document decision logic for AI-driven session routing and congestion management functions. This regulatory layer is most affecting session border controller deployments in Germany and France, where national regulators are interpreting conformity assessment procedures.
Carrier procurement of IMS infrastructure is consolidating toward framework agreements with single-vendor end-to-end responsibility. Wholesale carriers and mobile operators are abandoning multi-vendor best-of-breed strategies in favor of unified accountability for voice service quality. This pattern is most visible in Nordic markets, where Ericsson's integrated 5G core and IMS portfolios have captured expanded share of new awards.
Global Ip Multimedia Subsystem (Ims) Market Segmentation
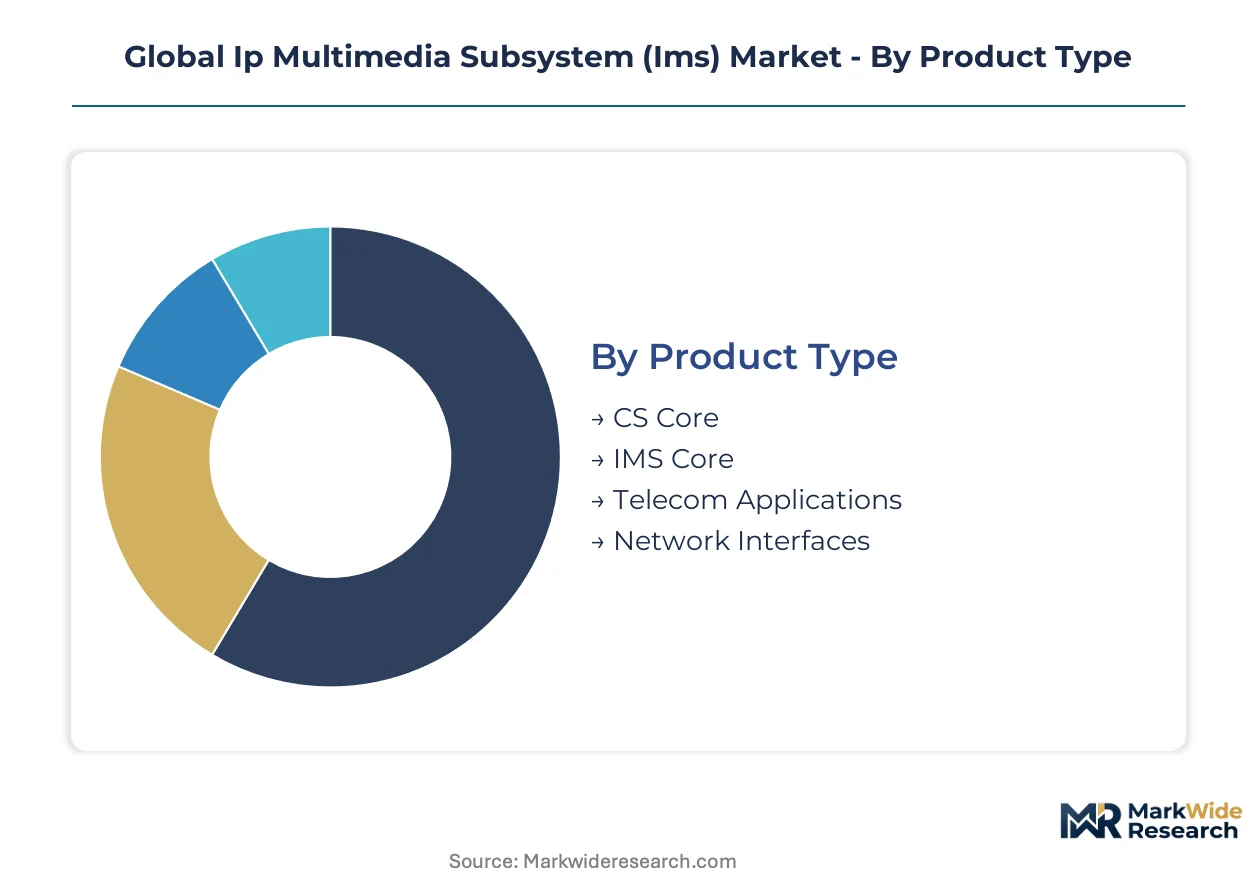
IMS infrastructure procurement patterns diverge sharply across deployment contexts, with signaling protocol choices and core architecture decisions locking operators into multi-year vendor relationships. Segmentation reveals where infrastructure spending concentrates and which technology combinations command premium positioning.
Product Type:
Supply concentration in virtualized core platforms is shifting procurement toward integrated IMS bundles rather than discrete network elements.
- IMS Core:Centralized signaling and session control functions deployed on cloud-native platforms enable elastic scaling of subscriber capacity. Tier-one carriers in the United States and South Korea are consolidating spending here as they migrate toward 5G standalone voice architectures.
- CS Core:Legacy circuit-switched call control infrastructure maintains residual deployment in markets with extended PSTN sunset timelines. Japan's regional carriers and select European incumbents still require these systems for interworking during transition periods.
- Telecom Applications:Value-added service enablers including voicemail, ringback tones, and presence servers. These components face margin compression as over-the-top alternatives displace native carrier services.
- Network Interfaces:Border gateways and interconnection equipment handling protocol translation between carrier networks. Wholesale carriers in Germany and France prioritize these elements for roaming hub consolidation.
Today's leader: IMS Core. Tomorrow's challenger: Network Interfaces.
Technology:
Protocol standardization under 3GPP specifications creates technology lock-in effects that shape vendor competitive dynamics.
- Session Initiation Protocol:Foundational signaling protocol for multimedia session establishment, mandatory for all VoLTE and VoNR deployments. This technology anchors virtually every greenfield IMS installation worldwide.
- Diameter Protocol:Authentication, authorization, and accounting framework governing policy control and charging interfaces. Mobile operators in India deploy Diameter-heavy architectures to support prepaid billing integration with legacy systems.
- SIP-T:ISUP-to-SIP interworking protocol enabling PSTN trunking over IP networks. Incumbent local exchange carriers in the United States rely on SIP-T for FCC-mandated IP transition compliance.
- SIP-I:Encapsulation protocol preserving ISUP parameters end-to-end across IP networks. European wholesale carriers favor SIP-I for international voice quality assurance.
- SIGTRAN:Signaling transport layer carrying SS7 over IP, essential for legacy interworking scenarios. This protocol is gaining share fastest in markets with extended PSTN coexistence requirements.
SIP maintains protocol dominance. SIGTRAN is climbing the fastest as interworking complexity persists.
Use Case:
Application-layer deployment priorities track directly with carrier revenue exposure to voice service quality.
- Voice over LTE:Packet-switched voice service replacing circuit-switched fallback, now mandatory for 3G network decommissioning. This use case captures the dominant infrastructure investment share as operators face hard shutdown deadlines.
- Video Calling:Native carrier-integrated video services competing with over-the-top alternatives. South Korean operators differentiate through HD voice and video bundles tied to 5G tariff plans.
- Messaging Services:Rich Communication Services and SMS-over-IP implementations. These deployments concentrate in European markets where GSMA standards enforcement is strongest.
- Conferencing Solutions:Enterprise-grade multi-party voice and video bridging. Government communication providers in the United States and Japan represent concentrated demand for secure, on-premise conferencing infrastructure.
VoLTE commands current capex. Video Calling shows steepest expansion trajectory as 5G standalone penetration deepens.
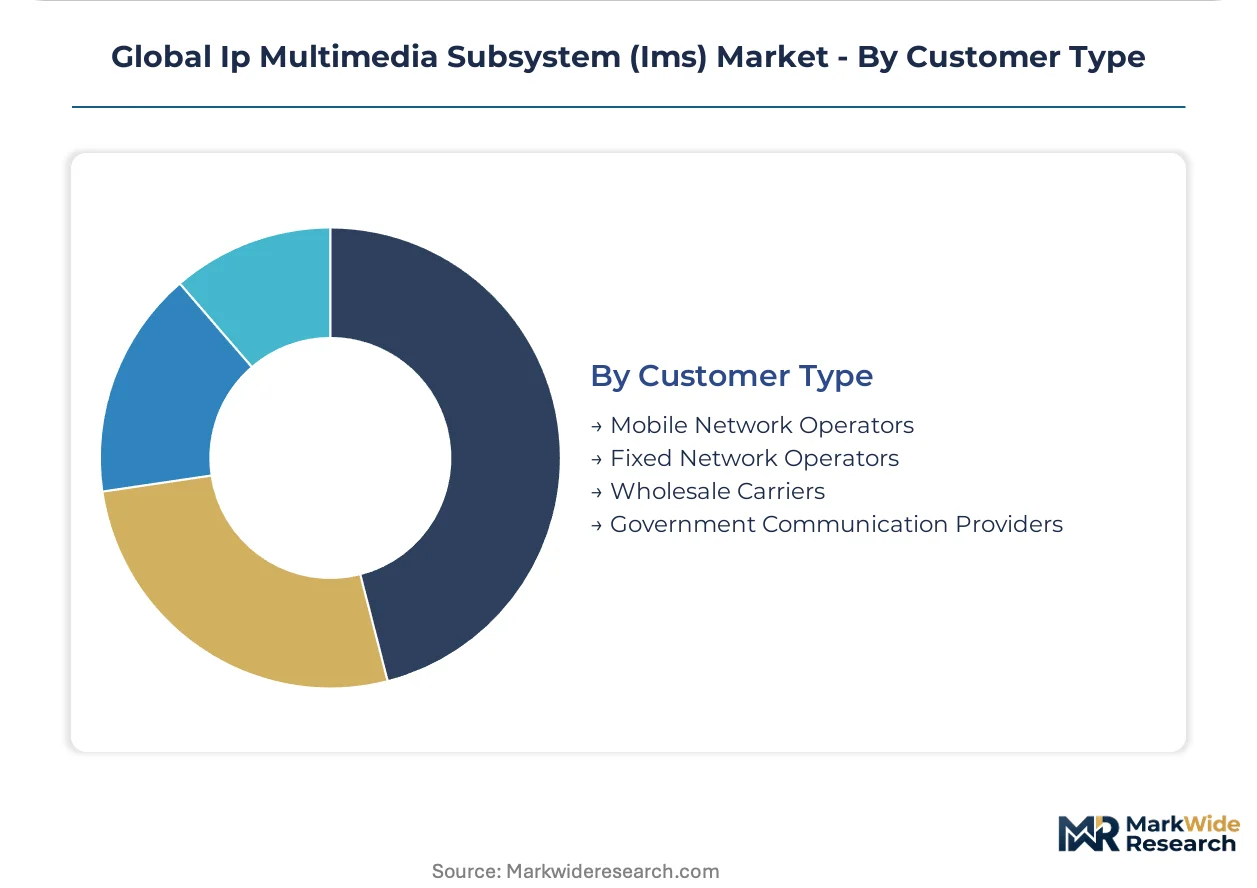
Customer Type:
Procurement authority and budget scale vary dramatically across operator categories, shaping vendor sales motion and solution packaging.
- Mobile Network Operators:Wireless carriers with the largest subscriber bases and most aggressive 5G timelines. These customers drive standardization and exert maximum pricing leverage through framework agreements.
- Wholesale Carriers:Interconnection and roaming specialists capturing premium margins from traffic aggregation. This segment is expanding most quickly as international voice hub consolidation accelerates.
- Fixed Network Operators:Wireline incumbents migrating PSTN subscribers to all-IP infrastructure. Operators in Japan face the most compressed timelines due to numbering policy enforcement.
- Government Communication Providers:Secure network operators with specialized requirements for classified traffic handling. These customers prioritize supply chain security and domestic sourcing over cost optimization.
Mobile Network Operators dominate volume. Wholesale Carriers deliver the fattest margins per port.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized systems integration labor concentrates in Stockholm, Seoul, and Dallas-Fort Worth, anchoring the geographic distribution of IMS core deployment expertise. Carrier procurement patterns track directly with spectrum refarming deadlines and standalone 5G core mandates.
United States
Tier-one carriers are retiring legacy circuit-switched infrastructure to support Voice over LTE services. The FCC mandates intercarrier compensation reform that accelerates IP transition timelines for incumbent local exchange carriers. Dallas-Fort Worth hosts concentrated deployment engineering teams serving AT&T and Verizon modernization programs.
Germany
Wholesale carriers prioritize network interface elements for roaming hub consolidation. The EU AI Act imposes algorithmic transparency requirements on automated network management systems deployed in European Union member states. Berlin anchors vendor certification cycles that shape operator procurement criteria across Central Europe.
South Korea
Mobile Network Operators adopt cloud-native IMS functions deployed as containerized microservices for elastic scaling. The Ministry of Science and ICT enforces standalone 5G core penetration targets that drive infrastructure replacement. Seoul-based engineering centers lead adoption of automated capacity forecasting in network operations centers.
Japan
Regional carriers face compressed IMS migration schedules due to numbering resource policies. The Ministry of Internal Affairs and Communications has tied numbering portability to IMS compliance, forcing core modernization. Tokyo anchors concentrated demand for secure, on-premise conferencing infrastructure among government communication providers.
India
The BharatNet initiative and associated USO fund disbursements create addressable demand for IMS-based voice services in previously unserved districts. TRAI regulations govern interconnection frameworks that shape wholesale carrier procurement. Bangalore hosts systems integration talent supporting multi-vendor deployments for Bharti Airtel and Reliance Jio.
Global Ip Multimedia Subsystem (Ims) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the infrastructure supply base. The vendor landscape exhibits tiered concentration, with end-to-end 5G core portfolios commanding expanded share of new awards. Three archetypes dominate: integrated telecom equipment vendors, cloud-native software specialists, and semiconductor-to-software stack providers. Strategic moves center on framework agreements with single-vendor responsibility and cloud-native architecture transitions.
Among integrated telecom equipment vendors, Ericsson and Nokia Corporation exemplify the shift toward unified accountability for voice service quality. Huawei Technologies occupies a position reflecting deep upstream control over silicon through software layers. Cisco Systems sits within the network interface tier, anchoring session border controller deployments for interconnection scenarios.
| Leading Market Players |
|---|
| Ericsson |
| Huawei Technologies |
| Nokia Corporation |
| Cisco Systems |
| ZTE Corporation |
| IBM Corporation |
| Oracle Corporation |
| Samsung Electronics |
| NEC Corporation |
| Others |
Supply & Pricing Matrix
Cloud-native containerization of IMS core functions is compressing hardware procurement cycles while concentrating silicon sourcing leverage among merchant foundry operators serving session border controller manufacturers. This architectural shift simultaneously reduces fixed-capacity overprovisioning costs and amplifies dependency on specialized packet processing chipsets from concentrated semiconductor fabrication sources.
Pricing Analysis
Bundled end-to-end IMS infrastructure packages command premium positioning against unbundled discrete network element procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments from tier-one mobile network operators. Cost compression in mid-tier deployments is intensifying because cloud-native software stacks displace proprietary hardware margins. Wholesale carriers exhibit the least price sensitivity due to premium interconnection service margins, while rural broadband initiatives in emerging markets demonstrate acute cost constraints.
Supply Chain Analysis
Freight cost volatility for specialized telecommunications equipment is amplifying regional procurement preferences among European and North American operators seeking to minimize transoceanic logistics exposure. Merchant silicon fabrication concentrates in Taiwan, South Korea, and the United States, while systems integration labor clusters in Sweden, South Korea, and Texas. Supply chain risk hinges on single-source vulnerability for high-performance packet processing chipsets used in session border controllers. Distribution runs through direct framework agreements with tier-one equipment vendors rather than channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where carrier procurement is consolidating toward unified vendor accountability as 5G standalone voice specifications harden interoperability requirements. The demand-shift toward cloud-native IMS cores with automated elastic scaling favors suppliers with proven containerized deployment credentials.
For Market Incumbents: Deploy framework agreement expansion to lock in multi-year IMS core refresh cycles before 3G sunset deadlines crystallize procurement decisions. Counter emerging cloud-native software specialists by accelerating certification investment for 3GPP Release 17 compliance. Anchor defensive positioning through captive supply of merchant silicon for session border controller production.
For New Entrants and Emerging Players: Containerized microservices architecture offers entry leverage into wholesale carrier segments where incumbent hardware-centric portfolios face displacement pressure. Target roaming hub consolidation projects in Germany and France where EU AI Act transparency requirements create procurement friction for legacy automated management systems. Pursue API monetization partnerships with 5G network exposure platforms as the primary go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among fixed-network operators in Japan facing compressed IMS migration timelines due to Ministry of Internal Affairs and Communications numbering policy enforcement. Long-term viability centers on suppliers with end-to-end 5G core integration capabilities spanning radio access through packet core. Monitor standalone 5G core penetration announcements from South Korean and United States regulators as the critical inflection signal for replacement capex acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native IMS Core Migration | Containerized microservices enable elastic scaling for VoNR traffic peaks in South Korean deployments. |
| Session Border Controller Consolidation | Roaming hub aggregation in Germany captures premium pricing from international voice traffic termination. |
| Merchant Silicon Supply Agreement | Captive foundry capacity secures packet processing chipsets against procurement bottlenecks in Taiwan. |
| EU AI Act Compliance Certification | Algorithmic transparency documentation satisfies German and French regulator conformity assessments. |
| Rural Broadband Voice Service Expansion | BharatNet initiative disbursements unlock IMS-based subscriber acquisition in previously unserved Indian districts. |
Research Methodology
Direct dialogue with network planning executives at tier-one mobile operators, procurement leads at wholesale carriers, systems integration specialists, and regulatory affairs officers at equipment vendors grounded qualitative assessment in operational reality. Secondary validation drew from 3GPP specification releases, FCC intercarrier compensation orders, ETSI certification databases, and operator capex disclosure filings. Bottom-up deployment sizing triangulated against top-down infrastructure spending estimates from national spectrum auction proceeds.
Segment-level projections across product type, protocol technology, use case application, and customer category fed into consolidated market sizing over the projection horizon. CAGR derivation incorporated 3G network decommissioning schedules, standalone 5G core mandates, and spectrum refarming announcements as demand-timing inputs. Voice over New Radio penetration curves and cloud-native adoption rates among South Korean and United States operators served as technology-transition anchors.
The model holds under stable regulatory enforcement of IP transition timelines; deviation in PSTN sunset coordination schedules or silicon supply disruptions would shift replacement capex phasing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Indonesia B2B Telecom Market
Telecommunications
Myanmar ICT Market
Telecommunications
5G Transport Networks Market
Telecommunications
Telecom Radio System Software Market
Telecommunications
Vietnam ICT Market
Telecommunications
Embedded SIM (Esim) Market
Telecommunications
5G Equipment Market
Telecommunications
A2P Messaging Market
Telecommunications
Diameter Signaling Market
Telecommunications
China ICT Market
Telecommunications
Global SS7 Market
Telecommunications
5G Technology Market
Telecommunications
Egypt ICT Market
Telecommunications
5G Radio Access Network Market
Telecommunications
Mobile Satellite Services (MSS) Market
Telecommunications
Call Control (PBX-IP PBX) Market