
 Egypt Telecom Market | 2026-2036
Egypt Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Telecom Market Analysis
Multi-sourcing of network infrastructure is shifting from single-vendor dependency toward diversified equipment and service partnerships across Egyptian operators. Vodafone Egypt leverages its international roaming agreements and enterprise solutions portfolio to sustain premium positioning in corporate connectivity. Orange Egypt anchors its competitive stance through deep fiber investments and digital banking integrations. WE (Telecom Egypt) dominates the fixed-line and submarine cable landing segments through its state-backed infrastructure control.
Egypt telecom encompasses voice, data, messaging, and broadband services delivered via terrestrial and undersea fiber, wireless macro cells, and emerging 5G-ready architectures operating across 700 MHz to 3.5 GHz spectrum allocations, serving consumer and enterprise communication needs. The technology dimension shows fiber optic deployment outpacing legacy 2G and 3G as operators prioritize fixed-mobile convergence and enterprise-grade latency performance. Within end user categories, large enterprise and government segments concentrate margin pools where managed service contracts and cybersecurity bundling command pricing premiums over commoditized residential voice and data plans.
The National Telecom Regulatory Authority governs licensing, interconnection, and spectrum allocation while the Ministry of Communications and Information Technology drives digital transformation mandates that compel operators to expand rural coverage and localize data centers. BIS-equivalent equipment certification requirements and cybersecurity compliance frameworks shape vendor selection and infrastructure procurement cycles for both incumbent and challenger operators. Stakeholders must monitor spectrum auction timelines and state-led submarine cable investments to calibrate capital deployment and partnership strategies.
Market Dynamics
The National Telecom Regulatory Authority's spectrum modernization mandates are compressing operator upgrade cycles while Cairo's financial district enterprise cloud migration pulls fiber-to-the-premises deployment forward across Greater Cairo and Alexandria.
Growth Catalysts
- Digital Transformation Agenda:The Ministry of Communications and Information Technology mandates compel operators to expand rural coverage and localize data centers, creating infrastructure pull-through.
- Fixed-Mobile Convergence:Enterprise-grade latency requirements from Cairo's banking sector accelerate fiber optic deployment outpacing legacy 2G and 3G architectures.
- Submarine Cable Landing Control:State-backed infrastructure investments in Red Sea and Mediterranean cable systems position Egypt as a regional connectivity hub.
Market Restraints
- Input Cost Volatility:Optical fiber and semiconductor component prices fluctuate with global supply chain disruptions, pressuring capex planning.
- Regulatory Friction:BIS-equivalent equipment certification requirements extend vendor qualification timelines and limit supplier pools.
- Technical Limitation:Legacy copper infrastructure in dense urban cores constrains last-mile fiber penetration without disruptive civil works.
Strategic Opportunities
- Underpenetrated Upper Egypt:Rural governorates south of Cairo present whitespace for wireless broadband and satellite-backhaul solutions.
- Cybersecurity Bundling:Managed service contracts combining connectivity with security services command pricing premiums in government segments.
- Open RAN Convergence:Disaggregated radio access network architectures enable multi-vendor interoperability and reduce single-supplier dependency.
Industry Challenges
- Skill Scarcity in Network Virtualization:Shortage of engineers proficient in SDN/NFV architectures delays cloud-native infrastructure rollouts.
- Capex Intensity of 5G Readiness:Spectrum acquisition and massive MIMO deployment demand sustained capital commitment amid revenue pressure.
- Integration Complexity:Legacy billing and customer management systems resist seamless interfacing with digital service platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Telecom Market |
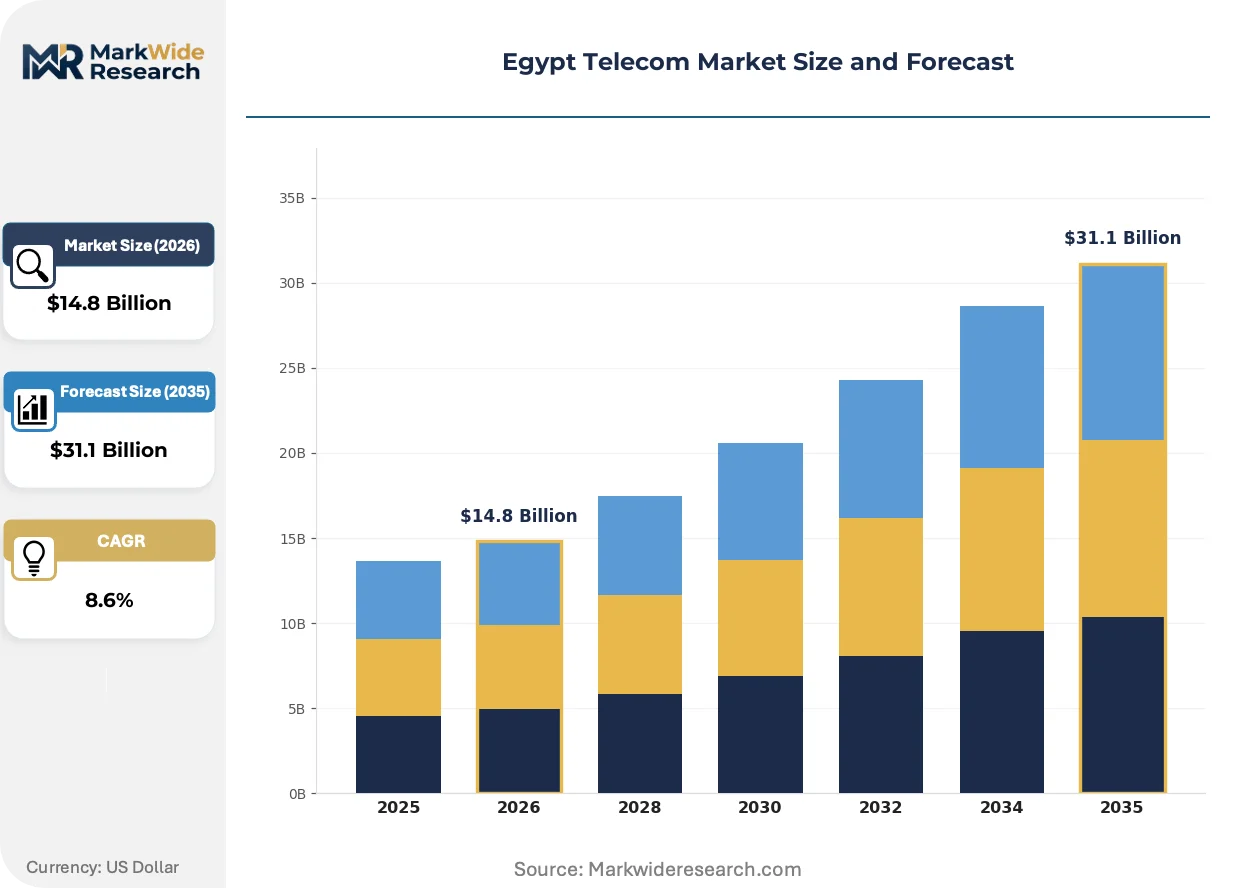
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Voice, Data, Messaging, Broadband Technology: 2G, 3G, 4G, Fiber Optic End User: Residential, Small Business, Large Enterprise, Government Deployment: On-premise, Cloud, Hybrid, Managed |
| Companies Covered | Vodafone Egypt, Orange Egypt, Etisalat Egypt, WE (Telecom Egypt), Telecom Egypt, Giza Systems, Si-Vision, HitekNOFAL Solutions, EcoTel for ICT Integrated Solution, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Telecom Market Emerging Trajectories
Network function virtualization and edge computing architectures are compressing traditional hardware-centric deployment models across Egyptian operator infrastructure.
Open radio access network technology is modularizing vendor relationships and procurement structures in Egyptian mobile networks. Enterprise and government buyers are piloting multi-vendor RAN configurations to reduce dependency on integrated equipment suppliers. This modularizing trend is fragmenting traditional single-source contracts and enabling systems integrators to capture implementation value previously retained by equipment vendors.
The National Telecom Regulatory Authority's spectrum auction frameworks are tightening interoperability mandates for 5G-ready equipment. Equipment vendors must now certify multi-band compatibility across 700 MHz to 3.5 GHz allocations before market entry. Fixed-line operators in Greater Cairo are accelerating certification cycles to secure preferred spectrum blocks ahead of rural coverage obligations.
Enterprise buyers in Alexandria's port and logistics corridor are unbundling connectivity from managed security and cloud access services. Traditional bundled telecom contracts are giving way to componentized procurement where enterprises source fiber transport, security, and compute separately. This pattern is most pronounced among multinational subsidiaries with regional headquarters in Cairo's New Administrative Capital.
Egypt Telecom Market Segmentation
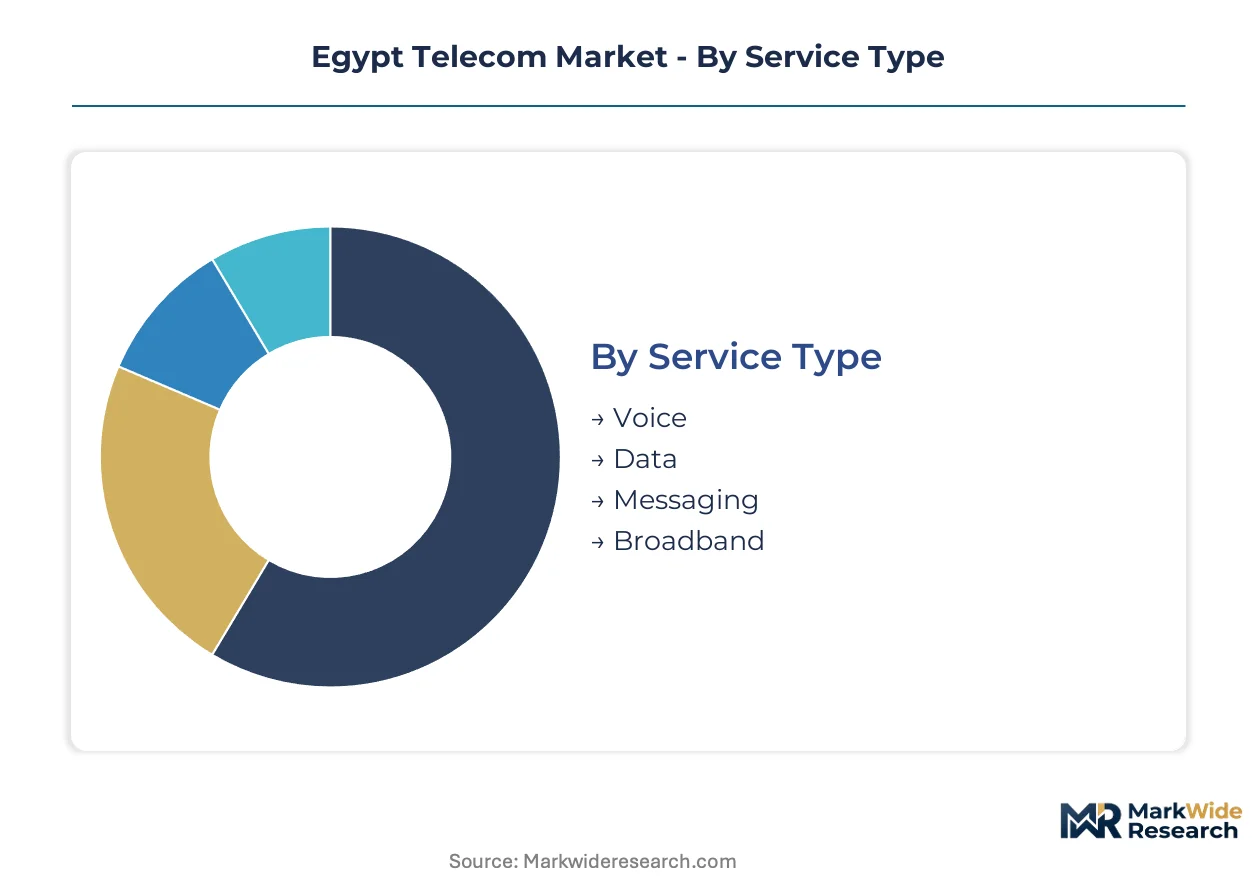
Segmentation in Egypt's telecom market reveals how capital deployment, regulatory obligations, and customer sophistication fragment revenue pools across infrastructure layers. Each dimension exposes distinct margin structures and vendor competitive dynamics.
Service Type:
Voice services demand minimal incremental investment given legacy network amortization, while broadband and enterprise data require sustained fiber and data center expenditure.
- Broadband:High-speed fixed and wireless internet delivered via fiber-to-the-premises and 4G/5G fixed wireless access. Demand concentrates in Greater Cairo's residential compounds and Alexandria's coastal developments where remote work adoption drives bandwidth upgrades. The National Telecom Regulatory Authority's universal service obligations push operators to extend coverage into secondary cities.
- Data:Enterprise-grade connectivity including dedicated leased lines, MPLS, and cloud interconnect services. Cairo's financial district and New Administrative Capital government complexes absorb the majority of premium data circuits as cloud migration accelerates.
- Voice:Traditional circuit-switched and VoIP telephony services. Legacy infrastructure in dense urban cores sustains service delivery with limited fresh capital requirements.
- Messaging:SMS, MMS, and over-the-top messaging platforms. Revenue erosion from OTT substitution compresses this segment's growth trajectory.
Broadband absorbs the bulk of installed capacity; data is expanding most quickly.
Technology:
Generational shifts in access technology determine spectrum allocation intensity and equipment refresh cycles across Egyptian operator portfolios.
- Fiber Optic:Terrestrial and submarine fiber infrastructure delivering ultra-low latency transport. WE's control over Mediterranean and Red Sea cable landings anchors Egypt's regional hub positioning. Cairo-Alexandria corridor deployment outpaces national averages.
- 4G:LTE macro and small cell networks operating across 1800 MHz and 2600 MHz bands. Urban capacity densification in Cairo and Alexandria consumes the majority of radio access network investment.
- 3G:Legacy WCDMA networks facing accelerated spectrum refarming pressure. Rural governorates retain 3G coverage where fiber backhaul remains uneconomical.
- 2G:GSM infrastructure sustaining basic voice and narrowband IoT services. Minimal capital allocation reflects sunset preparation timelines.
Fiber optic claims the steepest expansion trajectory; 2G retains residual subscriber volume but no growth.
End User:
Customer scale and procurement sophistication segment pricing power, with government and large enterprise buyers commanding service bundling and security integration.
- Large Enterprise:Multinational subsidiaries and major domestic conglomerates with managed service requirements. Cairo-based banking and logistics headquarters drive demand for latency-guaranteed connectivity.
- Government:National and municipal agencies subject to Ministry of Communications and Information Technology localization mandates. Data sovereignty requirements compel in-country data center deployment.
- Residential:Individual households consuming bundled voice, video, and internet services. Greater Cairo and Alexandria concentration reflects income distribution.
- Small Business:SMEs seeking standardized connectivity packages without customization. Price sensitivity limits margin capture relative to enterprise segments.
Large Enterprise absorbs the bulk of installed capacity; Government is climbing the fastest on digital transformation mandates.
Deployment:
Infrastructure control models determine capital efficiency and operational flexibility tradeoffs for Egyptian operators and enterprise customers.
- Managed:Outsourced network operations with service-level agreements covering availability and performance. Government agencies and financial institutions in Cairo favor this model to address skill scarcity in network virtualization.
- Cloud:Fully virtualized network functions delivered as subscription services. New Administrative Capital greenfield developments pilot cloud-native architectures without legacy migration burden.
- Hybrid:Mixed on-premise and cloud infrastructure with orchestration layers. Large enterprises adopt this posture to phase cloud migration while retaining critical system control.
- On-premise:Customer-owned and operated physical infrastructure. Declining share reflects total cost of ownership pressures and operator-managed service competitiveness.
Managed deployment absorbs the bulk of installed capacity; Cloud is gaining share fastest in greenfield developments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mediterranean submarine cable landings anchor Egypt's connectivity infrastructure. Red Sea corridor investments position the country as a regional data transit hub. Spectrum allocation frameworks from the National Telecom Regulatory Authority reshape deployment priorities across governorates.
Greater Cairo
Enterprise cloud migration from banking headquarters and government complexes drives fiber-to-the-premises deployment. The Ministry of Communications and Information Technology mandates data center localization for sensitive workloads. New Administrative Capital greenfield developments bypass legacy copper constraints entirely.
Alexandria
Port logistics corridors generate dedicated leased line demand from shipping and trade finance operators. NTRA spectrum modernization timelines compress equipment upgrade cycles for coastal operators. Smouha and Borg El Arab industrial zones concentrate SME connectivity procurement.
Suez Canal Zone
Special Economic Zone status attracts multinational logistics operators requiring low-latency international connectivity. State-backed submarine cable investments in Red Sea landing points strengthen regional backhaul positioning. Ismailia and Port Said serve as primary cable landing and data exchange points.
Delta Region
Agricultural processing and textile manufacturing clusters drive standardized SME connectivity packages. Universal service obligations push wireless broadband extension into secondary cities like Mansoura and Tanta. Fiber backhaul economics remain challenging outside major population centers.
Upper Egypt
Underpenetrated governorates south of Minya present whitespace for wireless broadband and satellite-backhaul solutions. Rural coverage mandates from the Ministry of Communications and Information Technology compel infrastructure investment despite lower revenue density. Luxor and Aswan tourism corridors generate seasonal capacity demand spikes.
Egypt Telecom Market Vendor Landscape
Global majors compete with regional champions across infrastructure control and enterprise service portfolios. The market structures around state-backed incumbents controlling fixed-line and submarine cable assets, with international operators competing on mobile and managed services. Three archetypes dominate: infrastructure incumbents with landing point control, international operators with roaming and enterprise expertise, and systems integrators capturing implementation value from disaggregated procurement. Competitive moves center on fiber densification in Greater Cairo and strategic partnerships for cloud and cybersecurity bundling.
Within the infrastructure incumbent tier, WE (Telecom Egypt) occupies the position of state-backed fixed-line and submarine cable controller. Vodafone Egypt and Orange Egypt represent international operator archetypes competing on mobile network quality and enterprise solutions. Giza Systems exemplifies the systems integrator model capturing value from multi-vendor network deployments and government digital transformation projects.
| Leading Market Players |
|---|
| Vodafone Egypt |
| Orange Egypt |
| Etisalat Egypt |
| WE (Telecom Egypt) |
| Telecom Egypt |
| Giza Systems |
| Si-Vision |
| HitekNOFAL Solutions |
| EcoTel for ICT Integrated Solution |
| Others |
Supply Flow & Price Mechanics
Service-bundling divergence between managed connectivity packages and unbundled component procurement splits Egyptian telecom pricing into two distinct configurations. Enterprise buyers in Cairo's financial district increasingly separate fiber transport from security and cloud services, while residential and SME segments absorb standardized bundles where operators cross-subsidize infrastructure costs.
Pricing Analysis
Warranty and service-level guarantees differentiate premium enterprise contracts from commoditized residential offerings. Three-tier pricing structure across premium, standard, and economy levels governs the market, with premium tiers commanding higher rates due to guaranteed latency performance and dedicated support channels. Price differentiation rests on certification grade and customization level, where government-mandated BIS-equivalent equipment compliance adds cost layers. Cost compression in residential broadband intensifies because OTT substitution erodes voice and messaging margins. Small businesses exhibit highest price sensitivity, while large enterprises and government agencies prioritize service reliability over unit cost.
Supply Chain Analysis
Regional distribution centers in Cairo and Alexandria anchor hub-and-spoke patterns for optical fiber and radio access network equipment. Geographic supply concentration centers on China, Finland, and South Korea for core network infrastructure. Raw material dependencies include optical fiber preform, semiconductor components, and lithium-ion backup power systems. Single-source vulnerability threatens operators dependent on integrated equipment vendors for massive MIMO arrays. Distribution runs through operator-managed warehouses with direct-to-site deployment for major infrastructure projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's telecom sector sits in a fiber-for-copper transition phase as operators accelerate fixed-mobile convergence architectures. 5G-ready fiber deployment is displacing legacy copper infrastructure across Greater Cairo and Alexandria corridors.
For Market Incumbents: To counter Open RAN disaggregation threatening integrated vendor relationships, WE and international operators should deepen fiber densification in New Administrative Capital and secure exclusive submarine cable landing rights through state partnership. Certification investment in multi-band 5G equipment ahead of NTRA auction timelines preserves spectrum access leverage.
For New Entrants and Emerging Players: Begin with satellite-backhaul solutions and fixed wireless access in Upper Egypt governorates where fiber economics fail. Rural coverage mandates from the Ministry of Communications and Information Technology create subsidized infrastructure opportunities. Partner with systems integrators like Giza Systems for government digital transformation contracts rather than building captive sales channels.
For Investors and Strategic Acquirers: Re-rating potential sits with fiber infrastructure specialists given NTRA's spectrum modernization mandates and enterprise cloud migration pull-through. Long-term viability favors operators controlling submarine cable landings and data center assets with localization compliance. Watch NTRA spectrum auction timelines as inflection indicators for capital deployment intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Fiber-to-the-Premises Acceleration | WE's Cairo-Alexandria corridor deployment captures enterprise latency premiums ahead of competitors. |
| Submarine Cable Landing Expansion | Red Sea and Mediterranean investments cement Egypt's regional connectivity hub positioning. |
| Open RAN Pilot Deployment | Multi-vendor interoperability reduces single-supplier dependency for Egyptian mobile operators. |
| Data Center Localization | Ministry of Communications and Information Technology mandates compel in-country sovereign cloud infrastructure. |
| Cybersecurity Service Bundling | Managed security contracts command pricing premiums in government and financial segments. |
Methodological Framework
Regulatory filings from the National Telecom Regulatory Authority, Ministry of Communications and Information Technology white papers, and operator infrastructure disclosure reports formed the secondary backbone for this analysis. Primary interviews with network engineering directors, government procurement officers, and systems integration specialists at Egyptian telecom operators and their vendor partners supplied operational validation. Bottom-up modeling of fiber deployment kilometers and active subscriber accounts triangulated against top-down market sizing from spectrum allocation data and submarine cable capacity announcements.
Historical trendline analysis of capital expenditure patterns and subscriber growth rates established baseline trajectories across the projection horizon. Segmentation dimensions modeled include service type, access technology generation, end-user scale tier, and deployment architecture. CAGRs were derived from regression analysis of infrastructure investment cycles correlated with regulatory mandate timelines. Forecast inputs incorporated NTRA spectrum auction schedules and Ministry rural coverage obligation trajectories.
Underlying measurement precision varies by segment; fiber deployment and enterprise data services carry tighter precision than emerging 5G subscriber forecasts. Projections reflect assumptions about regulatory enforcement consistency and state infrastructure funding continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Denmark ICT Market
Telecommunications
Cloud PBX Market
Telecommunications
Tetra Terminals Market
Telecommunications
Global Virtual PBX Market
Telecommunications
LTE Emergency Networks Market
Telecommunications
A2P Messaging Market
Telecommunications
Rich Communication Services (RCS) Messaging Market
Telecommunications
Global 5G Base Station Market
Telecommunications
Land Professional Mobile Radio Market
Telecommunications
5G Technology Market
Telecommunications
Global Policy Management in Telecom Market
Telecommunications
Poland Telecom Market
Telecommunications
5G RAN Market
Telecommunications
Middle East and Africa Telecom Expense Management Market
Telecommunications
Belgium ICT Market
Telecommunications
Rich Communication Services (RCS) Market