
 5G Technology Market | 2026-2036
5G Technology Market Size, Share, and Industry Trends Forecast 2026-2036
5G Technology Market Intelligence
The modularization of radio access network (RAN) components is decoupling hardware from software purchasing decisions for telecom operators. This shift allows new entrants to challenge established infrastructure providers. Telefonaktiebolaget LM Ericsson sustains its market position through deep relationships with major carriers, while Qualcomm Incorporated leads in modem and RF front-end technology for handsets. Huawei Technologies Co. Ltd. dominates the RAN segment through extensive R&D investment and manufacturing scale.
5G technology represents the fifth generation of cellular network standards, designed for higher data speeds, ultra-low latency, and greater network capacity. It operates across multiple frequency bands, including sub-6 GHz and millimeter Wave (mmWave), to support diverse use cases from mobile broadband to mission-critical communications. The Ultra-Reliable Low Latency Communications (URLLC) application segment is critical for industrial automation and autonomous vehicle development. Within the technology landscape, Massive MIMO antennas are fundamental for improving spectral efficiency and network coverage in dense urban environments.
Spectrum allocation policies set by national regulators, such as the FCC in the United States and China's MIIT, directly govern the pace and scale of network deployments. In parallel, security and data privacy frameworks, including the EU's GDPR, impose stringent requirements on network operators and equipment vendors. Stakeholders must now decide whether to prioritize network coverage expansion or focus investment on developing specialized enterprise services for vertical industries.
Market Dynamics
The disaggregation of the radio access network (RAN) into open, interoperable components is the central force shaping the 5G ecosystem. This shift decouples hardware and software, creating new entry points for specialized vendors and challenging incumbent infrastructure providers.
Growth Catalysts
- Network Slicing Maturation:The ability to create virtual, dedicated network slices with guaranteed quality of service enables telecom operators to offer premium connectivity for industrial IoT, smart factory automation, and mission-critical applications requiring ultra-low latency.
- Private Network Deployment:Demand from the manufacturing sector for private 5G networks is accelerating, particularly in industrial clusters within Germany and China. These deployments support advanced automation, predictive maintenance, and real-time process control in smart factories.
- Spectrum Allocation:Proactive spectrum allocation policies from regulators like the FCC in the United States and China's MIIT are releasing critical mid-band and mmWave frequencies. This directly enables carriers to expand network capacity and launch new services.
Market Restraints
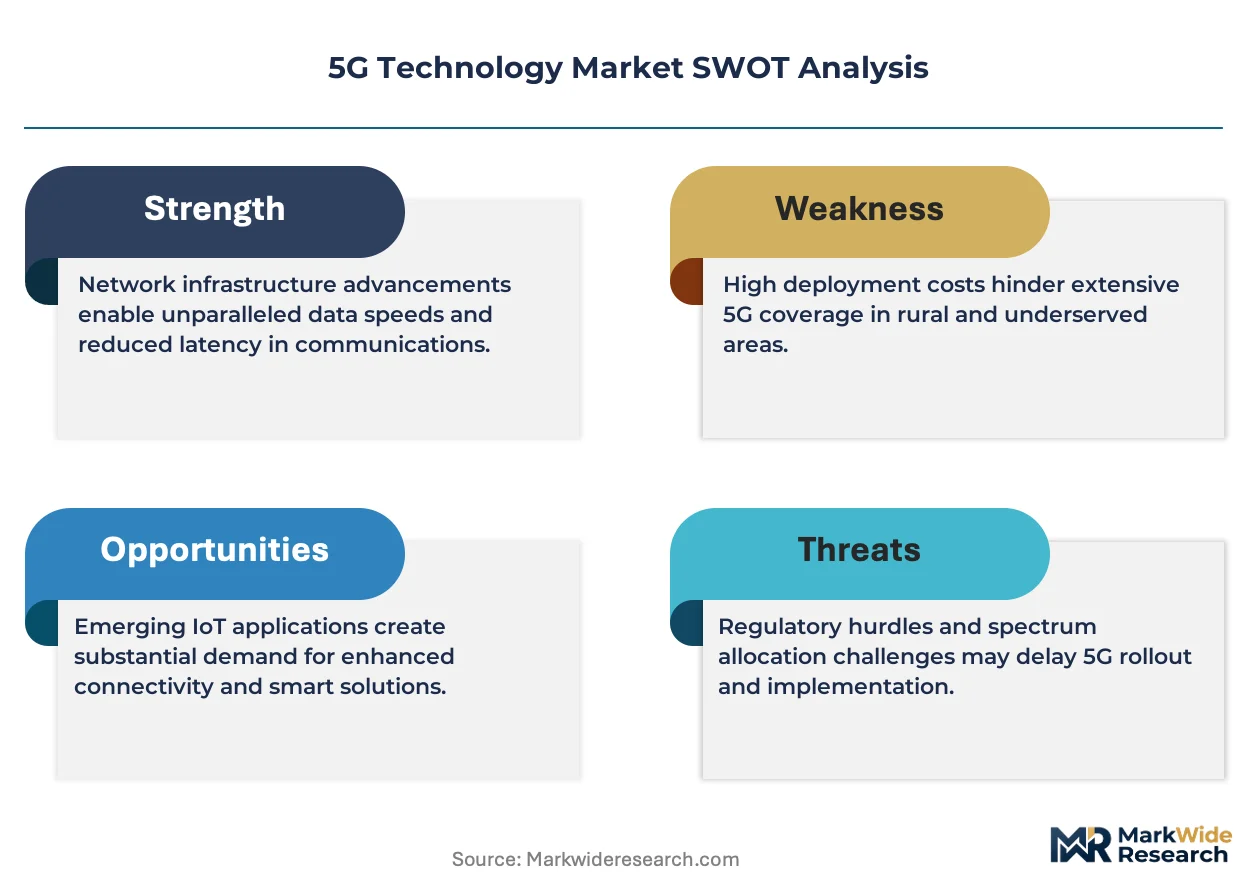
- High Deployment Costs:The capital expenditure required for dense mmWave cell site deployment is substantial, particularly in urban and suburban areas. This cost barrier slows the pace of achieving ubiquitous high-band 5G coverage and limits the return on investment.
- mmWave Propagation Limits:Millimeter Wave signals have a short range and are easily blocked by physical objects such as buildings, foliage, and even rain. These physical limitations necessitate a much denser network topology compared to sub-6 GHz bands, complicating network planning.
- Spectrum Fragmentation:Inconsistent allocation of 5G frequency bands across different countries and regions creates complexity for device and infrastructure manufacturing. This lack of harmonization increases design costs and can limit global roaming capabilities for end-users.
Strategic Opportunities
- URLLC for New Verticals:Developing Ultra-Reliable Low-Latency Communications services for nascent applications like autonomous vehicle platooning, remote surgery, and real-time augmented reality for field service technicians presents a significant value-creation opportunity beyond mobile broadband.
- 5G and Edge Computing Convergence:Integrating 5G connectivity with multi-access edge computing (MEC) allows for data processing closer to the end-user. This creates opportunities for new enterprise services that require real-time analytics and low-latency response, such as video surveillance and industrial robotics.
- Fixed Wireless Access (FWA):In areas with limited fiber-optic infrastructure, 5G FWA offers a competitive alternative for providing high-speed broadband to homes and businesses. This is a key growth vector in both developed and emerging markets, challenging incumbent cable and DSL providers.
Industry Challenges
- System Integration Complexity:Operators face significant operational challenges in integrating new 5G standalone (SA) core networks with existing 4G LTE and non-standalone (NSA) infrastructure. Ensuring seamless interoperability and managing hybrid networks increases operational expenditure and requires specialized engineering talent.
- Evolving Security Threats:The shift to software-defined, virtualized networks and the proliferation of IoT devices dramatically expand the potential attack surface. Securing these dynamic environments against sophisticated cyber threats requires a departure from traditional perimeter-based security models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Technology Market |
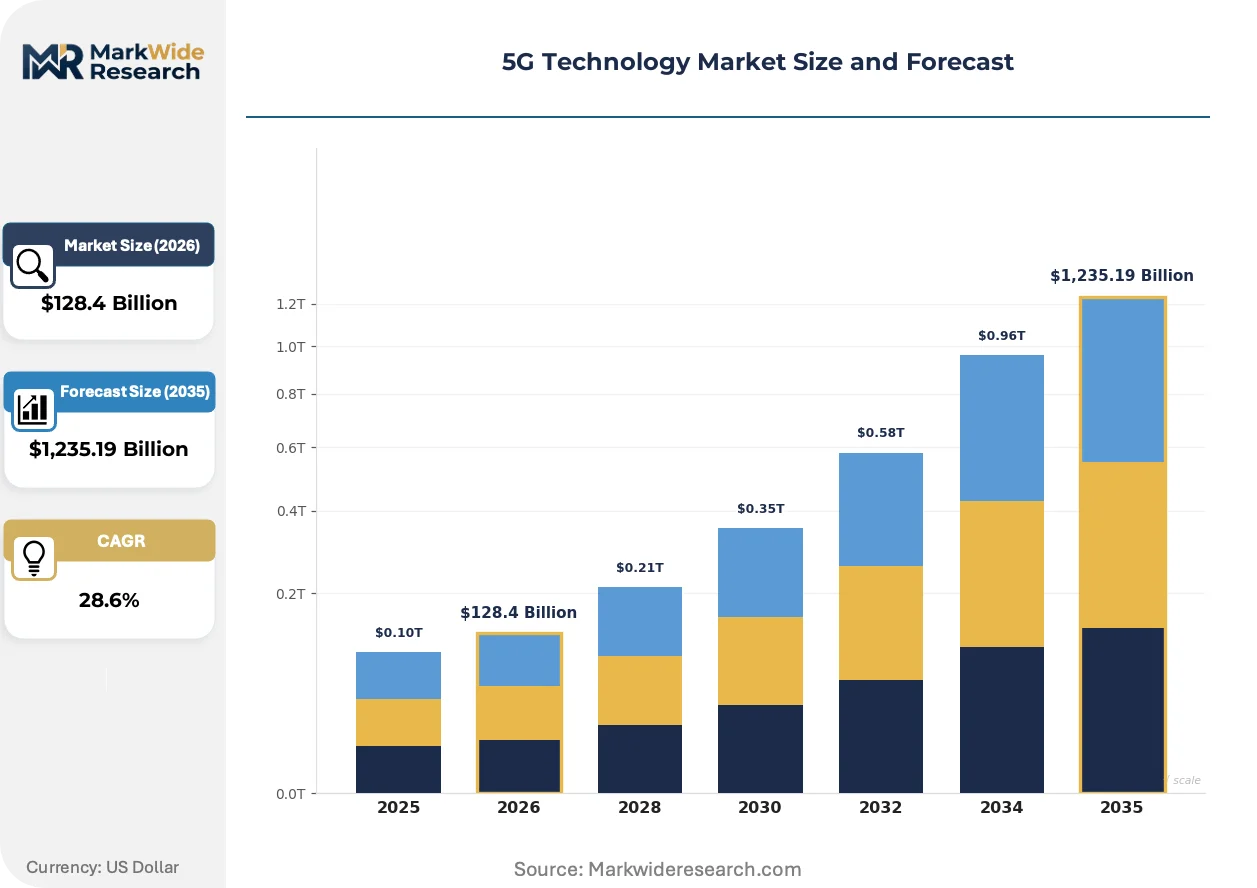
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $1,235.19 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Non-Standalone, Standalone, Hybrid, Private Networks Technology: Massive MIMO, Beamforming, Network Slicing, Millimeter Wave, Small Cells End User Industry: Telecom Operators, Smart Cities, Public Safety, Manufacturing, Media & Entertainment Application: Enhanced Mobile Broadband, Ultra-Reliable Low Latency Communications, Massive IoT, Fixed Wireless Access |
| Companies Covered | Huawei Technologies Co. Ltd., Telefonaktiebolaget LM Ericsson, Nokia Corporation, Samsung Electronics Co. Ltd., Qualcomm Incorporated, ZTE Corporation, Cisco Systems Inc., Intel Corporation, CommScope Holding Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Technology Market Strategic Shifts & Innovations
The market's primary evolution is the pivot from consumer-centric enhanced mobile broadband to enterprise-driven, specialized services for vertical industries. This transition is redefining value propositions, competitive dynamics, and the underlying technology architecture required for success.
Open Radio Access Network (Open RAN) architecture separates RAN hardware and software through open interfaces. Telecom operators are adopting this model to increase vendor diversity and reduce total cost of ownership. The adoption of Open RAN is decentralizing the historically concentrated network equipment supply chain, enabling software-focused firms to compete directly with integrated hardware incumbents.
European Union regulations, including GDPR and a broader strategic focus on digital sovereignty, are influencing network procurement decisions. This regulatory environment compels operators to increase scrutiny of equipment supply chains for security and data privacy compliance. In response, infrastructure vendors are adapting by establishing regional R&D, manufacturing, and data management centers within the EU to meet these stringent requirements.
Enterprise buyers are increasingly purchasing integrated vertical solutions rather than standalone connectivity. This trend is disrupting traditional carrier sales models, as system integrators and cloud hyperscalers gain influence by bundling 5G with IoT platforms, edge computing, and AI analytics. The shift is most visible in the manufacturing and logistics sectors, where outcome-based solutions for automation and asset tracking are in demand.
5G Technology Market Segmentation
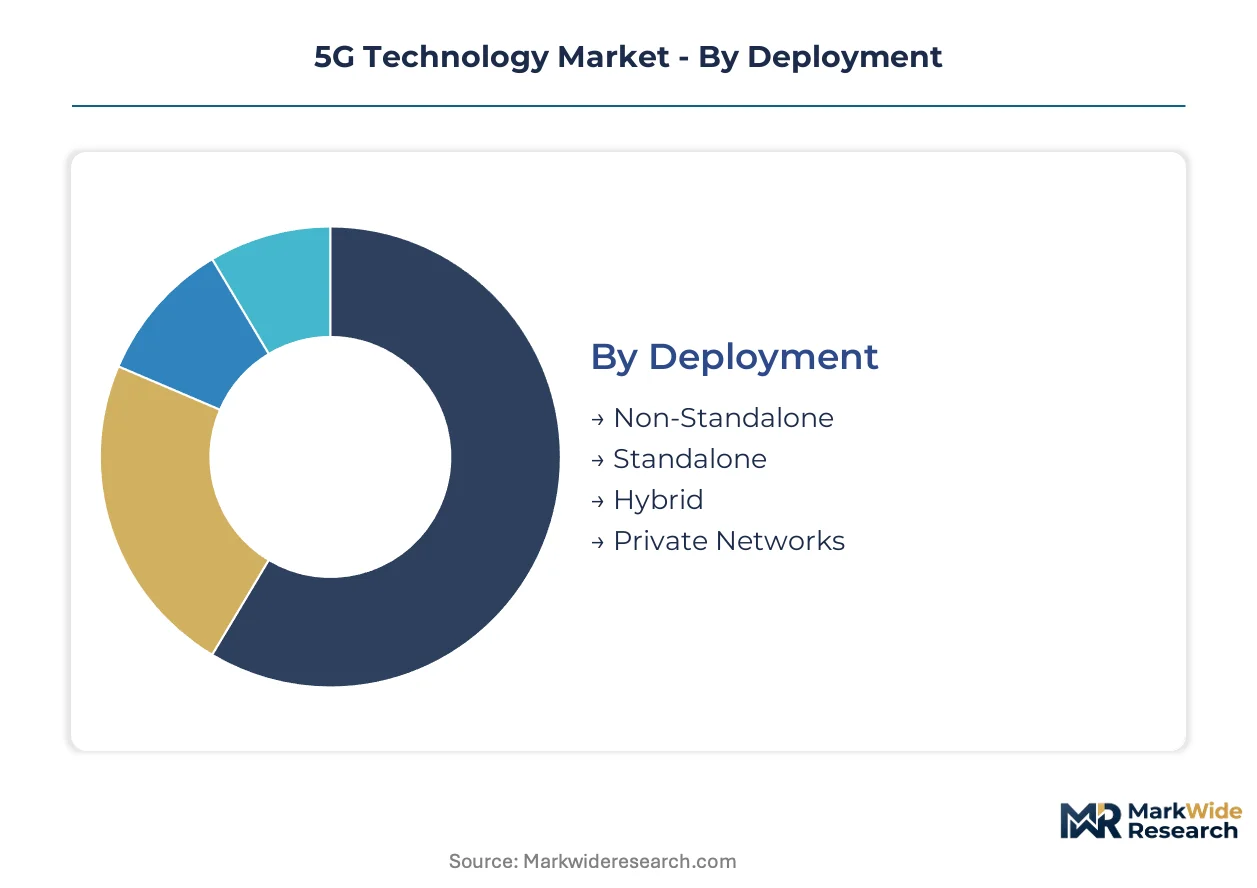
The 5G Technology Market segmentation highlights distinct operational models and underlying technological components driving network evolution. Analyzing these segments reveals where investment capital is concentrating and which innovations are delivering the most immediate commercial returns for operators and enterprises.
Deployment:
The integration depth of 5G infrastructure defines varied operational strategies, from leveraging existing 4G networks to building entirely new, dedicated systems.
- Non-Standalone:This deployment model utilizes existing 4G LTE core networks with 5G radio access networks for faster initial rollout. Demand concentrates in developed markets like the United States and Japan, driven by carriers prioritizing rapid enhanced mobile broadband service delivery.
- Private Networks:Dedicated 5G networks are built for specific enterprises, offering customized connectivity, security, and control. Demand concentrates within industrial clusters in Germany and China, supporting advanced automation and predictive maintenance in smart factories.
- Standalone:This model features a full 5G core network, enabling advanced capabilities like network slicing and ultra-low latency services.
- Hybrid:Hybrid deployments combine elements of both non-standalone and standalone architectures, offering flexibility during network transition phases.
Volume placements concentrate in Non-Standalone deployments; the faster expansion belongs to Private Networks.
Technology:
5G technology components underpin the network's enhanced capabilities, enabling higher speeds, lower latency, and greater capacity for diverse applications.
- Network Slicing:This technology creates multiple virtual networks on a single physical infrastructure, each optimized for specific service requirements. Telecom operators are deploying network slicing in Europe to offer guaranteed quality of service for industrial IoT and mission-critical applications.
- Massive MIMO:Massive Multiple-Input Multiple-Output systems use a large number of antennas at the base station to improve spectral efficiency and capacity. This technology is fundamental for improving network coverage in dense urban environments across South Korea and China.
- Beamforming:Beamforming directs wireless signals towards specific user devices, improving signal quality and reducing interference.
- Millimeter Wave:Millimeter Wave spectrum offers extremely high bandwidth for localized high-speed data transmission, primarily in urban hotspots.
- Small Cells:These compact base stations enhance coverage and capacity in specific areas, complementing larger macro cell deployments.
The core innovation propelling new service models rests with Network Slicing, while Massive MIMO provides the foundational capacity for broad deployments.
End User Industry:
Diverse industries are adopting 5G technology to transform operations, enhance services, and enable new business models.
- Manufacturing:This sector implements 5G for smart factory automation, real-time process control, and predictive maintenance. Demand for private 5G networks is particularly strong in German industrial zones, supporting Industry 4.0 initiatives.
- Telecom Operators:As primary infrastructure providers, telecom operators deploy and manage 5G networks, offering services to consumers and enterprises. Major carriers like Telefonaktiebolaget LM Ericsson continue to invest heavily in network build-out across the United States.
- Smart Cities:Urban environments leverage 5G for intelligent traffic management, public safety, and connected infrastructure.
- Public Safety:5G provides reliable, low-latency communication for emergency services and critical infrastructure protection.
- Media & Entertainment:This industry uses 5G for high-bandwidth content delivery, live streaming, and immersive experiences.
Strategic investment in 5G is currently highest within the Manufacturing sector, with Telecom Operators forming the foundational customer base.
Application:
5G applications span a wide range of use cases, from consumer mobile broadband to mission-critical industrial communications.
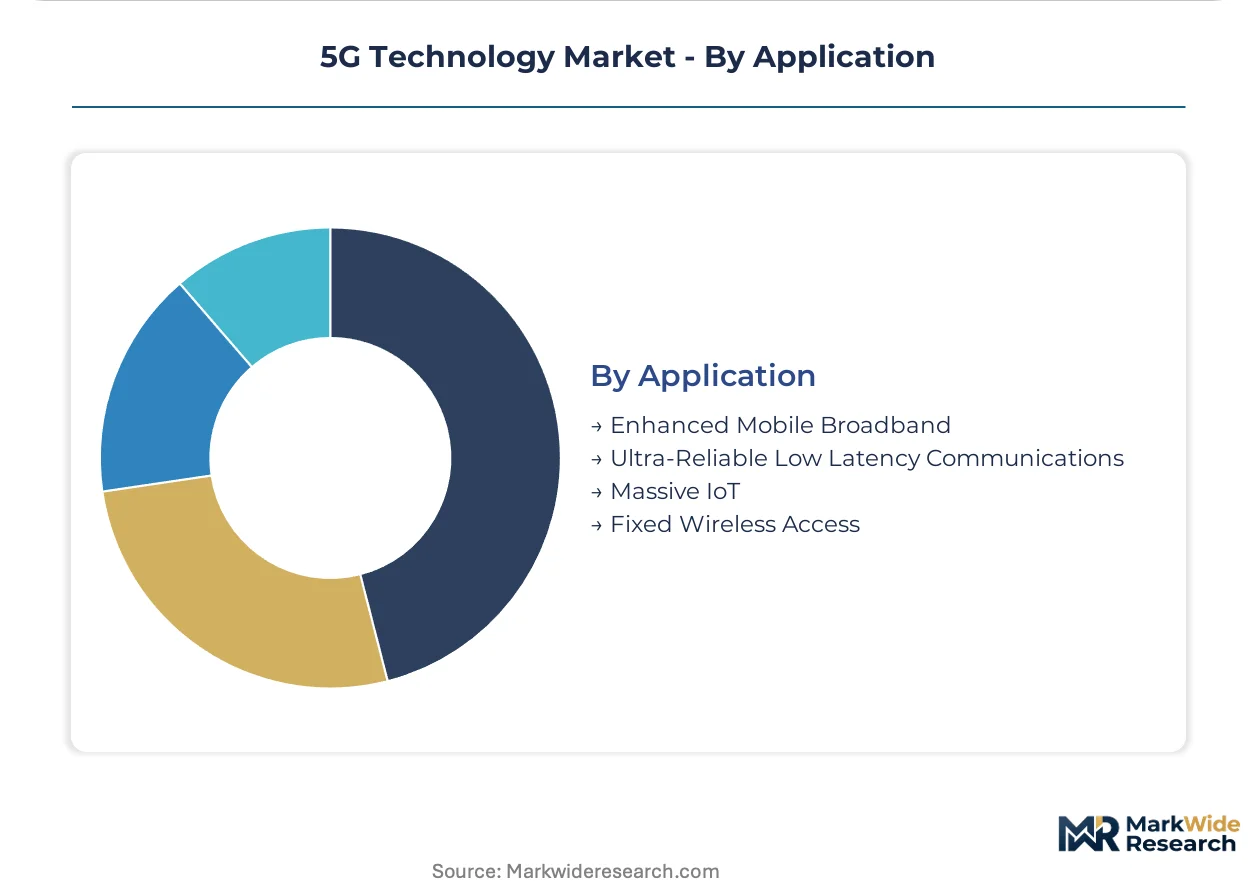
- Ultra-Reliable Low Latency Communications:URLLC provides extremely reliable and low-latency connectivity, essential for autonomous vehicles, remote surgery, and industrial automation. This application segment is crucial for developing new vertical services in advanced economies like Germany and Japan.
- Fixed Wireless Access:FWA delivers high-speed broadband internet to homes and businesses using 5G cellular networks, serving as an alternative to fiber. This application represents the fastest-growing trajectory in both developed and emerging markets, challenging incumbent broadband providers.
- Enhanced Mobile Broadband:EMBB focuses on delivering significantly higher data speeds and capacity for smartphone users and mobile devices.
- Massive IoT:Massive IoT supports a vast number of connected devices with low power consumption, suitable for smart agriculture and logistics.
The most mature application remains Enhanced Mobile Broadband, while Ultra-Reliable Low Latency Communications holds the greatest future growth potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The production-vs-consumption divide in 5G technology is notable, with Asia-Pacific countries like China and South Korea driving both infrastructure production and early adoption, while European nations such as Germany prioritize enterprise-specific deployments. Demand for specialized 5G services is concentrating in industrial hubs across advanced economies. Spectrum allocation policies significantly influence deployment strategies and service expansion in each region.
China
Demand for private 5G networks and Massive MIMO deployments propels China's market expansion. The Ministry of Industry and Information Technology (MIIT) actively promotes 5G infrastructure build-out and industrial integration. Industrial clusters within the Yangtze River Delta are rapidly adopting 5G for smart factory automation and real-time process control.
Germany
Germany's market for 5G technology is driven by the manufacturing sector's need for Industry 4.0 initiatives and URLLC applications. The Federal Network Agency (Bundesnetzagentur) has allocated specific spectrum for private industrial 5G networks. Automotive and machinery manufacturing hubs in Bavaria are investing heavily in 5G-enabled autonomous systems and predictive maintenance.
United States
The United States sees strong demand for enhanced mobile broadband and fixed wireless access (FWA) services. The Federal Communications Commission (FCC) has aggressively auctioned mid-band and millimeter wave spectrum to accelerate network deployments. Major urban centers like New York and Los Angeles are experiencing dense 5G millimeter wave rollouts to boost localized capacity.
South Korea
South Korea exhibits high adoption rates for 5G services, particularly in dense urban environments, driven by consumer demand for high-speed mobile data. The Ministry of Science and ICT (MSIT) supports early commercialization and advanced 5G application development. Seoul's metropolitan area leads in Massive MIMO deployment, enhancing spectral efficiency and network coverage.
Japan
Japan's 5G market focuses on ultra-reliable low-latency communications (URLLC) for industrial automation and smart city applications. The Ministry of Internal Affairs and Communications (MIC) facilitates spectrum allocation for advanced 5G use cases. Manufacturing zones in the Kansai region are piloting 5G solutions for remote surgery and autonomous vehicle platooning.
5G Technology Market Key Industry Players
The competitive structure tilts toward a tiered ecosystem, where established infrastructure providers coexist with specialized component vendors and new software-focused entrants. Integrated hardware manufacturers historically dominated, but the disaggregation of RAN components is fostering greater vendor diversity. Strategic partnerships between telecom operators and technology firms, alongside extensive research and development investments, represent dominant competitive moves.
Among established infrastructure providers, Telefonaktiebolaget LM Ericsson sustains its market position through deep relationships with major carriers globally. Huawei Technologies Co. Ltd. occupies a significant position in the RAN segment, supported by its extensive R&D and manufacturing scale. Qualcomm Incorporated exemplifies leadership in modem and RF front-end technology, particularly for handset components.
| Leading Market Players |
|---|
| Huawei Technologies Co. Ltd. |
| Telefonaktiebolaget LM Ericsson |
| Nokia Corporation |
| Samsung Electronics Co. Ltd. |
| Qualcomm Incorporated |
| ZTE Corporation |
| Cisco Systems Inc. |
| Intel Corporation |
| CommScope Holding Co. Inc. |
| Others |
Cost & Logistics Intelligence
The disaggregation of radio access network (RAN) components fundamentally reshapes both cost economics and supply concentration within the 5G technology market. This modularization fosters greater vendor diversity while driving down the total cost of ownership for telecom operators.
Pricing Analysis
Cost-down pressure on 5G infrastructure equipment accelerates because Open RAN architectures introduce new competition and reduce reliance on integrated hardware. Project-based pricing dominates private network deployments, reflecting customization and integration complexity for specific enterprise needs. Price differentiation stems from performance capabilities, such as URLLC support, and the level of post-deployment service. Telecom operators, facing substantial capital expenditure, represent the most price-sensitive buyers in infrastructure procurement.
Supply Chain Analysis
Skilled workforce availability in manufacturing hubs like China and South Korea significantly influences the 5G supply chain. The production of complex components, such as Massive MIMO antennas and advanced semiconductors, concentrates in these regions. The supply chain relies heavily on specialized chipsets and optical fiber, creating potential single-source vulnerabilities for critical components. Distribution runs through direct sales channels to major telecom operators and large enterprise clients globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a cost-of-compliance story, where stringent regulations like the EU's GDPR create a significant barrier-to-entry moat for compliant players. Adherence to data privacy and security frameworks is paramount for market participation.
For Market Incumbents:Deploy strategic partnerships with hyperscalers to offer integrated 5G and edge computing solutions, mitigating the threat from specialized software-focused entrants. Consolidate market share through targeted acquisitions of Open RAN software developers, addressing the evolving security threats inherent in virtualized networks. Invest in regional R&D and manufacturing centers within regulated markets to meet digital sovereignty requirements.
For New Entrants and Emerging Players:Begin with specialized software solutions for network slicing and orchestration, targeting the manufacturing sector's demand for private 5G networks in Germany and China. Focus on delivering outcome-based solutions that bundle connectivity with IoT platforms and AI analytics for specific industrial applications. Penetrate the market by partnering with system integrators to streamline complex deployments.
For Investors and Strategic Acquirers:Re-rating potential sits with innovative Open RAN component vendors and specialized enterprise service providers given the shift from consumer-centric to enterprise-driven 5G applications. Target firms with proven URLLC capabilities for nascent sectors like autonomous vehicles. A signal to watch is the accelerated adoption of 5G standalone (SA) core networks by major operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Open RAN Software Solutions | This initiative attracts new entrants and diversifies the vendor ecosystem for telecom operators. |
| Invest in Regional Manufacturing Facilities | This move addresses digital sovereignty concerns and strengthens compliance with EU regulations. |
| Form Edge Computing Partnerships | Such collaborations enable new low-latency enterprise services for industrial automation clients. |
| Expand Fixed Wireless Access Offerings | This strategy captures broadband market share from incumbent providers in underserved areas. |
| Acquire URLLC Technology Specialists | This secures critical intellectual property for future applications in autonomous systems and remote operations. |
Research Approach
Independent corroboration across telecom operator executives, industrial IoT solution architects, and spectrum regulators underwrites the qualitative findings of this study. Primary interviews with these industry stakeholders were rigorously validated against secondary sources, including regulatory filings from the FCC and MIIT, industry association reports, and financial statements of leading companies. This approach ensured a robust bottom-up and top-down triangulation of market data.
The analysis anchored the forecast window to historical reference periods, establishing a baseline for future projections across the modeling period. Segmentation dimensions, including deployment type, technology, end-user industry, application, and regional market, were individually modeled. Compound Annual Growth Rates were derived from a comprehensive assessment of spectrum allocation schedules and capital expenditure trends of major telecom operators.
Underlying measurement precision varies by segment; Non-Standalone deployments and Enhanced Mobile Broadband applications carry tighter precision than others. Forecasts reflect assumptions regarding technological adoption rates and regulatory developments. Material deviation in industrial automation investment or geopolitical trade policies warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Indonesia ICT Market
Telecommunications
Africa Entertainment and Telecommunication Market
Telecommunications
Transport Stream Switching Market
Telecommunications
Global Ip Multimedia Subsystem (Ims) Market
Telecommunications
Smart Feature Phone Market
Telecommunications
5G Connections Market
Telecommunications
Romania Telecom Market
Telecommunications
Asia Pacific Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Middle East and Africa Telecom Expense Management Market
Telecommunications
Tetra Terminals Market
Telecommunications
Telecom Managed Services Market
Telecommunications
Russia Telecom Market
Telecommunications
Global SMB Telecom Voice and Data Services Market
Telecommunications
South Africa Telecom Market
Telecommunications
IoT MVNO (Services) Market
Telecommunications
India Optical Transport Network (OTN) Market