
 Belgium ICT Market | 2026-2036
Belgium ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Belgium ICT Market Insights
Cloud-native architecture is fragmenting traditional enterprise IT deployments across Belgian organizations. Proximus Group leverages its nationwide fiber backbone to anchor hybrid cloud connectivity for mid-market clients. Orange Belgium competes through vertical specialization in cybersecurity services for regulated industries. Telenet Group Holding NV sustains pricing power via integrated fixed-mobile-entertainment bundles that reduce enterprise churn.
Information and communications technology in Belgium encompasses software applications, computing hardware, network infrastructure, and cloud-delivered services operating across fixed and wireless spectrum bands from 700 MHz to 26 GHz. These systems process, store, and transmit data to enable automation, analytics, and real-time collaboration across commercial and public sector workflows. Cloud Services capture expanding margin pools as Belgian enterprises shift capex to opex models, while Cybersecurity within the Technology dimension leads absolute spend growth due to NIS2-driven procurement mandates. Hardware retains structural importance in edge computing deployments for latency-sensitive manufacturing applications across Wallonia's industrial zones.
The Belgian Cyber Security Centre enforces NIS2 transposition requirements that compel critical infrastructure operators to upgrade network monitoring and incident response capabilities by statutory deadlines. BIS certification for encryption modules and GDPR data residency rules shape procurement specifications for government and healthcare buyers. Stakeholders must weigh sovereign cloud requirements against interoperability standards when structuring multi-year IT transformation contracts with Belgian public sector entities.
Market Dynamics
NIS2 transposition through the Belgian Cyber Security Centre is compressing procurement timelines for critical infrastructure operators while cloud-native architectures fragment traditional enterprise IT deployments across Flanders and Wallonia.
Growth Catalysts
- Regulatory compliance mandates:The Belgian Cyber Security Centre's NIS2 implementation compels energy, transport, and healthcare operators to upgrade network monitoring capabilities by statutory deadlines, creating immediate procurement pull.
- Edge computing hardware demand:Latency-sensitive manufacturing applications across Wallonia's industrial zones require localized processing infrastructure, sustaining capital investment in server and networking equipment.
- Flanders digital corridor concentration:Leuven-Ghent innovation clusters attract software development and AI research facilities, concentrating skilled labor and venture funding for ICT scale-ups.
Market Restraints
- GDPR data residency compliance costs:Strict localization requirements for government and healthcare buyers inflate total cost of ownership for cloud service providers operating multi-tenant infrastructure.
- Specialized cybersecurity talent scarcity:Shortage of certified incident response professionals limits execution capacity for NIS2-mandated security operations center deployments.
- Fiber backbone construction timelines:Proximus Group's nationwide fiber rollout faces municipal permitting delays that extend connectivity deployment schedules for rural enterprise locations.
Strategic Opportunities
- Sovereign cloud service provision:Belgian public sector entities require domestically hosted infrastructure that satisfies BIS certification for encryption modules, creating protected market segments for local operators.
- 5G private network integration:Manufacturing and logistics facilities in Antwerp port zones seek dedicated wireless spectrum for automated guided vehicles and real-time asset tracking systems.
- Managed security service expansion:Mid-market enterprises lacking in-house cybersecurity expertise present addressable demand for outsourced threat detection and response capabilities.
Industry Challenges
- Legacy system interoperability:Belgian financial institutions migrating core banking platforms to cloud environments encounter data format incompatibilities with decades-old COBOL-based transaction processing architectures.
- Certification timeline compression:BIS encryption module validation procedures create procurement bottlenecks for security vendors attempting to meet NIS2-imposed deployment deadlines for critical infrastructure clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belgium ICT Market |
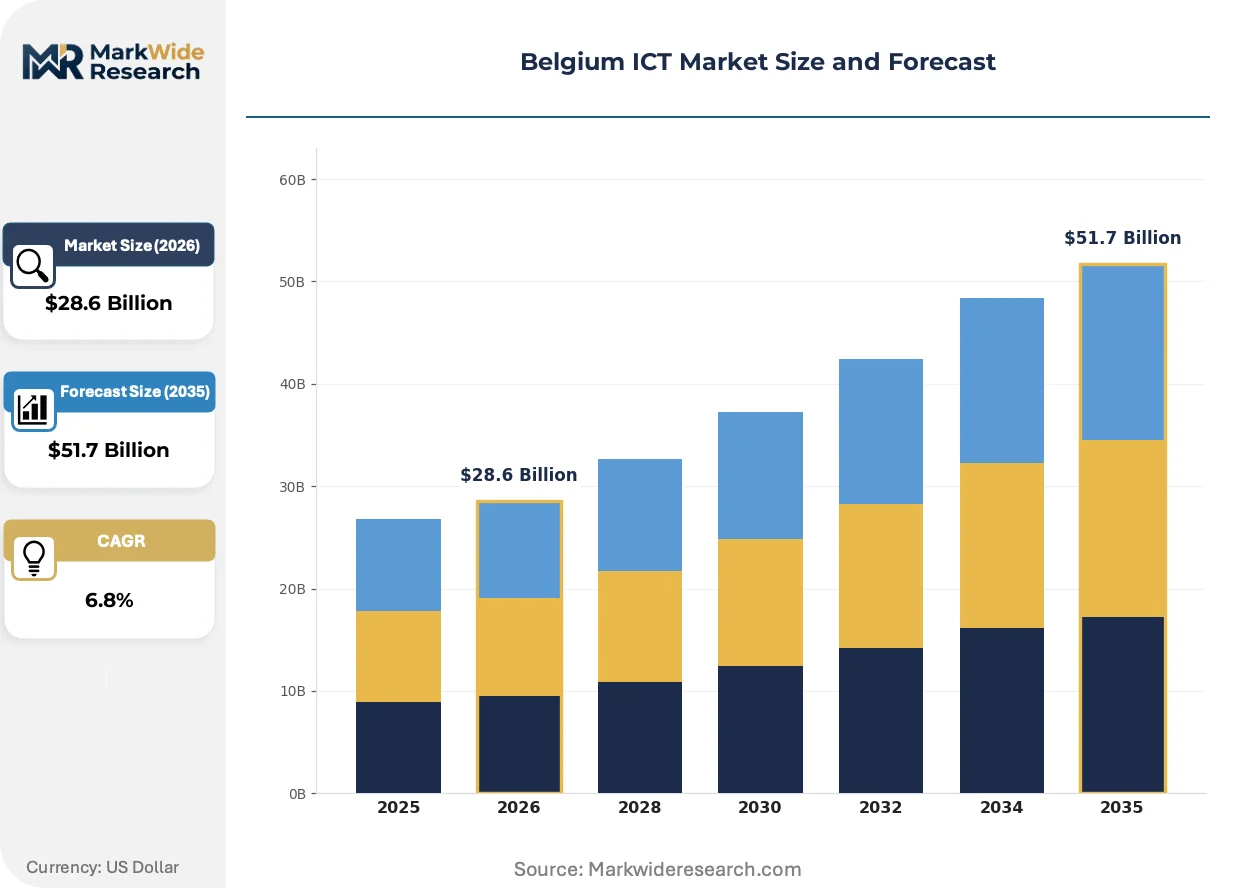
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Networking, Cloud Services End User: SMEs, Large Enterprises, Government, Educational Institutions Technology: AI, Blockchain, IoT, Cybersecurity Application: Data Analytics, Business Automation, Customer Management, Cloud Computing |
| Companies Covered | Proximus Group, Orange Belgium, Telenet Group Holding NV, Cegeka, NRB Group, Atos Belgium, IBM Belgium, Capgemini Belgium, Accenture Belgium, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belgium ICT Market Trends and Innovations
Belgian enterprise IT is fragmenting across hybrid deployment models as regulatory pressure and latency requirements pull workloads between centralized cloud, sovereign facilities, and edge locations.
Container orchestration and Kubernetes-based platforms are hybridizing application deployment patterns across Belgian organizations. Manufacturing enterprises in Wallonia's automotive supply chain adopt these technologies to balance cloud scalability with on-premise data sovereignty requirements. This architectural shift is compressing traditional three-year hardware refresh cycles into continuous infrastructure iteration.
The Belgian Cyber Security Centre's NIS2 enforcement timeline is accelerating security procurement across energy distribution and healthcare provider networks. Operators must demonstrate enhanced incident response capabilities and supply chain risk management procedures to maintain operating licenses. Healthcare IT departments in Brussels and Flanders are prioritizing network segmentation investments to satisfy audit requirements ahead of statutory deadlines.
Mid-market enterprises are unbundling traditional managed service contracts in favor of consumption-based cloud pricing. Fixed-fee infrastructure arrangements are losing share to metered compute and storage models that align technology spending with operational fluctuations. This purchasing pattern shift is most pronounced among logistics and professional services firms in Antwerp and Ghent seeking to convert capital expenditure to operational expenditure.
Belgium ICT Market Segmentation
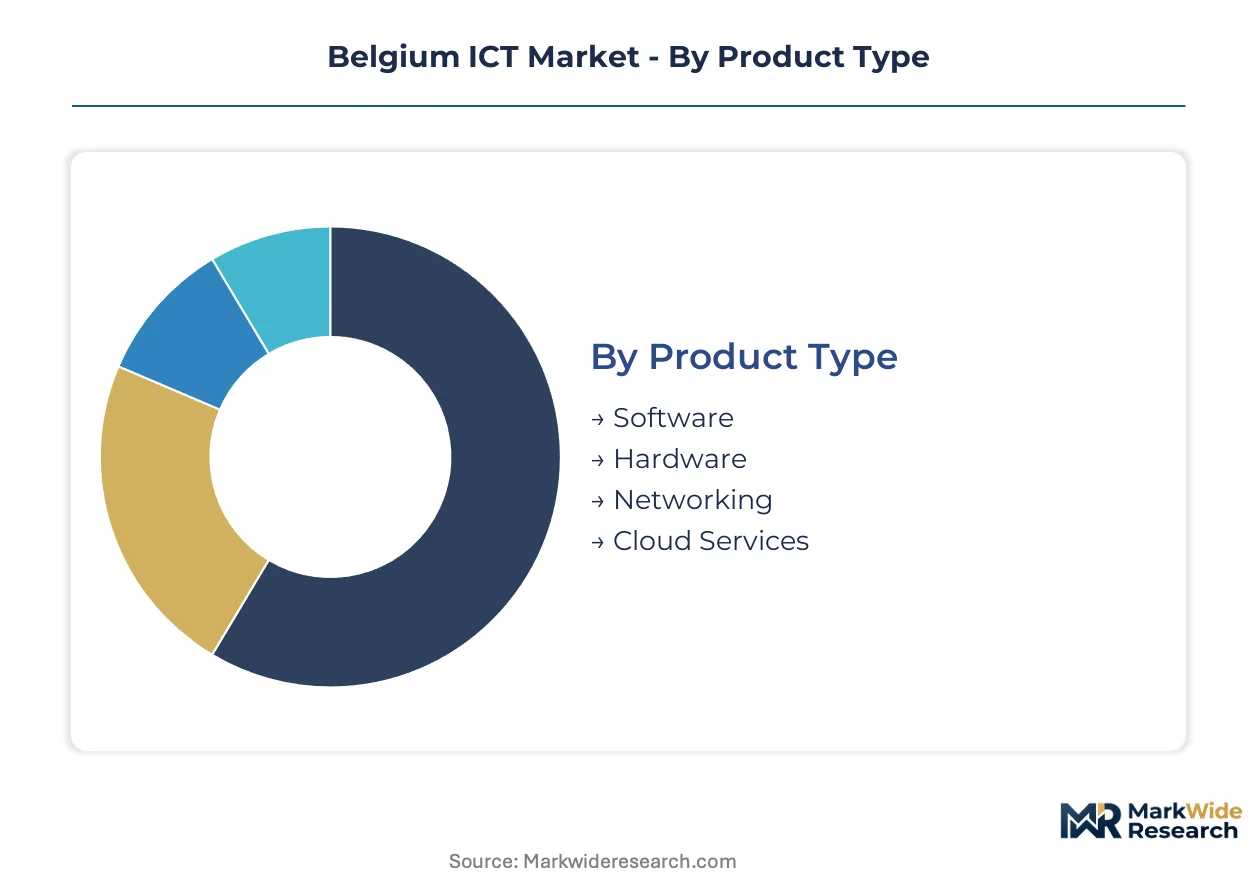
Belgian ICT procurement patterns diverge sharply across organizational scale and regulatory exposure. Enterprises structure vendor relationships around compliance mandates, while mid-market buyers prioritize consumption flexibility over sovereign hosting requirements.
Product Type:
After-sales service intensity varies dramatically across product categories, with hardware maintenance contracts demanding field technician networks while cloud services rely on remote support desks.
- Cloud Services:Subscription-based compute, storage, and platform resources delivered via Proximus Group's fiber backbone and competing data center facilities. Belgian financial institutions in Brussels are accelerating migration to hybrid configurations that satisfy NIS2 data residency requirements while retaining on-premise transaction processing for latency-critical operations.
- Hardware:Physical servers, networking equipment, and endpoint devices requiring installation, warranty management, and lifecycle refresh programs. Manufacturing facilities across Wallonia's industrial zones sustain capital investment in edge computing infrastructure for real-time quality control systems.
- Software:Licensed applications and custom development tools spanning enterprise resource planning, collaboration platforms, and industry-specific solutions.
- Networking:Fixed and wireless connectivity infrastructure including 5G private network deployments for Antwerp port logistics operations.
By volume, Hardware leads. By growth pace, Cloud Services is ahead.
End User:
Customer procurement sophistication determines contract structure complexity, with government tenders requiring BIS-certified encryption and multi-year service level agreements.
- Government:Federal, regional, and municipal entities subject to strict GDPR data localization and sovereign cloud mandates. Healthcare IT departments in Flanders prioritize network segmentation investments to satisfy Belgian Cyber Security Centre audit requirements ahead of statutory deadlines.
- Large Enterprises:Multinational corporations and major domestic groups with dedicated procurement teams negotiating enterprise licensing agreements. Energy distribution operators face compressed timelines for NIS2-mandated security operations center deployments.
- SMEs:Mid-market organizations unbundling traditional managed service contracts in favor of consumption-based cloud pricing models.
- Educational Institutions:Universities and research facilities in the Leuven-Ghent corridor driving demand for high-performance computing and AI research infrastructure.
By revenue concentration, Large Enterprises dominate. By expansion trajectory, Government is climbing the fastest.
Technology:
Implementation maturity separates experimental pilots from production deployments, with cybersecurity and IoT reaching operational scale while blockchain remains largely exploratory.
- Cybersecurity:Network monitoring, threat detection, encryption, and incident response capabilities. The Belgian Cyber Security Centre's NIS2 enforcement is accelerating procurement across critical infrastructure operators who must demonstrate enhanced supply chain risk management procedures.
- IoT:Sensor networks, asset tracking systems, and connected device platforms. Automated guided vehicle deployments in Antwerp port zones require dedicated wireless spectrum integration with existing enterprise systems.
- AI:Machine learning platforms, natural language processing, and predictive analytics tools.
- Blockchain:Distributed ledger applications for supply chain traceability and digital identity verification.
By deployment scale, Cybersecurity leads. By emerging application intensity, IoT is gaining share fastest.
Application:
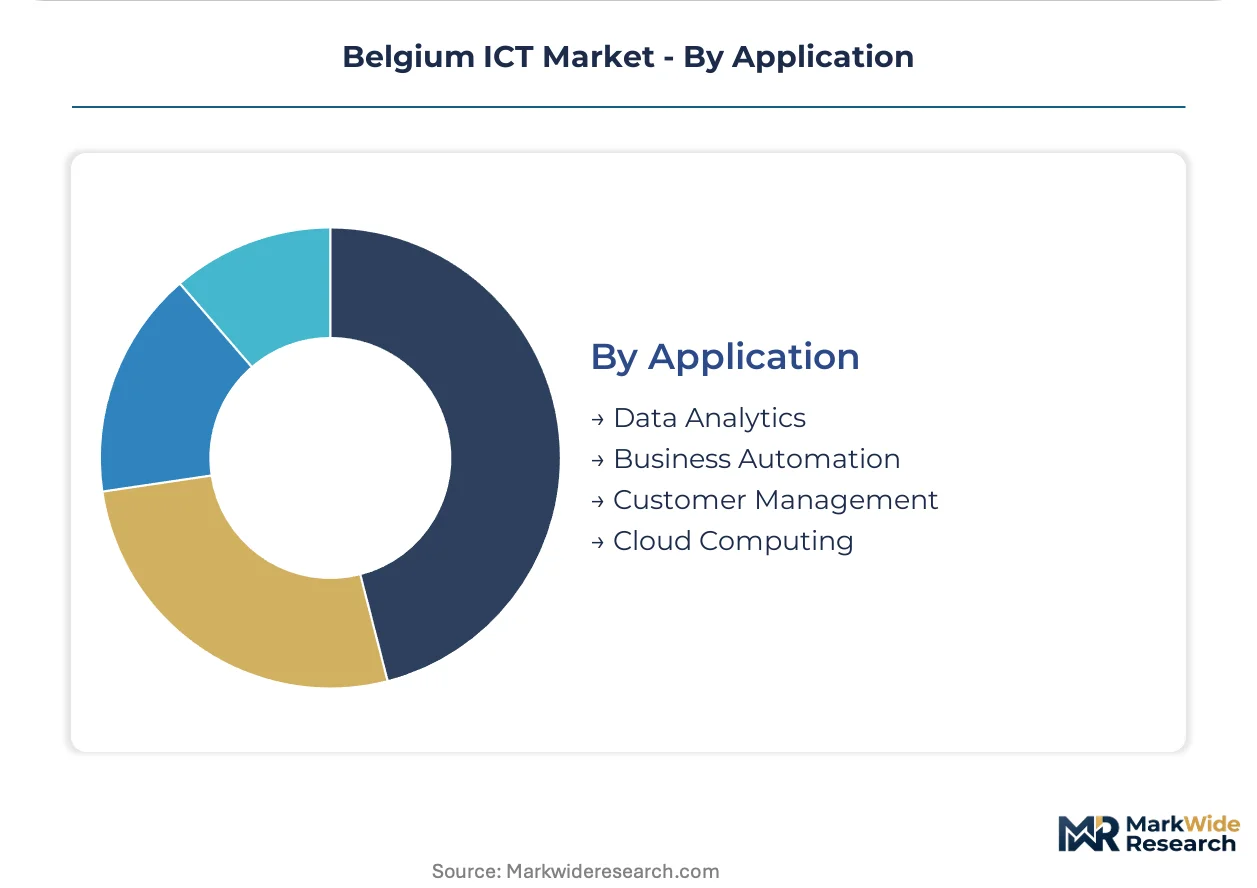
Functional priority reflects organizational digital maturity, with cost-sensitive adopters targeting automation while data-rich enterprises invest in analytics platforms.
- Cloud Computing:Infrastructure-as-a-service and platform-as-a-service deployments enabling operational expenditure conversion. Logistics and professional services firms in Ghent are shifting from fixed-fee infrastructure to metered compute models.
- Business Automation:Workflow orchestration, robotic process automation, and enterprise system integration. Financial institutions migrating core banking platforms encounter data format incompatibilities with legacy COBOL architectures.
- Data Analytics:Business intelligence, predictive modeling, and visualization tools.
- Customer Management:CRM platforms, digital engagement tools, and service desk solutions.
By adoption breadth, Business Automation leads. By investment growth rate, Cloud Computing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government buyers concentrate procurement authority in Brussels, while financial services demand clusters in the capital and logistics operators anchor requirements around Antwerp port infrastructure. Regional digital infrastructure maturity varies between Flanders' fiber-rich corridors and Wallonia's industrial edge computing zones.
Flanders
Leuven-Ghent innovation clusters attract AI research facilities and software scale-ups seeking skilled labor pools. The Flemish government operates digital transformation programs that subsidize SME cloud migration and cybersecurity upgrades. Port of Antwerp operators deploy private 5G networks for automated guided vehicles and real-time cargo tracking systems.
Wallonia
Automotive and aerospace manufacturers in Charleroi and Liège industrial zones sustain capital investment in edge computing infrastructure for latency-sensitive quality control. Wallonia's digital agency administers regional broadband expansion grants targeting rural enterprise connectivity gaps. Seraing-Namur manufacturing corridor hosts server deployments for localized data processing in supply chain operations.
Brussels-Capital Region
European Commission institutions and Belgian federal ministries generate concentrated demand for sovereign cloud services satisfying GDPR data residency mandates. The Belgian Cyber Security Centre enforces NIS2 compliance timelines for critical infrastructure operators headquartered in the capital. EU quarter IT departments prioritize BIS-certified encryption modules in multi-year transformation contracts.
Antwerp Province
Petrochemical and diamond logistics clusters drive specialized networking requirements for secure high-bandwidth data exchange. Provincial economic development agencies coordinate 5G spectrum allocation for port automation and warehouse robotics integration. Mechelen-Turnhout enterprise zones attract cloud service providers establishing edge presence for manufacturing clients.
Belgium ICT Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct service tiers. The Belgian ICT market structures around three layers: nationwide telecom operators with fiber infrastructure, systems integrators with vertical expertise, and global consultancies with transformation capabilities. Strategic archetypes include connectivity-anchored hybrid cloud providers, NIS2 compliance specialists, and sovereign cloud operators. Dominant competitive moves encompass fiber backbone expansion and cybersecurity service portfolio diversification.
Among Belgium-based integrated operators, Proximus Group anchors hybrid cloud connectivity through nationwide fiber assets. Orange Belgium and Telenet Group Holding NV occupy positions in the connectivity tier, with the former representing vertical specialization in regulated industries and the latter exemplifying integrated fixed-mobile-entertainment bundling. Cegeka and NRB Group sit within the systems integrator archetype, serving mid-market enterprises with compliance-driven transformation requirements.
| Leading Market Players |
|---|
| Proximus Group |
| Orange Belgium |
| Telenet Group Holding NV |
| Cegeka |
| NRB Group |
| Atos Belgium |
| IBM Belgium |
| Capgemini Belgium |
| Accenture Belgium |
| Others |
Pricing and Supply Chain Analysis
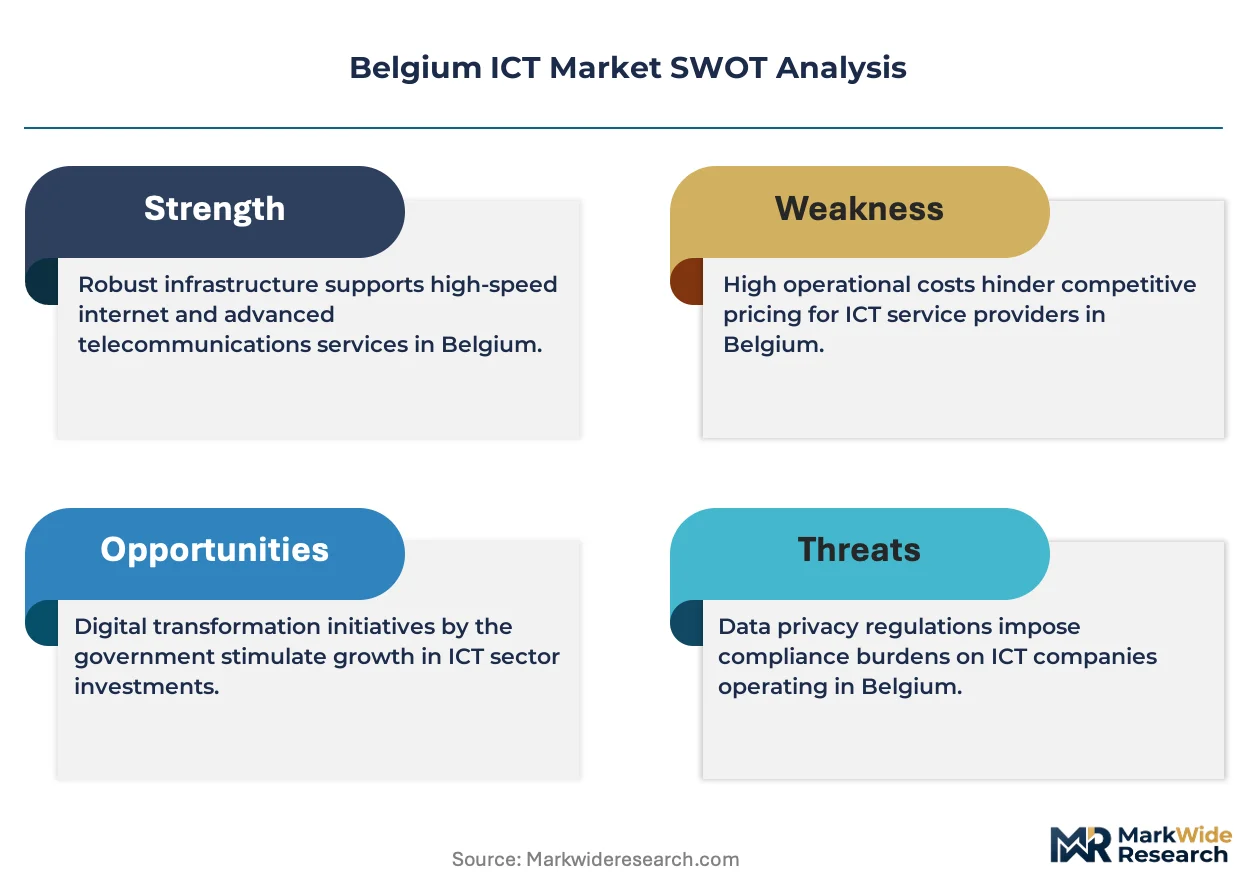
Undercapacity in sovereign cloud infrastructure across Brussels-Capital Region drives premium pricing for BIS-certified encryption modules while compressing procurement timelines for NIS2-compliant service providers competing for federal ministry contracts.
Pricing Analysis
Cost-plus contracts with semiconductor price indexation dominate hardware procurement for edge computing deployments across Wallonia's industrial zones. Three-tier pricing structure across premium, standard, and economy levels separates sovereign cloud providers with full BIS certification from hybrid operators with partial compliance and commodity resellers lacking encryption validation. Pricing pressure stems from mid-market enterprises unbundling traditional managed service contracts in favor of consumption-based metered models. SMEs exhibit highest price sensitivity due to constrained IT budgets, while federal government buyers prioritize compliance over cost.
Supply Chain Analysis
Export-control regimes limiting advanced semiconductor shipments constrain server processor availability for Belgian data center operators building sovereign cloud capacity. Supply concentration centers on Taiwan, South Korea, and USA for high-performance computing chips, with Netherlands and Germany anchoring networking equipment flows. Raw material dependencies span rare earth elements for magnetic storage, lithium for backup power systems, and high-purity silicon for chip fabrication. Single-source vulnerability runs through advanced node semiconductor foundries. Distribution runs through systems integrators with vertical specialization in NIS2 compliance and direct manufacturer relationships for hyperscale cloud providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Belgium's ICT market represents early-cycle expansion as NIS2 transposition accelerates cybersecurity procurement across critical infrastructure operators previously exempt from mandatory upgrade timelines.
For Market Incumbents: Insulate fiber backbone assets through accelerated rural deployment ahead of municipal permitting reform, while deepening cybersecurity service portfolios to capture NIS2-mandated security operations center demand from energy and healthcare operators facing statutory deadlines. Proximus Group and Orange Belgium must defend against emerging sovereign cloud specialists by securing BIS certification for encryption modules before competitor validation completes. For New Entrants and Emerging Players: Mid-market logistics firms in Antwerp port zones represent the most penetrable entry point for 5G private network integration, with automated guided vehicle deployments creating immediate addressable demand for dedicated wireless spectrum solutions. Sovereign cloud provision for Flemish government digital transformation programs offers protected market access through compliance-first positioning rather than price competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sovereign cloud infrastructure as BIS certification requirements and GDPR data residency rules extend deployment timelines and increase facility construction costs. Acquisition targets should emphasize systems integrators with established Belgian Cyber Security Centre audit relationships and existing federal procurement frameworks. The signal to monitor is acceleration in NIS2 enforcement penalties that would compress vendor selection windows and favor incumbent compliance track records.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | BIS encryption module validation creates procurement preference for federal ministry contracts. |
| 5G Private Network Deployment | Port of Antwerp automated guided vehicle integration drives dedicated spectrum allocation. |
| Cybersecurity Service Expansion | NIS2-mandated security operations center demand accelerates across energy distribution operators. |
| Fiber Backbone Extension | Rural enterprise connectivity gaps in Flanders sustain infrastructure investment returns. |
| Edge Computing Infrastructure | Wallonia automotive quality control systems require localized server deployments. |
Research Methodology
The analysis maps cloud services, cybersecurity, hardware, and networking segments, each validated through primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners across Belgian enterprises and public sector entities. Secondary sources include SEC filings from listed telecom operators, hyperscaler capex disclosures, Belgian Cyber Security Centre regulatory guidance documents, and federal procurement databases. Bottom-up demand modeling from enterprise survey responses triangulates against top-down market sizing from operator revenue disclosures.
Assumptions held fixed include NIS2 transposition timelines through the Belgian Cyber Security Centre, GDPR data residency enforcement patterns, and Proximus Group's fiber rollout schedule. Variables tested across sensitivity scenarios encompass mid-market cloud adoption velocity, sovereign cloud certification backlog duration, and edge computing hardware refresh cycles. CAGR derivation rests on segment-level demand elasticity modeling calibrated to Belgian enterprise IT spending patterns. Forecast inputs incorporate BIS certification queue lengths and municipal permitting timelines for rural fiber deployment.
Macroeconomic conditions sit as an overlay; deviation in eurozone interest rate trajectories or Belgian federal budget allocation for digital transformation would shift the trajectory. Material shifts in NIS2 penalty enforcement intensity or EU-wide export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Land Professional Mobile Radio Market
Telecommunications
China ICT Market
Telecommunications
Indonesia Communication Services Market
Telecommunications
Romania Telecom Market
Telecommunications
A2P Messaging Market
Telecommunications
Angola Telecom Market
Telecommunications
Malaysia Telecom Towers Market
Telecommunications
Global Telecom Operations Management Market
Telecommunications
5G Equipment Market
Telecommunications
Standalone 5G Network Market
Telecommunications
Global Relay Market
Telecommunications
Kuwait Telecom Market
Telecommunications
Mftpaas Market
Telecommunications
IoT MVNO (Services) Market
Telecommunications
Global Ip Multimedia Subsystem (Ims) Market
Telecommunications
Indonesia ICT Market