
 Poland Automotive Lubricants Market | 2026-2036
Poland Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Automotive Lubricants Market Analytics
Scheduled fluid analysis and predictive maintenance subscriptions is recalibring how workshops and fleet buyers procure lubricants in Poland. PKN ORLEN leverages its domestic refining network to anchor supply security for commercial channels. Royal Dutch Shell competes through premium synthetic formulations positioned at authorized service centers. FUCHS differentiates via specialized industrial-grade greases targeting mining and agricultural equipment operators.
Automotive lubricants are formulated base oil and additive packages designed to reduce friction, dissipate heat, and prevent wear in powertrain and chassis systems, with viscosity grades typically spanning SAE 0W-16 through 20W-50 depending on operating temperature and mechanical load. Their primary purpose is extending component life while maintaining fuel efficiency across internal combustion and hybrid drivetrains. Engine oil commands the largest revenue pool given high replacement frequency and OEM specification complexity, while transmission fluid generates stronger margins due to synthetic formulation requirements and lower price sensitivity among automatic gearbox owners. The passenger vehicle use case remains structurally dominant in volume terms, though heavy-duty vehicles exhibit faster growth as Polish road freight activity expands and Euro VI compliance intensifies drain interval pressures.
Poland's Office of Competition and Consumer Protection monitors lubricant labeling claims, while EU REACH and RoHS frameworks govern chemical composition and additive restrictions. These regulations elevate formulation costs but simultaneously filter out low-specification imports, tightening market access for non-compliant suppliers. Stakeholders must track how the EU Green Deal's carbon border adjustments and emerging bio-based lubricant standards reshape raw material sourcing decisions and product certification requirements.
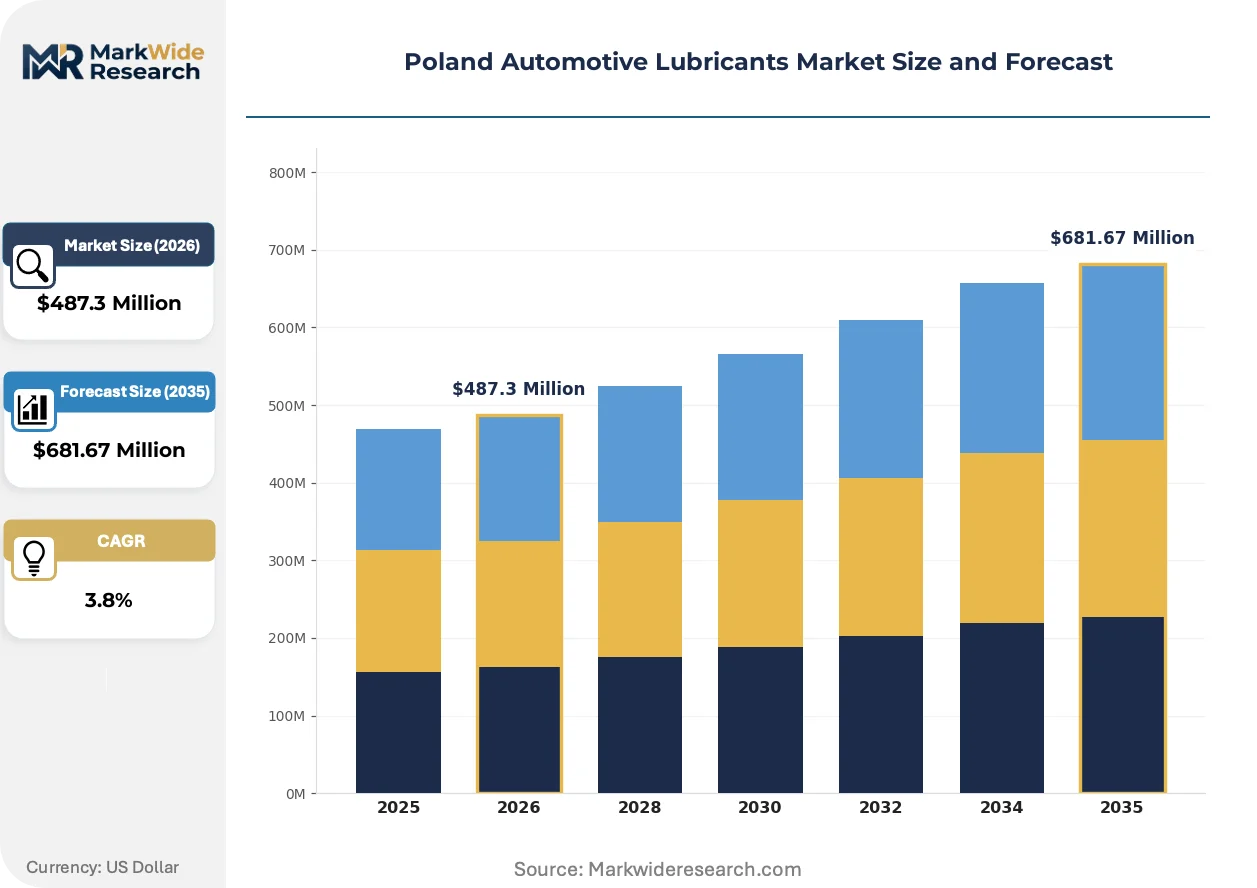
Market Dynamics
Fleet digitization and predictive maintenance platforms are restructuring procurement relationships across Poland's commercial vehicle sector, compressing traditional distributor margins while elevating technical service capabilities as the primary competitive differentiator.
Growth Catalysts
- EU F-Gas Regulation:Tightening emission standards for mobile air conditioning systems are forcing refrigerant-lubricant compatibility upgrades across Polish heavy-duty fleets, creating specification-driven replacement cycles.
- Silesian manufacturing clusters:Concentrated automotive and machinery production around Katowice and Gliwice generate sustained bulk demand for industrial-grade lubricants with specialized additive packages.
- Telematics integration:Connected vehicle platforms enabling real-time oil condition monitoring are shortening preventive maintenance intervals and expanding premium synthetic uptake among logistics operators.
Market Restraints
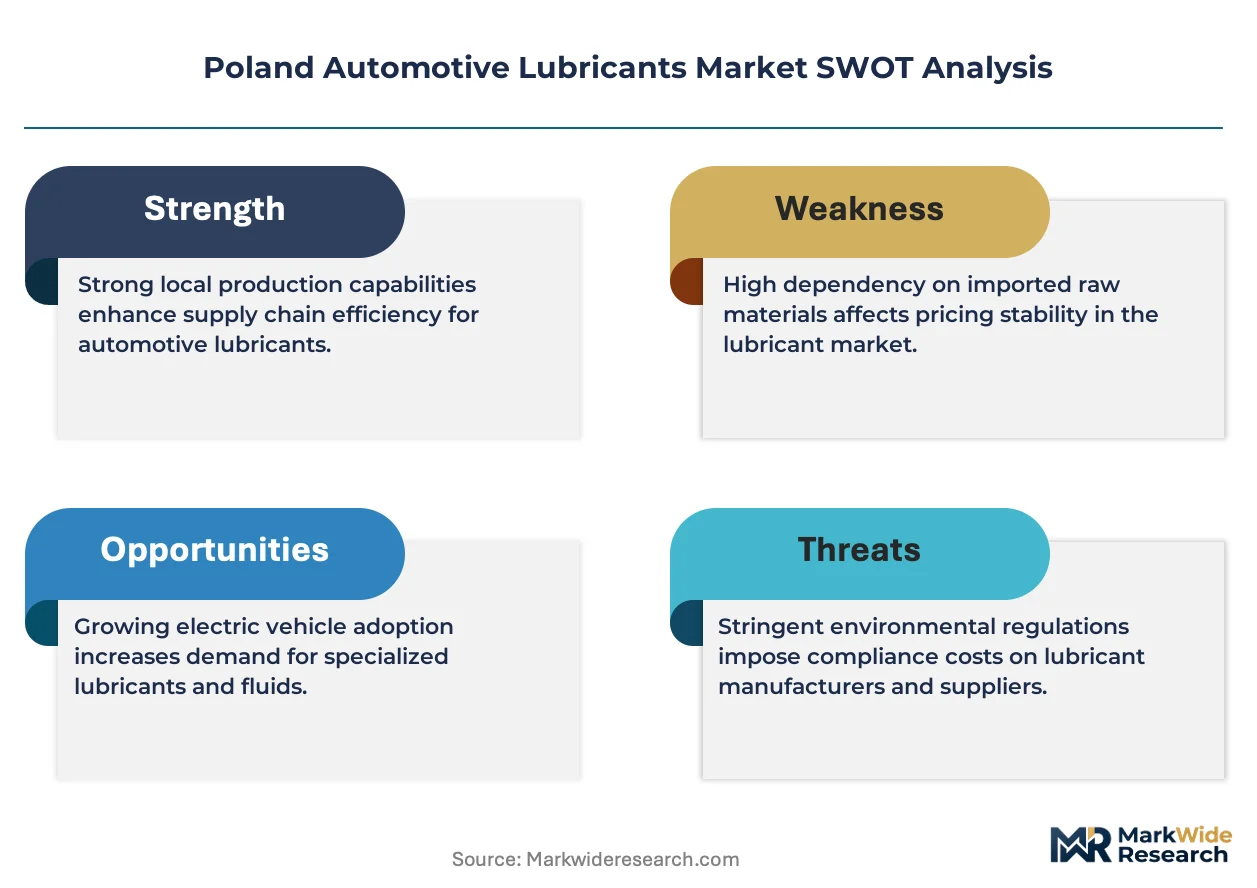
- Base oil import dependency:Poland's limited domestic Group II/III base oil production creates exposure to Rotterdam refinery pricing and Baltic shipping congestion.
- REACH compliance costs:ECHA-mandated substance registration and authorization expenses disproportionately burden small-formulation blenders, consolidating supply toward integrated refiners.
- Extended drain intervals:OEM-specified synthetic oil change periods stretching beyond 30,000 kilometers are structurally suppressing volume consumption per vehicle.
Strategic Opportunities
- Greater Poland logistics corridor:Poznań-Łódź freight hub expansion is attracting international fleet operators with centralized lubricant management requirements.
- Bio-based lubricant standards:Emerging EU Ecolabel criteria and national green public procurement rules are creating certification premiums for renewable-content formulations.
- Workshop subscription platforms:Predictive maintenance software vendors are integrating lubricant replenishment into bundled service contracts, bypassing traditional wholesale channels.
Industry Challenges
- Additive chemist scarcity:Specialized formulators capable of balancing OEM performance specifications with REACH-compliant chemistry command premium compensation and limited labor pool availability.
- Blending facility certification:ISO 14001 and IATF 16949 accreditation timelines stretch 18-24 months, delaying market entry for new domestic producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Automotive Lubricants Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $681.67 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Grease Use Case: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Vehicles, Off-Road Vehicles Distribution Channel: Retail, Online, Wholesalers, Direct Sales Capacity: 1L, 5L, 20L, Bulk |
| Companies Covered | FUCHS, Royal Dutch Shell, BP PLC (Castrol), Liqui Moly, LOTOS OIL, PKN ORLEN, ExxonMobil Corporation, Motul, TotalEnergies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Automotive Lubricants Market Evolving Landscape
Synthetic formulation chemistry and digital fleet management platforms are converging to redefine value capture in Poland's automotive lubricants sector, shifting competitive advantage from volume scale toward technical specification authority.
Low-viscosity SAE 0W-16 and 0W-20 engine oils engineered for turbocharged gasoline direct injection engines are rewriting service interval economics for Polish passenger car workshops. Independent garages in Warsaw and Kraków metropolitan areas are adopting these specifications at accelerating rates to retain warranty-compliant service authority. The technology is compressing conventional mineral oil demand while elevating synthetic blend premiums in urban service centers.
Poland's Office of Competition and Consumer Protection intensified scrutiny of lubricant performance claims and labeling accuracy during 2023-2024 enforcement cycles. The regulator's test-purchase programs and additive disclosure requirements are elevating compliance costs for imported private-label products. Domestic blenders with established quality documentation systems are capturing shelf space formerly occupied by non-compliant suppliers in retail automotive channels.
Subscription-based fluid analysis programs are displacing calendar-based oil change scheduling among commercial fleet operators with centralized maintenance operations. Major Polish logistics companies operating Euro VI tractor units are negotiating enterprise lubricant agreements tied to laboratory monitoring rather than distance intervals. This behavioral shift concentrates procurement authority with technical procurement departments and reduces spot-market purchasing across the Masovian and Lower Silesian voivodeships.
Poland Automotive Lubricants Market Segmentation
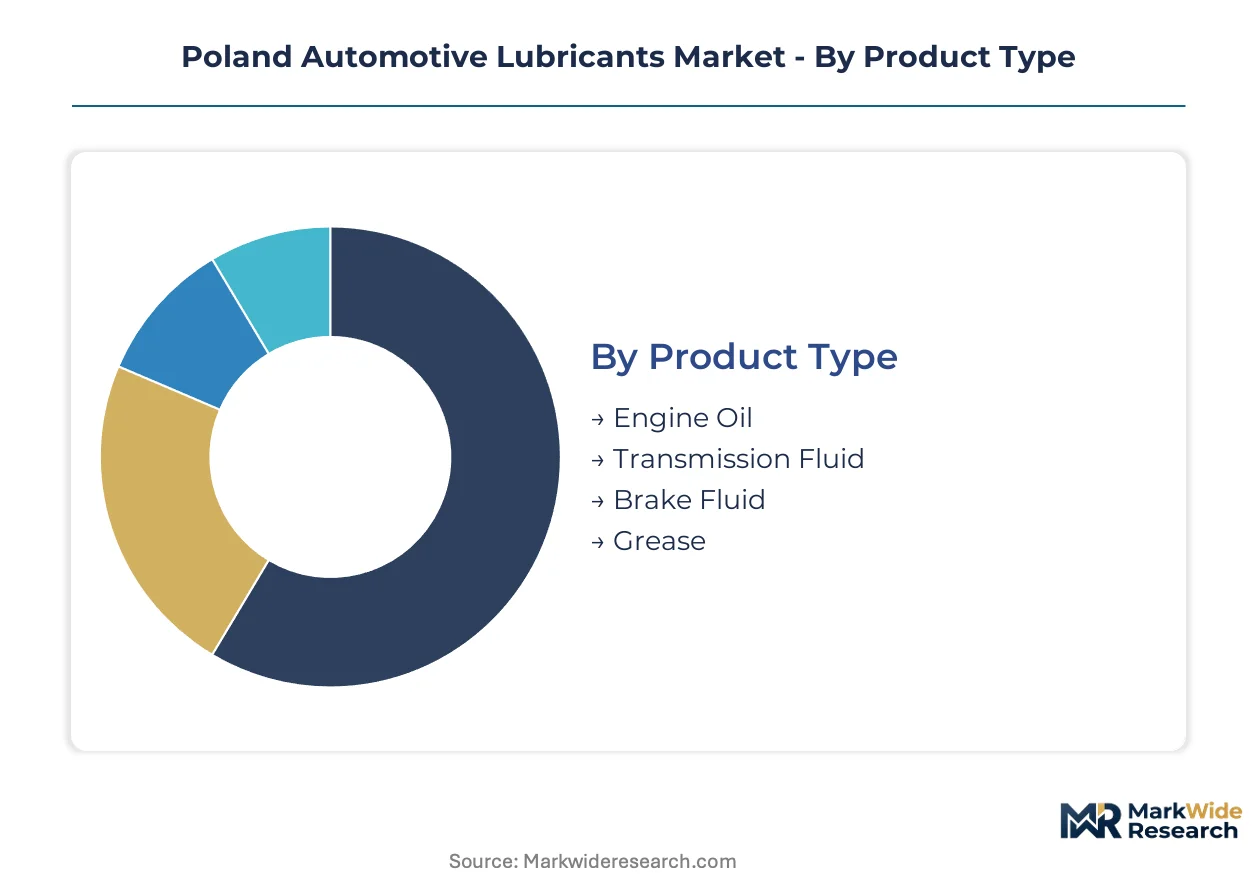
Segmentation in Poland's automotive lubricants market reveals how specification complexity and procurement channel fragmentation create distinct competitive arenas. Each dimension exposes different margin structures and customer loyalty mechanisms that suppliers must navigate strategically.
Product Type:
Upgrade cycles and replacement frequency vary dramatically across lubricant categories, with some formulations commanding technical premiums while others compete on volume throughput.
- Engine Oil:Formulated from base oil stocks with detergent-dispersant and anti-wear additive packages meeting ACEA and API specifications. Demand concentrates in Warsaw and Kraków metropolitan service centers where turbocharged gasoline direct injection engines require low-viscosity 0W-16 and 0W-20 grades. OEM warranty compliance pressures elevate synthetic blend premiums.
- Transmission Fluid:Specialized synthetic formulations with friction modifiers and shear stability additives for automatic and dual-clutch gearboxes. Fleet operators in the Greater Poland logistics corridor negotiate centralized procurement contracts for ATF and DCTF specifications. Lower price sensitivity among automatic gearbox owners sustains margin premiums.
- Brake Fluid:Glycol-ether or silicone-based hydraulic fluids meeting DOT 4 and DOT 5.1 boiling point specifications. Workshops in Silesian manufacturing clusters stock DOT 4 LV for ABS-equipped commercial vehicles.
- Grease:Thickened lubricants with lithium complex or calcium sulfonate bases for chassis and bearing applications. Mining equipment operators in Lower Silesia specify NLGI Grade 2 greases with extreme pressure additives.
Engine Oil sits at the top of the volume ranking, with Transmission Fluid climbing the fastest as automatic gearbox penetration rises among Polish passenger vehicles.
Use Case:
Cost tier differentiation separates high-frequency consumer replacements from capital-intensive fleet maintenance programs with enterprise-scale procurement authority.
- Passenger Vehicles:Individual owners and lease operators performing scheduled maintenance at authorized service centers and independent garages. Urban workshops in Warsaw and Kraków drive synthetic formulation uptake to retain warranty-compliant service authority.
- Commercial Vehicles:Light commercial fleets and delivery operators with centralized maintenance contracts. Logistics companies along the Poznań-Łódź freight corridor negotiate lubricant management agreements tied to telematics monitoring.
- Heavy-Duty Vehicles:Euro VI tractor units and long-haul fleets operating across Polish and EU corridors. Drain interval extension pressures from OEM specifications compress volume per vehicle while elevating synthetic grade requirements.
- Off-Road Vehicles:Agricultural machinery and construction equipment operating in contaminated environments. Equipment owners in Greater Poland and Podlaskie voivodeships prioritize contamination-resistant formulations with enhanced detergent packages.
Passenger Vehicles capture the largest volume share, though Heavy-Duty Vehicles are expanding most quickly as Polish road freight activity intensifies.
Distribution Channel:
Customer type and procurement sophistication determine channel selection, with digital platforms displacing traditional wholesale relationships among technically advanced buyers.
- Retail:Automotive parts stores and service station convenience formats serving DIY maintenance and emergency top-up demand. PKN ORLEN's domestic retail network dominates shelf presence for conventional grades.
- Online:E-commerce platforms and direct-to-consumer channels capturing specification-savvy buyers. Independent garages in metropolitan areas source boutique synthetic formulations through specialized digital distributors.
- Wholesalers:Traditional lubricant distributors serving independent workshops and regional service chains. Margin compression from fleet digitization pressures traditional wholesale economics across Masovian voivodeship.
- Direct Sales:Manufacturer-to-fleet contracts and enterprise lubricant management agreements. Major logistics operators negotiate laboratory-monitored fluid analysis programs bypassing distributor intermediaries.
Retail maintains volume leadership, while Direct Sales gains share fastest as predictive maintenance platforms restructure procurement relationships.
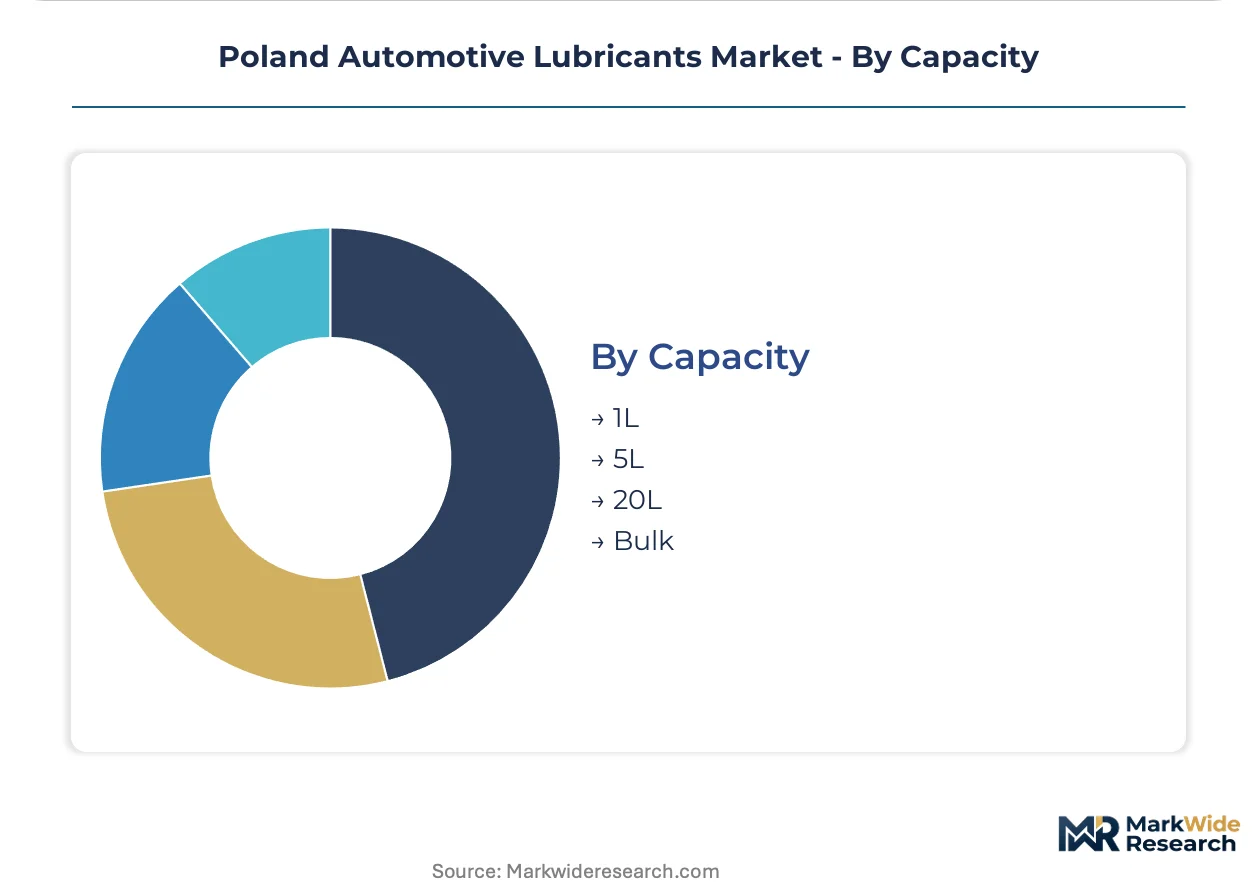
Capacity:
Supply concentration and packaging economics create distinct competitive dynamics across volume tiers, from consumer convenience formats to industrial bulk handling infrastructure.
- 1L:Single-serve packaging for emergency top-ups and specialty applications. Urban service centers stock 1L containers of specified grades for warranty-compliant top-off services.
- 5L:Standard workshop format for passenger vehicle oil changes and small fleet maintenance. Independent garages in Kraków metropolitan area prefer 5L packaging for inventory efficiency.
- 20L:Intermediate bulk format for commercial workshops and mid-size fleet operations. Regional distributors in Silesian voivodeship maintain 20L stocks for manufacturing cluster demand.
- Bulk:Tanker and tote deliveries for large fleet operators and industrial consumers. Centralized maintenance facilities at Poznań-Łódź logistics hubs receive bulk synthetic deliveries with on-site storage.
5L packaging holds the highest volume position, with Bulk deliveries climbing fastest as fleet consolidation concentrates procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive lubricant demand dwarfs Poland's by a factor of four, yet Poland's freight corridor expansion is narrowing the growth rate gap between these neighboring markets. Regional supply chains increasingly integrate Polish blending capacity with German additive chemistry expertise. Cross-border fleet operations between these economies are synchronizing specification standards across Central Europe.
Silesian Voivodeship
Katowice-Gliwice manufacturing clusters generate concentrated bulk demand for industrial-grade lubricants with extreme-pressure additive packages. The EU F-Gas Regulation drives refrigerant-lubricant compatibility upgrades across heavy-duty fleets operating from this region. Mining equipment operators in Lower Silesia specify NLGI Grade 2 greases for contaminated underground environments.
Greater Poland Voivodeship
Poznań-Łódź logistics corridor expansion attracts international fleet operators with centralized lubricant management requirements. REACH compliance costs filter out low-specification imports, tightening market access for non-compliant suppliers. Regional distributors maintain 20L intermediate bulk stocks to serve mid-size fleet operations along this freight axis.
Masovian Voivodeship
Warsaw metropolitan service centers drive synthetic formulation uptake to retain warranty-compliant service authority for turbocharged gasoline direct injection engines. Poland's Office of Competition and Consumer Protection intensified scrutiny of lubricant labeling claims during 2023-2024 enforcement cycles. Independent garages in the capital source boutique synthetic formulations through specialized digital distributors.
Lesser Poland Voivodeship
Kraków's urban workshops prefer 5L packaging for inventory efficiency in passenger vehicle maintenance. Telematics integration among commercial operators shortens preventive maintenance intervals and expands premium synthetic uptake. The voivodeship's tourism and logistics mix creates diverse viscosity grade requirements across seasonal demand patterns.
Lower Silesian Voivodeship
Wrocław's industrial base sustains demand for specialized hydraulic fluids and transmission formulations. Euro VI compliance intensifies drain interval pressures on long-haul fleets crossing Polish-German-Czech borders. Bulk synthetic deliveries with on-site storage serve centralized maintenance facilities at regional logistics hubs.
Poland Automotive Lubricants Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated refiners commanding supply security advantages in commercial channels while formulation specialists capture premium margins in technical applications. The market structure concentrates around three archetypes: domestic integrated refiners with captive base oil supply, international majors with synthetic formulation portfolios, and specialized industrial lubricant formulators. Consolidation pressures favor players with backward integration into additive chemistry or forward integration into fleet management platforms. Strategic partnerships between blenders and telematics providers are restructuring procurement relationships faster than capacity expansion alone.
Among domestic integrated operators, PKN ORLEN anchors supply security for commercial channels through its refining network, while LOTOS OIL occupies a comparable position in Baltic-adjacent markets. International majors including Royal Dutch Shell and FUCHS exemplify divergent specialization strategies—Shell through premium synthetic positioning at authorized service centers, FUCHS via industrial-grade grease expertise targeting mining and agricultural equipment operators. These three represent distinct competitive vectors: captive supply, premium brand authority, and technical specification depth.
| Leading Market Players |
|---|
| FUCHS |
| Royal Dutch Shell |
| BP PLC (Castrol) |
| Liqui Moly |
| LOTOS OIL |
| PKN ORLEN |
| ExxonMobil Corporation |
| Motul |
| TotalEnergies |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between REACH-compliant synthetics and gray-market mineral imports splits Poland's lubricant market into parallel supply ecosystems with divergent margin structures. Premium formulations commanding OEM warranty authority flow through authorized service networks with fixed-price contracts, while commodity grades compete on spot-market volatility sensitive to Rotterdam base oil quotations.
Pricing Analysis
Capacity additions in Germany and the Netherlands are reshaping price floors for Group III base oils reaching Polish blenders. Pricing stratifies across premium synthetic, mid-tier blend, and economy mineral tiers, with differentiation driven by ACEA certification level and volume commitment scale. Cost compression in the economy tier intensifies as Ukrainian and Belarusian gray-market imports undercut compliant suppliers. Fleet procurement departments exhibit lowest price sensitivity, while independent garages in secondary cities remain highly elastic.
Supply Chain Analysis
Used oil collection and re-refinement flows are gaining regulatory support under Poland's extended producer responsibility frameworks, creating circular feedstock alternatives to virgin base oils. Primary supply draws from Germany, the Netherlands, and Belgium for Group II/III base stocks, with additive packages sourced from France and the United States. Single-source vulnerability concentrates in polyalphaolefin synthetic bases from Belgian refineries. Distribution runs through PKN ORLEN's domestic terminal network for bulk deliveries, supplemented by regional distributors handling packaged goods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in synthetic formulation upgrades and predictive maintenance service bundling, as fleet operators trade volume discounts for technical integration fees.
For Market Incumbents: Extend backward integration into additive chemistry or forward integration into telematics platforms to defend against workshop subscription vendors displacing traditional wholesale channels. Prioritize ISO 14001 and IATF 16949 certification investments to filter out low-specification competitors. Lock in long-term supply agreements with Rotterdam refineries before carbon border adjustments reshape import economics. For New Entrants and Emerging Players: Bio-based lubricant certification gaps create entry pathways for renewable-content formulators targeting Polish public procurement tenders. The Greater Poland logistics corridor offers the most penetrable geography, with mid-size fleet operators underserved by enterprise-scale suppliers. Lead with laboratory-monitored fluid analysis subscriptions rather than commodity volume plays. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance costs disproportionately burden small-formulation blenders without captive base oil supply. Five-to-ten-year viability favors integrated operators with additive chemistry partnerships or fleet management platform integrations. Monitor ECHA substance authorization timelines for early signals of formulation cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Chemistry | Captive supply of REACH-compliant packages reduces exposure to ECHA authorization delays. |
| Predictive Maintenance Platform Partnership | Telematics integration locks in fleet procurement contracts bypassing distributor intermediaries. |
| Bio-Based Lubricant Certification Investment | EU Ecolabel qualification unlocks green public procurement premiums in Polish tenders. |
| Regional Blending Facility Expansion | Greater Poland hub proximity to Poznań-Łódź freight corridor reduces logistics costs. |
| Workshop Subscription Service Launch | Laboratory-monitored fluid analysis displaces calendar-based purchasing with recurring revenue. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with lubricant procurement managers at Polish fleet operators, technical directors at blending facilities, aftermarket distributors in Silesian and Greater Poland voivodeships, and regulatory affairs specialists familiar with REACH implementation. Secondary validation drew from Polish Customs Service trade statistics, ECHA substance registration databases, ACEA oil sequences documentation, and vehicle registration data from Polish automotive associations. Bottom-up volume estimates triangulated against top-down market sizing from refinery output and import records.
Historical reference periods anchored the projection horizon through regression analysis of base oil price elasticity, fleet expansion rates, and regulatory compliance cost trajectories. Segmentation modeling spanned product type, use case, distribution channel, and packaging capacity tier, with propulsion architecture and OEM warranty specification complexity as automotive-specific dimensions. CAGRs derived from trend extrapolation adjusted for drain interval extension effects and synthetic penetration rates. Forecast inputs incorporated telematics adoption curves and EU Green Deal carbon border adjustment timelines.
The model holds under stable REACH authorization schedules and continued Euro VI enforcement; deviation in ECHA substance restriction timelines or base oil supply disruptions would shift volume and value trajectories. Practitioners should monitor ECHA candidate list updates and Rotterdam refinery utilization rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
United Arab Emirates Lubricants Market
Lubricants
Europe Marine Lubricants Market
Lubricants
Global Hydraulic Fluid Market
Lubricants
Malaysia Automotive Engine Oils Market
Lubricants
Egypt Lubricants Market
Lubricants
Global Mineral Oil Market
Lubricants
North America Lubricants Market
Lubricants
Lube Skid Market
Lubricants
Canada Lubricants Market
Lubricants
Bulgaria Lubricants Market
Lubricants
Brazil Lubricants Market
Lubricants
Philippines Lubricants Market
Lubricants
Malaysia Automotive Lubricants Market
Lubricants
Russia Lubricants Market
Lubricants
Bulgaria Passenger Vehicles Lubricants Market
Lubricants
Aviation Lubricants Market