
 Egypt Lubricants Market | 2026-2036
Egypt Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Lubricants Market Foresight
Egypt's environmental compliance push under GAP guidelines is expanding demand for higher-grade lubricant formulations. Shell plc leverages its global R&D network to sustain premium engine oil positioning in Cairo's aftermarket channels. Misr Petroleum anchors domestic supply through its Suez-based refining complex, while AMOC competes on industrial-grade hydraulic oils for Nile Delta manufacturing zones.
Lubricants are formulated mixtures of base oils and performance additives designed to reduce friction, dissipate heat, and prevent wear in mechanical systems, with viscosity grades such as 5W-30 and 15W-50 denoting cold-start flow and high-temperature stability properties. Engine Oil dominates volume consumption across Egypt's vehicle parc, while Hydraulic Oil captures margin concentration in Alexandria's port machinery and Suez Canal logistics infrastructure. The Aftermarket segment leads value realization as fleet operators and independent workshops prioritize extended-drain synthetic formulations over conventional mineral products.
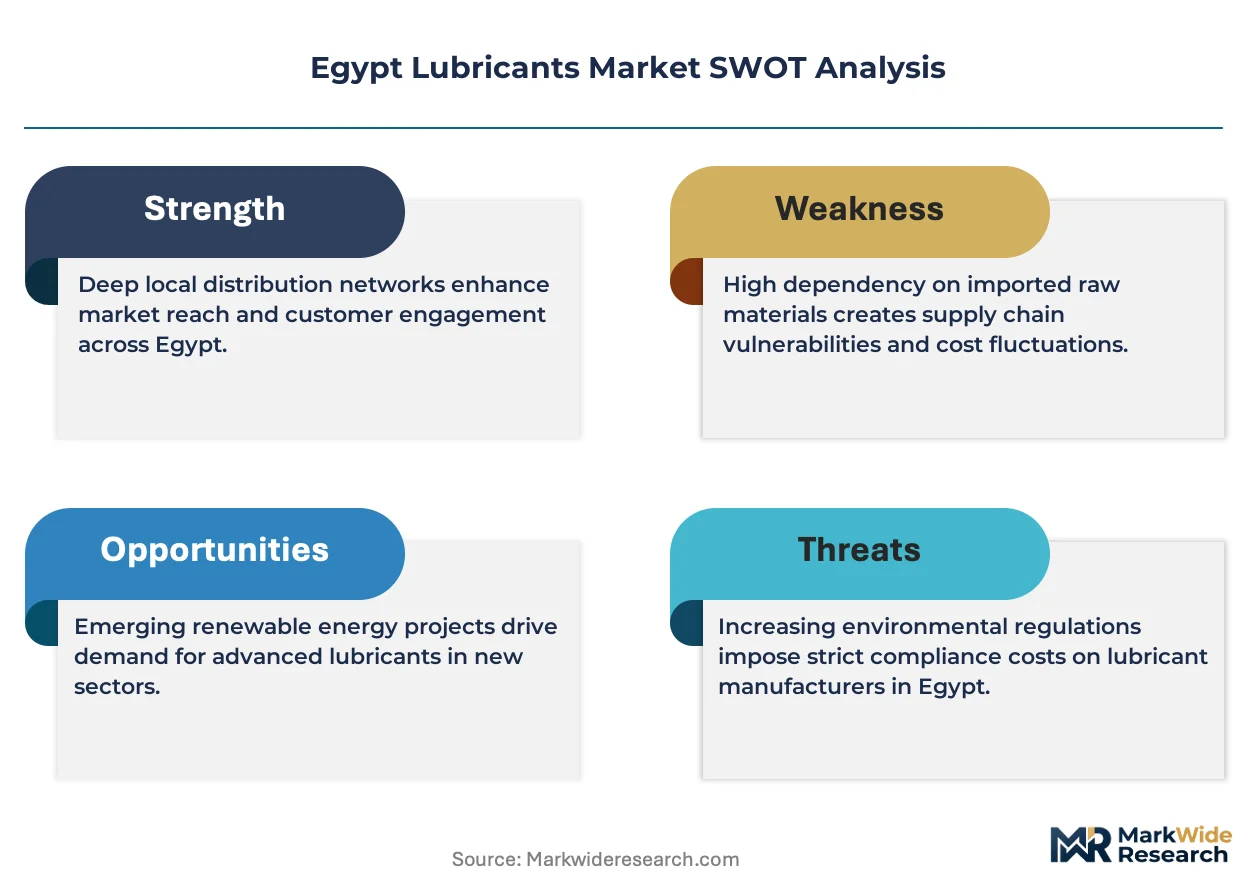
Egypt's General Authority for Petroleum (GAP) and the Egyptian Organization for Standardization and Quality (EOS) enforce base oil classification and additive content rules that shape import licensing and local blending requirements. The Ministry of Trade and Industry applies import tariff structures that influence pricing parity between domestic producers and Gulf-sourced finished lubricants. Stakeholders must monitor GAP's evolving specifications for sulfur content and biodegradability thresholds to align product portfolios with compliance trajectories.
Market Dynamics
Egypt's lubricant demand structure is pivoting around GAP's tightening base oil quality mandates, which force domestic blenders to upgrade formulation standards while creating procurement friction for importers unable to meet sulfur content thresholds.
Growth Catalysts
- Commercial Fleet Modernization:Cairo-based logistics operators are consolidating vehicle procurement around Euro 5-compliant engines that require synthetic 5W-30 and 0W-20 formulations, expanding the addressable premium lubricant pool.
- Industrial Corridor Concentration:Alexandria's port machinery and Suez Canal logistics infrastructure generate concentrated demand for high-performance hydraulic oils and marine cylinder lubricants with extended drain intervals.
- GAP Quality Enforcement:Egypt's General Authority for Petroleum base oil reclassification rules are phasing out Group I imports, creating volume pull for Group II and III base stocks through licensed domestic blending facilities.
Market Restraints
- Base Oil Import Dependency:Egypt lacks domestic Group II/III base oil production, forcing reliance on Gulf Cooperation Council refiners whose pricing power compresses blender margins during feedstock volatility.
- Technical Specification Gaps:Independent workshops in Upper Egypt lack viscosity testing equipment, limiting adoption of multi-grade synthetic formulations despite OEM recommendations.
- Substitution Pressure:Extended-drain synthetic formulations are reducing per-vehicle lubricant consumption volumes, offsetting fleet expansion effects in unit terms.
Strategic Opportunities
- Biodegradable Hydraulic Fluids:GAP's evolving biodegradability thresholds for Nile Delta agricultural machinery create first-mover positioning for vegetable-oil-based hydraulic formulations.
- Direct Fleet Contracting:Cairo's consolidated transport operators are bypassing traditional distributor networks for direct blender relationships, enabling volume-locked pricing structures.
- Suez Canal Marine Services:Vessel traffic through the canal expansion zone requires specialized slow-speed engine oils and stern tube lubricants with IMO 2020 sulfur compliance.
Industry Challenges
- Formulation Chemist Shortage:Egypt's technical universities produce limited lubricant-specific chemical engineers, constraining domestic R&D capacity for additive package customization.
- Certification Timeline Compression:EOS approval cycles for new lubricant grades lag product development by 8-14 months, delaying market entry for reformulated synthetic lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Lubricants Market |
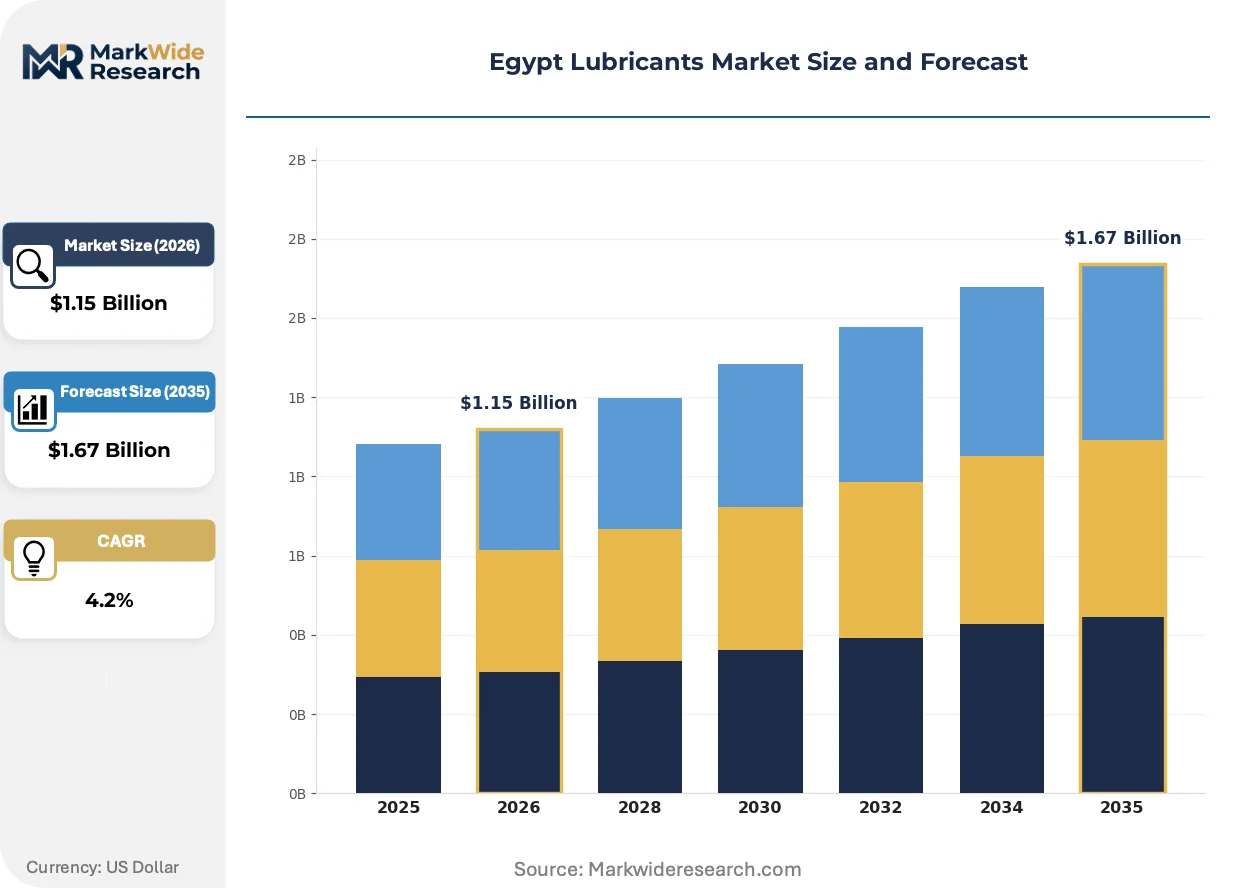
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $1.67 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Hydraulic Oil, Grease Viscosity Grade: 5W-30, 10W-40, 15W-50, ISO VG 32 Application: Automotive, Industrial, Marine, Agricultural End User: OEMs, Aftermarket, Service Stations, Fleet Operators |
| Companies Covered | Misr Petroleum, ADNOC Distribution, Shell plc, FUCHS, AMOC, Exxon Mobil Corporation, BP plc, Chevron Corporation, TotalEnergies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Lubricants Market Shifts & Advancements
Formulation chemistry and procurement channels are undergoing parallel transformation as synthetic base stocks and direct fleet engagement models displace legacy mineral oil distribution structures across Egypt's commercial vehicle and industrial segments.
Group III synthetic base oils are overtaking Group II formulations in Cairo's premium aftermarket channels. Fleet operators managing Euro 5 and Euro 6 diesel engines specify 5W-30 and 0W-20 grades to meet OEM warranty requirements. This specification compression is forcing independent workshops to upgrade bulk storage infrastructure or cede service contracts to authorized dealer networks.
GAP's 2024 base oil reclassification framework mandates sulfur content below 0.03% for all imported Group II stocks, eliminating several Gulf-sourced supply options. Domestic blenders with Suez-based storage terminals are securing preferential licensing status. Importers without captive blending capacity face extended customs clearance procedures at Alexandria port.
Fleet procurement centralization is restructuring Cairo's distribution hierarchy. Consolidated logistics operators with 500+ vehicle fleets negotiate direct supply agreements with blenders, extracting 12-18% price concessions against distributor list prices. Traditional channel intermediaries are repositioning toward technical services and inventory financing rather than pure product resale.
Egypt Lubricants Market Segmentation
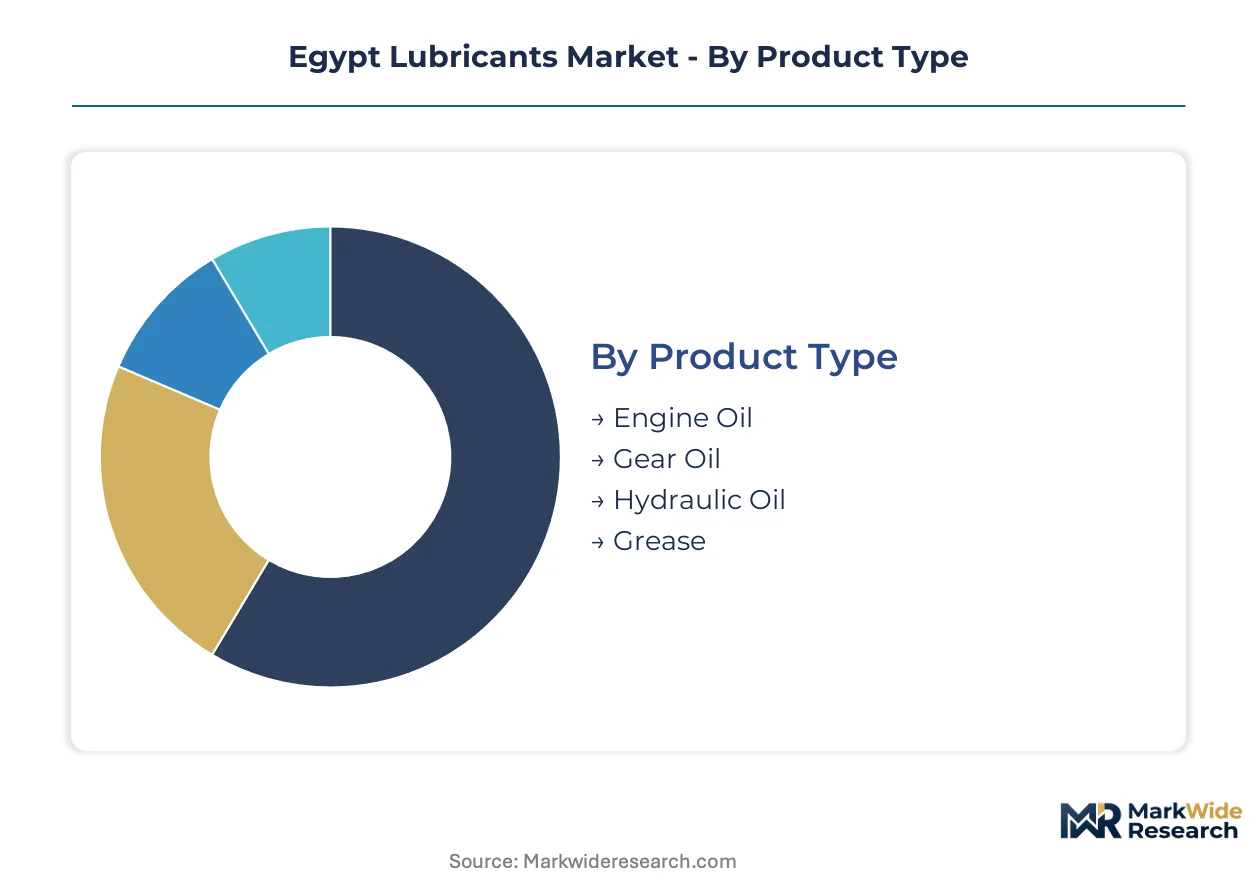
Egypt's lubricant segmentation reflects the tension between GAP-mandated formulation upgrades and the uneven technical capacity across Cairo's premium channels versus Upper Egypt's service infrastructure. Specification compression in automotive and industrial segments is fragmenting procurement patterns and margin structures.
Product Type:
Viscosity index improvers, detergent packages, and friction modifiers distinguish formulation tiers across Egypt's blending facilities.
- Engine Oil:Base oil blends with dispersant and anti-wear additives protect against piston deposits and camshaft wear. Cairo's Euro 5-compliant commercial fleets specify synthetic 5W-30 grades, though Group I mineral formulations still dominate volume in independent Upper Egypt workshops lacking multi-grade testing equipment.
- Hydraulic Oil:Anti-foam and rust inhibitor packages maintain viscosity stability under high-pressure pump cycling. Alexandria's port machinery and Suez Canal logistics infrastructure generate concentrated demand for zinc-free formulations with extended drain intervals, while Nile Delta agricultural equipment operators face GAP pressure to adopt biodegradable vegetable-oil-based alternatives.
- Gear Oil:Extreme-pressure sulfur-phosphorus compounds protect hypoid gear sets from scoring and pitting. Heavy-duty truck differentials in Cairo-Alexandria corridor fleet operations specify synthetic 75W-90 grades.
- Grease:Thickener systems (lithium complex, calcium sulfonate) suspend base oil for slow-speed bearing applications. Cement plants and steel mills in Suez industrial zones consume high-temperature NLGI Grade 2 formulations.
Engine Oil leads on scale; Hydraulic Oil leads on momentum.
Viscosity Grade:
Cold-crank simulation and high-temperature high-shear testing differentiate specification acceptance across Egypt's climate zones.
- 5W-30:Low-temperature pumpability ratings down to -30°C enable reliable cold starts. Cairo's consolidated logistics fleets with Euro 5/6 engines specify this grade for OEM warranty compliance, forcing bulk infrastructure upgrades at service stations.
- 10W-40:Semi-synthetic formulations balance cost and performance for mixed-duty commercial vehicles. Alexandria's port trucking operators favor this grade for moderate ambient temperature ranges.
- 15W-50:High-temperature viscosity retention suits older diesel engines without turbocharger protection requirements. Upper Egypt's temperature extremes and aged vehicle parc sustain residual demand.
- ISO VG 32:Kinematic viscosity at 40°C defines hydraulic system efficiency. Precision manufacturing in Cairo's industrial corridors specifies this grade for machine tool lubrication circuits.
5W-30 commands premium positioning; 15W-50 retains volume in legacy segments.
Application:
Operating environment severity and equipment utilization rates determine additive package intensity across Egyptian end-uses.
- Automotive:Passenger car and commercial vehicle engines, transmissions, and axles consume the majority of Egypt's lubricant volume. Cairo's fleet modernization toward Euro 5 compliance is accelerating synthetic formulation penetration.
- Industrial:Hydraulic systems, compressors, and gearboxes in manufacturing clusters require contamination control and extended service intervals. Alexandria's port machinery generates specialized demand.
- Marine:Slow-speed crosshead engines and stern tube systems in Suez Canal transit traffic need IMO 2020 sulfur-compliant cylinder oils with high base number detergency.
- Agricultural:Tractor engines and hydraulic implements in Nile Delta farming zones face emerging GAP biodegradability mandates for soil-contact applications.
Automotive anchors volume consumption; Marine offers steepest expansion trajectory.
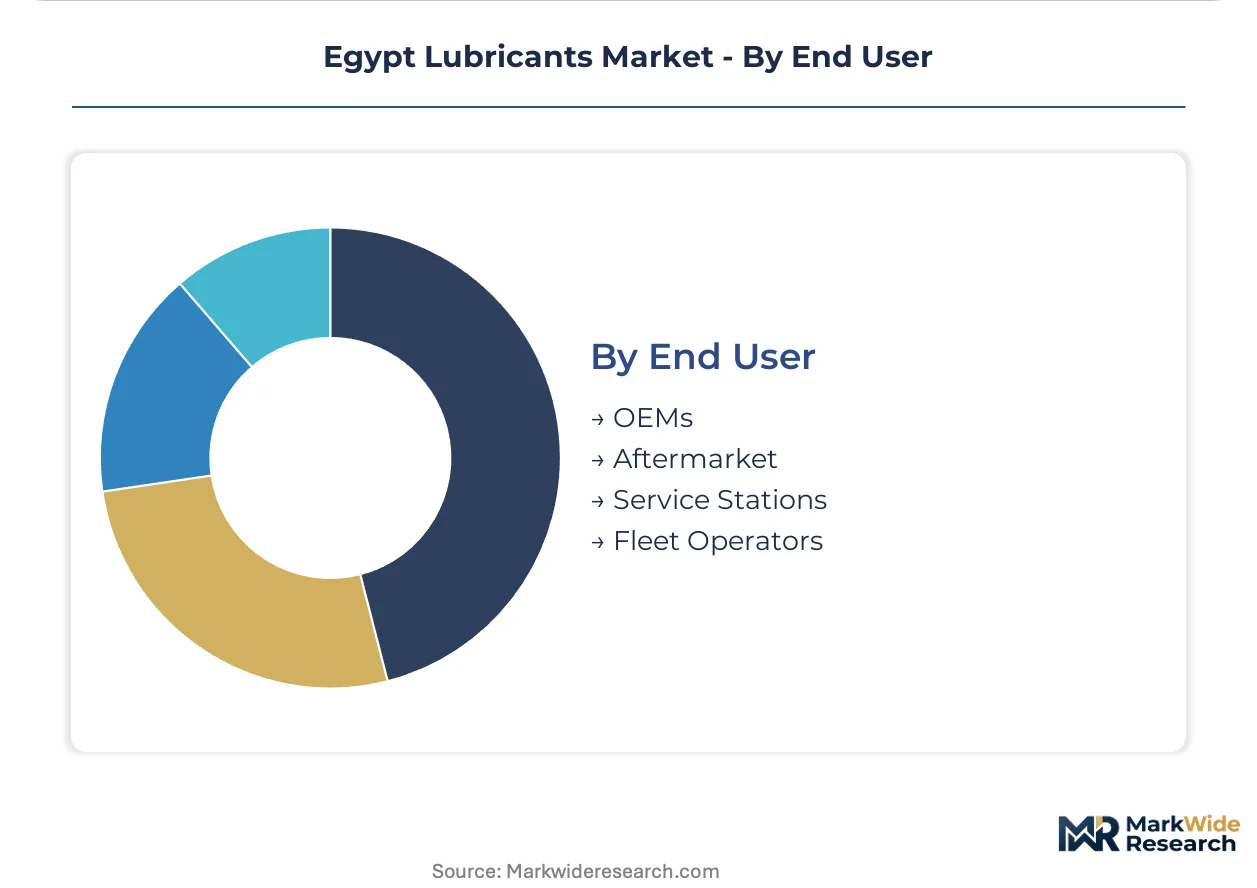
End User:
Procurement sophistication and technical specification authority vary sharply across Egypt's distribution hierarchy.
- OEMs:Vehicle and equipment manufacturers specify factory-fill lubricants for warranty coverage. Cairo-based commercial vehicle assemblers increasingly mandate synthetic grades for new unit releases.
- Aftermarket:Independent workshops and parts retailers dominate volume distribution. Technical specification gaps in Upper Egypt limit synthetic adoption despite OEM recommendations.
- Service Stations:Branded fuel retail networks with captive lubricant supply agreements control premium positioning in Greater Cairo.
- Fleet Operators:Consolidated logistics companies with 500+ vehicle parcs negotiate direct blender contracts, extracting price concessions and technical service bundling.
Aftermarket captures unit volume; Fleet Operators concentrate margin extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized lubricant formulation chemists and petroleum engineers concentrate in Cairo-Alexandria corridor refineries and blending facilities, anchoring technical capacity for GAP-compliant production.
Greater Cairo
Consolidated logistics fleets with 500+ vehicles specify synthetic 5W-30 grades for Euro 5 compliance. GAP's base oil reclassification mandates sulfur content below 0.03% for Group II imports. Cairo's industrial zones house Misr Petroleum's blending infrastructure serving aftermarket channels.
Alexandria
Port machinery and Suez Canal logistics generate concentrated demand for zinc-free hydraulic oils. The Egyptian Organization for Standardization and Quality enforces additive content rules for marine cylinder lubricants. Alexandria's manufacturing clusters consume ISO VG 32 hydraulic fluids for precision machine tools.
Suez Canal Zone
Vessel traffic requires IMO 2020 sulfur-compliant slow-speed engine oils and stern tube lubricants. The Ministry of Trade and Industry applies import tariffs influencing pricing parity for Gulf-sourced finished lubricants. Suez-based storage terminals secure preferential GAP licensing status for domestic blenders.
Nile Delta
Agricultural equipment operators face emerging GAP biodegradability mandates for soil-contact hydraulic applications. Egypt's General Authority for Petroleum guidelines phase out Group I base oil imports. Manufacturing zones in Mansoura and Tanta consume industrial greases for cement and steel processing.
Upper Egypt
Aged vehicle parc sustains residual 15W-50 mineral oil demand despite OEM synthetic recommendations. Technical specification gaps limit multi-grade adoption where viscosity testing equipment is scarce. Asyut and Luxor workshops rely on conventional formulations for older diesel engines.
Egypt Lubricants Market Competitive Landscape
Capital-heavy integrated refiners compete with asset-light specialized blenders for positioning across Egypt's specification-compressed lubricant tiers. The market structures around three archetypes: state-linked petroleum entities with captive refining, multinational oil majors leveraging global R&D networks, and regional distributors optimizing import logistics. Consolidation pressures favor domestic blenders with Suez storage terminals under GAP's tightened import licensing. Competitive moves center on direct fleet contracting bypassing traditional distribution and formulation upgrades to Group III synthetic base stocks.
Within the state-anchored tier, Misr Petroleum and AMOC exemplify integrated domestic supply with Suez-based refining and blending infrastructure. Shell plc occupies a position representing multinational majors deploying global formulation standards through Cairo's premium aftermarket channels. ADNOC Distribution anchors Gulf-origin supply relationships serving import-dependent segments.
| Leading Market Players |
|---|
| Misr Petroleum |
| ADNOC Distribution |
| Shell plc |
| FUCHS |
| AMOC |
| Exxon Mobil Corporation |
| BP plc |
| Chevron Corporation |
| TotalEnergies |
| Others |
Supply & Pricing Matrix
Specialized lubricant formulation chemists concentrated in Cairo-Alexandria corridor refineries create labor-cost differentials that widen spreads between premium synthetic tiers and economy mineral formulations across Egypt's distribution hierarchy.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments Egypt's lubricant market by base oil grade and certification compliance. Price differentiation hinges on Group III synthetic content versus Group I mineral stocks and GAP sulfur-threshold certification status. Cost compression in the economy tier is intensifying because independent Upper Egypt workshops lack testing infrastructure to justify premium grades. Fleet operators with direct blender contracts exhibit lowest price sensitivity, while unconsolidated agricultural buyers in Nile Delta zones show highest elasticity.
Supply Chain Analysis
Direct-to-fleet channels handle consolidated logistics demand exceeding 500 vehicles, bypassing traditional distributor markups. Geographic supply concentration rests on Saudi Arabia, Kuwait, and UAE as dominant Group II/III base oil sources. Raw material dependencies include polyalphaolefin synthetic stocks, viscosity index improver polymers, and zinc-based anti-wear additive packages. Single-source vulnerability from Gulf Cooperation Council refiners exposes blenders to feedstock volatility during regional supply disruptions. Distribution runs through Alexandria port customs clearance and Suez-based licensed storage terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's lubricant market offers margin-expansion potential as GAP-mandated formulation upgrades compress economy-tier volumes and redirect procurement toward premium synthetic tiers with higher per-liter realization.
For Market Incumbents: To counter direct-fleet contracting that erodes distributor intermediaries, Misr Petroleum and AMOC should deepen backward integration into additive package blending and secure exclusive technical service partnerships with Cairo-based logistics operators. Locking Suez storage terminal capacity under preferential GAP licensing creates defensive moats against Gulf-sourced import competitors facing extended customs delays. For New Entrants and Emerging Players: Capture biodegradable hydraulic fluid demand in Nile Delta agricultural zones where GAP's evolving soil-contact mandates create specification gaps unaddressed by incumbent mineral-oil portfolios. Vegetable-oil-based formulations with first-mover certification through EOS approval cycles offer penetrable white space. Target direct contracting with consolidated farming cooperatives bypassing traditional parts-retail channels. For Investors and Strategic Acquirers: Gulf-based national oil companies are the most active acquirer in this space, seeking downstream blending assets to secure Egyptian market access under tightening import licensing. Long-term viability hinges on domestic formulation capabilities that reduce feedstock import dependency. Watch GAP's sulfur-threshold enforcement trajectory as the critical inflection signal for economy-tier volume collapse.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Blending | Reduces import dependency on Gulf-sourced finished packages and compresses formulation costs for Misr Petroleum. |
| Biodegradable Hydraulic Fluid Certification | Positions first-movers for GAP's Nile Delta agricultural mandates ahead of EOS approval cycle completion. |
| Suez Storage Terminal Capacity Lock | Secures preferential customs clearance status under GAP's tightened Group II/III import licensing framework. |
| Direct Fleet Contracting Infrastructure | Enables volume-locked pricing with Cairo logistics operators extracting margin from distributor intermediaries. |
| Technical Service Partnership Model | Bundles lubricant supply with viscosity testing equipment deployment to Upper Egypt workshops. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with lubricant blending plant managers, fleet procurement directors at Cairo logistics operators, EOS certification officials, and aftermarket distributor principals with secondary validation against GAP regulatory filings, Egyptian customs import records, Suez Canal Authority vessel traffic data, and petroleum industry trade association reports. Bottom-up volume modeling across viscosity grades and end-use segments triangulated against top-down market sizing from refinery output disclosures.
Historical reference periods anchored the projection horizon to pre-reformulation baseline volumes and post-GAP enforcement trajectory shifts. The analytical framework modeled segmentation across product type, viscosity grade, application, and end-user procurement sophistication. CAGRs derived from elasticity-adjusted demand curves incorporating fleet modernization rates and specification substitution effects. Industry-specific inputs included Euro 5 engine penetration timelines and biodegradable hydraulic fluid adoption curves in agricultural zones.
Feedstock price volatility, GAP regulatory enforcement intensity, and fleet consolidation pace are the dominant revision risks that could compress or extend premium-tier volume migration. Forecasts reflect documented assumptions about sulfur-threshold compliance timelines and synthetic formulation cost curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Synthetic Lubricants Market
Lubricants
North America and Europe Forestry Lubricants Market
Lubricants
Global Group IV and V Lubricants Market
Lubricants
Industrial Gear Oil Market
Lubricants
EDM Oils/Fluids Market
Lubricants
Poland Industrial Lubricants Market
Lubricants
Myanmar Lubricants Market
Lubricants
Canada Commercial Vehicles Lubricants Market
Lubricants
Europe Marine Lubricants Market
Lubricants
Lubrication Equipment Market
Lubricants
Non-Flammable Hydraulic Fluids Market
Lubricants
Kenya Lubricants Market
Lubricants
Brazil Lubricants Market
Lubricants
Biolubricants Market
Lubricants
Polyurea Greases Market
Lubricants
Germany Lubricants Market