
 Malaysia Automotive Engine Oils Market | 2026-2036
Malaysia Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Automotive Engine Oils Market Foresight
Workshop networks and e-commerce platforms are rewriting how engine oils reach end users in Malaysia. PETRONAS Lubricants International leverages its domestic refinery complex and captive base oil supply to anchor pricing power across Peninsula Malaysia. Shell plc competes through an extensive branded service station footprint that extends consumer touchpoints into East Malaysia. ExxonMobil Corporation differentiates via specialized synthetic formulations targeting tropical operating conditions.
Automotive engine oils are formulated lubricants comprising base oils and additive packages designed to reduce friction, dissipate heat, and prevent wear in internal combustion engines, with synthetic grades typically offering viscosity stability at temperatures exceeding 150°C and extended drain intervals. Their primary commercial purpose is to protect engine hardware while enabling compliance with manufacturer warranty requirements and emissions standards. Synthetic products command premium positioning as OEM fill specifications shift toward lower viscosity grades, while the 5W-30 segment sustains broad compatibility across ASEAN-assembled passenger vehicles. Bottled retail packaging dominates consumer transactions, though bulk delivery systems are gaining traction among commercial fleet operators seeking inventory efficiency.
SIRIM QAS International sets mandatory product certification benchmarks for lubricants sold in Malaysia, while the Department of Environment enforces waste oil handling protocols that shape reverse logistics obligations for distributors. The Ministry of Investment, Trade and Industry coordinates domestic manufacturing incentives that influence local blending capacity expansion decisions. Stakeholders must monitor evolving OEM service fill specifications and the pace of electric vehicle penetration to calibrate portfolio transitions between conventional and advanced formulation investments.
Market Dynamics
Commercial fleet operators in Malaysia are consolidating lubricant procurement under long-term supply agreements, compressing distributor margins while elevating volume requirements for direct manufacturer relationships. This concentration of buying power is restructuring channel economics across Peninsula Malaysia.
Growth Catalysts
- SIRIM QAS International certification mandates:Mandatory quality benchmarks are eliminating substandard imports and elevating average product specifications nationwide. Domestic blenders with accredited laboratories capture displaced volume from uncertified suppliers.
- High-utilization commercial fleets:Logistics and ride-hailing operators running vehicles above 80,000 kilometers annually are accelerating drain interval compression. Fleet managers prioritize synthetic formulations to minimize downtime.
- Lower viscosity OEM fill specifications:ASEAN-assembled passenger vehicles are factory-filling with 0W-20 and 5W-30 grades. Aftermarket demand for matching specifications is expanding the synthetic product mix.
Market Restraints
- Base oil supply concentration:Malaysia's domestic base oil production is concentrated at PETRONAS refineries in Melaka and Kerteh. Blenders without captive supply face input cost volatility tied to regional Group II/III pricing.
- Electric vehicle powertrain incompatibility:Battery electric vehicles eliminate internal combustion engine lubrication requirements entirely. OEM electrification timelines threaten long-term volume erosion in the passenger segment.
- Additive package import dependency:Performance chemicals and detergent-dispersant packages are sourced primarily from Singapore and Thailand. Currency fluctuation against the US dollar creates margin pressure for local formulators.
Strategic Opportunities
- East Malaysia channel penetration:Sabah and Sarawak maintain lower synthetic penetration rates than Peninsula Malaysia. Branded distributors can establish direct warehouse operations in Kota Kinabalu and Kuching.
- Ministry of Investment, Trade and Industry manufacturing incentives:Domestic blending capacity expansion qualifies for tax holidays and capital allowance acceleration. New entrants can co-locate with PETRONAS base oil supply.
- E-commerce direct-to-workshop platforms:Independent service centers in Johor Bahru and Penang are migrating lubricant purchasing to B2B marketplaces. Digital procurement infrastructure enables disintermediation of traditional distributors.
Industry Challenges
- Formulation chemist talent scarcity:Malaysia produces limited graduates in tribology and lubricant engineering. Blenders compete with Singapore-based regional headquarters for experienced technologists.
- SIRIM certification timeline compression:New product registrations require six to nine months for full testing and audit cycles. Accelerated OEM specification changes outpace approval velocities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Automotive Engine Oils Market |
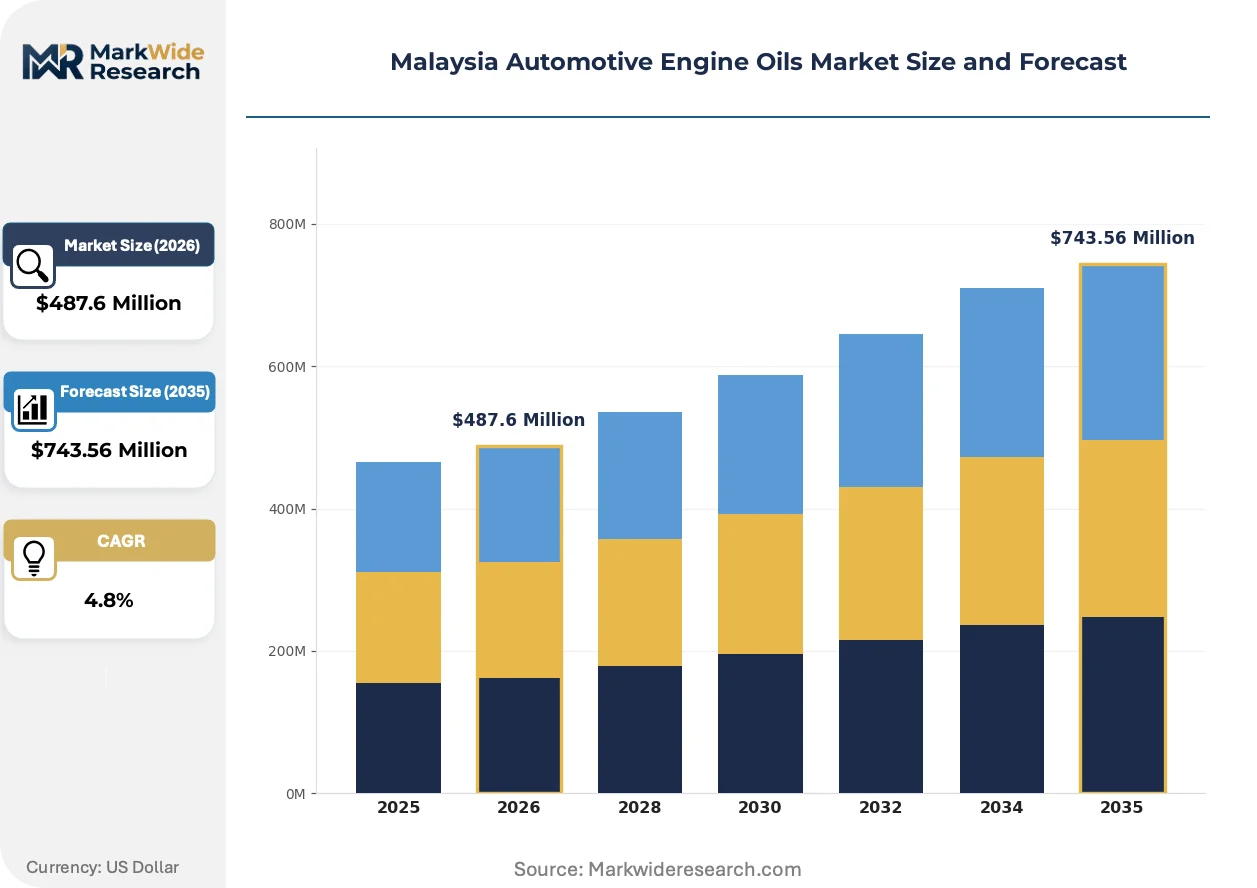
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Conventional, Semi-Synthetic, High Mileage Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 Packaging Type: Bulk, Bottles, Canisters, Pouches End User: Passenger Vehicles, Commercial Fleets, Motorcycles, Others |
| Companies Covered | ExxonMobil Corporation, Chevron Corporation (Caltex), PETRONAS Lubricants International, Idemitsu Kosan Co. Ltd, Fuchs Petrolub SE, Shell plc, TotalEnergies, UMW Lubetech Sdn Bhd, BP plc (Castrol), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Automotive Engine Oils Market Shifts & Advancements
Formulation chemistry and distribution logistics are converging to redefine product-service bundling in Malaysia's automotive lubricant sector. Three developments are restructuring competitive positioning.
Advanced Group III+ synthetic base stocks are delivering oxidative stability exceeding 10,000 kilometers in tropical stop-start conditions. Fleet operators in the Klang Valley are adopting these formulations at replacement rates three times faster than conventional mineral products. Extended drain capability is rendering obsolete the quarterly service interval model that anchored workshop revenue for decades.
Malaysia's Department of Environment is tightening enforcement of scheduled waste handling regulations under the Environmental Quality Act. Used oil collection and reverse logistics obligations now require licensed transporters and documented cradle-to-grave tracking. Independent workshops in Selangor are consolidating waste oil volumes to meet minimum collection thresholds, favoring distributors with integrated reclamation partnerships.
Workshop procurement managers are unbundling lubricant supply from technical service contracts. Previously captive arrangements tying oil supply to diagnostic equipment leases are dissolving. Independent chains in Johor and Penang are sourcing through multi-brand distributors, compressing single-brand market share concentration in the southern region.
Malaysia Automotive Engine Oils Market Segmentation
Malaysia's automotive engine oils market fragments across formulation chemistry, mechanical specification, logistics format, and vehicle application. Each dimension carries distinct margin profiles and regulatory exposure under SIRIM QAS International certification mandates.
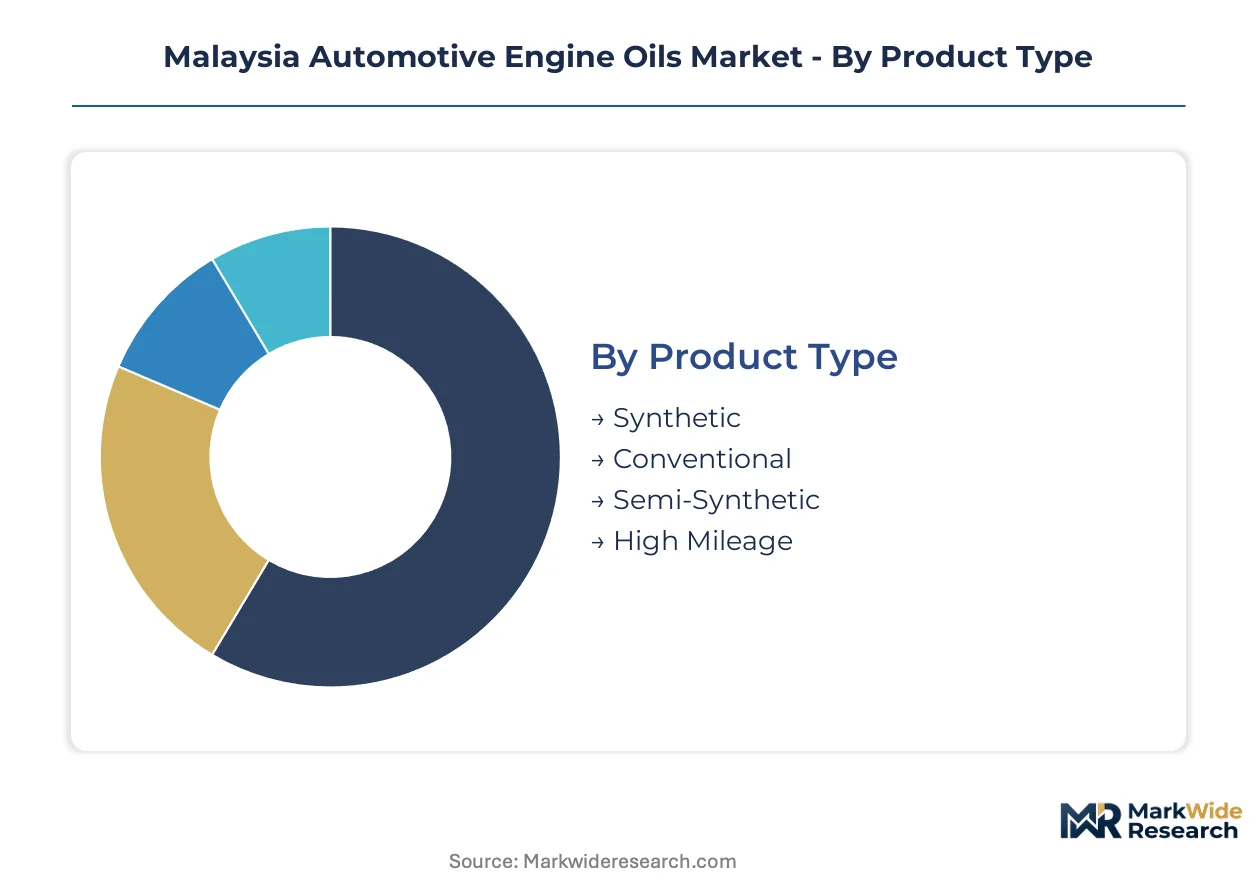
Product Type:
Cost tier differentiation separates premium synthetic formulations from mineral-based alternatives, with price spreads reflecting base oil group classification and additive package sophistication.
- Synthetic:Group III and III+ base stocks deliver oxidative stability exceeding 150°C operating temperatures. Fleet operators in the Klang Valley specify these grades for vehicles exceeding 80,000 kilometers annual utilization, compressing replacement cycles and workshop downtime.
- Conventional:Mineral-based formulations derived from Group I base oils dominate price-sensitive segments. Independent workshops in Johor Bahru and Penang stock these products for aging vehicle parc compatibility, though drain intervals lag synthetic alternatives by 40-60 percent.
- Semi-Synthetic:Blended formulations balance performance upgrade against cost increment for mid-market consumers.
- High Mileage:Seal conditioners and anti-wear additives target vehicles above 100,000 kilometers odometer readings.
Synthetic holds installed capacity. Semi-Synthetic is rotating up the share rankings.
Viscosity Grade:
Application requirements from OEM fill specifications and tropical climate conditions dictate viscosity selection across passenger and commercial segments.
- 0W-20:Ultra-low viscosity formulations reduce cold-start friction and improve fuel economy metrics. Japanese OEM assembly plants in Selangor factory-fill with this grade, creating aftermarket pull through dealer service networks.
- 5W-30:Broad compatibility spans ASEAN-assembled passenger vehicles and provides operational margin across ambient temperature swings. This grade captures the largest volume position in retail and fleet channels throughout Peninsula Malaysia.
- 10W-40:Higher viscosity protects older engine architectures with worn bearing clearances.
- 15W-50:Heavy-duty specification serves commercial diesel applications and high-performance motorcycles.
5W-30 anchors current volume. 0W-20 is climbing the fastest as OEM specifications tighten.
Packaging Type:
Customer type and procurement scale determine format preference, with bulk systems gaining traction among high-volume operators seeking inventory efficiency.
- Bulk:Tanker and tote delivery systems eliminate packaging waste and unit handling costs. Logistics operators with centralized maintenance depots in Shah Alam and Pasir Gudang specify bulk supply under annual framework agreements.
- Bottles:One-liter and four-liter retail formats dominate consumer transactions at service stations and auto parts retailers. PETRONAS and Shell branded networks push these SKUs through captive forecourt convenience stores.
- Canisters:Industrial-grade packaging serves commercial workshops with moderate volume requirements.
- Pouches:Flexible format targets motorcycle service points and rural distribution channels.
Bottles retain channel dominance. Bulk is expanding most quickly among fleet consolidators.
End User:
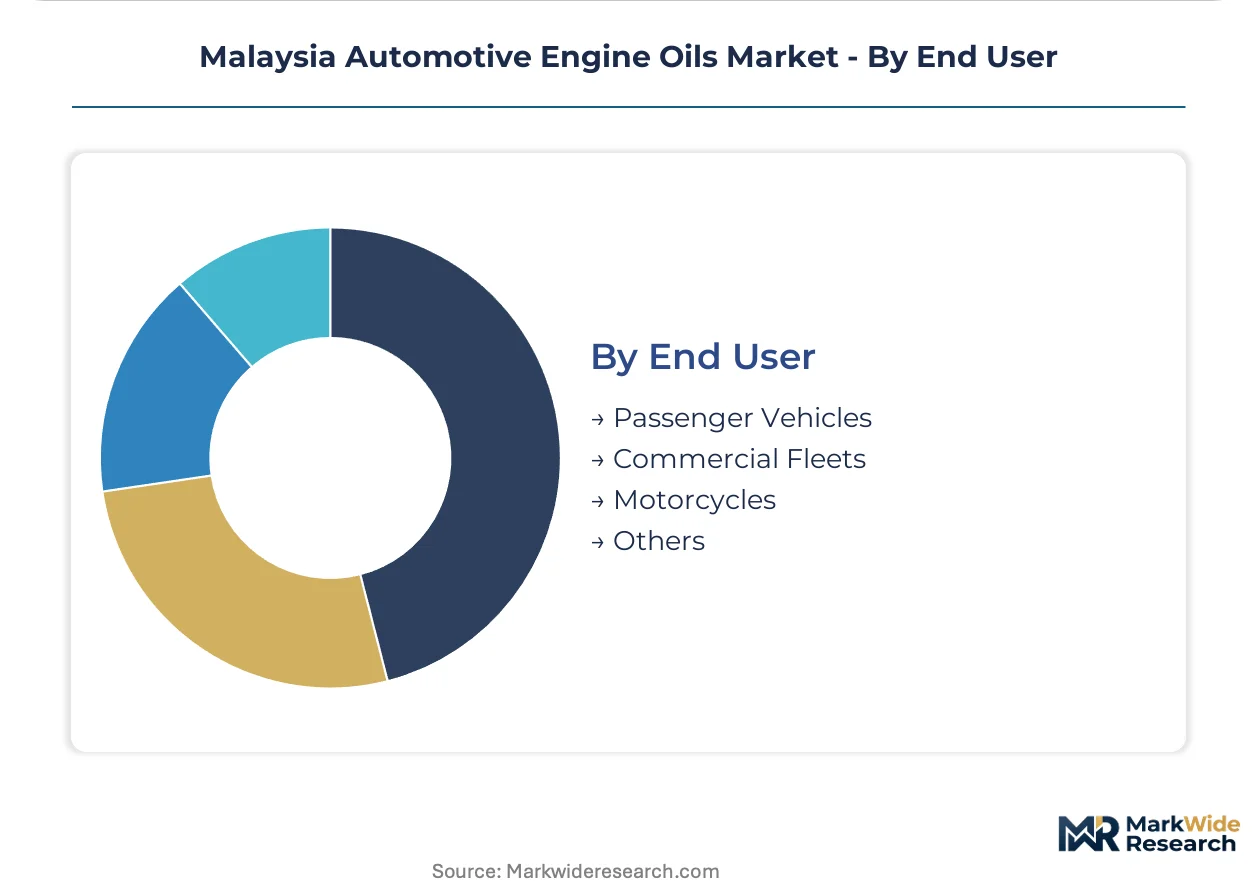
Volume concentration and specification sophistication diverge sharply between private vehicle owners and commercial operators running utilization-intensive schedules.
- Passenger Vehicles:Individual owners follow OEM warranty maintenance schedules with synthetic and semi-synthetic grades. Dealership service centers in Kuala Lumpur and Petaling Jaya capture this demand through tied servicing packages.
- Commercial Fleets:Ride-hailing and logistics operators prioritize extended drain intervals and direct manufacturer relationships. These buyers consolidate procurement under multi-year supply agreements, compressing distributor margins while elevating volume concentration.
- Motorcycles:Two-stroke and four-stroke formulations serve high-density urban commuting and rural transportation segments.
- Others:Marine, agricultural, and industrial engine applications represent fragmented specialty demand.
Passenger Vehicles maintains volume leadership. Commercial Fleets is gaining share fastest through procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peninsula Malaysia commands pricing power through PETRONAS captive base oil supply, while East Malaysia absorbs transport premiums that compress distributor margins. This asymmetry shapes procurement consolidation patterns across the federation.
Selangor and Kuala Lumpur
Klang Valley logistics operators running 80,000-kilometer annual schedules specify synthetic Group III formulations for extended drain intervals. SIRIM QAS International certification audits concentrate testing laboratory capacity in Shah Alam and Petaling Jaya. Port Klang free trade zone hosts bulk blending facilities serving ASEAN export markets.
Johor
Iskandar Malaysia manufacturing zones generate commercial fleet demand tied to cross-border Singapore freight corridors. The Ministry of Investment, Trade and Industry designated Pasir Gudang as a petrochemical hub eligible for accelerated capital allowances. Independent workshop chains in Johor Bahru are migrating procurement to B2B e-commerce platforms.
Sabah
Kota Kinabalu port logistics and palm oil plantation transport fleets sustain mineral oil demand at lower synthetic penetration rates than Peninsula Malaysia. The Department of Environment enforces scheduled waste handling regulations that consolidate used oil collection volumes. Branded distributors are establishing direct warehouse operations to bypass Peninsular supply chains.
Sarawak
Kuching and Miri service centers support offshore oil and gas logistics fleets operating under tropical high-load conditions. State infrastructure investment in Samalaju Industrial Park attracts blending capacity co-location with energy sector demand. East Malaysia's lower service density favors bulk delivery systems over packaged retail formats.
Penang
Bayan Lepas electronics manufacturing corridors generate light commercial vehicle demand with precise OEM warranty compliance requirements. Penang Port facilitates additive package imports from Singapore and Thailand. Independent service centers in Georgetown source through multi-brand distributors, dissolving previous single-brand captive arrangements.
Malaysia Automotive Engine Oils Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation chemistry differentiation. PETRONAS Lubricants International anchors domestic supply through captive Melaka and Kerteh refinery output, while international majors compete on branded service station density and synthetic formulation portfolios. Three archetypes populate the market: national oil company affiliates with backward base oil integration, multinational lubricant marketers with regional blending networks, and independent distributors exploiting e-commerce channel disintermediation. Competitive moves concentrate on East Malaysia warehouse establishment and fleet procurement consolidation under direct manufacturer relationships.
Among integrated national oil company operations, PETRONAS Lubricants International exemplifies captive supply chain control from base oil production through retail distribution. Shell plc and ExxonMobil Corporation occupy positions as multinational formulators with differentiated synthetic portfolios targeting tropical operating specifications. These three anchors represent distinct strategic postures: domestic vertical integration, global brand equity leverage, and specialized performance chemistry development.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Chevron Corporation (Caltex) |
| PETRONAS Lubricants International |
| Idemitsu Kosan Co. Ltd |
| Fuchs Petrolub SE |
| Shell plc |
| TotalEnergies |
| UMW Lubetech Sdn Bhd |
| BP plc (Castrol) |
| Others |
Supply & Pricing Matrix
Undercapacity in domestic Group II/III base oil production at PETRONAS Melaka and Kerteh refineries drives supplier prioritization toward long-term contract customers, compressing spot market availability and elevating pricing leverage for integrated blenders over independent competitors.
Pricing Analysis
The customization-premium spread between SIRIM-certified synthetic formulations and uncertified mineral alternatives spans three performance tiers. Contract-based long-term offtake dominates fleet procurement, while bottled retail transactions follow per-unit transactional models. Price differentiation hinges on SIRIM QAS International certification tier and volume scale, with commercial buyers commanding steeper discounts than individual consumers. Margins are tightening due to additive package import costs denominated in US dollars. Independent workshops in Johor Bahru exhibit highest price sensitivity; PETRONAS-integrated operators show least.
Supply Chain Analysis
Upstream feedstock concentration at PETRONAS refineries in Melaka and Kerteh anchors domestic base oil availability, with supplementary Group III imports drawing from Singapore and Thailand. Performance chemical additive packages and detergent-dispersant formulations rest on Singaporean and Thai chemical manufacturing. Single-source vulnerability manifests in PETRONAS captive supply control over Peninsula Malaysia. Distribution runs through branded service station networks, independent workshop distributors, and emerging B2B e-commerce platforms serving fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's automotive engine oils sector rewards players who control scarce formulation chemistry capabilities and SIRIM certification velocity, while penalizing those dependent on volatile imported additive inputs and third-party laboratory access.
For Market Incumbents: Build captive laboratory accreditation moats by securing SIRIM QAS International pre-audited capacity for accelerated product registration. Defend against e-commerce disintermediation by integrating waste oil collection services under Environmental Quality Act compliance obligations. Anchor channel control through direct warehouse establishment in Kota Kinabalu and Kuching before competitors replicate Peninsula infrastructure. For New Entrants and Emerging Players: Establish a beachhead in Sabah and Sarawak bulk delivery systems where synthetic penetration lags Peninsula Malaysia by substantial margins. Target palm oil plantation transport fleets and offshore oil and gas logistics operators running high-utilization schedules. Pursue co-location with PETRONAS base oil supply in Samalaju Industrial Park to neutralize feedstock cost disadvantages. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet procurement consolidators locking multi-year supply agreements with direct manufacturer relationships. Long-term viability favors blenders with backward integration into base oil production or additive package formulating capability. Monitor electric vehicle registration trajectories as volume erosion inflection signal for passenger segment exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | PETRONAS captive supply eliminates input cost volatility for integrated operators. |
| SIRIM Certification Pre-Investment | Accelerated laboratory accreditation compresses product registration timelines against competitors. |
| East Malaysia Warehouse Establishment | Direct Kota Kinabalu and Kuching operations bypass Peninsular supply chain premiums. |
| Waste Oil Collection Partnership | Department of Environment compliance integration binds workshops to distributor relationships. |
| B2B E-Commerce Platform Development | Digital procurement infrastructure disintermediates traditional distributor margins in Johor and Penang. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SIRIM QAS International certification registries, Department of Environment waste handling permits, and Ministry of Investment, Trade and Industry incentive disclosures. Primary interviews engaged lubricant blenders, commercial fleet procurement managers, independent workshop operators, and PETRONAS supply chain executives. Secondary sources incorporated customs trade data on base oil and additive imports, PETRONAS annual reports, and automotive production databases from ASEAN vehicle assembly plants. Bottom-up volume modeling triangulated against top-down market sizing from macroeconomic indicators.
Forecast inputs span formulation chemistry segments, viscosity grade specifications, packaging format logistics, and vehicle application categories across the projection horizon. CAGRs derive from trend extrapolation of OEM fill specification shifts, fleet utilization intensity patterns, and electric vehicle penetration assumptions. Industry-specific inputs include SIRIM certification velocity timelines and PETRONAS refinery capacity utilization disclosures.
Stress conditions across base oil supply interruptions, ringgit-dollar exchange rate volatility, and accelerated electric vehicle adoption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory enforcement shifts or OEM electrification timeline acceleration. Cross-checking against PETRONAS downstream segment disclosures and Shell plc Asia-Pacific lubricant revenue benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Global Lubrication Systems Market
Lubricants
Japan Lubricants Market
Lubricants
Brazil Commercial Vehicles Lubricants Market
Lubricants
Russia Automotive Engine Oils Market
Lubricants
Lubricants for Cement Industry Market
Lubricants
Netherlands Metalworking Fluids Market
Lubricants
Russia Commercial Vehicles Lubricants Market
Lubricants
Europe Lubricants Market
Lubricants
Turkey Commercial Vehicles Lubricants Market
Lubricants
Technical Fluids Market
Lubricants
Europe Metalworking Fluids Market
Lubricants
United Kingdom Automotive Lubricants Market
Lubricants
Marine Lubricants Market
Lubricants
Synthetic Lubricants and Functional Fluids Market
Lubricants
Yarn Lubricant Market
Lubricants
Food Grade Lubricant Market