
 Bulgaria Lubricants Market | 2026-2036
Bulgaria Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Bulgaria Lubricants Market Outlook
Fluid analysis and predictive maintenance subscription programs is shifting how Bulgarian fleet operators procure lubricants, bundling oil changes with wear-metal monitoring and drain-interval optimization. Prista Oil leverages its Blending Plant in Ruse to anchor supply security across the domestic market. Shell Plc competes through differentiated premium synthetic offerings distributed via established service station networks. Lukoil sustains vertical integration from base oil refining through retail, controlling cost structures that independent blenders cannot match.
Lubricants are formulated mixtures of base oils and performance additives engineered to reduce friction, dissipate heat, and prevent wear between moving mechanical surfaces, with key specifications including viscosity grade, pour point, and oxidation stability per SAE and ISO standards. Engine oil dominates value generation across Bulgarian automotive and transport applications, while hydraulic oil captures concentrated demand from industrial machinery operating in Plovdiv's manufacturing zones. Greases represent a specialized margin pool serving mining and heavy construction equipment where infrequent relubrication cycles command technical premiums over standard fluid products.
Bulgaria's lubricant quality framework operates under EU REACH chemical registration requirements and the F-Gas Regulation for fluorinated compound controls, supplemented by national BIS-aligned standards for industrial lubricant certification. The European Commission's Green Deal industrial plan shapes reformulation roadmaps, pressuring mineral oil dependence while creating compliance thresholds for imported formulations. Stakeholders must monitor how EU-wide carbon border adjustments and evolving biodegradability mandates reshape sourcing economics for base oil feedstocks and additive packages entering the Bulgarian market.
Market Dynamics
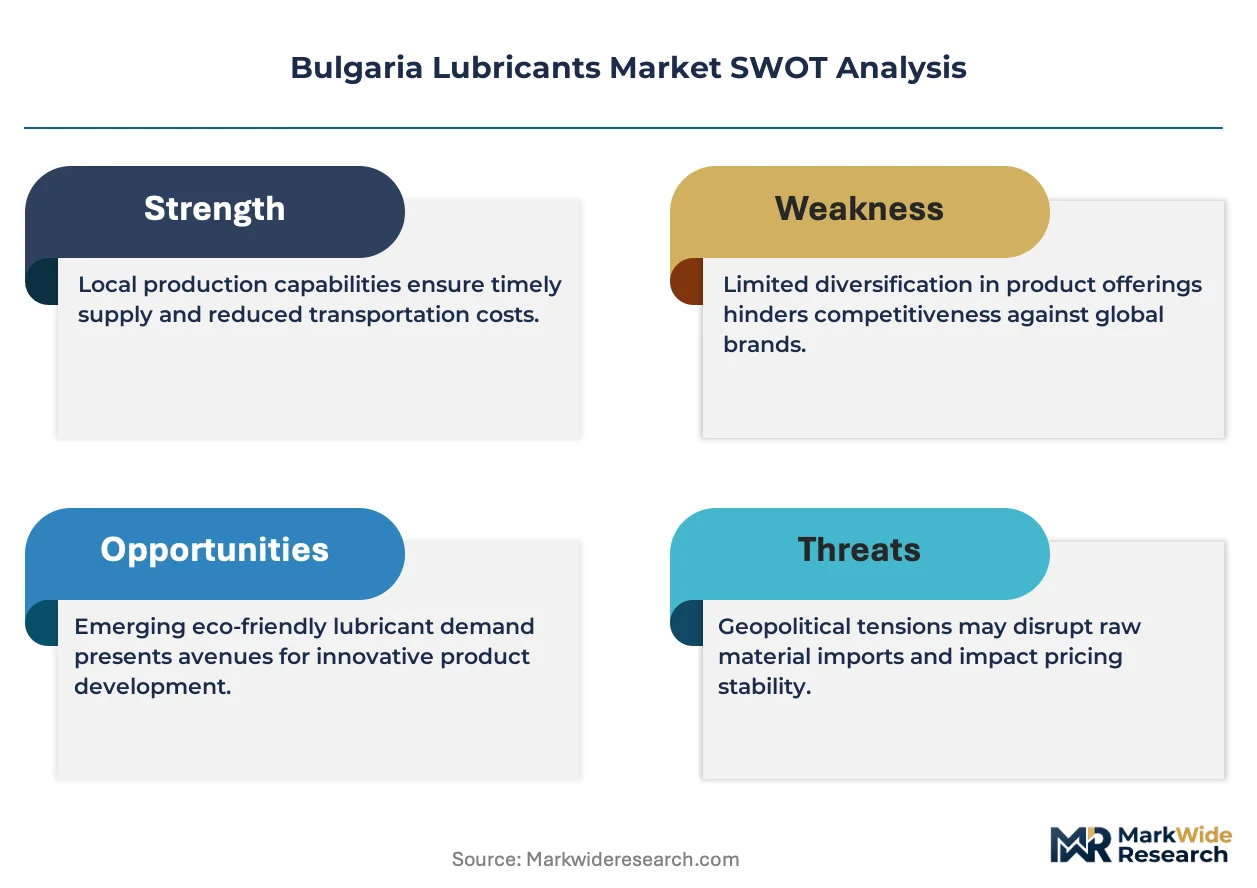
EU Green Deal emission targets are forcing Bulgarian blenders to reformulate mineral oil-dependent products toward bio-based and lower-viscosity chemistries, compressing traditional formulation margins while opening compliance-driven premium tiers.
Growth Catalysts
- Fleet maintenance intensification:Bulgarian transport operators are extending vehicle replacement cycles, increasing drain-interval frequency and bulk lubricant offtake for engine oils and hydraulic fluids.
- REACH registration thresholds:EU chemical compliance mandates are filtering out low-volume importers, consolidating shelf space for certified domestic blenders with established ECHA dossiers.
- Plovdiv manufacturing corridor expansion:Industrial machinery deployment across Bulgaria's second-largest city is concentrating demand for hydraulic oils and metalworking fluids.
Market Restraints
- Base oil feedstock volatility:Group I and Group II base oil prices fluctuate with regional refinery output, squeezing blender margins on standard-grade formulations.
- Import dependency for additives:Performance additive packages largely originate from German and Italian suppliers, exposing Bulgarian formulators to euro-denominated cost swings and extended lead times.
- Biodegradability certification gaps:EU Ecolabel and OECD 301B test requirements create technical barriers for small domestic blenders lacking in-house toxicity screening capability.
Strategic Opportunities
- Predictive maintenance bundling:Fluid analysis subscription programs allow lubricant vendors to capture recurring revenue from Sofia-based fleet operators seeking drain-interval optimization.
- Bio-based formulation incentives:EU Green Deal industrial plan funding channels are subsidizing rapeseed-derived base oil trials for agricultural and marine applications.
- Mining equipment grease specialization:Infrequent relubrication cycles in Bulgaria's extractive sectors command technical premiums for high-performance lithium complex and calcium sulfonate greases.
Industry Challenges
- Tribology expertise scarcity:Bulgarian technical universities produce limited lubricant formulation specialists, forcing blenders to recruit from Romanian and Serbian talent pools.
- Legacy equipment compatibility:Older Bulgarian industrial machinery requires higher-viscosity mineral oils, complicating the transition to synthetic and bio-based alternatives mandated by EU regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulgaria Lubricants Market |
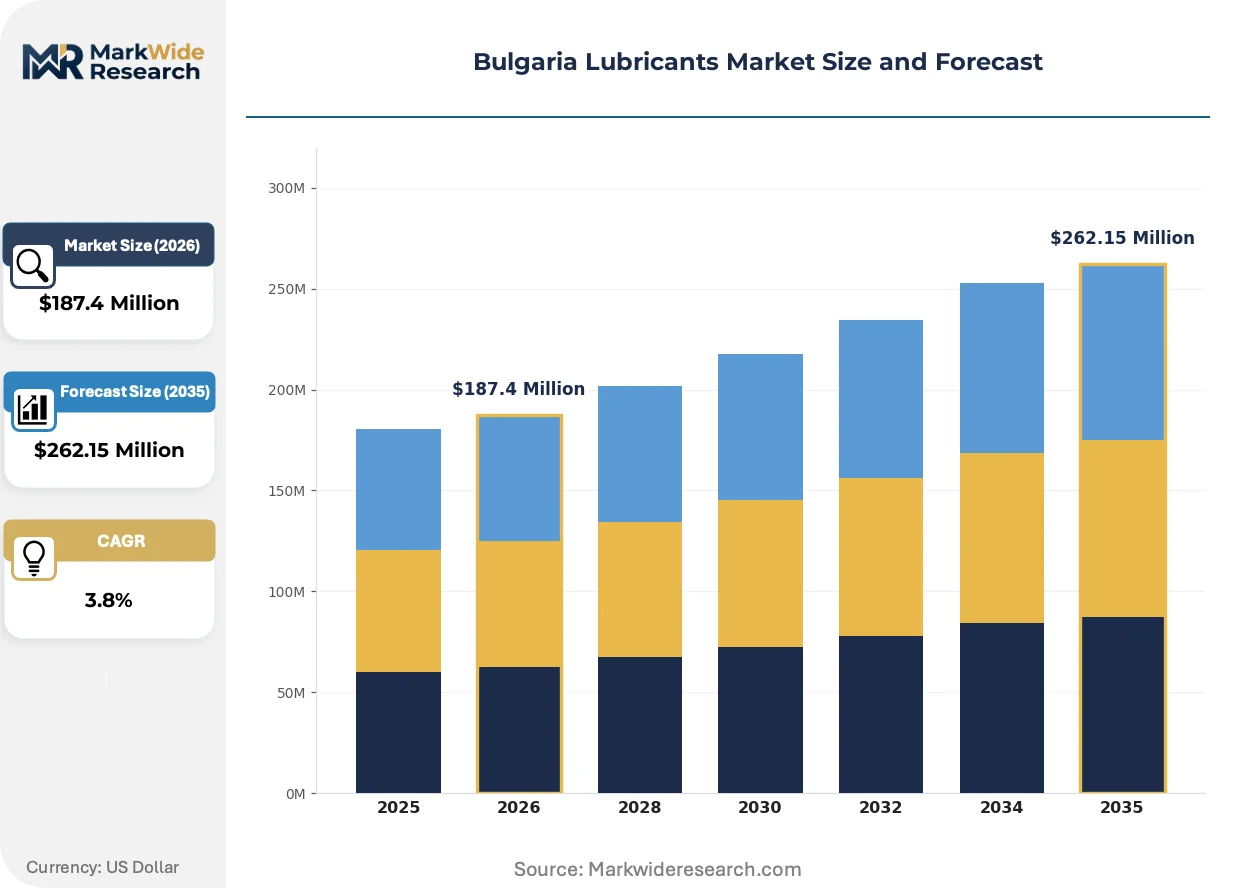
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Hydraulic Oil, Greases Application: Automotive, Industrial Machinery, Marine, Aviation End User: Manufacturers, Transport Companies, Service Stations, Freelance Mechanics Packaging Type: Bottle, Drum, IBC, Bulk |
| Companies Covered | Prista Oil, Lukoil, Shell Plc, ExxonMobil Corporation, BP Plc (Castrol), TotalEnergies SE, Chevron Corporation, AVIA International, Eni, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulgaria Lubricants Market Strategic Shifts
Digital fluid monitoring systems and predictive analytics platforms are restructuring how Bulgarian industrial buyers procure and consume lubricants, shifting transactions from spot purchases to integrated service contracts.
Sensor-enabled oil condition monitoring is automating drain-interval decisions for Plovdiv manufacturing plants and Sofia logistics fleets. Maintenance teams install particle counters and viscosity probes directly on hydraulic reservoirs and engine sumps. Real-time data streams eliminate calendar-based oil changes, compressing lubricant volume demand while raising per-liter value capture for analytics-integrated suppliers.
EU F-Gas Regulation phase-down schedules are accelerating synthetic ester adoption in Bulgarian refrigeration and compressor lubricant segments. Formulators face mandatory GWP (global warming potential) thresholds for fluorinated compounds. Industrial refrigeration operators in Sofia's cold-storage corridors are retrofitting systems with polyol ester lubricants compatible with lower-GWP refrigerants.
Fleet procurement departments are consolidating supplier relationships around full-service maintenance contracts. Bulgarian transport operators negotiate multi-year agreements bundling lubricant supply, used-oil collection, and wear-metal analysis. This consolidation favors blenders with Ruse-based logistics infrastructure capable of same-day delivery to northern industrial zones. Independent distributors without fluid analysis capabilities face margin compression as buyers prioritize predictive maintenance integration.
Bulgaria Lubricants Market Segmentation
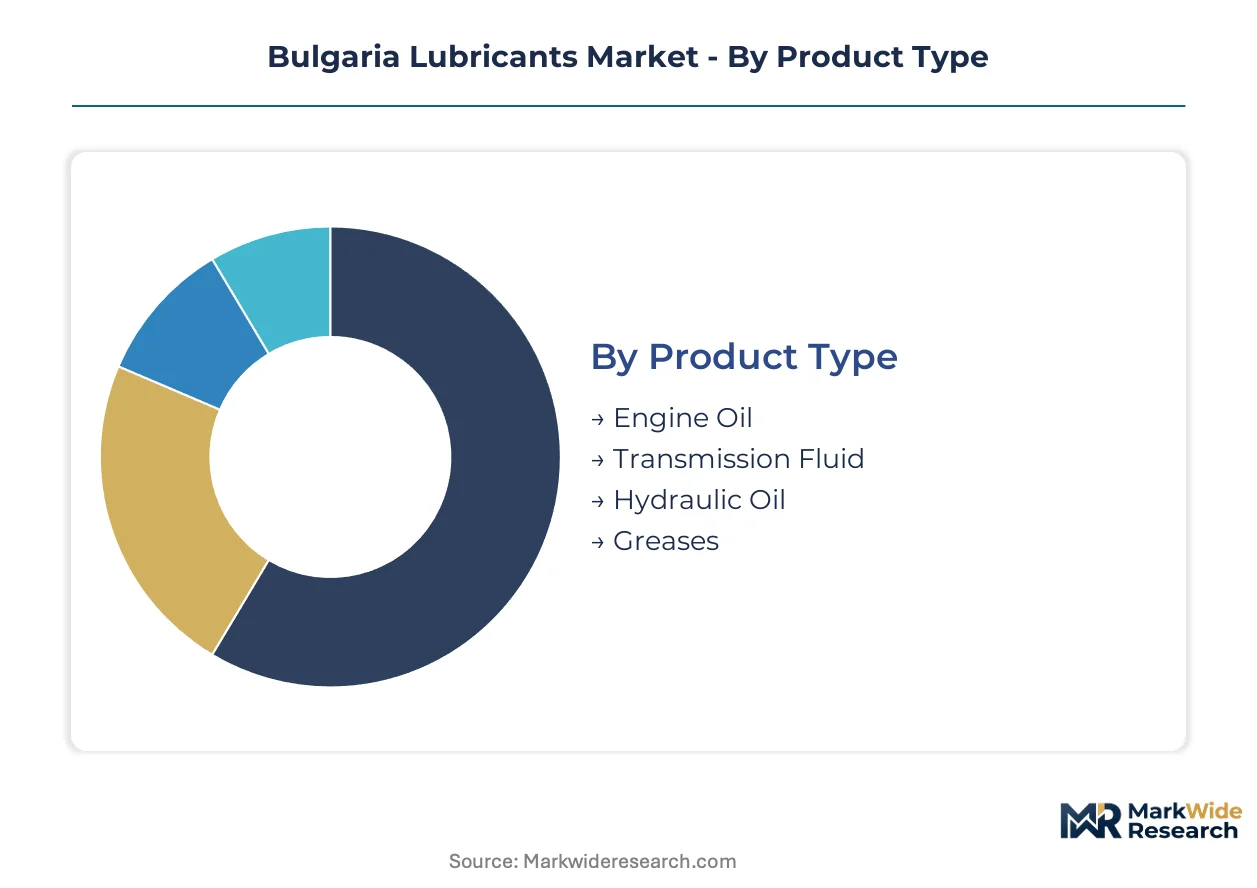
Segmentation in Bulgaria's lubricants market reveals how regulatory certification burdens, packaging logistics, and end-user procurement power reshape competitive positioning across formulation tiers. Each dimension carries distinct margin structures and compliance thresholds that determine which blenders capture volume versus value.
Product Type:
REACH registration requirements and SAE viscosity certification create tiered compliance costs across product categories, with full-synthetic formulations demanding more extensive ECHA dossier maintenance than mineral-based alternatives.
- Engine Oil:Formulated from Group II/III base stocks with viscosity modifiers and detergent-dispersant packages meeting ACEA C3 or API SP specifications. Sofia-based fleet operators and Plovdiv logistics corridors sustain concentrated demand for 5W-30 and 10W-40 grades as vehicle replacement cycles extend. Ecolabel compliance for bio-based variants remains uneven among domestic blenders.
- Hydraulic Oil:Anti-wear additive systems blended into ISO VG 32-68 viscosity grades for high-pressure fluid power transmission. Plovdiv's manufacturing machinery deployment drives volume, with zinc-free formulations gaining preference for environmental compliance in food-processing equipment.
- Transmission Fluid:Friction-modified formulations for automatic and manual gearboxes requiring OEM-specific approvals from Volkswagen, BMW, or commercial vehicle manufacturers. Bulgarian independent garages face inventory complexity serving diverse European vehicle parc.
- Greases:Thickened lubricants based on lithium complex or calcium sulfonate soap structures for bearings and chassis points. Mining equipment in Bulgaria's extractive zones commands technical premiums for extended relubrication intervals.
Engine Oil sits at the top of the volume ranking, with Greases climbing the fastest.
Application:
End-use concentration determines whether procurement flows through bulk supply contracts or fragmented retail channels, with industrial buyers commanding price leverage unavailable to individual consumers.
- Automotive:Light-duty and heavy-duty vehicle lubrication spanning passenger cars, commercial trucks, and buses. Bulgarian transport companies negotiate multi-year supply agreements bundling oil changes with fluid analysis, compressing spot-market participation.
- Industrial Machinery:Metalworking, hydraulics, and compressor lubrication for manufacturing plants. Plovdiv's expanding industrial zones concentrate demand for high-performance hydraulic and circulating oils with extended drain intervals.
- Marine:Stern tube, cylinder, and system oils for Danube River shipping and Black Sea port operations. Bio-based formulations face technical validation gaps for two-stroke crosshead engines.
- Aviation:Turbine oils and hydraulic fluids meeting SAE AS5780 or MIL-PRF-23699 specifications. Sofia Airport ground handling and limited general aviation activity generate narrow but high-margin demand.
Automotive commands absolute volume leadership, while Industrial Machinery gains share fastest through Plovdiv corridor expansion.
End User:
Procurement scale and technical sophistication separate enterprise buyers with predictive maintenance integration from price-sensitive independents purchasing on spot markets.
- Transport Companies:Fleet operators managing 50+ vehicles with centralized maintenance scheduling and bulk storage infrastructure. These buyers prioritize drain-interval optimization and wear-metal monitoring subscriptions over per-liter pricing.
- Manufacturers:Industrial plants with captive maintenance teams specifying lubricants against machinery OEM warranties. Plovdiv and Sofia manufacturing clusters negotiate annual framework agreements with technical service attachments.
- Service Stations:Retail fuel and lubricant outlets serving consumer vehicle maintenance with quick oil change bays. Shell, Lukoil, and OMV networks dominate shelf space for premium synthetic grades.
- Freelance Mechanics:Independent repair shops purchasing 20-200 liter quantities without fluid analysis capabilities. Price sensitivity drives private-label and economy-tier procurement.
Transport Companies anchor volume procurement, with Manufacturers expanding most quickly through industrial automation investments.
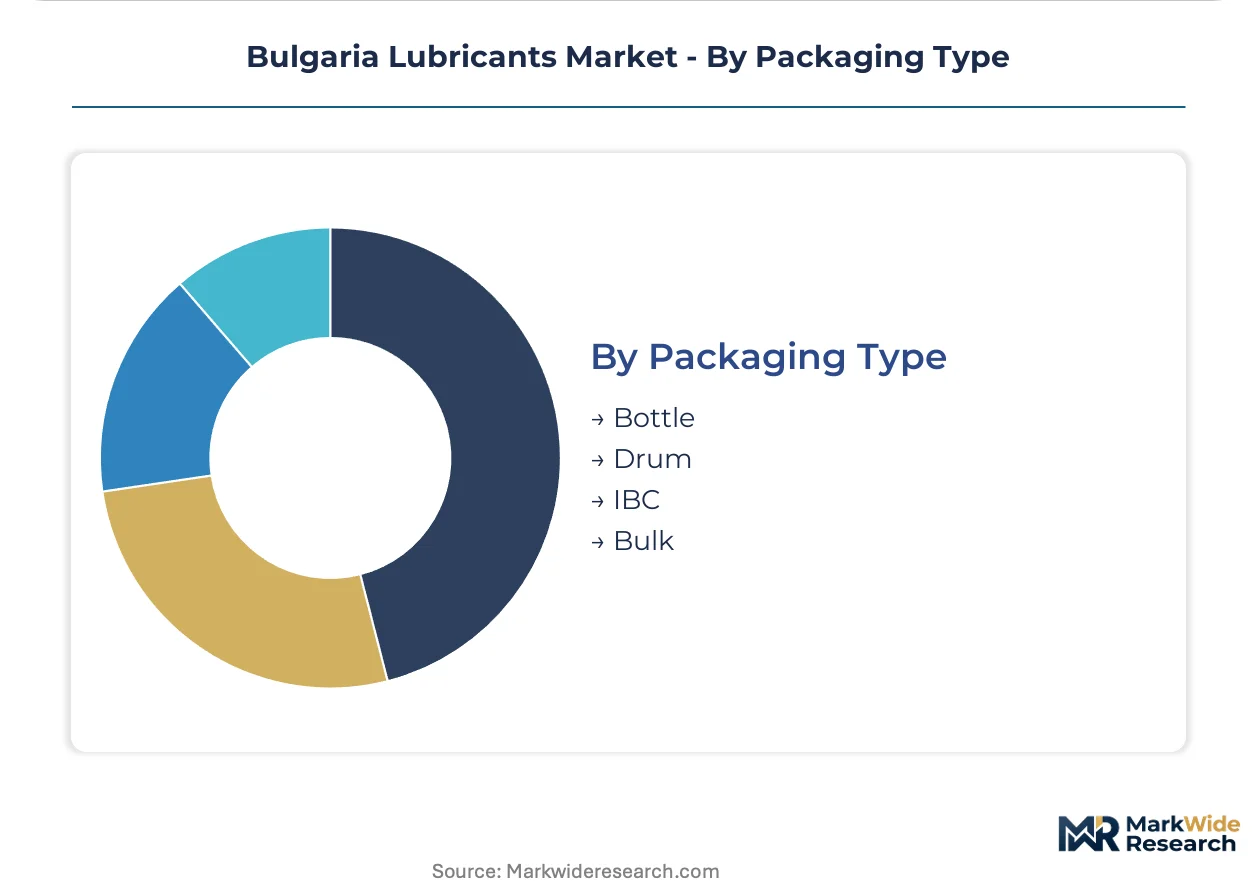
Packaging Type:
Logistics cost structures and inventory turnover rates determine packaging economics, with bulk supply requiring dedicated storage infrastructure unavailable to smaller end users.
- Bulk:Tanker or flexitank deliveries of 10,000+ liters to fleet depots and industrial plants with heated storage. Ruse-based blending capacity enables same-day replenishment for northern Bulgarian industrial zones.
- Drum:200-liter steel containers for mid-scale manufacturing and commercial vehicle workshops. Standard handling equipment and moderate storage footprints suit diverse industrial buyers.
- IBC:Intermediate bulk containers of 1,000 liters for hydraulic system fills and metalworking coolant make-up. Reusable totes reduce packaging waste for environmentally certified plants.
- Bottle:Consumer retail formats from 1 to 5 liters for passenger car owners and small repair shops. Shelf-space competition concentrates in Sofia and Plovdiv automotive retail corridors.
Bulk sits at the top of the volume ranking, with IBC climbing the fastest through sustainability-driven packaging transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping lubricant formulation economics across Southeast Europe, as EU REACH compliance costs filter out marginal importers while rewarding domestic blenders with established ECHA dossiers and localized supply infrastructure.
Sofia
Sofia's logistics corridors concentrate fleet maintenance demand from transport operators extending vehicle replacement cycles. EU Green Deal emission targets pressure local blenders toward lower-viscosity synthetic reformulations. The capital's industrial zones anchor predictive maintenance subscription programs bundling fluid analysis with lubricant supply.
Plovdiv
Plovdiv's manufacturing corridor expansion drives concentrated hydraulic oil demand from automated machinery deployment. REACH registration thresholds favor certified domestic blenders over low-volume importers lacking ECHA compliance infrastructure. Metalworking fluid procurement flows through annual framework agreements with technical service attachments.
Ruse
Ruse's Danube River port position sustains marine lubricant demand for Black Sea shipping and inland waterway operations. The EU F-Gas Regulation accelerates synthetic ester adoption in refrigeration compressor applications. Prista Oil's blending plant anchors supply security for northern Bulgarian industrial zones with same-day replenishment capability.
Burgas
Burgas hosts Bulgaria's largest oil refinery infrastructure, enabling captive base oil supply for downstream formulation. National BIS-aligned standards govern industrial lubricant certification for regional manufacturing customers. The Black Sea port generates narrow but high-margin marine cylinder oil demand from bulk cargo vessel operations.
Varna
Varna's container terminal and naval facility sustain specialized grease demand for port handling equipment and marine applications. EU biodegradability mandates under the Green Deal industrial plan create technical barriers for small blenders lacking OECD 301B screening capability. Mining equipment servicing in nearby extractive zones commands premium pricing for extended-interval lubricant formulations.
Bulgaria Lubricants Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated energy majors controlling retail fuel-station networks while independent blenders capture industrial bulk contracts through technical service differentiation. The vendor base concentrates around three archetypes: vertically integrated refiners with captive base oil supply, premium synthetic specialists leveraging global R&D platforms, and regional independents competing on logistics proximity and customized formulation. Capacity expansion and predictive maintenance bundling represent the dominant competitive moves reshaping procurement relationships.
Among the integrated refiner tier, Lukoil exemplifies backward integration from base oil production through retail distribution. Shell Plc occupies a position as a premium synthetic specialist with established service station infrastructure. Prista Oil anchors the regional independent archetype through its Ruse-based blending capacity and domestic logistics reach.
| Leading Market Players |
|---|
| Prista Oil |
| Lukoil |
| Shell Plc |
| ExxonMobil Corporation |
| BP Plc (Castrol) |
| TotalEnergies SE |
| Chevron Corporation |
| AVIA International |
| Eni |
| Others |
Value Chain & Pricing Dynamics
Bulgarian fleet operators with 50-plus vehicle counts command contract-based pricing leverage unavailable to fragmented freelance mechanics purchasing spot-market volumes. Their multi-year framework agreements bundle lubricant supply with fluid analysis services, compressing per-liter premiums while locking in predictable cost structures.
Pricing Analysis
Capacity additions in Romania and Serbia are reshaping price floors for standard-grade mineral formulations along Bulgaria's northern border. Three-tier pricing structure across premium synthetic, standard mineral, and economy private-label levels stratifies the market, with ACEA C3 certification and volume scale serving as primary differentiation drivers. Pricing pressure stems from euro-denominated additive import costs eroding blender margins. Freelance mechanics exhibit highest price sensitivity, while transport companies prioritize drain-interval optimization over per-liter rates.
Supply Chain Analysis
Regional distribution centers in Ruse and Plovdiv anchor hub-and-spoke patterns reaching Sofia manufacturing corridors and Black Sea port zones. Base oil feedstock draws from Russia, Romania, and Greece, while performance additive packages hinge on German and Italian chemical suppliers. Single-source vulnerability concentrates in zinc-free anti-wear additive systems for food-grade hydraulic applications. Downstream distribution runs through bulk tanker contracts for industrial accounts and service station networks for retail synthetic grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bulgaria's lubricants market functions as a stable compounder, with EU Green Deal regulatory mandates sustaining steady reformulation-driven replacement cycles across transport and industrial end uses.
For Market Incumbents: Cement backward integration into Group II/III base oil supply through offtake agreements with Burgas refinery infrastructure, insulating margin structures from regional feedstock volatility. Prioritize REACH dossier maintenance and Ecolabel certification investments to filter out low-volume importers lacking ECHA compliance infrastructure. Channel control through Ruse-based logistics networks defends against emerging Romanian blenders targeting northern Bulgarian industrial zones. For New Entrants and Emerging Players: The mid-tier price gap between Shell's premium synthetics and economy private-label offerings presents the most penetrable entry point for differentiated bio-based formulations targeting agricultural and marine applications. Sofia-based predictive maintenance service bundling remains underdeveloped relative to fleet operator demand for drain-interval optimization. A technical service-led go-to-market approach emphasizing wear-metal analysis subscriptions can bypass entrenched fuel-station retail shelf space. For Investors and Strategic Acquirers: Independent blenders with established ECHA dossiers and captive northern logistics infrastructure represent the most active acquirer target category for integrated energy majors seeking REACH-compliant European footholds. Long-term viability rests on reformulation capability for bio-based and lower-viscosity chemistries mandated through the EU Green Deal industrial plan. Monitor EU carbon border adjustment implementation timelines as the critical inflection signal for base oil sourcing economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Captive feedstock access from Burgas refinery infrastructure insulates blenders from regional Group I/II price volatility. |
| Predictive Maintenance Service Bundling | Fluid analysis subscriptions with Sofia fleet operators convert transactional lubricant sales into recurring revenue streams. |
| Bio-based Formulation Certification | EU Ecolabel and OECD 301B compliance opens premium tiers for rapeseed-derived alternatives in agricultural applications. |
| Regional Distribution Hub Expansion | Ruse-based capacity additions enable same-day replenishment for northern Bulgarian manufacturing corridors. |
| REACH Dossier Investment | ECHA registration maintenance filters low-volume importers, consolidating shelf space for certified domestic blenders. |
Study Parameters
Multiple input streams — blending plant technical directors, fleet maintenance managers at Bulgarian transport operators, procurement leads at Plovdiv manufacturing facilities, and aftermarket distribution channel partners — were reconciled against secondary validation from customs trade databases, ECHA registration filings, and EU Green Deal implementation documents. Bottom-up volume estimates from end-use consumption patterns were triangulated with top-down capacity assessments across domestic blending infrastructure.
Data-stream reconciliation informed analytical framework development across the projection horizon, with segmentation dimensions spanning formulation grade tier, end-use application, packaging format, and regional demand cluster within Bulgaria. CAGRs were derived through regression analysis of historical consumption trajectories and elasticity modeling against fleet replacement cycle extensions and industrial automation investments. Forecast inputs incorporated REACH compliance cost pass-through assumptions and bio-based feedstock trial outcomes.
Caveats apply where EU carbon border adjustment implementation, base oil refinery output fluctuations in neighboring supply markets, or biodegradability certification timeline accelerations could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Heavy Equipment Lubricants Market
Lubricants
Lubricants for Cement Industry Market
Lubricants
Nigeria Lubricants Market
Lubricants
Synthetic Lubricants Market
Lubricants
Global Process Oil Market
Lubricants
Offshore Lubricants Market
Lubricants
Aluminum Extrusion Lubricants Market
Lubricants
China Lubricants Market
Lubricants
US Lubricants Market
Lubricants
Canada Commercial Vehicles Lubricants Market
Lubricants
Lubrication Equipment Market
Lubricants
Poland Industrial Lubricants Market
Lubricants
Synthetic Ester Lubricants Market
Lubricants
Chile Lubricants Market
Lubricants
Mexico Lubricants Market
Lubricants
India Commercial Vehicles Lubricants Market