
 Russia Lubricants Market | 2026-2036
Russia Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Lubricants Market Analytics
Russian base oil production is consolidating around Volga-Ural and West Siberian refining corridors. Lukoil leverages captive crude supply to anchor its position across engine oil and industrial lubricant grades. Gazprom Neft sustains integrated refining-blending capacity at its Omsk and Yaroslavl facilities. Rosneft competes through wholesale channel control and direct supply contracts with state mining and rail operators.
Lubricants are formulated mixtures of base oils and functional additives engineered to reduce friction, dissipate heat, and prevent wear between moving mechanical surfaces, with viscosity grades typically spanning ISO VG 32 through 680 for industrial applications and SAE 0W-16 through 25W-60 for automotive engines. Engine oil dominates value generation due to high replacement frequency and OEM specification complexity, while industrial lubricants capture margin pools through long-term technical service agreements with steel and mining enterprises. Greases represent a specialized niche where formulation chemistry differentiates suppliers serving Arctic and sub-Arctic operating conditions.
Russia's TR CU 030/2012 lubricant quality regulation, administered by Rosstandart, mandates base oil group classification and additive package certification, elevating compliance costs for importers while shielding domestic blenders. The country's national standards body (GOST R) maintains parallel specifications for military and strategic sector procurement, creating dual-track product development requirements. Stakeholders must monitor how sanctions-driven supply chain restructuring affects additive import channels and whether domestic synthesis investments materialize.
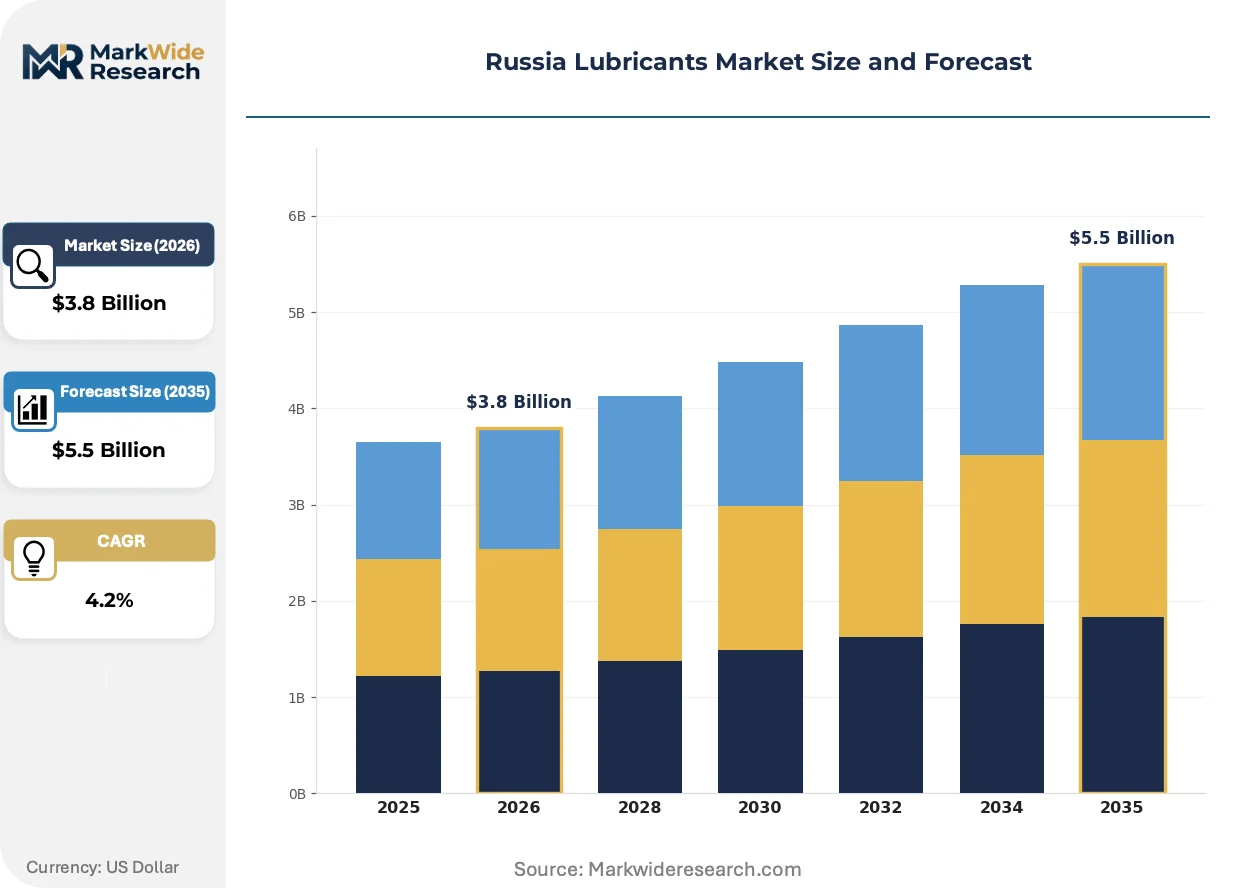
Market Dynamics
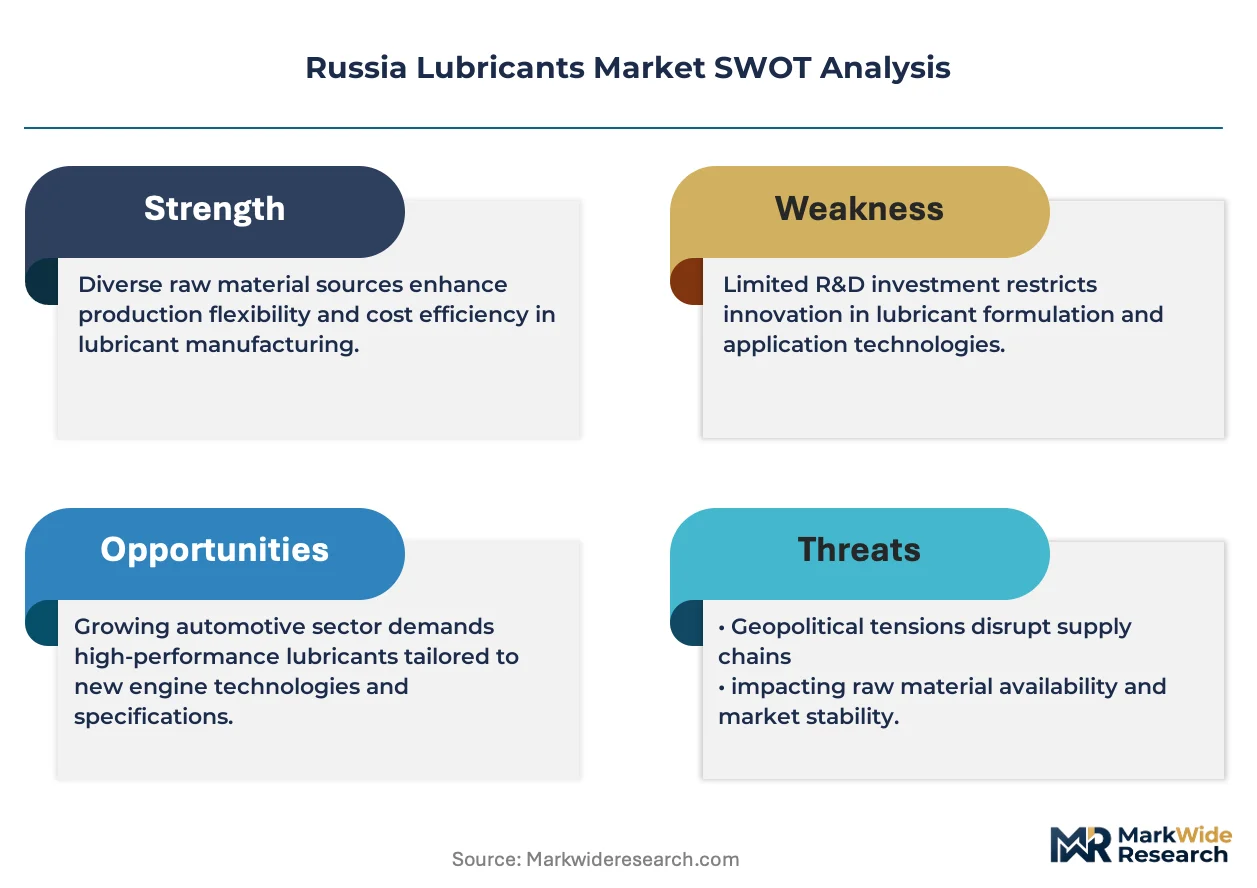
TR CU 030/2012 compliance costs are forcing domestic blenders to rebuild additive supply chains while import substitution mandates redirect procurement toward captive base oil production at Volga-Ural refineries.
Growth Catalysts
- Siberian Mining Expansion:High-viscosity industrial lubricant consumption is accelerating at Kuznetsk Basin and Norilsk operations where equipment duty cycles exceed standard formulations.
- TR CU 030/2012 Enforcement:Rosstandart certification requirements for base oil group classification are eliminating low-grade imports and clearing shelf space for compliant domestic products.
- Fleet Modernization:Moscow and Saint Petersburg commercial vehicle operators are upgrading to synthetic engine oils to meet extended drain intervals mandated by OEM service schedules.
Market Restraints
- Additive Import Dependency:PPD and detergent package supply from Western sources faces payment and logistics friction, compressing blender margins.
- Base Oil Grade Concentration:Group I capacity dominance at Samara and Ufa refineries limits high-performance Group III supply for premium automotive formulations.
- Arctic Logistics Costs:Grease distribution to Yamal and Vorkuta extraction sites requires heated transport infrastructure that inflates delivered costs.
Strategic Opportunities
- Far East Underpenetration:Vladivostok and Khabarovsk industrial zones lack dedicated lubricant blending, creating whitespace for regional distribution hubs.
- Rail Sector Long-Term Contracts:Russian Railways locomotive fleet renewal opens technical service agreements for transmission and axle grease supply.
- Domestic Additive Synthesis:State-backed investment into Omsk and Angarsk chemical complexes could localize antioxidant and anti-wear package production.
Industry Challenges
- Formulation Chemist Scarcity:Blending facilities in Tatarstan and Bashkortostan compete for talent trained in tribology and additive compatibility testing.
- Dual Certification Burden:Products for military procurement require parallel GOST R validation alongside TR CU compliance, extending development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Lubricants Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Industrial Lubricants, Greases, Transmission Fluids End User: Automotive, Manufacturing, Marine, Mining Application: Automotive Maintenance, Industrial Operations, Heavy Machinery, Construction Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | Shell, ExxonMobil, Lukoil, FUCHS, BP (Castrol), Gazprom Neft, DelfinGroup, TotalEnergies, Rosneft, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Lubricants Market Evolving Landscape
Synthetic base oil technology is reshaping competitive positioning as blenders race to localize Group III production and additive packages adapt to extended drain interval demands from fleet operators.
Group III synthetic base oils are overtaking Group I mineral stocks in premium automotive formulations. Lukoil and Gazprom Neft are converting hydrocracking units at Volgograd and Omsk to capture this shift. The technology is compressing import volumes while enabling SAE 0W-20 and 0W-16 grades previously supplied from Finnish and German blenders.
TR CU 030/2012's additive package certification mandate is elevating compliance barriers for importers. Rosstandart laboratory testing requirements now extend to cold-crank viscosity and high-temperature shear stability validation. Domestic blenders with captive testing infrastructure at Saint Petersburg and Kazan are capturing specification-driven procurement from state mining and rail operators.
Extended drain interval service contracts are displacing spot procurement at Moscow fleet maintenance depots. Synthetic formulations with 15,000-kilometer replacement cycles are unbundling traditional oil-change revenue models. This pattern concentrates among commercial vehicle operators managing Kamaz and GAZ Group truck fleets where downtime costs dominate lubricant selection criteria.
Russia Lubricants Market Segmentation
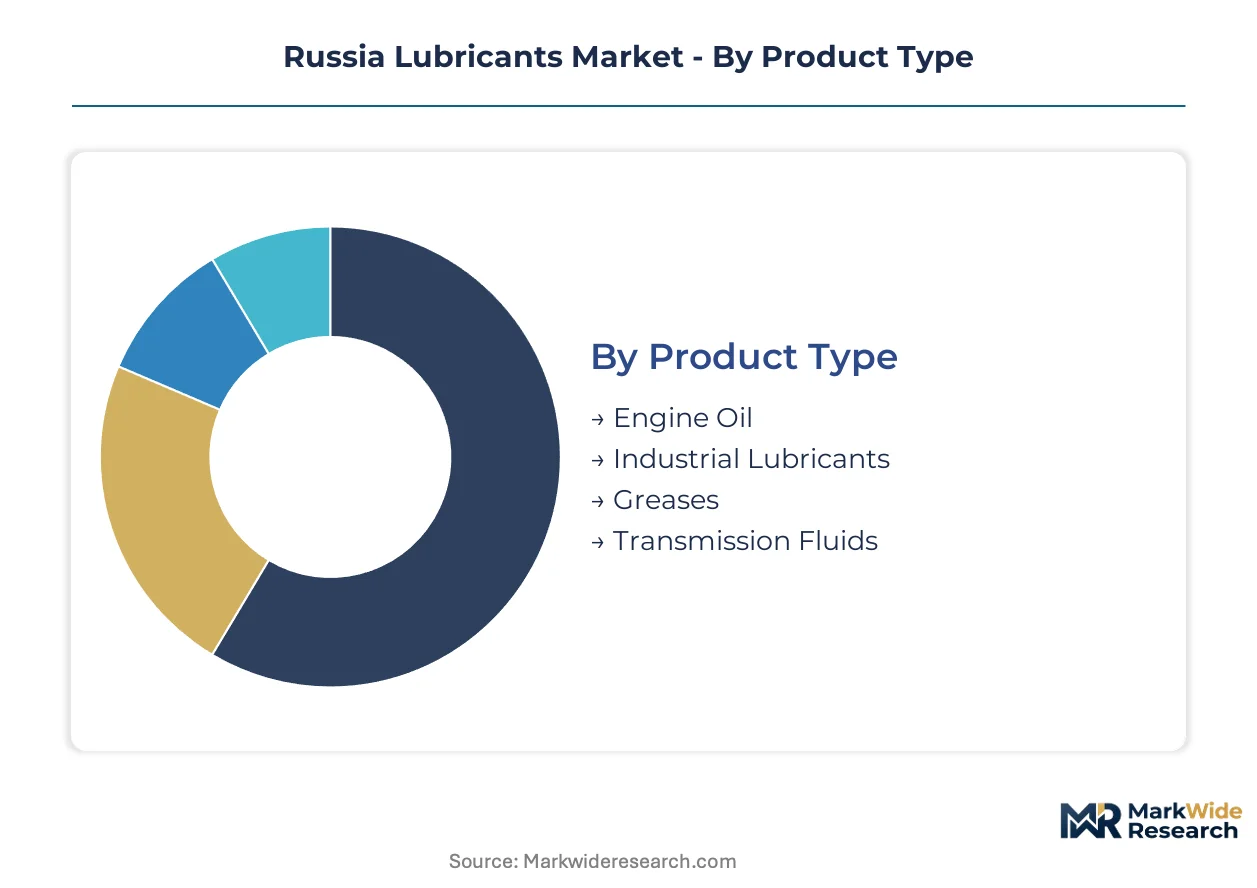
Lubricant segmentation in Russia reflects divergent capital requirements across formulation complexity, certification tiers, and distribution infrastructure. Blending facilities serving TR CU 030/2012-compliant segments demand disproportionate upfront investment in laboratory testing and additive synthesis capabilities.
Product Type:
Capital intensity peaks where formulation chemistry and certification infrastructure requirements intersect most sharply.
- Engine Oil:Synthetic base oil blends dominate premium formulations, with Group III hydrocracked stocks displacing Group I mineral bases. Moscow and Saint Petersburg fleet operators are consolidating procurement around extended drain interval specifications, forcing blenders to localize additive package production.
- Industrial Lubricants:High-viscosity formulations for hydraulic and compressor systems require specialized blending vessels and cold-flow testing infrastructure. Siberian mining clusters at Kuznetsk Basin and Norilsk absorb growing volumes where equipment duty cycles exceed standard formulation limits.
- Greases:Thickener chemistry and extreme-pressure additive selection differentiate suppliers for Arctic conditions.
- Transmission Fluids:OEM specification complexity limits qualified domestic blenders.
Most installed capacity flows through Engine Oil. Expansion is steepest in Industrial Lubricants.
End User:
Customer procurement scale determines blender investment in dedicated technical service teams and inventory positioning.
- Automotive:Fleet operators managing Kamaz and GAZ Group trucks concentrate demand in Moscow and Saint Petersburg maintenance depots. Extended drain interval contracts are displacing spot procurement, compressing traditional oil-change revenue models and elevating synthetic formulation requirements.
- Mining:State-owned extraction enterprises at Norilsk and Kuznetsk Basin negotiate long-term supply agreements with embedded technical service provisions. Equipment duty cycles in sub-Arctic conditions demand high-viscosity industrial lubricants with cold-crank performance validation.
- Manufacturing:Steel and machinery plants in Volga-Ural corridor source through wholesale channels with specification-driven procurement.
- Marine:Far East port operations at Vladivostok require specialized formulations meeting environmental discharge regulations.
Procurement scale concentrates in Automotive. Technical service intensity climbs fastest in Mining.
Application:
Operating environment severity dictates additive package investment and formulation durability testing.
- Industrial Operations:Continuous-duty steel mill and petrochemical equipment demands thermal stability and oxidation resistance beyond automotive specifications. Blending facilities serving this segment maintain dedicated laboratory infrastructure for high-temperature shear stability validation under TR CU 030/2012.
- Heavy Machinery:Construction and extraction equipment in Siberian and Far East regions confronts temperature extremes and contamination exposure. Grease formulations for Yamal and Vorkuta sites require heated transport infrastructure that inflates delivered costs.
- Automotive Maintenance:Service interval extension trends favor synthetic engine oils with 15,000-kilometer replacement cycles.
- Construction:Seasonal demand patterns and dispersed project sites challenge inventory optimization.
Formulation complexity peaks in Industrial Operations. Volume expansion is most pronounced in Heavy Machinery.
Distribution Channel:
Channel selection determines working capital intensity and customer intimacy requirements.
- Wholesale:Bulk supply contracts with Russian Railways and state mining enterprises dominate volume flows. Rosneft leverages wholesale channel control through direct supply agreements, capturing locomotive fleet renewal demand for transmission and axle grease.
- Direct Sales:Technical service agreements with steel and mining enterprises embed lubricant supply within maintenance contracts. This channel demands field engineering presence and tribology expertise that blender facilities in Tatarstan and Bashkortostan compete to staff.
- Retail:Automotive service stations and parts distributors serve fragmented consumer and small fleet demand.
- Online:Emerging channel for standardized formulations with established specifications.
Volume concentrates in Wholesale. Margin expansion is strongest in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic blenders are relocating production toward Volga-Ural refining corridors where TR CU 030/2012 compliance costs run lower than at import-dependent coastal facilities. This migration concentrates high-viscosity formulation capacity near captive base oil supply while trimming logistics exposure to disrupted additive import channels.
Volga-Ural Corridor
Samara and Ufa refineries anchor Group I base oil output serving industrial lubricant demand from steel mills in Magnitogorsk and Chelyabinsk. Rosstandart certification laboratories in Kazan validate cold-crank viscosity specifications for mining sector procurement. Blending facilities here leverage pipeline-connected feedstock to bypass Arctic logistics constraints affecting eastern distribution.
West Siberian Basin
Omsk and Yaroslavl integrated refineries supply hydrocracked base stocks to Siberian mining clusters at Kuznetsk Basin and Norilsk. Gazprom Neft maintains dedicated testing infrastructure for high-temperature shear stability validation under TR CU 030/2012. Regional procurement concentrates around long-term technical service agreements with state-owned extraction enterprises facing extreme equipment duty cycles.
Moscow-Saint Petersburg Axis
Fleet operators managing Kamaz and GAZ Group trucks drive synthetic engine oil demand through extended drain interval contracts displacing spot procurement. Lukoil captures premium automotive formulations via captive crude supply and hydrocracking unit conversion. Service depots here enforce OEM specification complexity that filters non-compliant imports from shelf space.
Far East Industrial Zone
Vladivostok and Khabarovsk manufacturing bases lack dedicated lubricant blending capacity, creating whitespace for regional distribution hubs. Marine port operations require specialized formulations meeting environmental discharge regulations at container terminals. State-backed infrastructure investment targets rail-linked storage to serve construction and extraction equipment across the Amur River basin.
Arctic Extraction Belt
Yamal and Vorkuta oil and gas sites absorb thickened grease formulations requiring heated transport infrastructure that inflates delivered costs. Norilsk Nickel operations negotiate supply agreements embedding tribology expertise for sub-Arctic equipment maintenance. Rosneft leverages wholesale channel control to capture locomotive fleet renewal demand for transmission and axle grease across the Northern Sea Route logistics network.
Russia Lubricants Market Competitive Landscape
Volga-Ural producers anchor one tier; Western specialists with residual import channels hold a narrowing premium position. Market structure tilts toward consolidation as sanctions-driven supply chain restructuring eliminates marginal blenders dependent on foreign additive packages. Three archetypes dominate: integrated oil companies with captive refining, independent blenders with Rosstandart-certified laboratories, and residual Western suppliers navigating payment friction. Competitive moves concentrate on hydrocracking unit conversion for Group III synthesis and backward integration into antioxidant package production.
Among Russia-based integrated producers, Lukoil, Gazprom Neft, and Rosneft exemplify the captive-refining archetype. Lukoil occupies a position tied to Volgograd hydrocracking conversion. Gazprom Neft anchors integrated capacity at Omsk and Yaroslavl. Rosneft sits within the wholesale channel control segment serving state mining and rail procurement. Western players Shell and ExxonMobil represent the contracting import-dependent tier facing additive logistics friction.
| Leading Market Players |
|---|
| Shell |
| ExxonMobil |
| Lukoil |
| FUCHS |
| BP (Castrol) |
| Gazprom Neft |
| DelfinGroup |
| TotalEnergies |
| Rosneft |
| Others |
Value Network & Pricing Analysis
Captive base oil integration at Volga-Ural refineries anchors both supply security and pricing power for domestic blenders, insulating compliant producers from additive import volatility while compressing margins for import-dependent competitors.
Pricing Analysis
Distributor margin compression runs deepest where Western additive packages face payment friction, forcing domestic blenders to absorb cost escalation or surrender shelf space. Three-tier pricing structure across synthetic premium, hydrocracked standard, and mineral economy levels separates fleet operators with extended drain contracts from spot-buying maintenance depots. Pricing pressure stems from Rosstandart certification costs that elevate compliance investment for Group III formulations. State mining enterprises exhibit lowest price sensitivity due to embedded technical service agreements, while fragmented retail automotive channels face acute cost compression.
Supply Chain Analysis
Regional distribution centers in Kazan and Saint Petersburg coordinate hub-and-spoke patterns that feed blending facilities across the Volga-Ural corridor and West Siberian Basin. Feedstock concentration rests on Samara, Ufa, Omsk, and Yaroslavl refineries with pipeline-connected Group I and hydrocracked Group III output. Additive package supply draws from residual Western channels and nascent domestic synthesis at Angarsk, creating single-source vulnerability for PPD and detergent chemistry. Distribution runs through wholesale bulk contracts with Russian Railways and state mining enterprises, supplemented by direct technical service agreements embedding field engineering support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Russia lubricants market functions as a geographic-arbitrage play where TR CU 030/2012 compliance costs in coastal import corridors exceed captive refining economics in Volga-Ural corridors by a substantial margin.
For Market Incumbents: To counter additive import dependency eroding formulation margins, Lukoil and Gazprom Neft should accelerate hydrocracking unit conversion at Volgograd and Omsk to localize Group III supply. Rosneft must deepen wholesale channel control through long-term technical service agreements with Russian Railways locomotive fleet renewal, embedding axle grease supply within maintenance contracts to lock out residual Western competitors. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Far East industrial zones creates whitespace for regional blending capacity at Vladivostok, where marine port demand and construction equipment supply lack dedicated infrastructure. Target underpenetrated Khabarovsk manufacturing bases with rail-linked storage investments, leveraging state-backed infrastructure programs to secure offtake agreements before integrated producers redirect capacity eastward. For Investors and Strategic Acquirers: Roll-up economics work for independent blenders with Rosstandart-certified laboratories because TR CU 030/2012 compliance barriers eliminate marginal competitors and concentrate procurement around validated domestic suppliers. Platform consolidation targets should prioritize Kazan and Tatarstan facilities with captive testing infrastructure and existing technical service contracts with steel or mining enterprises. The signal to monitor is state-backed investment into Omsk and Angarsk additive synthesis complexes, which would reshape competitive economics for antioxidant and anti-wear package production.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Synthesis | Domestic antioxidant production at Angarsk severs Western supply dependency for TR CU 030/2012 compliance. |
| Hydrocracking Unit Conversion | Group III base oil localization at Volgograd enables SAE 0W-20 formulations previously imported from Finnish blenders. |
| Regional Distribution Hub Buildout | Vladivostok blending capacity captures Far East marine and construction demand outside Volga-Ural supply radius. |
| Long-term Technical Service Agreement | Russian Railways locomotive fleet renewal embeds transmission fluid supply within maintenance contracts. |
| Rosstandart Certification Investment | Kazan laboratory infrastructure validates cold-crank specifications for Norilsk sub-Arctic procurement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with blending plant managers, procurement leads at state mining enterprises, Rosstandart certification officials, and aftermarket service heads with secondary validation from customs trade data, GOST R specification registries, and SEC filings of exposed Western suppliers. Bottom-up capacity assessments at Samara, Ufa, Omsk, and Yaroslavl refineries were triangulated against top-down demand modeling from fleet operator maintenance schedules and mining equipment duty cycle data.
Segment-weighting approaches distributed volume and value across engine oil, industrial lubricant, grease, and transmission fluid categories, with further disaggregation by base oil group classification and end-user procurement scale. CAGRs were derived from elasticity-adjusted demand curves incorporating OEM service interval extension trends and synthetic formulation penetration rates. Forecast inputs included hydrocracking capacity expansion timelines, additive import channel disruption scenarios, and state mining capital expenditure patterns.
The model assumes a particular technology adoption path; alternative pathways for domestic additive synthesis would alter the outlook if Angarsk and Omsk chemical complex investments accelerate or stall. Forecasts reflect documented assumptions around TR CU 030/2012 enforcement consistency and sanctions regime durability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Offshore Lubricants Market
Lubricants
Global Compressor Oil Market
Lubricants
Asia-Pacific Automotive Lubricants Market
Lubricants
Turkey Automotive Lubricants Market
Lubricants
Global Fire Resistant Hydraulic Fluid Market
Lubricants
Heavy Equipment Lubricants Market
Lubricants
Automotive Die Casting Lubricants Market
Lubricants
United States Automotive Lubricants Market
Lubricants
China Automotive Engine Oils Market
Lubricants
Cutting Fluid Market
Lubricants
Cold Rolling Oils/Lubricants Market
Lubricants
Turkey Marine Lubricants Market
Lubricants
Jordan Lubricants Market
Lubricants
Spain Automotive Lubricants Market
Lubricants
Global Lubricants Market
Lubricants
Middle East Commercial Vehicles Lubricants Market