
 Europe Marine Lubricants Market | 2026-2036
Europe Marine Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Marine Lubricants Market Insights
Capital-intensity divergence between integrated refiners and independent blenders is unwinding competitive stability in the Europe marine lubricants sector. TotalEnergies leverages its integrated refining network across French Atlantic ports to secure captive base oil supply. FUCHS anchors its position through specialized grease formulations for stern tube applications in Baltic shipping lanes. Royal Dutch Shell competes via extensive bunkering infrastructure that extends lubricant distribution reach into Mediterranean hubs.
Europe marine lubricants are formulated lubricating fluids and greases designed to reduce friction, dissipate heat, and prevent corrosion in propulsion engines, auxiliary machinery, and deck equipment operating under saline, high-load conditions; these formulations typically incorporate anti-wear additives such as zinc dialkyldithiophosphate and detergent-dispersant packages to meet OEM viscosity specifications across two-stroke crosshead and four-stroke trunk piston engines. Engine oil commands the dominant revenue share due to continuous consumption in main propulsion systems, while synthetic formulations are gaining structural prominence as ship operators prioritize extended drain intervals and cold-start reliability in North Atlantic routes. Bio-based lubricants occupy a niche but expanding margin pool, driven by EU Green Deal procurement mandates and port authority environmental incentive schemes.
EMA, REACH, and the EU Green Deal collectively constrain formulation chemistry, mandate biodegradability thresholds for lubricants discharged in European waters, and shape product registration pathways for non-EU suppliers. The F-Gas Regulation and impending FuelEU Maritime standards further tighten specifications for refrigerant and engine oils used in auxiliary systems aboard vessels calling at EU ports. Stakeholders must monitor regulatory alignment between national port authorities and Brussels-based framework revisions to anticipate formulation reformulation cycles and compliance cost pass-through structures.
Market Dynamics
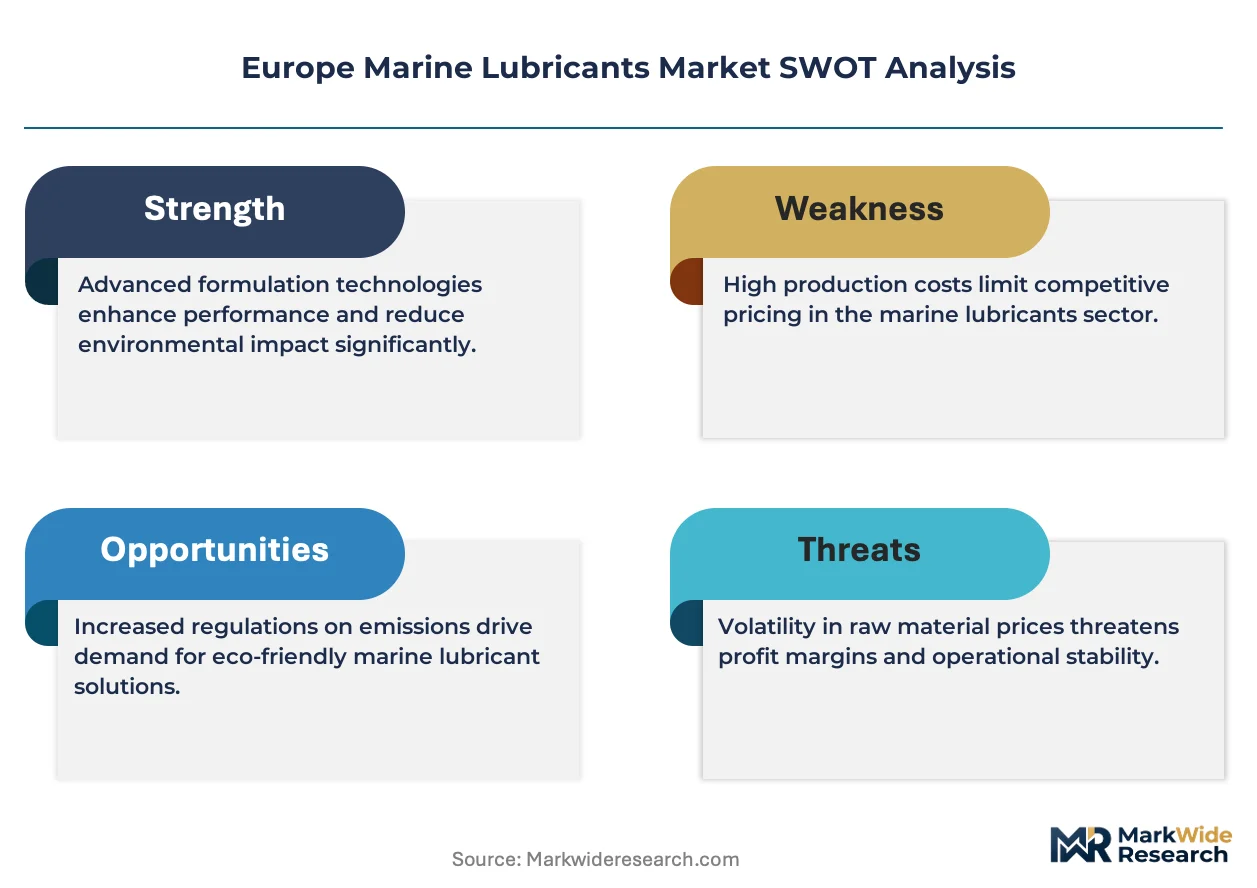
IMO 2020 sulphur compliance mandates and FuelEU Maritime standards are compressing formulation cycles across European blenders, forcing simultaneous investment in low-sulphur base stocks and bio-based additive packages.
Growth Catalysts
- FuelEU Maritime implementation:The EU regulation mandates progressive greenhouse gas intensity reductions for marine fuels, compelling vessel operators to seek lubricants compatible with alternative fuels and exhaust after-treatment systems.
- Container traffic through North Sea corridors:Intensified vessel rotations at Rotterdam and Hamburg generate continuous demand for high-performance engine oils with extended drain intervals.
- Two-stroke crosshead engine technology:New-generation low-speed engines operating on very low sulphur fuel oil require specialized cylinder lubrication strategies that increase oil consumption precision.
Market Restraints
- Group II/III base oil supply concentration:European refiners control limited hydrocracking capacity for high-quality marine base stocks, creating dependency on Middle Eastern and Asian supply.
- REACH registration costs:The ECHA framework imposes substantial data requirements on lubricant additive packages, elevating barriers for non-EU formulation suppliers.
- Extended drain interval technology:Synthetic formulations lasting 12,000+ operating hours reduce absolute lubricant volume demand per vessel despite premium pricing.
Strategic Opportunities
- Baltic Sea environmental incentive schemes:Port authorities in Sweden and Finland offer reduced harbor fees for vessels using biodegradable stern tube lubricants, creating preferential procurement channels.
- Auxiliary machinery electrification:Hybrid vessel architectures require new thermal management fluids for electric propulsion motors and power conversion systems.
- Digital condition monitoring convergence:Integration of IoT sensors with lubricant analysis services enables predictive maintenance contracts that lock in long-term supply relationships.
Industry Challenges
- Marine chemist certification timelines:The specialized expertise required for lubricant compatibility testing with dual-fuel engines faces constrained training pipeline capacity.
- Legacy inventory reconciliation:Ship operators managing mixed fleets must maintain parallel lubricant stocks for conventional and alternative-fuel vessels, complicating supply chain logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Marine Lubricants Market |
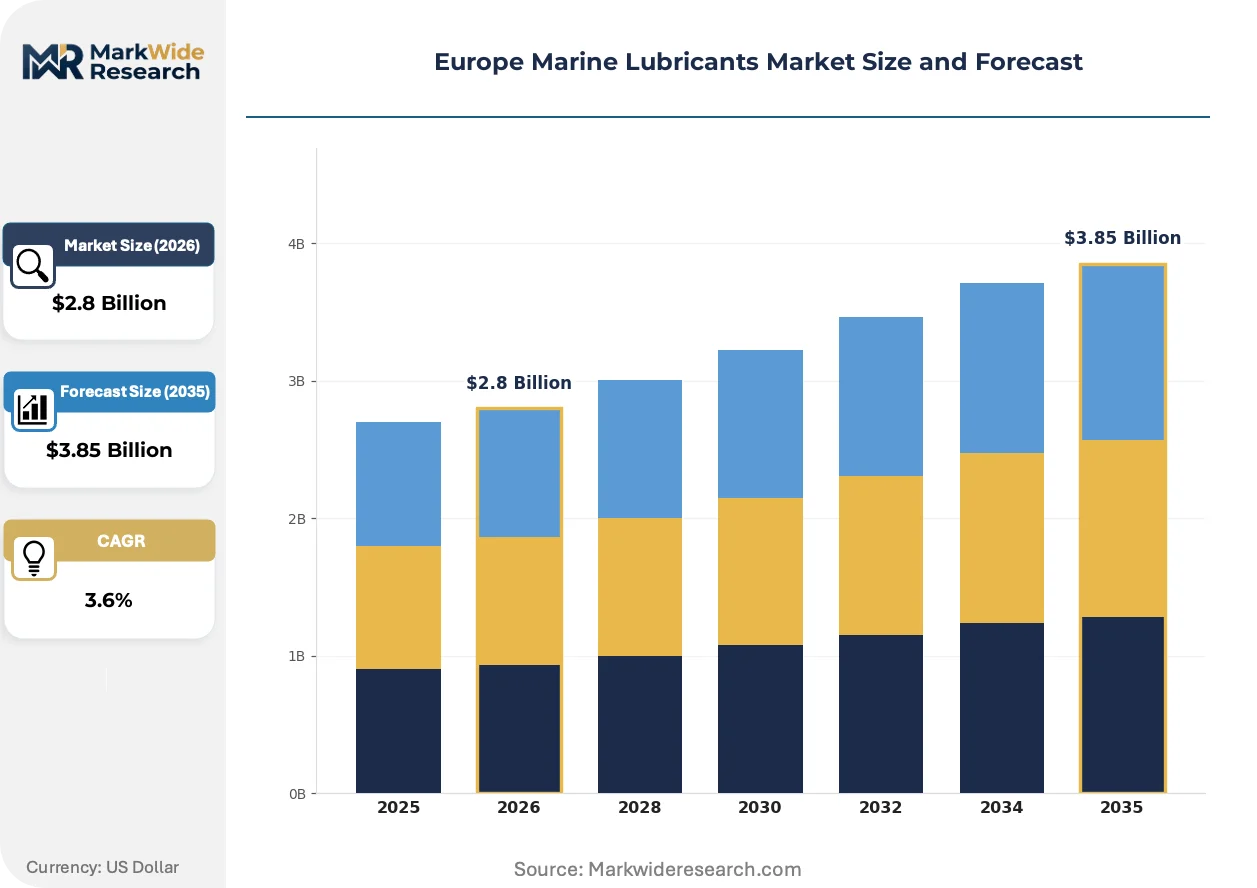
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $3.85 Billion |
| CAGR (2026 – 2036) | 3.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Hydraulic Oil, Gear Oil, Grease Formulation Type: Synthetic, Mineral, Bio-based, Semi-synthetic Application Type: Commercial Shipping, Recreational Boating, Fishing Vessels, Cargo Vessels End User: Shipping Companies, Yacht Owners, Fishing Enterprises, Marine Service Providers |
| Companies Covered | FUCHS, Exxon Mobil Corporation, Royal Dutch Shell, Repsol, Chevron Corporation, BP, LUKOIL, Eni, TotalEnergies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Marine Lubricants Market Trends and Innovations
Marine lubricant chemistry is pivoting toward compatibility with methanol and ammonia fuel systems, while digitalization restructures how technical service reaches vessel operators.
Synthetic ester formulations are displacing mineral-based stern tube oils in Baltic and North Sea routes. Shipowners operating ice-class vessels prioritize these fluids for their cold-flow properties and biodegradability credentials. The shift is compressing demand for conventional white oil products in environmentally sensitive waterways.
REACH authorization requirements for zinc dialkyldithiophosphate and other anti-wear additives are tightening formulation flexibility. ECHA's sunset date scheduling forces blenders to qualify alternative chemistries ahead of regulatory deadlines. The pressure concentrates most intensely on high-performance engine oil segments where EP additive loadings remain critical.
Technical service contracts are unbundling from product supply agreements. Major container lines now source lubricants and condition monitoring separately, awarding analysis contracts to specialized marine laboratories. The fragmentation is visible among German and Dutch operators with centralized fleet technical management functions.
Europe Marine Lubricants Market Segmentation
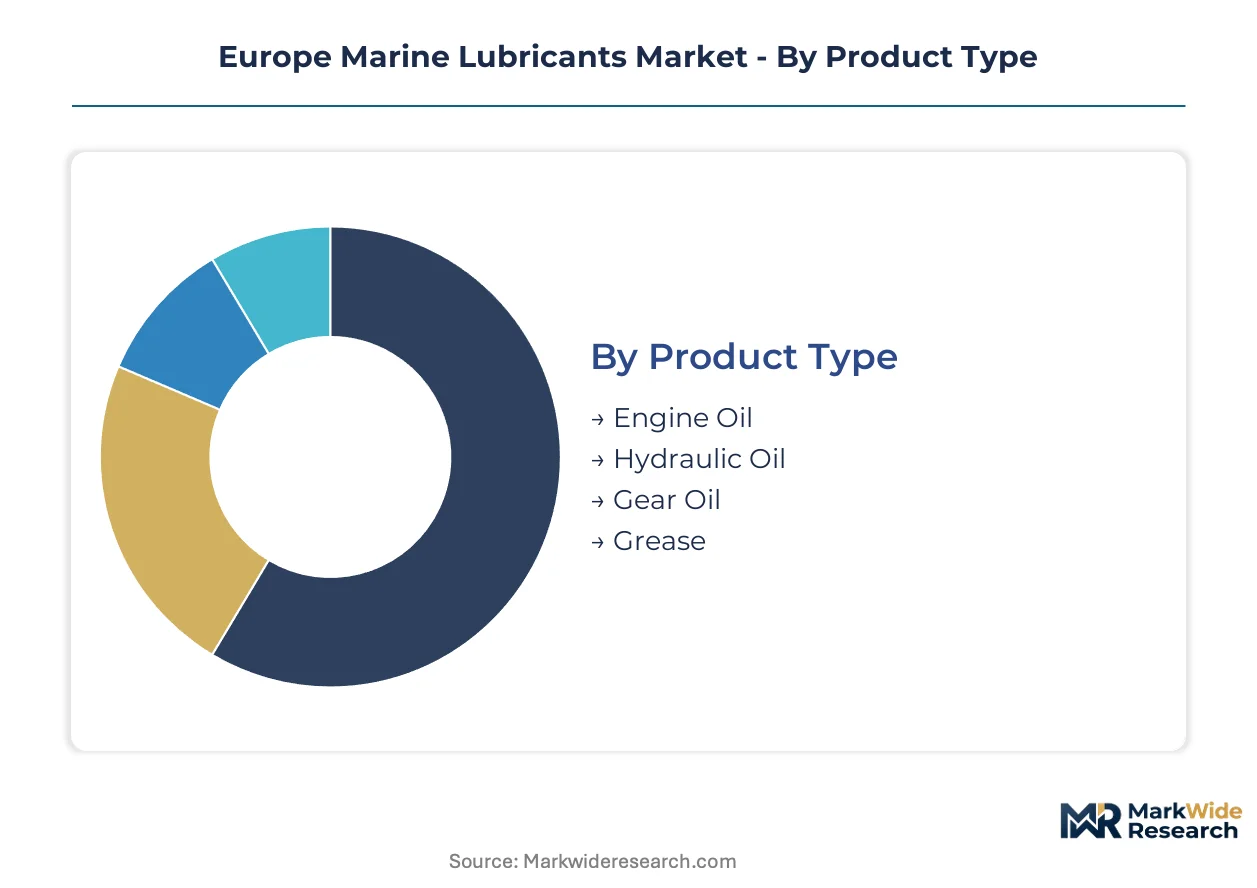
Segmentation in the Europe marine lubricants market reveals how formulation chemistry, vessel architecture, and procurement authority reshape distribution economics. Channel strategies diverge sharply between bulk engine oil supply to container fleets and specialized grease deliveries to Baltic fishing cooperatives.
Product Type:
Marine lubricant channels route high-volume engine oils through integrated refiner-bunkering networks, while hydraulic and gear oils flow via specialized marine distributors serving shipyards and repair facilities.
- Engine Oil:Formulations blend Group II/III base stocks with zinc dialkyldithiophosphate anti-wear packages to meet OEM viscosity specifications for two-stroke crosshead and four-stroke trunk piston engines. Rotterdam and Hamburg container terminals concentrate procurement of high-performance cylinder oils as vessel rotations intensify through North Sea corridors, with drain interval extension driving synthetic uptake despite premium positioning.
- Hydraulic Oil:Anti-wear hydraulic fluids incorporating detergent-dispersant packages maintain system cleanliness in deck machinery and steering gear under saline, high-load conditions. German and Dutch offshore service vessel operators prioritize fire-resistant formulations for dynamic positioning systems, with procurement flowing through specialized marine equipment distributors rather than bunkering infrastructure.
- Gear Oil:Extreme-pressure gear lubricants protect reduction gears and thruster systems in ice-class vessels operating Baltic routes.
- Grease:Specialized formulations for stern tube bearings and deck equipment serve fishing fleets and coastal shipping through regional marine supply cooperatives.
By volume, Engine Oil leads. By growth pace, Grease formulations for stern tube applications are climbing the fastest.
Formulation Type:
Cost tier stratification separates premium synthetics from commodity mineral oils, with bio-based products occupying a niche margin layer supported by EU Green Deal procurement mandates.
- Synthetic:Polyalphaolefin and ester-based formulations deliver extended drain intervals exceeding 12,000 operating hours alongside cold-start reliability for North Atlantic routes. Scandinavian container lines and German deep-sea operators drive procurement concentration, with REACH-compliant additive packages commanding price premiums over mineral alternatives.
- Mineral:Refined petroleum-based lubricants remain the volume baseline for older vessel fleets and cost-sensitive coastal operators, particularly in Mediterranean short-sea shipping where regulatory pressure on biodegradability remains lighter than in Baltic waters.
- Bio-based:Synthetic ester formulations from renewable feedstocks meet EU biodegradability thresholds for stern tube oils discharged in sensitive waterways.
- Semi-synthetic:Blended formulations balance performance enhancement against mineral oil cost structures for mid-life vessel retrofits.
By volume, Mineral formulations dominate. By margin expansion, Bio-based lubricants are gaining share fastest.
Application Type:
Vessel architecture determines lubricant consumption intensity, with commercial shipping generating continuous demand through main propulsion systems while recreational applications concentrate seasonal purchasing through retail marine channels.
- Commercial Shipping:Deep-sea container and bulk carriers consume continuous volumes of cylinder and system oils through integrated technical management contracts. Rotterdam-based fleet operators negotiate consolidated supply agreements covering lubricants alongside bunkering, with condition monitoring services increasingly unbundled from product supply.
- Cargo Vessels:General cargo and roll-on/roll-off fleets operating North Sea corridors require high-performance engine oils compatible with exhaust after-treatment systems mandated by FuelEU Maritime standards.
- Fishing Vessels:Stern tube and deck machinery lubricants serve Baltic and North Atlantic fishing cooperatives through regional supply networks.
- Recreational Boating:Outboard engine oils and marine greases flow through chandlery retail and marina service points with pronounced seasonal demand patterns.
By volume, Commercial Shipping leads. By procurement contract innovation, Cargo Vessels are expanding most quickly.
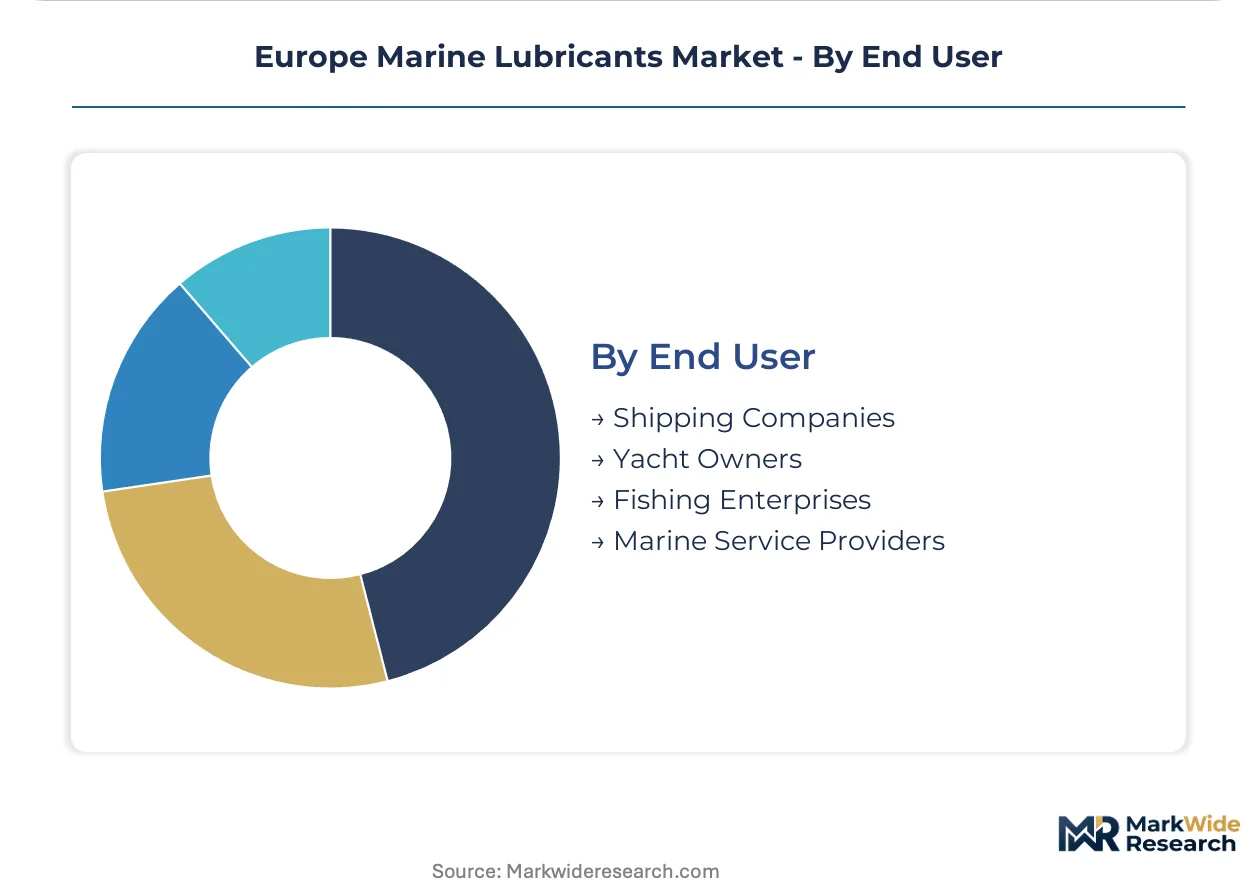
End User:
Customer type shapes technical service intensity, with shipping companies demanding predictive maintenance integration while yacht owners prioritize convenience through marina retail channels.
- Shipping Companies:Container line technical departments in Germany and the Netherlands centralize lubricant procurement across global fleets, awarding multi-year supply contracts tied to IoT-enabled condition monitoring. ECHA registration compliance and FuelEU Maritime compatibility dominate supplier qualification criteria.
- Marine Service Providers:Independent shipyards and repair facilities stock lubricants for unscheduled maintenance, sourcing through regional distributors with rapid delivery commitments.
- Fishing Enterprises:Cooperative purchasing structures in Sweden and Finland consolidate biodegradable stern tube oil procurement to capture port authority environmental incentives.
- Yacht Owners:High-net-worth recreational users access premium synthetic formulations through marina chandlery with limited price sensitivity.
By volume, Shipping Companies lead. By incentive-driven switching, Fishing Enterprises are moving fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with Rotterdam-based blenders serving North Sea container traffic, while Mediterranean operators absorb margin compression from fragmented supply chains and lighter regulatory pressure on biodegradability.
Germany
Container line technical departments in Hamburg and Bremen centralize procurement of synthetic engine oils with extended drain intervals. REACH registration requirements for zinc dialkyldithiophosphate additives elevate barriers for non-EU suppliers seeking port access. The Port of Hamburg anchors demand for high-performance cylinder lubricants as vessel rotations intensify through Elbe corridor connections.
Netherlands
Integrated refiner-bunkering networks at Rotterdam capture lubricant supply contracts tied to marine fuel procurement. FuelEU Maritime standards compel fleet operators to source formulations compatible with exhaust after-treatment systems. The Maasvlakte terminal complex concentrates blending capacity for low-sulphur base stocks serving deep-sea container lines.
Sweden
Baltic Sea fishing cooperatives consolidate biodegradable stern tube oil procurement to capture port authority environmental incentive schemes. EU Green Deal procurement mandates accelerate synthetic ester uptake for ice-class vessels operating northern routes. Gothenburg's port authority offers reduced harbor fees for vessels meeting biodegradability thresholds for lubricants discharged in Swedish waters.
France
TotalEnergies leverages captive base oil supply from Atlantic refining capacity to serve container and bulk carrier fleets calling at Le Havre and Marseille. ECHA sunset date scheduling for anti-wear additives forces qualification of alternative chemistries ahead of regulatory deadlines. The French Atlantic port corridor concentrates demand for high-performance system oils in main propulsion applications.
United Kingdom
London-based shipping company technical management functions unbundle lubricant supply from condition monitoring services, awarding analysis contracts to specialized marine laboratories. F-Gas Regulation compliance tightens specifications for refrigerant oils in auxiliary systems aboard vessels calling at UK ports. Southampton and Felixstowe container terminals generate continuous demand for cylinder oils compatible with very low sulphur fuel oil operations.
Europe Marine Lubricants Market Competitive Landscape
Concentration sits with integrated energy majors controlling captive refining capacity and bunkering infrastructure. Three strategic archetypes define competitive positioning: vertically integrated refiners securing base oil supply, specialized blenders dominating niche grease formulations, and global oil majors extending distribution reach through port-based logistics networks. Capacity expansion in Group II/III base oil hydrocracking and strategic partnerships for bio-based additive sourcing represent the dominant competitive moves.
Among integrated European energy groups, TotalEnergies, Royal Dutch Shell, and BP exemplify the refiner-bunkering archetype. TotalEnergies occupies a position anchored to French Atlantic refining networks. Royal Dutch Shell sits within the distribution-intensive tier leveraging extensive port infrastructure. BP represents the technical service unbundling trend as container lines separate lubricant procurement from condition monitoring contracts.
| Leading Market Players |
|---|
| FUCHS |
| Exxon Mobil Corporation |
| Royal Dutch Shell |
| Repsol |
| Chevron Corporation |
| BP |
| LUKOIL |
| Eni |
| TotalEnergies |
| Others |
Pricing and Supply Chain Analysis
Group II/III base oil substitution for traditional Group I stocks is compressing European blenders' feedstock flexibility while simultaneously elevating procurement costs toward Middle Eastern and Asian supply origins. This feedstock pivot concentrates pricing leverage with Rotterdam-based integrated refiners who control captive hydrocracking capacity, leaving independent blenders exposed to spot market volatility.
Pricing Analysis
The customization-premium spread separates synthetic ester formulations commanding REACH-compliant additive packages from commodity mineral oils serving Mediterranean short-sea operators. Three-tier pricing structure across premium synthetic, mid-grade semi-synthetic, and economy mineral levels tracks certification grade and drain interval performance. Price erosion runs through the mineral tier as extended drain technology reduces per-vessel volume demand. Coastal fishing cooperatives exhibit highest price sensitivity, while German deep-sea container lines prioritize technical service integration over unit cost.
Supply Chain Analysis
Inventory lead times for zinc dialkyldithiophosphate and other REACH-registered additives now stretch across ECHA authorization cycles, forcing blenders to pre-position additive stocks ahead of sunset date deadlines. Base oil supply draws from Netherlands, Belgium, and France where hydrocracking capacity concentrates, with additive packages sourcing from Germany and Switzerland. Single-source vulnerability sits with Middle Eastern Group III supply for premium synthetics. Distribution runs through Rotterdam bunkering networks for high-volume engine oils, while specialized greases flow via Baltic marine cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe marine lubricants constitute a service-attach opportunity where predictive maintenance contracts and IoT-enabled condition monitoring expand faster than base product volume. Technical service unbundling creates recurring revenue layers that lock in supply relationships beyond transactional lubricant sales.
For Market Incumbents: Shield market position by deepening backward integration into bio-based additive sourcing ahead of EU Green Deal procurement mandates, and accelerate certification investment for methanol-compatible formulations before FuelEU Maritime standards tighten. REACH registration barriers protect against non-EU formulation suppliers, but synthetic ester displacement of mineral stocks threatens legacy product margins. For New Entrants and Emerging Players: Anchor in Baltic Sea fishing cooperatives where port authority environmental incentives concentrate demand for biodegradable stern tube lubricants, and target auxiliary machinery electrification opportunities in hybrid vessel thermal management fluids. A go-to-market angle through digital condition monitoring partnerships bypasses entrenched bunkering infrastructure controlled by integrated refiners. For Investors and Strategic Acquirers: Capital is best deployed toward specialized blenders with captive bio-based formulation expertise and established ECHA registration portfolios, positioned for medium-term regulatory tailwinds. The inflection signal to watch is FuelEU Maritime implementation pace accelerating alternative fuel vessel orders and their corresponding lubricant compatibility requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Additives | Secures supply chains against REACH authorization timelines and EU Green Deal procurement thresholds. |
| Digital Condition Monitoring Partnership | Locks in long-term technical service contracts with Rotterdam and Hamburg container operators. |
| Capacity Expansion in Group III Base Oils | Reduces dependency on Middle Eastern supply for synthetic marine lubricant formulations. |
| Methanol Compatibility Certification | Positions formulations for FuelEU Maritime alternative fuel vessel requirements. |
| Baltic Port Authority Incentive Alignment | Captures preferential procurement channels through biodegradable stern tube oil qualifications. |
Research Methodology
A standing panel of marine technical superintendents, port authority environmental compliance officers, lubricant blending plant managers, and ECHA regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from customs trade data, EU MRV emissions databases, SEC filings of listed energy majors, and port authority tariff schedules. Bottom-up vessel fleet lubricant consumption estimates triangulated against top-down blender production capacity assessments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling spanned product type, formulation chemistry, vessel architecture, and procurement authority dimensions. CAGRs derived from regression analysis of historical consumption patterns adjusted for regulatory intervention effects. Forecast inputs incorporated FuelEU Maritime implementation schedules and REACH sunset date timelines without specific year anchoring.
Material uncertainties — regulatory acceleration or delay, alternative fuel vessel order volatility, base oil supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions about compliance cost pass-through structures and fleet renewal rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Bulgaria Passenger Vehicles Lubricants Market
Lubricants
Bangladesh Lubricants Market
Lubricants
Global Refrigeration Lubricants Market
Lubricants
Hydro Lubricants Market
Lubricants
Germany Automotive Lubricants Market
Lubricants
Indonesia Lubricants Market
Lubricants
Cold Rolling Oils/Lubricants Market
Lubricants
Malaysia Automotive Engine Oils Market
Lubricants
Middle East Lubricants Market
Lubricants
Polyurea Greases Market
Lubricants
Global Automotive Engine Oils Market
Lubricants
Perfluoropolyether Fluorinated Fluids Market
Lubricants
Argentina Lubricants Market
Lubricants
Qatar Lubricants Market
Lubricants
Europe Grease Market
Lubricants
Global Lubricants Market