
 Philippines Lubricants Market | 2026-2036
Philippines Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Lubricants Market Analytics
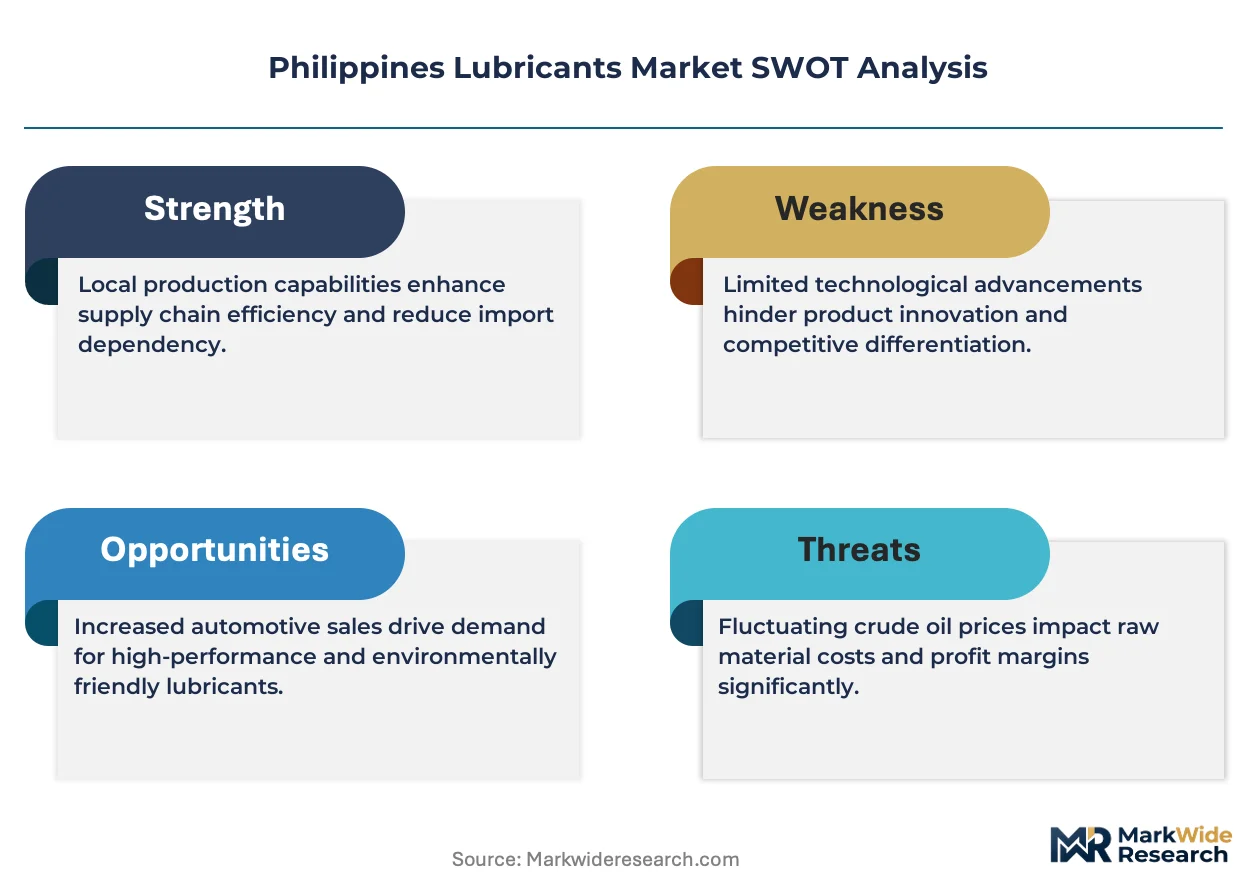
Commercial logistics is consolidating its share of lubricant offtake as fleet operators standardize on extended-drain synthetic formulations. Shell plc sustains manufacturing scale through its Tabangao refinery integration and nationwide depot network. Petron Corporation leverages backward integration into base oil refining to control input costs. SEAOIL Philippines Inc. competes through aggressive channel expansion in provincial retail stations.
Philippines lubricants are formulated blends of base oils and additive packages designed to reduce friction, dissipate heat, and prevent wear in mechanical systems, with viscosity grades typically ranging from ISO VG 32 to VG 680 for industrial applications and SAE 5W-30 to 15W-40 for automotive engines. Engine Oil dominates product type revenue due to the country's large parc of aging diesel-powered commercial vehicles. Industrial Machinery applications within the manufacturing end user segment are expanding fastest as food processing and electronics assembly plants automate production lines. The wholesale distribution channel retains structural importance for bulk industrial contracts while retail and online channels fragment consumer and light commercial purchasing.
The Philippine Department of Energy enforces fuel and lubricant quality standards aligned with ASEAN harmonization protocols, while the Bureau of Product Standards mandates labeling and performance certification under national standards. BIS-equivalent local testing laboratories verify additive content and viscosity stability for imported formulations. Stakeholders must monitor regulatory alignment between Philippine specifications and evolving ASEAN technical regulations to anticipate reformulation requirements and import licensing adjustments.
Market Dynamics
Fleet modernization across Philippine commercial logistics is consolidating lubricant procurement volumes toward higher-grade synthetics, compressing demand fragmentation and elevating formulation standards across the supply base.
Growth Catalysts
- DOE Fuel Quality Regulations:The Philippine Department of Energy's tightening base oil specifications are forcing refiners to upgrade hydrocracking capacity, expanding the addressable market for Group II and III base stocks.
- CALABARZON Manufacturing Expansion:Electronics assembly and food processing plants in this industrial corridor are automating production lines, accelerating demand for high-viscosity hydraulic fluids and synthetic gear oils.
- Extended-Drain Formulations:Synthetic lubricants with 50,000-kilometer service intervals are displacing mineral-based products in long-haul trucking fleets, reducing total cost of ownership and locking in supplier relationships.
Market Restraints
- Base Oil Import Dependency:Philippine refiners rely on regional Group I base oil imports from Singapore and South Korea, exposing margins to freight rate volatility and currency fluctuation.
- Group I Capacity Rationalization:Regional refiners are retiring solvent-refining capacity faster than local blenders can reformulate, creating formulation discontinuities for legacy equipment operators.
- Biodiesel Compatibility Testing:The Department of Energy's B20 mandate requires additional lubricant additive testing for fuel dilution resistance, extending product development timelines.
Strategic Opportunities
- Visayas and Mindanao Provincial Networks:Underpenetrated agricultural and fishing fleet markets outside Luzon offer volume expansion for distributors establishing cold-chain logistics partnerships.
- Wind Turbine Servicing:Emerging offshore wind projects in the Philippine Exclusive Economic Zone will require specialized synthetic greases and gearbox fluids with salt-water corrosion resistance.
- E-Commerce Channel Integration:Direct-to-workshop platforms are bypassing traditional jobber networks, enabling smaller blenders to reach independent repair shops in secondary cities.
Industry Challenges
- Formulation Chemist Shortage:Philippine universities produce limited graduates in tribology and lubricant engineering, forcing blenders to recruit from regional talent pools in Thailand and Malaysia.
- ASEAN Harmonization Alignment:Anticipated convergence between Philippine National Standards and ASEAN technical regulations requires preemptive reformulation investment before mandatory adoption deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Lubricants Market |
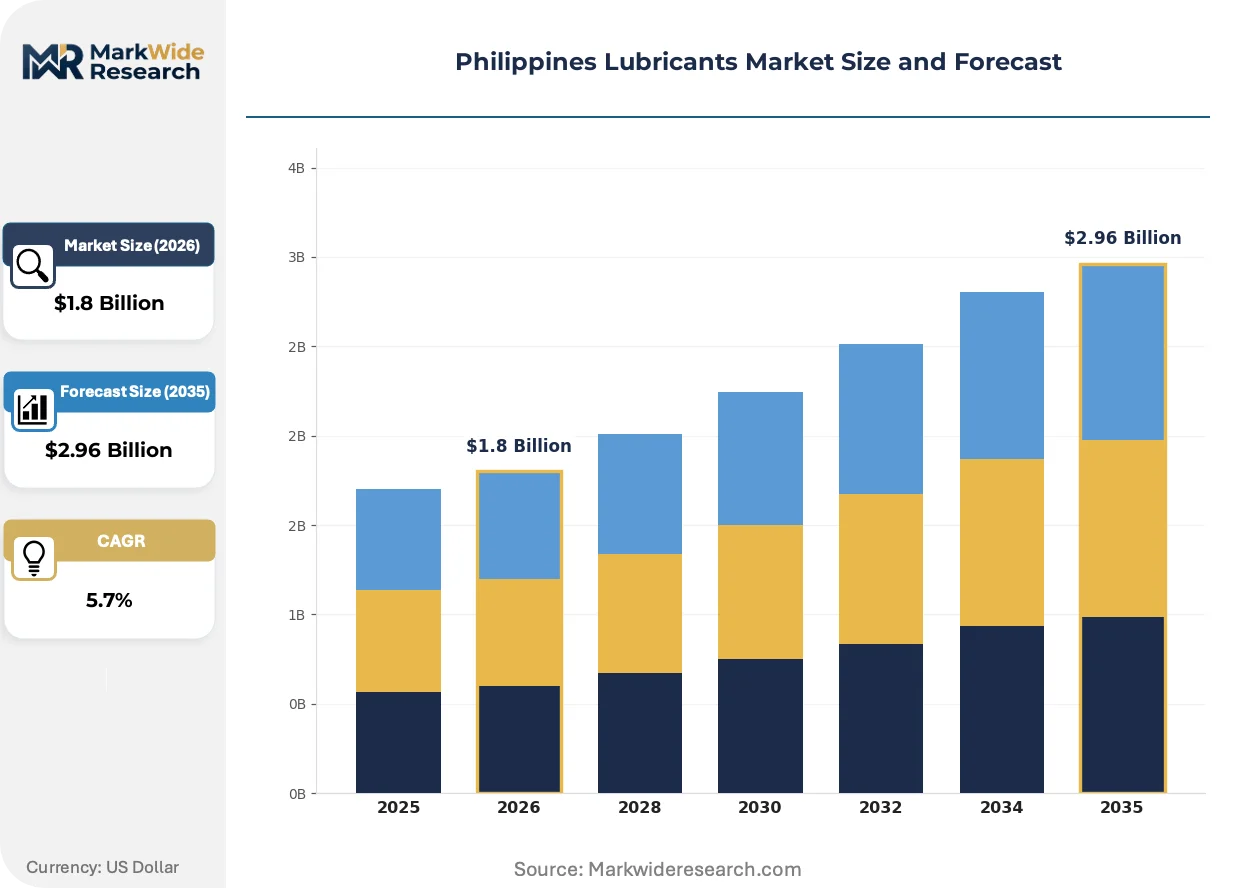
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Hydraulic Fluids, Industrial Lubricants End User: Automotive, Manufacturing, Marine, Agriculture Application: Automotive Use, Industrial Machinery, Metal Processing, Agriculture Equipment Distribution Channel: Retail, Direct Sales, Online, Wholesalers |
| Companies Covered | BP Plc (Castrol), SEAOIL Philippines Inc., Shell plc, PTT Lubricants, Phoenix Petroleum, Petron Corporation, TotalEnergies SE, ExxonMobil Corporation, Chevron Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Lubricants Market Evolving Landscape
Digitalization of fleet management and predictive maintenance systems is reshaping how lubricant specifications are selected and monitored across Philippine commercial vehicle operations.
Condition-based monitoring using IoT sensors and oil analysis algorithms is automating drain interval optimization for logistics operators. Major fleet managers in Metro Manila are piloting real-time viscosity and contamination tracking. This technology is automating the shift from calendar-based to predictive maintenance contracts, compressing the role of traditional service interval recommendations.
The Philippine Department of Energy's alignment with ASEAN fuel and lubricant quality standards is tightening additive disclosure requirements and performance certification protocols. Bureau of Product Standards mandates now require traceable additive content documentation for all imported formulations. Industrial end-users in food processing and pharmaceuticals are responding by demanding third-party verification of incidental food-contact compliance.
Consolidation of procurement authority within large fleet operators is fragmenting the jobber-distributor channel that historically served dispersed commercial vehicle owners. Direct sourcing agreements between national logistics companies and lubricant manufacturers are displacing traditional wholesale purchasing. This concentration is most visible in the CALABARZON manufacturing zone, where integrated supply contracts now cover both fuel and lubricant requirements.
Philippines Lubricants Market Segmentation
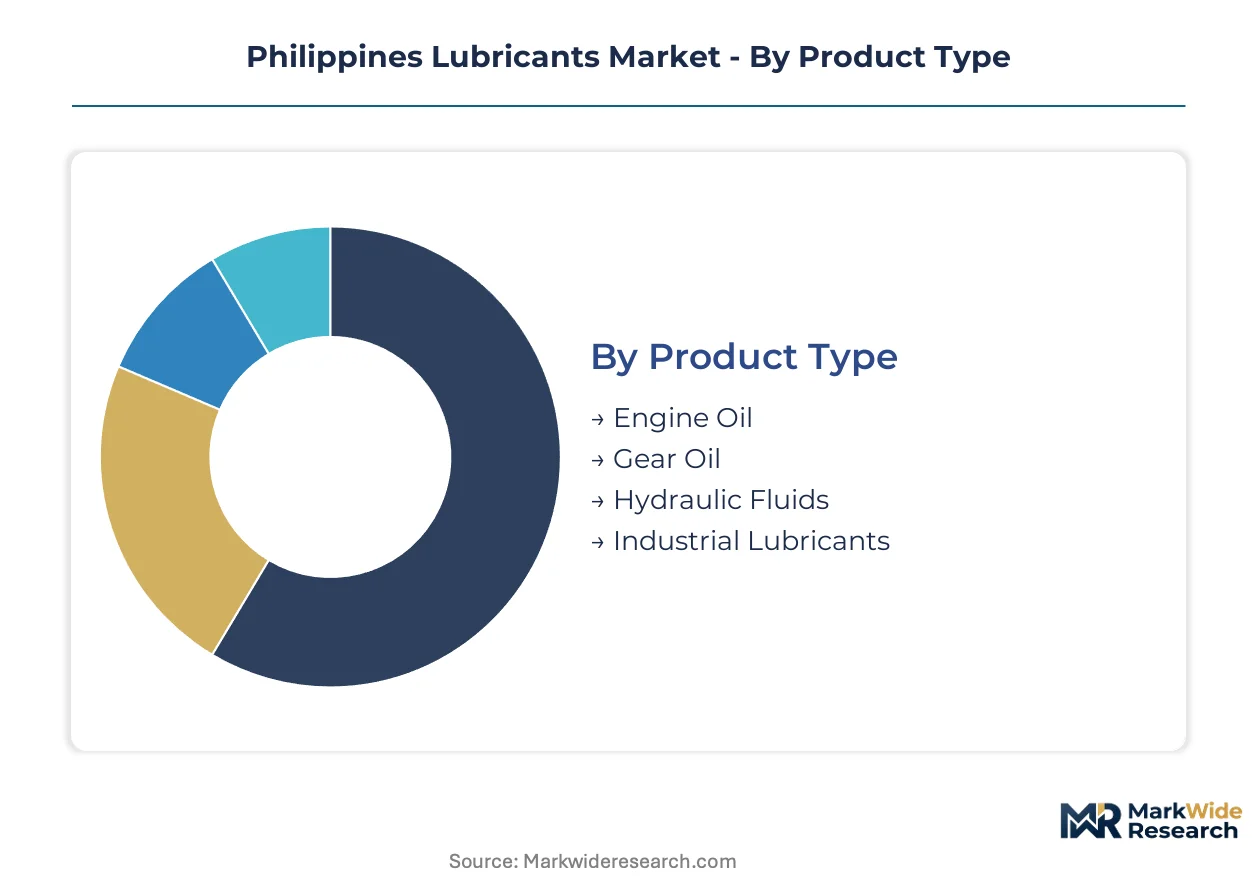
Philippine lubricant procurement patterns diverge sharply between volume-driven fleet operators and specification-sensitive industrial plants. Understanding these buyer archetypes clarifies why formulation standards, pricing tolerance, and channel preferences fracture across segment boundaries.
Product Type:
Buyers in this category separate by drain interval requirements and equipment warranty compliance rather than price sensitivity alone.
- Engine Oil:Blends of Group II/III base stocks with detergent-dispersant additive packages formulated for high-sulfur diesel combustion environments common in Philippine commercial fleets. Demand concentrates in Metro Manila's logistics corridors where extended-drain synthetics are displacing mineral formulations in long-haul trucking.
- Hydraulic Fluids:Anti-wear formulations with ISO VG 32-68 viscosity grades engineered for precision servo-hydraulic systems in electronics assembly automation. CALABARZON manufacturing zones drive specification intensity as semiconductor fabs and food processors upgrade to fire-resistant synthetic ester variants.
- Gear Oil:Extreme-pressure lubricants with sulfur-phosphorus additive chemistry for hypoid and helical gear sets in commercial vehicle transmissions and industrial reducers.
- Industrial Lubricants:Compressor, turbine, and heat transfer fluids serving captive power generation and process cooling in Philippine manufacturing facilities.
Volume sits with Engine Oil; growth tilts toward Hydraulic Fluids.
End User:
Customer scale and technical staffing depth determine whether procurement favors spot purchases or integrated supply contracts.
- Automotive:Fleet operators with centralized maintenance facilities and condition-monitoring capabilities. These buyers consolidate volumes through direct manufacturer agreements, bypassing traditional jobber networks in favor of predictive maintenance partnerships.
- Manufacturing:Electronics assembly and food processing plants with ISO-certified lubricant management programs. CALABARZON facilities specify third-verified incidental food-contact compliance and automated dispensing systems to prevent cross-contamination.
- Marine:Inter-island cargo vessels and fishing fleets operating under Bureau of Product Standards marine diesel engine specifications.
- Agriculture:Provincial rice and sugarcane operations with seasonal equipment utilization patterns and limited cold-chain logistics access.
Procurement scale concentrates with Manufacturing; expansion velocity favors Agriculture as provincial distribution networks mature.
Application:
Operating environment severity and downtime cost exposure differentiate specification requirements more than equipment first cost.
- Automotive Use:Passenger car and light commercial vehicle service fill and aftermarket top-up demand. Urban centers with high congestion indices accelerate soot-loading and fuel dilution stresses on crankcase lubricants.
- Industrial Machinery:Automated production line equipment requiring cleanroom-compatible lubricants with particle count certification. Electronics assembly plants in Cavite and Laguna provinces specify NAS 1638 Class 6 cleanliness for precision bearings and linear motion systems.
- Metal Processing:Cutting, forming, and stamping operations with soluble oil and synthetic coolant requirements for ferrous and non-ferrous workpiece materials.
- Agriculture Equipment:Tractor hydraulics and combine harvester drivetrains exposed to dust ingress and seasonal moisture contamination.
Specification intensity peaks in Industrial Machinery; unit volume accumulates in Automotive Use.
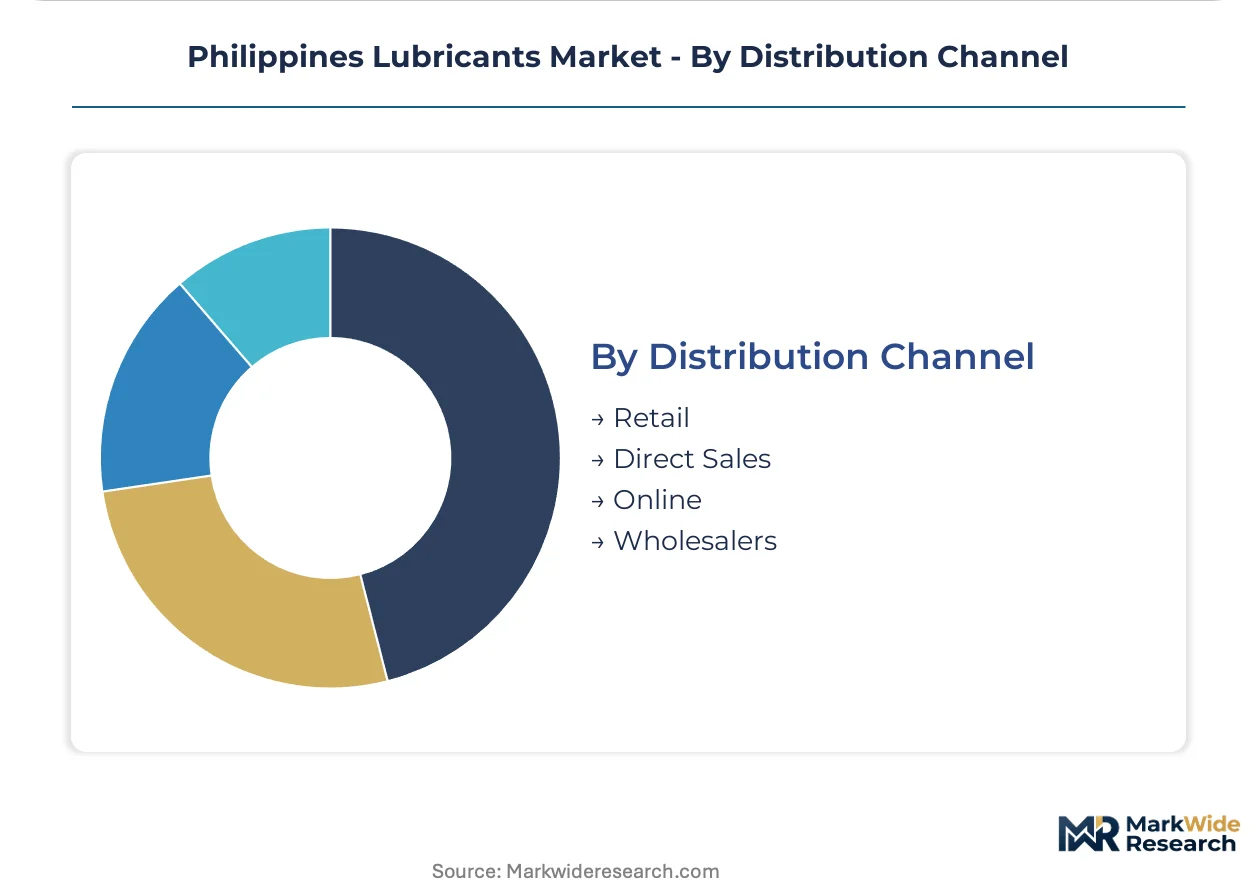
Distribution Channel:
Order size predictability and technical support requirements determine channel selection more than geographic coverage alone.
- Direct Sales:National fleet operators and integrated manufacturing groups with centralized procurement authority and bulk storage infrastructure. These buyers negotiate formulation customization and technical service embedding.
- Wholesalers:Regional distributors serving secondary cities and provincial industrial zones through depot networks and consignment inventory arrangements.
- Retail:Independent repair shops and owner-operator vehicle servicing through automotive parts stores and service station forecourts.
- Online:Direct-to-workshop platforms aggregating demand from dispersed small fleet operators and specialty equipment owners in underserved provincial markets.
Contract value aggregates through Direct Sales; channel development investment flows toward Online platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CALABARZON's special economic zones and PEZA-registered industrial parks concentrate lubricant demand from electronics exporters and food processors. Metro Manila's logistics corridors generate fleet-scale procurement volumes. Provincial distribution networks in Visayas and Mindanao remain underdeveloped relative to Luzon industrial density.
Luzon
Metro Manila's port-centric logistics operators consolidate synthetic lubricant procurement through direct manufacturer agreements. The Department of Energy's fuel quality regulations mandate tighter base oil specifications for all commercial transport registered in National Capital Region terminals. Cavite and Laguna provinces host semiconductor fabs specifying NAS 1638 Class 6 cleanliness for precision hydraulic systems.
CALABARZON
Electronics assembly and food processing automation in Batangas and Quezon provinces accelerates demand for fire-resistant synthetic ester hydraulic fluids. PEZA-registered economic zones require lubricant suppliers to maintain third-verified incidental food-contact compliance documentation. Toyota Motor Philippines' Santa Rosa assembly plant anchors automotive-grade lubricant specification standards for regional suppliers.
Central Visayas
Cebu City's inter-island shipping and fishing fleet operations drive marine diesel engine lubricant consumption under Bureau of Product Standards certification. The Philippine Economic Zone Authority's Mactan export processing zone attracts precision manufacturing with cleanroom-compatible lubricant requirements. Provincial agricultural equipment operators in Bohol and Negros Oriental rely on seasonal mineral oil purchases through fragmented retail channels.
Western Visayas
Iloilo City's emerging cold-chain logistics infrastructure creates distribution opportunities for synthetic lubricants serving fishing fleet modernization. The Department of Agriculture's mechanization programs in Panay Island accelerate tractor hydraulic fluid demand. Bacolod City's sugar milling operations specify industrial gear oils for seasonal crushing equipment with extended drain intervals.
Mindanao
Davao Region's banana and pineapple export processing plants automate packaging lines requiring food-grade synthetic lubricants with H1 certification. The Department of Energy's B20 biodiesel mandate extends to Mindanao commercial fleets, necessitating reformulated engine oils with fuel dilution resistance. Cagayan de Oro's port expansion supports inter-island cargo vessel servicing with marine lubricant bunkering infrastructure.
Philippines Lubricants Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated refiners dominating fleet procurement while independent blenders capture provincial retail fragmentation. The market structures around three tiers: multinational majors with captive base oil supply, national oil companies leveraging refinery integration, and regional distributors specializing in single-product categories. Strategic moves concentrate on backward integration into base oil refining and e-commerce channel development for workshop-direct sales.
Among multinational lubricant majors, Shell plc and BP Plc (Castrol) occupy positions defined by manufacturing scale and depot network density. Petron Corporation anchors the national oil company tier through refinery-linked supply security. SEAOIL Philippines Inc. represents the distributor-expansion archetype with provincial retail station penetration.
| Leading Market Players |
|---|
| BP Plc (Castrol) |
| SEAOIL Philippines Inc. |
| Shell plc |
| PTT Lubricants |
| Phoenix Petroleum |
| Petron Corporation |
| TotalEnergies SE |
| ExxonMobil Corporation |
| Chevron Corporation |
| Others |
Value Network & Pricing Analysis
Group II and III base oil import costs from Singapore and South Korea cascade through Philippine lubricant pricing tiers, with freight rate volatility and peso-dollar exchange movements compressing margins for independent blenders while integrated refiners absorb shocks through captive hydrocracking capacity.
Pricing Analysis
Short lead-time premiums for just-in-time hydraulic fluid deliveries to CALABARZON semiconductor fabs command 15-20 percent markups over contract volumes, while spot mineral oil inventories in provincial depots trade at discounts to clear seasonal overhang. Three-tier pricing structure across premium synthetic, standard hydrocracked, and economy solvent-refined levels stratifies by drain interval certification and OEM approval status. Pricing pressure stems from regional Group I capacity rationalization forcing accelerated reformulation investments. Fleet operators with centralized procurement exhibit lowest price sensitivity; independent owner-operators in agricultural provinces exhibit highest.
Supply Chain Analysis
Domestic-content mandates under the Philippine Department of Energy's fuel quality regulations are reshaping sourcing patterns, requiring local additive blending and BIS-equivalent laboratory verification for all imported formulations. Base oil supply concentrates in Singapore, South Korea, and Thailand, with hydrocracked Group II/III stocks displacing solvent-refined Group I for automotive and industrial applications. Key dependencies include polyalphaolefin synthetic base stocks, detergent-dispersant additive packages, and viscosity index improvers. Single-source vulnerability runs through Singapore's Jurong Island refining complex for specialized marine lubricant components. Distribution runs through integrated refinery-depot networks for fleet direct sales, fragmented jobber channels for provincial retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippines lubricants market is a vertical-integration race where control over hydrocracking capacity and base oil supply security separates margin-defensible majors from cost-pressured independents. Players are pursuing upstream leverage through refinery investments and downstream lock-in via predictive maintenance partnerships.
For Market Incumbents: Deploy predictive maintenance service embedding to lock in fleet operator procurement decisions before direct-to-workshop platforms erode jobber channel loyalty. Shell plc and Petron Corporation should accelerate Group III base oil capacity expansion at Tabangao and Bataan facilities to reduce Singapore import exposure. SEAOIL Philippines Inc. must defend provincial retail station density against e-commerce platform encroachment through cold-chain logistics partnerships for agricultural equipment servicing. For New Entrants and Emerging Players: Launch via direct-to-workshop e-commerce platforms targeting independent repair shops in secondary Visayas and Mindanao cities currently underserved by integrated distributor networks. White-space opportunities concentrate in food-grade synthetic lubricants for Davao Region banana export processors requiring H1 certification, and in marine diesel engine oils for inter-island shipping fleets outside Cebu City's established bunkering infrastructure. Prioritize Bureau of Product Standards pre-certification to compress market entry timelines. For Investors and Strategic Acquirers: Petron Corporation's backward integration announcement into base oil refining is the leading indicator that integrated supply security will command valuation premiums over pure blending operations. Target acquisition archetypes are regional distributors with established PEZA-registered economic zone relationships and proprietary additive formulation capabilities. Watch for Department of Energy enforcement actions on B20 biodiesel compatibility testing as the signal for reformulation investment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Refining | Petron Corporation's captive hydrocracking capacity insulates margins from Singapore freight volatility. |
| E-Commerce Platform Development | Direct-to-workshop channels bypass fragmented jobber networks in provincial secondary cities. |
| Predictive Maintenance Partnerships | IoT-enabled drain interval optimization locks fleet operators into long-term supply contracts. |
| Food-Grade Certification Investment | H1 lubricant qualification opens Davao Region export processing plant procurement. |
| Provincial Cold-Chain Logistics Expansion | SEAOIL Philippines Inc. extends station network reach to agricultural equipment seasonal demand. |
Research Methodology
Independent corroboration across lubricant blenders, fleet operator maintenance directors, and PEZA-registered plant engineers underwrites the qualitative findings in this study. Primary interviews with procurement leads at electronics assembly facilities, technical R&D directors at integrated refiners, and channel sales heads at regional distributors were validated against secondary sources including Bureau of Product Standards certification records, Department of Energy fuel quality regulatory filings, and Philippine customs import data for base oil trade flows. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers produces convergent volume estimates.
Rate-of-change decomposition separates volume growth from mix-shift effects across the analysis window, with CAGRs derived from segment-level elasticity modeling against industrial production indices and commercial vehicle fleet expansion rates. Segmentation dimensions include product type viscosity grade, end-user certification requirements, application cleanliness specifications, and distribution channel technical service intensity. Forecast inputs incorporate ASEAN harmonization protocol alignment timelines and B20 biodiesel mandate implementation schedules.
Regulatory enforcement variance, base oil freight rate spikes, and peso depreciation acceleration are the dominant revision risks to the projection envelope. Forecasts reflect documented assumptions on fleet modernization velocity and industrial automation penetration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
United Kingdom Commercial Vehicles Lubricants Market
Lubricants
China Automotive Engine Oils Market
Lubricants
Industrial Lubricants Market
Lubricants
Vietnam Automotive Engine Oils Market
Lubricants
Polyurea Greases Market
Lubricants
Global Agricultural Lubricants Market
Lubricants
Biolubricants Market
Lubricants
North America Automotive Lubricants Market
Lubricants
Aluminum Extrusion Lubricants Market
Lubricants
Global Lubrication Systems Market
Lubricants
China Refrigeration Lubricants Market
Lubricants
Aviation Lubricants Market
Lubricants
Indonesia Lubricants Market
Lubricants
Jordan Lubricants Market
Lubricants
Yarn Lubricant Market
Lubricants
Saudi Arabia Lubricants Market