
 North America DNA Sequencing Products Market | 2026-2036
North America DNA Sequencing Products Market Size, Share, and Industry Trends Forecast 2026-2036
North America DNA Sequencing Products Market Intelligence
Subscription-based bioinformatics software is rebalancing how sequencing platforms generate recurring revenue alongside instrument sales. Illumina, Inc. leverages its cloud-based analytics ecosystem to sustain high-margin recurring relationships with clinical laboratories. Pacific Biosciences anchors its competitive position through long-read accuracy advantages in complex genomic regions. Thermo Fisher Scientific Inc. dominates the reagent supply chain through vertically integrated manufacturing of sample preparation chemistries.
DNA sequencing products encompass instruments, consumable reagents, analytical software, and ancillary accessories that determine the order of nucleotides within DNA molecules, typically achieving read lengths from 50 base pairs to over 25,000 base pairs depending on platform chemistry. These products serve primary commercial purposes in clinical variant detection, pharmaceutical target validation, and population-scale genomic research. Next-generation sequencing instruments command the largest installed base across North American hospitals, while third-generation sequencing platforms represent the fastest-expanding technology category driven by epigenetic and structural variant applications. Reagents capture the deepest margin pools due to per-run consumption cycles and proprietary cartridge lock-in architectures.
FDA oversight of clinical sequencing devices, CMS reimbursement frameworks for molecular diagnostic procedures, and HIPAA data governance requirements collectively shape product development priorities and go-to-market pathways for vendors operating across the United States and Canada. The Canadian regulatory framework through Health Canada and provincial health technology assessment bodies adds a secondary compliance layer that influences pricing and adoption timelines in that market. Stakeholders must monitor evolving FDA guidance on artificial intelligence-integrated variant interpretation tools, as these standards will determine which software modules achieve clinical-grade certification and corresponding reimbursement eligibility.
Market Dynamics
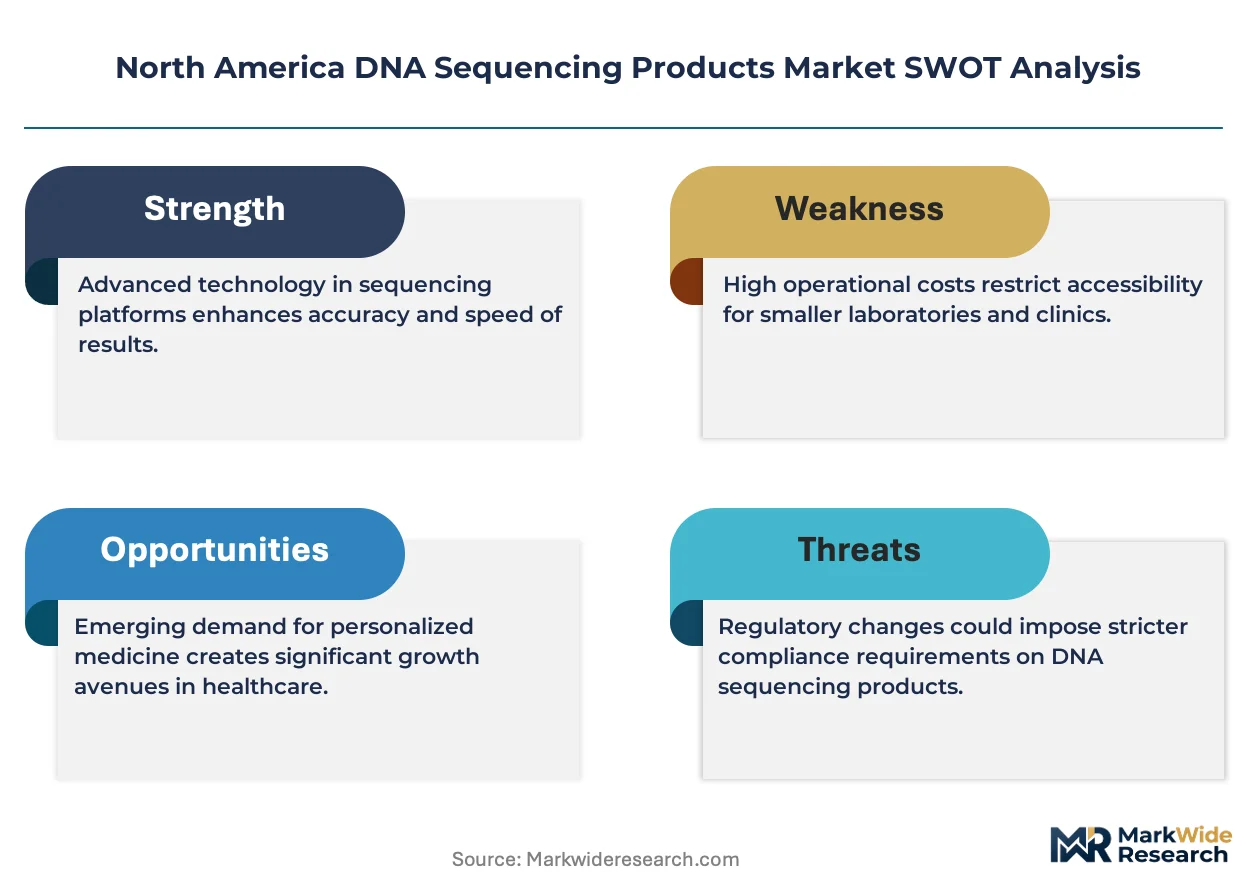
Sequencing platform vendors face intensifying pressure to convert instrument placements into recurring consumable revenue streams as hardware margins compress and capital expenditure cycles lengthen across hospital systems.
Growth Catalysts
- FDA Tumor Profiling Guidance:The agency's evolving framework for next-generation sequencing-based oncology diagnostics accelerates procurement timelines for clinical laboratories seeking reimbursable test menus.
- Epigenetic Research Expansion:Academic medical centers in the Boston-Cambridge corridor are deploying third-generation platforms for methylation analysis and structural variant detection in rare disease cohorts.
- Cloud Analytics Subscription Models:Bioinformatics software vendors are capturing recurring revenue through per-sample data processing contracts that extend customer lifetime value beyond initial instrument sales.
Market Restraints
- Reagent Supply Concentration:Proprietary cartridge architectures lock clinical laboratories into single-vendor consumable ecosystems, limiting price negotiation leverage and creating vulnerability to supply disruptions.
- Capital Intensity Barriers:High-throughput sequencing instruments require facility infrastructure investments including controlled-environment sequencing rooms and specialized electrical systems that strain hospital capital budgets.
- Interpretation Bottlenecks:Shortage of board-certified molecular pathologists capable of variant classification creates throughput ceilings that underutilize installed instrument capacity.
Strategic Opportunities
- Canadian Provincial Expansion:Health Canada regulatory harmonization with FDA standards creates pathway for US-validated platforms to enter Ontario and Quebec health technology assessment frameworks with abbreviated review timelines.
- Artificial Intelligence Integration:Machine learning variant interpretation tools eligible for FDA breakthrough device designation promise to automate reporting workflows and reduce pathologist review burden.
- Direct-to-Consumer Channel Development:Partnerships between sequencing laboratories and telehealth platforms enable at-home sample collection models that bypass traditional hospital-based ordering workflows.
Industry Challenges
- Bioinformatics Talent Scarcity:Pipeline of computational biologists trained in clinical-grade pipeline development lags behind instrument deployment rates, forcing vendors to internalize training costs.
- HIPAA-Compliant Data Architecture:Cloud-based analytics platforms must implement patient data encryption and access logging that satisfies both federal privacy requirements and institutional review board protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America DNA Sequencing Products Market |
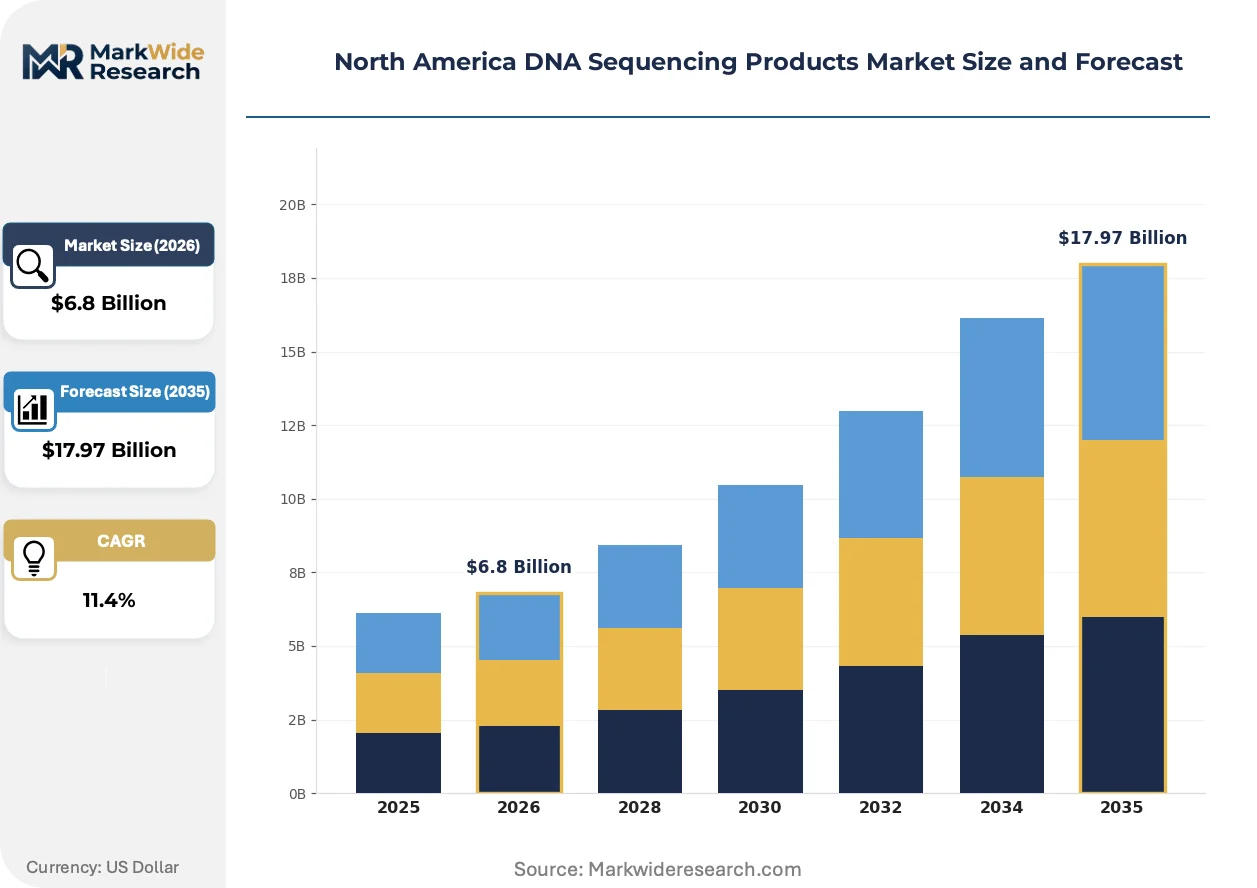
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instruments, Reagents, Software, Accessories Technology: Sanger Sequencing, Next-Generation Sequencing, Third-Generation Sequencing, Whole Genome Sequencing End User: Research Laboratories, Hospitals, Academic Institutions, Biotechnology Companies Application: Clinical Diagnostics, Drug Discovery, Genomics Research, Personalized Medicine |
| Companies Covered | F. Hoffmann-La Roche Ltd, Pacific Biosciences, Illumina, Inc., Bio-Rad Laboratories, Inc., Danaher, Thermo Fisher Scientific Inc., QIAGEN, Revvity, Agilent Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America DNA Sequencing Products Market Strategic Shifts & Innovations
Platform chemistry advances and regulatory digitization are compressing the interval between sample acquisition and clinical report generation while fragmenting traditional vendor-customer relationships.
Single-molecule real-time sequencing is electrifying structural variant detection workflows in constitutional disease research. Pediatric genetics departments at academic medical centers are adopting these systems for de novo mutation analysis. The technology is electrifying competitive positioning for vendors targeting undiagnosed rare disease programs where short-read platforms fail to resolve complex genomic rearrangements.
CMS molecular diagnostic reimbursement frameworks are restructuring laboratory economics around test performance metrics rather than technology platforms. The agency's coverage determinations for multi-gene panel tests create incentive alignment between sequencing depth and clinical utility documentation. Oncology practices in community hospital settings are responding by consolidating send-out contracts with reference laboratories capable of demonstrating outcome-linked validation data.
Consolidated service contracts are displacing discrete instrument and reagent purchasing across integrated delivery networks. Health system supply chain executives are negotiating multi-year partnerships that bundle sequencing capacity with bioinformatics support and variant interpretation services. This restructuring is most visible in the southeastern United States where hospital consolidation has created regional laboratory networks with standardized platform commitments.
North America DNA Sequencing Products Market Segmentation
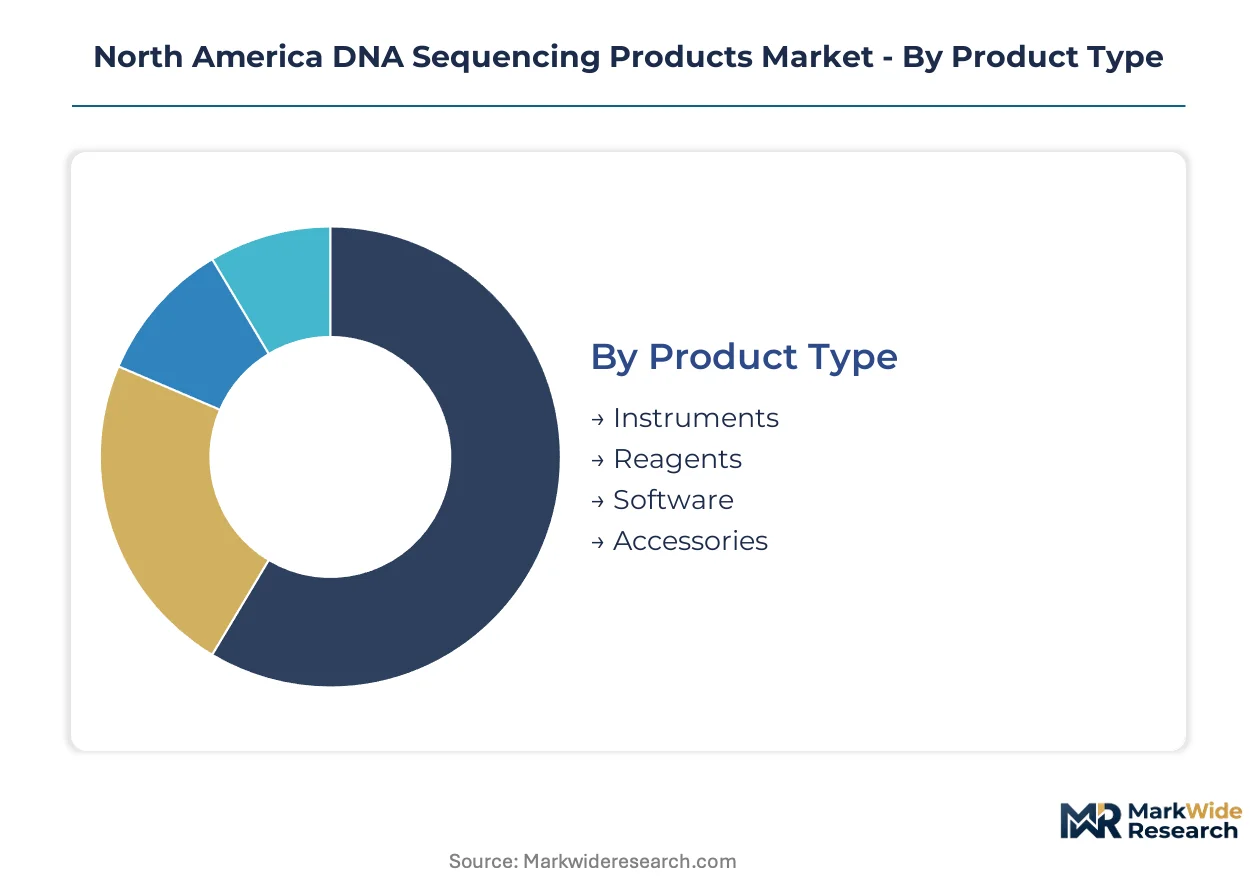
Segmentation of the North America DNA Sequencing Products Market reveals how purchasing decisions bifurcate between standalone instrument acquisitions and integrated platform ecosystems. Vendors structure pricing and service contracts differently across these boundaries, with embedded consumable streams commanding strategic priority.
Product Type:
Instruments function as standalone capital purchases requiring dedicated facility infrastructure, while reagents and software embed into recurring operational workflows with vendor lock-in architectures.
- Instruments:Sequencing platforms range from benchtop systems for targeted panels to high-throughput production-scale units. Demand concentrates in academic medical centers across the Boston-Cambridge corridor, where expansion of clinical laboratory capacity drives procurement cycles. Capital intensity and controlled-environment room requirements create elongated sales cycles.
- Reagents:Consumable chemistries including library preparation kits, sequencing cartridges, and quality control materials capture per-run revenue. Clinical laboratories in the United States face proprietary cartridge architectures that constrain vendor switching. FDA guidance on tumor profiling accelerates reagent validation timelines.
- Software:Bioinformatics platforms for base calling, alignment, and variant interpretation deploy through cloud-based subscription models. HIPAA-compliant data architecture requirements shape development priorities for vendors serving hospital systems.
- Accessories:Ancillary equipment including sample preparation workstations, thermal cyclers, and storage systems complete integrated workflows. Research laboratories prioritize modular accessories compatible with multi-platform environments.
Reagents lead volumes today; software is gaining share fastest.
Technology:
Technology segmentation tracks the transition from established short-read dominance toward emerging long-read capabilities, with cost per base and accuracy trade-offs determining adoption patterns.
- Sanger Sequencing:First-generation capillary electrophoresis methods deliver high accuracy for targeted validation of variants detected by broader screening approaches. Research laboratories retain Sanger capacity for confirmatory sequencing. Declining instrument placements reflect substitution by next-generation methods.
- Next-Generation Sequencing:Short-read massively parallel platforms command the largest installed base across North American hospitals. Illumina systems dominate clinical diagnostics laboratories seeking reimbursable oncology test menus. CMS coverage determinations for multi-gene panels reinforce platform standardization.
- Third-Generation Sequencing:Single-molecule real-time and nanopore technologies enable native DNA detection without amplification. Academic medical centers deploy these systems for methylation analysis and structural variant detection in rare disease cohorts. Native epigenetic detection expands addressable applications.
- Whole Genome Sequencing:Comprehensive genomic analysis at scale requires substantial computational infrastructure and interpretation pipelines. Pediatric genetics departments adopt whole genome approaches for undiagnosed disease programs where exome sequencing yields negative results.
Next-Generation Sequencing anchors current installed base; Third-Generation Sequencing shows steepest expansion trajectory.
End User:
End user segmentation reflects divergent procurement authority, with hospital systems consolidating purchasing through supply chain executives while biotechnology companies retain decentralized R&D equipment decisions.
- Research Laboratories:Academic and government facilities prioritize instrument flexibility and multi-platform compatibility. Canadian provincial research institutes navigate Health Canada regulatory frameworks for equipment procurement. Funding cycles from NIH and CIHR drive capital expenditure timing.
- Hospitals:Integrated delivery networks negotiate consolidated service contracts bundling instruments, reagents, and bioinformatics support. Southeastern United States health systems demonstrate standardized platform commitments across regional laboratory networks. FDA oversight of clinical sequencing devices shapes vendor qualification requirements.
- Academic Institutions:University core facilities serve diverse investigator portfolios requiring broad technology access. Core directors balance throughput demands against per-sample cost optimization. Training pipelines for computational biologists lag instrument deployment rates.
- Biotechnology Companies:Venture-funded firms in the Boston-Cambridge corridor co-locate sequencing infrastructure with contract research organizations. Pharmaceutical target validation programs demand rapid turnaround on variant confirmation studies.
Hospitals represent the largest revenue pool; biotechnology companies show most volatile growth patterns tied to funding cycles.
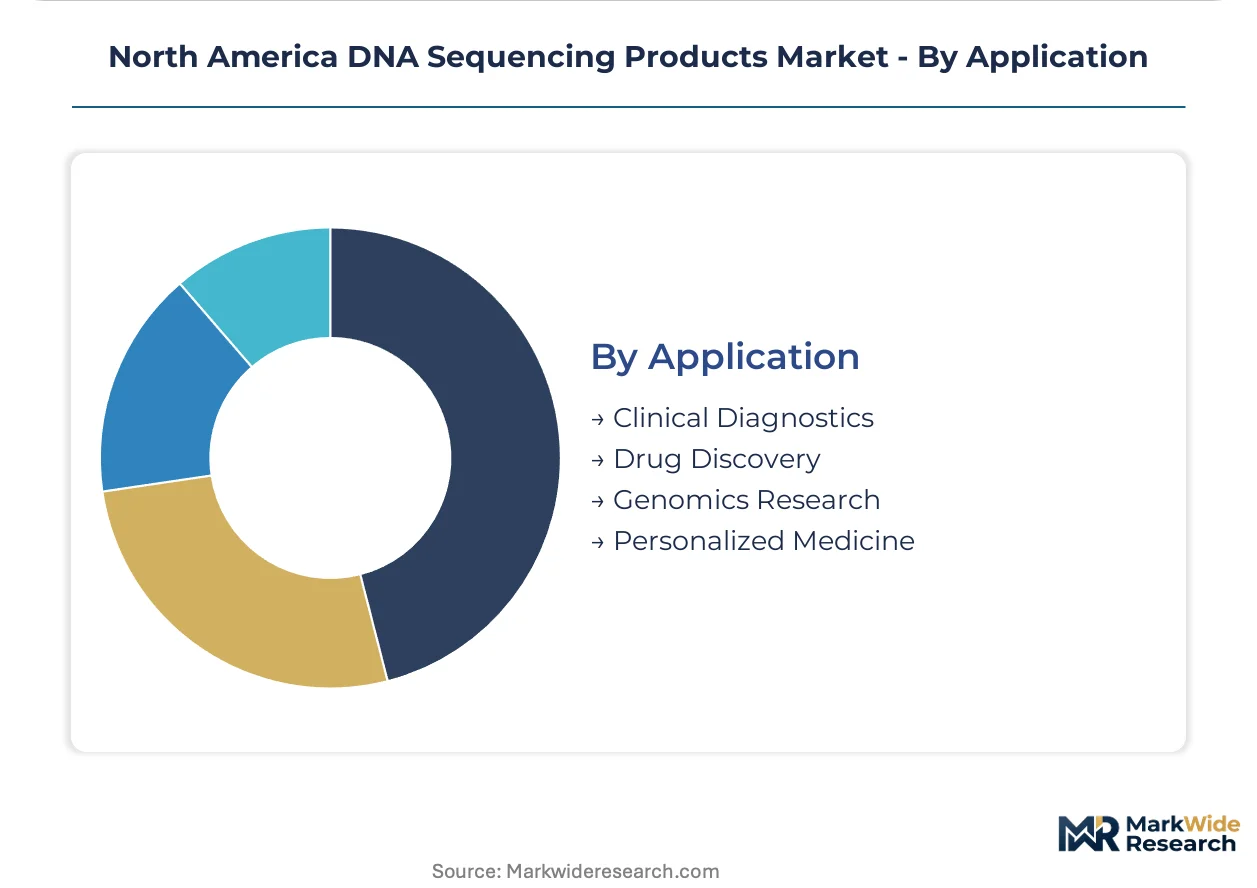
Application:
Application segmentation distinguishes between regulated clinical environments requiring FDA-compliant workflows and research settings with greater protocol flexibility.
- Clinical Diagnostics:Oncology profiling and rare disease testing operate under FDA guidance for next-generation sequencing-based assays. Molecular pathologist shortages create interpretation bottlenecks constraining test volume expansion. Reimbursement eligibility hinges on outcome-linked validation documentation.
- Drug Discovery:Pharmaceutical companies deploy sequencing for target identification, biomarker discovery, and patient stratification. Contract research organizations in the United States and Canada build sequencing capacity to capture outsourced genomics workflows.
- Genomics Research:Population-scale studies and functional genomics programs drive demand for high-throughput production platforms. NIH-funded initiatives sustain instrument utilization rates at major sequencing centers.
- Personalized Medicine:Pharmacogenomic testing and preventive screening applications expand addressable market beyond disease diagnosis. Direct-to-consumer channel development through telehealth partnerships enables at-home sample collection models.
Clinical Diagnostics generates premium pricing; Personalized Medicine demonstrates fastest adoption acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics in DNA sequencing favor jurisdictions with harmonized FDA-Health Canada pathways, reducing validation costs for cross-border platform deployments. United States laboratories absorb premium instrument pricing in exchange for streamlined reimbursement eligibility. Canadian provincial health technology assessment frameworks create secondary compliance layers that moderate adoption velocity.
United States
FDA guidance on next-generation sequencing-based tumor profiling accelerates procurement cycles for clinical diagnostics laboratories. CMS reimbursement frameworks for multi-gene panel tests reshape laboratory economics around outcome-linked validation. The Boston-Cambridge corridor concentrates sequencing infrastructure where academic medical centers and contract research organizations co-locate.
Canada
Health Canada regulatory harmonization with FDA standards creates abbreviated review pathways for United States-validated platforms. Provincial health technology assessment bodies in Ontario and Quebec influence pricing negotiations and adoption timelines. Canadian research institutes navigate CIHR funding cycles that drive capital expenditure timing for sequencing equipment.
California
Venture-funded biotechnology firms in the San Francisco Bay Area deploy sequencing infrastructure for pharmaceutical target validation programs. State-level privacy regulations supplement HIPAA requirements for cloud-based genomic data processing. Southern California hospital networks consolidate laboratory purchasing through integrated delivery network supply chain executives.
Texas
Medical center complexes in Houston expand clinical sequencing capacity for oncology and rare disease profiling under evolving FDA oversight frameworks. State-funded research initiatives sustain instrument utilization at academic institutions. Dallas-Fort Worth health systems demonstrate standardized platform commitments across regional laboratory networks.
Illinois
Chicago-area academic medical centers balance throughput demands against per-sample cost optimization in core facility operations. Midwest hospital consolidation creates regional laboratory networks with multi-year bundled service contracts. State bioscience initiatives support computational biology training pipelines that lag instrument deployment rates.
North America DNA Sequencing Products Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with instrument vendors capturing upfront capital while reagent suppliers lock in recurring consumable streams. The vendor base concentrates around vertically integrated platform ecosystems and specialized component suppliers. Two strategic archetypes dominate: integrated platform vendors bundling hardware with proprietary bioinformatics, and reagent specialists controlling niche chemistries. Competitive moves center on multi-year consolidated service contracts with integrated delivery networks and cloud analytics subscription models extending customer lifetime value.
Among United States-based platform vendors, Illumina, Inc. and Pacific Biosciences occupy positions representing contrasting technology philosophies—short-read scale versus long-read accuracy. Thermo Fisher Scientific Inc. anchors the reagent supply tier through captive manufacturing of sample preparation chemistries. These three exemplify how competitive positioning fragments between platform-centric and consumable-centric revenue architectures.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Pacific Biosciences |
| Illumina, Inc. |
| Bio-Rad Laboratories, Inc. |
| Danaher |
| Thermo Fisher Scientific Inc. |
| QIAGEN |
| Revvity |
| Agilent Technologies Inc. |
| Others |
Cost & Logistics Intelligence
Captive manufacturing of sample preparation chemistries anchors both supply security and pricing power for dominant reagent vendors serving North American clinical laboratories. This backward integration into proprietary cartridge architectures locks buyers into single-vendor consumable ecosystems while insulating suppliers from spot-market volatility in raw biochemical inputs.
Pricing Analysis
Distributor margins on sequencing instruments compress as direct procurement channels between platform vendors and integrated delivery networks expand. Three-tier pricing structure across premium, standard, and economy levels stratifies by throughput capacity and bioinformatics bundling, with FDA breakthrough device designation commanding brand premiums. Cost compression in the mid-tier benchtop segment intensifies as Chinese manufacturers enter the Canadian market through Health Canada abbreviated pathways. Community hospital laboratories exhibit highest price sensitivity due to capital budget constraints, while academic medical centers prioritize performance specifications over per-run economics.
Supply Chain Analysis
Dual-sourcing requirements mandated by major United States health systems for critical reagent chemistries are reshaping supplier qualification protocols across the industry. Manufacturing concentration centers on the United States, Germany, and Japan for precision optical components and flow cell substrates. Production draws from specialized polymer suppliers in Belgium and Singapore for sequencing cartridge housings. Single-source vulnerability in semiconductor-based detector arrays creates exposure to foundry capacity allocation decisions. Distribution runs through regional laboratory supply distributors with cold-chain logistics capabilities, supplemented by direct-to-laboratory cartridge replenishment programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America DNA Sequencing Products Market represents a late-cycle quality story as clinical laboratories prioritize FDA-validated platforms with demonstrated outcome-linked reimbursement over lower-cost alternatives. Demand is shifting toward premium specifications including AI-integrated variant interpretation modules eligible for breakthrough device designation.
For Market Incumbents: Deploy cloud analytics subscription models to extend customer lifetime value beyond initial instrument placements. Consolidate reagent supply positions through captive manufacturing expansion in the Boston-Cambridge corridor to defend against emerging long-read platform entrants. Counter Pacific Biosciences' structural variant accuracy advantages by accelerating short-read methylation chemistry development. Certification investment in FDA tumor profiling guidance compliance remains essential for maintaining hospital system contract renewals.
For New Entrants and Emerging Players: FDA guidance on artificial intelligence-integrated variant interpretation tools in the United States opens a window for software-native entrants to achieve clinical-grade certification without legacy instrument overhead. Target the Canadian provincial health technology assessment framework in Ontario and Quebec, where regulatory harmonization with FDA standards enables abbreviated platform validation timelines. Penetrate the direct-to-consumer channel through telehealth partnerships enabling at-home sample collection models that bypass hospital-based procurement committees.
For Investors and Strategic Acquirers: Roll-up economics work for bioinformatics software specialists because hospital system consolidation is fragmenting instrument vendor relationships while centralizing data interpretation purchasing. Long-term viability in this market hinges on recurring revenue architectures rather than capital equipment cyclicality. Acquisition targets should demonstrate HIPAA-compliant cloud infrastructure with per-sample processing contracts. Watch Health Canada regulatory harmonization progress as the inflection indicator for cross-border platform scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Analytics Subscription Launch | Illumina's DRAGEN platform demonstrates how per-sample processing contracts extend customer lifetime value beyond hardware sales. |
| Long-Read Chemistry Advancement | Pacific Biosciences' HiFi sequencing addresses structural variant detection gaps that short-read platforms cannot resolve in rare disease cohorts. |
| Canadian Regulatory Harmonization | Health Canada alignment with FDA tumor profiling guidance creates abbreviated pathways for United States-validated platform entry. |
| AI Variant Interpretation Module | FDA breakthrough device designation for machine learning tools promises to automate reporting workflows and reduce pathologist review burden. |
| Direct-to-Consumer Channel Partnership | Telehealth platform integrations enable at-home sample collection models that bypass traditional hospital-based ordering workflows. |
Research Approach
Coverage spans the United States and Canada, with primary inputs from each country's clinical laboratory and research institute ecosystem. The approach combines structured interviews with laboratory directors, hospital supply chain executives, molecular pathologists, and bioinformatics pipeline developers alongside secondary validation from FDA guidance documents, Health Canada regulatory filings, CMS coverage determinations, and hospital procurement databases. Bottom-up instrument placement tracking and top-down reagent consumption modeling provide triangulation across independent estimation frameworks.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. The analytical framework models segmentation dimensions including technology generation, end-user procurement authority, application regulatory status, and regional reimbursement pathway. CAGRs derive from instrument replacement cycle analysis, consumable run-rate extrapolation, and software subscription renewal patterns. Industry-specific forecast inputs include CMS molecular diagnostic reimbursement trajectory and CIHR funding cycle timing for Canadian research institutes.
Revisions become necessary when FDA artificial intelligence guidance finalization, Health Canada provincial adoption timelines, or molecular pathologist workforce expansion rates materialize differently than modeled assumptions. Deviation in CMS multi-gene panel coverage determination criteria would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Apolipoprotein Test Market
Genomics
Europe Hereditary Cancer Testing Market
Genomics
Non Invasive Prenatal Testing (NIPT) Market
Genomics
Genomic Biomarkers Market
Genomics
Dna Polymerase Market
Genomics
Microbiome Sequencing Market
Genomics
Transcriptomics Technologies Market
Genomics
Next-Generation Sequencing Library Preparation Market
Genomics
Global Mirna Sequencing and Assay Market
Genomics
Asia Pacific Pharmacogenetics Testing in Psychiatry/Depression Market
Genomics
Global Whole Genome Sequencing (WGS) Market
Genomics
Mendelian Disorders Testing Market
Genomics
Genomics Personalized Health Market
Genomics
Global Clinical Oncology Next Generation Sequencing Market
Genomics
Glycan Sequencing Market
Genomics
Global Single Nucleotide Polymorphism (SNP) Genotyping Market