
 DNA Gene Chip Market | 2026-2036
DNA Gene Chip Market Size, Share, and Industry Trends Forecast 2026-2036
DNA Gene Chip Market Analysis
Oncology diagnostics is broadening its share of DNA gene chip consumption as pharmaceutical companies integrate pharmacogenomic screening into clinical trial protocols. Illumina, Inc. dominates high-throughput sequencing arrays through in-house production of patterned flow cells. Thermo Fisher Scientific Inc. leverages its CLIA-certified laboratory network to anchor clinical service revenue alongside instrument sales. Agilent Technologies specializes in comparative genomic hybridization platforms for cancer cytogenetics laboratories.
DNA gene chips are solid substrates—typically glass or silicon—spotted with thousands of oligonucleotide probes that hybridize with fluorescently labeled nucleic acid samples to measure gene expression or genotype variation, with probe densities now exceeding six million features per square centimeter. Microarray technology leads in installed base across academic core facilities, though sequencing-based gene chips capture expanding share in translational research settings. Personalized medicine applications concentrate margin pools as payers gradually reimburse pharmacogenomic testing in cardiology and psychiatry.
The FDA regulates DNA gene chips as in vitro diagnostics under 21 CFR Part 820 quality system requirements, while the Centers for Medicare & Medicaid Services determines reimbursement codes that shape hospital purchasing cycles. The National Institutes of Health funding allocation for genomic medicine indirectly steers research institution procurement volumes through R01 and U01 mechanism awards. Stakeholders must monitor CMS coverage determination timelines for multi-gene panel tests, as these decisions cascade through hospital capital budgeting processes and reagent contract negotiations.
Market Dynamics
Pharmaceutical companies are integrating pharmacogenomic screening into clinical trial protocols, compressing development timelines and expanding the addressable base for companion diagnostic arrays. This demand pull from drug development pipelines is restructuring procurement volumes across research institutions and contract research organizations.
Growth Catalysts
- Companion Diagnostics Mandates:The FDA's evolving in vitro diagnostics guidance is accelerating microarray-based test submissions for oncology therapeutics. Drug sponsors now require biomarker stratification before Phase II enrollment.
- NIH Funding Allocation:Genomic medicine awards through R01 and U01 mechanisms steer capital equipment purchases at academic medical centers. Boston and San Francisco biotech clusters channel these funds into high-density array platforms.
- Patterned Flow Cell Production:In-house manufacturing of silicon substrates with six-million-probe densities is reducing per-test reagent costs. Semiconductor fabrication techniques are transferring into life sciences instrumentation.
Market Restraints
- Silicon Wafer Supply Concentration:Taiwan and South Korea dominate 300mm wafer production for microarray substrates. Geopolitical friction threatens substrate availability for North American instrument manufacturers.
- CMS Reimbursement Uncertainty:The Centers for Medicare & Medicaid Services has not established consistent coverage determination timelines for multi-gene panel tests. Hospital capital budgeting cycles stall pending coding decisions.
- Sequencing Cost Compression:Next-generation sequencing platforms are capturing share in translational research settings where microarrays previously dominated. Price-per-data-point economics favor sequencing for discovery applications.
Strategic Opportunities
- Cardiology Pharmacogenomics:Payers in the United States are gradually reimbursing CYP2C19 and SLCO1B1 testing for antiplatelet and statin therapy selection. Hospital laboratories are expanding test menus beyond oncology.
- Psychiatry Drug Metabolism Panels:Underpenetrated psychiatric medication management represents white space for gene chip vendors. CYP450 polymorphism screening can reduce adverse event rates in SSRI and antipsychotic prescribing.
- CLIA-Certified Laboratory Networks:Clinical service revenue streams are anchoring instrument placement strategies. High-complexity laboratory partnerships reduce customer acquisition costs for platform vendors.
Industry Challenges
- Bioinformatics Talent Scarcity:Core facilities lack computational biologists capable of interpreting six-million-feature datasets. Training pipelines have not kept pace with platform deployment.
- 21 CFR Part 820 Compliance Burden:Quality system documentation for in vitro diagnostic submissions requires 18-24 month preparation cycles. Smaller array developers face resource constraints for FDA readiness.
- Legacy System Integration:Hospital laboratory information systems require custom middleware to receive microarray results. Interface development delays revenue recognition for new test launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DNA Gene Chip Market |
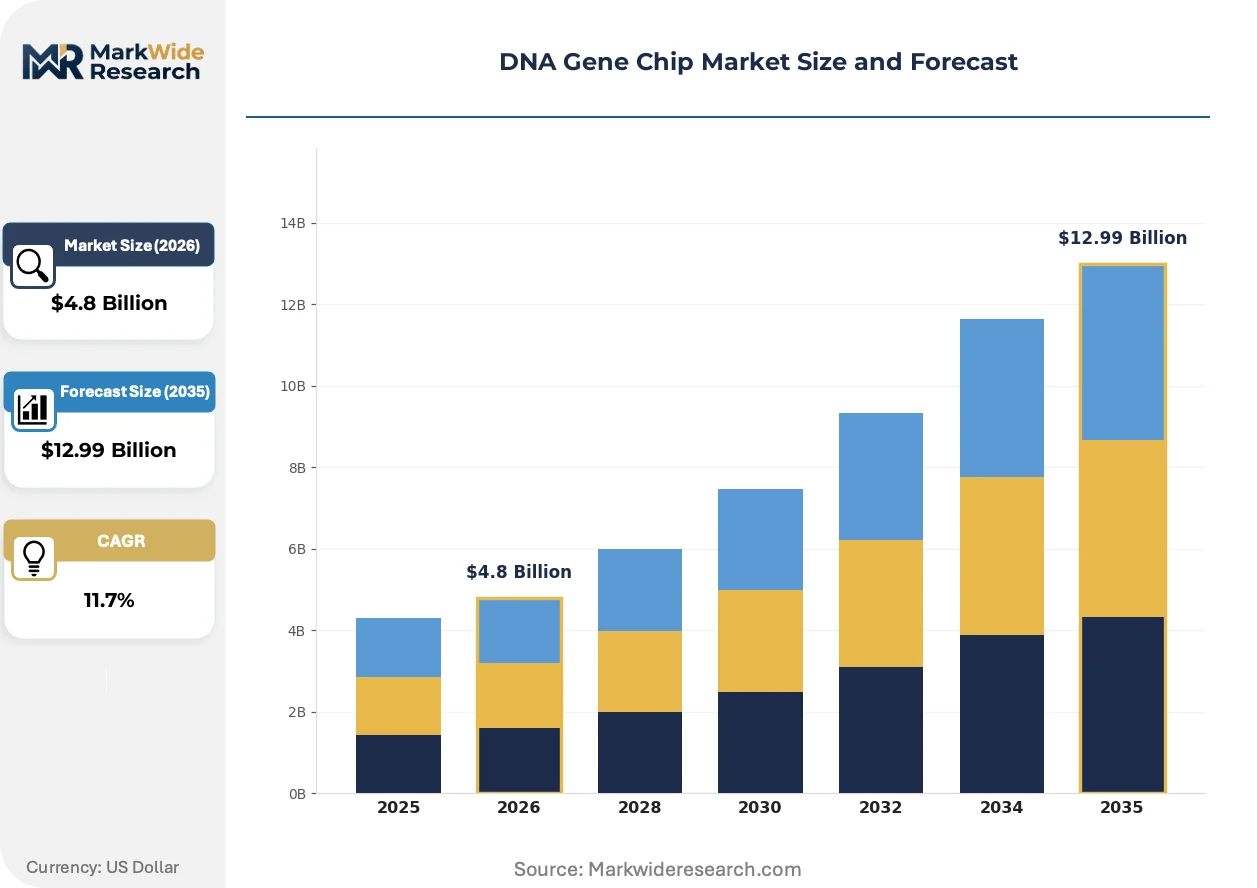
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Affymetrix, Illumina, Agilent, Roche Technology: Microarray, Sequencing, PCR, Hybridization Application: Genetic Research, Diagnostics, Drug Development, Personalized Medicine End User: Research Institutions, Hospitals, Pharmaceutical Companies, Biotechnology Firms |
| Companies Covered | Thermo Fisher Scientific Inc., Illumina, Inc., Agilent Technologies, Revvity, Arrayit Corporation, Macrogen, Inc., PerkinElmer Inc., CapitalBio Technology Co., Ltd., bioMérieux SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DNA Gene Chip Market Emerging Trajectories
Microarray technology is consolidating its position in clinical diagnostic workflows while sequencing platforms capture adjacent research segments. Three forces are reshaping competitive positioning: manufacturing scale, regulatory pathway clarity, and reimbursement infrastructure.
Patterned flow cell manufacturing is consolidating probe density leadership among vendors with captive semiconductor fabrication capabilities. Academic core facilities with established microarray infrastructure are extending platform lifecycles through reagent contract renewals rather than capital replacement. The technology is consolidating installed base retention through consumable lock-in and validated assay portfolios.
The FDA's 21 CFR Part 820 quality system requirements are compressing submission preparation timelines for microarray-based in vitro diagnostics. Drug-device combination product designations are expanding as pharmaceutical sponsors seek companion diagnostic co-development partnerships. Oncology biomarker panels face the most stringent premarket notification requirements, with sponsors investing in prospective clinical validation studies.
Hospital purchasing committees are unbundling instrument acquisition from reagent supply agreements. Procurement officers at academic medical centers now negotiate three-year total cost of ownership contracts rather than capital lease arrangements. This shift is most visible in the United States, where integrated delivery networks centralize laboratory procurement decisions across multi-hospital systems.
DNA Gene Chip Market Segmentation
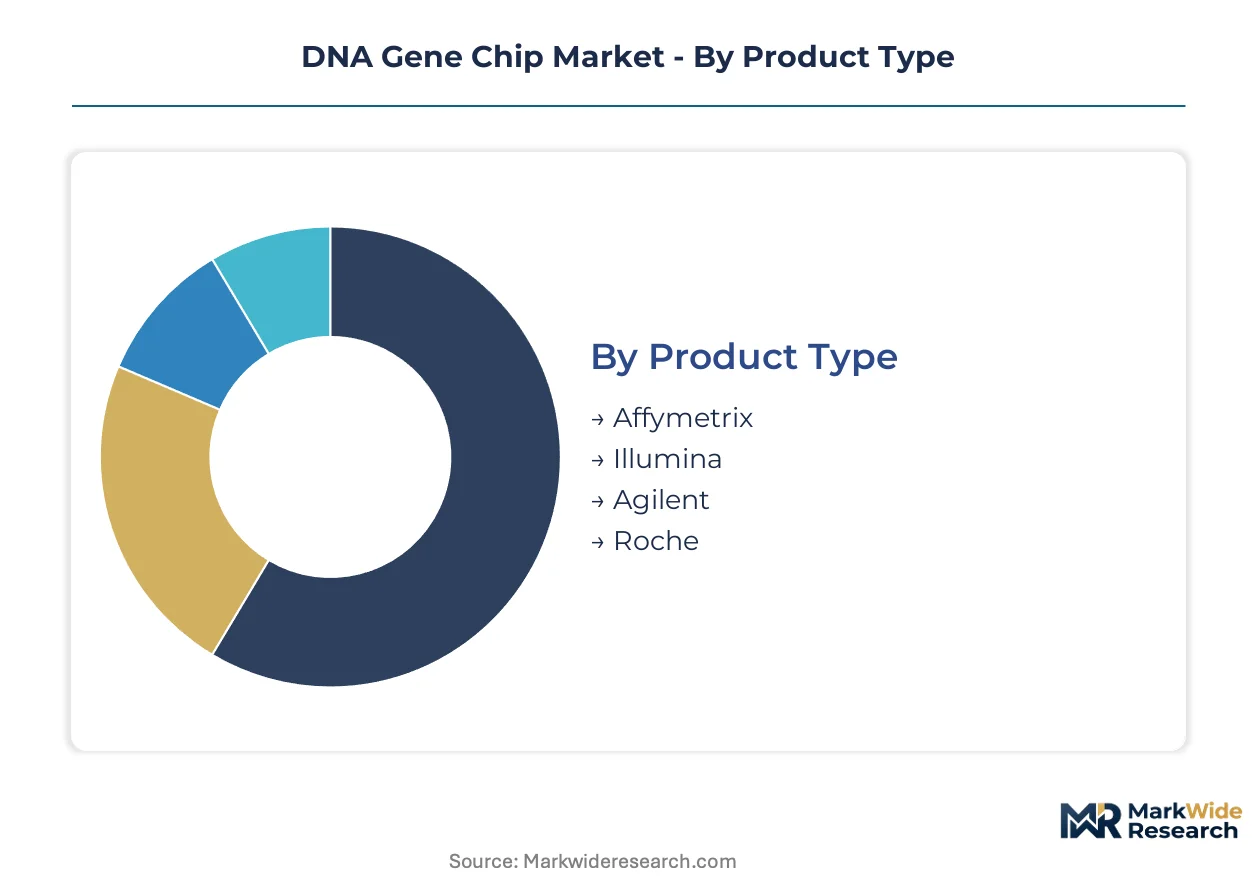
Segmentation in DNA gene chips reveals distinct capital requirements, technology maturity curves, and customer procurement patterns. Platform vendors structure pricing and service models around these divisions to capture recurring revenue from high-throughput users.
Product Type:
Capital intensity varies sharply across platform architectures, with semiconductor-integrated systems demanding the highest upfront investment.
- Affymetrix:Photolithographic manufacturing deposits oligonucleotide probes directly onto quartz substrates at densities exceeding one million features per chip. Academic core facilities in the United States retain substantial installed bases despite platform consolidation, driven by legacy assay validation workflows and reagent contract lock-in.
- Illumina:Patterned flow cells fabricated through in-house semiconductor processes enable six-million-probe densities with reduced per-sample reagent consumption. Pharmaceutical companies in Boston and San Francisco biotech clusters prioritize these platforms for clinical trial companion diagnostic development, where throughput economics dominate procurement decisions.
- Agilent:Inkjet-printed 60-mer oligonucleotide arrays serve comparative genomic hybridization applications with lower capital barriers.
- Roche:NimbleGen-maskless array synthesizers target boutique research applications with customizable probe content.
Illumina absorbs the bulk of installed capacity; Agilent is expanding most quickly in cytogenetics laboratories seeking CGH alternatives.
Technology:
Application context determines which technology layer delivers optimal cost-per-data-point economics.
- Microarray:Solid-substrate hybridization platforms with fluorescent detection remain the workhorse for expression profiling and SNP genotyping at scale. Hospital laboratories in the United States favor microarrays for pharmacogenomic panels where CMS reimbursement codes exist, as turnaround times and interpretive workflows are standardized.
- Sequencing:Next-generation sequencing platforms capture share in discovery-phase research where novel variant detection outweighs throughput cost considerations. Translational research settings previously dominated by microarrays are migrating to sequencing for hypothesis-free biomarker identification.
- PCR:Quantitative PCR arrays provide targeted gene expression analysis with minimal bioinformatics infrastructure requirements.
- Hybridization:Traditional Southern and Northern blot derivatives persist in regulatory validation contexts requiring probe-specific detection.
Microarray technology commands the largest revenue pool; sequencing is gaining share fastest in translational research budgets.
Application:
Margin structure diverges sharply between research-funded and clinically-reimbursed use cases.
- Genetic Research:NIH-funded academic laboratories drive volume for high-density expression arrays, with R01 and U01 mechanism awards steering capital equipment purchases at medical centers. Boston and San Francisco clusters channel these funds into multi-million-dollar core facility installations.
- Diagnostics:FDA-regulated in vitro diagnostic applications concentrate margin pools as payers gradually expand coverage for pharmacogenomic testing. Cardiology and psychiatry drug metabolism panels represent underpenetrated white space beyond established oncology biomarkers.
- Drug Development:Pharmaceutical sponsors integrate pharmacogenomic screening into Phase II enrollment protocols, compressing timelines and expanding companion diagnostic array demand.
- Personalized Medicine:Treatment selection algorithms incorporating patient genotype data are penetrating oncology first, with cardiology and psychiatry following reimbursement expansion.
Diagnostics captures the highest margin per test; drug development is expanding most quickly through companion diagnostic mandates.
End User:
Procurement authority and budget cycles differ fundamentally across institutional categories.
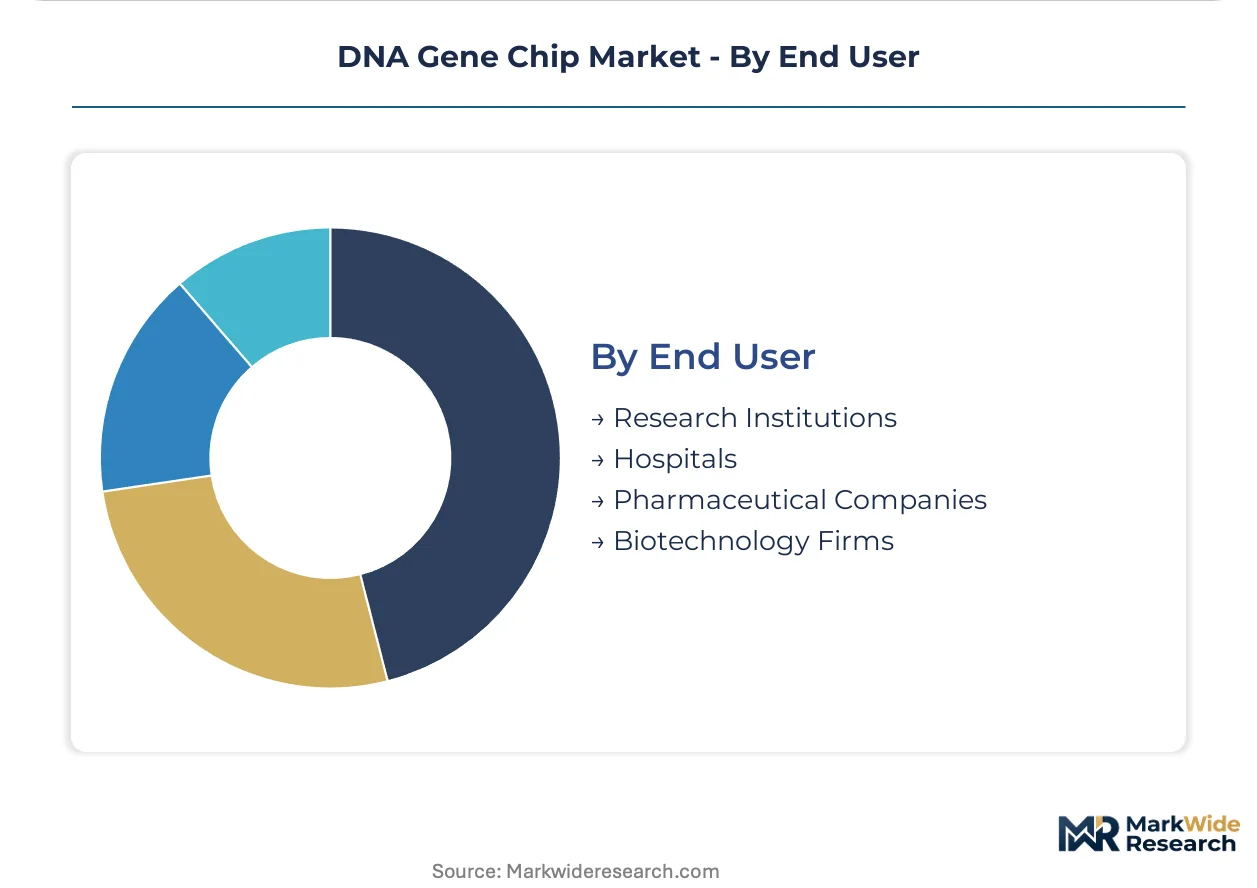
- Research Institutions:Academic medical centers and university core facilities purchase through NIH-funded capital equipment mechanisms, with grant award cycles determining procurement timing. The National Institutes of Health funding allocation indirectly steers volumes through R01 and U01 awards concentrated in Boston and San Francisco.
- Pharmaceutical Companies:Drug sponsors require biomarker stratification platforms for clinical trial protocols, with companion diagnostic co-development partnerships restructuring vendor relationships. Thermo Fisher Scientific leverages CLIA-certified laboratory networks to anchor service revenue alongside instrument placements.
- Hospitals:Integrated delivery networks in the United States centralize laboratory procurement across multi-hospital systems, negotiating three-year total cost of ownership contracts rather than capital leases.
- Biotechnology Firms:Venture-funded startups in Cambridge and South San Francisco prioritize flexible reagent rental models over capital acquisition.
Pharmaceutical companies deploy the highest per-site platform counts; hospitals are expanding test menus fastest as CMS coverage determinations mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Substrate fabrication concentrates in East Asian semiconductor foundries, while instrument consumption and clinical validation cluster in North American and European research hubs. This geographic split shapes procurement patterns and regulatory submission strategies.
United States
Pharmaceutical sponsors in Boston and San Francisco biotech corridors drive companion diagnostic array demand through FDA-mandated biomarker stratification protocols. The FDA's 21 CFR Part 820 quality system requirements compress submission timelines for microarray-based in vitro diagnostics. NIH R01 and U01 mechanism awards channel federal funding into academic medical center core facilities, with procurement cycles tied to grant award schedules.
Germany
Industrial research consortia in Bavaria and Baden-Württemberg deploy gene chips for pharmacogenomic screening in precision medicine initiatives. The EMA's evolving in vitro diagnostic medical device regulation creates pathway clarity for microarray-based oncology tests. Heidelberg and Munich host dense clusters of molecular diagnostics laboratories serving both research and clinical translation markets.
China
Domestic instrument manufacturers source patterned flow cell substrates from captive semiconductor fabrication while expanding clinical test menus. NMPA regulatory reforms accelerate approval timelines for locally developed gene chip platforms. Beijing and Shanghai biotech parks concentrate capital equipment procurement through state-backed genomic medicine funding mechanisms.
United Kingdom
Academic core facilities in Cambridge and London maintain substantial microarray infrastructure despite sequencing platform expansion. MHRA post-Brexit regulatory autonomy is reshaping conformity assessment procedures for diagnostic arrays. The Oxford-Cambridge arc channels venture funding into gene chip startups targeting pharmacogenomic applications.
Switzerland
Pharmaceutical headquarters in Basel and Roche's captive diagnostics division sustain demand for high-throughput array platforms. Swissmedic's streamlined quality system recognition facilitates parallel FDA-EMA submission strategies for companion diagnostics. Zurich and Geneva research institutions balance microarray legacy infrastructure with targeted sequencing investments.
DNA Gene Chip Market Vendor Landscape
Top-tier vendors anchor the high-throughput sequencing array segment, while mid-tier specialists compete on cytogenetics and boutique research applications. Semiconductor-integrated manufacturing capabilities consolidate probe density leadership among captive fabrication operators. Two strategic archetypes dominate: platform vendors with in-house substrate production and clinical service providers with CLIA-certified laboratory networks. Competitive moves center on companion diagnostic co-development partnerships and three-year total cost of ownership contract structures.
Among United States-based platform vendors, Thermo Fisher Scientific Inc. exemplifies the clinical service anchoring archetype through its laboratory network integration. Illumina, Inc. occupies a position representing semiconductor-captured manufacturing scale. Agilent Technologies sits within the specialized cytogenetics instrumentation tier. These three companies collectively illustrate the competitive segmentation between throughput-driven pharmaceutical applications and hospital laboratory diagnostic menus.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Illumina, Inc. |
| Agilent Technologies |
| Revvity |
| Arrayit Corporation |
| Macrogen, Inc. |
| PerkinElmer Inc. |
| CapitalBio Technology Co., Ltd. |
| bioMérieux SA |
| Others |
Supply Flow & Price Mechanics
Semiconductor-captive platform vendors with in-house wafer fabrication anchor pricing discipline through substrate cost control, while contract research organizations and hospital laboratories face divergent procurement economics shaped by grant funding cycles versus reimbursement code availability.
Pricing Analysis
Price erosion across standard-density microarray tiers traces to sequencing platform competition in translational research budgets, though probe density premiums hold firm for companion diagnostic applications. Three-tier pricing structure across high-density, mid-density, and targeted-panel levels separates pharmaceutical sponsors from academic core facilities from hospital laboratories. Cost-down pressure on reagent consumables accelerates because integrated delivery networks negotiate three-year total cost of ownership contracts bundling instrument depreciation with per-test chemistry. Hospital procurement committees exhibit highest price sensitivity; pharmaceutical companies prioritize throughput economics over unit cost.
Supply Chain Analysis
Freight costs for temperature-controlled oligonucleotide reagents from European synthesis houses to North American core facilities add logistics premiums to landed chemistry costs. Taiwan and South Korea dominate 300mm silicon wafer production for patterned flow cell substrates; China maintains expanding captive fabrication for domestic instrument manufacturers. Raw material dependencies center on high-purity silicon wafers, phosphoramidite nucleoside monomers, and fluorescent dye conjugates. Single-source vulnerability concentrates in photolithographic mask sets for legacy Affymetrix-compatible platforms. Distribution runs through direct field service organizations for high-throughput pharmaceutical accounts and distributor networks for mid-tier cytogenetics laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
300mm wafer fabrication capacity constraints in East Asian foundries prop instrument pricing power, limiting supply elasticity for probe density leadership.
For Market Incumbents: Cement installed base retention through reagent contract lock-in and validated assay portfolio expansion. Threat from next-generation sequencing cost compression demands backward integration into semiconductor fabrication for substrate cost control. Priority lever rests on CLIA-certified laboratory network scale anchoring clinical service revenue. For New Entrants and Emerging Players: Psychiatric medication management panels represent an underserved buyer archetype with minimal established competition. Cardiology pharmacogenomics in United States hospital laboratories offers the most penetrable segment given expanding CMS coverage determinations. Go-to-market angle should emphasize minimal bioinformatics infrastructure requirements for core facilities facing computational biologist scarcity. For Investors and Strategic Acquirers: FDA 21 CFR Part 820 quality system submission filings for companion diagnostic co-development partnerships is the leading indicator that platform vendor consolidation momentum is accelerating. Five-to-ten-year viability frames around semiconductor-captive manufacturing capabilities and regulatory pathway expertise. Acquisition target archetype: mid-tier cytogenetics specialists with established hospital laboratory relationships. Signal to monitor: CMS coverage determination timelines for multi-gene panel tests.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development Partnership | Pharmaceutical sponsors now mandate biomarker stratification before Phase II enrollment, restructuring vendor procurement authority. |
| CLIA-Certified Laboratory Network Expansion | Clinical service revenue anchors instrument placement economics and reduces customer acquisition costs for platform vendors. |
| Patterned Flow Cell Manufacturing Scale-Up | In-house semiconductor fabrication transfers cost advantages from electronics into life sciences instrumentation probe density leadership. |
| Multi-Gene Panel Reimbursement Strategy | CMS coverage determination timelines directly cascade through hospital capital budgeting and reagent contract negotiation cycles. |
| Psychiatry Pharmacogenomics Menu Expansion | CYP450 polymorphism screening for SSRI and antipsychotic prescribing represents underpenetrated white space beyond oncology biomarkers. |
Methodological Framework
Multi-period observation of NIH funding allocation patterns, FDA submission filing timelines, and CMS coverage determination schedules anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and core facility directors. Primary fieldwork combined with secondary validation from FDA 510(k) and PMA filings, ClinicalTrials.gov protocol registries, CMS Medicare coverage databases, and SEC 10-K instrument revenue disclosures. Bottom-up triangulation across end-user procurement volumes and top-down cross-check against vendor reported placements established convergence.
Segment-weighting across product type, technology layer, application context, and end-user procurement authority shaped the analytical framework across the projection horizon. Modeled dimensions included platform architecture capital intensity, probe density tier, clinical versus research funding source, and geographic regulatory cluster. CAGRs derived from fitted growth curves against historical NIH mechanism award trajectories and pharmaceutical R&D pipeline biomarker stratification trends. Industry-specific inputs incorporated semiconductor wafer supply forecasts and in vitro diagnostic regulatory pathway evolution assumptions.
Revisions become necessary when FDA guidance document updates, CMS national coverage determination reversals, or East Asian wafer supply disruptions materialize. Forecasts reflect documented assumptions about reimbursement expansion timelines and companion diagnostic mandate scope. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Sequencing Electrophoresis Systems Market
Genomics
Direct-To-Consumer (DTC) Genetic Testing Market
Genomics
DNA Methylation Market
Genomics
Cancer-Focused Genetic Testing Services Market
Genomics
Rare Disease Genetic Testing Market
Genomics
Global Pharmacogenomics Market
Genomics
Asia-Pacific Genetic Testing Market
Genomics
Next Generation Sequencing (NGS) Informatics Market
Genomics
Middle East and Africa Genetic Testing Market
Genomics
Non Invasive Prenatal Testing (NIPT) Market
Genomics
Human Genetics Market
Genomics
Spatial Genomics and Transcriptomics Market
Genomics
Europe DNA Sequencing Products Market
Genomics
Mrna Sequencing Market
Genomics
Pre-Pregnancy Genetic Testing Market
Genomics
Nutrigenomics Testing Market