
 Nutrigenomics Testing Market | 2026-2036
Nutrigenomics Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Nutrigenomics Testing Market Analysis
CLIA certification is reorganizing competitive access in nutrigenomics testing, elevating compliance costs for smaller laboratories while creating barriers to entry that favor established operators. Nutrigenomix leverages its university research origins to sustain credibility among healthcare providers seeking evidence-based genomic guidance. 23andMe anchors the direct-to-consumer channel with proprietary genotype databases that extend beyond ancestry into nutritional trait reporting. DNAfit specializes in athletic performance applications, competing for contracts with professional sports teams and elite training facilities.
Nutrigenomics testing analyzes genetic variants affecting nutrient metabolism, absorption, and dietary response through SNP genotyping and metabolite profiling, primarily to customize dietary recommendations and preventive health strategies. DNA testing kits dominate product type revenue due to their scalable manufacturing and repeat purchase potential, while analysis services capture margin pools through proprietary algorithmic interpretation. Consumers represent the fastest-growing end user segment as self-directed health management expands, though healthcare providers retain higher per-test value through integrated clinical consultation.
The FDA regulates laboratory-developed tests and direct-to-consumer genetic health risk assessments, while CLIA governs analytical validity standards for clinical laboratories; HIPAA shapes data handling requirements for covered entities offering nutrigenomic counseling. The EU AI Act and GDPR impose additional constraints on algorithmic health recommendations and biometric data processing for European market participants. Stakeholders must monitor evolving classification determinations that could reclassify nutrigenomic reports as medical devices, fundamentally altering distribution channels and reimbursement pathways.
Market Dynamics
CLIA certification requirements are compressing laboratory margins while concentrating analytical capacity among university-affiliated and health-system-integrated operators that can amortize compliance overhead across high-throughput workflows.
Growth Catalysts
- FDA pathway clarity for laboratory-developed tests:The agency's risk-based classification framework reduces regulatory ambiguity for nutrigenomic panels, accelerating commercialization timelines for validated assays targeting metabolic trait reporting.
- Metabolite profiling convergence:Integration of SNP genotyping with functional biomarker measurement strengthens clinical utility, driving adoption among registered dietitians seeking objective dietary response validation.
- United States consumer awareness saturation:Direct-to-consumer genetic testing penetration has normalized genomic literacy, creating pull-through demand for nutrition-specific interpretation services beyond ancestry applications.
Market Restraints
- CLIA analytical validity compliance:Smaller independent laboratories face capital-intensive equipment and personnel requirements that compress operating margins below sustainable thresholds.
- Reimbursement pathway opacity:Private payers and CMS maintain inconsistent coverage determinations for nutrigenomic counseling, constraining healthcare provider integration and forcing cash-pay models.
- Polygenic risk score limitations:Current algorithms explain modest variance in dietary response, creating credibility gaps with clinicians trained on monogenic diagnostic paradigms.
Strategic Opportunities
- Employer wellness channel penetration:Self-insured corporations in the United States are piloting nutrigenomic benefits as differentiated recruitment and retention tools, bypassing traditional clinical gatekeepers.
- EU AI Act algorithmic transparency requirements:Early compliance with explainability standards positions vendors for preferential access to European preventive health programs as member states operationalize digital health frameworks.
- Athletic performance vertical specialization:Professional sports organizations and Olympic training facilities represent concentrated demand for recovery-optimization and injury-prevention genomic profiling.
Industry Challenges
- Bioinformatics talent scarcity:Laboratories compete for computational biologists capable of integrating multi-omic datasets with nutritional epidemiology, compressing development timelines for proprietary interpretation engines.
- Data interoperability friction:Electronic health record integration requires HL7 FHIR compliance investments that strain mid-cap laboratory IT budgets and delay health-system contract execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutrigenomics Testing Market |
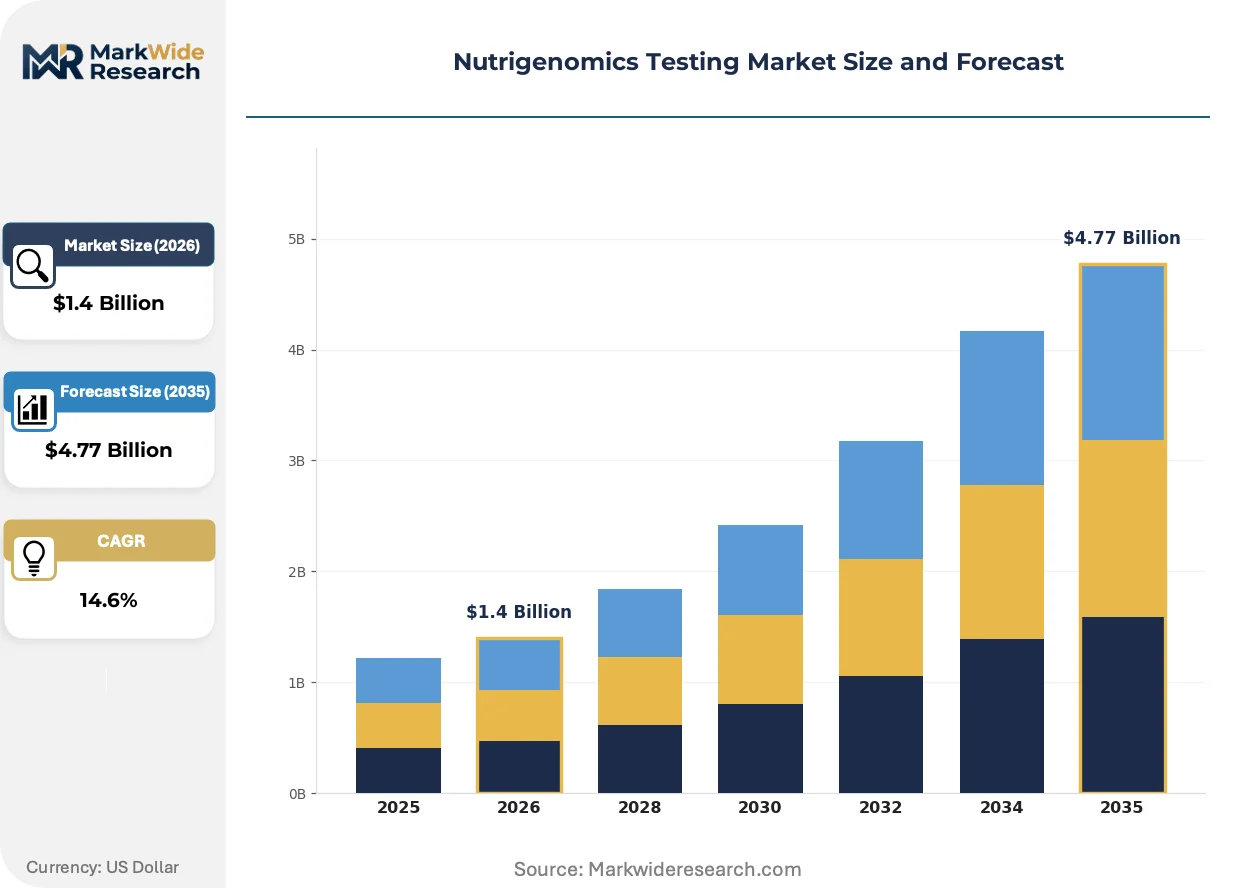
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.77 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Testing Kits, Sample Collection Kits, Analysis Services, Consultation Services Application: Personalized Nutrition, Wellness Management, Disease Prevention, Athletic Performance End User: Healthcare Providers, Fitness Centers, Research Institutions, Consumers Distribution Channel: Online Stores, Direct Sales, Retail Pharmacies, Educational Institutions |
| Companies Covered | Nutrigenomix, 23andMe, DNAfit, Genomind, GX Sciences, Cura Integrative Medicine, Interleukin Genetics, Pathway Genomics, Xcode Life, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutrigenomics Testing Market Emerging Trajectories
Portable sequencing hardware and cloud-based interpretation platforms are compressing the analytical workflow from sample collection to actionable recommendation, collapsing traditional laboratory turnaround constraints.
Point-of-care SNP genotyping instrumentation is miniaturizing. Fitness centers and corporate wellness clinics in the United States are deploying countertop devices that return same-day results, bypassing centralized CLIA laboratory logistics. This distributed architecture is compressing the addressable market for traditional kit-based mail-in models while expanding test frequency among convenience-seeking consumers.
The EU AI Act's risk classification for health-related algorithmic decision support is tightening documentation requirements for European market participants. Vendors must now maintain technical files demonstrating bias mitigation and performance validation across diverse populations. Germany and France are emerging as early enforcement theaters where national regulators are interpreting AI Act provisions through existing medical device frameworks.
Subscription-based nutrition coaching is displacing one-time test purchases as the dominant commercial model. United States direct-to-consumer platforms now bundle initial genomic assessment with ongoing algorithmic meal planning and registered dietitian access. This recurring revenue architecture is visible most acutely in coastal metropolitan markets where wellness expenditure concentration supports premium pricing tiers.
Nutrigenomics Testing Market Segmentation
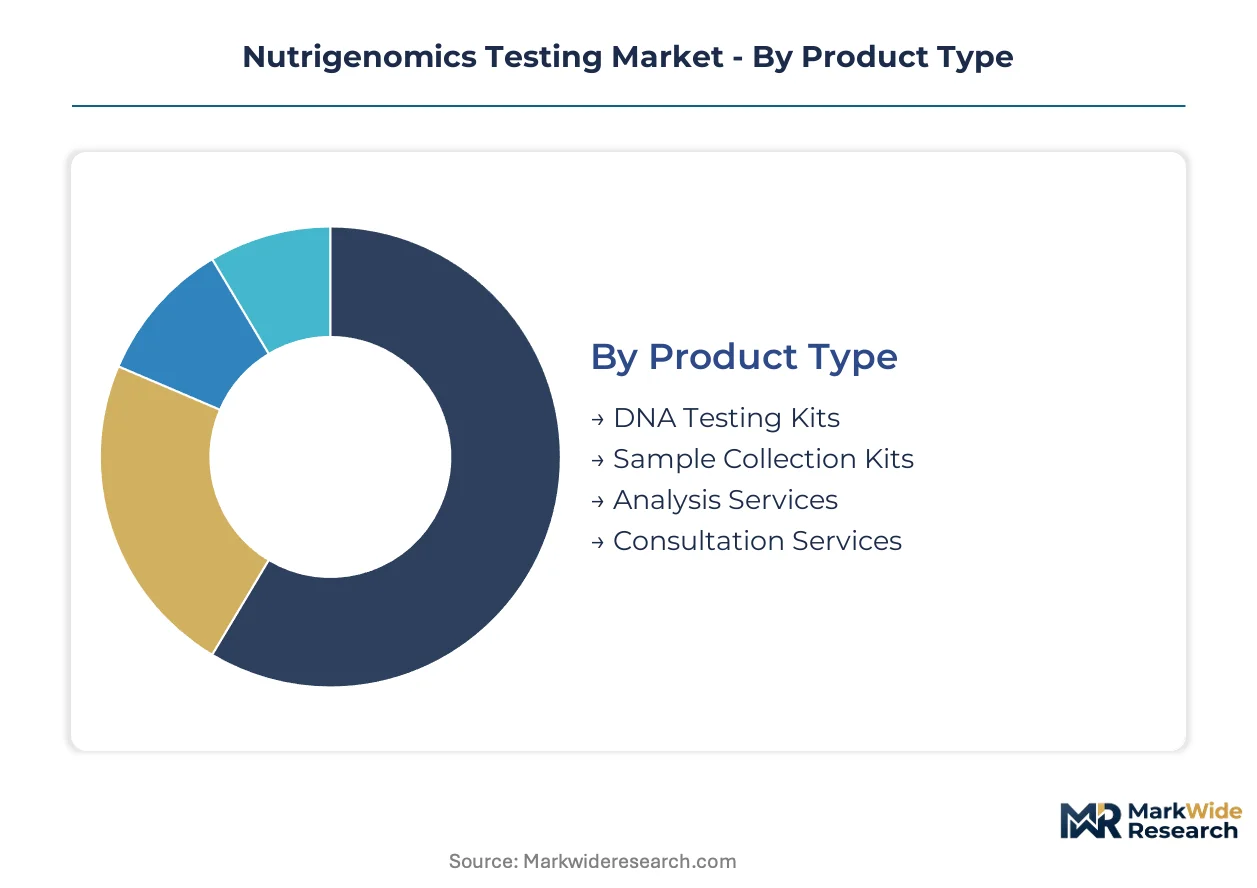
Nutrigenomics testing segments reflect divergent commercial models across hardware, services, and interpretation layers. Margin distribution favors recurring revenue architectures over one-time kit sales, while channel strategy determines regulatory exposure and customer acquisition economics.
Product Type:
Analysis services command the highest gross margins through proprietary algorithmic interpretation, while DNA testing kits drive volume through scalable manufacturing economics.
- DNA Testing Kits:Saliva-based collection vessels with stabilizing buffer solutions enable ambient temperature shipping. Demand concentrates in United States direct-to-consumer channels where ancestry testing has normalized genomic literacy, though kit commoditization pressures price points toward manufacturing cost floors.
- Analysis Services:Cloud-based bioinformatics pipelines interpret SNP arrays against nutritional epidemiology databases. Healthcare providers in Germany and France generate premium pricing through integrated clinical consultation, as EU AI Act compliance requirements favor established vendors with documented algorithmic validation.
- Sample Collection Kits:Buccal swabs and finger-prick blood cards with barcoded chain-of-custody documentation.
- Consultation Services:Registered dietitian sessions bundled with genomic report walkthroughs.
The dominant share belongs to DNA Testing Kits, while Analysis Services is closing the gap fastest through subscription bundling and clinical integration.
Application:
Athletic performance applications extract premium pricing from professional sports organizations, whereas disease prevention faces reimbursement friction that constrains provider adoption.
- Personalized Nutrition:Macronutrient and micronutrient recommendations calibrated to genetic variants in caffeine metabolism, lactose tolerance, and vitamin absorption. United States wellness clinics and corporate programs in California and New York deploy these assessments as employee benefits, bypassing traditional clinical gatekeepers.
- Athletic Performance:Recovery optimization and injury-risk profiling for muscle composition and tendon collagen genes. Olympic training facilities in Australia and professional football clubs in England contract for team-wide genomic screening, with results informing periodization protocols.
- Wellness Management:General health maintenance through polygenic risk scoring for metabolic traits.
- Disease Prevention:Early intervention targeting type 2 diabetes and cardiovascular susceptibility markers.
Personalized Nutrition holds the revenue base, yet Athletic Performance is expanding most quickly through sports medicine channel development.
End User:
Consumers generate the steepest volume expansion through self-directed health management, though healthcare providers retain superior per-test value through integrated clinical workflows.
- Consumers:Direct-to-customer purchases through online platforms and fitness center partnerships. Self-insured employers in Texas and Illinois are piloting nutrigenomic benefits as recruitment tools, creating B2B2C demand concentration that bypasses physician intermediaries.
- Healthcare Providers:Functional medicine clinics and registered dietitian practices incorporating genomic data into preventive care protocols. Reimbursement opacity from CMS and private payers forces cash-pay models, constraining adoption to affluent metropolitan markets.
- Fitness Centers:Boutique gyms and athletic clubs offering on-site testing with same-day results.
- Research Institutions:University laboratories conducting nutritional genomics cohort studies.
Healthcare Providers anchor current revenue, while Consumers are gaining share fastest through employer wellness channel penetration.
Distribution Channel:
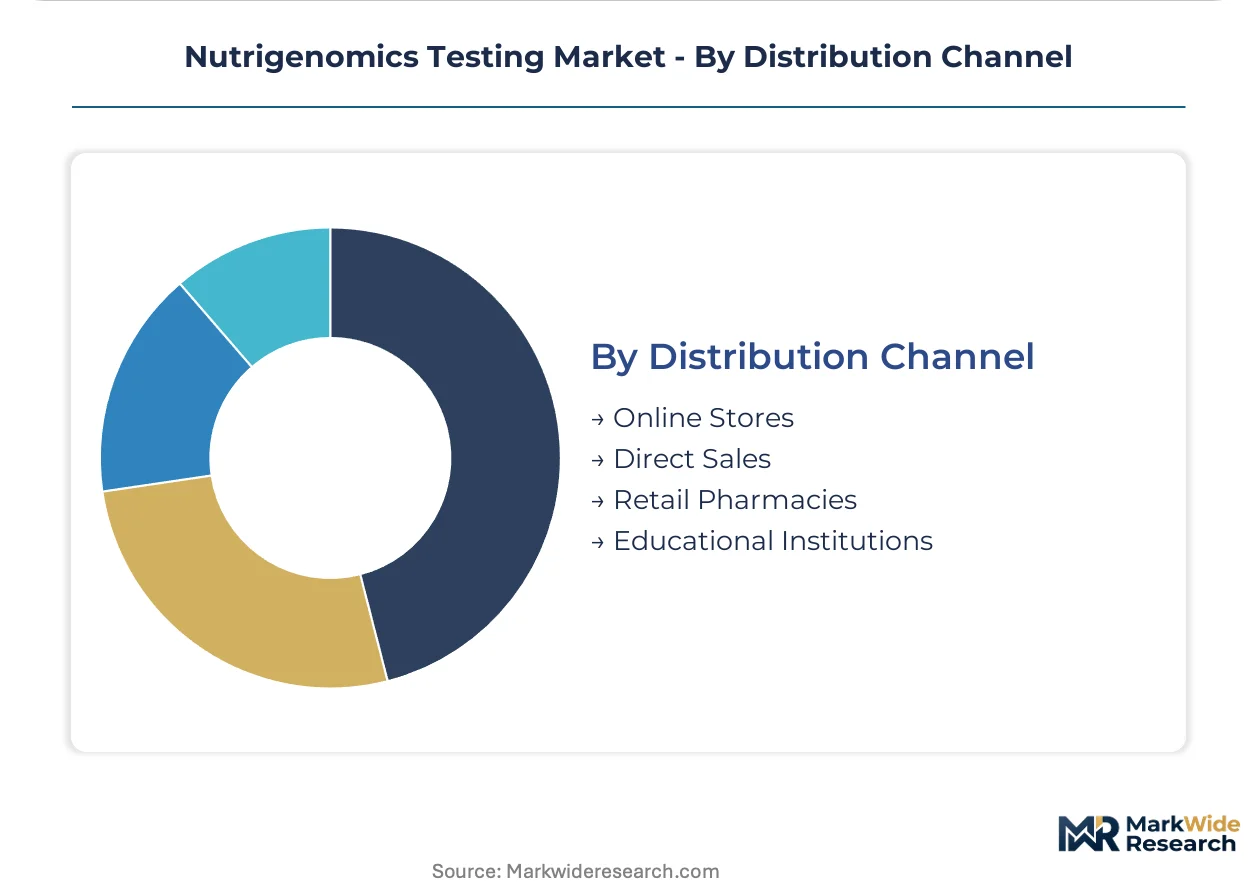
Online stores capture the broadest geographic reach with minimal regulatory overhead, whereas retail pharmacies face FDA and state board scrutiny that slows shelf placement.
- Online Stores:E-commerce platforms and proprietary brand websites with automated report delivery. United States vendors dominate this channel through HIPAA-compliant data infrastructure, while European participants navigate GDPR consent requirements for biometric data processing.
- Direct Sales:Enterprise contracts with health systems and corporate wellness vendors. CLIA-certified laboratories in Massachusetts and North Carolina leverage direct sales forces to secure multi-year service agreements with academic medical centers.
- Retail Pharmacies:Over-the-counter kit placement in drugstore chains.
- Educational Institutions:Campus health services and nutrition department research partnerships.
Online Stores maintain the volume lead, while Direct Sales is climbing the fastest through health-system integration and employer contract expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA pathway clarity for laboratory-developed tests and employer wellness incentive programs are accelerating commercialization timelines across key demand centers. CLIA certification requirements concentrate analytical capacity among high-throughput operators in specific metropolitan clusters.
United States
Direct-to-consumer genetic testing penetration has normalized genomic literacy, creating pull-through demand for nutrition-specific interpretation services beyond ancestry applications. FDA oversight of laboratory-developed tests shapes commercialization pathways for nutrigenomic panels. Boston and San Francisco anchor university-affiliated laboratory networks that amortize compliance overhead across research and clinical workflows.
Germany
National regulators are interpreting EU AI Act provisions through existing medical device frameworks, tightening documentation requirements for algorithmic health recommendations. GDPR consent requirements for biometric data processing constrain direct-to-consumer channel expansion. Munich and Heidelberg concentrate health-system-integrated operators with documented algorithmic validation for preventive health programs.
United Kingdom
Professional football clubs contract for team-wide genomic screening, with results informing periodization protocols for recovery optimization. The Medicines and Healthcare products Regulatory Agency maintains oversight of health-related genetic testing services. London anchors corporate wellness vendor networks piloting nutrigenomic benefits as differentiated recruitment tools.
Australia
Olympic training facilities represent concentrated demand for injury-prevention genomic profiling and athletic performance applications. The Therapeutic Goods Administration governs in vitro diagnostic medical devices including nutrigenomic assays. Melbourne and Sydney concentrate sports medicine channel development for elite training facility contracts.
France
ANSM and CNIL are emerging as early enforcement theaters for EU AI Act compliance in health-related algorithmic decision support. Registered dietitian practices generate premium pricing through integrated clinical consultation and genomic data interpretation. Paris anchors preventive health program networks operationalizing digital health frameworks under member state implementation.
Nutrigenomics Testing Market Vendor Landscape
Player mix skews toward university-spinout laboratories and direct-to-consumer genetic testing platforms with proprietary genotype databases. CLIA certification requirements compress operating margins for smaller independent operators while concentrating analytical capacity among health-system-integrated networks. Two strategic archetypes dominate: evidence-based genomic guidance providers leveraging research credibility, and ancestry-platform extenders monetizing existing user bases through nutritional trait reporting. Competitive moves center on employer wellness channel penetration and subscription-based nutrition coaching bundling.
Within the university-research-originated tier, Nutrigenomix exemplifies evidence-based positioning among healthcare providers seeking clinically credible genomic guidance. Among direct-to-consumer platform operators, 23andMe anchors the ancestry-to-nutrition extension model with proprietary databases, while DNAfit occupies a position in athletic performance vertical specialization competing for professional sports contracts. These three represent divergent archetype strategies for navigating regulatory complexity and channel economics.
| Leading Market Players |
|---|
| Nutrigenomix |
| 23andMe |
| DNAfit |
| Genomind |
| GX Sciences |
| Cura Integrative Medicine |
| Interleukin Genetics |
| Pathway Genomics |
| Xcode Life |
| Others |
Supply Flow & Price Mechanics
Seven-to-ten-day turnaround cycles for CLIA-validated nutrigenomic panels concentrate pricing power among high-throughput laboratories in Massachusetts and North Carolina, while smaller operators absorb margin compression from extended equipment depreciation schedules. This lead-time stratification reinforces tiered access to healthcare provider contracts and employer wellness channels.
Pricing Analysis
Certification level creates the primary spread between CLIA-certified clinical-grade testing and direct-to-consumer wellness tiers. Three-tier pricing structure across premium, standard, and economy levels segments by analytical validity documentation, algorithmic transparency, and registered dietitian consultation bundling. Cost compression in the direct-to-consumer tier intensifies as ancestry-platform extenders leverage existing genotype databases for nutritional trait reporting. Self-insured employers exhibit lowest price sensitivity due to recruitment-ROI justification, while individual consumers through online channels drive hardest bargain hunting.
Supply Chain Analysis
Seven-to-ten-day turnaround cycles for validated panels hinge on proximity to CLIA-certified laboratory networks in the United States, Germany, and Australia. Saliva collection vessels draw from medical-grade plastics suppliers in China and Mexico, while SNP array consumables rest on semiconductor fabrication concentrated in Taiwan and South Korea. Single-source vulnerability in Illumina sequencing chemistry creates procurement risk for mid-cap laboratories. Distribution runs through HIPAA-compliant cloud infrastructure for report delivery, with physical kit logistics anchored in regional fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from wearable-metabolite convergence devices that bypass genomic sampling entirely, threatening the core value proposition of SNP-based dietary recommendations.
For Market Incumbents: Consolidate analytical capacity through acquisition of CLIA-certified mid-cap laboratories in Texas and Illinois to amortize compliance overhead across employer wellness contract volumes. Deepen backward integration into proprietary SNP array design to reduce Illumina chemistry dependency and defend margin position against ancestry-platform extenders entering nutrition verticals. For New Entrants and Emerging Players: Anchor in athletic performance applications for Olympic training facilities and professional football clubs, where specialized recovery-optimization protocols command premium pricing and resist commoditization. Target corporate wellness vendors in coastal United States metropolitan markets with subscription-based nutrition coaching bundles that bypass physician gatekeepers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across algorithmic interpretation engine development as EU AI Act compliance demands bias-mitigation documentation and multi-population validation datasets. University-spinout laboratories with documented clinical credibility represent preferred acquisition archetypes. Watch for FDA reclassification determinations that would shift nutrigenomic reports into medical device pathways as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Certification Expansion | Extends analytical validity credentials to capture health-system integrated laboratory contracts in Boston and San Francisco clusters. |
| Algorithmic Transparency Documentation | Positions vendors for preferential access under EU AI Act enforcement emerging through ANSM and CNIL interpretation frameworks. |
| Employer Wellness Channel Partnership | Bypasses reimbursement opacity from CMS and private payers through self-insured corporate benefit procurement. |
| SNP-Metabolite Profiling Convergence | Strengthens clinical utility for registered dietitians seeking objective dietary response validation beyond polygenic risk scores. |
| Point-of-Care Instrument Miniaturization | Enables fitness center deployment with same-day results, compressing addressable market for mail-in kit models. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CLIA laboratory directors, registered dietitian practice owners, corporate wellness procurement managers, and bioinformatics platform engineers. Secondary validation drew from FDA 510(k) filings, CMS coverage determination databases, EU AI Act implementation guidance, and CLIA inspection records. Bottom-up test volume modeling triangulated against top-down market sizing from ancestry-platform financial disclosures.
Across the analysis window, forecasts incorporated segmentation by product type, application vertical, end-user archetype, and distribution channel. CAGRs were derived from test volume trajectory modeling and pricing evolution assumptions. Forecast inputs included employer wellness benefit adoption curves, CLIA certification pipeline data, and sports medicine channel development metrics.
Decision-makers should treat outputs as directional under base assumptions of sustained FDA pathway clarity for laboratory-developed tests and stable CLIA compliance cost structures; material deviation in reclassification risk or reimbursement policy would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Genetic Testing Market
Genomics
UAE Genetic Testing Market
Genomics
Whole Plasmid Sequencing Market
Genomics
Genetic Material Market
Genomics
Multiomics Market
Genomics
DNA Methylation Market
Genomics
Global Metagenomic Sequencing Market
Genomics
Prenatal Genetic Testing Market
Genomics
Global Single Nucleotide Polymorphism (SNP) Genotyping Market
Genomics
Global NGS Sample Preparation Market
Genomics
Pre-Pregnancy Genetic Testing Market
Genomics
Genome Sequencing Market
Genomics
Retail Genomics Market
Genomics
SNP Genotyping Market
Genomics
Agrigenomics Market
Genomics
Plant Genomics Market