
 Global Genomics Market | 2026-2036
Global Genomics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Genomics Market Analysis
Subscription-based bioinformatics software is shifting how genomics platforms monetize recurring value beyond instrument sales. Illumina, Inc. leverages its cloud-based analysis tools to deepen customer retention across sequencing workflows. Thermo Fisher Scientific, Inc. anchors its position through integrated reagent-instrument bundles that raise switching costs for research institutes. Oxford Nanopore Technologies differentiates via real-time, portable sequencing devices that extend field-based genomic surveillance capabilities.
Genomics encompasses the comprehensive study of an organism's complete DNA sequence, including structural variation, gene expression profiling, and epigenetic modification analysis through technologies capable of resolving single-nucleotide polymorphisms and large structural variants. Its primary commercial purpose centers on enabling precision diagnostics, targeted therapeutic development, and agricultural trait selection through molecular-level biological understanding. Next-Generation Sequencing instruments command the largest capital expenditure share, though reagents generate superior recurring margins due to per-run consumption. Services represent the fastest-expanding segment as pharmaceutical companies outsource complex bioinformatics analysis to specialized providers.
The FDA's oversight of laboratory-developed tests and companion diagnostics shapes product validation timelines, while the EMA's evolving framework for genomic-based therapeutics influences parallel submission strategies across jurisdictions. China's NMPA accelerates local registration pathways for sequencing instruments, redirecting some manufacturing investment toward domestic certification compliance. Stakeholders must monitor divergence between regulatory data-localization requirements and cross-border collaborative research needs.
Market Dynamics
Pharmaceutical outsourcing of bioinformatics pipelines is compressing in-house R&D timelines while concentrating analytical demand among specialized service providers. This structural shift reconfigures how sequencing platforms capture recurring revenue beyond instrument placement.
Growth Catalysts
- FDA companion diagnostics guidance:Accelerated clinical validation requirements push pharmaceutical developers toward integrated genomic profiling earlier in drug development cycles.
- China NMPA pathway streamlining:Domestic registration acceleration for sequencing instruments redirects manufacturing investment toward certification compliance within the country.
- Real-time surveillance demand:Field-deployable genomic monitoring capabilities expand addressable applications beyond traditional laboratory settings into environmental and agricultural monitoring.
Market Restraints
- Reagent supply concentration:Proprietary consumable lock-in from dominant platform vendors creates switching cost barriers for research institutes seeking analytical flexibility.
- Data localization mandates:Divergent cross-border genomic data transfer restrictions fragment collaborative research architectures and duplicate infrastructure requirements.
- Technical read-length limitations:Short-read sequencing platforms struggle with complex structural variant resolution, constraining certain clinical diagnostic applications.
Strategic Opportunities
- India diagnostic expansion:Underpenetrated molecular testing infrastructure in tier-two cities creates whitespace for decentralized sequencing service models.
- AI-variant interpretation convergence:Machine learning classification tools integrated with cloud-based analysis pipelines reduce turnaround time for rare disease diagnosis.
- Subscription platform migration:Bioinformatics software-as-a-service models displace perpetual licensing, capturing recurring revenue from smaller research laboratories.
Industry Challenges
- Bioinformatics talent scarcity:Computational biology expertise gaps constrain interpretation service scaling for clinical diagnostic laboratories.
- Multi-jurisdiction validation timelines:Parallel FDA-EMA submission requirements for companion diagnostics extend product commercialization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Genomics Market |
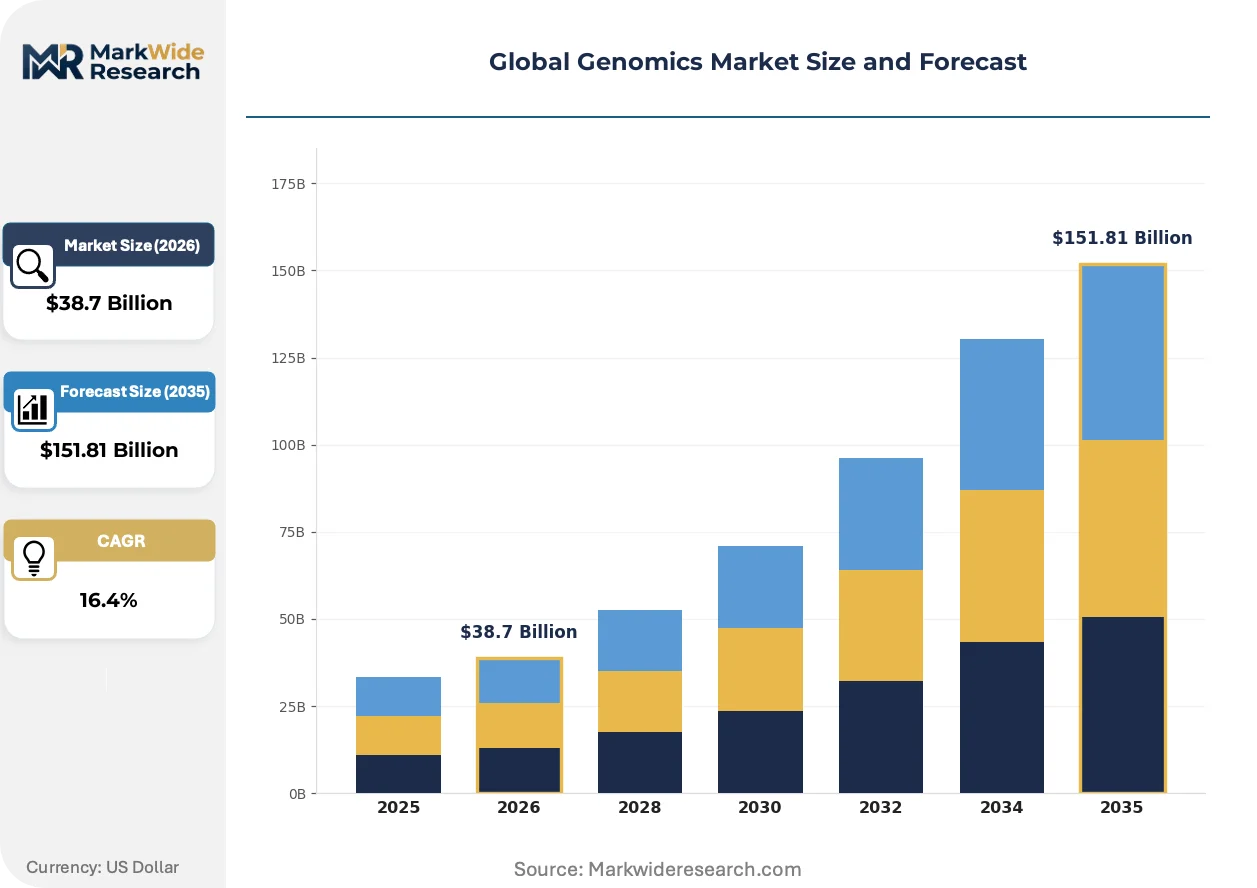
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Services End User: Research Institutes, Pharmaceutical Companies, Diagnostic Laboratories, Academic Institutions Technology: Sanger Sequencing, Next-Generation Sequencing, PCR, Microarrays Application: Personalized Medicine, Drug Discovery, Genetic Testing, Agriculture |
| Companies Covered | Illumina, Inc., Thermo Fisher Scientific, Inc., F. Hoffmann-La Roche Ltd., Danaher Corporation, Agilent Technologies, QIAGEN N.V., BGI Genomics, Oxford Nanopore Technologies, PacBio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Genomics Market Emerging Trajectories
Sequencing technology is fragmenting across performance dimensions, with portability, speed, and accuracy becoming separable purchase criteria rather than bundled trade-offs. This unbundling enables application-specific platform selection and challenges incumbent comprehensive solutions.
Long-read sequencing platforms is absorbing complex structural variant analysis previously requiring orthogonal validation methods. Clinical cytogenetics laboratories are adopting these systems for constitutional disorder diagnosis, compressing the diagnostic odyssey timeline from months to weeks while reducing confirmatory testing burden.
EMA's evolving genomic-based therapeutics framework is reshaping parallel submission strategies for pharmaceutical developers. Companies now design clinical trials with simultaneous regulatory dataset construction for both European and United States markets, accelerating cross-border therapeutic approval timelines for targeted oncology indications.
Research procurement patterns are gravitating toward bundled reagent-instrument service contracts that internalize operational risk. Academic medical centers in the United States increasingly favor all-inclusive per-sample pricing over capital-intensive equipment ownership, transferring maintenance and upgrade obligations to platform vendors.
Global Genomics Market Segmentation
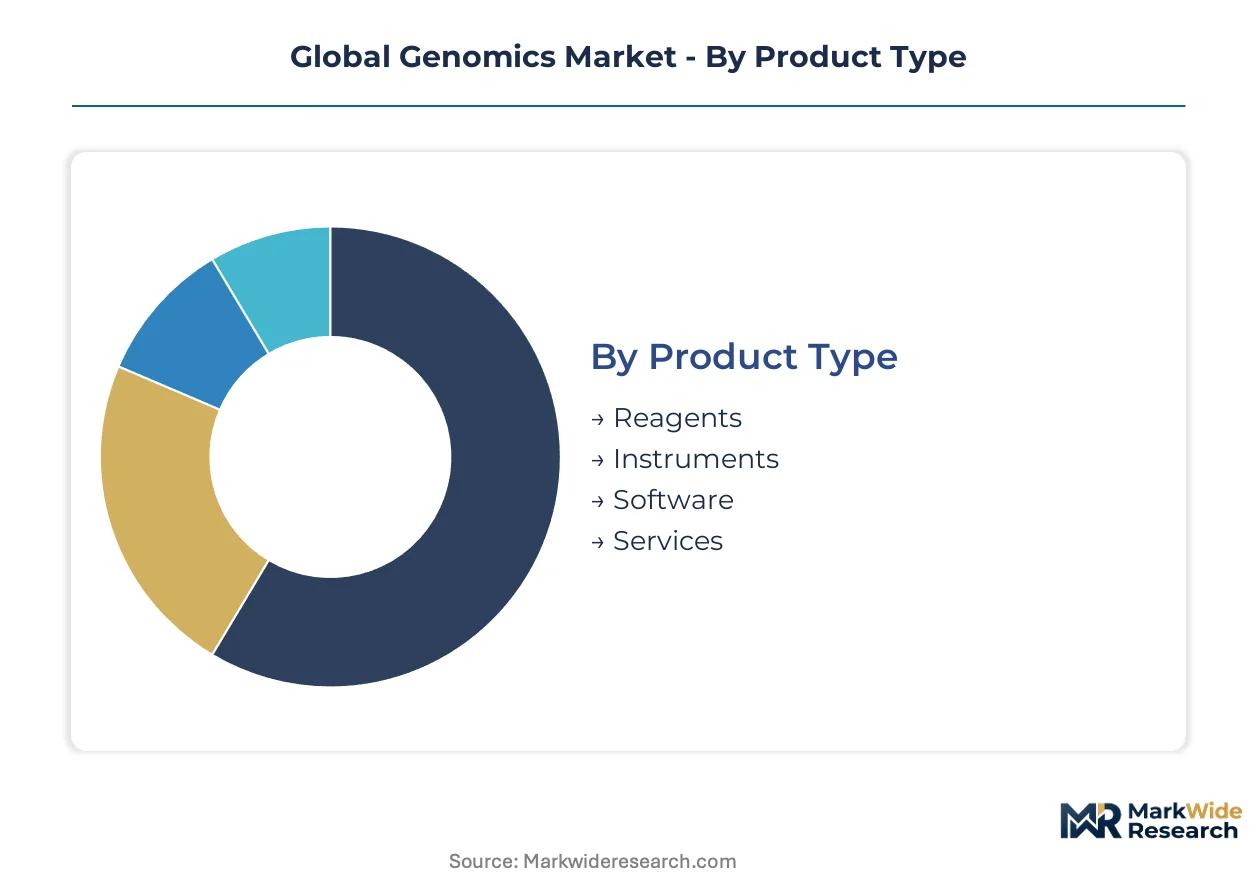
Genomics market segmentation reveals divergent margin structures across hardware, consumables, and analytical services. Platform vendors calibrate portfolio emphasis based on recurring revenue capture versus capital equipment cycles.
Product Type:
Reagents command superior recurring margins through per-run consumption models, while instruments anchor customer relationships despite lumpy revenue recognition.
- Reagents:Proprietary consumable formulations generate sustained attach rates to installed sequencing platforms. Pharmaceutical companies in the United States absorb the highest per-run chemical costs for clinical-grade nucleic acid preparation and library construction.
- Instruments:Capital equipment placements establish multi-year vendor relationships through embedded software ecosystems and validation protocols. Academic medical centers concentrate procurement in high-throughput systems for population-scale research initiatives.
- Software:Cloud-based analytical pipelines monetize recurring subscriptions for variant interpretation and workflow management.
- Services:Outsourced bioinformatics and sequencing operations expand most quickly as pharmaceutical developers compress internal R&D infrastructure.
Today's leader: Reagents. Tomorrow's challenger: Services.
End User:
Customer archetypes span capital-constrained academic settings through cash-generating diagnostic operations, each demanding distinct pricing and support architectures.
- Research Institutes:Grant-funded procurement favors modular instrument configurations with upgrade pathways. European molecular biology centers prioritize open-source analytical compatibility over proprietary software lock-in.
- Pharmaceutical Companies:Integrated genomic profiling now embeds into early-stage therapeutic pipelines under FDA companion diagnostics guidance. Parallel EMA submission requirements shape clinical trial dataset construction for cross-border oncology approvals.
- Diagnostic Laboratories:Clinical validation burdens and reimbursement complexity constrain operational scaling for rare disease testing.
- Academic Institutions:Shared core facility models distribute capital costs across departmental user bases.
Pharmaceutical outsourcing is accelerating fastest. Academic core facilities face the steepest budget pressure.
Technology:
Performance dimensions fragment across read length, accuracy, speed, and portability, enabling application-specific platform selection.
- Next-Generation Sequencing:Short-read platforms dominate clinical diagnostic volume through established validation libraries and reimbursement codes. China's NMPA pathway streamlining redirects manufacturing investment toward domestic certification compliance for high-throughput systems.
- Sanger Sequencing:First-generation methods retain niche utility for targeted variant confirmation and forensic applications.
- PCR:Amplification-based detection maintains cost advantages for single-gene clinical assays with rapid turnaround requirements.
- Microarrays:Genotyping arrays sustain agricultural trait selection and consumer ancestry markets despite sequencing displacement in clinical settings.
Short-read systems anchor current revenue. Long-read platforms are gaining structural variant resolution capabilities.
Application:
Commercial prioritization shifts from research tools toward reimbursable clinical outputs and regulated therapeutic development.
- Drug Discovery:Genomic target identification and patient stratification compress development timelines for precision oncology programs. Biotech clusters in Boston and San Francisco drive analytical service demand for preclinical pharmacogenomic studies.
- Personalized Medicine:Companion diagnostic integration requires parallel regulatory validation across FDA and EMA jurisdictions.
- Genetic Testing:Reimbursement variability and data localization mandates fragment direct-to-consumer and clinical testing business models.
- Agriculture:Trait selection and pathogen surveillance extend genomic applications into field-deployable environmental monitoring.
Therapeutic development captures premium pricing. Agricultural surveillance offers volume expansion through portable sequencing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States absorbs higher per-run sequencing costs than Germany, yet both concentrate manufacturing investment toward regulatory compliance within their respective jurisdictions. China's NMPA pathway streamlining redirects domestic certification priorities, while India's diagnostic infrastructure remains underpenetrated outside major metros.
United States
Academic medical centers in Boston and San Francisco drive sequencing volume for population-scale research initiatives. FDA companion diagnostics guidance accelerates clinical validation requirements for pharmaceutical developers. Biotech clusters across Massachusetts and California compress preclinical pharmacogenomic study timelines through integrated genomic profiling.
China
Domestic sequencing instrument registration accelerates under streamlined NMPA pathways. The country's national pharmaceutical regulator redirects manufacturing investment toward local certification compliance. Yangtze River Delta biomanufacturing hubs absorb high-throughput system placements for clinical-grade nucleic acid preparation.
Germany
European molecular biology centers prioritize open-source analytical compatibility over proprietary software lock-in. EMA's evolving framework for genomic-based therapeutics influences parallel submission strategies across jurisdictions. Bavarian research institutes favor modular instrument configurations with upgrade pathways for grant-funded procurement.
India
Tier-two cities present whitespace for decentralized sequencing service models in molecular testing infrastructure. CDSCO regulatory harmonization efforts accelerate diagnostic laboratory scaling for rare disease testing. Maharashtra and Karnataka host emerging biotech clusters where pharmaceutical outsourcing concentrates analytical demand.
United Kingdom
London-based genomic medicine centers integrate long-read platforms for constitutional disorder diagnosis. The national health service procurement patterns gravitate toward bundled reagent-instrument service contracts. Cambridge-Oxford research corridors sustain shared core facility models distributing capital costs across departmental user bases.
Global Genomics Market Vendor Landscape
Top-tier vendors anchor the sequencing platform tier, while specialized bioinformatics service providers occupy fragmented niches below. The market structure consolidates around instrument-reagent bundles that raise switching costs for research institutes. Strategic archetypes include integrated platform vendors, consumable specialists, and cloud-based analytical service operators. Dominant competitive moves encompass strategic partnerships for bioinformatics pipeline integration and geographic expansion into underpenetrated diagnostic markets.
Among North American platform vendors, Illumina, Inc. and Thermo Fisher Scientific, Inc. exemplify the integrated instrumentation archetype through embedded software ecosystems. Oxford Nanopore Technologies occupies a position within the portable sequencing segment, representing real-time field-deployable capabilities. These three companies anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Thermo Fisher Scientific, Inc. |
| F. Hoffmann-La Roche Ltd. |
| Danaher Corporation |
| Agilent Technologies |
| QIAGEN N.V. |
| BGI Genomics |
| Oxford Nanopore Technologies |
| PacBio |
| Others |
Supply Flow & Price Mechanics
Specialized nucleic acid reagent spot indices in the United States and Germany cascade through three-tier pricing structures, compressing margins for mid-grade consumable suppliers while amplifying premium capture for validated clinical-grade formulations. Pharmaceutical developers in Boston and San Francisco absorb the highest per-run chemical costs, transferring cost volatility downstream through bundled service contracts.
Pricing Analysis
Capacity additions in China's Yangtze River Delta biomanufacturing hubs are reshaping price floors for high-throughput sequencing reagents. The dominant pricing model stratifies across premium clinical-grade, standard research-grade, and economy bulk reagent tiers, with FDA validation status and ISO 13485 certification driving the steepest differentiation. Pricing pressure intensifies in the standard tier as domestic Chinese manufacturers achieve NMPA registration parity. Academic medical centers exhibit highest price sensitivity, while pharmaceutical companies prioritize assay consistency over unit cost.
Supply Chain Analysis
Freight cost volatility for temperature-controlled nucleic acid shipments between the United States, Germany, and China compresses margin buffers for just-in-time reagent replenishment models. Manufacturing concentration centers on Massachusetts and California for instrument final assembly, with Bavaria hosting precision optical component fabrication and the Yangtze River Delta absorbing high-throughput system integration. The supply chain draws from single-source vulnerabilities in specialized polymerase enzyme production. Distribution runs through authorized distributor networks for research institutes and direct vendor partnerships for pharmaceutical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Genomics Market represents a late-cycle quality story as therapeutic developers prioritize companion diagnostic-grade analytical specifications over throughput volume. Precision oncology pipelines now mandate clinical-grade validation from early discovery phases.
For Market Incumbents: To counter portable sequencing platform encroachment into field surveillance applications, Illumina and Thermo Fisher Scientific must deepen backward integration into proprietary reagent enzyme manufacturing while accelerating cloud-based analysis pipeline subscription retention through embedded AI-variant interpretation tools. For New Entrants and Emerging Players: Begin with decentralized sequencing service models in India's tier-two cities, where CDSCO regulatory harmonization and underpenetrated molecular testing infrastructure create whitespace. Target diagnostic laboratories in Maharashtra and Karnataka through per-sample pricing contracts that transfer capital equipment risk from cash-constrained operators. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized bioinformatics service providers possessing FDA-validated rare disease interpretation pipelines. Long-term viability hinges on multi-jurisdiction regulatory dataset construction capabilities. Watch for inflection signals in EMA parallel submission volume for genomic-based therapeutics.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Regulatory Submission | FDA and EMA parallel filings compress oncology therapeutic approval timelines across jurisdictions. |
| Cloud-Based Analysis Platform Integration | Illumina's subscription bioinformatics tools deepen customer retention beyond instrument placement cycles. |
| Long-Read Sequencing Technology Licensing | PacBio and Oxford Nanopore structural variant resolution displaces orthogonal cytogenetic validation methods. |
| Reagent Manufacturing Scale-Up | Proprietary consumable production in China's Yangtze River Delta redirects NMPA certification investment. |
| AI-Variant Interpretation Partnership | Machine learning classification tools reduce rare disease diagnostic turnaround from months to weeks. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads at companion diagnostic divisions, hospital procurement managers in academic medical centers, and bioinformatics service provider technical directors. Secondary validation drew from FDA 510(k) filings, EMA scientific advice letters, ClinicalTrials.gov genomic biomarker listings, and NMPA medical device registration databases. Bottom-up sequencing platform shipment analysis and top-down pharmaceutical R&D spend allocation were cross-referenced for triangulation.
Segment-weighting approaches distributed value estimates across product type, end user, technology, and application dimensions, with regional regulatory cluster intensity modeled as an overlay factor. CAGRs were derived from instrument placement trajectories, reagent attach rate assumptions, and service outsourcing velocity across the projection horizon. Forecast inputs incorporated NMPA pathway streamlining timelines, EMA genomic therapeutics framework evolution, and AI-variant interpretation adoption curves in clinical diagnostic laboratories.
Several conditions sit outside the modeled scope, including unforeseen regulatory data-localization mandates, novel sequencing chemistry disruptions, and pharmaceutical pipeline cancellations affecting companion diagnostic demand. Forecasts reflect documented assumptions about regulatory harmonization progress and reagent supply concentration stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Genetic Material Market
Genomics
DNA Gene Chip Market
Genomics
Mrna Sequencing Market
Genomics
DNA Sequencing Market
Genomics
US Direct-To-Consumer Genetic Testing Market
Genomics
North America DNA Sequencing Products Market
Genomics
China Genetic Testing Market
Genomics
Next-Generation Sequencing (NGS) Workflow Quality Control Test Kits and Instruments Market
Genomics
Japan Next Generation Sequencing Market
Genomics
Latin America Gene Expression Market
Genomics
RNA Transcriptome Profiling Test Market
Genomics
Next Generation Genomics Market
Genomics
Reproductive Genetics Market
Genomics
Global Genotyping Assay Market
Genomics
Europe Gene Synthesis (Research Use) Market
Genomics
Digital Genome Market