
 Next Generation Sequencing Market | 2026-2036
Next Generation Sequencing Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Sequencing Market Intelligence
Cloud-native bioinformatics pipelines is reconfiguring how sequencing data is processed, stored, and delivered across distributed research networks. Illumina Inc. leverages its installed base of sequencing instruments to sustain recurring consumables revenue. Thermo Fisher Scientific Inc. anchors its position through integrated sample-to-answer workflows spanning extraction through analysis. Oxford Nanopore Technologies differentiates via portable, real-time sequencing devices that compete with centralized lab systems.
Next generation sequencing encompasses massively parallel DNA or RNA analysis technologies that generate gigabase-scale read outputs through clonal amplification or single-molecule detection chemistries, with primary commercial purpose spanning variant discovery, gene expression profiling, and microbial identification. Consumables capture the dominant margin pool due to per-run reagent pull-through on installed instruments, while nanopore sequencing represents the fastest-expanding technology segment driven by field-deployable use cases. Oncology commands the largest application share as tumor profiling becomes standard of care, whereas personalized medicine applications are deepening as pharmacogenomic panels expand reimbursement coverage.
FDA oversight of laboratory-developed tests and companion diagnostics shapes product development timelines and clinical market access requirements for NGS platforms in the United States. EMA's In Vitro Diagnostic Regulation and the EU AI Act create layered compliance obligations for algorithm-driven variant interpretation software deployed in European clinical laboratories. China's NMPA medical device classification pathway for gene sequencing instruments adds a third jurisdictional gate. Stakeholders must monitor evolving reimbursement determinations for multi-gene panel tests across these three regulatory domains.
Market Dynamics
Cloud-native bioinformatics pipelines are compressing turnaround times from weeks to hours, forcing incumbent platform vendors to rearchitect software stacks around distributed computing rather than on-premise servers.
Growth Catalysts
- Companion diagnostic regulatory streamlining:FDA and EMA guidelines for tumor profiling tests accelerate clinical validation timelines and expand reimbursable indications for multi-gene panels.
- Liquid biopsy clinical integration:Circulating tumor DNA workflows are displacing repeat tissue biopsies in oncology monitoring, driving consumables pull-through on existing sequencers.
- China NMPA pathway maturation:Domestic gene sequencing instrument approvals under Class III medical device rules enable local manufacturing scale-up and hospital procurement.
Market Restraints
- Reagent supply concentration:Specialty polymerases and modified nucleotides source predominantly from single-region chemical suppliers, exposing workflows to input volatility.
- EU AI Act algorithmic scrutiny:Variant interpretation software deployed in European clinical laboratories faces layered validation requirements that extend product development cycles.
- Centralized lab infrastructure lock-in:High-throughput sequencers require climate-controlled facilities and specialized technicians, limiting deployment to capital-rich institutions.
Strategic Opportunities
- Point-of-care infectious disease surveillance:Portable nanopore devices enable field-deployable pathogen identification in rural India and sub-Saharan Africa without cold-chain logistics.
- Pharmacogenomic panel expansion:Payer reimbursement for preemptive genotyping in cardiology and psychiatry creates new test menu categories beyond oncology.
- ISO 15189 laboratory accreditation mandates:Quality management system requirements in emerging markets drive demand for integrated sample-to-answer workflow validation services.
Industry Challenges
- Bioinformatics talent scarcity:Variant curation and pipeline development require cross-trained computational biologists, with acute shortages in clinical laboratory settings.
- Legacy LIMS integration friction:Cloud-native sequencing platforms face interoperability hurdles with hospital information systems built on decade-old architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Sequencing Market |
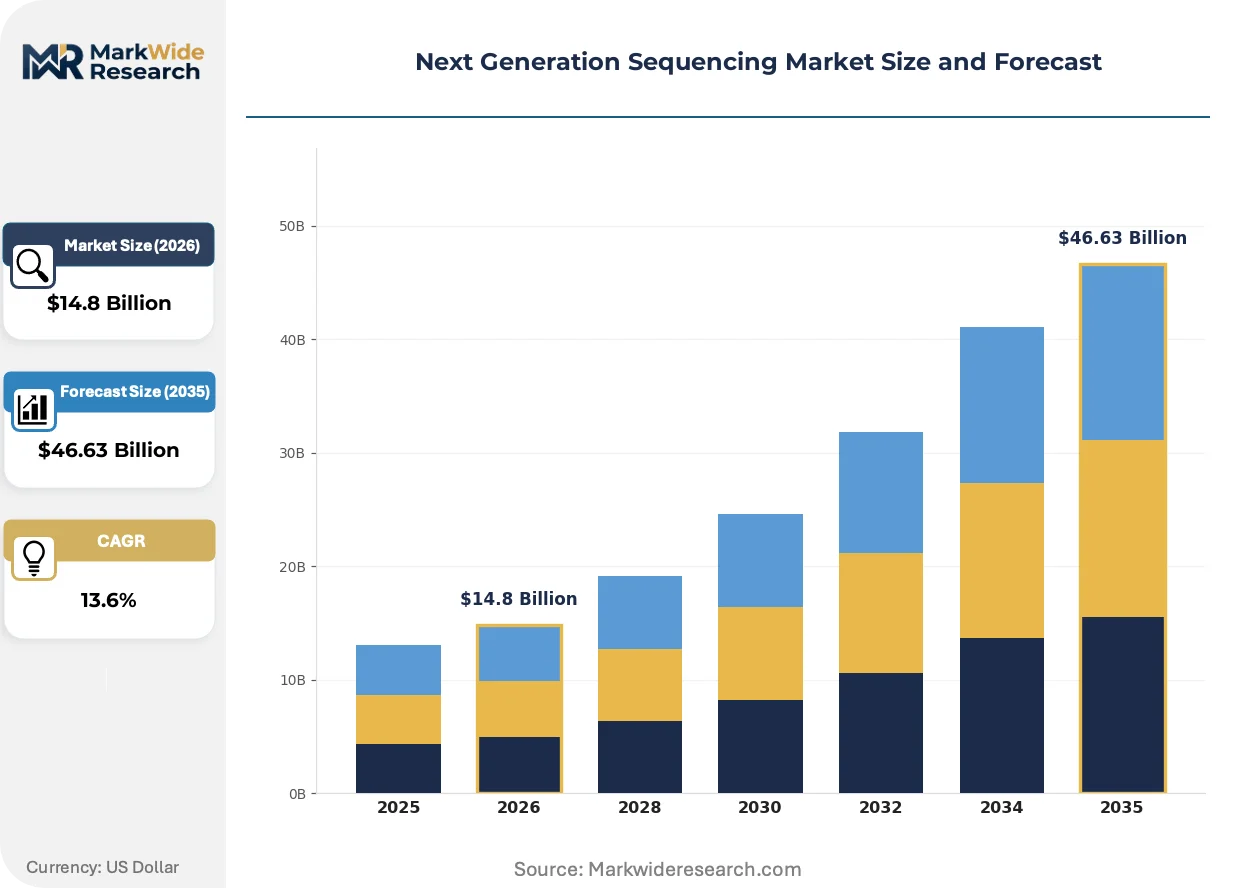
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $46.63 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instruments, Consumables, Software, Services Technology: Sequencing by Synthesis, Ion Semiconductor Sequencing, Single-Molecule Real-Time Sequencing, Nanopore Sequencing Application: Oncology, Infectious Diseases, Personalized Medicine, Reproductive Health End User: Clinical Laboratories, Research Institutes, Pharma Companies, Academic Institutions |
| Companies Covered | Illumina Inc., Thermo Fisher Scientific Inc., F. Hoffmann-La Roche Ltd., QIAGEN, PacBio, Oxford Nanopore Technologies, Agilent Technologies Inc., BGI Genomics, Revvity Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Sequencing Market Strategic Shifts & Innovations
Real-time sequencing architectures and AI-driven variant calling are compressing the traditional boundaries between sample acquisition, data generation, and clinical decision support.
Long-read sequencing chemistry is collapsing the distinction between structural variant detection and single-nucleotide resolution, enabling simultaneous phasing and copy-number analysis in single runs. Clinical cytogenetics laboratories in Germany and the United States are migrating from microarray-based workflows to nanopore and single-molecule real-time platforms for rare disease diagnosis. This transition is collapsing the equipment footprint required for comprehensive genome analysis from multiple instruments to single devices.
EMA's In Vitro Diagnostic Regulation implementation is forcing sequencing assay developers to revalidate existing products under new conformity assessment procedures. Manufacturers must now compile clinical evidence packages for algorithmic components previously classified as laboratory-developed tests. Oncology companion diagnostic developers face the steepest compliance burden, with several panels undergoing notified body review for CE marking transition.
Hospital procurement committees are unbundling sequencing instrument purchases from mandatory multi-year reagent contracts, shifting vendor selection criteria toward per-run cost transparency. Academic medical centers in the United States and university hospitals in China are leading this transition, negotiating spot pricing for consumables rather than locked-in minimum commitments. This behavior compresses supplier margin structures and accelerates competitive bidding for high-volume accounts.
Next Generation Sequencing Market Segmentation
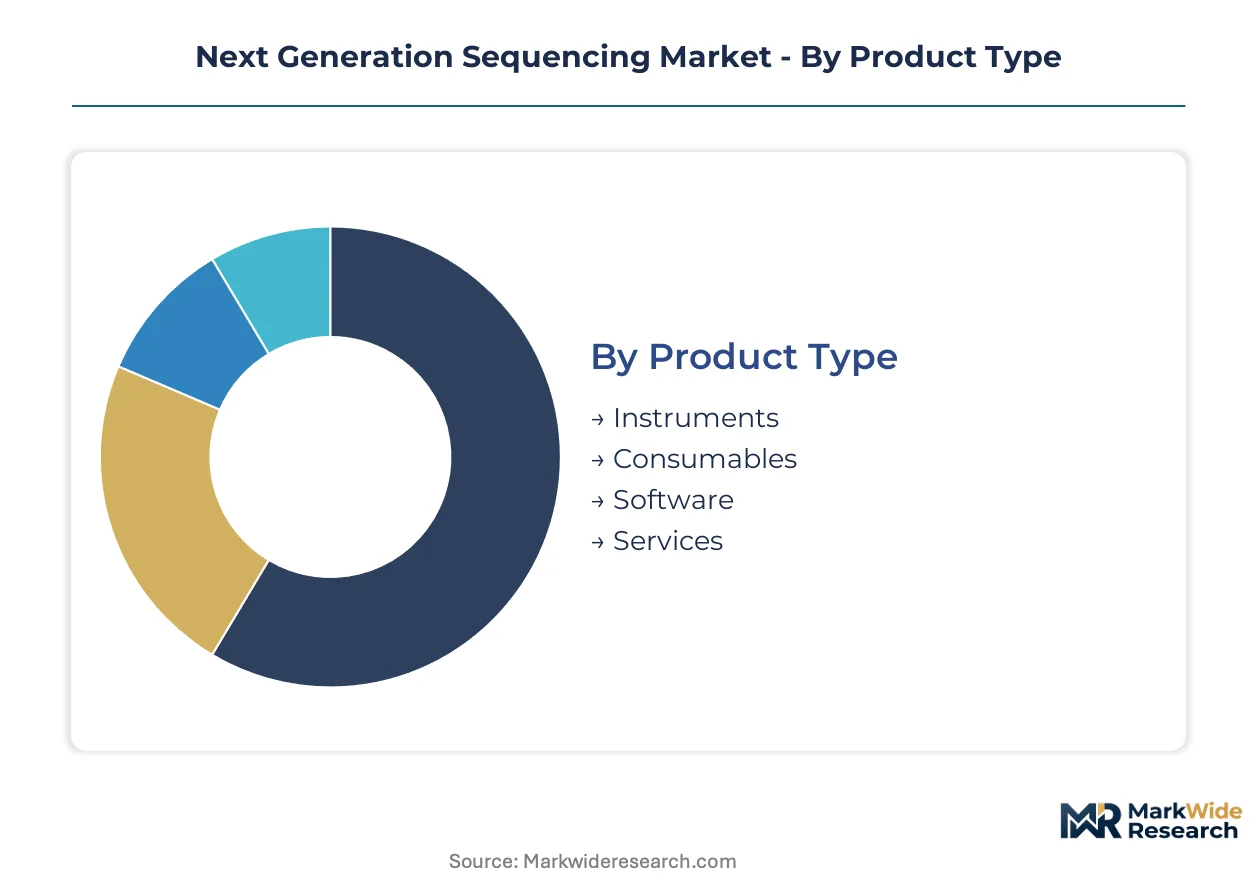
Segmentation in next generation sequencing reveals how value pools concentrate across the technology stack. Product mix, chemistry platforms, clinical applications, and customer archetypes each shape procurement patterns and margin structures differently.
Product Type:
The use-case spectrum spans capital equipment deployment at academic medical centers to recurring reagent pull-through in high-throughput clinical labs.
- Consumables:Reagent kits, flow cells, and library preparation chemistry generate recurring revenue tied to instrument utilization rates. Clinical laboratories in the United States and Germany drive volume through oncology panel testing, with per-run chemistry costs dominating total cost of ownership calculations.
- Instruments:Sequencing platforms range from benchtop systems for targeted panels to production-scale machines for population genomics. China's NMPA Class III medical device pathway is accelerating hospital procurement of domestically manufactured units.
- Software:Bioinformatics pipelines for variant calling and clinical interpretation deploy across cloud-native and on-premise architectures. EMA's EU AI Act is extending validation requirements to algorithmic components previously treated as laboratory-developed tests.
- Services:Contract sequencing and data analysis offerings address capacity constraints at mid-sized research institutes. ISO 15189 accreditation mandates in emerging markets are expanding demand for integrated workflow validation support.
Established volume favors consumables; emerging adoption favors software.
Technology:
Cost tier stratification separates high-throughput centralized systems from portable field-deployable devices.
- Sequencing by Synthesis:Illumina's reversible terminator chemistry dominates installed base metrics and clinical validation literature. United States academic medical centers and German university hospitals anchor demand through large-scale genome center investments.
- Nanopore Sequencing:Oxford Nanopore's single-molecule detection enables real-time analysis without amplification bias. Field surveillance programs in rural India and sub-Saharan Africa are climbing the fastest for infectious disease identification use cases.
- Ion Semiconductor Sequencing:Thermo Fisher's semiconductor detection chemistry targets rapid turnaround clinical workflows. Smaller footprint instruments suit hospital pathology departments with limited climate-controlled laboratory space.
- Single-Molecule Real-Time Sequencing:Pacific Biosciences' zero-mode waveguide technology delivers long-read capabilities for structural variant resolution. Rare disease diagnostic laboratories are migrating from microarray workflows to this platform for comprehensive genome analysis.
High-throughput centralization favors sequencing by synthesis; distributed access favors nanopore sequencing.
Application:
Customer type differentiation separates reimbursed clinical testing from grant-funded research discovery.
- Oncology:Tumor profiling for therapy selection and resistance monitoring represents the largest revenue concentration. FDA and EMA companion diagnostic guidelines are streamlining regulatory pathways for multi-gene panels in solid malignancies.
- Personalized Medicine:Pharmacogenomic testing for cardiology and psychiatry indications is expanding beyond oncology. United States payer reimbursement decisions for preemptive genotyping are creating new test menu categories.
- Infectious Diseases:Pathogen identification and antimicrobial resistance profiling deploy in both clinical and public health surveillance contexts. China's CDC network and hospital microbiology laboratories are scaling metagenomic sequencing for outbreak investigation.
- Reproductive Health:Non-invasive prenatal testing and carrier screening utilize cell-free DNA analysis workflows. Laboratory accreditation requirements vary across United States state-level regulations and European national health system frameworks.
Reimbursement maturity favors oncology; test menu expansion favors personalized medicine.
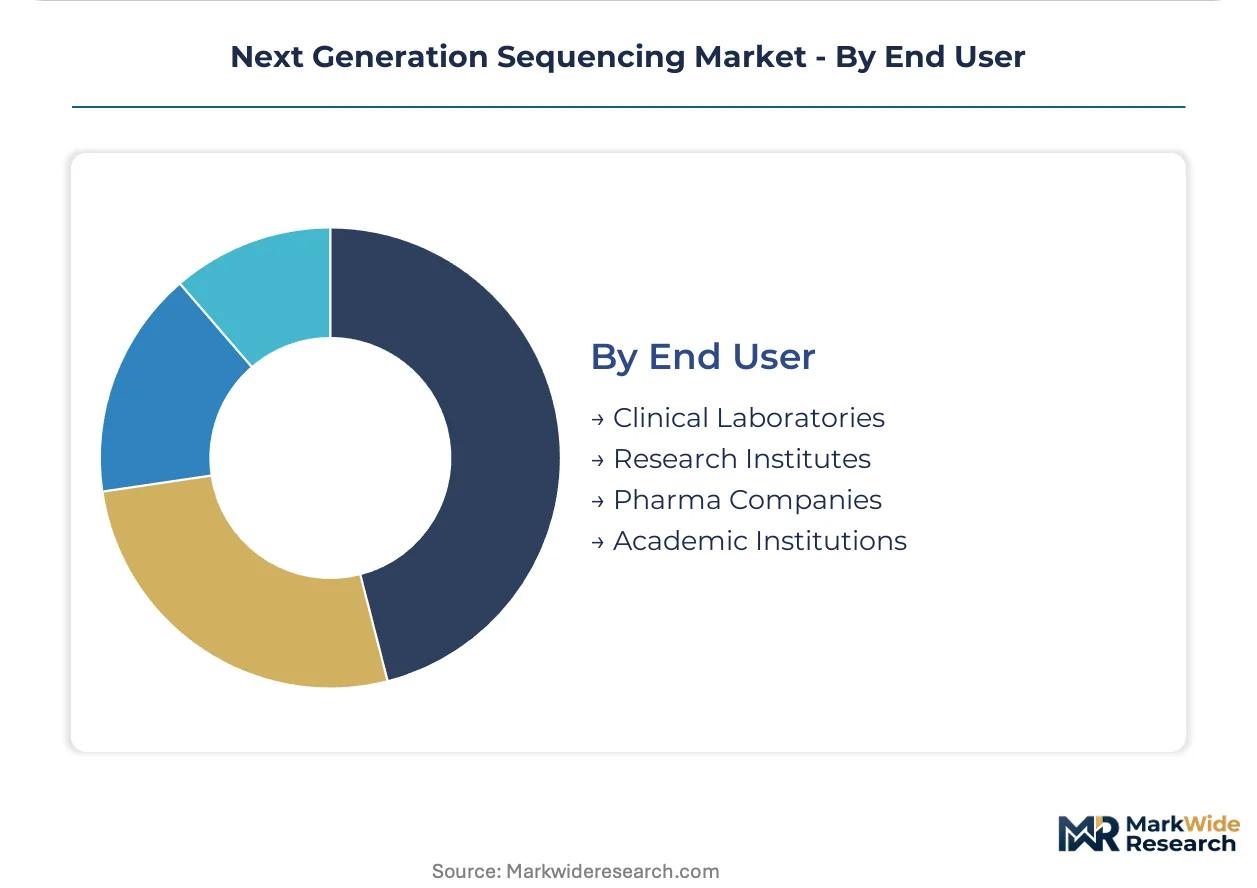
End User:
Supply concentration clusters around institutions with capital access and technical staffing depth.
- Clinical Laboratories:Hospital-based and independent reference labs perform reimbursed diagnostic testing under regulatory oversight. China's NMPA medical device classification pathway enables domestic instrument procurement at provincial hospital networks.
- Research Institutes:Government-funded genome centers and disease-focused research consortia drive technology adoption for discovery applications. Germany's Max Planck Institutes and United States NIH-funded centers anchor demand for highest-throughput platforms.
- Pharma Companies:Biopharmaceutical developers utilize sequencing for biomarker discovery and patient stratification in clinical trials. Companion diagnostic co-development agreements with platform vendors are restructuring R&D outsourcing patterns.
- Academic Institutions:University core facilities balance service provision to multiple principal investigators against internal research priorities. Procurement committees are unbundling instrument purchases from mandatory multi-year reagent contracts.
Regulatory integration favors clinical laboratories; technology access favors academic institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports sequencing instruments and consumables to hospital networks across Southeast Asia and the Middle East, while the United States ships high-throughput platforms to genome centers in Europe and Australia. Germany serves as the primary European hub for clinical validation studies and regulatory reference testing.
United States
FDA companion diagnostic guidelines accelerate multi-gene panel approvals for oncology, while academic medical centers in Boston and the San Francisco Bay Area deploy production-scale sequencers for population genomics research. Hospital procurement committees unbundle instrument purchases from mandatory reagent contracts, shifting vendor selection toward per-run cost transparency.
China
NMPA Class III medical device rules enable domestic gene sequencing instrument manufacturing scale-up at provincial hospital networks. The country's dual carbon goals drive energy-efficient platform development in the Yangtze River Delta sequencing cluster. Shenzhen and Shanghai anchor demand for both clinical diagnostics and agricultural genomics applications.
Germany
EMA's In Vitro Diagnostic Regulation forces sequencing assay developers to revalidate algorithmic components under new conformity assessment procedures. Munich and Heidelberg host rare disease diagnostic laboratories migrating from microarray workflows to long-read sequencing platforms. The country's national pharmaceutical regulator coordinates with notified bodies on companion diagnostic CE marking transitions.
India
CDSCO medical device rules and ISO 15189 laboratory accreditation mandates expand demand for integrated workflow validation services in emerging markets. Maharashtra and Karnataka host contract research organizations building sequencing capacity for pharmacogenomic panel development. Field surveillance programs deploy portable devices for infectious disease identification in rural districts without cold-chain logistics.
United Kingdom
Genomics England and NHS diagnostic networks drive standardized tumor profiling adoption across cancer centers. London and Cambridge anchor biopharmaceutical sequencing demand for biomarker discovery and patient stratification in clinical trials. The country's national health system framework shapes reimbursement determinations for cell-free DNA analysis workflows.
Next Generation Sequencing Market Key Industry Players
Channel-controlling players compete with product-specialist players across instrument, consumables, and software layers. The market exhibits tiered concentration with dominant platform vendors anchoring high-throughput clinical segments and emerging specialists capturing field-deployable applications. Strategic archetypes include installed-base defenders leveraging recurring reagent revenue, workflow integrators spanning sample-to-answer solutions, and portability-first challengers targeting distributed access. Competitive moves center on cloud-native bioinformatics stack rearchitecture and companion diagnostic co-development agreements with pharmaceutical developers.
Among United States-based platform developers, Illumina Inc. and Thermo Fisher Scientific Inc. occupy positions as installed-base anchors with extensive clinical validation literature. Oxford Nanopore Technologies, a United Kingdom-based specialist, exemplifies the portability-first archetype through real-time single-molecule detection devices. These three entities represent distinct strategic vectors: reagent pull-through optimization, integrated workflow control, and field-deployable access expansion.
| Leading Market Players |
|---|
| Illumina Inc. |
| Thermo Fisher Scientific Inc. |
| F. Hoffmann-La Roche Ltd. |
| QIAGEN |
| PacBio |
| Oxford Nanopore Technologies |
| Agilent Technologies Inc. |
| BGI Genomics |
| Revvity Inc. |
| Others |
Cost & Logistics Intelligence
Undercapacity in long-read sequencing consumables drives supplier allocation decisions and sustains premium pricing for zero-mode waveguide reagent kits. This utilization imbalance concentrates pricing power with Pacific Biosciences and Oxford Nanopore Technologies while compressing margins for legacy short-read chemistry providers.
Pricing Analysis
Current-generation sequencing-by-synthesis platforms command 40-60% per-run cost premiums over prior-generation capillary electrophoresis workflows, while next-generation nanopore field-deployable devices price at 3-5x standard benchtop systems. The dominant pricing structure runs through tiered reagent contracts with minimum volume commitments, though hospital procurement committees are shifting toward spot pricing. Price differentiation rests on clinical validation depth and FDA companion diagnostic certification tier, with oncology panels sustaining premiums while research-grade chemistry faces compression. Pricing pressure stems from China's NMPA accelerating domestic instrument approvals and enabling provincial hospital networks to negotiate aggressively. Academic medical centers exhibit highest price sensitivity due to grant-funded budget constraints, whereas pharmaceutical companion diagnostic co-development agreements show lowest sensitivity.
Supply Chain Analysis
Export control regimes limiting semiconductor manufacturing equipment flows constrain specialty CMOS sensor supply for ion semiconductor sequencers and waveguide array fabrication for single-molecule real-time platforms. Geographic supply concentration clusters in the United States for modified nucleotide chemistry, China for flow cell manufacturing substrates, and Germany for precision optical components. Raw material dependencies include phosphoramidite nucleosides, fluorophore-labeled terminators, and nanopore membrane materials. Single-source vulnerability runs through specialty polymerase suppliers concentrated in single-region chemical production zones. Distribution runs through direct sales forces for high-throughput clinical instruments and channel partners for portable field-deployable devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to hospital capital expenditure normalization following pandemic-era deferred instrument procurement. The recovery justifies through China's NMPA Class III medical device approval acceleration enabling provincial hospital network expansion.
For Market Incumbents: Pre-empt margin erosion by securing backward integration into modified nucleotide chemistry production and establishing captive supply agreements for fluorophore-labeled terminators. Defensive consolidation through companion diagnostic co-development partnerships with oncology pharmaceutical developers locks in multi-year reagent pull-through. Threat from China's domestic sequencing instrument manufacturers intensifies pricing pressure in Asia-Pacific procurement tenders.
For New Entrants and Emerging Players: Pursue white-space expansion in pharmacogenomic panel development for cardiology and psychiatry indications where reimbursement coverage is deepening but platform competition remains thin. Rural India and sub-Saharan Africa present the most penetrable geographies for field-deployable infectious disease surveillance. Go-to-market angle centers on ISO 15189 workflow validation bundling with instrument placement.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring revenue consumables play because clinical laboratory instrument installed bases generate predictable reagent pull-through with 70-80% gross margin profiles. Acquisition target archetype: cloud-native bioinformatics pipeline developers with EMA EU AI Act compliance infrastructure. Signal to watch is FDA laboratory-developed test enforcement discretion shifts affecting algorithmic variant interpretation software classification.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Locks in multi-year reagent contracts with pharmaceutical developers pursuing FDA tumor profiling approvals. |
| Cloud-Native Bioinformatics Stack Migration | Enables distributed computing architectures that compress turnaround times from weeks to hours for clinical laboratories. |
| ISO 15189 Workflow Validation Services | Captures emerging market demand for quality management system compliance in hospital-based diagnostic networks. |
| Domestic Manufacturing Scale-Up | Aligns with China's NMPA Class III medical device rules enabling provincial hospital procurement of locally produced instruments. |
| Long-Read Chemistry Platform Transition | Addresses rare disease diagnostic laboratory migration from microarray workflows to structural variant resolution capabilities. |
Research Approach
Operator-level perspectives from clinical laboratory directors, hospital procurement committee members, regulatory affairs specialists at sequencing platform vendors, and companion diagnostic development leads anchored the qualitative base. These primary insights combined with secondary validation drawn from FDA 510(k) and PMA filings, EMA In Vitro Diagnostic Regulation guidance documents, NMPA Class III medical device approval databases, and hospital GPO contract disclosures. Bottom-up instrument shipment tracking and top-down healthcare expenditure modeling provided triangulation across the analysis window.
Scenario bracketing around regulatory approval timelines and reimbursement coverage expansion shaped the analytical framework. Segmentation dimensions modeled include technology chemistry platforms, clinical application areas, end-user institution types, and regional regulatory clusters. CAGRs derived from instrument installed base projections coupled with per-run consumables utilization assumptions. Industry-specific forecast inputs incorporated companion diagnostic approval velocity and cloud-native pipeline adoption curves in academic medical centers.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles or biopharmaceutical R&D outsourcing intensity would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway maturation and reimbursement determination timelines. Material shifts in FDA laboratory-developed test enforcement posture or EMA EU AI Act implementation stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Human Genetics Market
Genomics
Global Gene Expression Market
Genomics
Global Metagenomics Market
Genomics
DNA Gene Chip Market
Genomics
DNA Mass Ladder Market
Genomics
Genetic Testing Panels Market
Genomics
Global Blockchain in Genomic Data Management Market
Genomics
Whole Plasmid Sequencing Market
Genomics
SNP Genotyping Market
Genomics
Microbiome Sequencing Market
Genomics
Microarray Scanners Market
Genomics
North America Whole Exome Sequencing Market
Genomics
Cancer Biomarkers Market
Genomics
Middle East and Africa Genetic Testing Market
Genomics
NGS Automation Market
Genomics
Sequencing Electrophoresis Systems Market