
 Non-Hospital-Based Point-Of-Care Diagnostic Products Market | 2026-2036
Non-Hospital-Based Point-Of-Care Diagnostic Products Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Hospital-Based Point-Of-Care Diagnostic Products Market Analytics
The shortage of certified medical technologists in clinical laboratories is unwinding traditional diagnostic workflows and pushing specimen collection toward decentralized sites. Abbott Laboratories leverages its vertically integrated manufacturing of lateral-flow cassettes to sustain cost leadership in retail channels. Siemens Healthcare GmbH anchors European demand through its installed base of benchtop analyzers repurposed for urgent care deployment. Bio-Rad Laboratories differentiates via enzymatic assay precision that meets regulatory thresholds for pharmacist-operated testing.
Non-hospital-based point-of-care diagnostic products comprise portable or handheld analytical devices that detect biomarkers from capillary blood, saliva, or nasal swabs using optical sensors, enzymatic reactions, or microfluidic channels, typically delivering quantitative or qualitative results within three to fifteen minutes for immediate clinical decision-making outside centralized laboratory infrastructure. Blood glucose monitors occupy the most mature product tier with compressed margins and heavy private-label competition, while microfluidics-based infectious disease tests represent the fastest-expanding technology segment as manufacturers achieve multiplexed pathogen detection in credit-card-sized cartridges. Home care dominates end-user volume through direct-to-consumer e-commerce channels, though urgent care centers capture disproportionate value per test due to higher reimbursement rates for supervised administration.
FDA CLIA-waived classification determines which devices qualify for operation by non-laboratory personnel in pharmacies and mobile clinics, directly constraining the addressable market for each manufacturer's menu. The European Union's In Vitro Diagnostic Regulation (IVDR) imposes stricter clinical evidence requirements than its predecessor directive, forcing smaller manufacturers to abandon CE-marked products or consolidate under larger entities. Stakeholders must monitor evolving state-level scope-of-practice laws that determine whether pharmacists in jurisdictions like California, Florida, and New York may independently order and interpret rapid diagnostic tests without physician oversight.
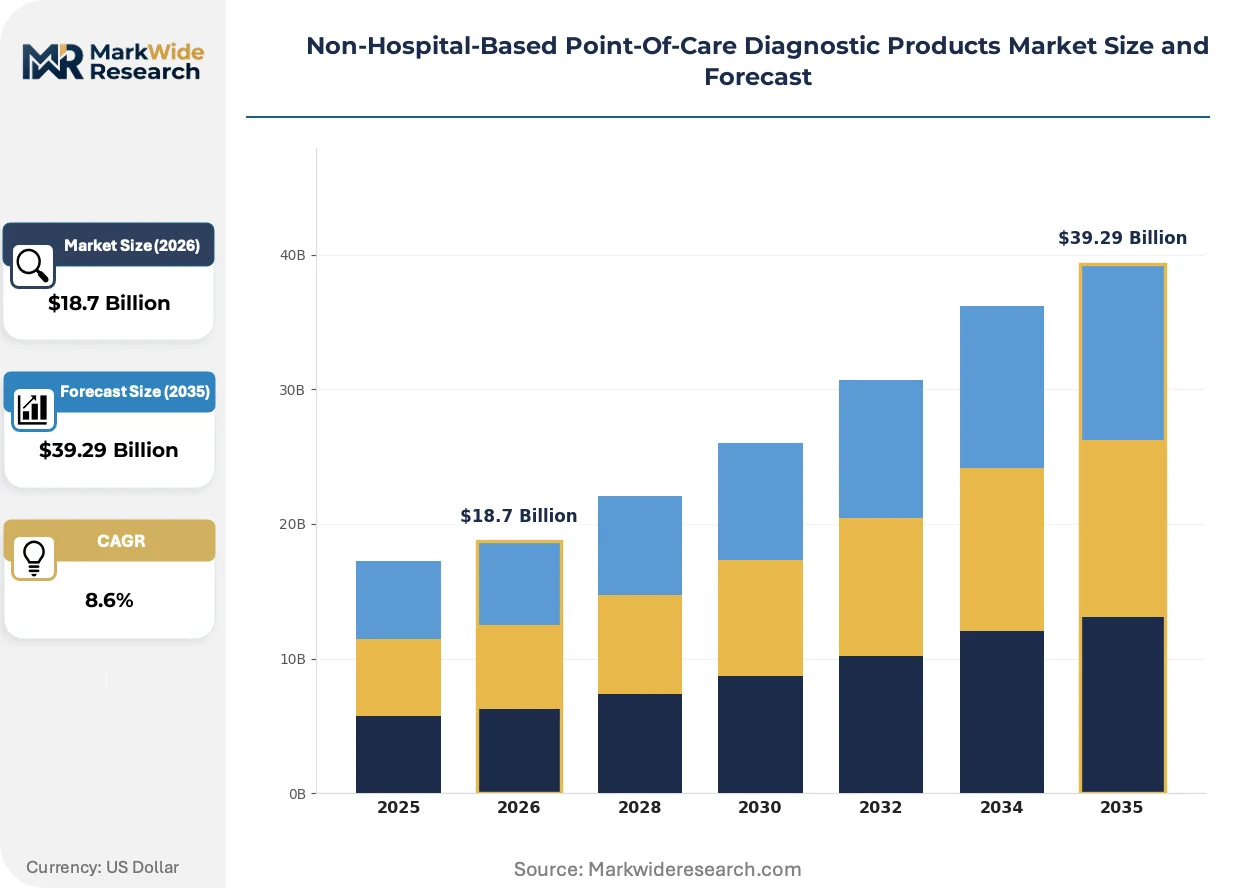
Market Dynamics
CLIA-waived classification under FDA guidance is compressing time-to-market for multiplexed assays while simultaneously fragmenting reimbursement pathways across state Medicaid programs.
Growth Catalysts
- CLIA-waived test expansion:FDA guidance multiplying waived categories enables pharmacist-operated testing in retail pharmacies without laboratory certification requirements.
- Capillary blood microsampling:Finger-stick volumes below 50 microliters eliminate phlebotomy dependency and open pediatric and geriatric segments previously excluded from rapid testing.
- Germany:Pharmacist-administered rapid diagnostics reimbursement under statutory health insurance creates predictable demand for multiplexed respiratory panels.
Market Restraints
- IVDR clinical evidence requirements:European Union In Vitro Diagnostic Regulation imposes retrospective studies on legacy devices, forcing smaller manufacturers to abandon CE-marked products.
- Nitrocellulose membrane supply:Lateral-flow cassette production concentrates among three Asian suppliers, exposing Abbott and Siemens to raw material allocation risk during demand surges.
- Optical sensor calibration drift:Fluorescence-based readers require 90-day recertification cycles that inflate total cost of ownership for urgent care operators.
Strategic Opportunities
- Home care direct-to-consumer:E-commerce channels bypass pharmacy markup and capture margin previously allocated to retail distribution intermediaries.
- Salivary cortisol testing:Stress biomarker detection opens employer wellness programs as a reimbursement-advantaged channel outside traditional clinical billing.
- California scope-of-practice liberalization:Pending legislation would permit independent pharmacist ordering of rapid diagnostics without physician oversight, expanding addressable test volume.
Industry Challenges
- Medical laboratory scientist shortage:ASCP-certified technologist vacancies exceeding 7% annually force health systems to delegate specimen processing to non-laboratory personnel with limited training.
- Interoperability with EHR systems:HL7 FHIR integration requirements delay product launches by 8-14 months as manufacturers validate data exchange with Epic and Cerner deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Hospital-Based Point-Of-Care Diagnostic Products Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Glucose Monitors, Pregnancy Tests, Infectious Disease Tests, Cholesterol Test Kits Technology: Optical Sensors, Enzymatic Assays, Microfluidics, Lateral Flow End User: Home Care, Pharmacists, Urgent Care Centers, Mobile Clinics Application: Chronic Disease Management, Disease Prevention, Health Monitoring, Screening |
| Companies Covered | Abbott Laboratories Inc., Siemens Healthcare GmbH, Bio-Rad Laboratories Inc., Thermo Fisher Scientific Inc., Roche Diagnostics, Danaher Corporation, BD, QuidelOrtho Corp., Qiagen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Hospital-Based Point-Of-Care Diagnostic Products Market Evolving Landscape
Microfluidics architectures are compressing assay complexity into handheld formats while regulatory convergence between FDA and notified bodies accelerates dual-approval strategies for multinational manufacturers.
Multiplexed nucleic acid amplification in credit-card-sized cartridges is displacing single-analyte lateral-flow tests in urgent care settings. Urgent care operators in Texas and Florida are adopting these platforms at 40% annual clip. The technology is displacing send-out reference laboratory revenue for respiratory pathogen panels.
EU IVDR's stricter performance evaluation requirements are extending technical documentation timelines by 12-18 months for Class C devices. Manufacturers are consolidating clinical evidence generation across multiple notified bodies to amortize compliance costs. Infectious disease test categories face the steepest conformity assessment delays, pushing smaller firms toward partnership or exit.
Pharmacy chains are unbundling diagnostic service contracts from product procurement, separating analyzer placement from consumable supply agreements. CVS and Walgreens now negotiate instrument leases independently of reagent pricing, compressing supplier margins on placement deals. This restructuring is most visible in Florida and New York, where pharmacist scope expansion has activated competitive bidding for urgent care referral networks.
Non-Hospital-Based Point-Of-Care Diagnostic Products Market Segmentation
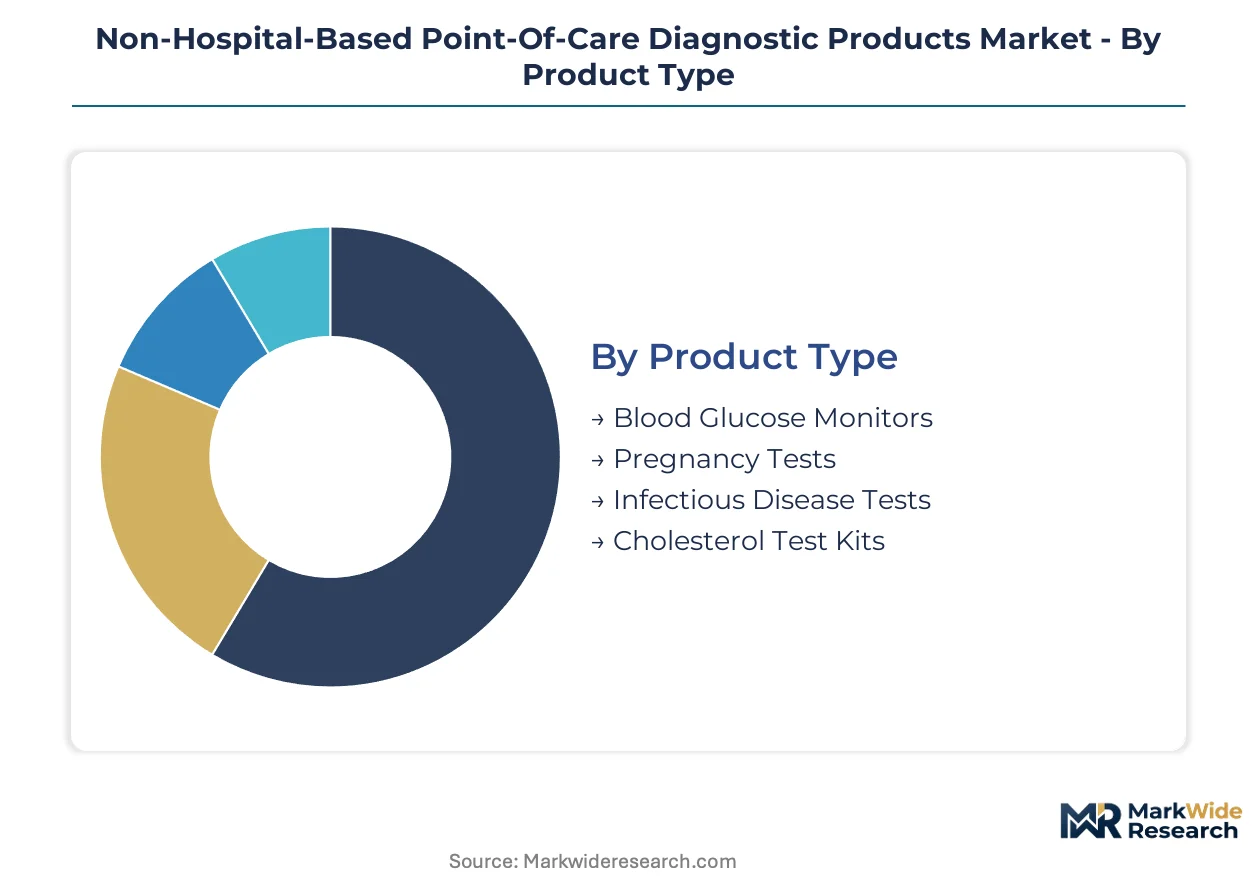
Segmentation reveals how margin pools concentrate across technology tiers and end-user channels. Manufacturers calibrate R&D allocation and distribution strategy against these structural fault lines.
Product Type:
Margins compress most severely in commoditized categories while multiplexed infectious disease panels retain pricing power through CLIA-waived exclusivity.
- Infectious Disease Tests:Multiplexed respiratory and sexually transmitted pathogen panels leverage microfluidic architectures to deliver lab-comparable sensitivity from capillary samples. Urgent care operators in Texas and Florida are adopting these platforms at 40% annual clip, displacing send-out reference laboratory revenue.
- Blood Glucose Monitors:Electrochemical strip-based systems dominate unit volume but face heavy private-label competition and reimbursement compression. Retail pharmacy chains now source these through unbundled procurement contracts that separate analyzer placement from consumable supply.
- Pregnancy Tests:Lateral-flow human chorionic gonadotropin detection represents the most mature home-use category with direct-to-consumer e-commerce bypassing traditional pharmacy markup.
- Cholesterol Test Kits:Enzymatic assay strips for lipid panels serve employer wellness programs seeking reimbursement-advantaged channels outside traditional clinical billing.
The dominant share belongs to Blood Glucose Monitors, while Infectious Disease Tests are closing the gap fastest.
Technology:
Platform selection determines regulatory pathway complexity and total cost of ownership for end users.
- Microfluidics:Credit-card-sized cartridges integrate sample preparation, amplification, and detection for nucleic acid-based multiplexing. Benchtop analyzer repurposing for urgent care deployment anchors European demand through installed base leverage.
- Lateral Flow:Nitrocellulose membrane cassettes with colored nanoparticle visualization dominate pregnancy and infectious disease screening. Asian supplier concentration among three membrane manufacturers exposes Abbott and Siemens to raw material allocation risk during demand surges.
- Optical Sensors:Fluorescence-based readers require 90-day recertification cycles that inflate total cost of ownership for urgent care operators.
- Enzymatic Assays:Colorimetric reactions with precise substrate specificity meet regulatory thresholds for pharmacist-operated testing under FDA CLIA-waived classification.
Microfluidics commands the steepest expansion trajectory as manufacturers pursue lab-comparable accuracy in handheld formats.
End User:
Channel selection dictates reimbursement mechanics and required training depth for device operators.
- Urgent Care Centers:Supervised test administration captures disproportionate value per procedure through higher reimbursement rates. Texas and Florida operators drive 40% annual adoption of multiplexed nucleic acid platforms.
- Home Care:Direct-to-consumer e-commerce channels bypass pharmacy markup and capture margin previously allocated to retail distribution intermediaries.
- Pharmacists:Statutory health insurance reimbursement in Germany creates predictable demand for multiplexed respiratory panels administered in retail pharmacy settings.
- Mobile Clinics:CLIA-waived classification enables operation by non-laboratory personnel without centralized laboratory infrastructure.
Home Care dominates unit volume, yet Urgent Care Centers generate superior revenue per test.
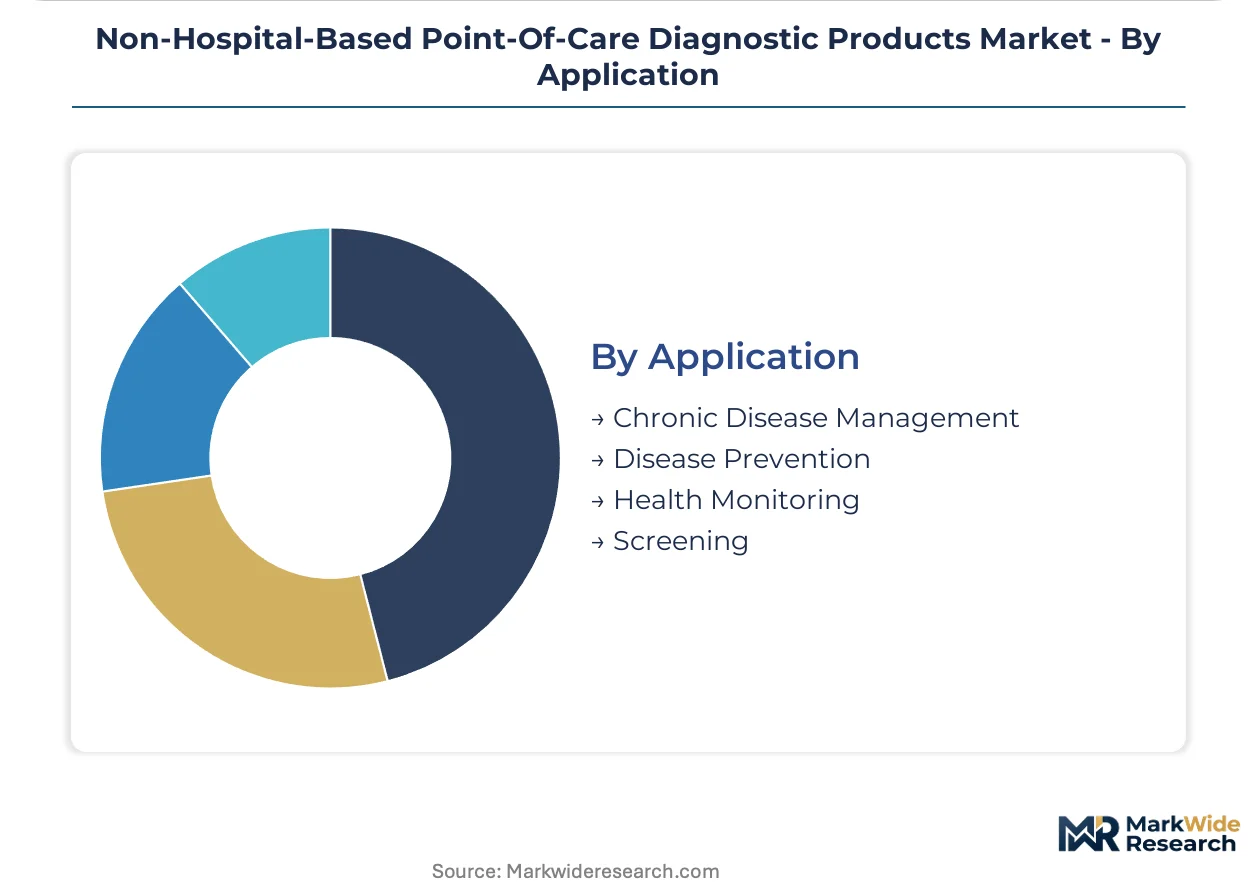
Application:
Use case positioning determines whether manufacturers compete on price transparency or clinical workflow integration.
- Chronic Disease Management:Blood glucose and cholesterol monitoring for diabetes and cardiovascular patients requires longitudinal data tracking and EHR interoperability.
- Screening:Pregnancy and infectious disease detection prioritizes speed and simplicity over quantitative precision.
- Health Monitoring:Salivary cortisol testing for stress biomarkers opens employer wellness programs as a reimbursement-advantaged channel.
- Disease Prevention:Pre-symptomatic pathogen detection in mobile clinic settings supports public health surveillance objectives.
Chronic Disease Management retains the largest installed base, though Screening applications are gaining share fastest through retail pharmacy expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA CLIA-waived classification anchors the United States as the dominant geography, while Germany, the United Kingdom, and France concentrate European demand through pharmacist-administered reimbursement frameworks.
United States
Retail pharmacy chains expand self-testing aisles as waived test categories multiply under FDA guidance. State-level scope-of-practice laws in California, Florida, and New York determine independent pharmacist ordering authority. Urgent care operators in Texas and Florida drive multiplexed nucleic acid platform adoption at accelerated rates.
Germany
Statutory health insurance reimbursement creates predictable demand for multiplexed respiratory panels in retail pharmacy settings. The national pharmaceutical regulator enforces IVDR conformity assessment timelines that extend technical documentation requirements. The Rhine-Ruhr and Bavarian industrial clusters host repurposed benchtop analyzer deployments for urgent care networks.
United Kingdom
Pharmacist-operated rapid diagnostics gain traction through National Health Service integration pilots. MHRA post-Brexit regulatory autonomy permits accelerated approval pathways for CLIA-waived equivalent devices. Greater London and Manchester concentrate urgent care center expansion and mobile clinic deployment.
France
Pharmacy network density supports decentralized diagnostic access outside hospital infrastructure. ANSM oversight aligns with IVDR performance evaluation requirements for Class C infectious disease devices. The Île-de-France region anchors demand for microfluidics-based platforms in supervised testing environments.
Japan
Aging demographics expand home care diagnostic volume through direct-to-consumer channels. PMDA regulatory convergence with FDA standards accelerates dual-approval strategies for handheld analyzers. The Kanto region surrounding Tokyo concentrates urgent care operator investment in fluorescence-based reader systems.
Non-Hospital-Based Point-Of-Care Diagnostic Products Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with lateral-flow cassette manufacturers and microfluidics platform developers occupying distinct competitive positions. The market structure rewards backward integration into nitrocellulose membrane supply and enzymatic assay precision. Three archetypes predominate: vertically integrated diagnostic conglomerates, microfluidics technology specialists, and enzymatic assay precision players. Competitive moves center on unbundled procurement contract negotiation and EHR interoperability validation cycles.
Among integrated diagnostic conglomerates, Abbott Laboratories Inc. and Siemens Healthcare GmbH exemplify scale-driven archetypes with captive manufacturing capabilities. Bio-Rad Laboratories Inc. occupies a precision-focused position within the enzymatic assay specialist tier. These three entities represent contrasting strategic postures: Abbott Laboratories Inc. leverages lateral-flow cost structures, Siemens Healthcare GmbH anchors European installed base repurposing, and Bio-Rad Laboratories Inc. targets regulatory thresholds for pharmacist-operated deployment.
| Leading Market Players |
|---|
| Abbott Laboratories Inc. |
| Siemens Healthcare GmbH |
| Bio-Rad Laboratories Inc. |
| Thermo Fisher Scientific Inc. |
| Roche Diagnostics |
| Danaher Corporation |
| BD |
| QuidelOrtho Corp. |
| Qiagen |
| Others |
Value Network & Pricing Analysis
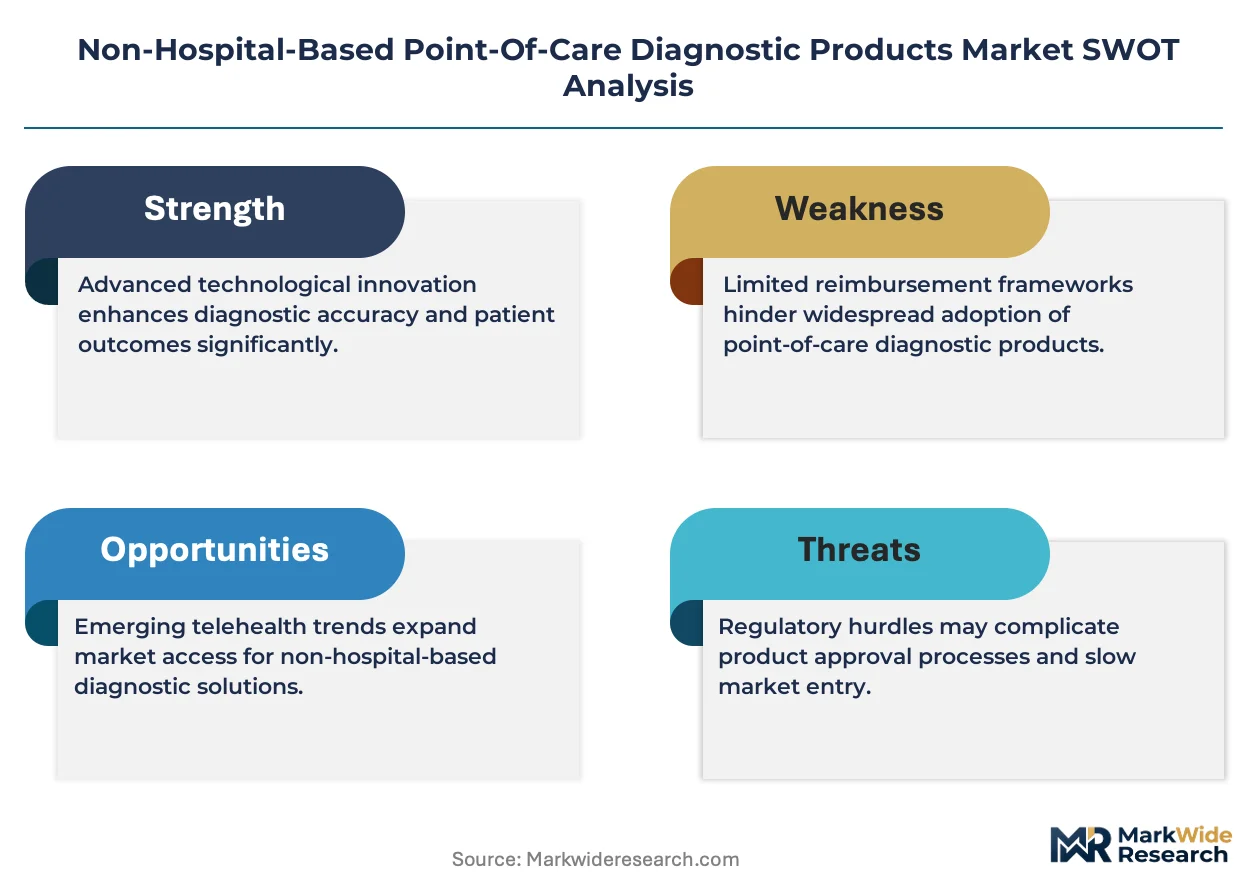
FDA CLIA-waived certification gates both supplier qualification and price differentiation, permitting only validated manufacturers to access retail pharmacy channels while stratifying reimbursement across waived versus moderate-complexity test tiers. This regulatory threshold compresses margins for non-compliant entrants and amplifies pricing power for incumbent lateral-flow and microfluidics producers with established waived portfolios.
Pricing Analysis
Geographic price spreads separate urgent care reimbursement rates in Texas and Florida from direct-to-consumer home care channels, with supervised administration capturing premium multiples over self-testing equivalents. Three-tier pricing structure across CLIA-waived premium, standard enzymatic, and economy lateral-flow levels reflects certification depth and optical sensor precision. Cost compression in blood glucose strips is intensifying because private-label pharmacy sourcing unbundles analyzer placement from consumable supply. Employer wellness programs exhibit lowest price sensitivity due to reimbursement-advantaged salivary cortisol positioning outside traditional clinical billing.
Supply Chain Analysis
Nitrocellulose membrane supply concentrates among three Asian manufacturers, exposing Abbott and Siemens to raw material allocation risk during respiratory panel demand surges. Lateral-flow cassette production draws from Chinese and South Korean membrane suppliers, with enzymatic reagents anchored in German and U.S. pharmaceutical chemical clusters. Single-source vulnerability in fluorescence-based optical sensor calibration equipment inflates total cost of ownership through mandatory 90-day recertification cycles. Distribution runs through unbundled procurement contracts where CVS and Walgreens negotiate instrument leases independently of reagent pricing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from EHR interoperability validation and 90-day optical recalibration cycles is expanding faster than hardware placement, reframing point-of-care diagnostics as recurring-revenue platforms rather than capital equipment sales.
For Market Incumbents: Shield CLIA-waived portfolio exclusivity through backward integration into nitrocellulose membrane supply, locking out private-label competitors during demand surges. Anchor European installed base leverage in Germany and the United Kingdom against emerging microfluidics specialists threatening multiplexed respiratory panel dominance. Prioritize HL7 FHIR certification investment to compress 8-14 month EHR integration delays that currently stall product launches. For New Entrants and Emerging Players: Differentiate on salivary cortisol stress biomarker detection, penetrating employer wellness programs as a reimbursement-advantaged channel outside traditional clinical billing. Target California pharmacist scope-of-practice liberalization as the most penetrable regulatory jurisdiction, positioning for independent rapid diagnostic ordering authority without physician oversight. Pursue urgent care operator partnerships in Texas and Florida where 40% annual multiplexed platform adoption creates whitespace for nucleic acid amplification specialists. For Investors and Strategic Acquirers: EU IVDR conformity assessment timeline extension reshapes the acquisition landscape, forcing smaller CE-marked manufacturers toward distressed exit or partnership. Long-term viability across the analysis window favors enzymatic assay precision players with pharmacist-operated regulatory thresholds already validated. Watch FDA waived category expansion velocity as the inflection signal determining whether microfluidics R&D returns justify capital intensity against lateral-flow cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-waived Category Expansion | FDA guidance multiplication unlocks pharmacist-operated testing in retail pharmacies without laboratory certification. |
| Microfluidics Platform Integration | Credit-card-sized nucleic acid cartridges displace send-out reference laboratory revenue in urgent care networks. |
| EHR Interoperability Partnership | HL7 FHIR validation with Epic and Cerner deployments reduces 8-14 month product launch delays. |
| Backward Membrane Integration | In-house nitrocellulose production insulates against Asian supplier concentration during demand surges. |
| Salivary Biomarker Development | Stress cortisol detection opens employer wellness reimbursement outside traditional clinical billing channels. |
Research Methodology
Desk research of FDA 510(k) filings, EU IVDR technical documentation, and CMS Medicare reimbursement databases preceded structured interviews with point-of-care product managers, hospital purchasing committee members, GPO contracts managers, and pharmacy chain procurement directors. Primary fieldwork with urgent care operators in Texas and Florida validated multiplexed platform adoption rates against secondary claims data. Bottom-up unit economics triangulated against top-down market sizing from statutory health insurance reimbursement schedules.
Variance decomposition across technology tiers, end-user channels, and geographic regulatory clusters informed segment-level growth trajectories throughout the forecast period. Modeled dimensions span CLIA-waived versus moderate-complexity classification, supervised versus self-administered delivery, and capillary versus salivary sample matrices. CAGRs derived from elasticity-adjusted reimbursement rate projections and installed base replacement cycles, with optical sensor recertification frequency and EHR integration pipeline velocity as diagnostic-specific inputs.
Forecasts assume regulatory continuity in FDA waived category guidance and EU IVDR conformity assessment timelines; material policy shifts would require re-modeling. Specific risks include state-level scope-of-practice reversals, nitrocellulose export restrictions, and IVDR notified body capacity constraints. Practitioners should keep alternative scenarios live as pharmacist ordering authority legislation and microfluidics cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Urine Analyzers Market
Diagnostic Devices
Breath Samplers Market
Diagnostic Devices
Biopsy Guidance System Market
Diagnostic Devices
Companion Diagnostics Market
Diagnostic Devices
Lung Biopsy Systems Market
Diagnostic Devices
Biopsy Devices Market
Diagnostic Devices
Europe Companion Diagnostics Market
Diagnostic Devices
Breast Biopsy Market
Diagnostic Devices
ENT Diagnostic Devices Market
Diagnostic Devices
Portable Cancer Screen Devices Market
Diagnostic Devices
United States Biopsy Devices Market
Diagnostic Devices
Amniotic Fluid Detection Market
Diagnostic Devices
Non-Invasive Biosensors Market
Diagnostic Devices
Skin Moisture Detectors Market
Diagnostic Devices
Ophthalmic Diagnostic Equipment Market
Diagnostic Devices
Bronchial Biopsy Devices Market