
 Auto Chemistry Analyzers Market | 2026-2036
Auto Chemistry Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Auto Chemistry Analyzers Market Insights
Multi-sourced component procurement is decoupling from legacy single-vendor dependencies across the auto chemistry analyzer supply base. Danaher Corporation leverages its life sciences portfolio breadth to sustain captive reagent supply chains. Siemens Healthineers anchors European installed-base service contracts through direct field-engineer networks. Abbott Laboratories differentiates its positioning via integrated informatics platforms that lock in laboratory workflow software.
An auto chemistry analyzer is an automated clinical instrument that quantifies biochemical constituents in biological samples through photometric, electrochemical, or chromatographic detection methods, typically processing 200-800 tests per hour with liquid-handling precision measured in microliters. These systems serve diagnostic laboratories by standardizing throughput, reducing manual pipetting error, and enabling continuous batch processing of serum, plasma, urine, and cerebrospinal fluid panels. Benchtop analyzers occupy the highest-margin tier where mid-volume hospitals prioritize footprint efficiency over maximum throughput. Spectrophotometry technology leads installed capacity while immunoassay-integrated platforms capture the fastest expansion in oncology and endocrinology testing menus. Diagnostic laboratories represent the most concentrated end-user revenue pool, though research centers are extending contract durations for multiplexed assay development.
FDA quality-system regulation and CLIA proficiency standards govern instrument validation and operator certification requirements across the United States, while the EU In Vitro Diagnostic Regulation mandates notified-body conformity assessment for European market access. These frameworks elevate capital barriers for new entrants and compel incumbent manufacturers to maintain dedicated regulatory-affairs functions. Stakeholders must monitor evolving premarket submission pathways as decentralized point-of-care testing strains traditional centralized-lab compliance architectures.
Market Dynamics
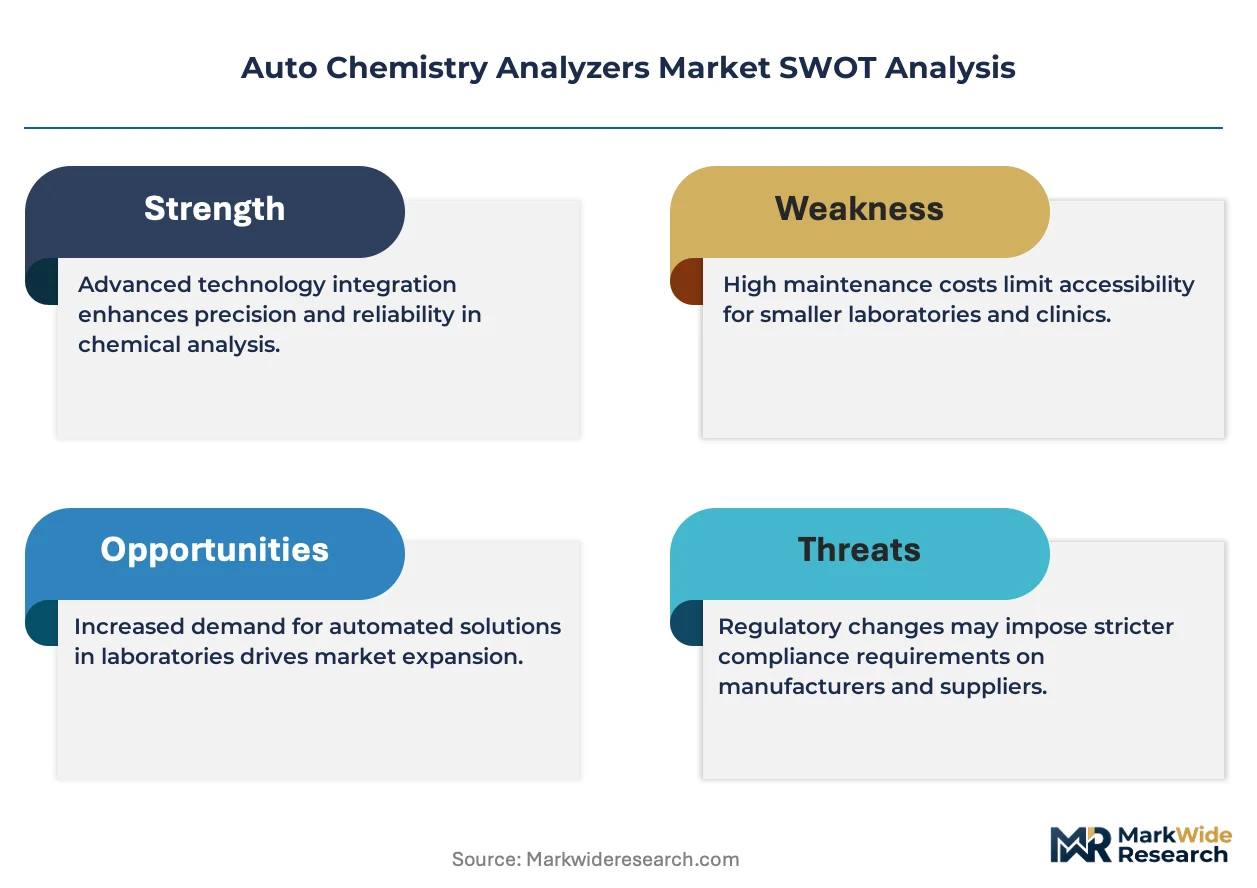
The FDA's tightening quality-system requirements for in vitro diagnostic devices are compressing product certification timelines while elevating capital barriers for new entrants, forcing incumbent manufacturers to maintain dedicated regulatory-affairs functions and reshape competitive positioning.
Growth Catalysts
- CLIA Proficiency Standards:United States laboratory accreditation mandates are standardizing operator certification requirements, expanding replacement demand for compliant next-generation instruments.
- Oncology Testing Menus:Immunoassay-integrated platforms are capturing expanded assay development in diagnostic laboratories, driving menu breadth as a procurement criterion.
- Centralized Lab Infrastructure:Hospital networks in Germany, Japan, and the United States are sustaining capital allocation toward high-throughput systems, concentrating demand in mature healthcare markets.
Market Restraints
- Notified-Body Conformity Assessment:EU In Vitro Diagnostic Regulation mandates are extending European market access timelines and elevating compliance costs for manufacturers without established CE marking pathways.
- Liquid-Handling Precision Requirements:Microliter-scale accuracy specifications are constraining component supplier qualification, limiting viable sourcing alternatives for optical and fluidic subsystems.
- Reagent Supply Concentration:Captive reagent supply chains controlled by integrated life sciences conglomerates are locking out independent instrument vendors from full-menu service contracts.
Strategic Opportunities
- Research Center Multiplexed Assay Development:Academic and contract research organizations are extending contract durations for custom panel configuration, creating service revenue beyond instrument sales.
- Benchtop Footprint Efficiency:Mid-volume hospitals are prioritizing space-constrained installations over maximum throughput, opening margin expansion in compact system tiers.
- Integrated Informatics Platforms:Laboratory workflow software lock-in is enabling recurring revenue streams through subscription-based middleware and data management tools.
Industry Challenges
- Field-Engineer Network Scalability:Direct service contract fulfillment requires geographic density of specialized technicians, constraining rapid installed-base expansion in secondary markets.
- Legacy System Integration Complexity:Hospital laboratory information systems demand customized middleware development, extending implementation timelines and elevating project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auto Chemistry Analyzers Market |
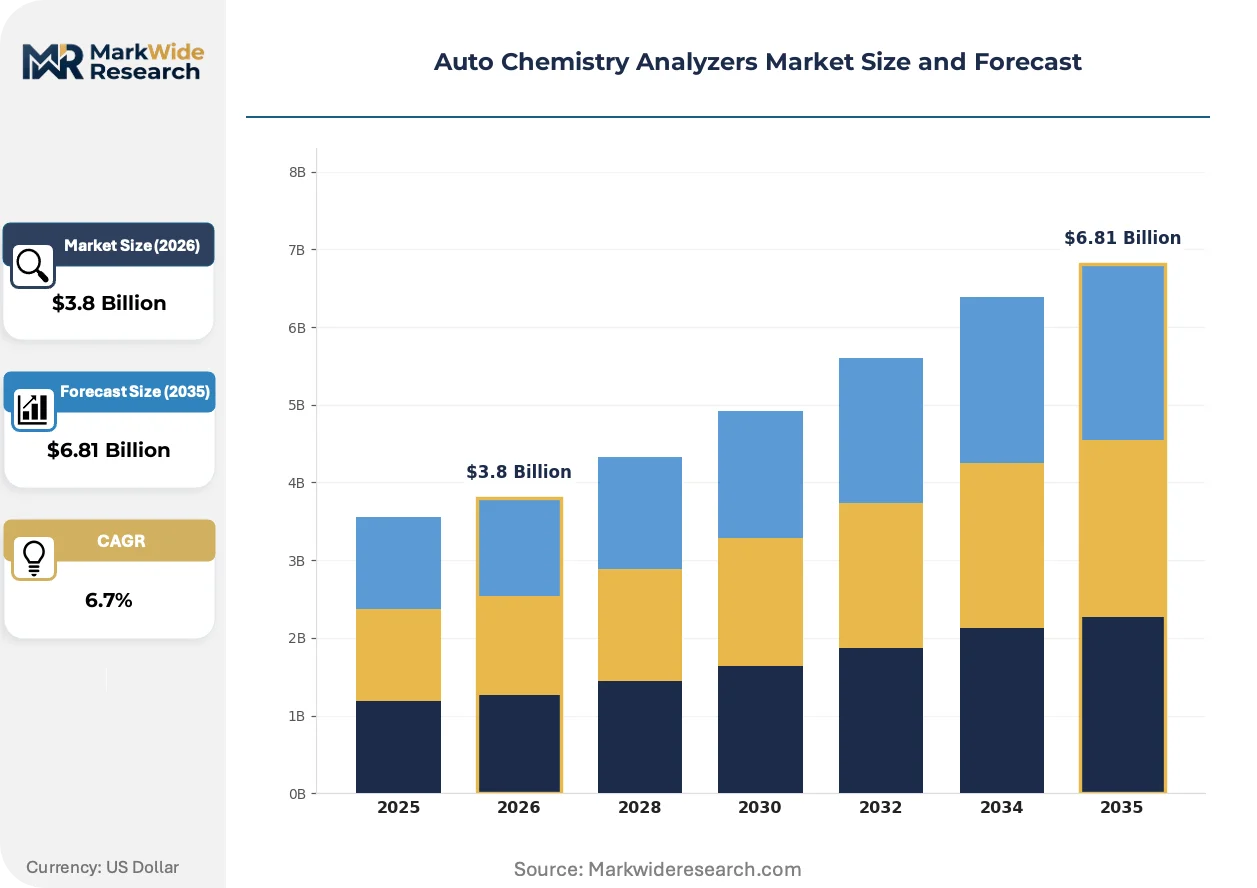
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop Analyzers, Portable Analyzers, Analyzers for Blood Tests, Analyzers for Urine Tests Technology: Spectrophotometry, Electrochemistry, Chromatography, Immunoassays End User: Hospitals, Diagnostic Laboratories, Research Centers, Clinics Application: Clinical Testing, Environmental Testing, Food Safety Testing, Forensic Testing |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd., Siemens Healthineers AG, Danaher Corporation, Thermo Fisher Scientific, Becton Dickinson, Agilent Technologies, Beckman Coulter, HORIBA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auto Chemistry Analyzers Market Trends and Innovations
Spectrophotometry and immunoassay technologies are converging into unified detection platforms, while regulatory frameworks on both sides of the Atlantic are rewriting certification economics. These forces are compressing vendor differentiation strategies around software integration and captive consumable supply.
Multiplexed assay platforms are unifying photometric, electrochemical, and chromatographic detection methods within single instrument architectures. Diagnostic laboratories in hospital networks are adopting these systems at accelerated replacement cycles, consolidating multiple standalone analyzers into unified workflow stations. This convergence is unifying vendor competition around comprehensive menu breadth rather than discrete technology performance.
The EU In Vitro Diagnostic Regulation is mandating notified-body conformity assessment for all new market entrants and legacy product renewals. European manufacturers are restructuring quality-management systems and expanding clinical evidence requirements for existing portfolios. Diagnostic laboratories in Germany and France are delaying procurement decisions pending supplier MDR certification status, compressing competitive windows for non-compliant vendors.
Service contract unbundling is separating instrument hardware from reagent supply and maintenance agreements in procurement negotiations. Mid-volume hospital buyers are negotiating standalone pricing for each cost component, pressuring bundled-margin structures. This pattern is most visible in United States health system purchasing cooperatives, where multi-hospital networks leverage aggregate volume for line-item transparency.
Auto Chemistry Analyzers Market Segmentation
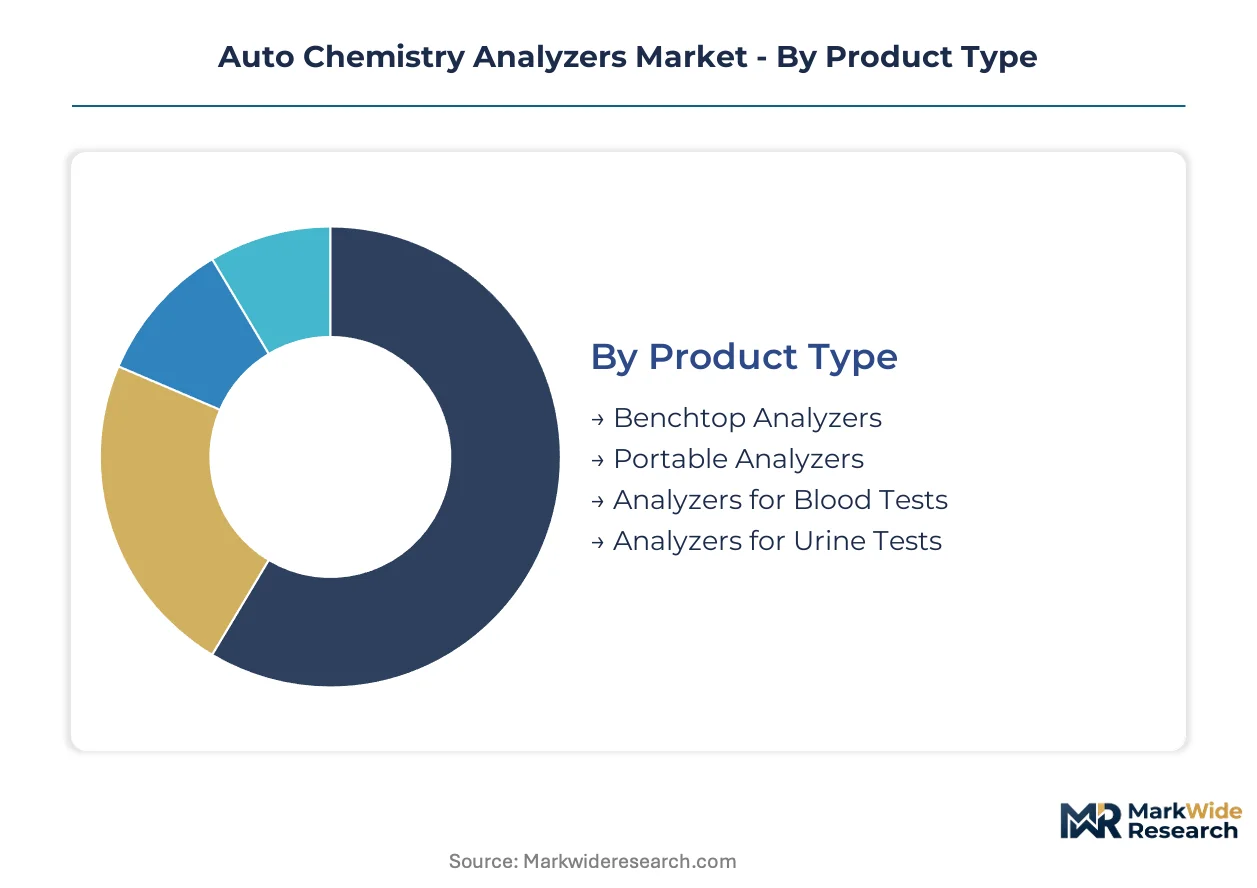
Segmentation in auto chemistry analyzers reveals how capital allocation, regulatory compliance, and throughput requirements fragment procurement patterns across healthcare infrastructure. Manufacturers calibrate product portfolios to match divergent investment capacities and testing volumes.
Product Type:
Capital intensity varies sharply across form factors, with floor-standing systems demanding multimillion-dollar installations while compact units require minimal facility retrofitting.
- Benchtop Analyzers:Compact systems integrate photometric detection with automated liquid handling in footprints under one square meter. Mid-volume hospitals in Germany and Japan prioritize these units where laboratory space constraints limit expansion. These configurations command premium pricing through reduced installation costs and faster regulatory clearance timelines.
- Portable Analyzers:Battery-operated units deploy electrochemical sensors for point-of-care deployment in emergency departments and satellite clinics. Demand concentrates in United States health systems pursuing decentralized testing networks to reduce central lab transport bottlenecks. FDA CLIA waiver pathways accelerate procurement decisions for moderate-complexity operators.
- Analyzers for Blood Tests:High-throughput systems process serum and plasma panels with continuous feed mechanisms.
- Analyzers for Urine Tests:Specialized units target metabolic and renal function assays with sediment analysis modules.
Most installed capacity flows through benchtop configurations. Expansion is steepest in portable systems.
Technology:
Technology selection determines reagent compatibility, menu breadth, and long-term service revenue potential for instrument vendors.
- Spectrophotometry:Optical detection systems measure absorbance at discrete wavelengths for enzymatic and substrate quantification. These platforms dominate legacy installed bases in diagnostic laboratories across the United States and Japan. Replacement cycles accelerate as FDA quality-system requirements mandate updated photometric calibration protocols.
- Immunoassays:Antibody-antigen binding detection enables protein and hormone quantification with femtomolar sensitivity. Oncology and endocrinology testing menus in hospital networks are consolidating onto these platforms to reduce send-out volumes. Integrated immunoassay modules capture the steepest expansion trajectory as menu breadth becomes the primary procurement criterion.
- Electrochemistry:Ion-selective electrodes provide rapid electrolyte and blood gas analysis.
- Chromatography:Separation-based methods target therapeutic drug monitoring and specialized metabolic panels.
Installed capacity concentrates in spectrophotometry platforms. Technology investment is climbing fastest in immunoassay integration.
End User:
Customer type dictates purchasing authority, contract duration, and sensitivity to total cost of ownership versus upfront capital expenditure.
- Diagnostic Laboratories:Independent and hospital-affiliated labs operate high-throughput instruments across extended shifts with dedicated technical staff. These buyers in Germany and the United States negotiate multi-year reagent supply agreements with volume-based pricing tiers. Capital budgets prioritize throughput per square meter and interoperability with laboratory information systems.
- Hospitals:Integrated health systems consolidate testing across inpatient, emergency, and outpatient settings. Procurement decisions in Japan emphasize vendor field-service density and rapid response guarantees. Consolidated purchasing cooperatives extract line-item transparency for hardware, software, and consumable components.
- Research Centers:Academic and contract organizations demand configurable assay protocols for multiplexed panel development.
- Clinics:Primary care and specialty practices prioritize waived-complexity systems with minimal operator training requirements.
Diagnostic laboratories anchor manufacturer revenue. Hospital network consolidation is accelerating replacement demand.
Application:
Application scope determines regulatory pathway complexity and the breadth of quality-control documentation required for operational compliance.
- Clinical Testing:Diagnostic applications for patient management require FDA premarket notification or EU MDR conformity assessment. Hospital laboratories in the United States and Germany represent the concentrated demand pool with sustained capital allocation toward menu expansion. CLIA proficiency standards and CAP accreditation requirements elevate barriers for non-compliant instrument vendors.
- Environmental Testing:Water and soil analysis applications deploy modified clinical platforms with custom calibration curves. Demand from municipal utilities and industrial compliance programs in Japan is extending instrument utilization beyond healthcare settings. EPA method equivalency certifications open procurement pathways distinct from clinical regulatory frameworks.
- Food Safety Testing:Pathogen and contaminant screening applications require specialized sample preparation modules.
- Forensic Testing:Toxicology and DNA analysis applications demand chain-of-custody documentation and enhanced audit trails.
Clinical testing commands dominant installed capacity. Environmental applications are gaining share fastest outside traditional healthcare procurement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting manufacturing investment toward jurisdictions with streamlined conformity assessment pathways, while mature healthcare markets sustain premium instrument demand through centralized laboratory capital programs.
United States
Hospital network consolidation in Texas and the Midwest is accelerating replacement cycles for high-throughput systems. FDA quality-system regulations and CLIA proficiency standards govern instrument validation across diagnostic laboratories. The Boston-Cambridge cluster anchors immunoassay platform development for oncology testing menus.
Germany
Diagnostic laboratories in Bavaria and North Rhine-Westphalia prioritize vendor field-service density in procurement negotiations. EU In Vitro Diagnostic Regulation mandates notified-body conformity assessment for market access, extending certification timelines. The Rhine-Main region concentrates reagent supply chain infrastructure for captive consumable production.
Japan
Mid-volume hospitals in the Kanto region are prioritizing benchtop footprint efficiency over maximum throughput capacity. PMDA and METI oversight shapes premarket submission requirements for automated clinical instruments. The Osaka-Kobe industrial corridor hosts precision fluidic component fabrication for liquid-handling subsystems.
China
Domestic diagnostic laboratory chains in the Yangtze River Delta are expanding installed base for multiplexed assay platforms. NMPA regulatory pathways are elevating clinical evidence requirements for imported instrument registrations. Shenzhen-based manufacturers are scaling electrochemical sensor production for portable analyzer configurations.
India
Private hospital networks in Maharashtra and Karnataka are importing refurbished high-throughput systems to manage capital expenditure constraints. CDSCO medical device rules govern registration timelines for automated chemistry analyzers. The Delhi-NCR cluster concentrates third-party maintenance service providers for legacy instrument support.
Auto Chemistry Analyzers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular component supply and regional service partnerships as entry vectors. The vendor base stratifies across integrated life sciences conglomerates with captive reagent ecosystems and specialized instrument fabricators competing on footprint efficiency. Three archetypes dominate: full-menu platform vendors, benchtop efficiency specialists, and point-of-care portability developers. Competitive maneuvering concentrates on strategic partnerships for middleware integration and backward integration into optical subsystem production.
Among diversified healthcare conglomerates, Abbott Laboratories and Danaher Corporation exemplify the integrated-platform archetype through captive supply chain control. Siemens Healthineers anchors European installed-base positioning. F. Hoffmann-La Roche Ltd. occupies the premium-tier diagnostic systems segment. These entities represent contrasting strategic postures around reagent lock-in versus open-system flexibility.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd. |
| Siemens Healthineers AG |
| Danaher Corporation |
| Thermo Fisher Scientific |
| Becton Dickinson |
| Agilent Technologies |
| Beckman Coulter |
| HORIBA |
| Others |
Pricing and Supply Chain Analysis
Captive reagent supply chain integration anchors both procurement leverage and margin structure for dominant life sciences conglomerates. This vertical control over consumable production in Germany and the United States enables premium pricing for full-menu service contracts while constraining independent instrument vendors to hardware-only revenue pools.
Pricing Analysis
Distributor margin compression is reshaping contract structures as hospital purchasing cooperatives extract line-item transparency for hardware, software, and consumable components. Three-tier pricing structure across premium, standard, and economy levels separates integrated platform vendors from benchtop efficiency specialists and refurbished equipment brokers. Cost compression in the economy tier intensifies because capital-constrained buyers in India and secondary US markets prioritize refurbished high-throughput systems. Mid-volume hospitals in Japan exhibit highest price sensitivity, while diagnostic laboratories in Germany demonstrate lowest sensitivity due to reagent lock-in effects.
Supply Chain Analysis
Domestic-content mandates in China and India's medical device procurement frameworks are reshaping component sourcing toward local precision fluidic fabrication. Optical subsystem production concentrates in Japan, Germany, and the United States, while electrochemical sensor manufacturing scales in Shenzhen and the Yangtze River Delta. Microliter-scale liquid-handling modules draw from specialized component suppliers in the Osaka-Kobe corridor. Single-source vulnerability persists for photometric calibration standards certified to FDA quality-system protocols. Distribution runs through direct field-engineer networks for installed-base service contracts, supplemented by third-party maintenance providers in Delhi-NCR and Mumbai for legacy instrument support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Auto chemistry analyzers constitute a late-cycle quality story as diagnostic laboratories prioritize CLIA-compliant next-generation instruments over price-minimizing alternatives. This demand shift toward premium specifications reflects FDA quality-system tightening and EU MDR conformity assessment elevation.
For Market Incumbents: Anticipate service contract unbundling pressure from US health system purchasing cooperatives by deepening captive reagent supply chain control and accelerating middleware integration investments. Consolidate field-engineer network density in Germany and Japan to defend against emerging regional service partnerships. Certification investment for EU MDR renewal represents the critical defensive lever.
For New Entrants and Emerging Players: Direct-to-laboratory digital procurement platforms offer lower customer acquisition cost than traditional distributor relationships for portable analyzer configurations. Target environmental testing applications in Japanese municipal utilities as the most penetrable segment outside clinical regulatory frameworks. Pursue modular component supply partnerships with Shenzhen-based electrochemical sensor manufacturers as the primary go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for benchtop efficiency specialists because hospital network consolidation in Texas and the Midwest generates replacement demand for space-constrained installations. Long-term viability across the analysis window hinges on software companion development capabilities and informatics platform integration depth. Watch FDA premarket notification timelines for immunoassay-integrated platforms as the inflection indicator for competitive window compression.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified-body conformity assessment extends certification timelines for European market access. |
| Hospital System Partnership | Multi-year reagent supply agreements with German diagnostic laboratories lock in recurring revenue streams. |
| Software Companion Development | Integrated informatics platforms enable subscription-based middleware revenue beyond instrument sales. |
| Backward Integration | In-house optical subsystem production reduces dependency on Japanese precision component suppliers. |
| Reimbursement Strategy | CLIA waiver pathways for portable analyzers accelerate procurement decisions in US emergency departments. |
Research Methodology
Multiple input streams — primary interviews with hospital laboratory directors, GPO contracts managers, and biomedical engineers; secondary validation against FDA 510(k) filings, EU MDR notified-body databases, and hospital procurement records; plus customs data for instrument import flows — were reconciled through bottom-up and top-down triangulation. Conversations with field-service technicians and regulatory-affairs leads at instrument manufacturers provided operational context for certification timeline estimates. SEC filings from listed life sciences conglomerates supplied financial segmentation detail.
Data-stream reconciliation across product type, technology platform, end-user category, and geographic regulatory cluster enabled consistent volume and value modeling throughout the forecast period. CAGRs were derived from replacement cycle analysis and installed-base expansion patterns. Segment-specific inputs included CLIA proficiency standard adoption rates, EU MDR transition schedules, and hospital network consolidation trajectories in Texas and the Midwest.
The model assumes a particular technology adoption path; alternative pathways for immunoassay-integrated platforms would alter the outlook if spectrophotometry replacement cycles accelerate beyond projected timelines. Forecasts reflect underlying assumptions about regulatory clearance velocity and capital allocation continuity in German and Japanese hospital networks. A small set of named triggers — FDA quality-system rulemaking, EU MDR implementation delays, and reagent supply chain disruptions — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
US Medical Thermometer Market
Diagnostic Instruments
Global Wavefront Aberrometers Market
Diagnostic Instruments
Luminometers Market
Diagnostic Instruments
Genetic Analyzers Market
Diagnostic Instruments
Global Radioimmunoassay Market
Diagnostic Instruments
Trichoscope Devices Market
Diagnostic Instruments
Immunochemistry Analyzer Market
Diagnostic Instruments
Immunoassay Instruments Market
Diagnostic Instruments
Dental Fluorescence Analyzer Market
Diagnostic Instruments
Blood Flow Measurement Devices Market
Diagnostic Instruments
Global Cell Surface Markers Detection Market
Diagnostic Instruments
Global Blood Coagulation Analyzer Market
Diagnostic Instruments
Eye Testing Equipment Market
Diagnostic Instruments
Platelet Aggregation Devices Market
Diagnostic Instruments
Lower GI Series Market
Diagnostic Instruments
Tympanometers Market