
 Urine Analyzers Market | 2026-2036
Urine Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Urine Analyzers Market Analytics
Software-defined maintenance subscriptions is repositioning capital equipment into recurring revenue relationships for manufacturers. Siemens Healthineers leverages its service infrastructure to lock in long-term hospital contracts across installed bases. ARKRAY Inc. specializes in compact bench-top systems that occupy space-constrained clinical laboratories. Sysmex Corporation dominates high-volume flow cytometry urinalysis with differentiated particle-counting precision.
Urine analyzers constitute automated clinical chemistry instruments that process physical, chemical, and microscopic properties of urine specimens using photometric detection at specified wavelengths and flow-cell particle characterization. These systems serve primary diagnostic screening for metabolic disorders, renal impairment, and urinary tract pathology in centralized and point-of-care settings. Automatic analyzers capture the dominant installed base where throughput economics govern procurement decisions, while portable analyzers represent the fastest-expanding category as home healthcare reimbursement frameworks mature. Flow cytometry technology commands premium positioning against colorimetric analysis due to superior cellular differentiation capabilities and reduced manual microscopy dependency.
FDA clinical laboratory regulations and CAP accreditation standards mandate performance verification protocols that elevate barriers for new instrument entrants seeking hospital laboratory adoption. The EU In Vitro Diagnostic Regulation introduces notified body conformity assessment requirements that extend market access timelines for systems distributed in Europe. Stakeholders must evaluate how evolving decentralized testing policies and remote patient monitoring reimbursement decisions will redistribute volume between centralized laboratories and ambulatory settings.
Market Dynamics
Hospital laboratory consolidation is compressing procurement timelines while elevating performance verification requirements under FDA clinical laboratory improvement amendments. This structural concentration favors vendors with integrated service infrastructure and multi-site contract management capabilities.
Growth Catalysts
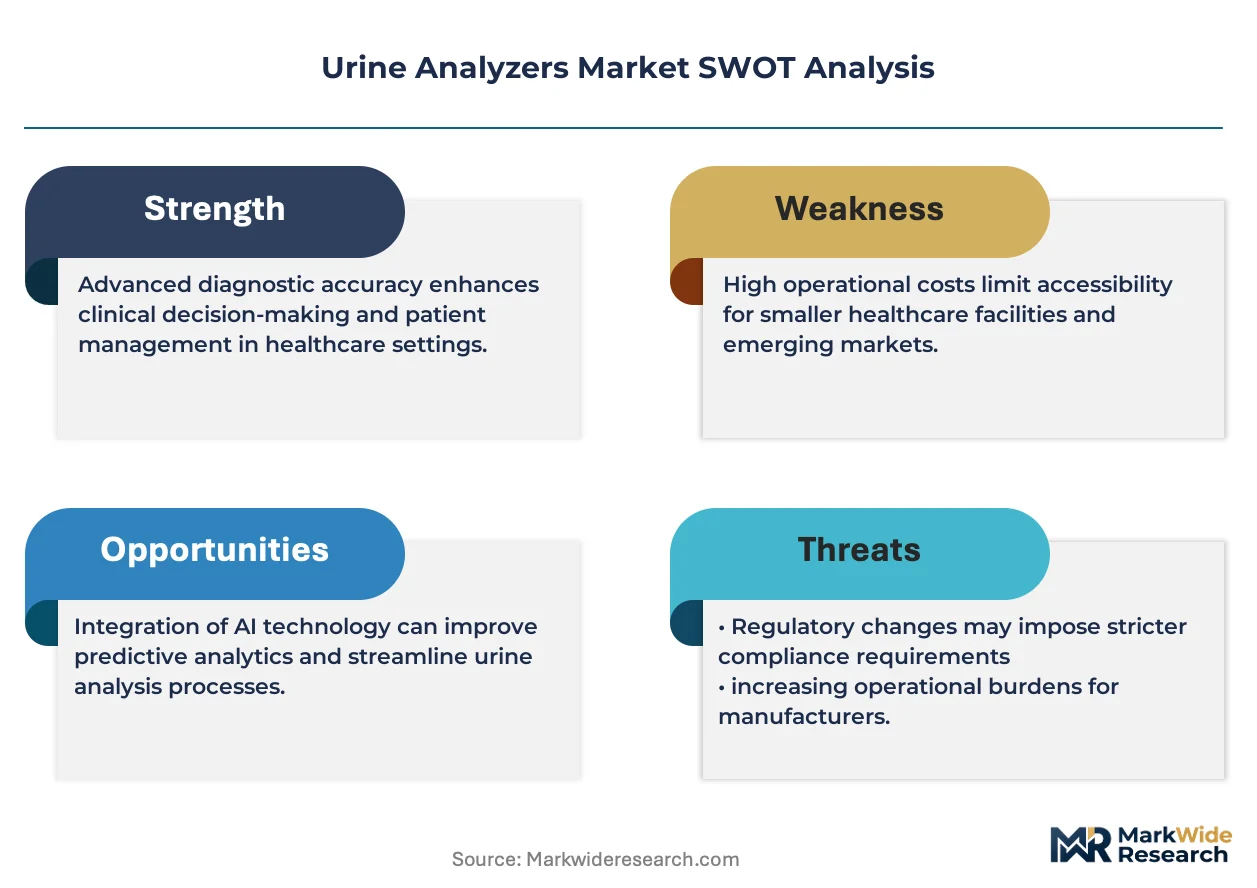
- Automated workflow expansion:Hospital laboratories are replacing manual microscopy with high-throughput flow cytometry systems to process rising sample volumes without proportional staff increases.
- CLIA enforcement:The FDA's continued scrutiny of instrument validation protocols is locking in incumbent vendors with established quality management systems and documented performance verification.
- Home healthcare reimbursement:CMS and private payers are expanding coverage frameworks for remote patient monitoring, accelerating portable analyzer deployment in ambulatory settings.
Market Restraints
- Optical component concentration:Precision photodetectors and laser diodes for flow cytometry modules concentrate among Japanese and German component suppliers, creating input vulnerability.
- EU MDR transition friction:The In Vitro Diagnostic Regulation's notified body conformity assessment requirements are extending market access timelines by 12-18 months for European distribution.
- Manual microscopy persistence:Pathologist preference for cellular morphology confirmation in complex cases limits full automation penetration in academic medical centers.
Strategic Opportunities
- India diagnostic expansion:The country's National Health Mission and growing private laboratory networks are creating demand for compact bench-top systems in tier-2 and tier-3 cities.
- AI-enabled particle classification:Machine learning algorithms trained on flow cytometry scatter patterns are converging with automated microscopy to reduce false-positive rates.
- Subscription service models:Reagent rental and per-test pricing arrangements are penetrating integrated health networks seeking to convert capital expenditures to operational budgets.
Industry Challenges
- Cross-trained technologist scarcity:Clinical laboratories face recruitment gaps for personnel proficient in both automated urinalysis operation and regulatory compliance documentation.
- Legacy LIS integration:Health systems with decades-old laboratory information systems encounter data mapping complexity when connecting modern analyzers requiring HL7 FHIR interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urine Analyzers Market |
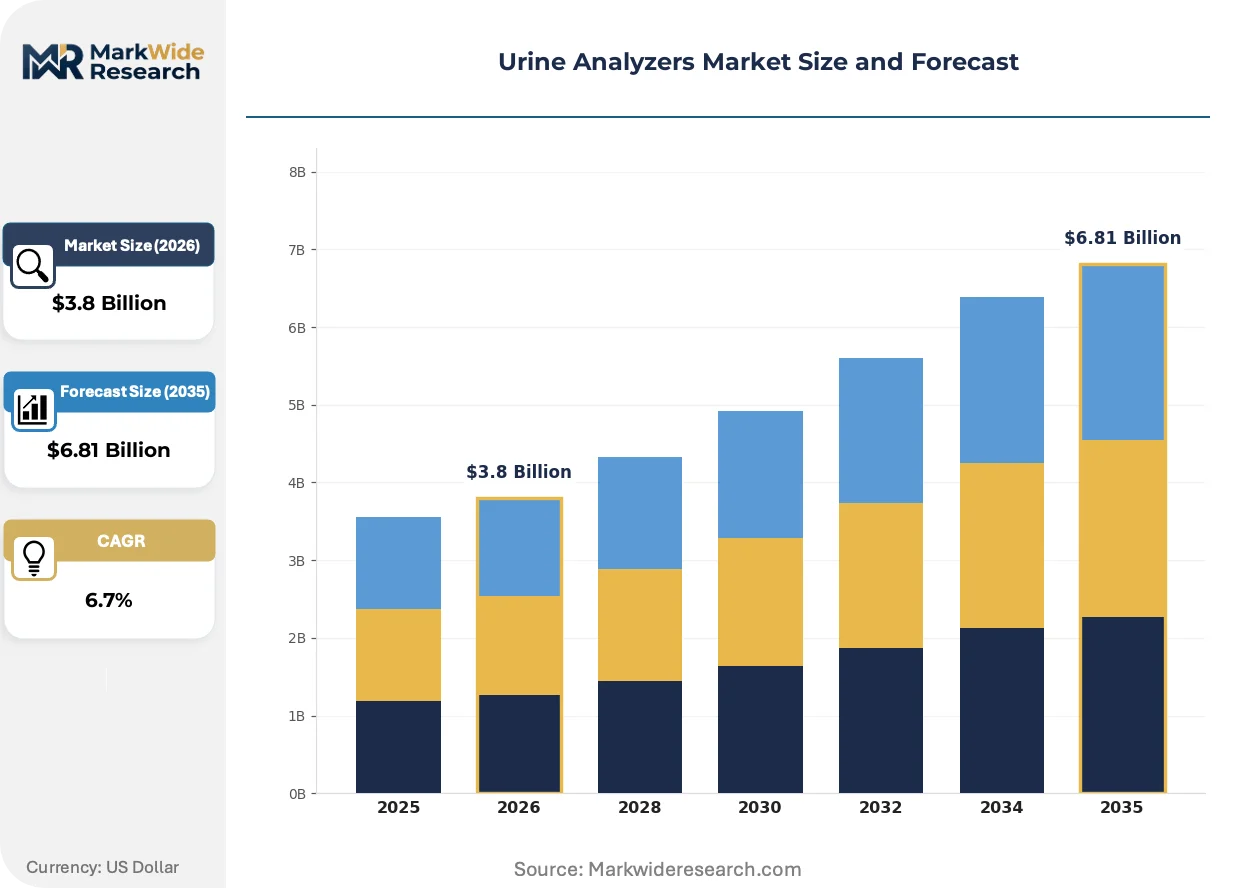
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Analyzers, Semi-Automatic Analyzers, Portable Analyzers, Bench-Top Analyzers End User: Hospitals, Laboratories, Clinics, Home Healthcare Technology: Colorimetric Analysis, Microscopic Examination, Electrophoresis, Flow Cytometry Application: Diabetes Management, Kidney Function Assessment, Infection Testing, Drug Screening |
| Companies Covered | Sysmex Corporation, ARKRAY Inc., Siemens Healthineers, Beckman Coulter Inc., 77 Elektronika Kft, F. Hoffmann-La Roche Ltd., Cardinal Health, Abbott, QuidelOrtho Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urine Analyzers Market Evolving Landscape
Digital morphology and artificial intelligence are converging to reduce manual microscopy dependency while regulatory frameworks on both sides of the Atlantic recalibrate validation requirements for software-as-a-medical-device functionality.
Flow cytometry urinalysis is unifying physical, chemical, and cellular analysis into single-platform workflows. Academic medical centers and high-volume reference laboratories are adopting these systems at accelerating pace. This technology compression is eliminating discrete analyzer islands and reducing laboratory footprint requirements.
The EU In Vitro Diagnostic Regulation is mandating clinical evidence documentation for Class C and D devices that previously required only self-certification. Manufacturers are restructuring quality management systems to accommodate notified body audits. European hospital procurement committees are delaying purchase decisions pending MDR certificate availability.
Consolidated buying by integrated delivery networks is compressing vendor evaluation cycles and elevating total cost-of-ownership analysis. Multi-year reagent supply agreements are displacing capital purchase models in the United States. This behavioral shift is most pronounced among systems operating more than 50 hospital laboratories.
Urine Analyzers Market Segmentation
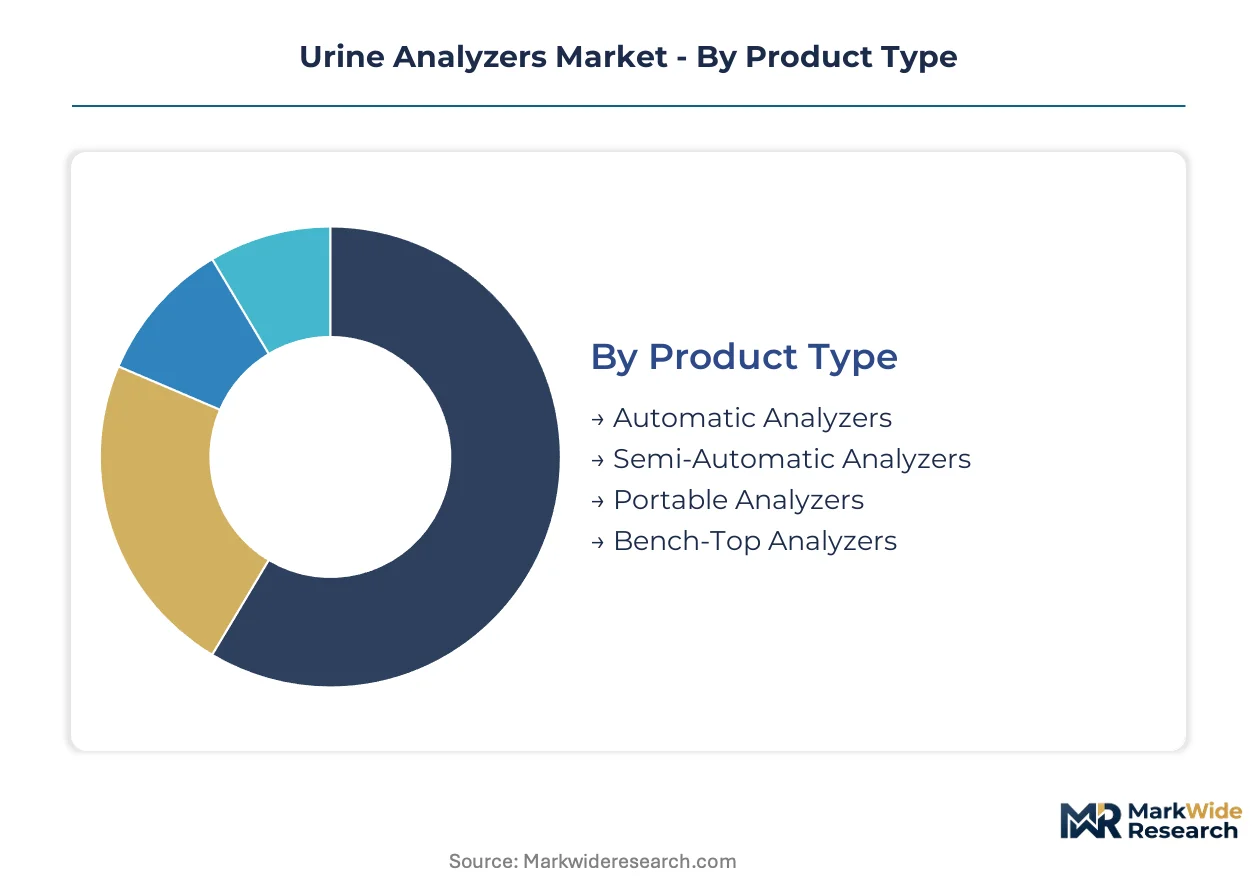
Urine analyzer procurement patterns diverge sharply across installation settings, with throughput economics governing hospital decisions while portability drives ambulatory expansion. Manufacturers configure product portfolios around these divergent operational requirements, creating distinct supply chains for high-volume centralized systems versus distributed point-of-care devices.
Product Type:
Supply concentration in precision photodetector manufacturing concentrates production of high-throughput systems among vendors with established Japanese and German component partnerships.
- Automatic Analyzers:These systems integrate sample handling, photometric detection, and particle counting into continuous workflows processing hundreds of specimens hourly. Hospital laboratories in the United States deploy these platforms to manage rising test volumes without proportional staffing increases under CLIA personnel requirements.
- Portable Analyzers:Battery-powered units weighing under five kilograms enable testing at bedside, in ambulances, and in home settings. CMS reimbursement expansion for remote patient monitoring is accelerating deployment in Medicare Advantage networks seeking to reduce emergency department utilization.
- Semi-Automatic Analyzers:Mid-tier systems requiring technologist intervention for sample loading suit laboratories with moderate throughput and capital constraints.
- Bench-Top Analyzers:Compact footprint designs occupy limited counter space in physician office laboratories and small clinical facilities.
Today's leader: Automatic Analyzers. Tomorrow's challenger: Portable Analyzers.
End User:
Customer procurement authority is consolidating, with integrated health networks in the United States centralizing decisions across dozens of affiliated laboratories.
- Hospitals:Academic medical centers and community hospital systems generate the highest specimen volumes, driving demand for flow cytometry-based systems with automated particle classification. These institutions prioritize vendors with multi-site service infrastructure and documented FDA quality system compliance.
- Laboratories:Independent reference laboratories and hospital-affiliated central labs focus on throughput economics and LIS integration capabilities. CAP accreditation requirements mandate performance verification protocols that favor established instrument platforms with extensive validation documentation.
- Clinics:Outpatient facilities prioritize rapid turnaround and minimal operator training for same-visit result delivery.
- Home Healthcare:Skilled nursing facilities and home health agencies deploy portable systems for patients with limited mobility.
Procurement gravity centers on Hospitals. Volume expansion is climbing the fastest in Home Healthcare.
Technology:
Technology selection determines capital intensity and regulatory pathway, with flow cytometry modules requiring more extensive FDA premarket notification documentation than colorimetric systems.
- Flow Cytometry:Laser-based particle counting and fluorescence detection enable automated cellular differentiation with reduced manual microscopy dependency. High-volume reference laboratories in the United States adopt these systems to consolidate physical, chemical, and microscopic analysis onto single platforms.
- Colorimetric Analysis:Photometric detection at specified wavelengths measures chemical constituents through reagent strip reflectance. This mature technology dominates installed bases in cost-sensitive settings where cellular analysis proceeds through separate manual microscopy workflows.
- Microscopic Examination:Digital imaging systems capture sediment images for technologist review, bridging manual and automated workflows.
- Electrophoresis:Protein separation techniques support specialized renal and metabolic diagnostics in academic medical centers.
Technology leadership resides with Flow Cytometry. Colorimetric Analysis maintains the broadest installed base penetration.
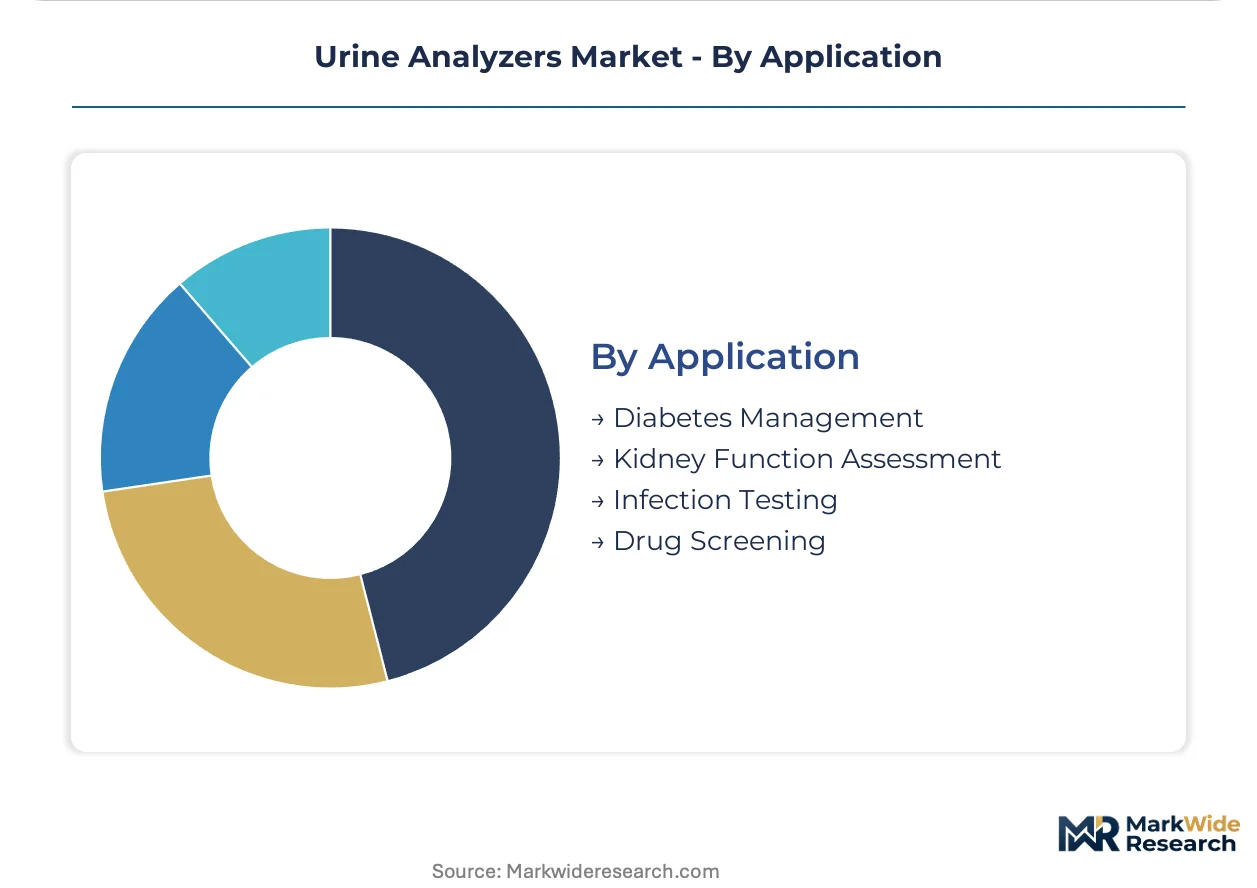
Application:
Reimbursement coding specificity varies across test categories, with diabetes monitoring enjoying more favorable coverage determinations than drug screening panels in United States payer policies.
- Kidney Function Assessment:Albumin-to-creatinine ratio and sediment analysis constitute standard monitoring for chronic kidney disease progression. Nephrology practices and primary care networks drive consistent demand as diabetes and hypertension prevalence expands the at-risk population.
- Diabetes Management:Glucose and ketone monitoring through urine specimens supports glycemic control verification, particularly in type 1 diabetes and gestational diabetes populations. Endocrinology clinics and diabetes educators represent concentrated demand pockets.
- Infection Testing:Urinalysis with culture correlation guides antibiotic stewardship decisions in emergency and primary care settings.
- Drug Screening:Workplace compliance and pain management monitoring create demand for adulteration-resistant testing protocols.
Clinical priority centers on Kidney Function Assessment. Steepest expansion trajectory appears in Diabetes Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates high-throughput flow cytometry demand within integrated health networks, while Japan anchors precision photodetector supply chains for laser-based particle counting modules. Germany's laboratory infrastructure favors automated urinalysis consolidation under EU MDR compliance timelines.
United States
Hospital laboratory consolidation across Kaiser Permanente and HCA Healthcare networks drives centralized procurement of CLIA-validated systems. FDA enforcement of clinical laboratory improvement amendments elevates barriers for new instrument entrants. The Research Triangle Park cluster in North Carolina hosts reference laboratories deploying multi-site automated workflows.
Germany
Academic medical centers in Baden-Württemberg and Bavaria prioritize flow cytometry platforms with documented EU MDR conformity assessment. The country's national pharmaceutical regulator mandates clinical evidence documentation for Class C in vitro diagnostic devices. Berlin-Brandenburg laboratories are restructuring quality management systems ahead of notified body audit schedules.
Japan
Domestic demand for compact bench-top systems concentrates in Tokyo and Osaka metropolitan hospital networks. METI standards govern precision optical component manufacturing for laser diode modules. The Nagoya industrial corridor supplies photodetectors to global flow cytometry instrument assemblers.
India
The National Health Mission expansion into tier-2 and tier-3 cities creates demand for cost-optimized semi-automatic analyzers. CDSCO medical device rules classify urine analyzers under import licensing requirements with post-market surveillance obligations. Maharashtra's private laboratory networks in Mumbai and Pune are adopting subscription-based reagent rental models.
China
Domestic production of colorimetric analysis systems accelerates under NMPA Class II medical device registration pathways. The country's national pharmaceutical regulator requires clinical trial data for novel flow cytometry platforms. Yangtze River Delta diagnostic manufacturers in Shanghai and Suzhou are scaling automated microscopy integration.
Urine Analyzers Market Competitive Landscape
Top-tier vendors anchor hospital and reference laboratory segments, while mid-tier specialists occupy space-constrained clinical settings and emerging market tiers. Siemens Healthineers and Sysmex Corporation exemplify the integrated service infrastructure archetype, whereas ARKRAY Inc. represents compact system specialization. Beckman Coulter Inc. occupies the diversified diagnostics conglomerate position. Strategic moves concentrate on multi-year reagent supply agreements displacing capital purchase models, alongside AI-enabled particle classification partnerships bridging flow cytometry and digital morphology.
Within the precision photonics tier, Sysmex Corporation and ARKRAY Inc. exemplify divergent scale strategies—one anchoring high-volume particle-counting platforms, the other specializing in footprint-optimized bench-top configurations. Siemens Healthineers AG represents the service-integrated conglomerate archetype, leveraging multi-site contract management capabilities across installed bases. Beckman Coulter Inc. occupies a diversified position within broader clinical chemistry portfolios. These three entities collectively illustrate how technology differentiation and geographic footprint govern competitive positioning under tightening FDA and EU regulatory frameworks.
| Leading Market Players |
|---|
| Sysmex Corporation |
| ARKRAY Inc. |
| Siemens Healthineers |
| Beckman Coulter Inc. |
| 77 Elektronika Kft |
| F. Hoffmann-La Roche Ltd. |
| Cardinal Health |
| Abbott |
| QuidelOrtho Corporation |
| Others |
Value Network & Pricing Analysis
Precision photonics engineering talent clustering in Japan's Nagoya industrial corridor and Germany's Baden-Württemberg region feeds labor-cost differentials that widen pricing spreads between premium flow cytometry systems and economy colorimetric platforms. These regional wage disparities compound with component sourcing economics to stratify manufacturer margins across three distinct performance tiers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for colorimetric analysis modules. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated flow cytometry platforms from CE-marked mid-tier systems and domestically certified economy units. Price differentiation hinges on laser diode precision grades and after-sales service bundling. Cost compression in the economy tier is intensifying because domestic Chinese manufacturers are scaling automated microscopy integration. Reference laboratories exhibit lowest price sensitivity; physician office laboratories face acute budget constraints.
Supply Chain Analysis
Refurbished flow cytometry modules and certified pre-owned photodetector arrays circulate through secondary channels serving India's tier-2 city laboratory networks. Precision photodetectors and laser diodes draw from Japan, Germany, and the United States. Raw material dependencies include silicon photomultipliers, optical-grade sapphire windows, and rare-earth doped laser crystals. Single-source vulnerability concentrates in Japanese suppliers of high-sensitivity avalanche photodiodes. Distribution runs through authorized service distributors with regional technical certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The urine analyzers market functions as a regulatory compounder where FDA CLIA enforcement and EU MDR transition timelines continuously elevate compliance-driven replacement demand. These overlapping regulatory milestones sustain vendor pricing power while compressing procurement cycles for validated systems.
For Market Incumbents: Deepen multi-site service infrastructure penetration across integrated health networks to lock in reagent rental contracts. Incumbent vendors must accelerate AI-enabled particle classification R&D to defend against software-as-a-medical-device entrants. Backward integration into precision photodetector sourcing reduces exposure to Japanese supplier concentration.
For New Entrants and Emerging Players: AI-powered sediment classification algorithms offer a technology-first wedge into the portable analyzer segment where incumbents lag software development. India's tier-2 and tier-3 city private laboratory networks represent the most penetrable geography. A reagent rental partnership model with Maharashtra-based diagnostic chains bypasses capital purchase barriers.
For Investors and Strategic Acquirers: Integrated health network procurement committees are the most active acquirer in this space, consolidating vendor relationships across affiliated laboratories. Long-term viability rests on recurring revenue conversion from capital equipment to subscription service models. Acquisition targets should demonstrate EU MDR conformity assessment progress and installed base density. Monitor CMS remote patient monitoring reimbursement determinations as volume redistribution signal.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Particle Classification Development | Machine learning algorithms trained on flow cytometry scatter patterns reduce false-positive rates and manual microscopy dependency. |
| Reagent Rental Subscription Conversion | Per-test pricing arrangements penetrate integrated health networks seeking operational budget flexibility over capital expenditure. |
| EU MDR Conformity Assessment Completion | Notified body certification unlocks European hospital procurement committees delaying purchase decisions pending certificate availability. |
| Compact Bench-Top System Localization | Footprint-optimized configurations address space-constrained clinical laboratories in Japan's Tokyo and Osaka metropolitan networks. |
| HL7 FHIR Interface Standardization | Modern laboratory information system connectivity resolves legacy LIS integration complexity for health systems with decades-old infrastructure. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and emerging markets, with primary inputs from each region's hospital laboratory networks and diagnostic manufacturers. The analysis combines structured interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists with secondary validation from FDA 510(k) filings, EU MDR notified body databases, CMS reimbursement determinations, and hospital procurement databases. Bottom-up instrument shipment tracking and top-down healthcare expenditure analysis provide triangulation.
Granularity extends to product type, end user, technology, and application dimensions across the projection horizon. The analytical framework models automatic, portable, semi-automatic, and bench-top analyzer categories separately. CAGRs derive from regression analysis against hospital laboratory consolidation rates and CLIA personnel requirement changes. Industry-specific inputs include flow cytometry adoption curves in academic medical centers and remote patient monitoring reimbursement expansion trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR notified body capacity constraints and CMS policy shifts on decentralized testing. Forecasts reflect assumptions about regulatory enforcement continuity and component supply stability. Practitioners should monitor FDA guidance on software-as-a-medical-device validation and photodetector supplier geographic diversification for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Digital Diagnostic Audiometer Market
Diagnostic Devices
Immunochromatography Kits Market
Diagnostic Devices
Skin Moisture Detectors Market
Diagnostic Devices
Electrochemical Biosensors Market
Diagnostic Devices
Immunology-Oncology ELISA Kits Market
Diagnostic Devices
Cotinine Screening Devices Market
Diagnostic Devices
Europe Point of Care Diagnostics Market
Diagnostic Devices
Breathalyzers Market
Diagnostic Devices
Diagnostic Stopper Market
Diagnostic Devices
ENT Diagnostic Devices Market
Diagnostic Devices
AI Portable Chest X-ray Triage Device Market
Diagnostic Devices
Contactless Vital Sign Monitoring Device Validation Test Platforms Market
Diagnostic Devices
Hearing Screening Diagnostic Devices Market
Diagnostic Devices
Diagnostic Ophthalmic Devices Market
Diagnostic Devices
Biopsy Guidance System Market
Diagnostic Devices
Ocular Allergy Diagnostic System Market