
 Breathalyzers Market | 2026-2036
Breathalyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Breathalyzers Market Intelligence
Multi-source procurement of fuel cell sensors is shifting toward captive production among tier-one manufacturers. Drägerwerk AG & Co. KGaA anchors its position through backward integration into electrochemical sensor fabrication. Lifeloc Technologies, Inc. differentiates via laser-focused specialization in law enforcement-grade calibration protocols. BACtrack competes aggressively in the direct-to-consumer channel with app-connected semiconductor models.
A breathalyzer is an analytical instrument that quantifies blood alcohol concentration from exhaled breath, typically employing fuel cell or infrared spectroscopy technology with detection thresholds as precise as 0.001% BAC for evidential-grade units. The device serves commercial and institutional buyers who require legally defensible intoxication screening for traffic safety, employment compliance, and medical triage. Professional-grade fuel cell devices command the deepest margin pools due to calibration burdens and certification requirements. Personal semiconductor units represent the fastest-expanding volume tier, though price compression limits profitability. Police and wall-mounted installations remain mature segments with replacement-driven demand cycles.
The U.S. Department of Transportation, OSHA, and Germany's KBA collectively mandate evidential-grade accuracy for workplace and roadside screening, creating a dual-tier compliance environment that filters out uncertified suppliers. FDA oversight of medical-use breathalyzers adds a separate clearance pathway for devices deployed in rehabilitation and emergency medicine. Stakeholders must monitor evolving accuracy standards and sensor supply security as enforcement agencies tighten interoperability requirements across jurisdictions.
Market Dynamics
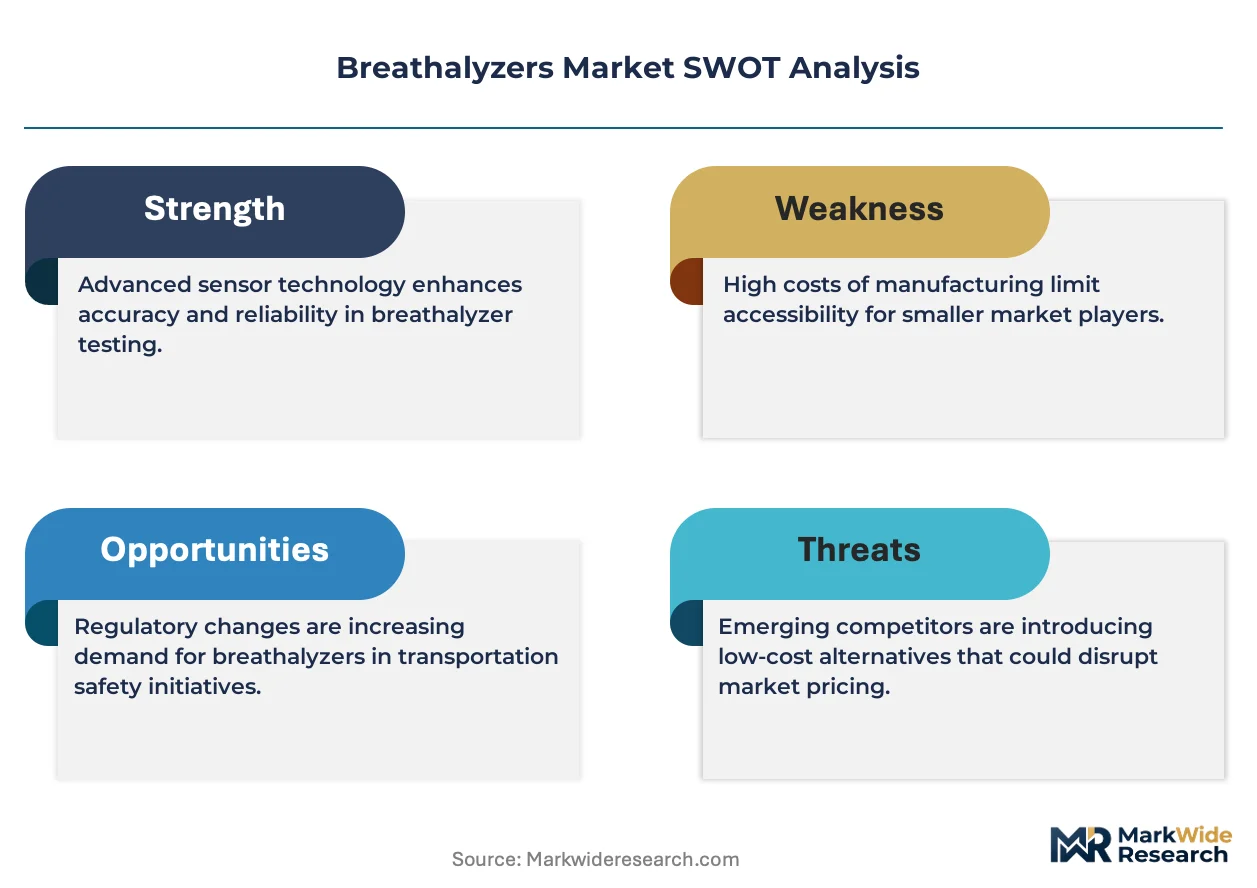
Workplace safety mandates and sensor supply consolidation are restructuring competitive advantage around calibration certification and captive electrochemical production rather than device assembly alone.
Growth Catalysts
- OSHA workplace screening expansion:Mining and logistics firms in the United States face intensified compliance audits, accelerating fleet-wide breathalyzer deployment across shift-change protocols.
- Fuel cell precision thresholds:Evidential-grade detection at 0.001% BAC enables law enforcement agencies to replace infrared spectroscopy units in roadside checkpoints.
- Germany's occupational health audits:Fleet operators under KBA jurisdiction must document alcohol-free duty periods, creating institutional procurement pipelines for wall-mounted monitoring systems.
Market Restraints
- Platinum catalyst cost volatility:Fuel cell electrodes depend on platinum group metals whose price swings compress margin stability for electrochemical sensor manufacturers.
- Sensor supply concentration:Three Asian component suppliers control bulk electrochemical membrane fabrication, exposing tier-one device makers to single-source vulnerability.
- Semiconductor accuracy ceilings:Metal oxide sensors in personal units lack evidential-grade reliability, restricting their use to non-binding self-monitoring despite volume expansion.
Strategic Opportunities
- Rehabilitation clinic integration:FDA-cleared medical breathalyzers for emergency triage remain underdeployed in addiction treatment centers, opening recurring revenue streams through calibration subscriptions.
- App-connected preventive monitoring:Direct-to-consumer platforms pair semiconductor hardware with telehealth dashboards, capturing wellness-oriented buyers outside enforcement channels.
- EU Green Deal procurement standards:Public sector tenders increasingly require recyclable sensor housings and reduced platinum loadings, rewarding redesign investments with preferential contract access.
Industry Challenges
- Calibration technician scarcity:Evidential-grade certification demands specialized training in electrochemical drift correction that outpaces vocational program output in most markets.
- Interoperability standard delays:Jurisdictional fragmentation in data formats between NHTSA, KBA, and national police forces forces redundant engineering for multi-market suppliers.
- Legacy fleet replacement cycles:Wall-mounted installations in mature segments exhibit decade-long refresh intervals, compressing near-term revenue visibility for established product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breathalyzers Market |
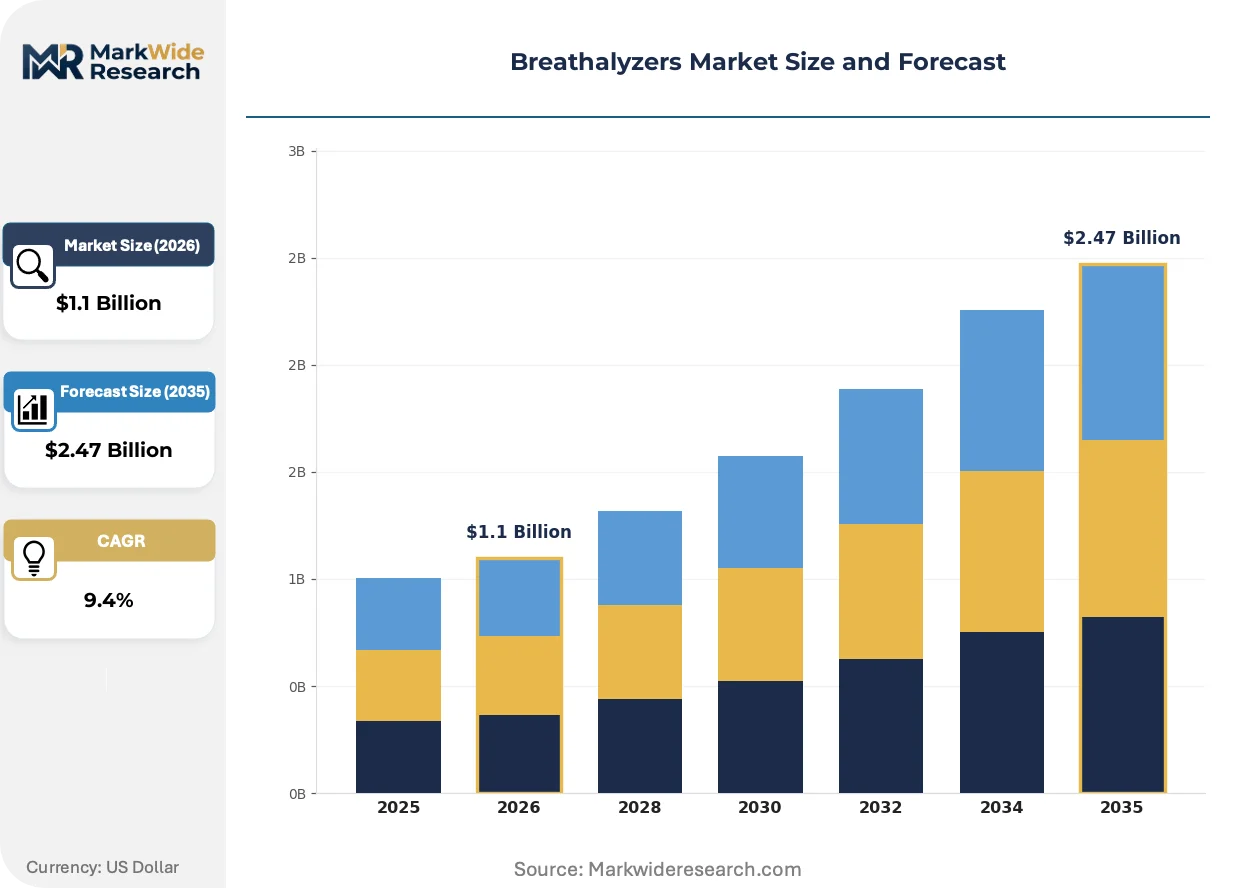
| Market Size in 2026 | $1.1 Billion |
| Market Size in 2035 | $2.47 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Professional, Personal, Police, Portable, Chamber, Wall-Mounted Technology: Fuel Cell, Semiconductor, Infrared Spectroscopy, Tin Oxide, Electrochemical, Metal Oxide Application: Traffic Enforcement, Workplace Safety, Rehabilitation Centers, Hospitality, Event Security, Transportation Safety End User: Law Enforcement Agencies, Occupational Safety Departments, Medical Facilities, Event Organizers, Public Transportation Providers, Educational Institutions |
| Companies Covered | Drägerwerk AG & Co. KGaA, Lifeloc Technologies, Inc., Intoximeters, Alcohol Countermeasure Systems Corp., BACtrack, Lion Laboratories, Alcolizer Pty Ltd, Bedfont Scientific Ltd., Quest Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breathalyzers Market Strategic Shifts & Innovations
Infrared spectroscopy miniaturization and fuel cell material substitution are compressing cost-performance trade-offs while regulatory data-sharing mandates reshape procurement specifications across enforcement and occupational health channels.
Fuel cell technology is converging with solid-state electrochemical architectures to reduce platinum loading while maintaining evidential-grade precision. Law enforcement procurement agencies in Germany and the United States are piloting these hybrid sensors for roadside deployment. This convergence is compressing the cost gap between professional and personal device tiers, threatening semiconductor-based market positions in the mid-range segment.
The U.S. Department of Transportation's updated screening mandates tighten accuracy thresholds and mandate digital chain-of-custody documentation for admissible evidence. Device manufacturers must now embed tamper-evident logging and encrypted data transmission to qualify for federal procurement. Police departments and commercial fleet operators face 18-month compliance windows, accelerating replacement demand for legacy analog units.
Subscription calibration services are displacing one-time hardware sales in institutional channels. Fleet management firms and rehabilitation clinics now prioritize vendors offering remote diagnostics and automated recertification scheduling over lowest-unit-cost procurement. This shift concentrates vendor relationships around service capability rather than sensor specifications, with strongest uptake in Germany's occupational health audit environment.
Breathalyzers Market Segmentation
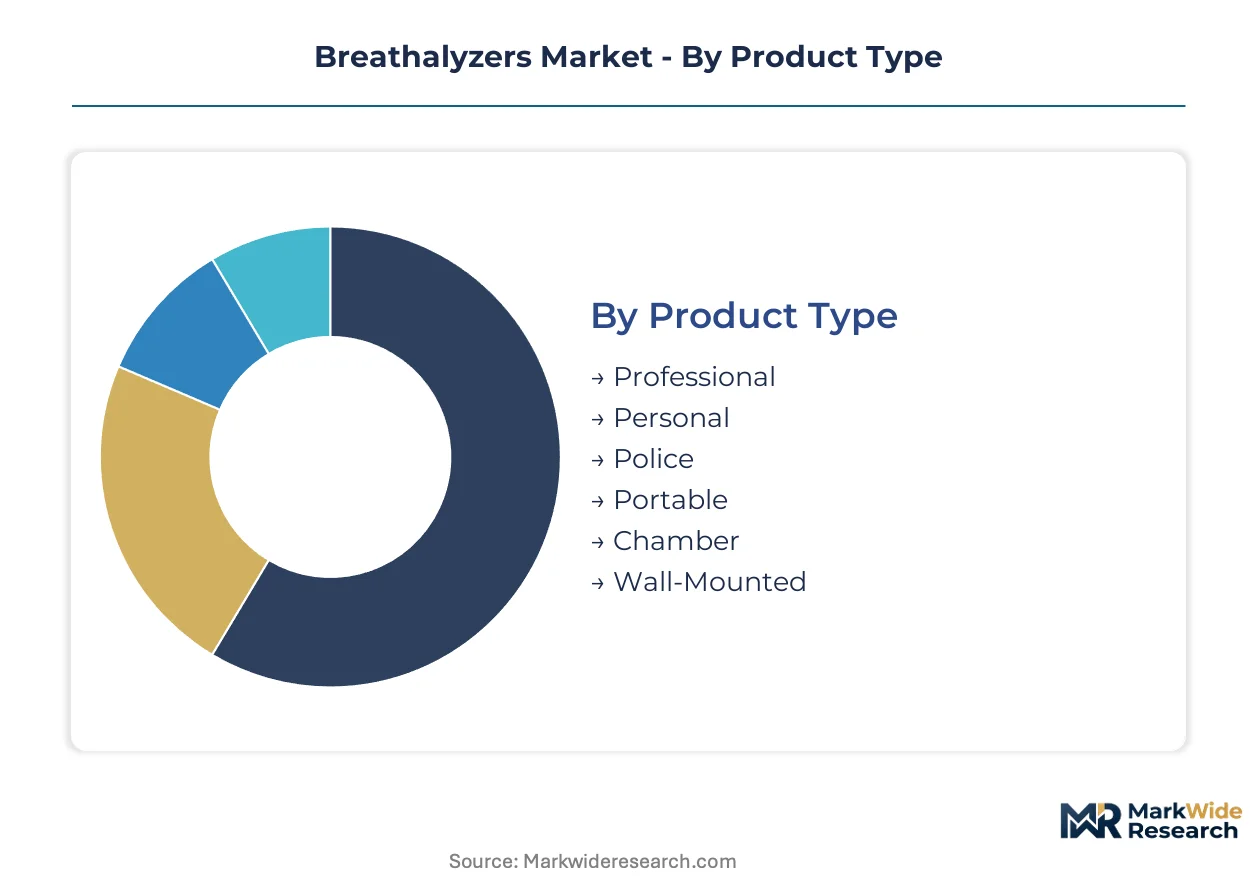
Breathalyzer procurement patterns diverge sharply across use cases, with certification grade and calibration burden determining vendor selection more than unit economics alone. Segmentation reveals how fuel cell precision commands institutional budgets while semiconductor portability captures consumer volume.
Product Type:
Capital intensity peaks in wall-mounted and police-grade installations, where fixed infrastructure and certification documentation drive upfront outlays.
- Professional:Evidential-grade fuel cell devices with 0.001% BAC detection thresholds serve fleet operators and occupational health auditors. Mining and logistics firms in the United States deploy these across shift-change protocols under intensified OSHA compliance audits.
- Personal:Semiconductor-based handheld units with app connectivity target wellness-oriented consumers outside enforcement channels. BACtrack and similar vendors compete aggressively on price in this direct-to-consumer tier, though accuracy ceilings restrict use to non-binding self-monitoring.
- Police:Roadside units with tamper-evident logging and encrypted data transmission satisfy U.S. Department of Transportation chain-of-custody mandates. Germany's KBA jurisdiction drives parallel procurement for admissible evidence standards.
- Portable:Battery-operated field units balance mobility with fuel cell precision for event security and transportation spot checks.
- Chamber:Enclosed sampling systems reduce ambient interference in medical and rehabilitation settings requiring documented repeatability.
- Wall-Mounted:Fixed installations in fleet depots and industrial facilities exhibit decade-long replacement cycles, compressing near-term revenue visibility.
Professional-grade devices absorb the bulk of installed capacity; personal units are expanding most quickly.
Technology:
Technology selection locks in margin structure through platinum loading, calibration frequency, and certification pathway requirements.
- Fuel Cell:Platinum-catalyzed electrochemical sensors deliver evidential-grade precision with 0.001% BAC thresholds. Drägerwerk AG anchors supply security through backward integration into electrochemical membrane fabrication.
- Semiconductor:Metal oxide sensors in personal devices sacrifice accuracy for cost compression, capturing volume despite exclusion from legally defensible screening.
- Infrared Spectroscopy:Miniaturized optical benches pilot in German and U.S. law enforcement for roadside deployment, threatening mid-range semiconductor positions.
- Tin Oxide:Early-generation semiconductor chemistry persists in legacy personal units facing replacement by solid-state alternatives.
- Electrochemical:Solid-state architectures reduce platinum loading while maintaining precision, converging with fuel cell performance at lower cost tiers.
- Metal Oxide:Broad sensor category spanning tin oxide and newer formulations, differentiated by selectivity and drift characteristics.
Fuel cell platforms dominate institutional procurement; electrochemical solid-state alternatives are gaining share fastest.
Application:
Application mix determines regulatory exposure, with enforcement and occupational health channels subject to distinct compliance architectures.
- Traffic Enforcement:Roadside checkpoint deployment demands evidential-grade accuracy and digital chain-of-custody documentation under U.S. Department of Transportation mandates. Police departments face 18-month compliance windows for legacy analog replacement.
- Workplace Safety:Mining and logistics firms implement fleet-wide breathalyzer protocols under intensified OSHA audits, creating recurring calibration subscription revenue.
- Rehabilitation Centers:FDA-cleared medical devices for addiction treatment remain underdeployed, opening recurring revenue through calibration subscriptions.
- Hospitality:Bars and restaurants deploy personal-grade units for liability mitigation without evidential requirements.
- Event Security:Temporary deployment of portable units at concerts and sporting venues drives rental and short-term procurement.
- Transportation Safety:Public transit and commercial fleet operators under Germany's KBA jurisdiction document alcohol-free duty periods through wall-mounted monitoring.
Workplace safety absorbs the bulk of institutional procurement; rehabilitation centers are climbing the fastest.
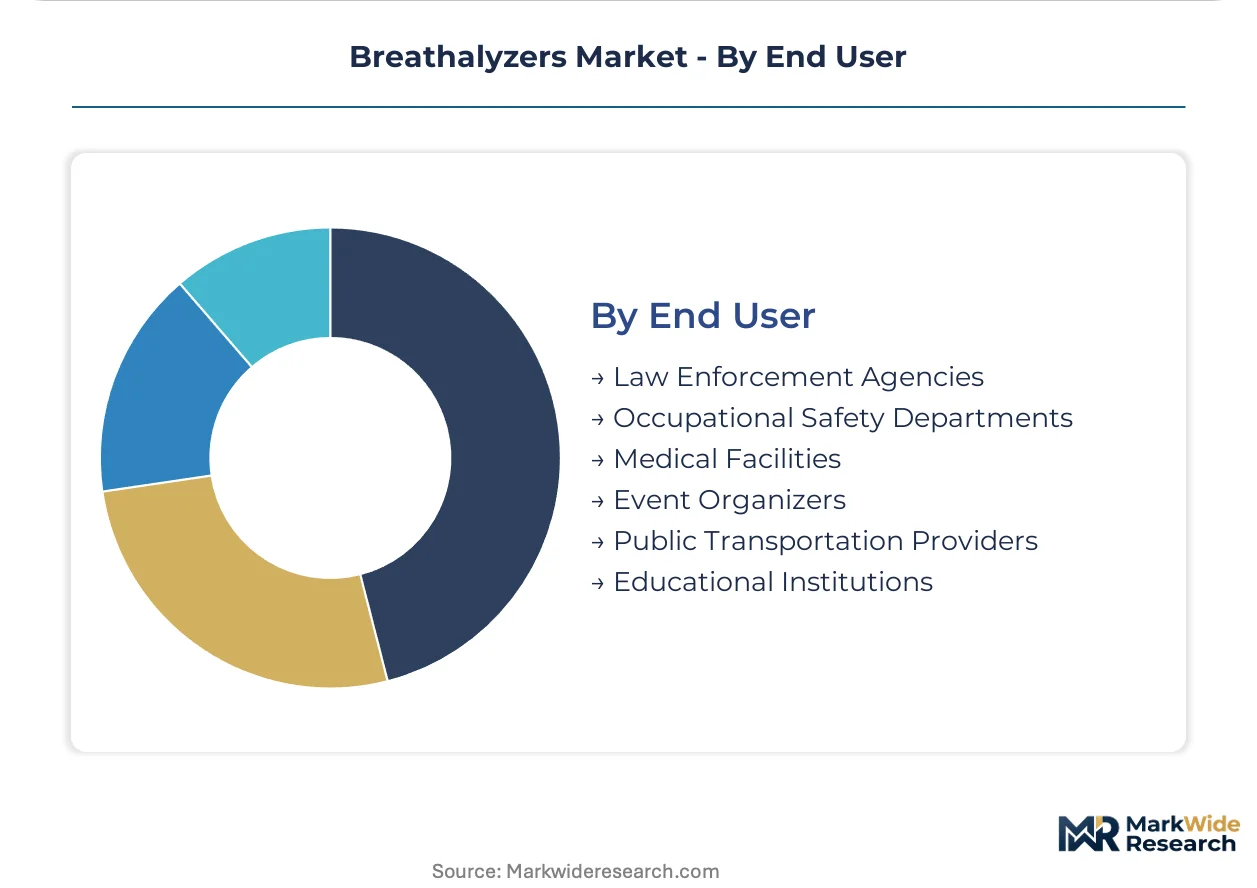
End User:
End-user concentration shapes vendor relationship economics, with subscription calibration displacing one-time hardware sales in institutional accounts.
- Law Enforcement Agencies:Federal, state, and municipal police departments procure through NHTSA-compliant tender processes prioritizing tamper-evident logging and encrypted transmission.
- Occupational Safety Departments:Corporate safety offices in mining, logistics, and manufacturing prioritize vendors offering remote diagnostics and automated recertification scheduling.
- Medical Facilities:Emergency departments and addiction clinics require FDA-cleared devices with medical-use labeling distinct from law enforcement specifications.
- Event Organizers:Temporary staffing agencies and venue operators rent portable units for single-event liability coverage.
- Public Transportation Providers:Municipal transit authorities deploy wall-mounted systems in operator facilities under occupational health mandates.
- Educational Institutions:University health services and campus safety offices adopt personal-grade units for student wellness programs without enforcement authority.
Occupational safety departments command the deepest vendor relationships; medical facilities are expanding procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for evidential-grade breathalyzers concentrates in jurisdictions with strict occupational health mandates and roadside enforcement protocols. Fleet operators and law enforcement agencies drive procurement in Germany and the United States, while mining and logistics sectors expand workplace screening across multiple continents.
United States
OSHA workplace screening expansion accelerates fleet-wide breathalyzer deployment across mining and logistics firms. The Department of Transportation mandates digital chain-of-custody documentation and tamper-evident logging for admissible evidence. Police departments in California and Texas face 18-month compliance windows for legacy analog replacement.
Germany
KBA jurisdiction requires fleet operators to document alcohol-free duty periods through wall-mounted monitoring systems. Occupational health audits intensify procurement of evidential-grade devices with 0.001% BAC precision. Industrial clusters in Bavaria and North Rhine-Westphalia anchor calibration subscription growth for corporate safety programs.
China
Transportation safety mandates expand breathalyzer deployment in public transit and commercial fleet operations. National standards for workplace intoxication screening tighten compliance thresholds for logistics enterprises. Manufacturing zones in the Yangtze River Delta and Pearl River Delta concentrate semiconductor sensor production for personal device exports.
Japan
METI guidelines for occupational safety drive corporate adoption of fuel cell precision devices in manufacturing and construction sectors. Medical-use breathalyzers for rehabilitation clinics gain traction under PMDA oversight. The Kansai region around Osaka hosts specialized calibration service providers serving institutional accounts.
Australia
Mining sector safety protocols mandate pre-shift breathalyzer screening at remote extraction sites. State transportation authorities deploy roadside units with encrypted data transmission for enforcement admissibility. Western Australia and Queensland concentrate wall-mounted installation demand in resource extraction facilities.
Breathalyzers Market Key Industry Players
Backward integration into electrochemical sensor fabrication dominates the current landscape as tier-one manufacturers secure supply chains against platinum volatility. The vendor base separates into three distinct tiers: integrated specialists with captive membrane production, calibration-focused service providers, and direct-to-consumer hardware vendors competing on price. Strategic archetypes include precision-grade institutional suppliers, wellness-oriented consumer brands, and regional compliance specialists. Capacity expansion in solid-state electrochemical architectures and M&A consolidation of calibration service networks represent the dominant competitive moves reshaping positioning.
Among integrated European manufacturers, Drägerwerk AG & Co. KGaA exemplifies the backward-integrated archetype through in-house electrochemical membrane production. Lifeloc Technologies, Inc. occupies a position within the calibration-specialist tier, anchoring service capability around law enforcement-grade protocols. BACtrack represents the consumer-facing vector, competing through app-connected hardware in direct-to-consumer channels outside enforcement markets.
| Leading Market Players |
|---|
| Drägerwerk AG & Co. KGaA |
| Lifeloc Technologies, Inc. |
| Intoximeters |
| Alcohol Countermeasure Systems Corp. |
| BACtrack |
| Lion Laboratories |
| Alcolizer Pty Ltd |
| Bedfont Scientific Ltd. |
| Quest Products, Inc. |
| Others |
Cost & Logistics Intelligence
Platinum group metal price volatility cascades through electrochemical sensor fabrication into three distinct pricing tiers for breathalyzer procurement. Fuel cell electrodes draw from spot-market platinum loadings that compress margin stability for manufacturers, forcing cost absorption or tiered pass-through to fleet operators, law enforcement agencies, and direct-to-consumer channels.
Pricing Analysis
Volume concentrates in personal semiconductor units while margins pool in professional fuel cell devices. Three-tier pricing structure across evidential-grade, workplace-certified, and personal self-monitoring levels separates certification burden from portability convenience. Cost compression in the consumer tier intensifies because semiconductor accuracy ceilings restrict use to non-binding applications. Fleet operators under OSHA and KBA mandates exhibit lowest price sensitivity; wellness-oriented buyers through direct-to-consumer channels show highest elasticity.
Supply Chain Analysis
Reverse-logistics flows for calibration recertification create recurring revenue infrastructure that anchors vendor relationships in institutional channels. Electrochemical membrane fabrication concentrates in Japan, South Korea, and China, with three Asian component suppliers controlling bulk production. Fuel cell electrodes rest on platinum catalyst and Nafion membrane dependencies. Single-source vulnerability in electrochemical membrane supply exposes tier-one device makers to disruption. Distribution runs through direct OEM relationships for institutional procurement and e-commerce platforms for consumer sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The breathalyzer market sits in a technology-transition phase as solid-state electrochemical architectures displace legacy infrared spectroscopy units in roadside enforcement applications.
For Market Incumbents: Hedge against platinum cost volatility through captive electrochemical membrane production or long-term offtake agreements with Asian component suppliers. Secure calibration technician training pipelines ahead of OSHA workplace screening expansion that intensifies demand for evidential-grade certification. Defensive consolidation around service capability rather than sensor specifications concentrates vendor relationships. For New Entrants and Emerging Players: FDA clearance pathways for medical-use breathalyzers in rehabilitation clinics open a window for recurring calibration subscription revenue outside saturated enforcement channels. Target addiction treatment centers and emergency departments with FDA-cleared devices distinct from law enforcement specifications. Pursue telehealth platform partnerships for app-connected preventive monitoring in wellness-oriented consumer segments. For Investors and Strategic Acquirers: Distressed-cycle entries favor calibration service networks in Germany and the United States where occupational health audit mandates institutionalize recurring revenue. Long-term viability hinges on vendor relationships built around remote diagnostics and automated recertification scheduling. Monitor solid-state electrochemical pilot programs in German and U.S. law enforcement for inflection signals on technology substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrochemical Sensors | Drägerwerk AG anchors supply security through captive membrane fabrication against platinum volatility. |
| Calibration Service Network Expansion | Subscription recertification displaces one-time hardware sales in Germany's KBA-mandated occupational health environment. |
| FDA Medical-Use Clearance Pathway | Rehabilitation clinic integration opens recurring revenue streams distinct from enforcement channel saturation. |
| Solid-State Electrochemical R&D Investment | Hybrid sensor pilots in German and U.S. roadside deployment threaten mid-range semiconductor market positions. |
| Telehealth Platform Partnership | App-connected preventive monitoring captures wellness-oriented buyers outside traditional enforcement procurement channels. |
Research Approach
Document review covered FDA 510(k) filings, DOT NHTSA procurement specifications, and KBA technical standards, complemented by interviews with electrochemical sensor procurement leads at tier-one manufacturers, calibration service technicians, fleet safety managers at mining and logistics firms, and rehabilitation clinic operations directors. Secondary validation drew from OSHA enforcement data, German occupational health audit reports, and platinum group metal price benchmarks. Bottom-up unit economics triangulated against top-down regulatory mandate sizing.
Historical shipment data cross-referenced against expert panel input on compliance window timing across jurisdictions. Segmentation modeled technology type, certification grade, application channel, and end-user concentration across the analysis window. CAGRs derived from installation base growth, replacement cycle compression, and subscription service attach rates. Platinum price trajectories and calibration technician supply constraints informed margin sensitivity scenarios.
Caveats apply where OSHA enforcement intensity, KBA audit scope expansion, or solid-state electrochemical technology maturation could materially shift the outlook. Practitioners should monitor pilot program outcomes in German and U.S. roadside deployment and platinum group metal price volatility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Contactless Vital Sign Monitoring Device Validation Test Platforms Market
Diagnostic Devices
Point-Of-Care Breathalyzer Market
Diagnostic Devices
Pulmonary Function Testing Devices Market
Diagnostic Devices
Dual Energy X-Ray Absorptiometry Market
Diagnostic Devices
Non-Invasive Biosensors Market
Diagnostic Devices
Hearing Screening Diagnostic Devices Market
Diagnostic Devices
Pelvic Floor Diagnostics Market
Diagnostic Devices
Global Dermatology Diagnostic Devices Market
Diagnostic Devices
US Breath Analyzers Market
Diagnostic Devices
Lung Biopsy Systems Market
Diagnostic Devices
Global Breath Analyzer Market
Diagnostic Devices
Point of Care Blood Testing Devices Market
Diagnostic Devices
Biopsy Devices Market
Diagnostic Devices
Breath Samplers Market
Diagnostic Devices
Global Breast Lesion Localization Methods Market
Diagnostic Devices
Portable Diagnostic Devices Market