
 Artificial Pancreas Market | 2026-2036
Artificial Pancreas Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Pancreas Market Analysis
Algorithm-driven predictive control is reconfiguring how glucose-responsive insulin delivery systems achieve autonomous regulation. Medtronic leverages decades of pump manufacturing scale to anchor its position in integrated closed-loop hardware. Tandem Diabetes Care differentiates through touchscreen-native interfaces and smartphone connectivity that appeals to younger patient cohorts. Dexcom sustains technology leadership in continuous glucose sensing accuracy, which forms the essential input layer for any automated insulin delivery architecture.
An artificial pancreas constitutes a closed-loop metabolic control system combining continuous glucose monitoring, algorithmic processing, and automated insulin delivery to maintain euglycemia without patient-initiated dosing decisions. These systems typically employ subcutaneous glucose sensors sampling interstitial fluid every one to five minutes, paired with control algorithms running on embedded or smartphone-based processors that command either patch or tethered insulin pumps. Closed-loop systems command the dominant share of current revenue as the only fully automated modality, while artificial intelligence segments within algorithm control represent the fastest-expanding capability layer as machine learning enables predictive hypoglycemia prevention and personalized basal rate adaptation. Home care settings absorb the majority of unit volume, though hospitals retain margin concentration through acute inpatient glycemic management protocols and clinical trial sponsorship.
The FDA regulates artificial pancreas systems as Class III medical devices requiring premarket approval, while the EMA's Medical Device Regulation imposes stricter post-market surveillance and clinical evidence requirements for EU market access. BIS certification in India and NMPA oversight in China create additional compliance thresholds for manufacturers seeking entry into high-growth Asia-Pacific territories. Stakeholders must monitor evolving reimbursement decisions from national health technology assessment bodies, as payer willingness to cover fully automated systems versus sensor-augmented pumps will determine the addressable patient population expansion trajectory.
Market Dynamics
The artificial pancreas sector is undergoing structural compression as algorithmic control migrates from embedded pump processors to smartphone-native architectures, collapsing the traditional hardware-software boundary that once defined competitive moats.
Growth Catalysts
- Reimbursement Framework Maturation:The United States Centers for Medicare and Medicaid Services has established Category III CPT codes for therapeutic CGM integration, enabling physician billing for closed-loop system optimization and accelerating clinical adoption.
- Sensor Accuracy Threshold Crossover:Continuous glucose monitoring devices have achieved mean absolute relative difference below eight percent in hypoglycemic ranges, satisfying the input precision requirements for fully autonomous insulin dosing without patient confirmation.
- Algorithmic Personalization:Machine learning models trained on individual glycemic patterns are reducing time-in-range variability by adapting basal rates to circadian rhythms and stress hormone fluctuations unique to each patient physiology.
Market Restraints
- Insulin Analog Cost Concentration:Rapid-acting insulin analogs from three manufacturers command pricing power that constrains total system affordability, particularly in markets lacking therapeutic substitution policies.
- Subcutaneous Sensor Limitation:Interstitial fluid glucose lag times of five to fifteen minutes versus capillary blood create inherent control loop delays that algorithms cannot fully compensate during rapid glucose excursions.
- EMA Post-Market Surveillance Burden:The European Union's Medical Device Regulation mandates annual clinical evidence updates for Class III active implantable devices, extending compliance costs across the product lifecycle.
Strategic Opportunities
- Pediatric Population Expansion:Regulatory approvals for patients aged two to six years remain sparse, creating first-mover advantage for manufacturers completing juvenile glycemic control trials.
- Dual-Hormone Architecture:Convergence of micro-dosed glucagon delivery with insulin automation addresses hypoglycemia prevention without carbohydrate intervention, opening premium positioning.
- India PLI Scheme Alignment:The country's production-linked incentive scheme for medical electronics offers tariff relief and capital subsidies for local manufacturing of CGM transmitters and pump assemblies.
Industry Challenges
- Control Algorithm Validation Burden:FDA premarket approval requires multi-month in-silico testing followed by supervised clinical trials, extending development timelines beyond eighteen months for algorithm updates.
- Interoperability Certification Complexity:Achieving seamless data exchange between sensor, pump, and smartphone platforms demands compliance with IEEE 11073 and Bluetooth SIG medical device profiles that fragment across OEM ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Pancreas Market |
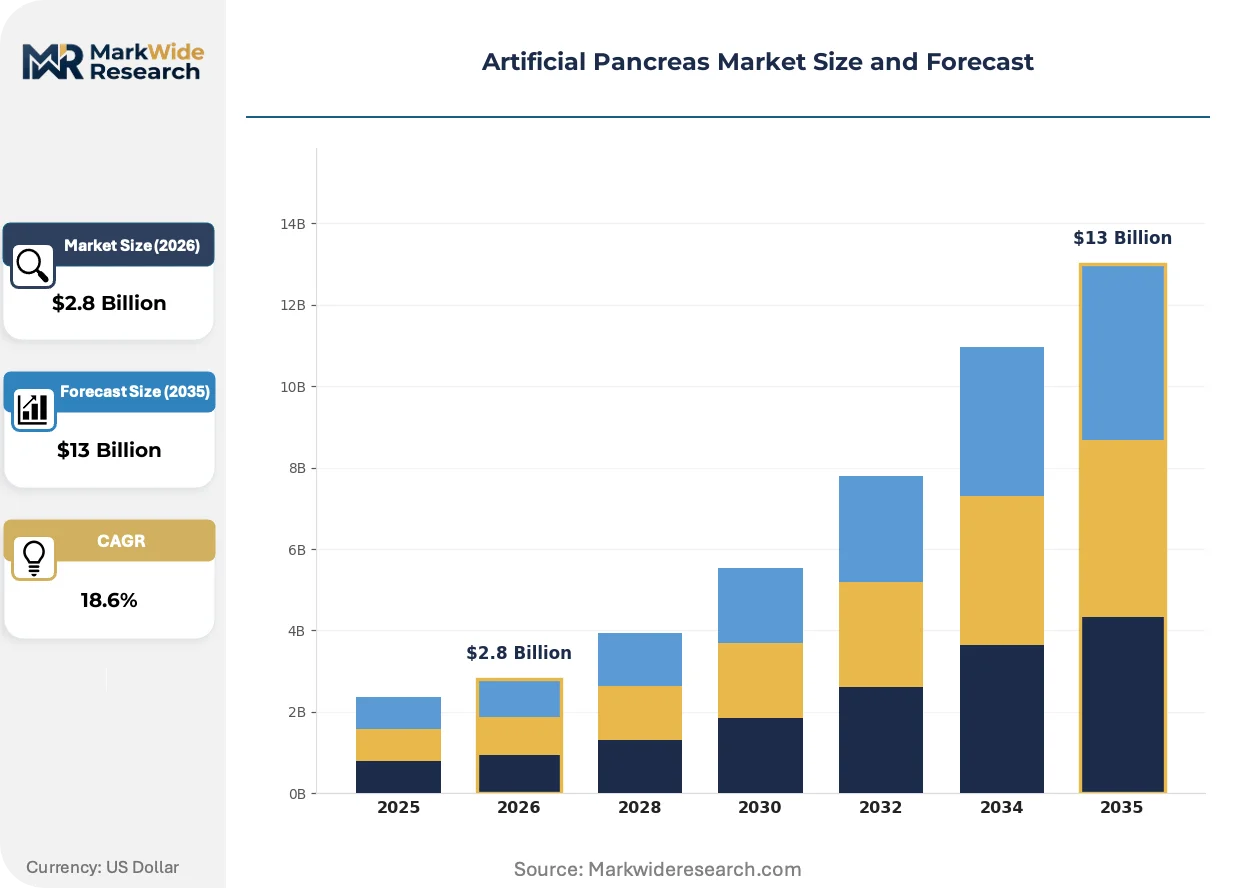
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed-loop Systems, Open-loop Systems, Wearable Devices, Continuous Glucose Monitors Technology: Insulin Delivery, Glucose Monitoring, Algorithm Control, Artificial Intelligence End User: Hospitals, Home Care Settings, Clinics, Research Institutions Application: Type 1 Diabetes Management, Type 2 Diabetes Management, Clinical Trials, Patient Education |
| Companies Covered | Medtronic, Tandem Diabetes Care, Insulet Corporation, Dexcom, Beta Bionics, Bigfoot Biomedical, Diabeloop SA, Ypsomed, Pancreum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Pancreas Market Emerging Trajectories
Artificial pancreas development is pivoting from closed-loop automation toward predictive metabolic intervention, with algorithms anticipating glucose excursions before they materialize rather than reacting to threshold breaches.
Machine learning inference is digitizing glycemic prediction by deploying recurrent neural networks on smartphone edge processors. Adolescent and young adult patients are adopting these architectures fastest, drawn to interface parity with consumer electronics. This shift is digitizing the competitive basis away from pump hardware durability toward software update velocity and cloud-connected personalization.
The FDA's breakthrough device designation pathway is compressing premarket review timelines for hybrid closed-loop platforms that demonstrate superior hypoglycemia reduction. Manufacturers receiving this status gain prioritized review resources and enhanced FDA feedback during clinical protocol design. Pediatric indication expansions and dual-hormone submissions are concentrating breakthrough applications, with sponsors responding by front-loading juvenile trial enrollment.
Patient self-management behavior is fragmenting across channel preferences, with direct-to-consumer CGM subscriptions displacing traditional endocrinology-mediated pump prescriptions in the United States. Younger cohorts favor smartphone-integrated systems purchased through pharmacy retail channels, while older patients retain specialist-driven procurement. This bifurcation is most visible in urban coastal markets where telehealth prescribing authority has expanded.
Artificial Pancreas Market Segmentation
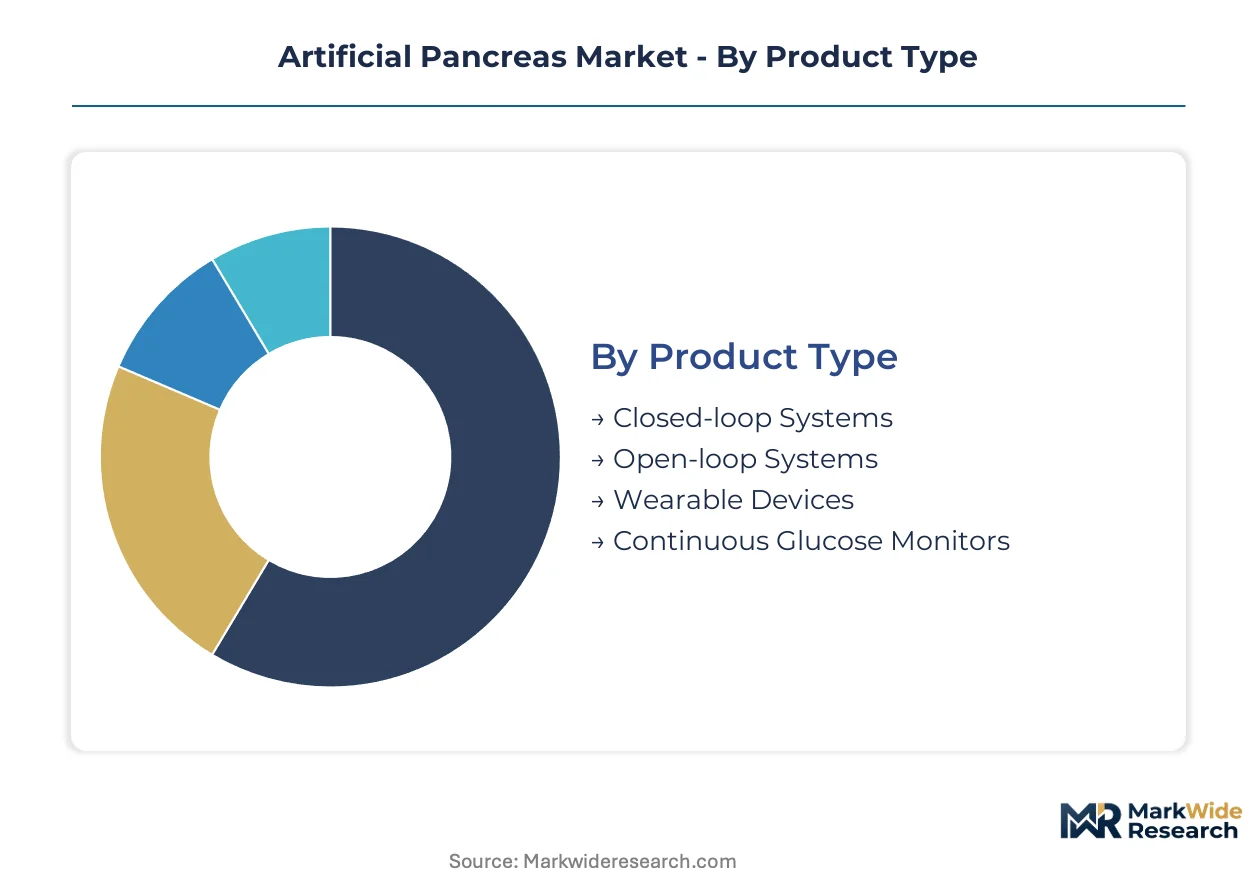
Segmentation in the artificial pancreas market reveals how clinical requirements, reimbursement pathways, and patient self-management capabilities reshape procurement decisions across healthcare delivery contexts.
Product Type:
The use-case spectrum spans fully autonomous metabolic control to patient-supervised glucose tracking, with hardware form factors dictating where each configuration deploys.
- Closed-loop Systems:These platforms integrate CGM sensors, control algorithms, and insulin pumps into autonomous feedback loops that adjust dosing without patient intervention. Demand concentrates in the United States where CMS reimbursement for therapeutic CGM integration covers system optimization visits. The FDA breakthrough device pathway accelerates premarket review for platforms demonstrating superior hypoglycemia reduction.
- Wearable Devices:Patch-form insulin delivery systems eliminate tubing and enable discreet wear under clothing, appealing to adolescent and young adult patients prioritizing lifestyle flexibility. Adoption runs fastest through pharmacy retail channels in urban coastal markets where telehealth prescribing authority has expanded.
- Open-loop Systems:Sensor-augmented pumps requiring patient-initiated bolus decisions serve as transition technology for patients building confidence in automated dosing.
- Continuous Glucose Monitors:Standalone sensing devices without integrated insulin delivery function as entry-level glycemic awareness tools and algorithm input layers.
The dominant share belongs to Closed-loop Systems, while Wearable Devices is closing the gap fastest.
Technology:
Cost tier differentiation separates established hardware components from emerging software capabilities that command premium positioning through personalization velocity.
- Artificial Intelligence:Machine learning models trained on individual glycemic patterns enable predictive hypoglycemia prevention and circadian basal rate adaptation. Deployment concentrates in smartphone-native architectures where edge processors run recurrent neural networks for real-time inference. Algorithm update velocity replaces pump durability as the competitive basis.
- Algorithm Control:Embedded or cloud-hosted processing engines translate glucose sensor inputs into insulin dosing commands, with FDA premarket approval requiring multi-month in-silico validation followed by supervised clinical trials.
- Insulin Delivery:Patch and tethered pump hardware provides the mechanical execution layer for automated dosing commands.
- Glucose Monitoring:Subcutaneous interstitial fluid sensors sampling every one to five minutes supply the essential input data stream for any automated control architecture.
Artificial Intelligence commands premium pricing through personalization capabilities, while Algorithm Control retains volume concentration in embedded pump processors.
End User:
Volume distribution reflects how acute care protocols, chronic disease management reimbursement, and research sponsorship allocate system deployment across delivery settings.
- Home Care Settings:Patient self-management environments absorb the majority of unit volume as closed-loop systems shift metabolic control from clinical facilities to domestic spaces. Reimbursement frameworks for therapeutic CGM integration in the United States enable physician billing for remote system optimization.
- Hospitals:Acute inpatient glycemic management protocols and clinical trial sponsorship retain margin concentration despite lower unit volumes. EMA Medical Device Regulation post-market surveillance requirements extend compliance costs across the product lifecycle.
- Clinics:Outpatient endocrinology practices serve as initial prescription channels and algorithm personalization sites.
- Research Institutions:Academic medical centers conduct juvenile glycemic control trials and dual-hormone architecture development.
Home Care Settings capture volume leadership, while Hospitals maintain margin density through acute protocol sponsorship.
Application:
Patient population characteristics and regulatory approval pathways determine where manufacturers concentrate clinical trial investment and indication expansion.
- Type 1 Diabetes Management:Autoimmune insulin deficiency creates the primary addressable population for fully automated closed-loop systems, with regulatory approvals for patients aged two to six years remaining sparse and creating first-mover opportunities. Pediatric indication expansions concentrate breakthrough device applications.
- Clinical Trials:Sponsored research protocols generate revenue through device provision and data collection services, with juvenile trial enrollment front-loaded in response to regulatory prioritization.
- Type 2 Diabetes Management:Insulin-resistant populations with residual beta-cell function present algorithm adaptation challenges for automated dosing.
- Patient Education:Training programs and self-management support services accompany system deployment.
Type 1 Diabetes Management anchors regulatory strategy and revenue concentration, while Clinical Trials is expanding most quickly through pediatric enrollment acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of artificial pancreas components concentrate in established medical device manufacturing clusters, while import demand tracks reimbursement maturity and regulatory approval velocity. The United States maintains net exporter status in closed-loop system assembly, whereas European and Asia-Pacific markets absorb sensor hardware and pump subassemblies.
United States
CMS Category III CPT codes for therapeutic CGM integration drive physician billing for closed-loop optimization, expanding the addressable patient population. FDA breakthrough device designation compresses premarket review timelines for hybrid closed-loop platforms. The Minneapolis-St. Paul corridor anchors Medtronic's integrated pump manufacturing and algorithm development operations.
Germany
EMA Medical Device Regulation post-market surveillance requirements extend compliance costs across product lifecycles, filtering market entry to well-capitalized manufacturers. The country's statutory health insurance system covers sensor-augmented pumps with prior authorization protocols. The Baden-Württemberg region clusters precision medical electronics fabrication serving EMA-regulated device assembly.
Japan
PMDA consultation pathways for software as a medical device accelerate algorithm update approvals for smartphone-native control architectures. METI medical device reimbursement pricing surveys establish reference prices for closed-loop system components. The Kansai region around Osaka concentrates CGM transmitter manufacturing for Asia-Pacific distribution.
India
BIS certification for active implantable medical devices creates compliance thresholds for imported closed-loop hardware, incentivizing local assembly partnerships. The PLI scheme for medical electronics offers capital subsidies for CGM transmitter and pump manufacturing. The Maharashtra- Gujarat industrial corridor attracts contract manufacturing for sensor hardware destined for domestic and export markets.
China
NMPA Class III medical device registration requires domestic clinical trials for closed-loop systems, extending market entry timelines for foreign manufacturers. MIIT smart health initiatives prioritize glucose monitoring device localization under dual carbon goals. The Yangtze River Delta clusters precision electromechanical component suppliers serving NMPA-registered device assemblers.
Artificial Pancreas Market Vendor Landscape
On the supply side, the industry is consolidating around integrated hardware-software platforms that collapse traditional component boundaries. Three archetypes dominate: diversified medical device conglomerates with pump manufacturing heritage, continuous glucose monitoring specialists extending into algorithm control, and emerging pure-play closed-loop developers. Competitive moves concentrate on strategic partnerships bridging sensor-pump-algorithm gaps and geographic expansion through regulatory approval stacking.
Within the diversified device tier, Medtronic and Tandem Diabetes Care exemplify scale-driven platform integration, occupying positions that span embedded pump processors through smartphone-native control interfaces. Dexcom represents the sensing-specialist archetype, anchoring the essential input layer that enables any automated insulin delivery architecture. Beta Bionics occupies a position among emerging pure-play developers focused on dual-hormone automation.
| Leading Market Players |
|---|
| Medtronic |
| Tandem Diabetes Care |
| Insulet Corporation |
| Dexcom |
| Beta Bionics |
| Bigfoot Biomedical |
| Diabeloop SA |
| Ypsomed |
| Pancreum |
| Others |
Supply Flow & Price Mechanics
The Minneapolis-St. Paul corridor concentrates Medtronic's pump manufacturing scale and algorithm development operations, translating captive production capacity into pricing power for integrated closed-loop hardware that commands premium positioning against modular competitors.
Pricing Analysis
Industrial OEM buyers anchor subscription-based pricing structures across closed-loop system deployments. Three-tier pricing stratifies across premium hybrid closed-loop platforms, standard sensor-augmented pumps, and economy CGM-only entry points, with FDA breakthrough designation and CE marking tier creating certification-based price differentiation. Cost compression in the standard tier intensifies as smartphone-native architectures displace embedded pump processors. Pediatric endocrinology practices exhibit highest price sensitivity due to reimbursement authorization burdens, while hospital procurement committees demonstrate lowest sensitivity given acute protocol sponsorship margins.
Supply Chain Analysis
Upstream insulin analog feedstock draws from three manufacturers in the United States, Denmark, and France, creating concentrated sourcing dependencies for rapid-acting formulations essential to automated dosing. CGM sensor substrates and pump electromechanical subassemblies hinge on precision manufacturing clusters in Ireland, Malaysia, and Costa Rica. Single-source vulnerability runs through subcutaneous glucose sensor membranes produced by two specialty chemical suppliers. Distribution runs through direct-to-consumer pharmacy retail channels and endocrinology-mediated specialty distributors in roughly equal volume splits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithmic control expertise now constitutes the scarcest capability layer, with machine learning inference specialists commanding premium talent costs and FDA premarket approval experience residing in fewer than a dozen development teams globally.
For Market Incumbents: Pre-empt pure-play algorithm developers through strategic acquisition of smartphone-native control platforms before pediatric indication expansions concentrate competitive positioning. Backward integration into CGM sensor substrate manufacturing secures supply continuity against membrane supplier concentration. Defensive patent clustering around predictive hypoglycemia prevention algorithms blocks emerging entrant freedom-to-operate in the fastest-expanding capability segment. For New Entrants and Emerging Players: Establish a beachhead in the two-to-six-year pediatric population segment where regulatory approvals remain sparse and first-mover advantage persists through juvenile glycemic control trial completion. White-space concentration appears in dual-hormone micro-dosed glucagon architectures addressing hypoglycemia without carbohydrate intervention. Direct-to-consumer telehealth prescribing channels in urban coastal markets offer lowest customer acquisition friction for smartphone-integrated system launches. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates seeking to divest non-core diabetes portfolios amid algorithmic control migration toward software-centric competitive bases. Long-term viability favors platforms demonstrating software update velocity and cloud-connected personalization capabilities over hardware durability heritage. Watch FDA breakthrough device designation grants to emerging dual-hormone developers as inflection signal for premium valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway Submission | Prioritized review resources compress premarket timelines for hypoglycemia-reduction platforms. |
| Dual-Hormone Architecture Development | Micro-dosed glucagon integration commands premium positioning through automated hypoglycemia prevention. |
| Pediatric Indication Expansion | Juvenile trial enrollment front-loading secures first-mover advantage in sparse two-to-six-year approvals. |
| Smartphone-Native Control Migration | Edge processor deployment displaces embedded pump processors and collapses hardware-software boundaries. |
| Reimbursement Strategy Alignment | CMS Category III CPT code optimization expands physician billing for therapeutic CGM integration. |
Methodological Framework
Initial hypotheses were tested against primary input from endocrinologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA premarket approval databases, CMS reimbursement filings, ClinicalTrials.gov enrollment records, and EMA Medical Device Regulation guidance documents. Bottom-up unit volume estimates triangulated with top-down addressable population modeling.
Demand-supply balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include closed-loop system configuration, algorithm control architecture, patient age indication, care delivery setting, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to adoption rate trajectories. Forecast inputs incorporated sensor accuracy threshold crossover timing and breakthrough device designation velocity.
Macroeconomic conditions sit as an overlay; deviation in CMS reimbursement policy or EMA post-market surveillance cost burdens would shift the trajectory substantially. Cross-checking against hospital procurement database benchmarks and GPO contract pricing disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Phototherapy Lamps Market
Medical Devices
Spain Aesthetic Devices Market
Medical Devices
Peripheral Interventions Market
Medical Devices
Global Pelvic Floor Electric Stimulator Market
Medical Devices
Peritoneal Dialysis Solutions Market
Medical Devices
Europe Breast Implant Market
Medical Devices
Polyp Trap Devices Market
Medical Devices
US Biomedical Sensors Market
Medical Devices
Medical Germicidal Lamps Market
Medical Devices
Global Cerebral Somatic Oximeters Market
Medical Devices
Global Intravenous (IV) Equipment Market
Medical Devices
Volumetric Arc Therapy Market
Medical Devices
Implantable Pacemaker Market
Medical Devices
Global Electrotherapy System Market
Medical Devices
Global Surgical Microscopes Market
Medical Devices
United States Anesthesia Devices Market