
 North America Warehouse Management Systems Market | 2026-2036
North America Warehouse Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Warehouse Management Systems Market Insights
The third-party logistics channel is reconfiguring how warehouse operators source and deploy management software across North America. Manhattan Associates sustains deep penetration in retail fulfillment through specialized yard management modules. SAP SE anchors enterprise-grade deployments with ERP-native integration that reduces custom interface costs. Oracle Corp competes aggressively in multi-warehouse environments through database-centric architecture that unifies inventory visibility.
North America Warehouse Management Systems comprise software platforms that coordinate inventory movement, labor allocation, and equipment routing within distribution facilities, typically processing transaction volumes exceeding ten thousand stock-keeping unit events per hour. Cloud-based deployments now lead new installations as operators trade capital expenditure for subscription flexibility, while on-premises systems retain dominance among defense and pharmaceutical handlers with data residency requirements. Artificial Intelligence segments within the technology dimension attract disproportionate R&D investment as machine learning models optimize pick-path algorithms and demand forecasting accuracy.
The US Department of Transportation enforces electronic logging device mandates that synchronize inbound freight scheduling with warehouse labor planning, while OSHA warehouse safety standards shape aisle width and equipment interaction protocols embedded in system logic. California Air Resources Board warehouse rules indirectly accelerate automation module procurement as operators seek to reduce vehicle dwell times and associated emissions calculations. Stakeholders must weigh subscription portability against customization depth as deployment model decisions increasingly lock in operational architectures for decade-long horizons.
Market Dynamics
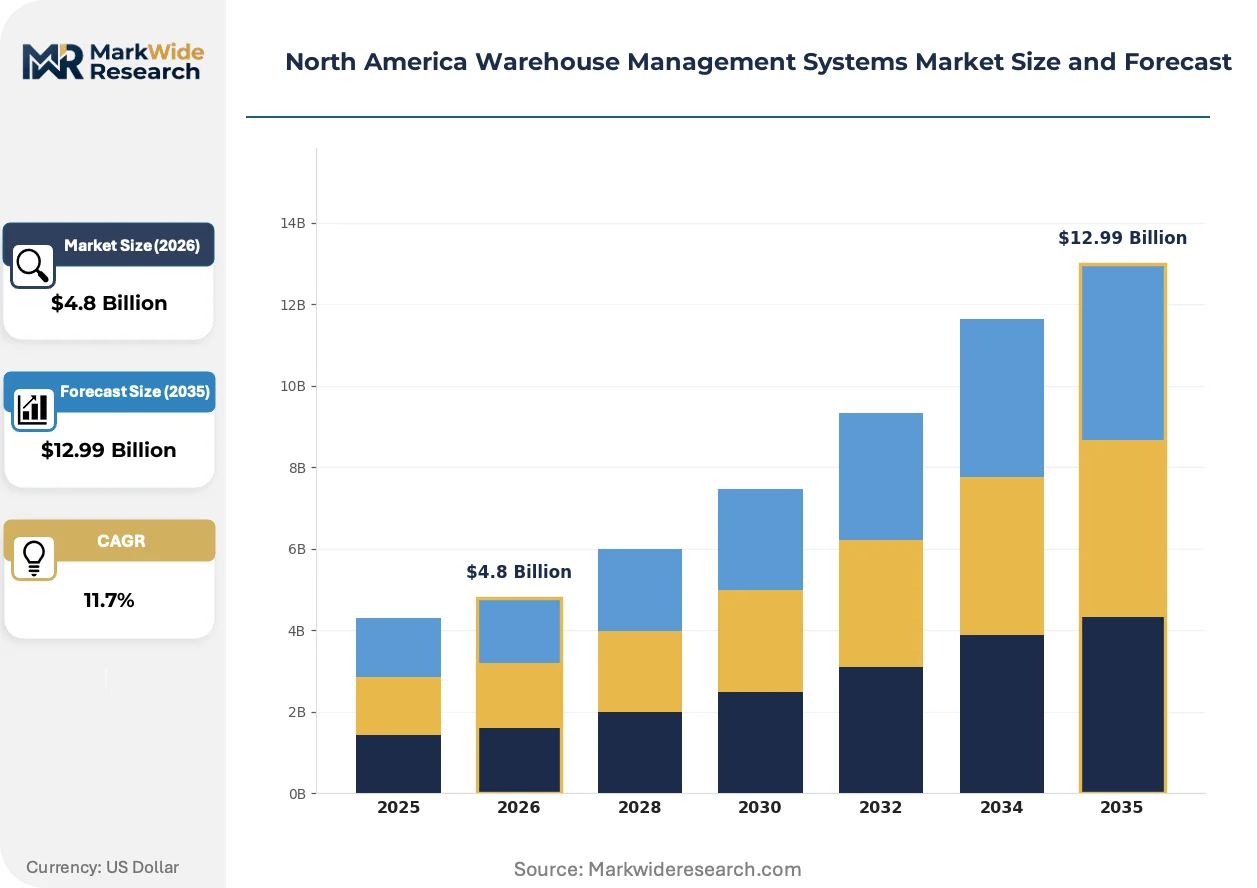
E-commerce fulfillment velocity requirements and California's warehouse emissions mandates are compressing deployment timelines for automated inventory orchestration platforms across North American distribution networks.
Growth Catalysts
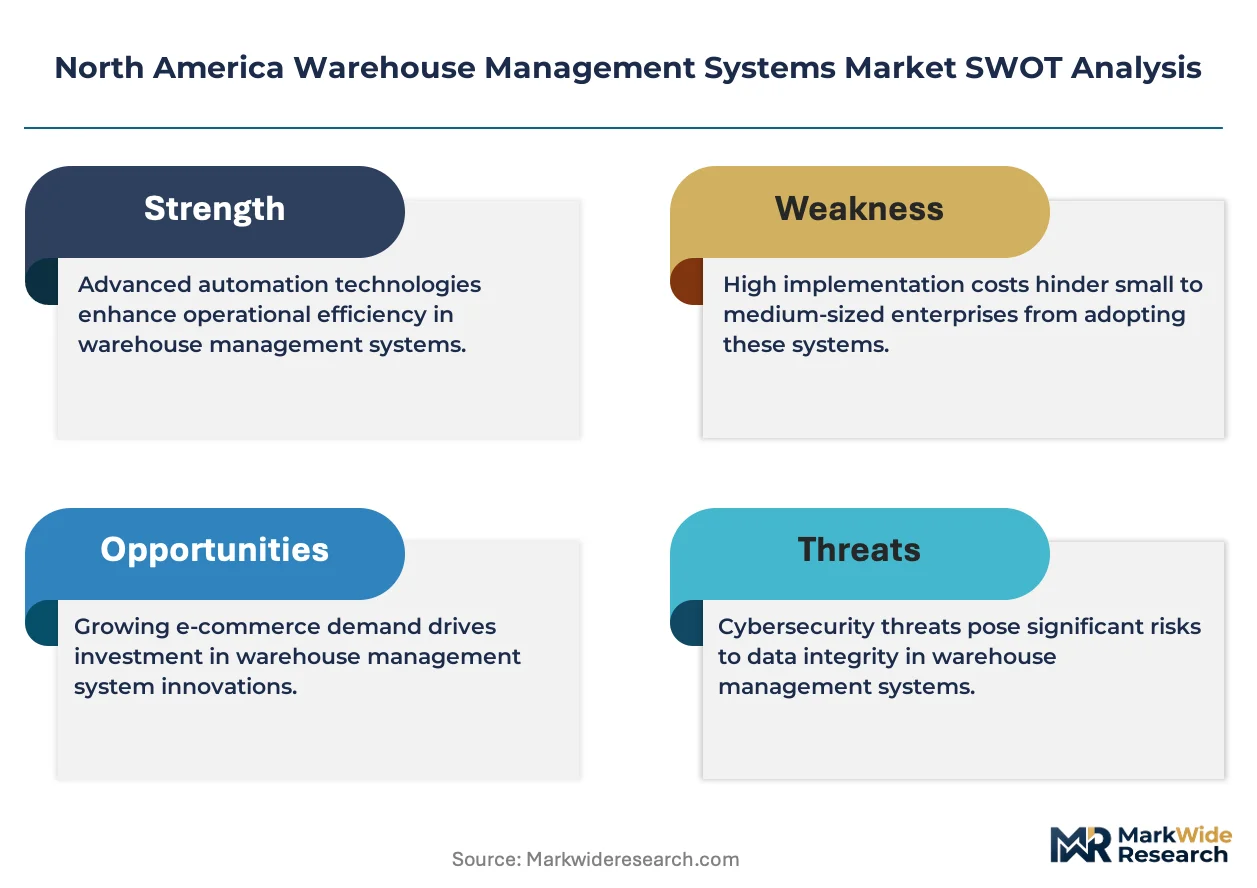
- OSHA Warehouse Safety Standards:Aisle width and equipment interaction protocols embedded in system logic drive software procurement as operators automate compliance documentation and incident prevention workflows.
- Machine Learning Optimization:Pick-path algorithms and demand forecasting accuracy improvements attract disproportionate R&D investment from third-party logistics providers seeking labor efficiency gains.
- Great Lakes Manufacturing Corridor:Concentrated demand across Michigan, Ohio, and Illinois distribution hubs creates regional scale effects for multi-warehouse deployment templates.
Market Restraints
- Cloud Migration Friction:Defense and pharmaceutical handlers with data residency requirements retain on-premises systems, fragmenting vendor R&D allocation across deployment architectures.
- Subscription Lock-in Risk:Decade-long operational architecture commitments reduce portability as customization depth binds operators to specific platform ecosystems.
- Legacy Integration Complexity:ERP-native integration requirements elevate custom interface costs for mid-tier operators lacking SAP SE or Oracle Corp enterprise footprints.
Strategic Opportunities
- US Department of Transportation ELD Synchronization:Electronic logging device mandates create inbound freight scheduling software modules that coordinate warehouse labor planning with carrier availability.
- Artificial Intelligence Convergence:Machine learning models combined with robotic process automation enable predictive inventory positioning that reduces vehicle dwell times under California Air Resources Board calculations.
- Illinois Distribution Hub Expansion:Chicago-area intermodal terminals present underpenetrated deployment opportunities for yard management modules serving cross-border freight corridors.
Industry Challenges
- Warehouse Technician Skill Shortage:Convergence of robotics maintenance, data analytics, and regulatory compliance documentation strains regional technical training pipelines.
- Capital Intensity of Automation Retrofits:Brownfield facility sensor deployment and conveyor reconfiguration demand upfront expenditure that conflicts with subscription-model CFO preferences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Warehouse Management Systems Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premises, Hybrid, Mobile Solutions End User: Retail, E-commerce, Manufacturing, Wholesale Distribution Technology: Barcode Scanning, RFID, IoT, Artificial Intelligence Deployment Model: Single Tenant, Multi-Tenant, Edge Computing, Virtualized Solutions |
| Companies Covered | Manhattan Associates, SAP SE, Oracle Corp, Blue Yonder Group, Infor, Epicor Software, Körber AG, Softeon, Tecsys, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Warehouse Management Systems Market Trends and Innovations
Software architecture decisions are hardening into decade-long operational commitments as operators trade customization depth against cloud portability, reshaping how vendors structure platform roadmaps and customer success functions.
Cloud-based warehouse management deployments are migrating from capital expenditure avoidance toward strategic flexibility mandates as operators prioritize subscription scalability over sunk infrastructure costs. Third-party logistics providers in the Great Lakes corridor accelerate this transition fastest, seeking rapid facility onboarding without hardware procurement cycles. The structural compression of deployment timelines is eliminating traditional pilot phases in favor of direct production rollouts.
California Air Resources Board warehouse emissions rules are forcing automation module procurement decisions that reduce vehicle dwell times through predictive dock scheduling algorithms. Industrial consequence extends beyond California into neighboring Arizona and Nevada distribution networks serving the same consumer bases. Food and beverage cold chain operators face the steepest compliance cost escalation, driving disproportionate investment in yard management optimization.
Buyer procurement patterns are compressing vendor evaluation cycles from eighteen-month RFP processes to direct platform trials with limited scope deployments. Third-party logistics channels increasingly displace direct enterprise sales as the dominant contract origination path, particularly among mid-market retailers lacking dedicated supply chain IT functions. This behavioral shift concentrates most visibly in Ohio and Pennsylvania e-commerce fulfillment networks where operator density enables reference-based vendor selection.
North America Warehouse Management Systems Market Segmentation
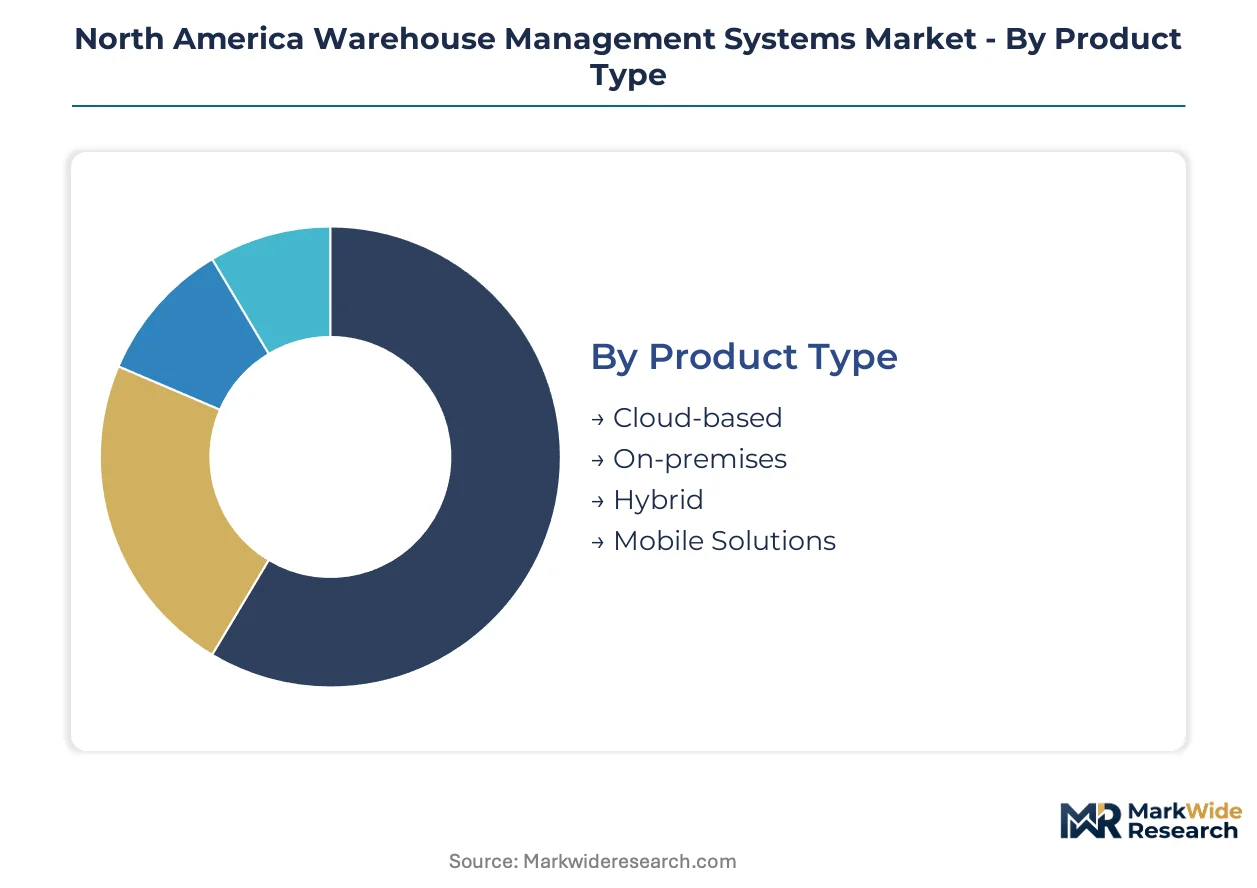
Warehouse management software procurement patterns diverge sharply across deployment architectures and operational scales. Understanding these fault lines reveals where vendor R&D investments concentrate and which customer profiles command premium pricing.
Product Type:
Mature on-premises installations coexist with rapidly maturing cloud-native platforms as capital expenditure preferences shift across operator categories.
- Cloud-based:Subscription licensing eliminates upfront server procurement and reduces IT headcount requirements for multi-site operators. E-commerce fulfillment networks in Illinois and Ohio adopt these platforms fastest to compress facility onboarding from quarters to weeks.
- On-premises:Perpetual licensing with localized data storage addresses defense and pharmaceutical handlers subject to data residency mandates. Michigan automotive parts distributors maintain these installations to preserve direct control over inventory databases.
- Hybrid:Combines edge transaction processing with cloud analytics aggregation for operators balancing latency sensitivity against centralized reporting needs.
- Mobile Solutions:Native tablet and handheld applications extend core platform functionality to yard management and remote inventory auditing workflows.
Cloud-based deployments handle the majority of new customer acquisition; mobile solutions are expanding most quickly on share as labor mobility requirements intensify.
End User:
Customer scale and inventory velocity requirements create distinct procurement patterns across vertical applications.
- Retail:Seasonal demand surges and omnichannel fulfillment complexity drive investment in wave planning and store replenishment modules. Great Lakes corridor department store chains anchor this segment with multi-warehouse template deployments.
- E-commerce:Same-day delivery promises and returns processing volume strain conventional batch-oriented systems. California and Arizona fulfillment networks prioritize these platforms to minimize vehicle dwell times under emissions calculations.
- Manufacturing:Work-in-process tracking and supplier milk-run coordination require ERP-native integration that elevates implementation complexity.
- Wholesale Distribution:Full-pallet throughput and cross-dock velocity favor simpler configurations with limited value-added service modules.
E-commerce commands the steepest pricing premiums; wholesale distribution maintains the largest installed base.
Technology:
Identification and sensing capabilities determine labor efficiency ceilings and inventory accuracy floors.
- Barcode Scanning:Linear and 2D symbology reading remains the default data capture method for case-level tracking. Ohio food distribution centers standardize on these systems for FDA traceability compliance documentation.
- RFID:Passive and active radio-frequency identification enables bulk reading without line-of-sight constraints. Apparel retailers in Pennsylvania deploy these systems to accelerate receiving and reduce cycle-count labor.
- IoT:Sensor networks monitor environmental conditions and equipment health across cold chain and automated storage environments.
- Artificial Intelligence:Machine learning models optimize pick-path sequencing and demand forecasting accuracy for high-SKU-density operations.
Barcode scanning anchors the majority of transaction volume; artificial intelligence is gaining share fastest as labor costs rise.
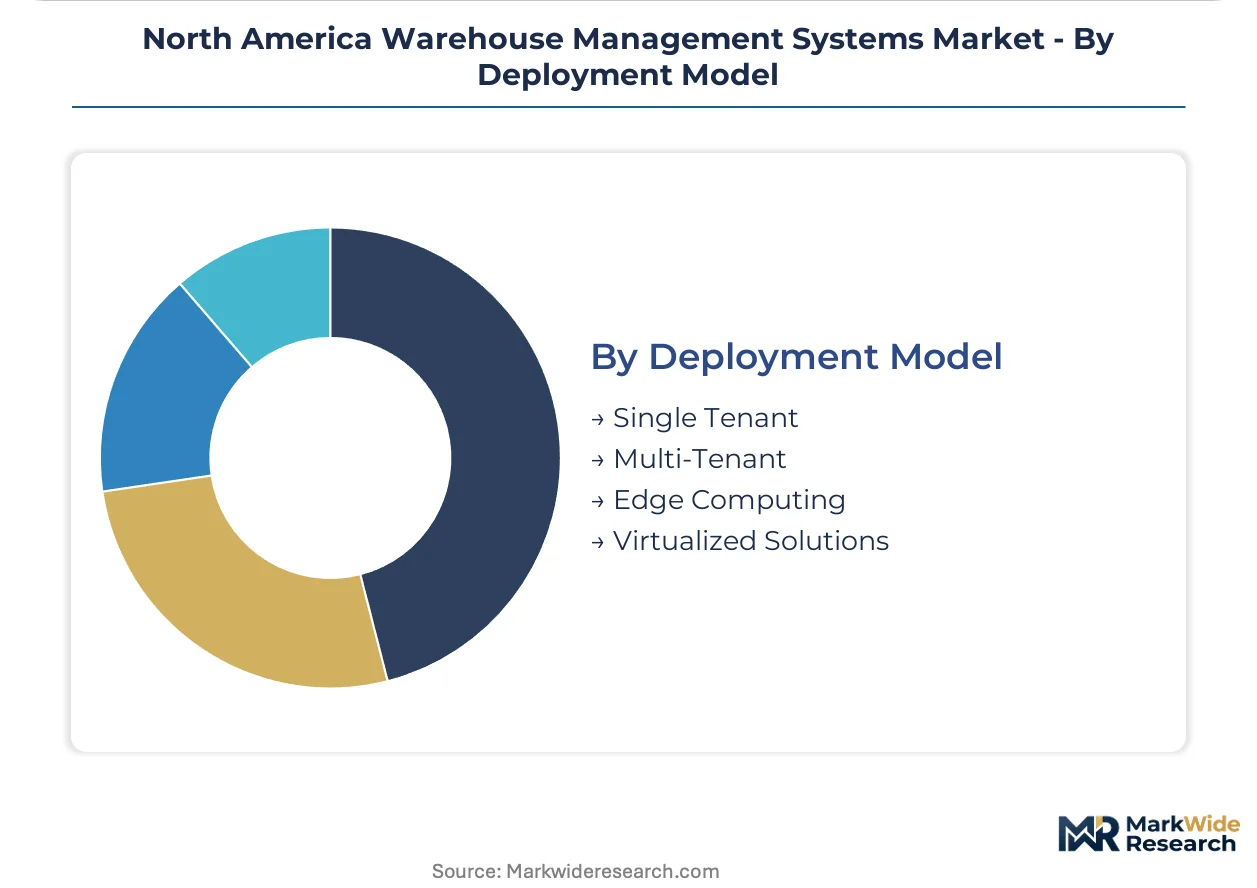
Deployment Model:
Infrastructure isolation requirements and processing latency tolerances segment customer preferences.
- Single Tenant:Dedicated instance hosting preserves customization depth for operators with unique workflow requirements. Defense logistics handlers mandate these configurations for security audit compliance.
- Multi-Tenant:Shared infrastructure with tenant isolation reduces per-customer operational overhead for standardized use cases. Third-party logistics providers serving mid-market retailers favor these economics.
- Edge Computing:Localized processing nodes maintain operations during connectivity interruptions and reduce cloud data transfer costs.
- Virtualized Solutions:Containerized deployment across private or hybrid cloud infrastructure balances resource elasticity against infrastructure control.
Multi-tenant architectures dominate new subscription originations; edge computing is climbing fastest as uptime guarantees tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach and Los Angeles rail intermodal complex anchors North American distribution velocity, channeling Pacific container volume into Midwestern fulfillment networks. This infrastructure concentration shapes software procurement patterns across the continent.
United States
OSHA warehouse safety standards mandate aisle width and equipment interaction protocols that operators automate through compliance documentation modules. The Department of Transportation enforces electronic logging device synchronization that coordinates inbound freight scheduling with labor planning. Chicago-area intermodal terminals concentrate demand for yard management software serving cross-border freight corridors.
Canada
Cold chain logistics expansion around Toronto and Vancouver drives investment in environmental monitoring and IoT sensor integration platforms. Health Canada pharmaceutical traceability requirements preserve on-premises system preferences among vaccine distributors. Ontario's automotive parts hub maintains hybrid deployment architectures balancing latency sensitivity against centralized analytics.
Mexico
Nearshoring manufacturing relocation accelerates warehouse management platform deployment across Nuevo León and Baja California distribution corridors. Mexican customs modernization programs require electronic manifest integration that elevates ERP-native connectivity requirements. Tijuana maquiladora clusters adopt cloud-native systems to compress cross-border inventory cycle times.
North America Warehouse Management Systems Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers. Enterprise-grade vendors anchor multi-warehouse deployments through database-centric architecture, while specialized providers capture mid-market share with rapid-implementation templates. Strategic archetypes include ERP-native integrators, best-of-breed fulfillment specialists, and vertical-focused cold chain operators. Dominant competitive moves center on subscription model migration and AI module augmentation.
Within the enterprise software tier, Manhattan Associates, SAP SE, and Oracle Corp exemplify divergent architectural philosophies. Manhattan Associates occupies a position emphasizing yard management and retail fulfillment specialization. SAP SE anchors ERP-native integration strategies that reduce custom interface overhead for manufacturing-linked distributors. Oracle Corp represents database-centric consolidation approaches unifying inventory visibility across fragmented facility footprints.
| Leading Market Players |
|---|
| Manhattan Associates |
| SAP SE |
| Oracle Corp |
| Blue Yonder Group |
| Infor |
| Epicor Software |
| Körber AG |
| Softeon |
| Tecsys |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Great Lakes distribution corridors tightens vendor pricing power as third-party logistics operators compete for limited implementation bandwidth, compressing negotiation timelines and elevating subscription commitments for multi-warehouse deployments.
Pricing Analysis
Volume-discount tiering structures separate enterprise-grade multi-warehouse contracts from mid-market single-facility subscriptions, with customization depth and integration complexity driving tier placement. Price differentiation hinges on ERP-native connectivity requirements and after-sales support bundling, with SAP SE and Oracle Corp commanding premiums for manufacturing-linked distributors. Pricing pressure stems from cloud-native entrants undercutting perpetual licensing models, though defense and pharmaceutical handlers with data residency mandates show minimal price sensitivity. Mid-market retailers lacking dedicated supply chain IT functions exhibit highest price elasticity, prioritizing rapid-deployment templates over feature depth.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from systems integrators ease upfront capital burdens for brownfield automation retrofits, particularly among Ohio and Illinois operators. Software development concentrates in the United States, India, and Ireland, with implementation services drawing from regional systems integrators across North America. Raw material dependencies include cloud infrastructure from hyperscalers, edge computing hardware from Taiwan and South Korea, and sensor components from China. Tariff exposure on Chinese-manufactured IoT sensors elevates total deployment costs for RFID and environmental monitoring modules. Distribution runs through direct enterprise sales for large operators and third-party logistics channel partnerships for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is underway as ERP-native integration becomes table stakes, with interoperability mandates from the US Department of Transportation's electronic logging device synchronization forcing modular architecture adoption across vendor ecosystems.
For Market Incumbents: Entrench multi-warehouse template deployments through yard management specialization and AI module augmentation, defending against cloud-native entrants by deepening ERP-native integration that elevates switching costs. Prioritize R&D concentration in pick-path optimization algorithms and predictive dock scheduling to maintain differentiation under California Air Resources Board compliance pressures. Channel control through third-party logistics partnerships anchors retention in the Great Lakes corridor where operator density enables reference-based vendor selection. For New Entrants and Emerging Players: Pursue underpenetrated Illinois intermodal terminals and cross-border freight corridors serving Tijuana maquiladora clusters, where rapid facility onboarding requirements outpace incumbent implementation bandwidth. Target mid-market food and beverage cold chain operators facing steepest California emissions compliance cost escalation with subscription-scalable yard management modules. Go-to-market leverage rests on direct platform trials with limited scope deployments that bypass traditional eighteen-month RFP cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment architectures as subscription models displace perpetual licensing, compressing working capital requirements and accelerating cash conversion. Long-term viability favors vendors with multi-tenant infrastructure and AI-augmented product roadmaps over legacy on-premises specialists. Acquisition target archetype: vertical-focused cold chain operators with Health Canada pharmaceutical traceability compliance capabilities. Signal to watch: Defense logistics handlers relaxing data residency requirements would indicate cloud portability tipping point.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ERP-native connectivity with SAP SE and Oracle Corp reduces custom interface overhead for manufacturing-linked distributors. |
| AI Module Augmentation | Machine learning pick-path optimization addresses labor efficiency pressures from OSHA warehouse safety standards. |
| Geographic Expansion | Chicago-area intermodal terminal penetration captures cross-border freight corridor demand from Nuevo León distribution networks. |
| Strategic Partnership | Third-party logistics channel alliances displace direct enterprise sales as dominant contract origination path in Ohio and Pennsylvania. |
| Product Launch | Predictive dock scheduling algorithms reduce vehicle dwell times under California Air Resources Board emissions calculations. |
Research Methodology
A standing panel of warehouse operations directors, third-party logistics procurement leads, systems integration specialists, and compliance officers provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC 10-K filings of publicly traded vendors, US Department of Transportation regulatory dockets, California Air Resources Board rulemaking records, and customs data on automation hardware imports. Bottom-up facility deployment tallies and top-down software spending estimates were triangulated to anchor market sizing.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling spanning deployment architecture, end-user vertical, identification technology, and tenant isolation requirements. CAGRs were derived from facility onboarding velocity trends, cloud migration penetration curves, and regulatory compliance cost trajectories. Forecast inputs incorporated electronic logging device mandate synchronization timelines and Great Lakes manufacturing corridor expansion patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler-backed cloud-native entrants or accelerated defense sector cloud relaxation would shift outcomes. Macroeconomic contraction in e-commerce fulfillment, regulatory delay in emissions enforcement, or breakthroughs in autonomous robotics standardization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
United States Customer Technical Support Services Market
Enterprise Services
Network Outsourcing Market
Enterprise Services
Global Enterprise Data Warehouse (EDW) Market
Enterprise Services
Europe IT Staffing Market
Enterprise Services
Multi Vendor Support Services Market
Enterprise Services
Managed Services Market
Enterprise Services
Electronics Contract Manufacturing Services (EMS) Market
Enterprise Services
Enterprise Social Graph Market
Enterprise Services
Enterprise Social Software Market
Enterprise Services
Field Service Management Market
Enterprise Services
Qatar Cloud Managed Services Market
Enterprise Services
Global AWS Managed Services Market
Enterprise Services
US Enterprise Asset Management Market
Enterprise Services
Travel and Expense Management Market
Enterprise Services
Global Supply Chain As a Service (Scaas) Market
Enterprise Services
Outsourced Customer Care Services Market