
 Global Zig-Bee Automation Market | 2026-2036
Global Zig-Bee Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Zig-Bee Automation Market Outlook
Zigbee 3.0 certification is reorganizing competitive access by mandating unified application-layer protocols across hardware vendors. Texas Instruments Incorporated leverages its integrated radio-frequency portfolio to sustain design wins in smart meter programs across multiple continents. Silicon Laboratories Inc. anchors its position through dedicated mesh-networking software stacks that simplify OEM certification cycles. Qualcomm Incorporated competes by extending its wireless connectivity intellectual property into low-power home automation chipsets.
Zig-Bee automation denotes a wireless mesh networking ecosystem operating in the 2.4 GHz ISM band with data rates up to 250 kbps, purpose-built for low-power, low-latency device coordination in building and industrial control systems. Smart Sensors and Smart Lighting product categories currently occupy the largest revenue pools, though Industrial Controllers are registering the fastest expansion as factories retrofit legacy equipment with wireless monitoring. The Services component segment is deepening margin concentration as system integrators bundle network commissioning with ongoing firmware management for enterprise deployments.
The FCC in the United States governs spectrum allocation and emission limits for unlicensed Zigbee operation, while the EU Green Deal and REACH frameworks in Europe mandate energy transparency and material disclosure for connected building products. China's MIIT enforces GB standards for radio equipment that shape import requirements for foreign module suppliers. Stakeholders must monitor evolving spectrum policy in Brazil and India, where national regulators are drafting localized certification rules that could fragment hardware approval pathways.
Market Dynamics
Zigbee 3.0 certification mandates are compressing hardware vendor differentiation by enforcing unified application-layer protocols across the ecosystem. This regulatory-technical convergence is redistributing competitive advantage toward software stack maturity and certification velocity rather than proprietary radio designs.
Growth Catalysts
- EU Green Deal energy mandates:Building automation retrofits across Germany, France, and Italy must meet tightened interoperability standards, accelerating mesh-network deployments in commercial real estate.
- Smart meter rollouts:Utilities in China and the United States are standardizing on Zigbee for home area networks, creating sustained module demand through 2035.
- Industrial wireless retrofit:Factory operators in Japan are replacing wired sensor infrastructure with battery-operated Zigbee endpoints to reduce installation downtime.
Market Restraints
- Silicon supply concentration:Advanced RF foundry capacity concentrates in Taiwan, exposing module vendors to geopolitical disruption and allocation constraints.
- Wi-Fi 6 and Thread substitution:Home automation OEMs are evaluating lower-latency alternatives for bandwidth-intensive video doorbell and camera integrations.
- REACH material disclosure:European importers face escalating compliance costs for documenting rare earth and conflict mineral content in radio modules.
Strategic Opportunities
- Brazil smart grid buildout:ANEEL's grid modernization program creates first-mover advantage for certified module suppliers in Latin America's largest economy.
- Matter protocol convergence:Zigbee Alliance's migration path to Matter over Thread enables cross-ecosystem compatibility with Apple, Google, and Amazon smart home platforms.
- India building automation:BIS adoption of harmonized radio standards under the National Smart Grid Mission is opening procurement pathways for foreign OEMs.
Industry Challenges
- Firmware security certification:PSA Certified and SESIP evaluation timelines extend product launch schedules by 6-12 months for resource-constrained vendors.
- Mesh network commissioning complexity:Enterprise deployments require specialized field engineering that system integrators struggle to staff at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Zig-Bee Automation Market |
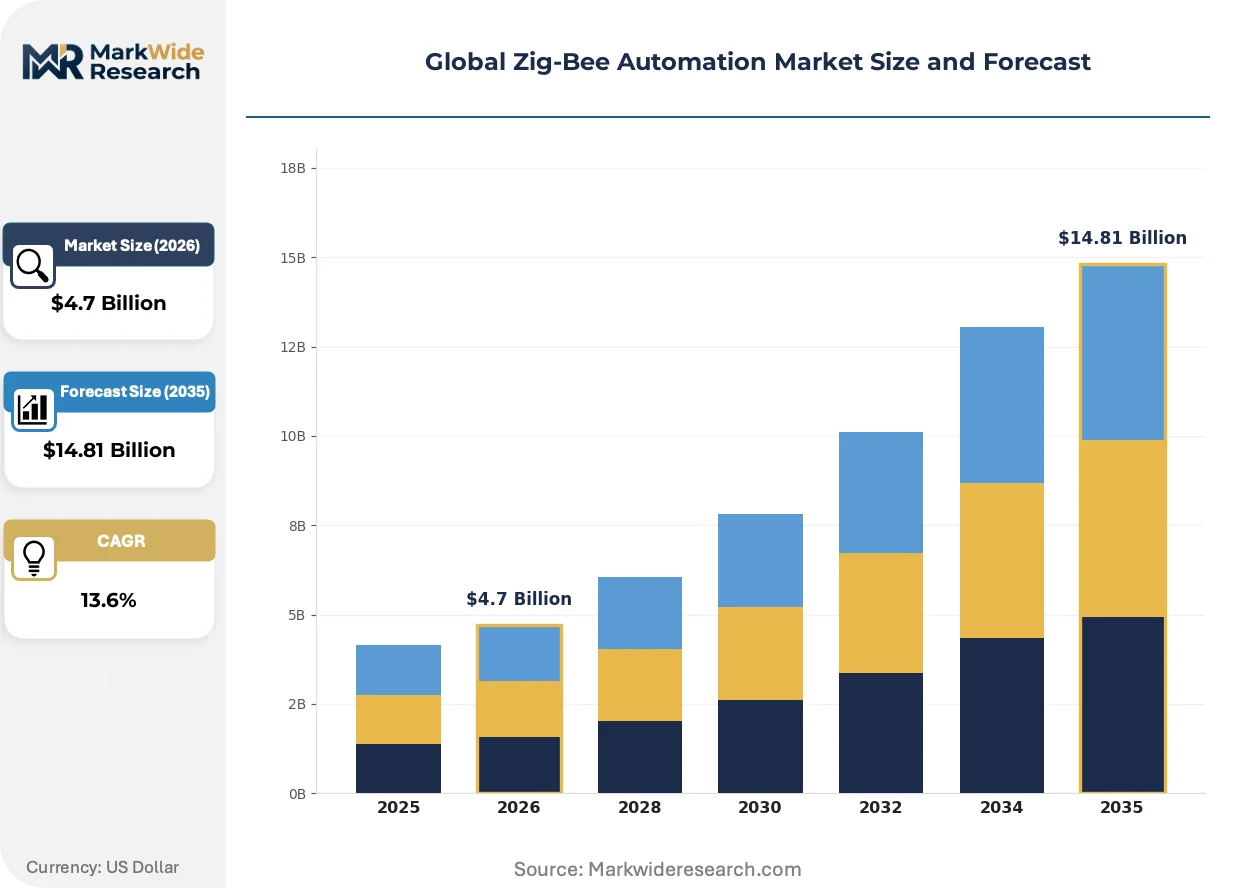
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $14.81 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Sensors, Smart Lighting, Home Automation, Industrial Controllers Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Component: Hardware, Software, Services, Gateways End User: Residential, Commercial, Industrial, Healthcare |
| Companies Covered | Texas Instruments Incorporated, NXP Semiconductors, Silicon Laboratories Inc., Microchip Technology Inc., STMicroelectronics, Digi International Inc., Qualcomm Incorporated, Renesas Electronics Corporation, Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Zig-Bee Automation Market Strategic Shifts
Protocol unification and edge intelligence are compressing the traditional separation between connectivity hardware and application software. Vendors are repositioning around full-stack ownership rather than component supply.
Multi-protocol radio silicon is fragmenting the single-standard module market by enabling dynamic switching between Zigbee, Thread, and Bluetooth Low Energy on identical hardware. Smart lighting OEMs in the Netherlands and South Korea are adopting these flexible architectures to reduce SKU proliferation. This convergence is fragmenting procurement patterns as buyers prioritize firmware-upgradable platforms over fixed-function chips.
China's MIIT GB standards for radio equipment are tightening spurious emission limits and mandating domestic cybersecurity evaluation for connected building products. Foreign module suppliers must establish local testing partnerships to maintain market access. Industrial controller manufacturers are responding by pre-certifying designs against both MIIT and FCC requirements to accelerate dual-market entry.
Enterprise facility managers are unbundling network commissioning from hardware procurement, treating mesh deployment as a specialized service category distinct from device purchase. System integrators in Germany and California are capturing this margin by offering multi-year firmware management contracts. This service-layer separation is most pronounced in healthcare and data center verticals where uptime guarantees override capital expenditure optimization.
Global Zig-Bee Automation Market Segmentation
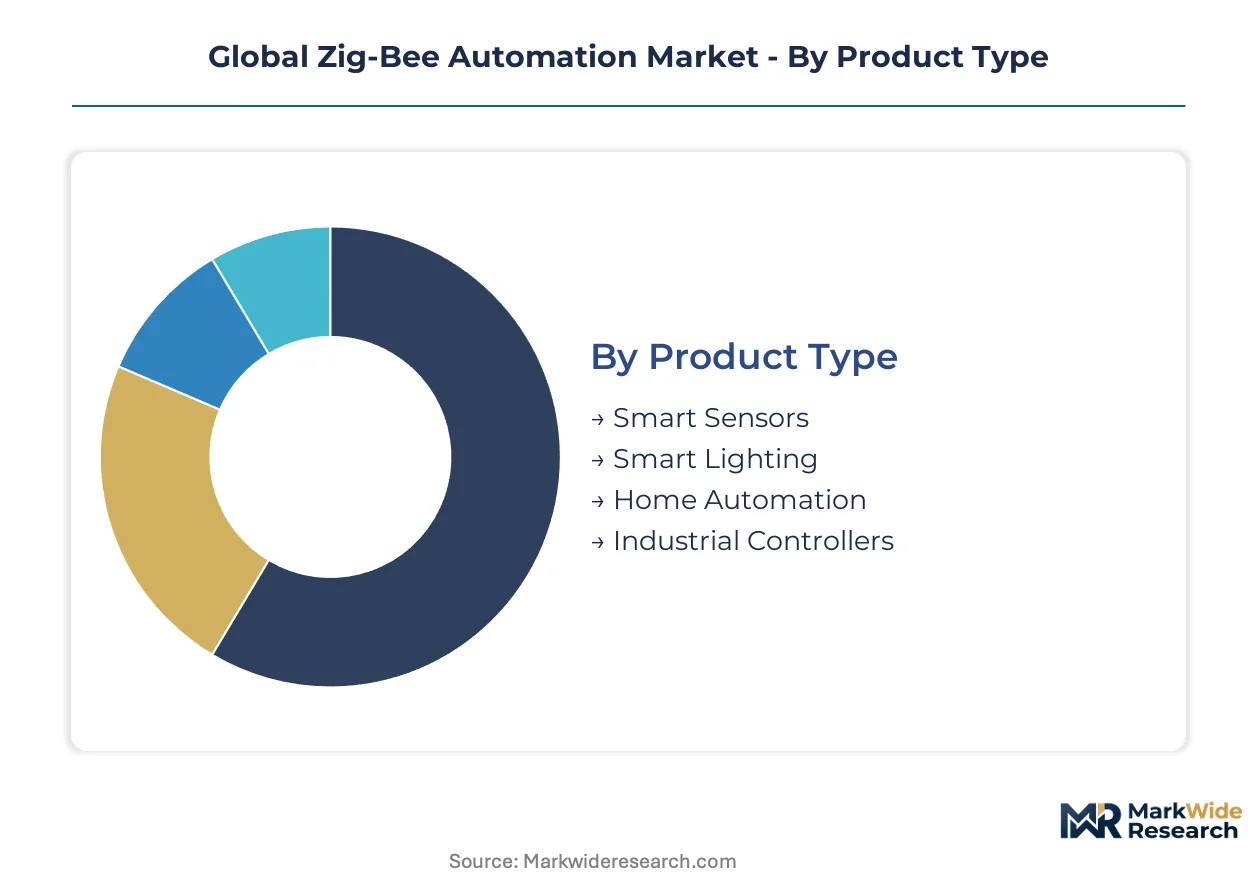
Zig-Bee automation markets fragment across four distinct category axes that reshape procurement patterns and vendor positioning. Product type and deployment mode determine hardware margins, while component mix and end-user verticals govern service attach rates and certification complexity.
Product Type:
EU Green Deal energy mandates differentiate compliance requirements across device categories, with lighting and sensor products facing tightened interoperability standards.
- Smart Sensors:Battery-operated endpoints measuring temperature, occupancy, and environmental conditions with sub-100ms latency. Demand concentrates in German commercial real estate retrofits where the EU Green Deal mandates granular energy monitoring for building certification.
- Smart Lighting:Dimmable LED controllers with daylight harvesting and circadian rhythm programming. Dutch and South Korean OEMs are adopting multi-protocol silicon to reduce SKU proliferation across Zigbee, Thread, and Bluetooth Low Energy variants.
- Home Automation:Integrated hubs and scene controllers coordinating security, climate, and entertainment systems. Chinese MIIT GB standards require domestic cybersecurity evaluation for connected building products.
- Industrial Controllers:Ruggedized actuators and programmable logic interfaces for factory floor deployment. Japanese manufacturers are replacing wired sensor infrastructure to reduce installation downtime in legacy equipment retrofits.
Established volume favors Smart Lighting; emerging adoption favors Industrial Controllers.
Deployment:
Cost tier separation distinguishes capital-intensive on-premises installations from operational expenditure models in cloud and hybrid configurations.
- On-Premises:Local gateway infrastructure with dedicated mesh coordinators and no external connectivity dependency. German healthcare facilities and California data centers prioritize this architecture for uptime guarantees that override capital expenditure optimization.
- Cloud-Based:Centralized orchestration platforms with over-the-air firmware distribution and predictive maintenance analytics. Utilities in China and the United States standardize on this model for home area network scalability.
- Hybrid:Edge-coordinated local control with cloud telemetry for energy reporting and remote diagnostics. French and Italian commercial real estate operators favor this balance for GDPR-compliant data residency.
- Edge Computing:Distributed intelligence at mesh router nodes enabling sub-50ms autonomous response. Industrial deployments in Japan and Germany adopt this for safety-critical actuator control.
Hybrid deployments capture mid-market expansion; edge computing climbs the fastest in manufacturing verticals.
Component:
Margin concentration shifts from hardware commoditization toward software stack ownership and multi-year service contracts.
- Hardware:Radio modules, antennas, and power management circuits with FCC Part 15 or MIIT GB certification. Taiwan foundry concentration exposes vendors to geopolitical disruption and allocation constraints.
- Software:Mesh networking stacks, commissioning tools, and security libraries achieving Zigbee 3.0 certification. Silicon Laboratories anchors position through dedicated software that simplifies OEM certification cycles.
- Services:Network commissioning, firmware management, and field engineering bundled as multi-year contracts. System integrators in Germany and California capture this margin in healthcare and data center verticals.
- Gateways:Protocol translation devices bridging Zigbee mesh to IP networks and cloud platforms. Brazil's ANEEL grid modernization program creates first-mover advantage for certified gateway suppliers.
Hardware dominates procurement volume; services deepen margin capture in enterprise deployments.
End User:
Application maturity separates consumer-driven residential adoption from regulated industrial and healthcare requirements.
- Residential:Smart home ecosystems integrating lighting, climate, security, and entertainment through voice and mobile interfaces. Matter protocol convergence enables cross-ecosystem compatibility with Apple, Google, and Amazon platforms.
- Commercial:Building automation for offices, retail, and hospitality with energy management and space optimization. EU Green Deal mandates accelerate mesh-network deployments across Germany, France, and Italy.
- Industrial:Factory wireless retrofit replacing wired sensor infrastructure with battery-operated endpoints. PSA Certified and SESIP evaluation timelines extend product launch schedules by 6-12 months for resource-constrained vendors.
- Healthcare:Patient monitoring, environmental control, and asset tracking with HIPAA or GDPR compliance requirements. Specialized field engineering for mesh commissioning struggles to staff at scale.
Commercial buildings sustain deployment scale; healthcare applications gain share fastest on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal energy efficiency mandates are accelerating Zigbee mesh deployments across German commercial real estate, while China's MIIT enforces GB standards that reshape import requirements for foreign module suppliers.
United States
FCC Part 15 emission limits govern unlicensed Zigbee operation across smart meter home area networks. Utilities in California and Texas are standardizing on Zigbee for residential energy management, creating sustained module demand through 2035. Silicon Valley system integrators are capturing service-layer margins through multi-year firmware management contracts for data center deployments.
Germany
EU Green Deal building certification requirements mandate granular energy monitoring in commercial retrofits. REACH frameworks impose escalating material disclosure costs for radio module importers. Industrial clusters in Bavaria and North Rhine-Westphalia are replacing wired sensor infrastructure with battery-operated endpoints to reduce factory installation downtime.
China
MIIT GB standards tighten spurious emission limits and mandate domestic cybersecurity evaluation for connected building products. The National Smart Grid Mission drives procurement standardization for home area network infrastructure. Shenzhen and Shanghai hardware vendors are pre-certifying designs against both MIIT and FCC requirements to accelerate dual-market entry.
Japan
METI industrial efficiency programs subsidize wireless retrofit of legacy factory equipment. JIS standards shape procurement specifications for building automation in commercial real estate. Manufacturing clusters in Aichi Prefecture and Osaka are adopting battery-operated Zigbee endpoints to minimize production line disruption during sensor infrastructure upgrades.
Brazil
ANEEL grid modernization programs create first-mover advantage for certified gateway suppliers in Latin America's largest economy. National regulators are drafting localized certification rules that could fragment hardware approval pathways. São Paulo-based system integrators are bundling network commissioning with utility-scale smart meter rollouts.
Global Zig-Bee Automation Market Competitive Environment
Listed leaders compete with private specialists across certification velocity and software stack maturity. The vendor base organizes around three tiers: integrated semiconductor conglomerates with radio-frequency portfolios, dedicated wireless connectivity chipmakers, and industrial module specialists focused on mesh-networking firmware. Consolidation pressures favor players with in-house foundry relationships or captive testing partnerships. Competitive moves center on multi-protocol silicon development and pre-certification against divergent national standards.
Within the integrated semiconductor tier, Texas Instruments Incorporated and Qualcomm Incorporated exemplify scale-driven positioning through wireless connectivity intellectual property extension. Silicon Laboratories Inc. occupies a specialist position through dedicated mesh-networking software stacks. STMicroelectronics and NXP Semiconductors represent European-based alternatives with broad industrial customer relationships. These anchors illustrate how competitive advantage redistributes toward certification velocity rather than proprietary radio designs.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| NXP Semiconductors |
| Silicon Laboratories Inc. |
| Microchip Technology Inc. |
| STMicroelectronics |
| Digi International Inc. |
| Qualcomm Incorporated |
| Renesas Electronics Corporation |
| Intel Corporation |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal interoperability mandates and FCC Part 15 certification gates simultaneously determine supplier qualification tiers and price differentiation in Zigbee module procurement. Buyers face dual cost pressures from REACH material disclosure compliance and multi-protocol silicon qualification, compressing margins for uncertified vendors while rewarding pre-certified stack providers.
Pricing Analysis
Certification level (Zigbee 3.0/PSA Certified/SESIP-grade) creates the primary spread between premium firmware-integrated modules and commodity radio chips. Three-tier pricing structure across premium, standard, and economy levels reflects software stack maturity, with Silicon Laboratories and Texas Instruments commanding premiums for pre-certified mesh networking libraries. Cost compression in economy-tier hardware is intensifying because Taiwan foundry allocation constraints force smaller vendors into spot-market wafer purchases. Residential smart home OEMs exhibit highest price sensitivity, while German healthcare facilities and California data centers prioritize certification velocity over unit cost.
Supply Chain Analysis
Strategic stockpiling of certified radio modules dominates enterprise procurement, with German system integrators and Chinese smart meter programs maintaining 6-9 month buffer inventories against foundry allocation volatility. Supply concentrates in Taiwan for advanced RF silicon, China for module assembly and testing, and the Netherlands for multi-protocol lighting controller production. Raw material dependencies include gallium arsenide substrates, rare earth magnetics for antenna components, and conflict-mineral-classified tantalum capacitors. Single-source vulnerability in Taiwan semiconductor foundries exposes vendors to geopolitical disruption. Distribution runs through authorized distributor networks for hardware, with direct engagement models for multi-year firmware management services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Matter protocol convergence over Thread is compressing Zigbee's standalone value proposition, creating platform-economics pressure where full-stack ownership determines survival. Vendors must reposition around certification velocity and cross-ecosystem compatibility rather than single-protocol hardware dominance.
For Market Incumbents: Consolidate around multi-protocol silicon development and captive certification partnerships to defend against Wi-Fi 6 and Thread substitution in bandwidth-intensive applications. Deepen backward integration into Taiwan foundry relationships or secure allocation guarantees through long-term wafer agreements. Prioritize PSA Certified and SESIP evaluation investment to compress 6-12 month security certification timelines that currently delay product launches. For New Entrants and Emerging Players: Lead with unbundled network commissioning services for healthcare and data center verticals where specialized field engineering scarcity creates margin capture opportunities. Target Brazil's ANEEL grid modernization program and India's National Smart Grid Mission as first-mover geographies with localized certification pathways still forming. Pursue gateway-focused go-to-market positioning, as protocol translation devices bridge procurement gaps in utility-scale deployments. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with dormant wireless connectivity divisions lacking Zigbee 3.0 certification velocity. Long-term viability hinges on software stack ownership rather than hardware component supply, favoring acquisitions with embedded firmware management contract revenue. Watch Matter protocol adoption rates in residential smart home ecosystems as the critical inflection signal for Zigbee standalone demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Silicon Development | Enables dynamic switching between Zigbee, Thread, and Bluetooth Low Energy for Dutch and South Korean lighting OEMs. |
| Dual Certification Pre-Qualification | Accelerates market entry by validating designs against both MIIT GB and FCC Part 15 requirements simultaneously. |
| Firmware Management Service Bundling | Captures recurring revenue from German healthcare and California data center verticals with uptime guarantees. |
| Foundry Allocation Security | Mitigates Taiwan semiconductor concentration risk through long-term wafer agreements or alternative sourcing partnerships. |
| Matter Protocol Migration Path | Preserves ecosystem relevance as Zigbee Alliance transitions cross-compatibility to Apple, Google, and Amazon platforms. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, encompassing smart lighting OEM procurement directors, industrial controller firmware engineers, German system integrators, and Taiwan semiconductor foundry planning officers. Secondary validation drew from FCC equipment authorization databases, MIIT GB standard filings, EU Green Deal implementation guidance, and utility smart meter deployment disclosures. Bottom-up module shipment estimates triangulated against top-down infrastructure investment projections across the analysis window.
Across the projection horizon, the analytical framework modeled volume and value trajectories by product type, deployment architecture, component mix, and end-user vertical, with additional segmentation by regional regulatory cluster. CAGRs were derived from infrastructure deployment timelines and replacement cycle analysis. Forecast inputs incorporated EU Green Deal building retrofit mandates, China's National Smart Grid Mission procurement schedules, and industrial wireless retrofit subsidy programs under Japan's METI efficiency initiatives.
The analysis sits within stated boundaries; outcomes outside sustained smart meter rollout continuity, stable Taiwan foundry capacity, or Matter protocol adoption trajectories would require recalibration. Forecasts reflect documented assumptions regarding certification timeline compression and multi-protocol silicon penetration rates. Revision becomes warranted when geopolitical disruption in semiconductor supply or regulatory fragmentation in Brazil and India certification rules crosses material thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Global Business Process Automation Software Market
Automation
AR Automation Market
Automation
Service Delivery Automation (SDA) Market
Automation
Laboratory Benchtop Automation Market
Automation
Italy Marketing Automation Market
Automation
North America Home Automation Systems Market
Automation
Workload Scheduling and Automation Market
Automation
Middle East and Africa Workforce Management Market
Automation
Smart Home Automation Market
Automation
Global Form Automation Software Market
Automation
Global Warehouse Barcode System Market
Automation
Helpdesk Automation Market
Automation
Database Automation Market
Automation
Global Warehouse Execution System Market
Automation
Automation Testing Market
Automation
Process Automation Market