
 Artificial Intelligence-Based Security Market | 2026-2036
Artificial Intelligence-Based Security Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence-Based Security Market Analysis
Enterprise distribution of AI-based security tools is fragmenting as direct sales, managed security service providers, and cloud marketplaces compete for procurement budgets. Palo Alto Networks leverages integrated platform strategies to sustain enterprise relationships. CrowdStrike anchors cloud-native endpoint protection with behavioral AI models. Fortinet competes through hardware-software convergence at the network edge.
Artificial Intelligence-Based Security encompasses systems that apply machine learning algorithms, neural network architectures, and statistical pattern recognition to identify, classify, and respond to cyber threats or physical security anomalies in real time. These systems process log data, network traffic, video feeds, or access events to automate detection and reduce mean time to response across enterprise environments. Video surveillance solutions dominate current deployment value as municipalities and critical infrastructure operators retrofit legacy camera networks with computer vision analytics. Cloud-based deployment expands fastest among mid-market enterprises seeking elastic compute for model training without capital-intensive infrastructure. Machine learning technology leads R&D allocation, though deep learning applications in behavioral biometrics are gaining traction for high-assurance access control scenarios.
The EU AI Act classifies certain security AI applications as high-risk systems, mandating conformity assessments before market placement. The US SEC requires registrants to disclose material cybersecurity incidents, accelerating board-level investment in AI-augmented security operations. China's NMPA and MIIT coordinate standards for facial recognition and data processing in security contexts. Stakeholders must monitor how divergent regulatory timelines for algorithmic accountability reshape product development roadmaps and geographic rollout sequencing.
Market Dynamics
The Artificial Intelligence-Based Security Market is undergoing structural compression as sovereign cyber defense mandates force procurement localization and algorithmic accountability requirements multiply compliance burdens across jurisdictions.
Growth Catalysts
- EU AI Act high-risk classification:Mandatory conformity assessments for automated security decision-making systems are creating certified vendor ecosystems that lock out unqualified competitors and accelerate enterprise upgrade cycles.
- Behavioral biometrics adoption:Deep learning architectures for high-assurance access control are penetrating financial services and critical infrastructure operators seeking to replace static credential systems.
- Cloud-native elasticity:Mid-market enterprises are abandoning capital-intensive on-premise model training infrastructure for consumption-based compute, expanding addressable demand beyond Fortune 500 accounts.
Market Restraints
- GPU supply concentration:Training infrastructure for neural security models depends on Taiwan Semiconductor Manufacturing and NVIDIA supply allocations, creating procurement bottlenecks during demand surges.
- Cross-border data localization:China's MIIT and NMPA facial recognition standards conflict with EU GDPR data transfer mechanisms, fragmenting product architectures and duplicating R&D expenditure.
- False positive fatigue:Machine learning detection systems generate alert volumes that exceed Security Operations Center analyst capacity, degrading trust and delaying response authorization.
Strategic Opportunities
- Legacy camera network retrofit:Municipalities in Germany and critical infrastructure operators across the United States are overlaying computer vision analytics on existing video surveillance hardware without full replacement.
- Federated learning architectures:Privacy-preserving model training across distributed endpoints addresses GDPR and sector-specific data residency constraints without centralizing sensitive telemetry.
- SEC disclosure acceleration:Material cybersecurity incident reporting requirements are compressing board-level procurement approval timelines and elevating AI-augmented security operations to strategic investment priority.
Industry Challenges
- Adversarial ML expertise scarcity:Security teams lack personnel capable of defending neural networks against poisoned training data and evasion attacks, forcing reliance on external specialists.
- Multi-jurisdiction certification sequencing:Divergent EU AI Act, US SEC, and China NMPA conformity timelines delay product launches and fragment engineering roadmaps across compliance workstreams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence-Based Security Market |
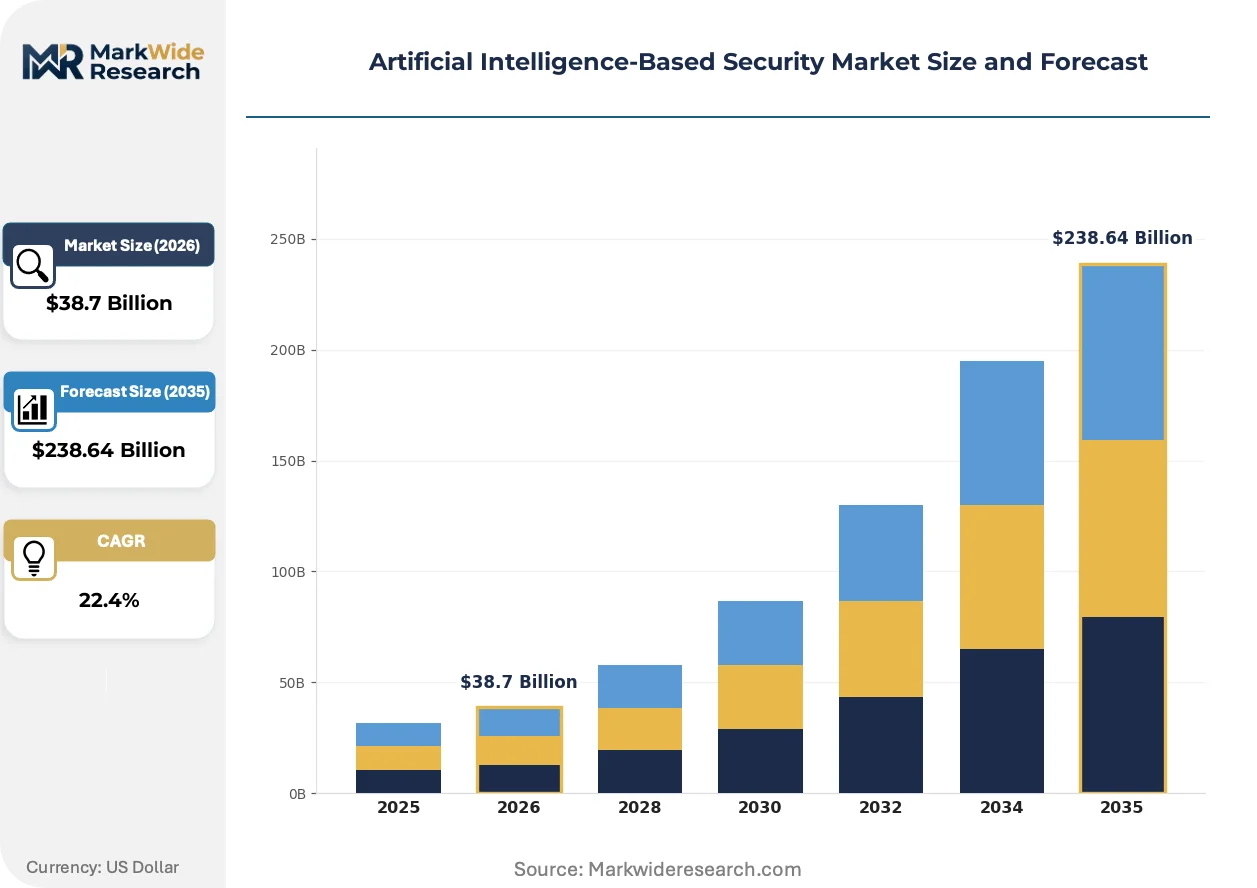
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $238.64 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Video Surveillance, Intrusion Detection, Threat Intelligence, Access Control Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing End User: Government, BFSI, Retail, Healthcare Technology: Machine Learning, Deep Learning, Natural Language Processing, Computer Vision |
| Companies Covered | Palo Alto Networks, CrowdStrike, Fortinet, Check Point Software Technologies, Darktrace, SentinelOne, Cisco Systems, Trend Micro, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence-Based Security Market Emerging Trajectories
Three intersecting developments are restructuring competitive advantage in AI-based security: hardware-software convergence at the network edge, algorithmic accountability mandates, and procurement channel fragmentation.
Edge AI accelerators are collapsing the latency gap between threat detection and automated response. Network equipment manufacturers are embedding Tensor Processing Units directly into firewall appliances and access switches. Manufacturing facilities and energy utilities with sub-10-millisecond response requirements are eliminating cloud round-trip dependencies.
The EU AI Act's high-risk system classification is forcing architectural redesigns for automated security decision-making. Vendors must implement human-in-the-loop override mechanisms and algorithmic transparency documentation. Financial services institutions in Germany and France are prioritizing conformity-assessed solutions to preempt regulatory enforcement.
Enterprise buyers are unbundling security procurement across direct vendor relationships, managed security service providers, and hyperscaler marketplaces. Mid-market enterprises in the United States are consolidating purchasing through cloud marketplaces to leverage existing cloud consumption commitments. This channel rotation is compressing traditional enterprise sales cycles and elevating platform integration capabilities over point-product performance.
Artificial Intelligence-Based Security Market Segmentation
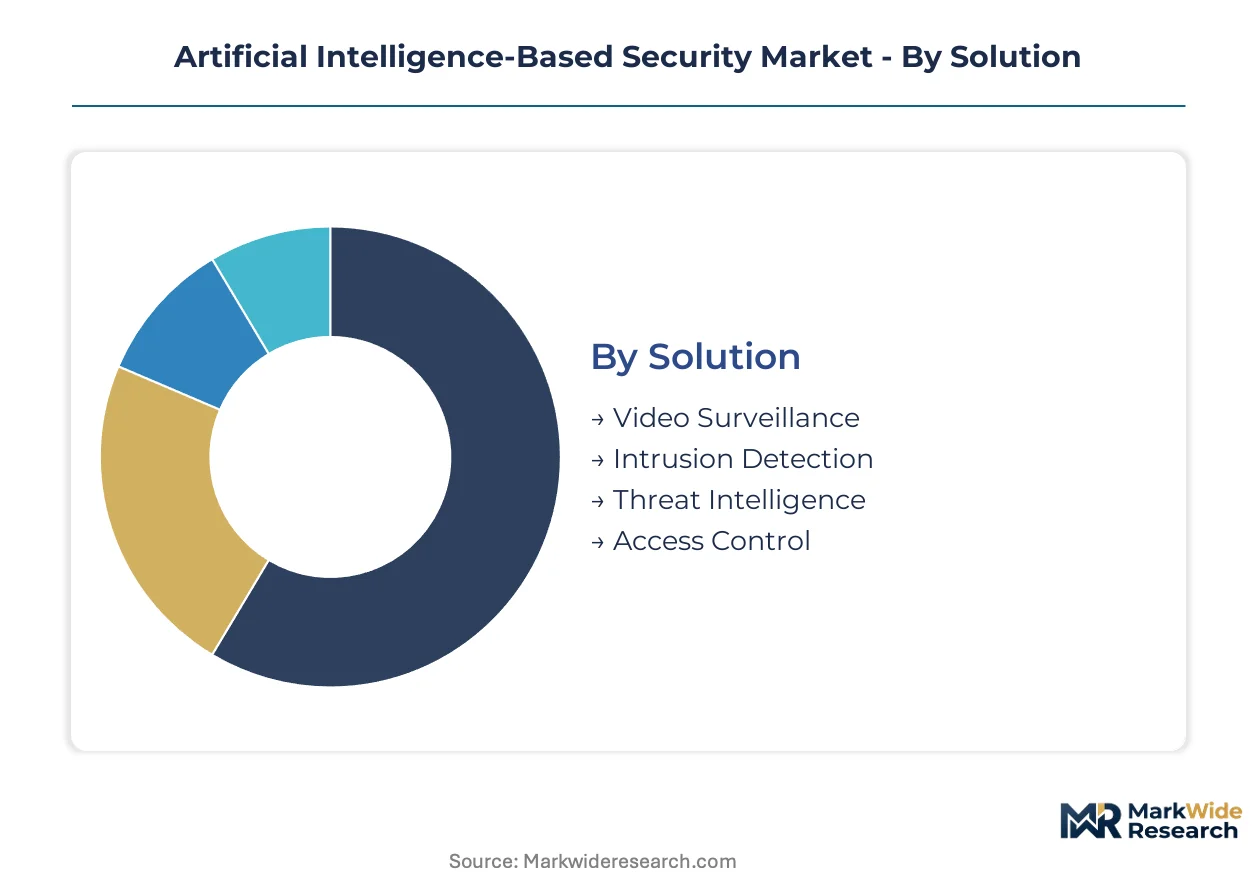
Segmentation in AI-based security reveals how procurement priorities diverge across infrastructure maturity, regulatory exposure, and operational tempo. Buyers select architectures based on data sovereignty requirements and response latency constraints rather than feature checklists alone.
Solution:
After-sales service intensity varies sharply across solution types, with video surveillance demanding continuous model retraining and intrusion detection requiring 24/7 analyst escalation protocols.
- Video Surveillance:Computer vision analytics overlay legacy camera networks in municipalities and critical infrastructure. German operators prioritize GDPR-compliant retention policies; US utilities emphasize thermal anomaly detection for perimeter hardening.
- Intrusion Detection:Behavioral ML models flag lateral movement patterns in enterprise networks. Financial services institutions in the United States deploy these systems to satisfy SEC disclosure readiness mandates.
- Threat Intelligence:Automated indicator correlation and attribution scoring.
- Access Control:Biometric and credential management with AI-driven risk scoring.
Video Surveillance holds the largest share; momentum sits with Intrusion Detection.
Deployment:
Cost tier stratification separates capital-intensive on-premises builds from consumption-priced cloud alternatives, with hybrid architectures capturing buyers seeking workload-specific optimization.
- Cloud-Based:Elastic compute for model training without infrastructure ownership. Mid-market enterprises in the United States consolidate purchasing through hyperscaler marketplaces to leverage existing cloud commitments.
- On-Premises:Air-gapped environments for classified or regulated data. Government agencies in Germany and China specify sovereign hardware stacks to satisfy MIIT and EU AI Act localization requirements.
- Hybrid:Split processing between edge inference and cloud retraining.
- Edge Computing:Sub-10-millisecond response for manufacturing and energy utilities.
Cloud-Based deployment leads current procurement volume; Edge Computing shows the steepest expansion trajectory as latency requirements tighten.
End User:
Application urgency drives segment differentiation, with BFSI facing regulatory disclosure deadlines and healthcare managing protected health information exposure.
- Government:Sovereign cyber defense mandates concentrate procurement in the United States, China, and Germany. National security agencies specify conformance to NMPA, EU AI Act, and classified processing standards.
- BFSI:SEC disclosure rules compress board-level approval timelines. US banks prioritize AI-augmented security operations centers to meet material incident reporting windows.
- Retail:Loss prevention and customer behavior analytics at scale.
- Healthcare:HIPAA-covered entities deploy access control with audit trail automation.
Government accounts dominate contract value; BFSI is climbing the fastest as regulatory enforcement intensifies.
Technology:
Customer technical sophistication determines technology selection, with deep learning reserved for organizations possessing data science infrastructure and machine learning serving broader enterprise adoption.
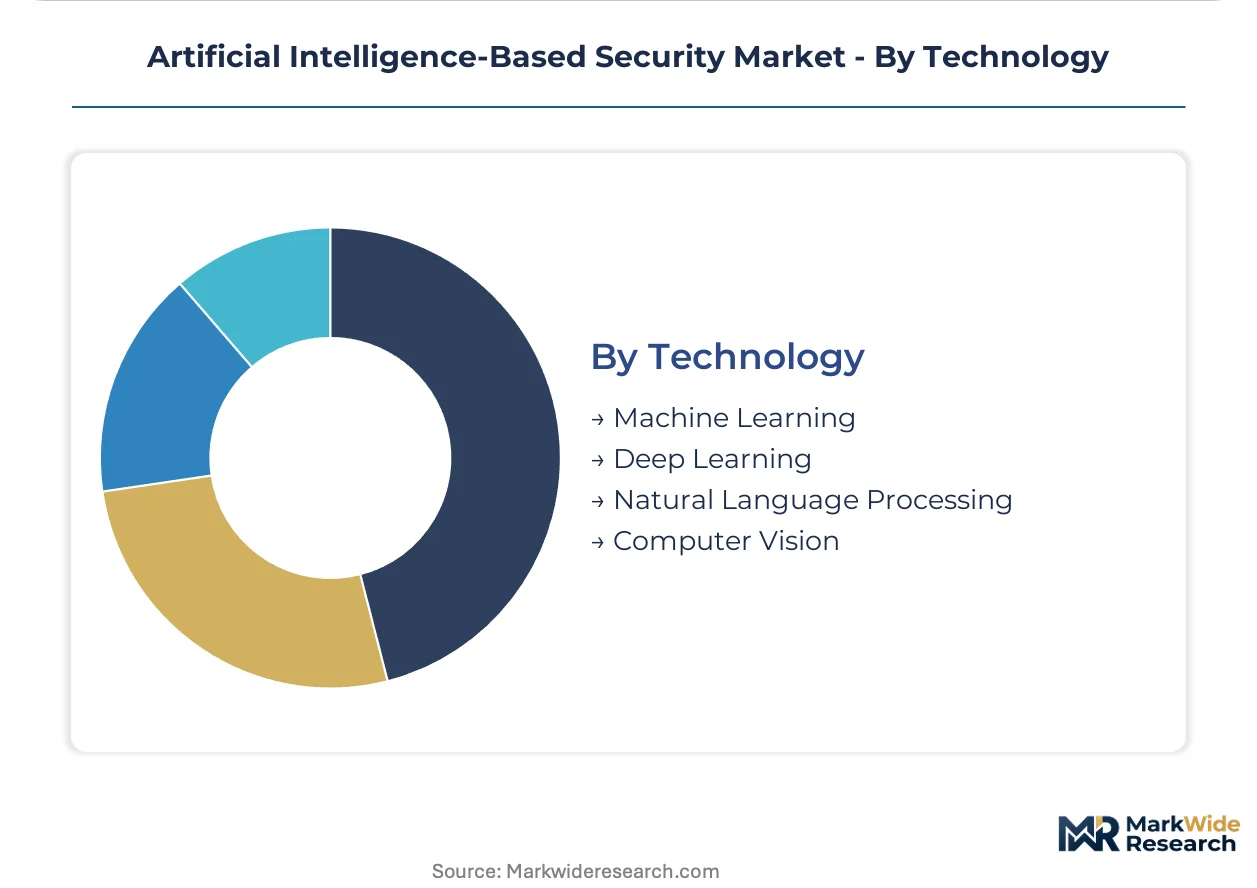
- Machine Learning:Statistical pattern recognition for log analysis and anomaly detection. R&D allocation concentrates here due to implementation tractability across mid-market security operations centers.
- Deep Learning:Neural architectures for behavioral biometrics and facial recognition. China's NMPA and MIIT coordinate standards that shape product development for domestic and export markets.
- Natural Language Processing:Phishing detection and security operations automation.
- Computer Vision:Object detection and activity recognition in physical security contexts.
Machine Learning anchors current deployment value; Deep Learning is gaining share fastest in high-assurance access control scenarios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The submarine cable landing stations at Virginia Beach and Fortaleza anchor transatlantic data flows that drive AI security procurement in the United States and Brazil. Sovereign cloud infrastructure investments in Frankfurt and Singapore reshape how enterprises deploy threat detection systems across three continents.
United States
Financial services institutions in New York and Chicago accelerate AI-augmented security operations center investments to meet SEC disclosure deadlines. The SEC mandates material cybersecurity incident reporting within four business days. Northern Virginia's data center corridor concentrates cloud-native security deployments for federal contractors.
Germany
Industrial operators in Bavaria and North Rhine-Westphalia retrofit legacy manufacturing networks with edge AI accelerators for sub-10-millisecond threat response. The EU AI Act imposes conformity assessments on automated security decision-making systems. Frankfurt's financial district prioritizes certified vendors to preempt regulatory enforcement.
China
Critical infrastructure operators in Beijing and Shanghai deploy facial recognition and behavioral biometrics under NMPA and MIIT coordinated standards. The MIIT mandates data localization for security AI processing. Shenzhen's hardware ecosystem supplies edge computing appliances for domestic and Belt and Road markets.
United Kingdom
London's financial services firms consolidate security procurement through hyperscaler marketplaces to leverage existing cloud commitments. The National Cyber Security Centre publishes algorithmic accountability guidance for automated threat detection. Cambridge's machine learning research cluster feeds talent pipelines into security AI vendors.
Japan
Manufacturing facilities in Nagoya and Osaka embed Tensor Processing Units directly into firewall appliances for air-gapped production environments. METI promotes sovereign cyber defense capabilities through public-private partnerships. Tokyo's financial district demands human-in-the-loop override mechanisms for automated security decisions.
Artificial Intelligence-Based Security Market Vendor Landscape
On the supply side, the industry is consolidating around integrated platform strategies that bundle network, endpoint, and cloud security under unified management consoles. Tier-one vendors leverage hardware-software convergence at the network edge while cloud-native specialists compete on behavioral AI model sophistication. Two strategic archetypes dominate: full-stack platform providers and point-solution specialists with deep learning differentiation. Competitive moves center on strategic partnerships with hyperscalers and vertical integration into edge AI accelerator silicon.
Within the platform-provider tier, Palo Alto Networks and CrowdStrike exemplify divergent architectural bets on network-centric versus endpoint-native security intelligence. Fortinet occupies a position bridging hardware-software convergence with cloud-delivered services. These three companies represent the competitive fault lines between integrated stack depth and cloud-native agility.
| Leading Market Players |
|---|
| Palo Alto Networks |
| CrowdStrike |
| Fortinet |
| Check Point Software Technologies |
| Darktrace |
| SentinelOne |
| Cisco Systems |
| Trend Micro |
| Microsoft |
| Others |
Supply Flow & Price Mechanics
Taiwan Semiconductor Manufacturing's capacity allocation decisions for NVIDIA AI accelerators directly shape pricing power for security AI vendors downstream. GPU supply scarcity concentrates procurement leverage among hyperscalers and tier-one platform providers, forcing mid-market buyers into longer contract terms with less favorable unit economics.
Pricing Analysis
Volume-discount tiering structures dominate AI-based security procurement, with enterprise buyers above ten thousand seats capturing 40-60% unit cost reductions against mid-market commitments. Certification grade under EU AI Act conformity assessment protocols and after-sales service bundling separate premium-tier vendors from standard offerings. Pricing pressure stems from cloud marketplace consolidation, where AWS and Azure consumption commitments drive commoditization of baseline threat detection features. Government and BFSI segments exhibit lowest price sensitivity due to regulatory compliance mandates; mid-market retail and healthcare buyers face acute budget constraints and demand modular, unbundled pricing.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for AI security hardware manufacturers. Taiwan, South Korea, and the United States anchor GPU and TPU fabrication capacity, while China controls rare earth processing and PCB assembly for edge computing appliances. Neural security model training draws from NVIDIA H100 allocations, Taiwan Semiconductor advanced node wafers, and high-bandwidth memory modules from SK Hynix and Samsung. Single-source vulnerability around TSMC's 4nm production node threatens delivery timelines during demand surges. Distribution runs through direct enterprise sales, managed security service providers, and hyperscaler marketplaces in roughly equal share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as mid-market enterprises consolidate procurement through hyperscaler marketplaces, fragmenting traditional vendor-direct relationships and compressing sales cycle leverage.
For Market Incumbents: Pre-empt cloud-native entrants by embedding Tensor Processing Units into firewall appliances at the network edge, securing manufacturing and energy utility accounts with sub-10-millisecond response requirements. Fortify certification positioning under EU AI Act high-risk system classification before conformity assessment backlogs delay competitor market entry. Channel control through managed security service provider partnerships remains essential as enterprise buyers unbundle procurement. For New Entrants and Emerging Players: Establish a beachhead in federated learning architectures for GDPR-constrained European financial services institutions, where privacy-preserving model training addresses data residency requirements incumbent platforms struggle to meet. Target German industrial operators retrofitting legacy camera networks with computer vision analytics, leveraging after-sales service intensity gaps left by platform providers. Lead with consumption-based pricing through hyperscaler marketplaces to bypass lengthy enterprise procurement cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors point-solution specialists with deep learning differentiation in behavioral biometrics, as platform consolidation matures and high-assurance access control demands accelerate. Long-term viability hinges on regulatory certification moats and edge AI accelerator silicon integration. Acquisition target archetype: computer vision analytics vendors with municipal and critical infrastructure customer concentration. Watch for EU AI Act enforcement actions as inflection indicator for certified vendor valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Palo Alto Networks and CrowdStrike exemplify unified console strategies that reduce buyer switching costs. |
| Edge AI Accelerator Development | TPU-embedded firewall appliances address manufacturing and energy utility latency requirements below 10 milliseconds. |
| EU AI Act Certification Investment | Conformity assessment completion locks out unqualified competitors from German and French financial services procurement. |
| Federated Learning Architecture Deployment | Privacy-preserving training across distributed endpoints satisfies GDPR constraints without centralizing sensitive telemetry. |
| Hyperscaler Marketplace Partnership | AWS and Azure consumption commitment leverage expands addressable demand among mid-market US enterprises. |
Methodological Framework
Initial hypotheses were tested against primary input from chief information security officers, managed security service provider procurement leads, cloud marketplace integration specialists, and EU regulatory compliance officers, then refined through secondary validation. Security vendor SEC 10-K filings, hyperscaler capex disclosures, EU AI Act implementation guidance, and NMPA facial recognition standard drafts anchored quantitative triangulation. Bottom-up deployment volume estimates and top-down market sizing converged through iterative reconciliation.
Demand-supply-balance framing structured the analytical approach across the projection horizon. Segmentation dimensions modeled include solution type, deployment architecture, end-user vertical, technology sophistication tier, and geographic regulatory cluster. CAGRs were derived from fitted growth curves against historical adoption patterns and policy enforcement timelines. Forecast inputs incorporated GPU supply allocation constraints from Taiwan Semiconductor and NVIDIA, alongside EU AI Act conformity assessment capacity limits.
Sensitivities concentrate around Taiwan semiconductor fabrication disruptions, EU AI Act enforcement acceleration, and hyperscaler marketplace pricing compression. Forecasts reflect documented assumptions regarding sovereign cyber defense procurement localization and neural network training infrastructure availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
North America Artificial Intelligence Market
Artificial Intelligence (AI)
Automotive Gesture Recognition Market
Artificial Intelligence (AI)
AI As a Service (Aiaas) Market
Artificial Intelligence (AI)
Decision Intelligence Market
Artificial Intelligence (AI)
Content Automation AI Tools Market
Artificial Intelligence (AI)
Digital Intelligence Technology Market
Artificial Intelligence (AI)
Multimodal AI Market
Artificial Intelligence (AI)
AI in Medical Writing Market
Artificial Intelligence (AI)
Context Aware Computing Market
Artificial Intelligence (AI)
Enterprise Generative AI Market
Artificial Intelligence (AI)
Home AI Oven Market
Artificial Intelligence (AI)
Machine Learning in Pharmaceutical Industry Market
Artificial Intelligence (AI)
Machine Learning As a Service (Mlaas) Market
Artificial Intelligence (AI)
AI Demand Forecasting Software Market
Artificial Intelligence (AI)
North America Conversational AI Market
Artificial Intelligence (AI)
AI Search Engine Market