
 US Workload Scheduling and Automation Market | 2026-2036
US Workload Scheduling and Automation Market Size, Share, and Industry Trends Forecast 2026-2036
US Workload Scheduling and Automation Market Insights
Aftermarket service revenue from legacy mainframe workload schedulers is narrowing as enterprises shift toward cloud-native orchestration platforms. BMC Software leverages its Control-M franchise to sustain recurring maintenance streams while navigating subscription transitions. IBM Corporation anchors hybrid cloud automation through its acquisition-integrated workload portfolio, while ServiceNow competes by extending IT service management workflows into automated job scheduling across enterprise accounts.
Workload scheduling and automation encompasses software systems that sequence, trigger, and monitor computational jobs across distributed computing environments, typically managing dependencies through event-driven architectures with sub-second latency thresholds for real-time pipelines. These platforms orchestrate batch processes, ETL workflows, and microservice chains to ensure resource utilization efficiency and service-level compliance in data-intensive operations. Cloud-based deployment models are capturing the fastest expansion as SaaS delivery eliminates infrastructure provisioning cycles, while on-premises installations retain dominance in regulated segments where data residency requirements constrain off-premise migration. Job scheduling solutions concentrate mature margin pools in mainframe-centric financial services, whereas API-based integration levels are gaining share as enterprises dismantle monolithic batch architectures.
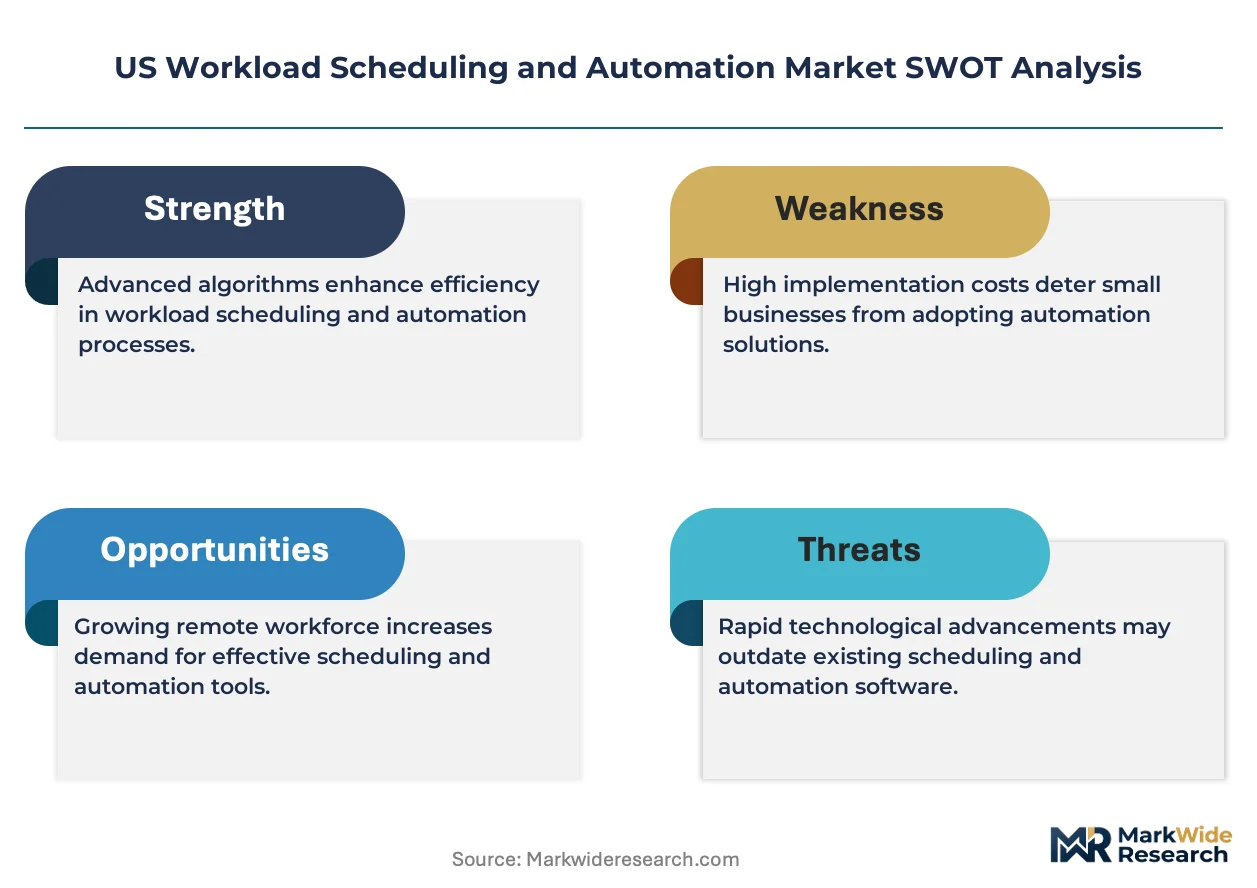
FedRAMP authorization requirements from GSA shape vendor qualification for federal agency procurement, while NIST SP 800-53 security controls mandate audit logging and access management capabilities that filter market participants by compliance infrastructure depth. State-level data privacy statutes in California and Virginia impose additional residency and encryption standards that influence deployment model selection for multi-tenant automation platforms. Stakeholders must monitor how NIST's evolving AI risk management framework intersects with automated decision pipelines in workload systems, as algorithmic transparency requirements could reshape product roadmaps and competitive positioning.
Market Dynamics
FedRAMP authorization requirements and NIST cybersecurity frameworks are compressing vendor qualification timelines while federal agencies accelerate cloud migration mandates. This regulatory overlay favors established automation platforms with pre-certified compliance infrastructure over emerging entrants.
Growth Catalysts
- Cloud-Native Orchestration:Kubernetes-based workload schedulers are capturing enterprise batch processing migrations as containerization standardizes deployment patterns across hybrid environments.
- California Data Privacy Statutes:State-level residency and encryption mandates in CCPA-aligned jurisdictions are sustaining on-premises automation demand among financial services firms with multi-state operations.
- Real-Time Pipeline Latency:Sub-second event-driven architectures are displacing traditional polling-based job schedulers in fraud detection and algorithmic trading workflows.
Market Restraints
- Mainframe Skill Scarcity:Retiring COBOL and JCL specialists are constraining migration velocity for legacy Control-M and CA-7 estates in banking and insurance sectors.
- FedRAMP Certification Costs:Authorization timelines stretching 12-18 months and six-figure audit expenses are filtering SaaS vendors from federal procurement pools.
- Hybrid Integration Complexity:API translation layers between on-premises schedulers and cloud-native orchestrators are extending implementation cycles and inflating professional services dependencies.
Strategic Opportunities
- Texas Data Center Expansion:Hyperscale facility construction in Dallas-Fort Worth and Austin corridors is generating greenfield automation deployments for colocation and enterprise tenants.
- AI Risk Management Framework Convergence:NIST's evolving algorithmic transparency requirements are creating compliance automation modules for automated decision pipelines in federal workload systems.
- API-First Microservice Chains:Event mesh architectures integrating Apache Kafka with workload schedulers are opening displacement opportunities against monolithic batch platforms in retail and logistics.
Industry Challenges
- Cross-Platform Credential Federation:Identity synchronization between legacy mainframe security domains and cloud IAM systems is fragmentating access control policies and audit trails.
- Observability Stack Fragmentation:Splunk, Datadog, and Prometheus integration requirements are forcing automation vendors to maintain multiple telemetry adapters, diluting R&D concentration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Workload Scheduling and Automation Market |
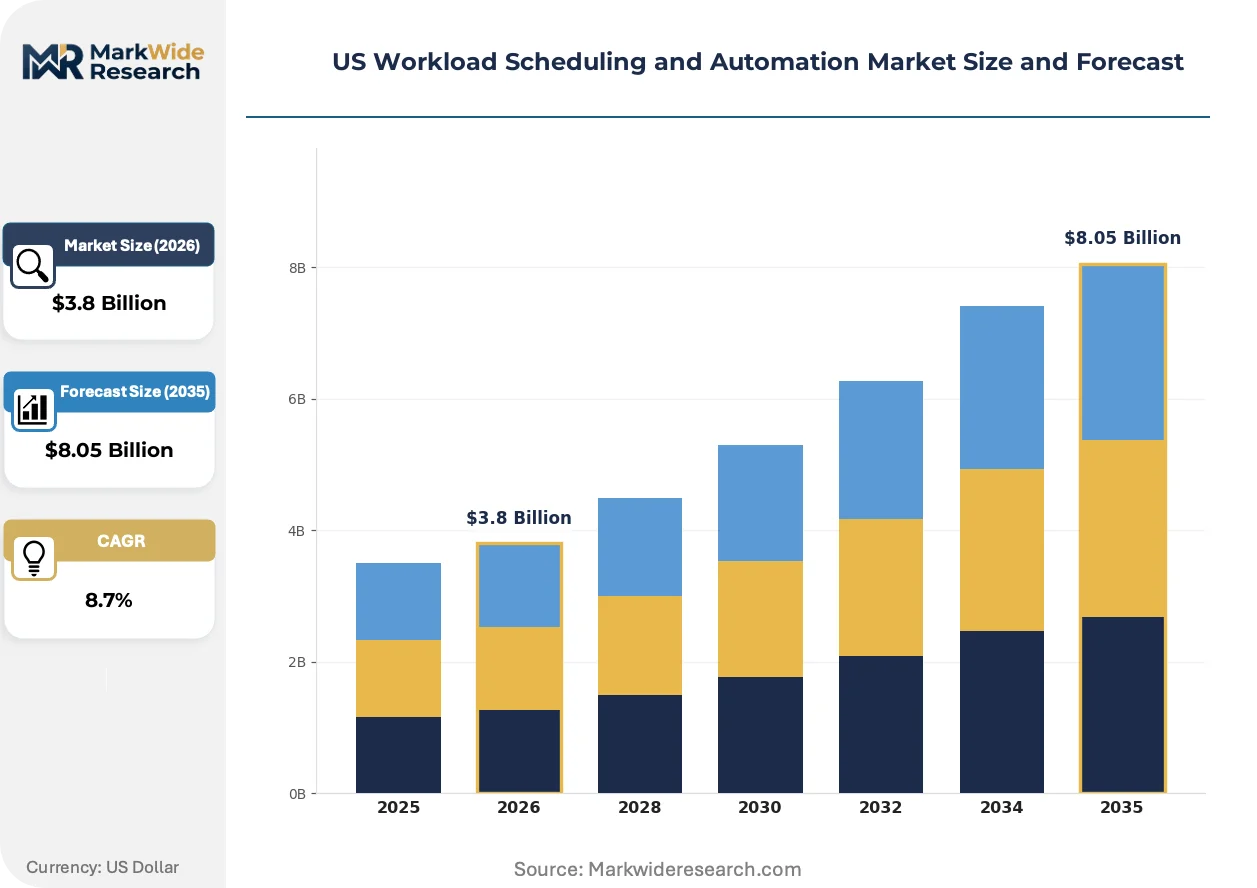
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Workload Automation Tools, Schedule Management Software, Resource Allocation Systems, Job Scheduling Solutions Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: IT Departments, Financial Services, Healthcare Providers, Manufacturing Firms Integration Level: API-Based, Batch Processing, Real-Time Integration, Custom Integration |
| Companies Covered | BMC Software, Inc., IBM Corporation, Oracle Corporation, VMWare Inc., Stonebranch Inc., ServiceNow, CA Technologies, ASG Technologies Group, Inc., Hitachi Vantara Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Workload Scheduling and Automation Market Trends and Innovations
Workload automation architectures are pivoting from time-based polling to event-driven responsiveness as real-time data pipelines displace overnight batch windows. This shift is compressing infrastructure provisioning cycles and elevating API-first design principles.
Container-native schedulers are virtualizing job execution environments through Kubernetes operators and custom resource definitions. Financial services DevOps teams are adopting these patterns at enterprise scale, collapsing the boundary between infrastructure and application orchestration while enabling elastic resource scaling for variable compute loads.
NIST SP 800-53 security controls and FedRAMP Moderate baselines are mandating immutable audit logging and role-based access management in federal procurement specifications. Defense contractors and civilian agencies are prioritizing pre-authorized platforms, narrowing vendor pools to those with sustained compliance infrastructure investments and documented continuous monitoring postures.
Enterprise buyers are consolidating automation procurement under platform engineering functions rather than distributed IT operations teams. This centralization is displacing point-tool acquisitions in favor of unified orchestration suites, with Virginia-based federal contractors and California technology firms exhibiting the most pronounced organizational restructuring toward internal developer platforms.
US Workload Scheduling and Automation Market Segmentation
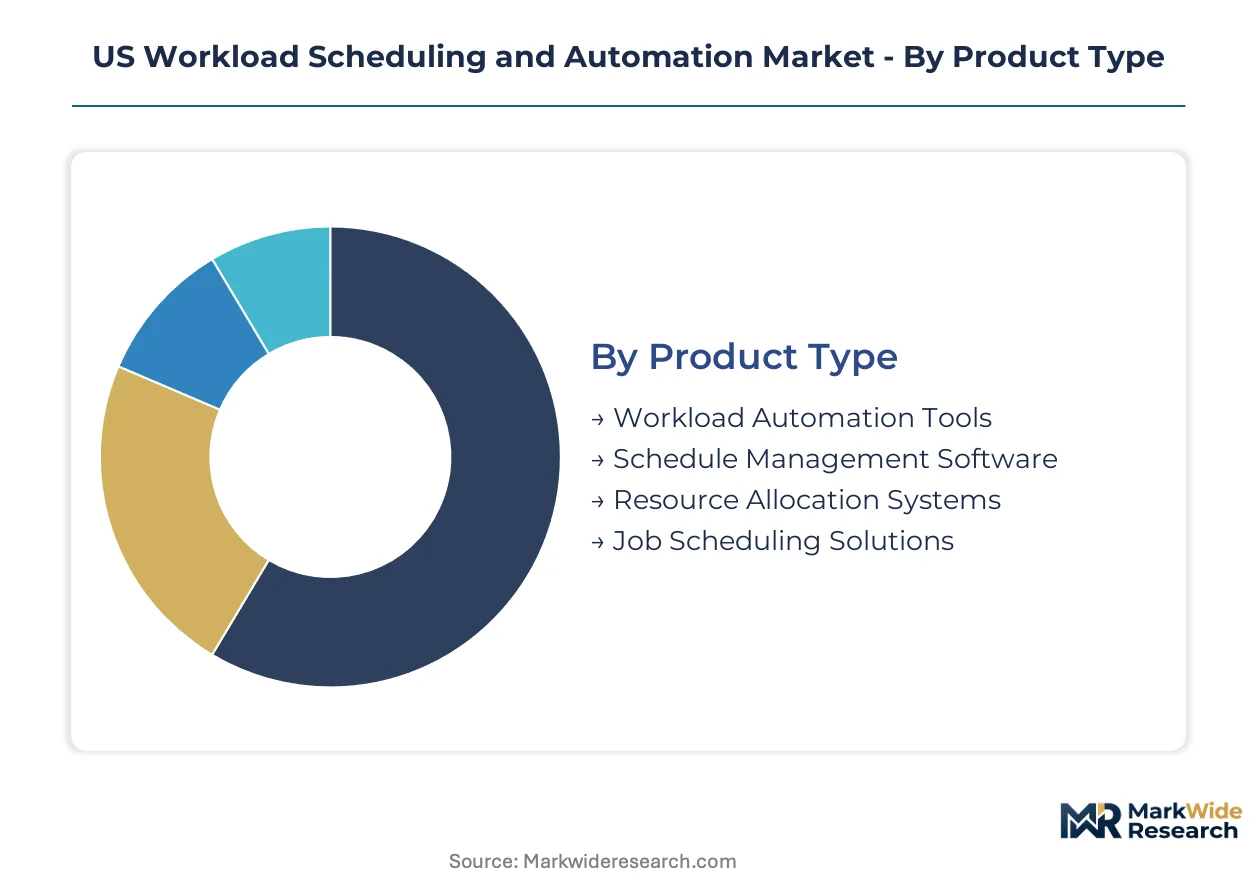
Segmentation in workload scheduling reflects divergent infrastructure maturity across US enterprises. Deployment preferences split between legacy-bound regulated sectors and cloud-native technology firms, while integration architectures separate batch-centric financial services from event-driven digital operations.
Product Type:
Use-case spectrum spans mainframe-centric batch orchestration to Kubernetes-native microservice chaining, with functional depth determining procurement budgets and implementation complexity.
- Workload Automation Tools:These platforms orchestrate cross-platform job dependencies through centralized control planes, supporting both distributed and mainframe environments. Financial services firms in New York and Chicago deploy these for end-of-day settlement batching, driven by regulatory reporting deadlines and zero-downtime requirements.
- Schedule Management Software:Calendar-driven systems trigger jobs based on time-based policies with dependency chaining and exception handling. Manufacturing firms across Michigan and Ohio leverage these for production line synchronization, constrained by legacy ERP integration requirements and shop-floor system interoperability.
- Resource Allocation Systems:Compute optimization engines match job requirements against available infrastructure capacity.
- Job Scheduling Solutions:Entry-tier products handle straightforward task sequencing without complex dependency management.
Established volume favors Workload Automation Tools; emerging adoption favors Schedule Management Software.
Deployment Model:
Cost tier separation distinguishes capital-intensive perpetual licenses from operational expenditure SaaS contracts, with compliance overhead driving hybrid middle-ground selections.
- On-Premises:Infrastructure deployed within enterprise data centers with full operational control over hardware and security stacks. Defense contractors in Virginia and intelligence community vendors maintain these deployments to satisfy FedRAMP High and classified processing requirements, constrained by NIST SP 800-53 control implementation costs.
- Cloud-Based:Multi-tenant or dedicated cloud infrastructure eliminates hardware procurement cycles and enables elastic scaling. Technology startups in Austin and Seattle prefer these models, driven by venture capital efficiency mandates and rapid product iteration cycles.
- Hybrid:Split deployments maintaining sensitive workloads on-premises while bursting variable loads to cloud infrastructure.
- SaaS:Fully managed subscription delivery with vendor-controlled infrastructure and automatic feature updates.
Defense procurement sustains On-Premises dominance; Cloud-Based deployments are climbing the fastest among commercial enterprises.
End User:
Customer type segmentation aligns with vertical-specific compliance burdens and digital transformation maturity, separating regulated infrastructure from agile development cultures.
- IT Departments:Centralized technology organizations procure automation platforms as shared services across business units. State government IT shops in California and Texas standardize on these systems, driven by consolidated procurement mandates and inter-agency workflow coordination requirements.
- Financial Services:Banks, insurers, and payment processors operate mission-critical batch windows with sub-second recovery objectives. Healthcare providers in Massachusetts and Minnesota are expanding adoption, constrained by HIPAA audit logging specifications and patient data residency requirements.
- Healthcare Providers:Hospital systems and payers automate claims processing and clinical data pipelines.
- Manufacturing Firms:Discrete and process manufacturers synchronize supply chain and production systems.
Financial Services anchor current revenue concentration; Healthcare Providers show steepest expansion trajectory as clinical analytics pipelines mature.
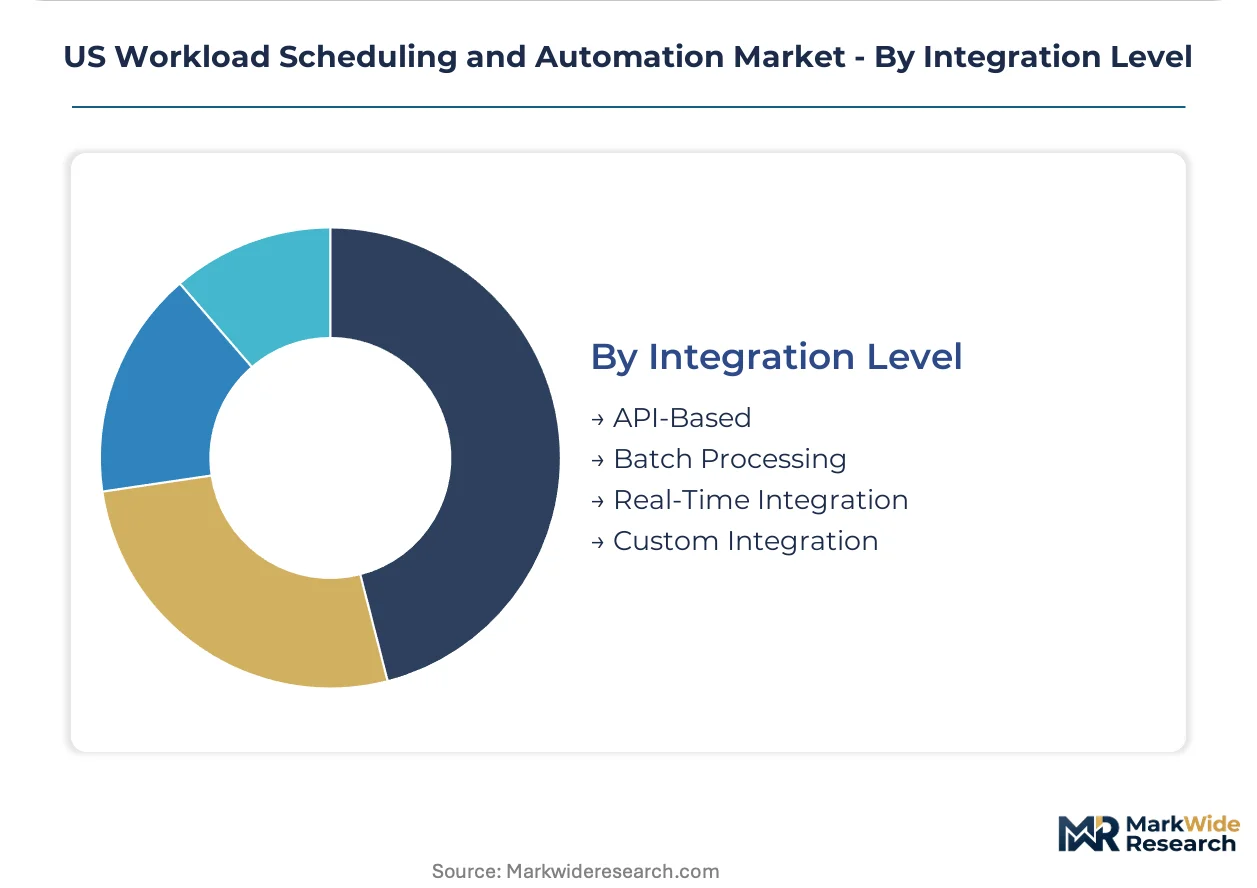
Integration Level:
Technical architecture maturity separates legacy batch paradigms from modern event-driven responsiveness, with API standardization enabling ecosystem connectivity.
- API-Based:REST and GraphQL interfaces enable real-time triggering and status monitoring across distributed systems. E-commerce platforms in Los Angeles and logistics operators in Memphis deploy these patterns, driven by customer-facing SLA requirements and microservice decomposition strategies.
- Batch Processing:File-based or database-polling architectures process accumulated data during defined windows. Insurance claims processors in Hartford and Hartford-adjacent markets retain these systems, constrained by decades-old policy administration platforms and mainframe data formats.
- Real-Time Integration:Event streaming through message brokers enables sub-second pipeline responsiveness.
- Custom Integration:Bespoke connectors address proprietary or obsolete system interoperability requirements.
Batch Processing retains installed base dominance; API-Based architectures are gaining share fastest as platform engineering teams consolidate tooling standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across US sub-regions: federal contractors in Virginia show minimal price sensitivity due to compliance mandates, while Texas-based commercial enterprises negotiate aggressively on SaaS licensing terms.
California
Technology enterprises in Silicon Valley and San Francisco drive cloud-native orchestration procurement, prioritizing API-first architectures for microservice chains. CCPA and emerging state privacy statutes enforce data residency requirements that sustain hybrid deployment models. Los Angeles-based e-commerce platforms and San Diego defense contractors anchor dual demand streams for real-time pipeline automation.
Texas
Hyperscale data center construction in Dallas-Fort Worth and Austin corridors generates greenfield automation deployments for colocation providers and enterprise tenants. State procurement frameworks emphasize vendor certification standards without federal-level FedRAMP overhead. Houston energy sector firms and Austin technology startups diverge on deployment preferences, splitting between on-premises control and elastic cloud scaling.
Virginia
Defense contractors and intelligence community vendors in Northern Virginia maintain rigid on-premises infrastructure to satisfy FedRAMP High and classified processing requirements. NIST SP 800-53 control implementation costs filter vendor participation, favoring established platforms with sustained compliance investments. The Dulles technology corridor concentrates federal systems integrators with specialized automation expertise.
New York
Financial services firms in Manhattan and Jersey City operate mission-critical batch windows with sub-second recovery objectives, preserving mainframe-centric workload estates alongside cloud migration initiatives. State Department of Financial Services cybersecurity regulations impose audit logging specifications that shape vendor selection. Legacy Control-M installations in banking and insurance sectors constrain migration velocity due to retiring COBOL specialist scarcity.
Illinois
Manufacturing and logistics operators in Chicago and Peoria leverage schedule management software for production line synchronization and supply chain orchestration. Legacy ERP integration requirements and shop-floor system interoperability constrain rapid platform modernization. The region's industrial base exhibits slower cloud migration timelines compared to coastal technology centers.
US Workload Scheduling and Automation Market Competitive Landscape
Capability concentration sits with legacy mainframe automation specialists; scale advantage sits with cloud-native platform providers expanding through subscription transitions. The vendor base stratifies across three tiers: established enterprise suites with decades-long customer relationships, mid-market challengers emphasizing Kubernetes-native architectures, and point-solution specialists addressing niche compliance requirements. Dominant competitive moves include portfolio diversification into adjacent IT service management workflows and strategic partnerships with hyperscale cloud providers to accelerate FedRAMP authorization pathways.
Within the legacy enterprise tier, BMC Software and IBM Corporation exemplify vendors navigating recurring maintenance streams toward subscription models. ServiceNow occupies a position bridging IT service management and automated job scheduling for enterprise accounts. Stonebranch Inc. and ASG Technologies Group, Inc. sit within the specialist segment addressing hybrid integration complexity between on-premises schedulers and cloud-native orchestrators.
| Leading Market Players |
|---|
| BMC Software, Inc. |
| IBM Corporation |
| Oracle Corporation |
| VMWare Inc. |
| Stonebranch Inc. |
| ServiceNow |
| CA Technologies |
| ASG Technologies Group, Inc. |
| Hitachi Vantara Corporation |
| Others |
Pricing and Supply Chain Analysis
The Dallas-Fort Worth logistics corridor anchors software distribution cost dynamics for workload automation vendors, concentrating supply-side leverage among hyperscale cloud providers while downstream price differentiation splits between FedRAMP-authorized premium tiers and commercial SaaS discounting. California data center density and Virginia defense procurement requirements feed opposing pricing pressures that reshape vendor margin allocation across deployment models.
Pricing Analysis
Aftermarket maintenance contracts and professional services bundles drive lifetime value capture for established workload automation vendors. Subscription pricing stratifies across FedRAMP-authorized premium tiers, standard commercial SaaS, and economy-tier self-managed licenses, with certification level and compliance infrastructure depth as primary differentiation drivers. Pricing pressure stems from open-source Kubernetes-native alternatives commoditizing container orchestration layers. Federal contractors in Virginia exhibit minimal price sensitivity due to mandate-locked procurement, while Austin technology startups negotiate aggressively on per-seat SaaS terms.
Supply Chain Analysis
Upstream compute infrastructure feeds from Taiwan semiconductor foundries, South Korea memory fabrication, and domestic Intel and AMD processor supply. Cloud orchestration platforms rest on hyperscale data center buildouts in Texas, Virginia, and California, with API middleware and security certification modules as critical software components. Single-source vulnerability concentrates around FedRAMP authorization consultancies and specialized compliance auditors. Distribution runs through direct enterprise sales teams, channel partners, and cloud marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from open-source Kubernetes schedulers and low-code automation platforms that erode proprietary orchestration value. Defense of established revenue streams demands strategic repositioning around compliance moats and hybrid integration complexity.
For Market Incumbents: Build FedRAMP authorization moats by accelerating continuous monitoring investments and pre-certifying Moderate and High baseline platforms before competitors complete audit cycles. Deepen vertical integration into professional services capabilities to capture migration complexity from legacy Control-M estates. Counter open-source substitution by embedding immutable audit logging and role-based access management as non-negotiable procurement requirements in federal and financial services verticals.
For New Entrants and Emerging Players: Pursue white-space expansion in Texas hyperscale data center greenfield deployments where procurement frameworks lack federal-level certification overhead. Target mid-market healthcare providers in Massachusetts and Minnesota with HIPAA-aligned automation modules that incumbent suites price beyond reach. Lead go-to-market through platform engineering function relationships rather than traditional IT operations channels.
For Investors and Strategic Acquirers: Specialist compliance automation vendors with pre-authorized FedRAMP infrastructure and documented continuous monitoring postures represent priority acquisition archetypes. Long-term viability hinges on subscription transition completion and recurring revenue mix expansion. Watch NIST AI risk management framework finalization as inflection signal for algorithmic transparency module demand.
| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Acceleration | Pre-certification investments filter federal procurement pools to compliant vendors. |
| Kubernetes-Native Platform Launch | Container-native schedulers capture cloud migration momentum in financial services. |
| Hybrid Integration Partnership | API translation layers collapse implementation cycles for legacy-to-cloud transitions. |
| Acquisition of Compliance Specialist | Continuous monitoring capabilities and audit infrastructure deepen federal positioning. |
| Geographic Expansion into Texas | Dallas-Fort Worth data center construction generates greenfield automation demand. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with platform engineering directors, IT procurement officers, federal systems integrators, and DevOps leads; and secondary validation through SEC filings, hyperscaler capex disclosures, FedRAMP authorization databases, and NIST publication records. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against aggregate software spending patterns anchored market sizing.
Forecast inputs encompassed deployment model segmentation, organization size tiers, vertical compliance intensity, and integration architecture maturity across the projection horizon. CAGRs derived from elasticity modeling of cloud migration velocity and regulatory mandate implementation timelines. Modeled variables included Kubernetes adoption rates in financial services, FedRAMP authorization completion rates, and mainframe skill scarcity constraints on legacy estate migration.
Sensitivities concentrate around NIST AI risk management framework finalization, open-source scheduler commoditization velocity, and federal cloud migration mandate acceleration. Cross-checking against GSA procurement database trends and hyperscaler partnership announcement patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Home Automation System Market
Automation
Elevator Control Market
Automation
Automated Cell Block Systems Market
Automation
Global Sales Force Automation (SFA) Market
Automation
Global Process Automation and Instrumentation Market
Automation
Global Automated Liquid Handling System Market
Automation
Database Automation Market
Automation
Global Smart Vending Machines Market
Automation
Asia Pacific Marketing Automation Software Market
Automation
Process Automation Market
Automation
Helpdesk Automation Market
Automation
Middle East and Africa Workforce Management Market
Automation
Computer Numerical Control Market
Automation
APAC Water Automation and Instrumentation Market
Automation
Marketing Automation Solutions Market
Automation
CNC Controller Market