
 Polymerization Catalysts Market | 2026-2036
Polymerization Catalysts Market Size, Share, and Industry Trends Forecast 2026-2036
Polymerization Catalysts Market Intelligence
The EU Green Deal's push for a circular economy is rebalancing demand toward catalysts that enable the production of more recyclable and biodegradable polymers. LyondellBasell Industries Holdings BV leverages its extensive portfolio in polypropylene technologies to meet this shift. W. R. Grace & Co. specializes in advanced single-site catalysts for differentiated polyethylene grades, while Clariant AG competes on high-performance solutions for specialty applications in the automotive and electronics sectors.
Polymerization catalysts are substances that initiate and control the rate of reactions converting monomers into polymers. Their industrial function is the efficient, large-scale production of plastics like polyethylene and polypropylene with specific molecular structures and properties. Ziegler-Natta catalysts dominate the commodity polypropylene segment due to established process economics and high yields. In contrast, Metallocene catalysts command a premium in specialty polyethylene applications where precise polymer architecture is required for advanced packaging films.
Regulatory frameworks like the EU's REACH and oversight from the US EPA dictate catalyst composition and handling protocols. These agencies impose stringent requirements on chemical safety and environmental discharge, directly influencing research and development priorities. The key decision for manufacturers is how to balance investments between compliance with existing regulations and innovation for next-generation, sustainable polymers that support circular economy goals.
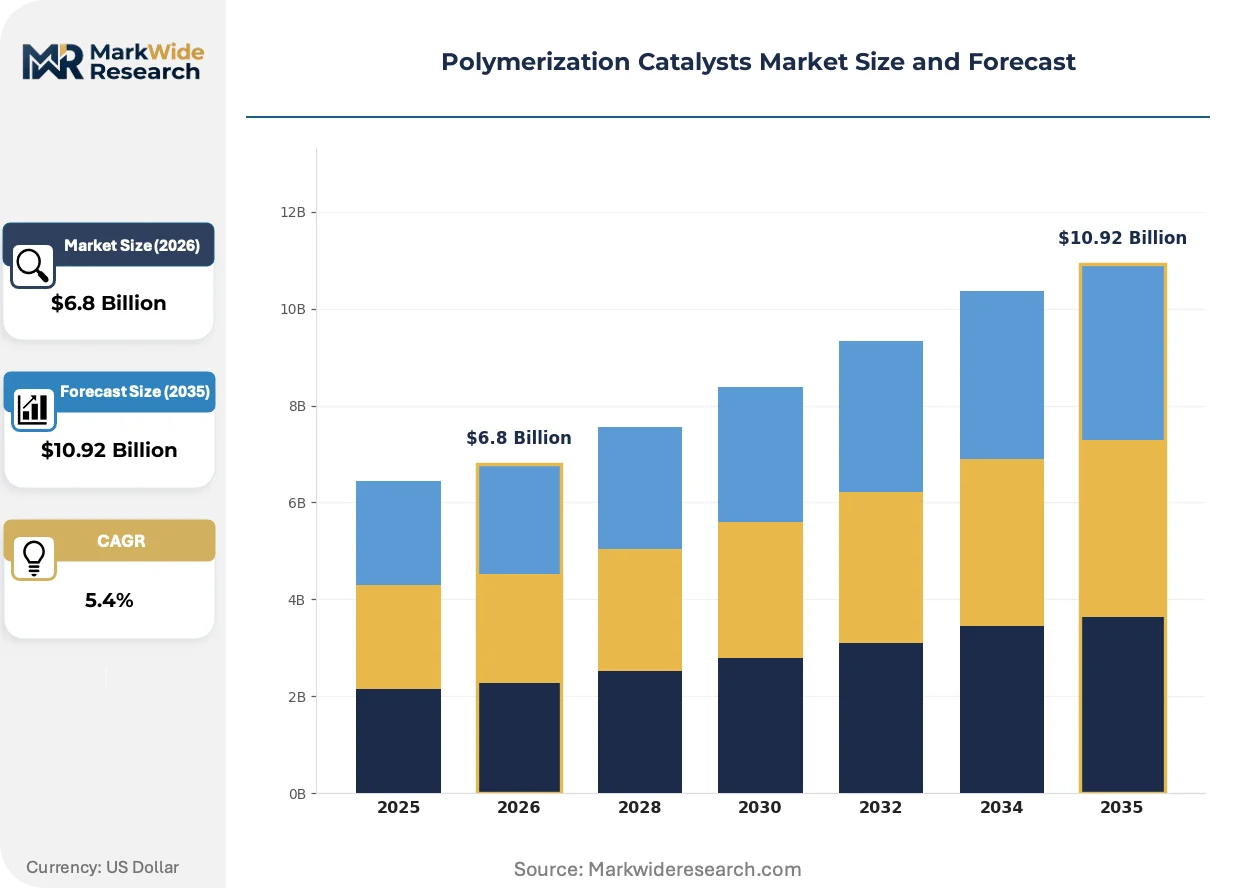
Market Dynamics
The central force shaping the polymerization catalysts market is the global regulatory pivot towards a circular economy. This shift directly influences R&D, prioritizing catalysts that enable the production of recyclable, biodegradable, or high-performance sustainable polymers.
Growth Catalysts
- EU Green Deal Framework:Mandates for increased recycled content and circularity in packaging are accelerating demand for catalysts that produce mono-material polymers and improve recyclability.
- Advanced Packaging Demand:The need for stronger, lighter, and more complex multilayer films in the food and medical packaging industries drives adoption of specialty catalysts like metallocenes.
- China's Chemical Hubs:The scaling of specialty chemical production in Chinese industrial zones requires a corresponding increase in the supply of high-performance catalysts to support advanced material manufacturing.
Market Restraints
- Input Cost Volatility:The price of essential raw materials for metallocene and other single-site catalysts, including organometallic compounds and cocatalysts, remains a significant source of margin pressure.
- Regulatory Compliance Burden:Navigating the complex chemical registration and evaluation processes under frameworks like the EU's REACH can delay the commercialization of new catalyst formulations.
- Performance Trade-offs:Developing catalysts that simultaneously optimize for activity, polymer properties, and compatibility with bio-based monomers presents a persistent technical challenge for researchers.
Strategic Opportunities
- Chemical Recycling Catalysts:A significant opportunity exists in developing novel catalysts specifically designed for depolymerization processes like pyrolysis, converting plastic waste back into monomer feedstocks.
- AI-Driven Catalyst Discovery:The integration of machine learning algorithms with high-throughput experimentation platforms can dramatically accelerate the identification and optimization of new catalyst structures.
- Bio-Polymer Synthesis:There is an emerging need for catalysts tailored for the efficient polymerization of bio-derived monomers, such as polylactic acid (PLA), to produce commercially viable bioplastics.
Industry Challenges
- Intellectual Property Complexity:The dense and overlapping patent landscape for established Ziegler-Natta and metallocene catalyst systems creates significant licensing hurdles and litigation risks for new entrants.
- High Capital Expenditure:The construction of world-scale catalyst manufacturing plants or the retrofitting of existing facilities to produce advanced formulations requires substantial upfront capital investment.
- Specialized Talent Scarcity:A shortage of polymer scientists and process engineers with deep expertise in catalyst design, synthesis, and scale-up inhibits innovation across the industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymerization Catalysts Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ziegler-Natta, Metallocene, Anionic, Cationic Application: Polyethylene, Polypropylene, Polystyrene, Polyurethane End User: Automotive, Packaging, Textiles, Electronics Catalyst Form: Liquid, Solid, Powder, Granular |
| Companies Covered | China Petrochemical Corporation (Sinopec), Univation Technologies LLC, W. R. Grace & Co., INEOS AG, Honeywell International Inc., LyondellBasell Industries Holdings BV, Clariant AG, Toho Titanium Co. Ltd, Mitsui Chemicals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymerization Catalysts Market Strategic Shifts & Innovations
Innovation in polymerization catalysts is defined by a fundamental tension between enhancing polymer performance and meeting stringent sustainability mandates. This dynamic steers research away from incremental improvements and toward breakthrough designs for circular material life cycles.
Single-site catalysts provide precise control over polymer molecular weight distribution and comonomer incorporation. The automotive and advanced packaging sectors are rapidly adopting these for lightweight components and high-clarity films. This technology is expanding into commodity applications, enabling producers to offer differentiated polyethylene and polypropylene grades previously unattainable with conventional catalysts.
China’s national "dual carbon goals" impose new efficiency standards on its massive chemical production sector. This policy compels polymer manufacturers to adopt catalysts that increase reaction yields and lower energy consumption per ton of output. The commodity polyolefins segment is most affected, triggering a wave of investment in catalyst upgrades to comply with stricter environmental performance metrics.
A notable behavioral shift is occurring as consumer brand owners and converters prioritize polymer feedstocks designed for recyclability. This disrupts traditional procurement models focused purely on cost, creating a pull for catalysts that yield mono-materials or simplify waste streams. The shift is most pronounced in the European fast-moving consumer goods (FMCG) packaging supply chain, driven by both regulatory targets and consumer sentiment.
Polymerization Catalysts Market Segmentation
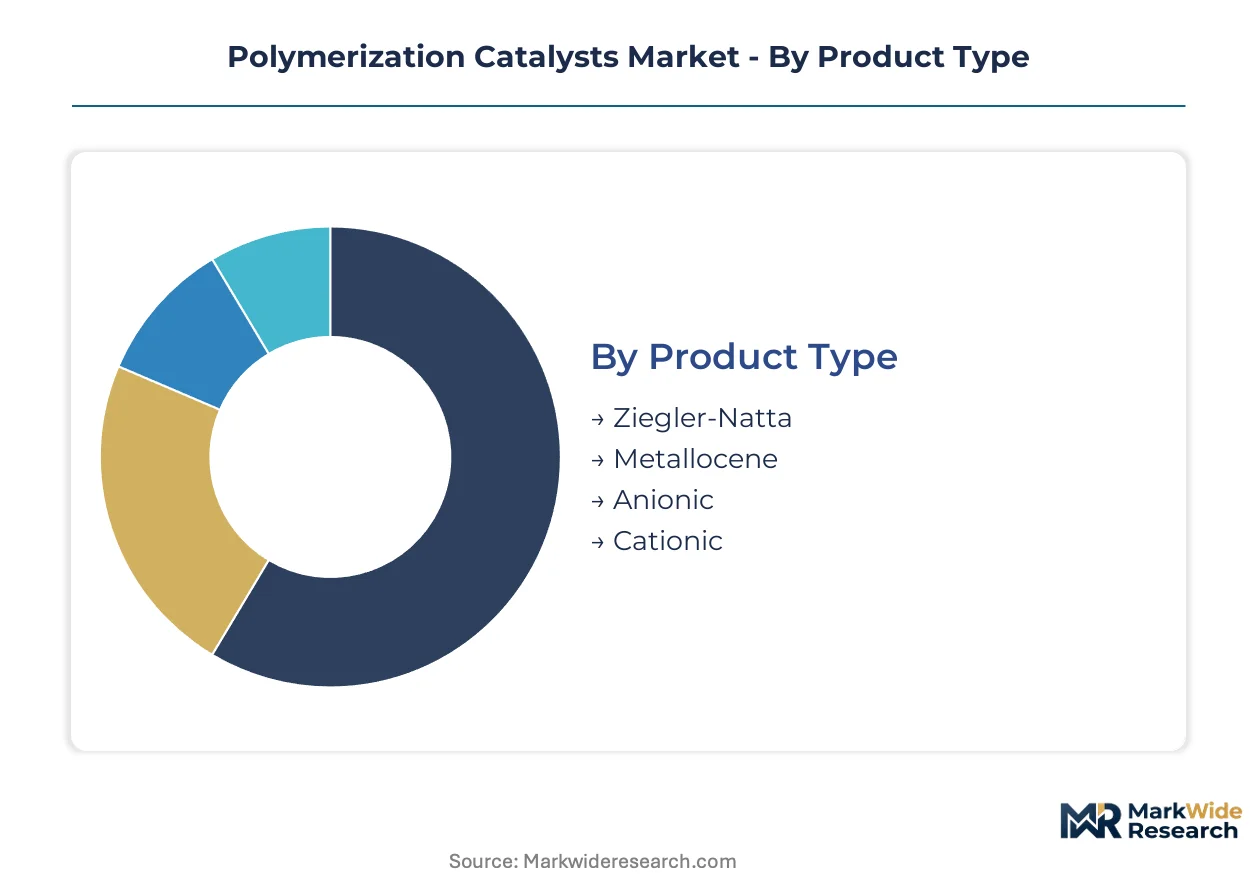
Segmentation of the polymerization catalysts market illuminates the diverse technological requirements across polymer production. Different catalyst types enable specific polymer architectures, influencing end-product performance and process efficiency. Understanding these segments helps manufacturers align investments with evolving industry demands, particularly those driven by circular economy principles and advanced material needs.
Product Type:
The capital expenditure required for catalyst production varies significantly across product types, with complex multi-component systems demanding substantial upfront investment in specialized manufacturing facilities.
- Ziegler-Natta:These heterogeneous catalysts, comprising transition metal compounds and organoaluminum cocatalysts, drive the stereospecific polymerization of olefins. Demand concentrates in the commodity polypropylene sector, where high yields and established process economics are critical for large-scale production facilities across China.
- Metallocene:Single-site catalysts featuring a transition metal atom sandwiched between cyclopentadienyl ligands offer precise control over polymer molecular weight and comonomer distribution. Advanced packaging films in Europe require these catalysts to achieve superior clarity, strength, and recyclability for mono-material designs.
- Anionic:These catalysts facilitate polymerization through a carbanion intermediate, commonly used for producing synthetic rubbers and specialty block copolymers.
- Cationic:Cationic catalysts initiate polymerization via a carbocation, primarily employed for highly reactive monomers like isobutylene to produce butyl rubber.
Most installed capacity flows through Ziegler-Natta catalysts. Expansion is steepest in metallocene catalysts.
Application:
The volume of polymer production for each application segment dictates the scale and consistency required from polymerization catalyst suppliers.
- Polyethylene:This thermoplastic polymer, synthesized through various catalytic processes, finds extensive use in packaging films, pipes, and containers. Global packaging industry shifts towards recyclable solutions drive demand for catalysts that produce high-density and linear low-density polyethylene grades.
- Polypropylene:A versatile thermoplastic, polypropylene is used in automotive components, textiles, and rigid packaging due to its strength and heat resistance. China's expanding automotive manufacturing sector requires high-performance catalysts for lightweight polypropylene composites.
- Polystyrene:This rigid, transparent thermoplastic is produced via free-radical polymerization, commonly used for disposable packaging and insulation.
- Polyurethane:Polyurethanes are thermosetting polymers formed by reacting isocyanates with polyols, finding applications in foams, coatings, and adhesives.
Polyethylene applications consume the largest share of catalyst volume. Polypropylene applications are gaining share fastest.
End User:
End-user industries exhibit varied requirements for polymer properties, influencing the selection and development of specialized polymerization catalysts.
- Packaging:This sector utilizes polymers for films, bottles, and containers, prioritizing properties like barrier protection, clarity, and recyclability. The EU Green Deal's push for circularity mandates catalysts that enable mono-material packaging solutions.
- Automotive:Polymers in automotive applications contribute to lightweighting, fuel efficiency, and interior comfort through components like dashboards and bumpers. Manufacturers in Germany increasingly demand catalysts for advanced polypropylene and polyethylene grades that reduce vehicle weight without compromising safety.
- Textiles:Polymers such as polyester and nylon are used in fibers for clothing, carpets, and industrial fabrics, requiring catalysts that optimize fiber strength and dye uptake.
- Electronics:This industry employs polymers for insulation, casings, and circuit boards, seeking materials with specific dielectric properties and flame retardancy.
The packaging industry represents the largest end-user segment for polymerization catalysts. The automotive sector is experiencing significant expansion in catalyst demand for lightweight materials.
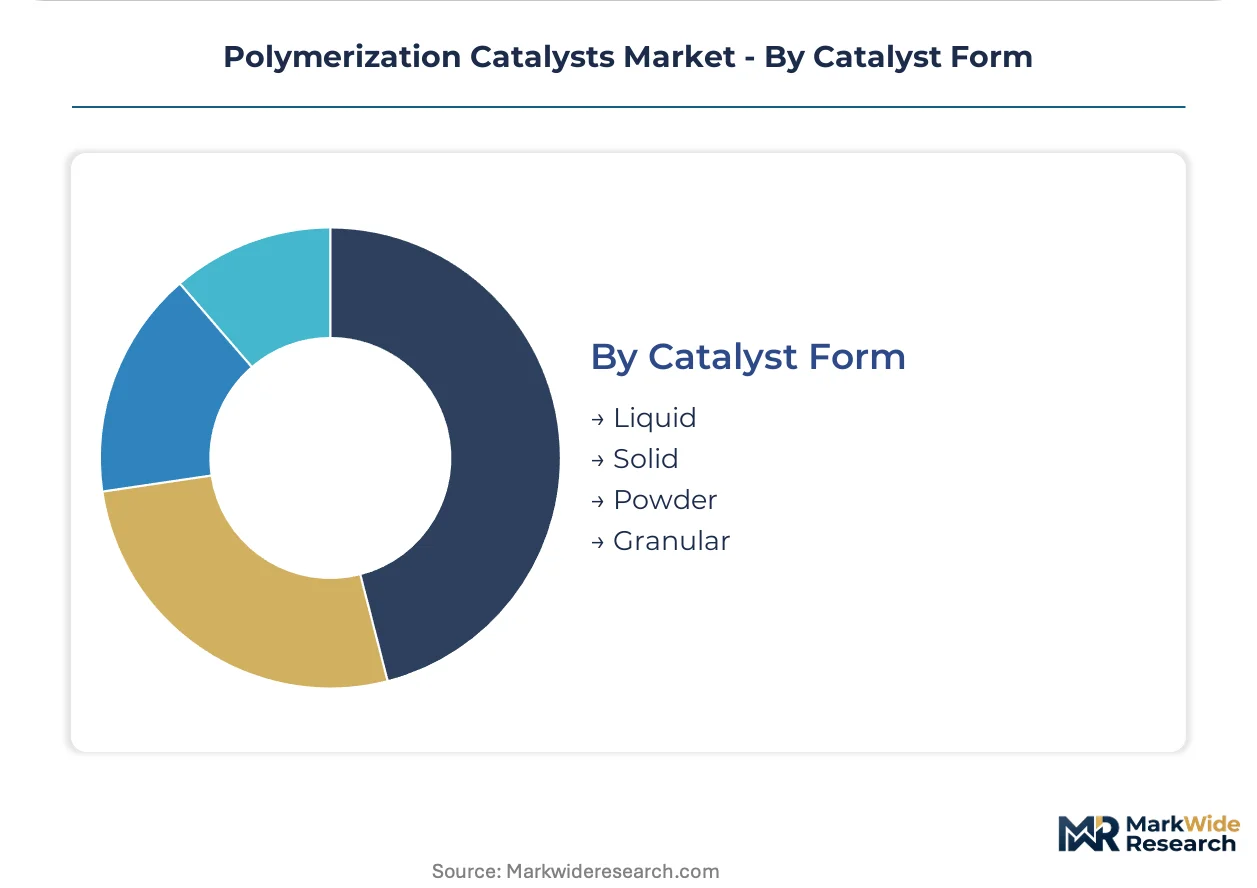
Catalyst Form:
The physical form of a polymerization catalyst directly impacts its handling, storage, and dosing complexity within industrial reactors.
- Solid:Solid catalysts, often supported on inert carriers, are widely used in gas-phase and slurry polymerization processes. Their ease of separation from the polymer product and robust performance make them suitable for large-scale commodity polymer production.
- Granular:Granular catalysts offer improved flowability and reduced dusting compared to powder forms, enhancing safety and handling efficiency in automated feeding systems. This form is increasingly preferred for continuous polymerization processes in advanced manufacturing hubs.
- Liquid:Liquid catalysts, typically homogeneous solutions, provide excellent mixing and high activity but can present challenges in recovery and separation from the polymer.
- Powder:Powder catalysts offer a large surface area for reaction but require careful handling to prevent agglomeration and ensure uniform dispersion in the reactor.
Solid catalyst forms dominate the market due to established infrastructure. Granular catalyst forms are demonstrating the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A highly skilled workforce in chemical engineering and materials science anchors the global polymerization catalysts market. This talent pool drives innovation and operational excellence across key manufacturing hubs worldwide. Their expertise supports advanced polymer production for diverse industrial applications.
China
China's extensive chemical manufacturing capabilities drive significant demand for high-performance polymerization catalysts. The nation's "dual carbon goals" impose stringent efficiency standards on polymer producers. Industrial zones across the Yangtze River Delta are scaling up production of specialty materials, requiring a corresponding increase in catalyst supply.
Germany
German manufacturers prioritize catalysts for advanced polypropylene and polyethylene grades to reduce vehicle weight. The EU Green Deal significantly influences investment in sustainable polymer development. Chemical parks in the Rhine-Main region are focusing on developing advanced polymer grades for automotive and electronics sectors.
United States
The United States sees sustained demand for catalysts supporting advanced packaging solutions and specialty polymer applications. The US EPA dictates stringent requirements for catalyst composition and environmental discharge. Gulf Coast chemical complexes are expanding capacity for polyolefin production, driven by domestic and export market needs.
Japan
Japanese industries require catalysts for high-performance materials, particularly in the electronics and automotive sectors. METI actively promotes advanced materials research to enhance industrial competitiveness. Chemical industry clusters around Tokyo Bay are developing next-generation catalysts for precision polymer architectures.
India
India's rapid infrastructure development and expanding consumer goods packaging sector fuel catalyst demand. BIS standards influence polymer quality and safety requirements across the country. Petrochemical complexes in Gujarat are significantly increasing polymer output to meet domestic and regional market needs.
Polymerization Catalysts Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the polymerization catalysts market, shaping a tiered competitive structure. The market exhibits consolidation among established players, while specialized firms focus on niche applications. Archetypes include integrated chemical giants, pure-play catalyst developers, and technology licensors. Dominant competitive moves involve strategic partnerships for R&D and targeted capacity expansion to meet regional demand.
At the integrated chemical giant end of the spectrum, LyondellBasell Industries Holdings BV exemplifies extensive portfolio management in polypropylene technologies. W. R. Grace & Co., a US-based corporation, represents a pure-play catalyst developer specializing in advanced single-site catalysts for differentiated polyethylene grades. Furthermore, Clariant AG, a Swiss-based chemical company, occupies a position in high-performance solutions for specialty applications, particularly in the automotive and electronics sectors. These companies anchor innovation and supply chain resilience across diverse polymer markets.
| Leading Market Players |
|---|
| China Petrochemical Corporation (Sinopec) |
| Univation Technologies LLC |
| W. R. Grace & Co. |
| INEOS AG |
| Honeywell International Inc. |
| LyondellBasell Industries Holdings BV |
| Clariant AG |
| Toho Titanium Co. Ltd |
| Mitsui Chemicals Inc. |
| Others |
Cost & Logistics Intelligence
Sovereign-backed producers and integrated chemical giants exert pricing discipline, influencing material costs and supply chain stability for polymerization catalysts. This structure impacts global market access.
Pricing Analysis
Bundled catalyst solutions, including technical support and process optimization, command premium pricing, contrasting with unbundled commodity catalyst sales. Contract-based long-term offtake agreements dominate the market, with price differentiation driven by catalyst performance grade and customization level. Pricing pressure stems from input cost volatility for organometallic compounds, particularly impacting standard grades. The packaging and automotive sectors exhibit lower price sensitivity due to stringent performance requirements, unlike commodity polyolefin producers who prioritize cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized suppliers for critical raw materials, including specific organometallic compounds sourced primarily from China and Germany. The supply chain draws from key production hubs in China, Germany, and the United States, with raw material dependencies on titanium tetrachloride and aluminum alkyls. Commodity price volatility for these inputs represents a significant structural risk. Distribution runs through a mix of direct sales from integrated producers and specialized chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polymerization catalysts market acts as a stable compounder, driven by the packaging industry's continuous shift towards more recyclable and sustainable polymers. This fundamental demand underpins long-term growth.
For Market Incumbents:Acquire advanced R&D capabilities in bio-polymer synthesis or chemical recycling catalysts to counter the threat of disruptive sustainable material technologies. Incumbents should also enhance global manufacturing capacity, particularly in Asian chemical hubs, to meet regional demand for advanced polyolefins. Investing in regulatory compliance expertise across diverse jurisdictions like the EU's REACH framework strengthens market position.
For New Entrants and Emerging Players:Enter via niche applications requiring highly specialized catalysts, focusing on high-performance bioplastics or advanced composites for electronics. The most penetrable segment lies within catalysts for bio-derived monomers, driven by emerging sustainability mandates. A strong go-to-market angle involves collaborating directly with brand owners and converters in the European FMCG packaging supply chain.
For Investors and Strategic Acquirers:Valuations sit cheapest among asset-light catalyst technology licensors with strong intellectual property portfolios but limited manufacturing footprints. The long-term viability of the market rests on the successful commercialization of catalysts for circular economy applications. Acquisition targets should include specialized firms developing AI-driven catalyst discovery platforms. The signal to watch is the adoption rate of chemically recycled polymers by major brand owners.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increase production in China to meet growing demand for commodity polyolefins. |
| Green Manufacturing Transition | Implement sustainable production processes to align with EU Green Deal objectives. |
| Joint Venture | Form strategic partnerships for developing novel chemical recycling catalysts to address plastic waste. |
| Technology Licensing | License metallocene catalyst technology to expand into specialty polyethylene grades. |
| R&D Investment | Focus research on catalysts for bio-derived monomers to support bioplastics growth. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region, combining extensive interviews and secondary validation. Stakeholders included R&D directors, plant managers, and procurement leads at polymer manufacturers. Secondary data sources comprised customs data, chemical industry reports, and corporate filings. This bottom-up approach was triangulated with top-down market sizing.
Market sizing was modeled at the product type, application, end-user, and catalyst form level, including regional production hubs. Compound annual growth rates were derived through regression analysis of historical trends and projected future demand. Key forecast inputs included polymer production volumes and regulatory shifts like the EU Green Deal mandates across the analysis window.
Inputs from major chemical producers and regulatory bodies were available through the study window; gaps in real-time supply chain data introduce uncertainty bands. Forecasts reflect assumptions regarding technological advancements in sustainable polymers. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Copper Bismuth Catalyst Market
Catalysts
Europe PGM Catalyst Market
Catalysts
Emission Control Catalyst for Marine Market
Catalysts
Oxalate Hydrogenation Catalyst Market
Catalysts
Aluminum-Nickel Catalyst Market
Catalysts
Europe Homogeneous Precious Metal Catalyst Market
Catalysts
Chemical Processing Catalysts Market
Catalysts
Middle-East and Africa Refining Catalysts Market
Catalysts
Heterogeneous Catalyst Market
Catalysts
Marine Selective Catalytic Reduction Systems Market
Catalysts
Polymer Catalyst Market
Catalysts
Petrochemical Catalyst Market
Catalysts
BDO Synthesis Catalyst Market
Catalysts
Fluid Catalytic Cracking Catalyst Market
Catalysts
Global VOC Catalysts Market
Catalysts
Photocatalyst Market