
 Refinery Catalyst Market | 2026-2036
Refinery Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Refinery Catalyst Market Analysis
Dual-function metal-zeolite composite architectures are reshaping how hydrocracking catalysts achieve simultaneous acidity and hydrogenation balance. Albemarle Corporation leverages integrated bauxite-to-catalyst supply chains to sustain cost positions in FCC zeolite production. Haldor Topsoe A/S anchors its portfolio in sulfur-resistant metal sulfide formulations for hydrotreating applications. Johnson Matthey specializes in structured reforming catalysts that dominate platinum-rhenium regeneration cycles.
Refinery catalysts comprise engineered porous solids, typically aluminosilicate zeolites or supported transition metal sulfides, manufactured via ion exchange, impregnation, and calcination to accelerate petroleum cracking, reforming, and hydrotreating reactions at 300-500°C and 10-200 bar. Zeolite-based catalysts lead fluid catalytic cracking due to well-defined pore structures that resist coke deactivation, while metal-based catalysts capture expanding margin pools in hydrocracking as refiners process heavier, higher-sulfur feedstocks. Fixed bed technology remains the installed base standard, though fluidized bed configurations are gaining share in continuous regeneration reforming units where catalyst circulation optimizes octane barrel economics.
EPA sulfur regulations under the Clean Air Act and the EU F-Gas Regulation constrain refinery emissions profiles, directly mandating lower-sulfur gasoline and diesel that require more active hydrotreating catalyst loadings. China's MEE enforces national VI fuel standards that push domestic refiners toward imported high-activity catalyst systems. Stakeholders must monitor how carbon border adjustments and renewable fuel blending mandates redefine catalyst specifications for co-processing biofeedstocks in existing hydrocracker circuits.
Market Dynamics
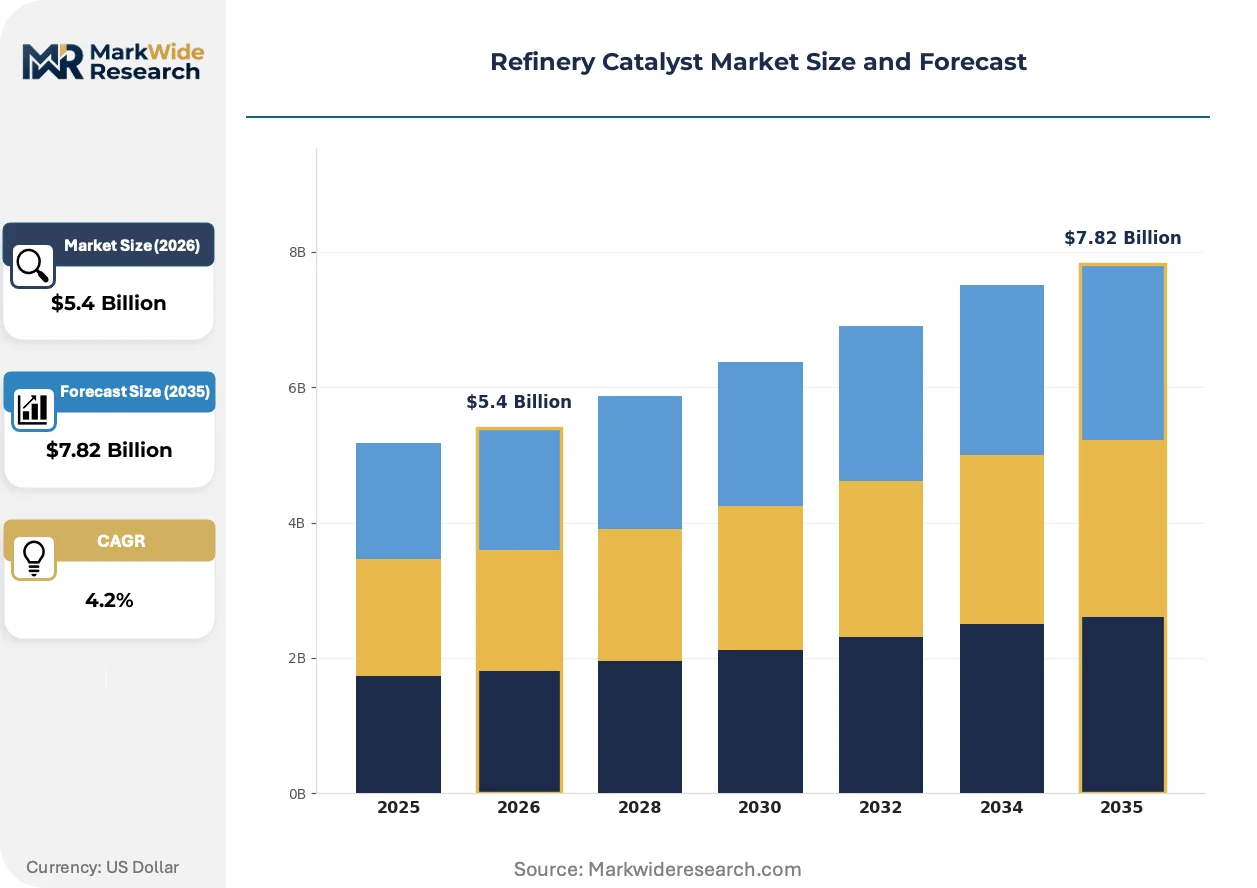
Refinery catalyst demand pivots on the tension between heavier crude processing requirements and tightening sulfur specifications, with EPA Tier 3 and EU F-Gas mandates forcing simultaneous upgrades to hydrotreating and cracking catalyst loadings across complex refining circuits.
Growth Catalysts
- EPA Tier 3 Sulfur Standards:US refiners must achieve 10 ppm gasoline sulfur limits, mandating higher-activity hydrotreating catalyst replacements in naphtha units.
- China's National VI Fuel Standards:MEE enforcement pushes domestic refiners toward imported high-activity catalyst systems for diesel hydrotreating.
- Heavy Crude Upgrading:Resid hydrocracking and coking units on the US Gulf Coast require specialized metal-sulfide catalyst formulations to handle higher metals and asphaltene content.
Market Restraints
- Rare Earth Supply Concentration:Lanthanum and cerium for FCC zeolite stabilization concentrates in Chinese processing facilities, creating input cost volatility.
- Platinum Group Metal Prices:Reforming catalyst regeneration economics fluctuate with palladium and rhenium spot markets, compressing margin predictability.
- EU F-Gas Phase-Down:Fluorinated gas restrictions constrain certain zeolite activation processes, adding compliance friction to catalyst manufacturing.
Strategic Opportunities
- Biofeedstock Co-Processing:Renewable diesel mandates in California and the EU enable catalyst retrofits for hydrotreating vegetable oils and waste fats in existing units.
- India's BS-VI Expansion:Refinery capacity additions targeting 450 million tonnes by 2030 create demand for fresh catalyst loading in new hydrocracking trains.
- Continuous Catalyst Regeneration:CCR reforming technology diffusion in Middle Eastern and Asian refineries opens service contracts for platinum-rhenium catalyst management.
Industry Challenges
- Specialized Catalyst Engineering Talent:Shortage of professionals skilled in zeolite synthesis and metal sulfide impregnation constrains R&D throughput at catalyst manufacturers.
- Extended Catalyst Qualification Cycles:Refiner pilot-plant testing protocols for new formulations demand 12-18 month validation timelines before commercial adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refinery Catalyst Market |
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $7.82 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zeolites, Metal-based Catalysts, Supported Catalysts, Heterogeneous Catalysts Application: Hydrocracking, Fluid Catalytic Cracking, Reforming, Alkylation End User: Oil Refineries, Petrochemical Plants, Chemical Manufacturers, Energy Companies Technology: Fixed Bed, Fluidized Bed, Moving Bed, Batch Processing |
| Companies Covered | Albemarle Corporation, W. R. Grace & Co., BASF SE, Haldor Topsoe A/S, Honeywell UOP, Clariant, Axens, Johnson Matthey, Shell Catalyst & Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refinery Catalyst Market Emerging Trajectories
Digital process control and molecular engineering are converging to reshape how catalyst performance is optimized, with real-time kinetic modeling and advanced characterization tools compressing development cycles and enabling predictive regeneration scheduling.
Metal-zeolite composite architectures for hydrocracking are digitizing how refiners balance acidity and hydrogenation functions in a single particle. Integrated bauxite-to-catalyst supply chains now embed sensor networks at calcination and ion-exchange stages. Major hydrocracking operators in the US Gulf Coast and Rotterdam clusters are digitizing catalyst lifecycle management through digital twin integration.
REACH authorization requirements and the EU F-Gas Regulation are tightening disclosure and substitution obligations for catalyst precursors containing fluorinated compounds. ECHA's SVHC candidate list now captures certain zeolite binder chemistries. European catalyst formulators are reformulating with alternative activation routes to maintain market access.
Refiner procurement of catalyst systems is fragmenting from long-term sole-source contracts toward multi-vendor qualification pools with performance-guarantee clauses. Integrated oil companies now run competitive catalyst trials across FCC and hydrotreating units simultaneously. This pattern is most pronounced in US independent refining and Middle Eastern national oil company complexes seeking supply security.
Refinery Catalyst Market Segmentation
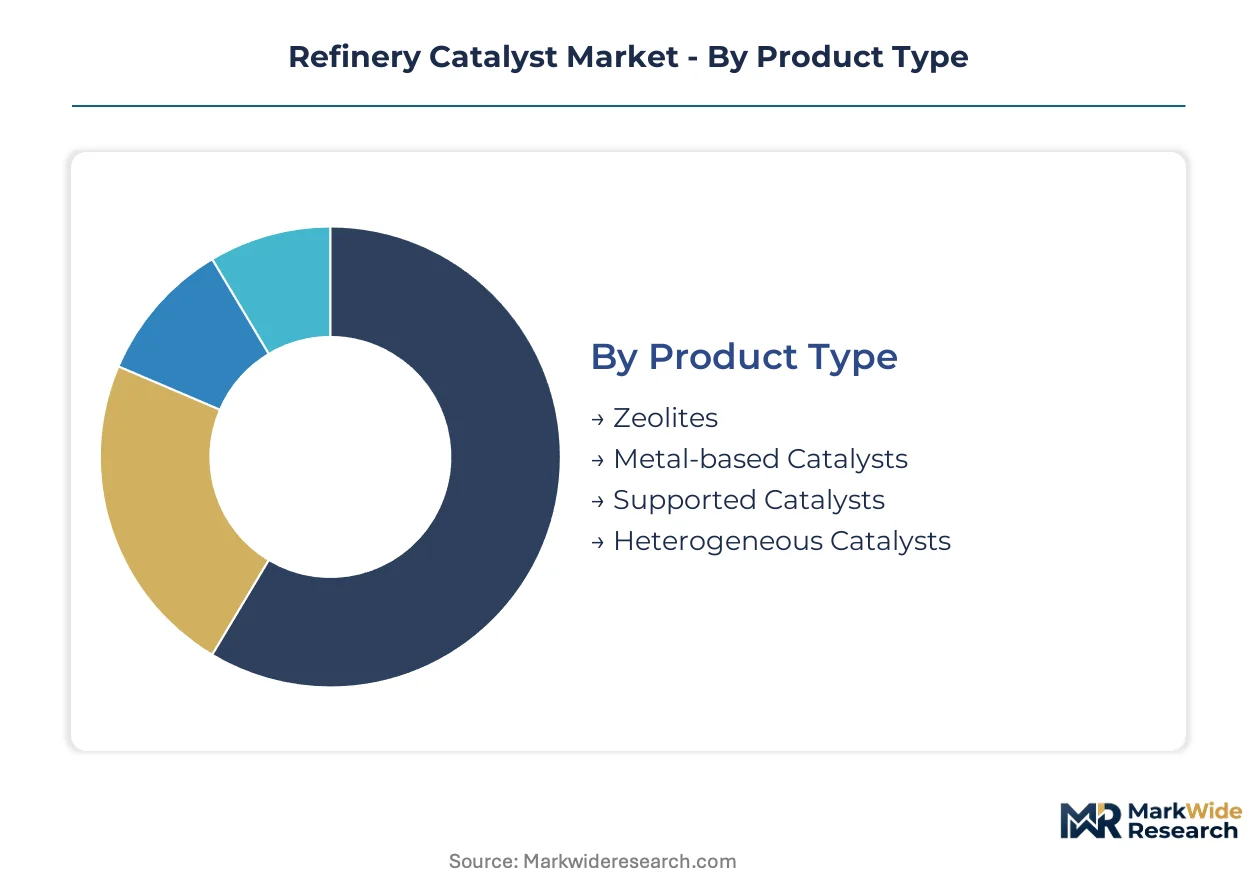
Catalyst selection in refining circuits hinges on feedstock quality, unit configuration, and regulatory sulfur limits. Each segmentation dimension carries distinct procurement criteria and technical qualification protocols that shape supplier relationships and lifecycle economics.
Product Type:
Cost tier differentiation separates commodity zeolite platforms from specialized metal formulations commanding premium loadings.
- Zeolites:Aluminosilicate frameworks with controlled pore architectures dominate fluid catalytic cracking. US Gulf Coast refiners favor Y-type zeolites stabilized with rare earth elements for heavy resid processing.
- Metal-based Catalysts:Supported nickel-molybdenum and cobalt-molybdenum sulfides enable hydrocracking and hydrotreating. Demand concentrates in Rotterdam and Singapore refining hubs where vacuum gas oil upgrading requires sulfur-resistant active phases.
- Supported Catalysts:Alumina or silica carriers impregnated with active metals for fixed-bed hydrotreaters.
- Heterogeneous Catalysts:Solid-phase systems enabling separation from liquid products in slurry-phase resid upgrading.
Zeolites hold installed capacity. Metal-based catalysts are rotating up the share rankings.
Application:
Application scope determines catalyst replacement frequency and regeneration economics across refining trains.
- Hydrocracking:Dual-function catalysts combining acidic zeolite cracking with metal sulfide hydrogenation handle heavy feedstocks. Complexes on the US Gulf Coast and in the Netherlands deploy these for maximum distillate yields from vacuum gas oil.
- Fluid Catalytic Cracking:Zeolite-based systems in riser-reactor configurations convert heavy gas oil to gasoline and light olefins. Chinese refiners under MEE National VI standards drive demand for high-activity rare-earth-stabilized formulations.
- Reforming:Platinum-rhenium on chlorided alumina boosts octane in naphtha processing.
- Alkylation:Solid acid catalysts replace liquid acid systems in isobutane-olefin coupling.
Fluid catalytic cracking holds installed capacity. Hydrocracking is rotating up the share rankings.
End User:
Customer type governs procurement scale, technical service requirements, and contract duration.
- Oil Refineries:Integrated operators and independents purchase catalyst loadings for FCC, hydrocracking, and hydrotreating units. US independent refiners on the Gulf Coast run multi-vendor trials to secure supply security and performance guarantees.
- Petrochemical Plants:Steam cracker feedstock pretreatment and aromatics production require specialized catalyst systems. Facilities in South Korea and Saudi Arabia import high-activity hydrotreating catalysts for naphtha purification.
- Chemical Manufacturers:Process catalysts for intermediates and specialty chemicals.
- Energy Companies:Integrated oil majors with downstream assets manage catalyst procurement centrally.
Oil refineries hold installed capacity. Petrochemical plants are rotating up the share rankings.
Technology:
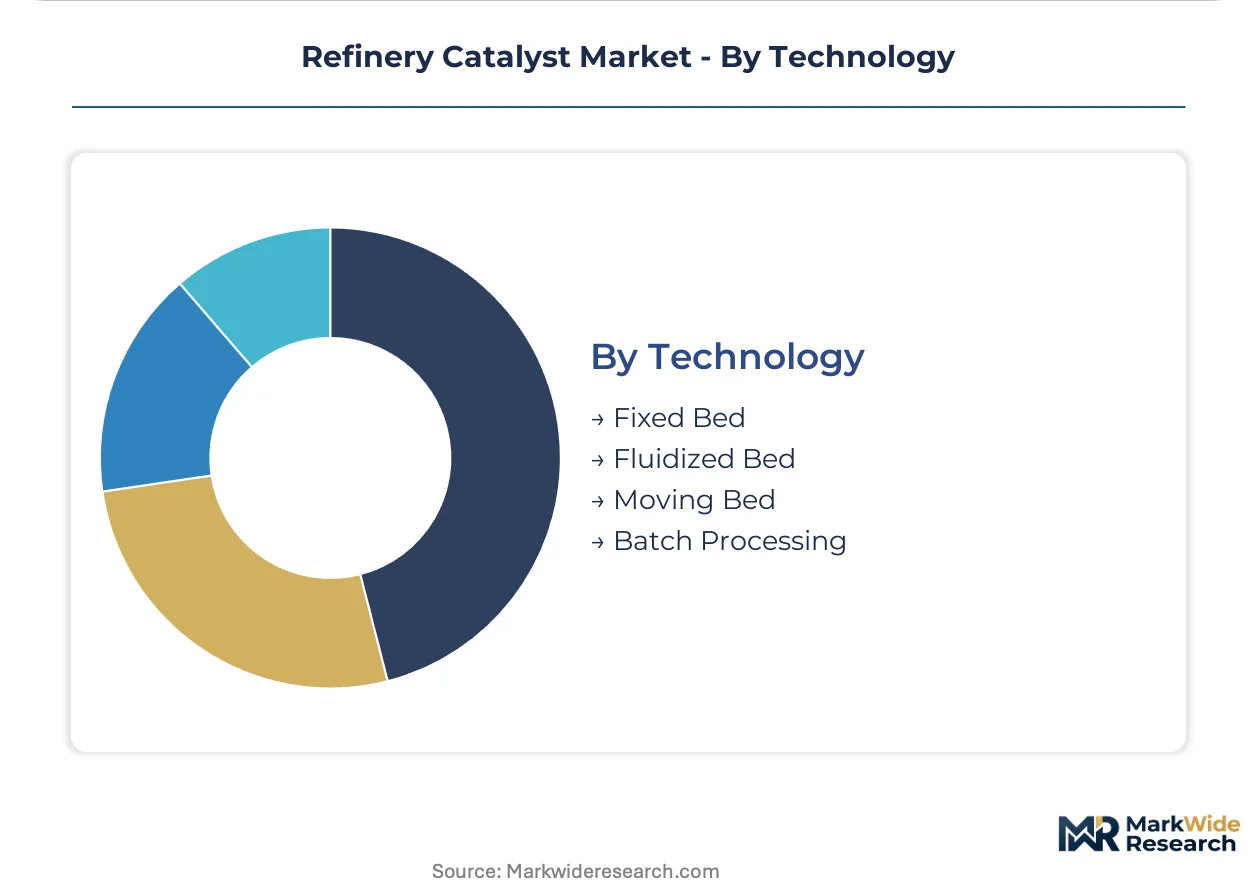
Reactor configuration dictates catalyst particle design, attrition resistance, and regeneration protocols.
- Fixed Bed:Pellet or extrudate catalysts in tubular reactors dominate hydrotreating and hydrocracking. This technology anchors the installed base in US and European refineries where reactor retrofits carry high capital costs.
- Fluidized Bed:Microspherical catalysts circulate between reactor and regenerator in FCC units. Continuous regeneration preserves activity and enables heavier feedstock processing in complex refineries.
- Moving Bed:Catalyst slowly descends through the reactor with continuous withdrawal and replacement.
- Batch Processing:Discrete catalyst charges for specialty chemical and pilot-scale operations.
Fixed bed holds installed capacity. Fluidized bed is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German catalyst formulators export high-activity hydrotreating systems to Rotterdam and Singapore refining hubs, while Chinese rare earth processors supply stabilized zeolite precursors to FCC operators on the US Gulf Coast.
United States
EPA Tier 3 sulfur mandates and heavy crude upgrading requirements drive catalyst replacements across complex refining circuits. The Clean Air Act enforcement compels 10 ppm gasoline sulfur compliance through higher-activity hydrotreating loadings. Texas and Louisiana Gulf Coast clusters deploy specialized metal-sulfide formulations for resid hydrocracking units processing high-metals feedstock.
China
MEE National VI fuel standards push domestic refiners toward imported high-activity catalyst systems for diesel hydrotreating. The dual carbon goals framework tightens emissions controls on refining operations. Shandong and Jiangsu province refining corridors concentrate demand for rare-earth-stabilized FCC zeolites in resid processing applications.
Germany
REACH authorization requirements and EU F-Gas Regulation constraints force reformulation of zeolite activation processes in catalyst manufacturing. The EU Green Deal accelerates disclosure obligations for fluorinated compound precursors. BASF SE and Clariant anchor production in Ludwigshafen and Munich regions, serving Rotterdam and Antwerp refining demand.
India
BS-VI expansion and refinery capacity additions targeting 450 million tonnes by 2030 create demand for fresh catalyst loading in new hydrocracking trains. The PLI scheme for petrochemicals indirectly supports catalyst procurement scale. Gujarat and Maharashtra coastal refining zones import high-activity systems for vacuum gas oil upgrading units.
Saudi Arabia
Carbon intensity reduction commitments and domestic crude valorization strategies expand hydrocracking and hydrotreating capacity. SFDA chemical registration requirements align with EU REACH disclosure standards for catalyst imports. Jubail and Yanbu industrial cities concentrate CCR reforming technology deployments with platinum-rhenium catalyst management contracts.
Refinery Catalyst Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered procurement pools. The vendor base clusters around integrated chemical conglomerates with captive raw material positions and independent catalyst engineering houses with formulation agility. Three archetypes dominate: rare earth-integrated zeolite producers, metal sulfide formulation specialists, and platinum group metal regeneration service providers. Capacity expansion in Middle Eastern catalyst loading facilities and technology licensing for continuous regeneration systems represent the dominant competitive moves.
Among US-based chemical conglomerates, Albemarle Corporation and W. R. Grace & Co. occupy positions anchored in bauxite-to-catalyst supply chain control. German diversified chemical groups BASF SE and Clariant exemplify the REACH-compliant formulation archetype with alternative activation route capabilities. Danish catalyst engineering specialist Haldor Topsoe A/S represents the sulfur-resistant metal sulfide tier serving hydrocracking and hydrotreating applications.
| Leading Market Players |
|---|
| Albemarle Corporation |
| W. R. Grace & Co. |
| BASF SE |
| Haldor Topsoe A/S |
| Honeywell UOP |
| Clariant |
| Axens |
| Johnson Matthey |
| Shell Catalyst & Technologies |
| Others |
Supply Flow & Price Mechanics
Rare earth processing concentration in Chinese facilities for lanthanum and cerium stabilization directly determines margin capture at FCC zeolite formulators serving US Gulf Coast refiners. This upstream bottleneck forces catalyst manufacturers to absorb input volatility or pass through costs to refiners already squeezed by heavy crude upgrading investments.
Pricing Analysis
Current-generation rare-earth-stabilized Y-zeolites command substantial premiums over prior-generation unstabilized formulations, while next-generation metal-zeolite composites for hydrocracking sit in pre-commercial qualification. Three-tier pricing structure separates premium platinum-rhenium reforming catalysts with full regeneration service contracts from standard nickel-molybdenum hydrotreating grades and economy alumina-supported base metal formulations. Cost compression in standard hydrotreating tiers is intensifying because Chinese refiners under MEE National VI standards are importing high-activity systems at volume scale, eroding Western supplier pricing power. Independent US Gulf Coast refiners exhibit highest price sensitivity through competitive multi-vendor trials, while Middle Eastern national oil companies accept premium pricing for integrated catalyst management contracts.
Supply Chain Analysis
Contract manufacturing for FCC zeolite synthesis concentrates at Albemarle Corporation and W. R. Grace & Co. facilities in the United States, with metal sulfide impregnation capacity clustering at Haldor Topsoe A/S in Denmark and BASF SE in Germany. Raw material dependencies center on Australian bauxite for alumina carriers, Chinese rare earth oxides for zeolite stabilization, and South African platinum group metals for reforming catalysts. Single-source vulnerability from Chinese rare earth concentration creates supply disruption exposure if export controls tighten. Distribution runs through refinery technical service teams that manage catalyst loading, regeneration, and replacement scheduling on long-term performance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refinery catalyst procurement is shifting from transactional spot purchases toward integrated service contracts where catalyst performance guarantees, regeneration management, and technical advisory generate recurring revenue expanding faster than base chemical sales. This service-attach transformation rewards suppliers who embed lifecycle optimization capabilities alongside physical product delivery.
For Market Incumbents: Harden supply security through backward integration into rare earth oxide processing or binding offtake agreements with Chinese separation facilities. Defend margin position by expanding continuous catalyst regeneration service footprints in Middle Eastern and Asian refineries where CCR technology diffusion outpaces local technical service capacity. Regulatory pressure from EU F-Gas and REACH authorization requirements favors incumbents with established alternative activation route capabilities.
For New Entrants and Emerging Players: Pursue white-space opportunities in biofeedstock co-processing catalyst retrofits for California and EU renewable diesel mandates, where incumbent formulations underperform with vegetable oil and waste fat feedstocks. India's BS-VI refinery expansion presents the most penetrable geography given 450 million tonne capacity additions requiring fresh hydrocracking catalyst loading without entrenched supplier relationships. Go-to-market positioning should emphasize rapid pilot-plant qualification protocols that compress standard 12-18 month validation timelines.
For Investors and Strategic Acquirers: Capital is best deployed toward metal sulfide formulation specialists with proven sulfur-resistant catalyst platforms for resid hydrocracking, as heavy crude processing requirements strengthen across the analysis window. Long-term viability hinges on capabilities in dual-function metal-zeolite architectures that balance acidity and hydrogenation. Watch for inflection signals in carbon border adjustment implementation timelines that would accelerate biofeedstock co-processing catalyst demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Oxides | Captive lanthanum and cerium supply secures FCC zeolite cost positions against Chinese export volatility. |
| Continuous Catalyst Regeneration Service Expansion | CCR technology diffusion in Saudi Arabian and Indian refineries opens multi-year platinum-rhenium management contracts. |
| Biofeedstock Co-Processing Catalyst Development | California LCFS and EU RED III mandates create retrofit demand for vegetable oil hydrotreating formulations. |
| Alternative Activation Route Investment | EU F-Gas phase-down compliance maintains market access for REACH-authorized catalyst formulators. |
| Multi-Vendor Qualification Pool Positioning | US independent refiner procurement fragmentation rewards suppliers with performance-guarantee contract structures. |
Methodological Framework
A spread of perspectives from refinery operations managers, catalyst procurement leads at integrated oil companies, technical R&D directors at formulation houses, and aftermarket service heads converged on the working assumptions underlying this analysis. Primary field engagement with hydrocracking unit engineers and FCC operations specialists was cross-referenced against secondary validation from EPA enforcement databases, ECHA REACH registration filings, MEE National VI compliance disclosures, and customs trade data on rare earth oxide imports. Bottom-up catalyst loading estimates by unit type and refinery configuration were reconciled with top-down market size triangulation.
Demand-supply balance modeling across the analysis window incorporated capacity utilization rates at major refining corridors, regulatory mandate implementation schedules, and crude slate quality trends. Segmentation dimensions included catalyst product type, application unit, end-user category, and reactor technology configuration. CAGRs were derived from regression analysis of historical replacement cycles projected against regulatory-driven upgrade intensities. Industry-specific forecast inputs captured MEE National VI diesel sulfur limits and EPA Tier 3 gasoline specifications as demand pull factors.
Macroeconomic conditions sit as an overlay; deviation in crude oil price trajectories, refinery margin cycles, or carbon policy stringency would shift the trajectory of catalyst replacement timing and premium formulation adoption. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and technology qualification timelines. Quarterly review of refinery utilization rates, rare earth oxide export license data, and pilot-plant trial announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Hydrogenation Catalyst Market
Catalysts
Hydrotreating Catalyst Market
Catalysts
Solid Acid Catalysts Market
Catalysts
Primary Reforming Catalyst Market
Catalysts
Europe Homogeneous Precious Metal Catalyst Market
Catalysts
Platinum-Based Catalysts Market
Catalysts
Global Zeolites Market
Catalysts
Global Phase Transfer Catalyst Market
Catalysts
Polyurethane Catalysts Market
Catalysts
Inorganic Catalyst Market
Catalysts
Marine Selective Catalytic Reduction Systems Market
Catalysts
Petrochemical Catalyst Market
Catalysts
Catalyst Regeneration Market
Catalysts
Catalyst Carrier Market
Catalysts
Polymer Catalyst Market
Catalysts
Global VOC Catalysts Market