
 Fire Rated Duct Market | 2026-2036
Fire Rated Duct Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Rated Duct Market Analysis
Multi-source procurement among mechanical contractors is repositioning how fire-rated duct specifications reach project sites. Roxtec leverages its cable and pipe sealing expertise to extend into integrated fire containment systems for duct penetrations. Kingspan anchors its position through insulated panel technology that intersects with fire-rated building envelopes. Lindab competes with precision-manufactured galvanized steel ductwork engineered to European fire resistance classifications.
Fire rated ducts are passive fire protection components fabricated from steel, aluminum, fiberglass, or composite materials, designed to maintain structural integrity and prevent flame propagation through HVAC networks for specified durations measured in hours. Rigid ducts fabricated from steel dominate commercial and institutional specifications due to their tested performance under ASTM E119 and EN 1366 fire exposure protocols. Flexible ducts are gaining specification share in retrofit and renovation installations where spatial constraints limit rigid routing options. Fiberglass and composite materials represent the fastest-growing material category as manufacturers reduce weight while preserving hourly fire ratings.
NFPA 90A in the United States, EN 1366 test standards administered by EU-notified bodies, and the EU Construction Products Regulation collectively mandate fire resistance testing, CE marking, and documented performance for ductwork in occupied structures. These frameworks create compliance barriers that favor established testing relationships and certified manufacturing facilities over unvalidated suppliers. Stakeholders must monitor evolving test protocols and regional amendment cycles to maintain specification relevance as jurisdictions tighten enforcement of passive fire protection mandates.
Market Dynamics
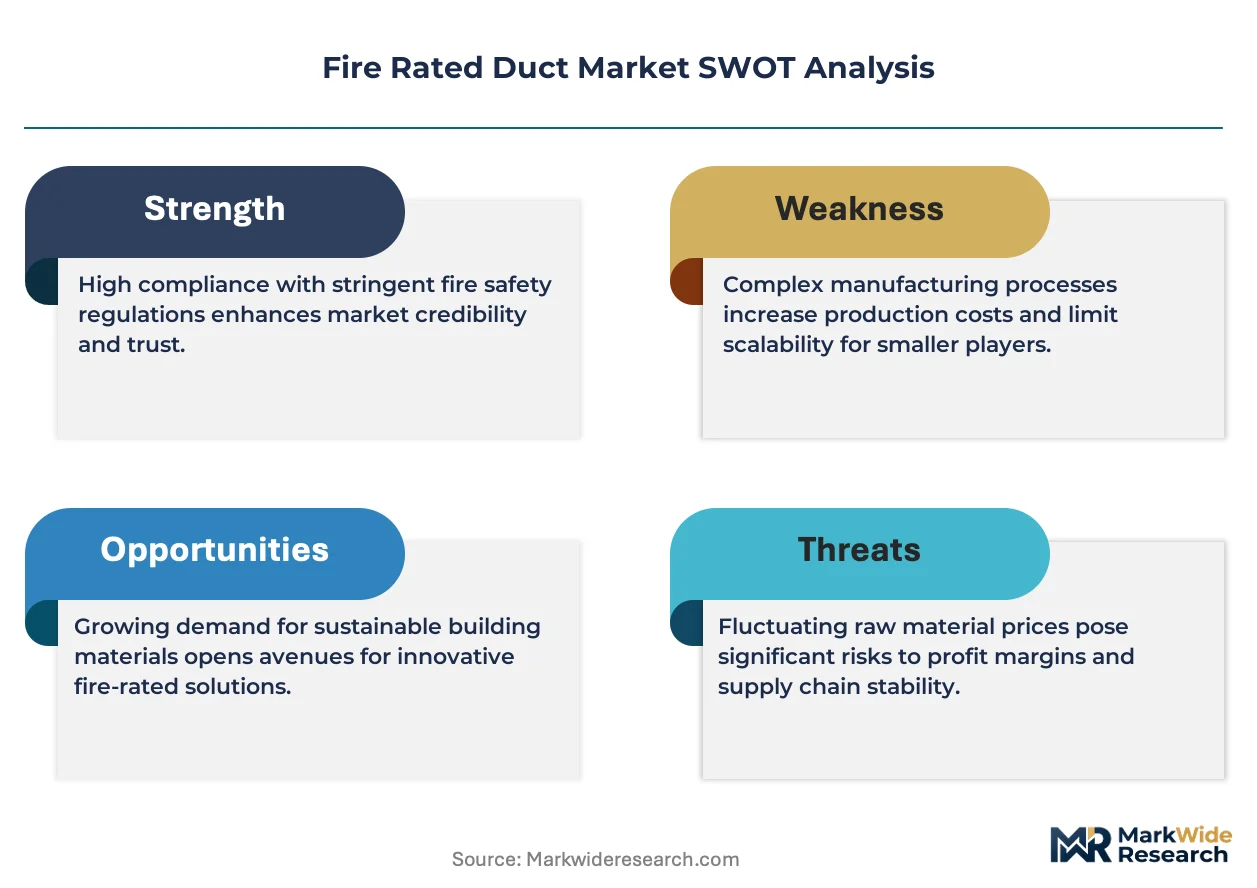
Building code harmonization across jurisdictions is compressing specification timelines while elevating certification requirements, forcing manufacturers to maintain multi-standard testing portfolios that strain smaller competitors.
Growth Catalysts
- EU Construction Products Regulation:Mandatory CE marking for fire-resistant ductwork in occupied structures creates specification pull across German, French, and Italian commercial construction pipelines.
- High-rise residential towers:Urban densification in China and the United States drives mechanical infrastructure procurement that must satisfy ASTM E119 and GB 50016 fire containment protocols.
- Fiberglass composite fabrication:Weight reduction in vertical shaft installations enables faster crane-time schedules and reduced structural load requirements in mixed-use developments.
Market Restraints
- Galvanized steel price volatility:Input cost swings tied to zinc and iron ore markets compress margin predictability for fabricated ductwork producers.
- Notified body capacity constraints:EU test laboratory backlogs for EN 1366 certification extend product launch timelines by six to twelve months.
- Intumescent coating substitution:Spray-applied fireproofing on structural steel competes for specification against encapsulated duct systems in budget-constrained projects.
Strategic Opportunities
- India commercial real estate:BIS fire safety standard enforcement in Mumbai and Bangalore high-rises opens specification windows for certified imported systems.
- Data center HVAC retrofit:Hyperscale facility operators in Northern Virginia and Frankfurt seek fire-rated containment for critical cooling infrastructure.
- Modular offsite fabrication:Prefabricated mechanical room packages bundle ductwork with controls, compressing field installation labor and inspection cycles.
Industry Challenges
- Multi-standard engineering talent:Technical staff must simultaneously navigate ASTM, EN, and GB test protocols without cross-certification recognition.
- Legacy building integration:Fire-rated duct routing through existing occupied structures demands asbestos abatement coordination and phased shutdown scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Rated Duct Market |
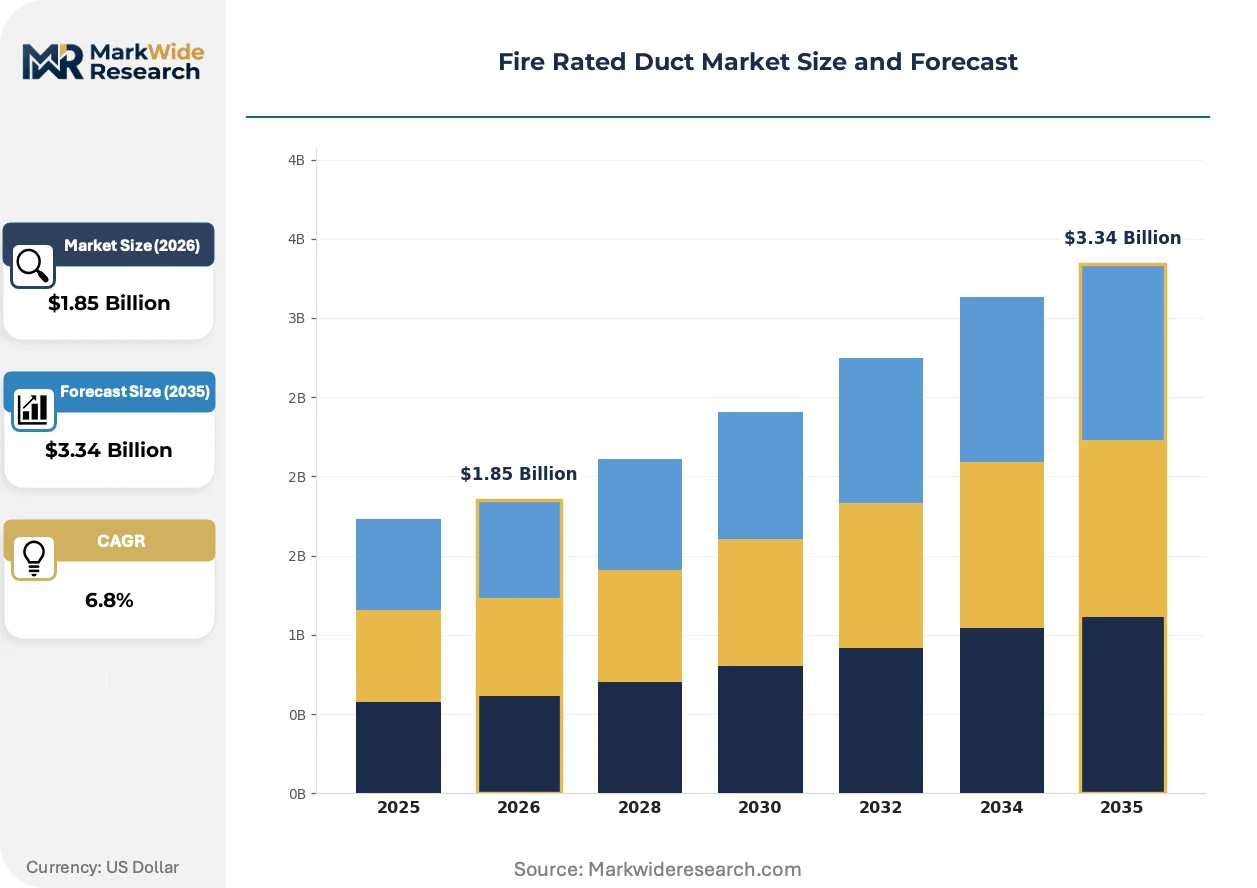
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Ducts, Rigid Ducts, Variable Air Volume Ducts, Fire/Smoke Dampers Material: Steel, Aluminum, Fiberglass, Composite Installation Type: New Construction, Retrofit, Renovation, Maintenance End User: Commercial Buildings, Residential Structures, Industrial Facilities, Institutional Establishments |
| Companies Covered | Roxtec, Kingspan, Lindab, Unifrax, DuraSystems, Firemac, FläktGroup, THERMAFLEX, Trox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Rated Duct Market Emerging Trajectories
Material science advances and regulatory precision are converging to redefine performance benchmarks, with manufacturers racing to certify lighter systems that satisfy stricter hourly ratings without escalating installation complexity.
Composite intumescent layering is unifying thermal insulation and fire containment in single-panel duct construction. Hospital and laboratory specifiers in Switzerland and Singapore are fast-tracking these systems for cleanroom applications. The technology is unifying previously separate supply chains for insulation and sheet metal fabrication.
REACH chemical restrictions on halogenated flame retardants are forcing reformulation of duct liner adhesives and coatings across EU manufacturing facilities. Compounders in Germany and the Netherlands are pivoting toward phosphorus-based alternatives that maintain EN 13501-1 classification. HVAC contractors in Nordic markets report extended material qualification periods as they validate new chemistries.
Mechanical contractors are consolidating vendor relationships to reduce specification risk on complex projects. Single-source accountability for ductwork, dampers, and penetration seals is displacing fragmented procurement across separate trades. This concentration is most visible in United States healthcare construction, where Joint Commission accreditation audits reward documented system integration.
Fire Rated Duct Market Segmentation
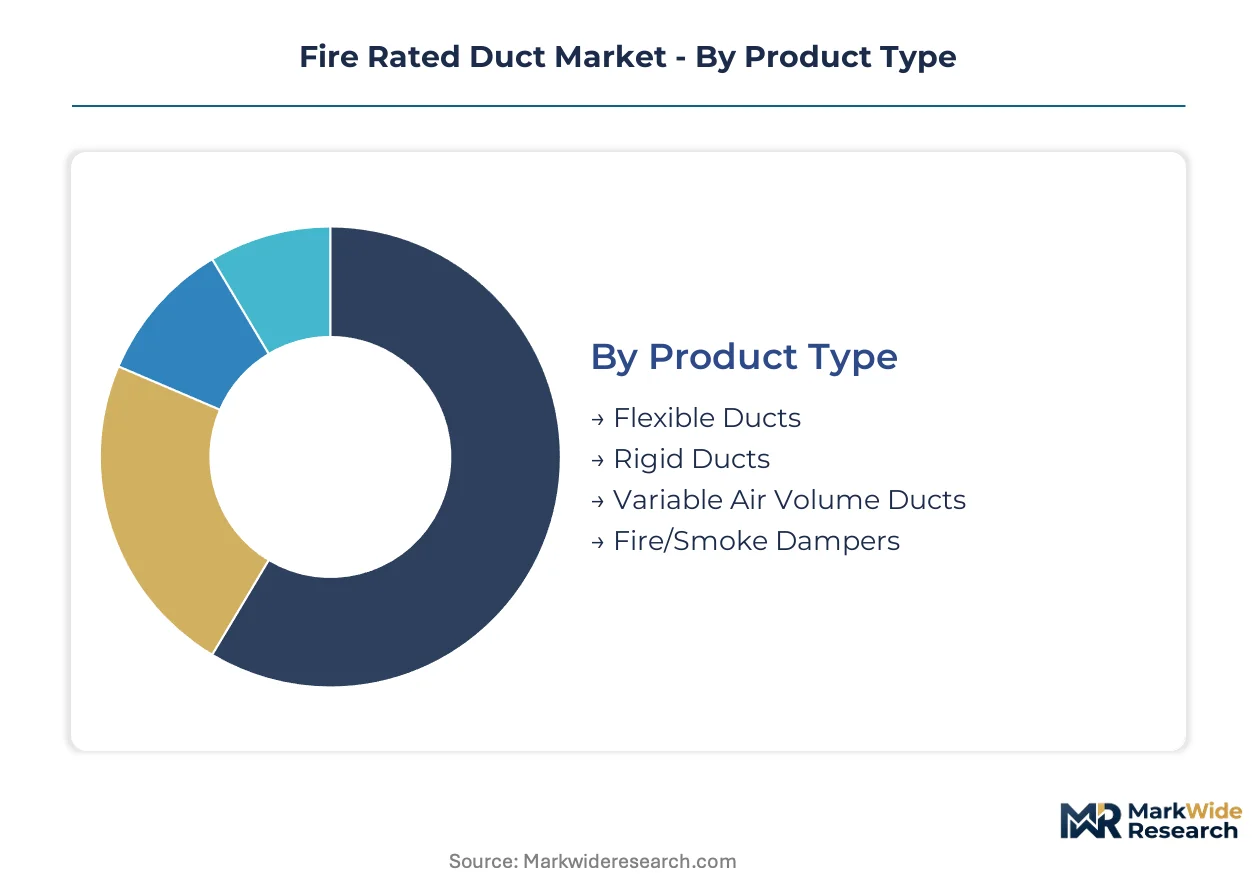
Segmentation in fire rated duct markets reveals how specification requirements diverge across building lifecycle stages, material performance tiers, and occupancy risk profiles. Procurement patterns shift measurably between new high-rise construction and legacy facility retrofit, with each segment demanding distinct certification documentation and installation protocols.
Product Type:
Upgrade and replacement cycles vary dramatically across duct product categories, with rigid systems dominating 20-30 year infrastructure horizons while flexible formats capture shorter-cycle renovation work.
- Rigid Ducts:Fabricated from galvanized steel or aluminum with welded seam construction, these systems maintain dimensional stability under ASTM E119 and EN 1366 fire exposure for 1-4 hour ratings. Demand concentrates in German commercial towers and United States healthcare facilities where code officials mandate documented structural integrity across multi-story HVAC risers. Replacement cycles align with major building envelope renovations at 25-30 year intervals.
- Flexible Ducts:Spiral-wound metal or fabric-reinforced construction permits routing through constrained plenum spaces where rigid fabrication proves impractical. Retrofit contractors in United Kingdom and Australian markets specify these for phased occupancy upgrades requiring minimal structural penetration. Faster degradation drives 10-15 year replacement horizons versus rigid alternatives.
- Variable Air Volume Ducts:Integrated damper and sensor assemblies modulate airflow while maintaining fire compartment boundaries.
- Fire/Smoke Dampers:Spring-loaded or motorized closure devices activate at specified temperatures to isolate duct penetrations through rated assemblies.
Rigid Ducts sits at the top of the volume ranking, with Flexible Ducts climbing the fastest.
Material:
Cost tier positioning separates commodity metal fabrication from advanced composite systems, with price premiums of 40-60% separating base steel from engineered fiberglass alternatives.
- Steel:Galvanized and stainless steel variants dominate commercial specifications due to established test protocols and familiar fabrication methods. German and United States mechanical contractors default to steel for projects requiring EN 1366-1 or UL 555S certification without material deviation reviews.
- Fiberglass:Reinforced polymer matrix construction reduces installed weight by 50-70% versus steel equivalents, enabling faster crane schedules in Chinese and Singaporean high-rise construction. REACH-compliant resin formulations from Netherlands compounders now satisfy EU flame spread classifications without halogenated additives.
- Aluminum:Lightweight corrosion-resistant fabrication suits coastal and chemical process environments where steel degradation accelerates.
- Composite:Multi-layer intumescent and insulating laminates unify thermal and fire performance in single-panel construction.
Steel commands the largest installed base, though Fiberglass gains share fastest in vertical shaft applications.
Installation Type:
Customer type segmentation separates owner-occupied institutional buyers with long-term maintenance planning from speculative developers prioritizing first-cost minimization.
- New Construction:Integrated design-build delivery permits ductwork prefabrication alongside structural steel, compressing field installation schedules. United States healthcare and data center developers specify factory-tested assemblies to satisfy Joint Commission and Uptime Institute audit protocols.
- Retrofit:Phased installation within occupied buildings demands asbestos abatement coordination and temporary HVAC bypass systems. United Kingdom school districts and French hospital networks allocate dedicated capital budgets for fire safety system end-of-life replacement.
- Renovation:Tenant improvement projects trigger localized duct replacement where occupancy changes invalidate original fire ratings.
- Maintenance:Inspection-driven component replacement addresses damper actuator failure and seal degradation.
New Construction generates the highest absolute volume, with Retrofit expanding most quickly as building stock ages across developed economies.
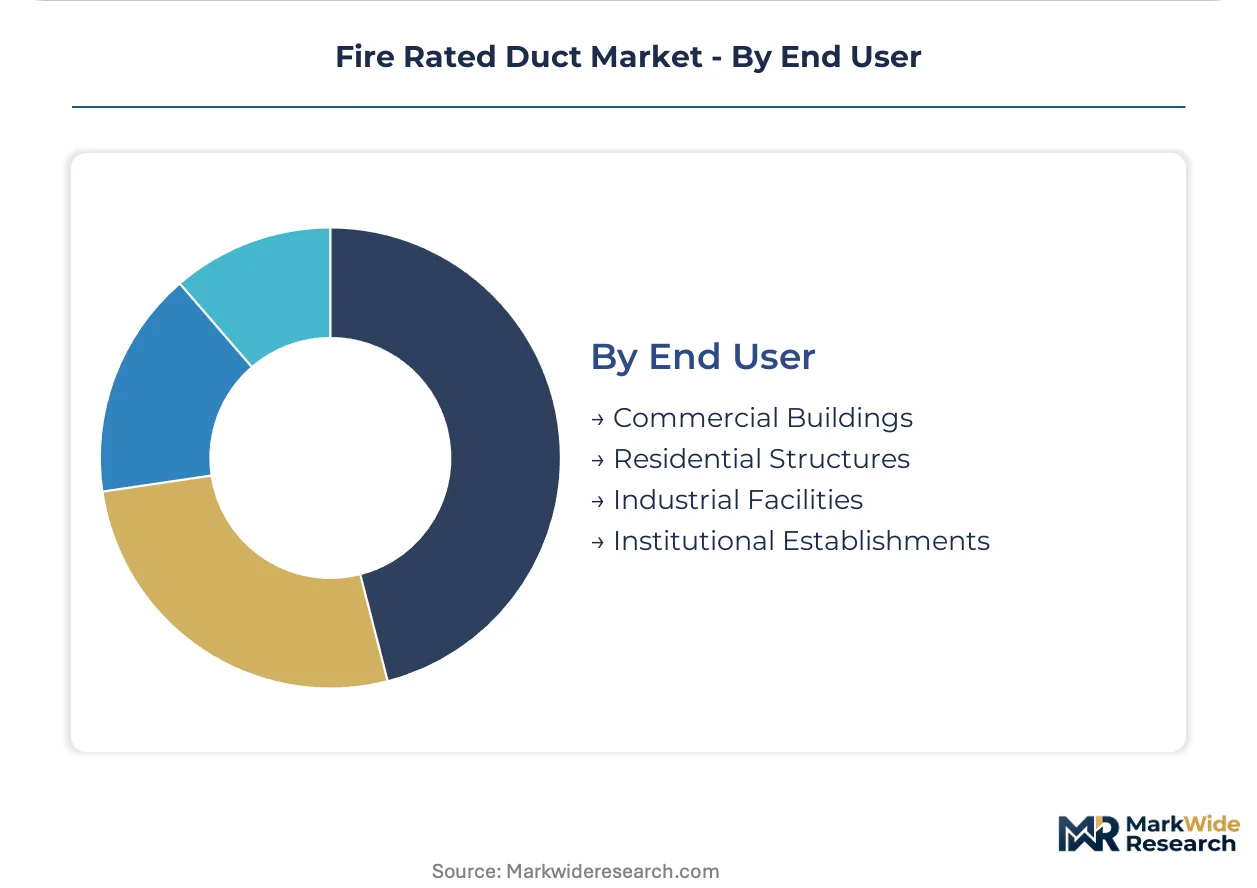
End User:
Application-specific performance requirements separate high-occupancy institutional specifications from lower-risk residential deployments, with code enforcement intensity varying by occupancy classification.
- Commercial Buildings:Office towers, retail complexes, and hospitality structures require tested duct systems for return air plenums and vertical shaft continuity. Mumbai and Bangalore commercial developers now procure BIS-certified systems as Maharashtra and Karnataka authorities tighten high-rise enforcement.
- Institutional Establishments:Hospitals, laboratories, and correctional facilities demand redundant containment with documented damper inspection protocols. Swiss and Singaporean cleanroom specifications now specify composite intumescent ductwork for simultaneous thermal and fire performance.
- Industrial Facilities:Manufacturing and process environments combine fire rating requirements with corrosion resistance and particulate containment.
- Residential Structures:Mid-rise and high-rise multifamily construction applies fire-rated ductwork to corridor ventilation and garbage chute exhaust systems.
Commercial Buildings leads by installed value, while Institutional Establishments shows the steepest specification upgrade trajectory as accreditation standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as producers relocate testing and fabrication to jurisdictions with shorter certification queues and lower compliance overhead. This migration pattern concentrates supply in established industrial clusters while opening specification windows in enforcement-heavy markets.
United States
Commercial tower construction in Manhattan and Chicago drives specification of ASTM E119-certified rigid duct systems for vertical HVAC risers. NFPA 90A enforcement by municipal fire marshals in these jurisdictions mandates documented hourly ratings for all occupied high-rises. Northern Virginia data center clusters now require fire-rated containment for critical cooling infrastructure, creating specialized procurement channels distinct from general commercial construction.
Germany
Notified body certification under EN 1366-1 governs ductwork specification across Frankfurt and Munich commercial developments. The EU Construction Products Regulation mandates CE marking for all fire-resistant mechanical systems in occupied structures. Industrial fabricators in the Ruhr region maintain multi-standard testing portfolios to serve both domestic and export markets, compressing lead times for certified product delivery.
China
Urban densification in Shanghai and Shenzhen accelerates procurement of GB 50016-compliant duct systems for residential towers exceeding 100 meters. Local fire safety authorities in these municipalities conduct unannounced inspections of mechanical shaft installations, elevating documentation requirements. Fiberglass composite fabrication in Jiangsu province supplies weight-reduced alternatives for crane-constrained vertical installations.
India
BIS fire safety standard enforcement in Mumbai and Bangalore high-rises opens specification windows for certified imported systems. Maharashtra state authorities now require third-party testing documentation for all fire-rated mechanical components in commercial structures above 15 stories. Domestic distributors in these cities are building inventory positions to capture retrofit demand from aging building stock.
Singapore
Cleanroom specifications in biomedical and semiconductor facilities specify composite intumescent ductwork for simultaneous thermal and fire performance. The national building regulator mandates EN 13501-1 classification for all mechanical containment in healthcare and research occupancies. Fabrication specialists in Jurong serve regional export markets from this enforcement-heavy hub.
Fire Rated Duct Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent sealing and insulation technologies to capture specification bundling opportunities. The vendor base organizes around three archetypes: integrated building envelope specialists, precision metal fabricators with certified testing relationships, and material science compounders advancing composite formulations. Competitive positioning hinges on multi-standard certification maintenance and pre-engineered modular system development. Consolidation pressure is mounting as mechanical contractors reduce vendor counts to streamline project accountability.
Among European-anchored fabricators, Lindab exemplifies the precision-manufactured metal duct archetype with its galvanized steel focus. Kingspan occupies a position at the intersection of insulated panel technology and fire-rated envelope systems. Roxtec represents the penetration-sealing specialist vector extending into integrated duct containment solutions. These three entities anchor distinct competitive positions without overlapping core fabrication competencies.
| Leading Market Players |
|---|
| Roxtec |
| Kingspan |
| Lindab |
| Unifrax |
| DuraSystems |
| Firemac |
| FläktGroup |
| THERMAFLEX |
| Trox |
| Others |
Supply Flow & Price Mechanics
Mechanical contractor consolidation in United States healthcare and data center construction concentrates procurement leverage among a shrinking pool of specification gatekeepers, compressing channel margins while elevating certification premiums for tested systems. This buyer concentration rewards manufacturers with documented EN 1366 and UL 555S relationships, penalizing uncertified competitors with price exclusion from major project pipelines.
Pricing Analysis
Distributor margins in European fire-rated duct channels absorb 15-25 point compression as mechanical contractors consolidate vendor relationships toward single-source accountability. Three-tier pricing structure across premium certified, standard tested, and economy non-rated levels separates Lindab precision-fabricated steel from regional metal shops lacking notified body documentation. Cost compression in standard-grade galvanized steel intensifies because zinc price volatility transfers directly to fabricator cost bases. Price-sensitive speculative developers in Indian commercial towers prioritize first-cost minimization, while institutional buyers in Swiss hospitals accept 40-60% premiums for composite intumescent systems.
Supply Chain Analysis
Galvanized steel coil supply rests on German and Chinese integrated mills with direct hot-dip capacity, while specialty fiberglass resin formulation draws from Netherlands and German compounders navigating REACH-compliant phosphorus-based chemistry transitions. Zinc ingot and iron ore feedstocks anchor input cost volatility, with European fabricators maintaining six-month inventory buffers against spot price swings. Single-source vulnerability concentrates in notified body testing capacity, where EN 1366-1 certification queues extend launch timelines. Distribution runs through regional mechanical wholesalers in Germany and United States, with direct OEM relationships gaining share in data center and healthcare verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fire rated duct market compounds steadily as regulatory harmonization across jurisdictions mandates certified passive fire protection in every new high-rise mechanical specification. Building code tightening provides durable demand visibility independent of cyclical construction volatility.
For Market Incumbents:Cement multi-standard certification maintenance across ASTM E119, EN 1366, and GB 50016 protocols to defend specification relevance as mechanical contractors reduce approved vendor lists. Backward integration into zinc-coated steel coil processing mitigates margin compression from raw material volatility. Prioritize modular offsite fabrication investments to capture healthcare and data center procurement shifting toward factory-tested mechanical room packages.
For New Entrants and Emerging Players:BIS fire safety standard enforcement in India opens a window for certified imported systems in Mumbai and Bangalore high-rise construction, where domestic testing infrastructure lags demand. Target fiberglass composite fabrication for Chinese vertical shaft installations, where weight reduction commands crane-time savings premiums. Pursue cleanroom specification in Singapore biomedical facilities as a go-to-market anchor, leveraging EN 13501-1 classification requirements to bypass established steel duct incumbents.
For Investors and Strategic Acquirers:Building envelope specialists with fire-rated insulation portfolios are the most active acquirer in this space, seeking ductwork capabilities to bundle mechanical containment with envelope systems. Long-term viability centers on regulatory compliance durability rather than technology disruption, favoring targets with deep notified body relationships over material science innovators. Watch EN 1366 test laboratory capacity expansion announcements as the signal indicating whether certification bottlenecks ease or intensify competitive moat durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Standard Certification Investment | EN 1366-1, ASTM E119, and GB 50016 testing relationships secure specification access across German, United States, and Chinese project pipelines. |
| Modular Offsite Fabrication | Prefabricated mechanical room packages compress field installation labor for United States healthcare Joint Commission compliance. |
| Composite Material Formulation | REACH-compliant phosphorus-based resin systems from Netherlands compounders satisfy EU flame spread without halogenated additives. |
| Regional Testing Laboratory Capacity | Notified body expansion in Ruhr region reduces EN 1366 certification queues that currently extend product launches. |
| Single-Source Accountability Bundling | Integrated ductwork, damper, and penetration seal procurement displaces fragmented trade relationships in United States construction. |
Methodological Framework
Bottom-up commercial building and institutional facility modeling reconciled against top-down steel and fiberglass fabrication capacity tracking forms the analytical core of this study. Primary interviews with mechanical contractors, fire protection engineers, notified body certification managers, and healthcare facility procurement directors combined with secondary validation from EU Construction Products Regulation filings, NFPA standard revision documentation, and BIS enforcement notices. Trade data from German and Chinese steel coil customs records, EN 1366 test laboratory throughput disclosures, and United States healthcare construction permit databases triangulated supply-side and demand-side estimates.
Input-output matrices mapped rigid duct, flexible duct, and composite system volumes against high-rise residential, commercial tower, and institutional end-use construction starts across the projection horizon. Segmentation dimensions included product type, material grade tier, installation mode, and regional regulatory cluster. CAGRs derived from regression analysis of historic specification penetration rates applied to forward construction forecasts, with fiberglass composite share gains modeled separately based on crane-time cost savings in vertical shaft applications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under notified body capacity constraints or abrupt zinc price spikes. Projections reflect assumptions regarding steady regulatory enforcement intensification without retroactive grandfathering relief. A small set of triggers warrants ongoing watch: EN 1366 test laboratory expansion announcements, REACH chemical restriction amendments affecting resin formulations, and BIS inspectorate staffing levels in Maharashtra state.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Fire-Retardant Treated Wood Market
Building & Construction Materials
Decorative Tiles Market
Building & Construction Materials
Global Iron and Steel Casting Market
Building & Construction Materials
Sawn Timber Market
Building & Construction Materials
Sliding Bearing Market
Building & Construction Materials
US and Canada Corner Beads and Caps Market
Building & Construction Materials
Global Aluminum Cladding Panels Market
Building & Construction Materials
Exterior Wall System Market
Building & Construction Materials
Global Concrete Repair Mortars Market
Building & Construction Materials
Global Cool Roofs Market
Building & Construction Materials
Plastic Roofing Tiles Market
Building & Construction Materials
US Glass Curtain Wall Market
Building & Construction Materials
Middle-East and Africa Industrial Flooring Market
Building & Construction Materials
APAC Commercial Glazing System Market
Building & Construction Materials
SBS Waterproofing Membrane Market
Building & Construction Materials
China Marble Market