
 Cleanroom Flooring Market | 2026-2036
Cleanroom Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Cleanroom Flooring Market Outlook
REACH compliance is pivoting the cost-of-entry calculus for resin suppliers serving European pharmaceutical cleanrooms. Nora Systems leverages captive polymer compounding to sustain margin control across vinyl sheet production. Forbo Flooring Systems anchors its position through specialized conductive formulations that navigate aerospace certification requirements.
Cleanroom flooring comprises resin-based or elastomeric surface systems engineered to limit particulate shedding, electrostatic discharge, and microbial colonization, typically specified with surface resistivity between 10^4 and 10^9 ohms. These installations create sealed, monolithic envelopes that protect sensitive processes in semiconductor lithography and aseptic drug filling. Epoxy systems lead in microelectronics applications where chemical resistance and seamless integration with wall cove bases prove critical, while vinyl sheet dominates hospital and research facility environments where removability and thermal welding of seams support infection control protocols. Modular installation formats are gaining traction in biotechnology facilities requiring rapid reconfiguration of classified spaces.
The FDA enforces Current Good Manufacturing Practice standards that mandate flooring integrity in aseptic processing suites, while ISO 14644-1 classification protocols directly specify surface cleanliness thresholds for particulate generation. EPA regulations on volatile organic compound emissions from resin curing processes constrain formulation choices and installation practices in US manufacturing plants. Stakeholders must weigh the trade-off between permanent epoxy installations with lower lifecycle particulate risk and modular systems that accommodate faster facility repurposing as therapeutic modalities shift from small molecules to biologics and cell therapies.
Market Dynamics
Semiconductor lithography nodes below 7nm demand flooring systems with particulate thresholds tighter than ISO Class 3, forcing resin formulators to abandon legacy carbon-black conductive loads in favor of precision-engineered silver nanowire networks.
Growth Catalysts
- EPA VOC emission caps:US manufacturing plants face stricter volatile organic compound limits during epoxy curing, accelerating waterborne polyurethane adoption in electronics fabrication facilities.
- Taiwan semiconductor cluster expansion:New 2nm fab construction in Hsinchu Science Park drives demand for monolithic flooring with integrated electrostatic discharge protection and seamless wall cove integration.
- Cell therapy facility buildout:Aseptic processing suites for CAR-T manufacturing require thermal-weldable vinyl sheet systems that support rapid cleanroom reclassification between GMP grades.
Market Restraints
- Epoxy resin supply concentration:Bisphenol A and specialty amine hardener production clusters in China create input cost volatility and freight exposure for North American installers.
- REACH authorization timelines:ECHA scrutiny of isocyanate-containing polyurethane formulations extends product registration cycles by 18-24 months for European pharmaceutical projects.
- Modular panel substitution:Raised-access flooring with HEPA-integrated plenums captures share in biotechnology temporary cleanrooms where permanence is undesirable.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO enforcement of Schedule M compliance for domestic drug production creates first-time demand for ISO 14644-1 certified flooring in Ahmedabad and Hyderabad clusters.
- EU Green Deal procurement mandates:Public hospital construction in Germany and France now requires environmental product declarations, favoring suppliers with verified lifecycle carbon data.
- Antimicrobial additive convergence:Integration of photocatalytic titanium dioxide with conductive carbon systems enables single-surface solutions addressing both particulate and bioburden control.
Industry Challenges
- Installation technician certification:Proper seam welding and static-dissipative grounding require specialized training that lags behind facility construction timelines in emerging markets.
- Legacy substrate incompatibility:Existing pharmaceutical plants with aged concrete slabs face moisture vapor emission barriers that complicate epoxy adhesion and extend project schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cleanroom Flooring Market |
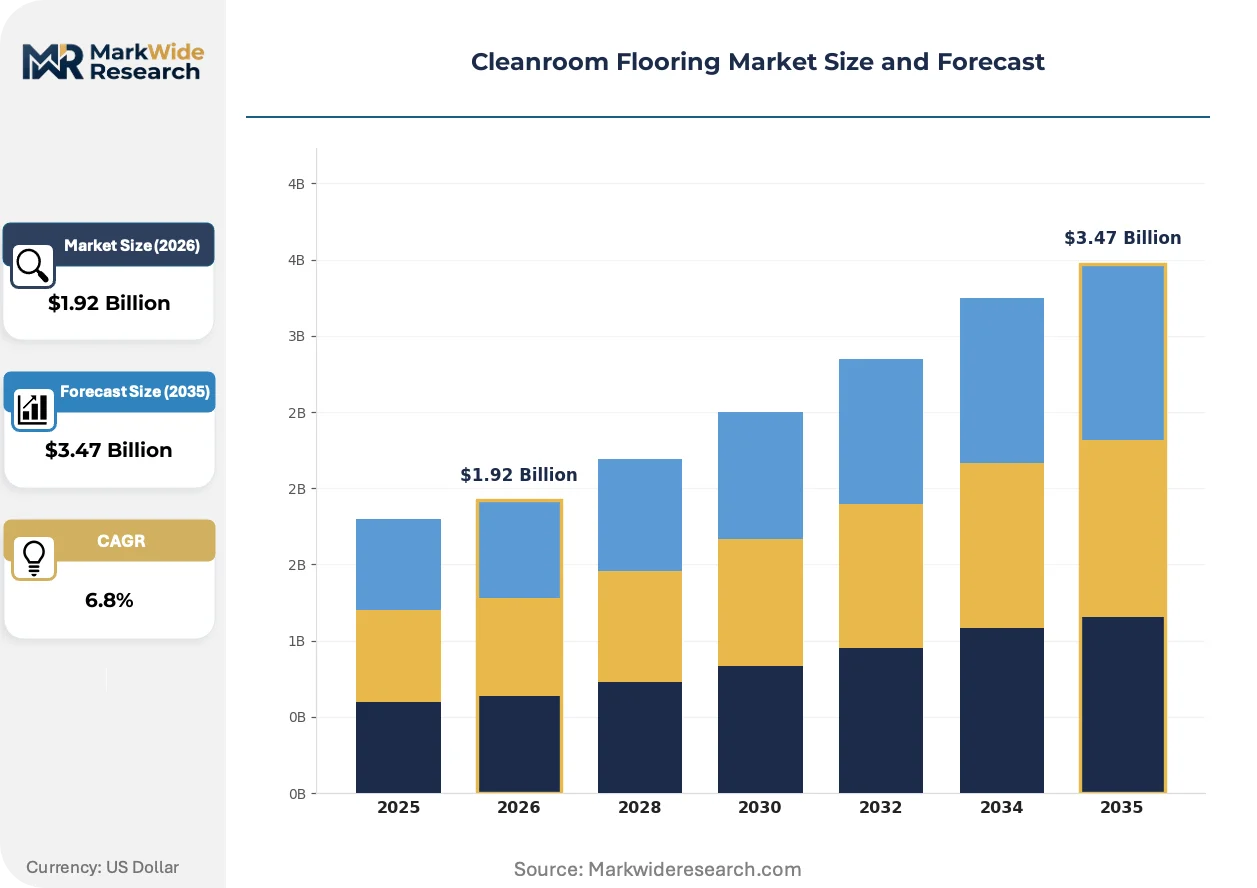
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.47 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl, Epoxy, Rubber, Tile Application: Pharmaceutical, Biotechnology, Microelectronics, Aerospace End User: Hospitals, Research Facilities, Manufacturing Plants, Laboratories Installation Type: Permanent, Removable, Modular, Custom |
| Companies Covered | Nora Systems, Polyflor, Gerflor Group, Cleanroom Industries, Florock Polymer Flooring, Forbo Flooring Systems, Lindner Group, Total Clean Air, AES Clean Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cleanroom Flooring Market Strategic Shifts
Material science breakthroughs and regulatory stringency are compressing product development cycles while fragmenting procurement authority across facility engineering, quality assurance, and sustainability functions.
Silver nanowire conductive networks are overtaking traditional carbon-loaded epoxy formulations in microelectronics cleanrooms. Taiwan Semiconductor Manufacturing and Samsung Foundry specify surface resistivity below 10^6 ohms with optical clarity for lithography bay inspection protocols. This displacement is compressing margins for commodity conductive flooring suppliers unable to achieve nanoscale dispersion uniformity.
REACH authorization requirements for diisocyanates now mandate workplace exposure training and medical surveillance across EU member states. Flooring contractors must document installer certification before project mobilization, adding 10-15 days to pharmaceutical facility timelines. German and Swiss pharmaceutical operators increasingly specify waterborne alternatives to preempt authorization risk.
Integrated facility service contracts now bundle flooring installation with predictive maintenance and scheduled resurfacing. Large-scale biotechnology campuses in Boston and San Francisco negotiate decade-long agreements that transfer lifecycle performance risk to applicators. This model displaces transactional procurement in multi-phase campus expansions where cleanroom classification continuity is critical.
Cleanroom Flooring Market Segmentation
Cleanroom flooring procurement splits across incompatible performance requirements. Semiconductor fabs demand electrostatic discharge control that hospital suites ignore, while biotechnology campuses prioritize reconfigurability over permanence. Specification authority fragments between facilities engineering, quality assurance, and procurement functions.
Product Type:
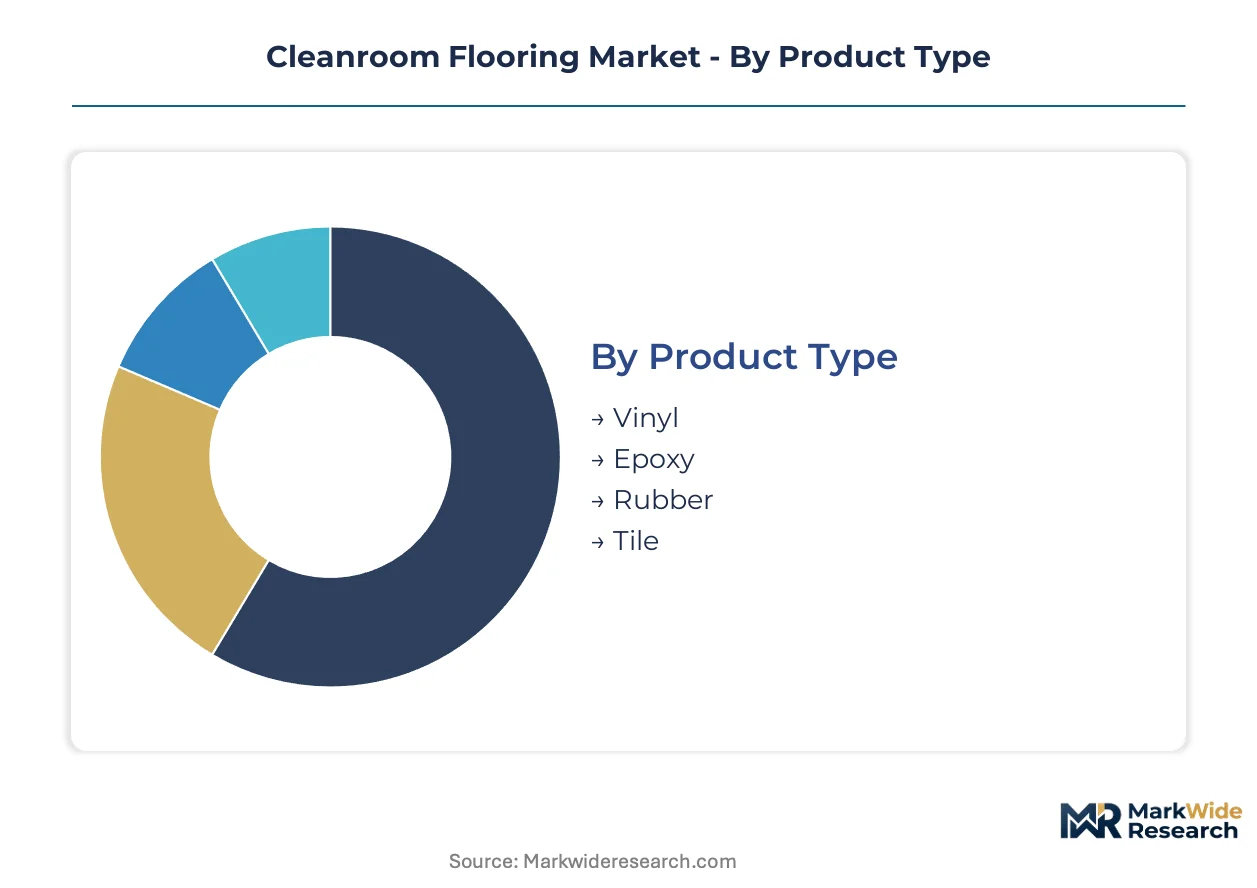
Replacement cycles vary sharply by chemistry—epoxy installations endure 10-15 years while vinyl sheets face 5-7 year refresh intervals in high-traffic pharmaceutical corridors.
- Epoxy:Thermoset polymer systems cure into seamless, chemically resistant monolithic surfaces. Taiwan Semiconductor Manufacturing and Samsung Foundry specify silver nanowire conductive formulations for sub-7nm lithography bays where surface resistivity below 10^6 ohms prevents electrostatic discharge damage to wafers. EPA VOC emission caps during curing accelerate waterborne polyurethane substitution in US electronics fabrication.
- Vinyl:Homogeneous or heterogeneous PVC sheet systems enable thermal welding of seams for aseptic integrity. Hospital pharmacies and CAR-T manufacturing suites in Boston and San Francisco specify welded vinyl for rapid cleanroom reclassification between GMP grades. REACH authorization timelines for diisocyanate-containing alternatives extend European pharmaceutical project schedules.
- Rubber:Elastomeric formulations with conductive carbon loading serve aerospace assembly environments where fatigue resistance under rolling loads matters.
- Tile:Precision-milled modular units with interlocking edges support rapid deployment in temporary biotechnology cleanrooms.
Volume placements concentrate in epoxy systems for microelectronics fabrication; the faster expansion belongs to vinyl sheet as cell therapy facility buildout accelerates.
Application:
End-use specifications diverge on particulate thresholds, chemical exposure profiles, and regulatory audit frequencies.
- Microelectronics:Lithography bay flooring must achieve ISO Class 3 particulate thresholds with optical clarity for inspection protocols. Silver nanowire networks displace legacy carbon-black conductive loads as nodes shrink below 7nm.
- Pharmaceutical:Aseptic processing suites demand seamless surfaces that withstand aggressive disinfectant regimens. FDA Current Good Manufacturing Practice standards mandate flooring integrity documentation during pre-approval inspections.
- Biotechnology:Multi-product facilities require surfaces supporting rapid cleanroom reclassification. Modular installation formats gain traction where therapeutic modalities shift from small molecules to cell therapies.
- Aerospace:Conductive formulations navigate certification requirements for satellite assembly environments where electrostatic discharge threatens sensitive avionics.
Microelectronics commands premium pricing for specialized conductive formulations; biotechnology applications are climbing the fastest as facility repurposing cycles compress.
End User:
Procurement sophistication varies—multinational pharmaceutical operators specify lifecycle performance guarantees while research facilities prioritize capital cost containment.
- Manufacturing Plants:Integrated facility service contracts now bundle installation with predictive maintenance. Large-scale biotechnology campuses negotiate decade-long agreements transferring performance risk to applicators.
- Hospitals:EU Green Deal procurement mandates require environmental product declarations for public hospital construction in Germany and France.
- Research Facilities:University and government laboratories face constrained capital budgets that favor modular systems over permanent epoxy.
- Laboratories:Contract research organizations prioritize rapid deployment to meet volatile sponsor demand timelines.
Manufacturing plants dominate absolute volume; research facilities are expanding most quickly as academic cell therapy programs proliferate.
Installation Type:
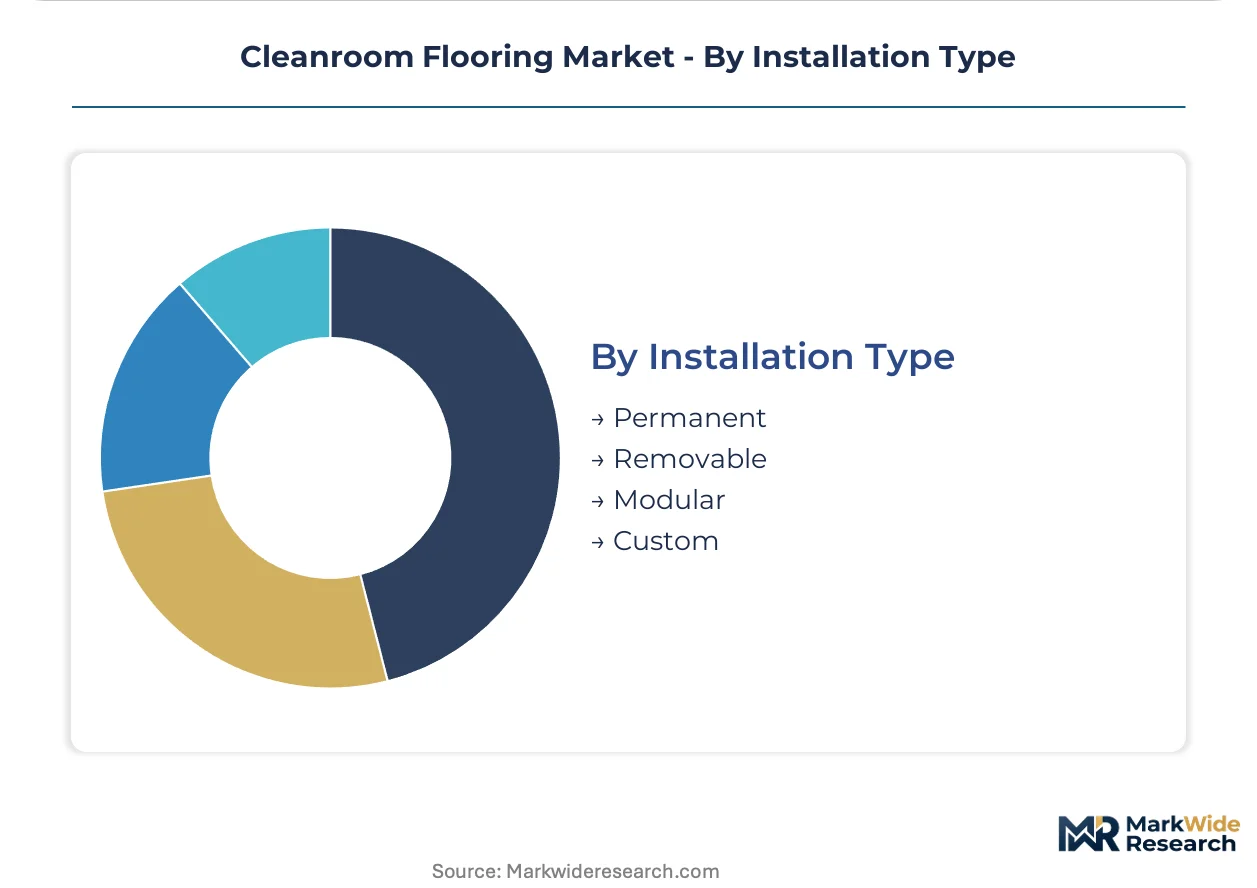
Permanence trade-offs structure facility lifecycle economics—epoxy bonds create lower particulate risk but foreclose rapid reconfiguration.
- Permanent:Monolithic epoxy or welded vinyl systems integrate with wall cove bases for sealed envelopes. Semiconductor fabs in Hsinchu Science Park specify permanent installations with 15-year performance guarantees.
- Modular:Raised-access flooring with HEPA-integrated plenums captures share in biotechnology temporary cleanrooms where permanence is undesirable.
- Removable:Floating vinyl sheet systems support rapid decommissioning for facility repurposing between therapeutic modalities.
- Custom:Hybrid systems combine permanent subfloors with replaceable wear layers for specialized aerospace certification requirements.
Permanent installations retain volume leadership in microelectronics; modular formats are gaining share fastest as biotechnology facility reconfiguration cycles accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park in Taiwan anchors semiconductor cleanroom flooring demand through TSMC's 2nm fab buildout, while regulatory tightening across multiple jurisdictions reshapes specification standards.
United States
EPA VOC emission caps during epoxy curing accelerate waterborne polyurethane adoption in electronics fabrication facilities. FDA Current Good Manufacturing Practice standards mandate flooring integrity documentation during pre-approval inspections for pharmaceutical suites. Boston and San Francisco biotechnology campuses negotiate decade-long integrated facility service contracts bundling installation with predictive maintenance.
Taiwan
Sub-7nm lithography nodes at TSMC and United Microelectronics drive demand for silver nanowire conductive formulations with surface resistivity below 10^6 ohms. Industrial Development Bureau incentives support contamination-controlled environment scaling across Hsinchu and Tainan Science Parks. New fab construction in Hsinchu Science Park specifies monolithic flooring with integrated electrostatic discharge protection and seamless wall cove integration.
Germany
EU Green Deal procurement mandates require environmental product declarations for public hospital construction in Germany and France. ECHA scrutiny of diisocyanate-containing polyurethane formulations extends product registration cycles by 18-24 months for pharmaceutical projects. Nora Systems leverages captive polymer compounding to sustain margin control across vinyl sheet production serving hospital pharmacies.
South Korea
Samsung Foundry and SK Hynix specify optical clarity flooring for lithography bay inspection protocols at nodes below 7nm. Korean Ministry of Trade, Industry and Energy supports domestic semiconductor supply chain localization. Pyeongtaek and Hwaseong industrial clusters drive premium conductive formulation demand for advanced memory fabrication facilities.
India
CDSCO enforcement of Schedule M compliance for domestic drug production creates first-time demand for ISO 14644-1 certified flooring. Pharmaceutical manufacturing clusters in Ahmedabad and Hyderabad require rapid facility buildout for export-oriented generic production. Installation technician certification gaps complicate project mobilization timelines in emerging cleanroom markets.
Cleanroom Flooring Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across chemistry and installation service segments. The vendor base organizes around three strategic archetypes: captive polymer compounders controlling resin supply chains, specialized conductive formulators serving microelectronics certification requirements, and integrated facility service providers bundling installation with lifecycle maintenance. Dominant competitive moves include backward integration into polymer compounding and decade-long performance guarantee contracts transferring operational risk to applicators.
Among European flooring specialists, Nora Systems and Gerflor Group exemplify the captive-compounding archetype, while Forbo Flooring Systems anchors the conductive-formulation tier for aerospace certification requirements. These three occupy positions across distinct specification vectors—pharmaceutical vinyl sheet, industrial elastomeric systems, and precision electronics flooring—reflecting fragmented procurement authority between facilities engineering, quality assurance, and sustainability functions.
| Leading Market Players |
|---|
| Nora Systems |
| Polyflor |
| Gerflor Group |
| Cleanroom Industries |
| Florock Polymer Flooring |
| Forbo Flooring Systems |
| Lindner Group |
| Total Clean Air |
| AES Clean Technology |
| Others |
Value Chain & Pricing Dynamics
Bisphenol A spot prices in East Asian commodity markets cascade through epoxy resin formulations into three distinct procurement tiers for cleanroom flooring buyers. Pharmaceutical operators absorbing REACH compliance premiums face cost compression at the standard tier, while semiconductor fabs in Taiwan and South Korea absorb nanowire-conductive premiums without volume negotiation leverage.
Pricing Analysis
Short lead-time premiums of 15-25% separate spot procurement from contract-scheduled deliveries in resin-based flooring systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 14644-1 certification grade and silver nanowire loading density. Cost compression in standard epoxy formulations is intensifying because vinyl sheet alternatives capture pharmaceutical share with faster installation cycles. Contract research organizations exhibit highest price sensitivity; integrated biotechnology campuses with decade-long service agreements demonstrate lowest sensitivity due to risk-transfer bundling.
Supply Chain Analysis
Specialty amine hardener production rests on concentrated chemical manufacturing clusters in China, Germany, and the United States. Epoxy resin formulations draw from bisphenol A, carbon black or silver nanowire conductive loads, and isocyanate-based polyurethane alternatives. Single-source vulnerability in Chinese hardener supply creates freight exposure and tariff uncertainty for North American installers. Distribution runs through authorized applicator networks with mandatory ECHA installer certification documentation for EU pharmaceutical projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cleanroom flooring market functions as a cost-of-compliance arena where REACH authorization timelines and EPA VOC emission caps erect formidable barrier-to-entry moats for resin suppliers lacking regulatory infrastructure.
For Market Incumbents: Deepen captive polymer compounding capabilities to insulate margin structures from bisphenol A price volatility. Expand certified installer training programs in India and Southeast Asia to preempt technician shortage bottlenecks that delay project mobilization. Carbon nanotube conductive formulations threaten silver nanowire incumbency in sub-5nm lithography specifications. For New Entrants and Emerging Players: Launch via modular installation service contracts targeting biotechnology campuses in Boston and San Francisco where facility reconfiguration cycles compress replacement demand. India's CDSCO Schedule M enforcement creates first-time ISO 14644-1 certified flooring demand in Ahmedabad and Hyderabad pharmaceutical clusters. Partner with regional construction firms to bypass established applicator network gatekeeping. For Investors and Strategic Acquirers: Distressed-cycle entries favor captive-compounding vinyl sheet specialists with EU environmental product declaration infrastructure in Germany and France. Five-to-ten-year viability hinges on regulatory compliance automation rather than commodity resin trading. Watch ECHA diisocyanate authorization enforcement velocity as inflection indicator for waterborne polyurethane substitution rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Nora Systems leverages captive resin production to sustain margin control across REACH-regulated European pharmaceutical supply. |
| Silver Nanowire Conductive Formulation Investment | TSMC and Samsung Foundry specifications for sub-7nm lithography bays displace legacy carbon-black loaded epoxy systems. |
| Integrated Facility Service Contract Expansion | Boston and San Francisco biotechnology campuses transfer lifecycle performance risk to applicators through decade-long maintenance bundling. |
| Waterborne Polyurethane Product Line Launch | EPA VOC emission caps during epoxy curing accelerate substitution in US electronics fabrication facilities facing compliance deadlines. |
| Installer Certification Infrastructure Buildout | ECHA diisocyanate workplace exposure mandates extend pharmaceutical project timelines where trained technician pools remain shallow. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with resin formulation chemists, cleanroom facility engineering directors, pharmaceutical quality assurance managers, and flooring installation contractors combined with EPA emission disclosure documents, ECHA authorization timelines, and semiconductor fab construction permits. Bottom-up project pipeline tracking across Hsinchu Science Park and Pyeongtaek industrial clusters reconciled with top-down resin consumption estimates from customs import records.
Data-stream reconciliation across product type, application end-use, installation format, and regional regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs derived from facility construction pipeline velocity, resin price elasticity modeling, and substitution rate assumptions between epoxy and vinyl sheet systems. Forecast inputs incorporated ISO 14644-1 classification threshold tightening schedules and CDSCO Schedule M enforcement trajectories.
The model assumes a particular technology adoption path; alternative pathways for photocatalytic antimicrobial integration would alter the outlook. Forecasts reflect assumptions regarding silver nanowire dispersion cost reduction and ECHA authorization timeline stability. A small set of triggers—tariff escalation on Chinese hardener imports, sub-5nm lithography node acceleration, and EU Green Deal procurement mandate expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Asia Pacific Sanitaryware Market
Building & Construction Materials
India Ceramic Tiles Market
Building & Construction Materials
Europe Particle Board Market
Building & Construction Materials
Tar Paper Market
Building & Construction Materials
Construction Sustainable Materials Market
Building & Construction Materials
Outside Door Handle Market
Building & Construction Materials
Construction Aggregates Market
Building & Construction Materials
Welded Wire Mesh Market
Building & Construction Materials
South Africa Wall Putty Market
Building & Construction Materials
Plastic Door and Window Market
Building & Construction Materials
US Exterior Wall Systems Market
Building & Construction Materials
Cladding Systems Market
Building & Construction Materials
Fiberglass Light Poles Market
Building & Construction Materials
Roofing Tiles Market
Building & Construction Materials
Plastic Roofing Tiles Market
Building & Construction Materials
Sectional Door Market