
 Bio-Based Cutlery Market | 2026-2036
Bio-Based Cutlery Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Cutlery Market Outlook
Modular cutlery kits—combining forks, spoons, and knives in pre-sorted, portion-controlled packs—is hardening as the default procurement format for institutional foodservice buyers. Huhtamäki Oyj leverages its thermoforming expertise to dominate CPLA-based kit assembly for European contract catering. Vegware Ltd. competes through closed-loop composting partnerships that anchor its brand in UK foodservice channels.
Bio-based cutlery denotes disposable eating utensils manufactured from renewable feedstocks such as polylactic acid (PLA), crystallized PLA (CPLA), bamboo fiber, or sugarcane bagasse, with heat-deflection temperatures ranging from 55°C for standard PLA to 85°C for CPLA formulations designed for hot-food contact. CPLA material commands the widest margin pool due to its thermal performance premium over standard PLA in soup and hot-beverage applications. Forks and spoons lead volume within product type, while bamboo registers the fastest material growth as Asian manufacturers scale fiber-compression molding for export markets.
The EU Single-Use Plastics Directive and FDA food-contact substance notifications jointly shape material approval pathways and cross-border market access for bio-based cutlery suppliers. BIS certification requirements in India and EFSA compostability standards in Europe create divergent compliance thresholds that fragment supplier qualification costs. Stakeholders must monitor municipal composting capacity buildouts against certification mandates to avoid stranded inventory in markets where industrial composting lags regulatory bans on conventional plastics.
Market Dynamics
The EU Single-Use Plastics Directive functions as the dominant structural force, mandating material substitution across foodservice supply chains and compressing the transition timeline for conventional plastic cutlery elimination.
Growth Catalysts
- EU Single-Use Plastics Directive:Bans on conventional plastic cutlery across member states create immediate replacement demand for certified bio-based alternatives in foodservice channels.
- Quick-service restaurant procurement mandates:North American QSR chains now embed compostable cutlery specifications directly into supplier contracts, locking in material transition.
- CPLA thermal performance:Crystallized PLA formulations withstand hot-food contact up to 85°C, opening soup and beverage applications previously closed to bio-based materials.
Market Restraints
- Industrial corn price volatility:PLA feedstock costs track agricultural commodity swings, compressing margin predictability for manufacturers without long-term supply agreements.
- Municipal composting infrastructure gaps:Certified biodegradable products face stranded inventory risk in regions where industrial composting capacity lags regulatory bans on conventional plastics.
- BIS-EFSA certification divergence:India's BIS requirements and Europe's EFSA compostability standards create fragmented qualification costs that fragment supplier market access.
Strategic Opportunities
- German municipal composting networks:Dense industrial composting infrastructure supports premium pricing for certified biodegradable cutlery in institutional foodservice procurement.
- Closed-loop composting partnerships:Direct brand anchoring through waste-stream integration creates channel lock-in with UK contract catering operators.
- Bamboo fiber compression molding:Asian manufacturers scaling fiber-composite production for export markets unlocks fastest-growing material segment with lower feedstock cost exposure.
Industry Challenges
- Thermoforming equipment retooling:CPLA processing requires modified mold temperatures and cycle times, demanding capital deployment that mid-scale converters struggle to finance.
- Compostability certification timelines:EFSA and BIS approval pathways extend 12-18 months, creating inventory risk for products launched ahead of full certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based Cutlery Market |
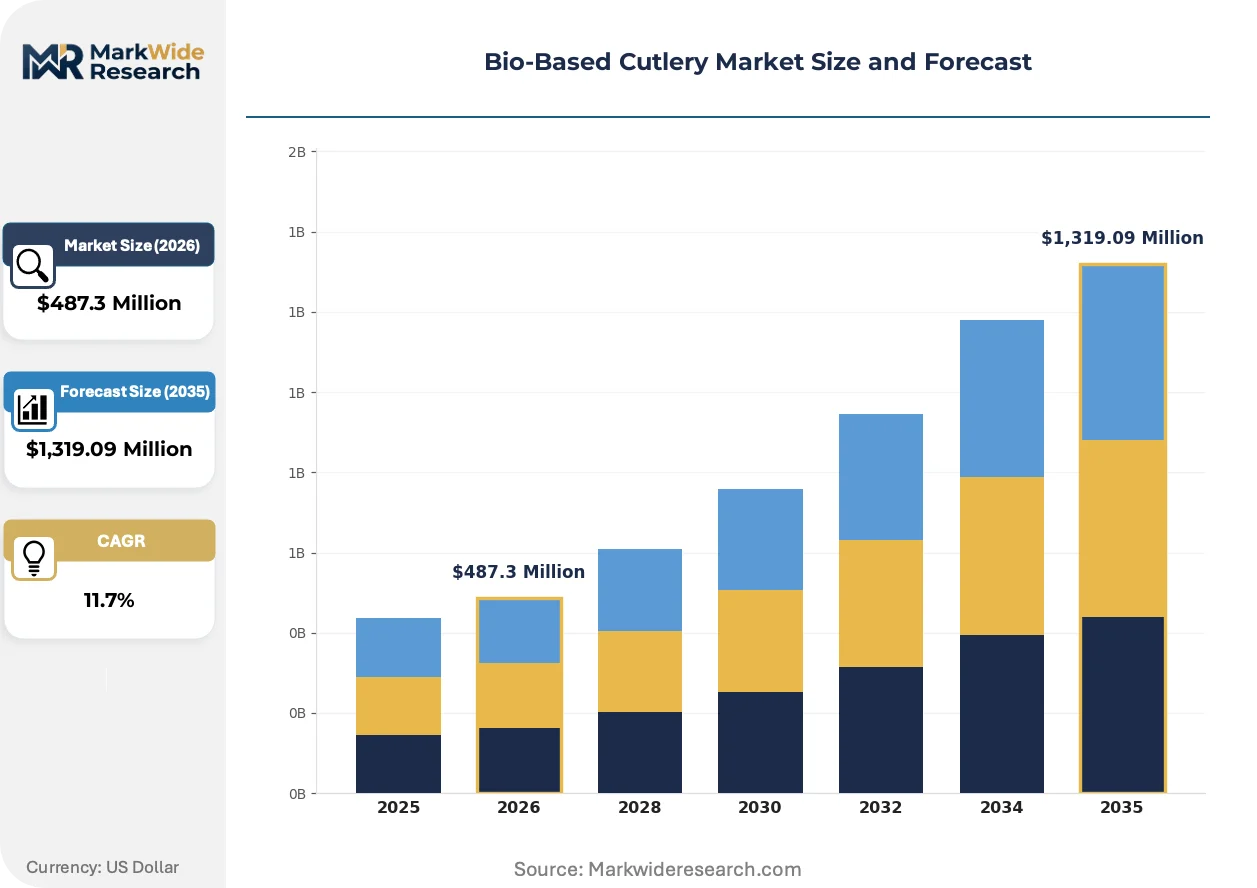
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forks, Spoons, Knives, Plates Material: PLA, CPLA, Bamboo, Sugarcane End User: Households, Catering Services, Food Trucks, Restaurants Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | BioPak, Leafware LLC, Huhtamäki Oyj, Pactiv Evergreen Inc., Anchor Packaging Inc., Vegware Ltd., Natur-Tec, Biodegradable Food Service, LLC, Biotrem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Cutlery Market Strategic Shifts
Material science advances and procurement model evolution are compressing product lifecycles while regulatory mandates accelerate format standardization across foodservice channels.
Bamboo fiber composite technology is expanding into European and North American export markets as Asian manufacturers refine compression-molding parameters for dimensional stability. Quick-service restaurant chains in Germany and France are qualifying bamboo-based kits for cold-food applications where thermal performance requirements relax. This material trajectory is expanding into price-sensitive institutional segments previously dominated by conventional plastic, compressing the premium gap between bio-based and petroleum-derived alternatives.
REACH substance restrictions and FDA food-contact substance notifications are jointly tightening migration limits for additives in bio-based cutlery formulations. European manufacturers face reformulation costs to eliminate plasticizers flagged under ECHA candidate list reviews. CPLA suppliers serving dual-market export strategies must maintain parallel compliance documentation, increasing quality-system overhead while creating competitive separation between integrated compounders and pure converters.
Modular kit procurement is consolidating purchasing authority within institutional foodservice operators, displacing single-item replenishment with pre-sorted portion-controlled packs. Contract catering buyers in Germany and the UK now specify kit configuration in tender documents, compressing supplier flexibility on format mix. This specification tightening is most visible in airport and healthcare foodservice channels where operational efficiency metrics override material preference flexibility.
Bio-Based Cutlery Market Segmentation
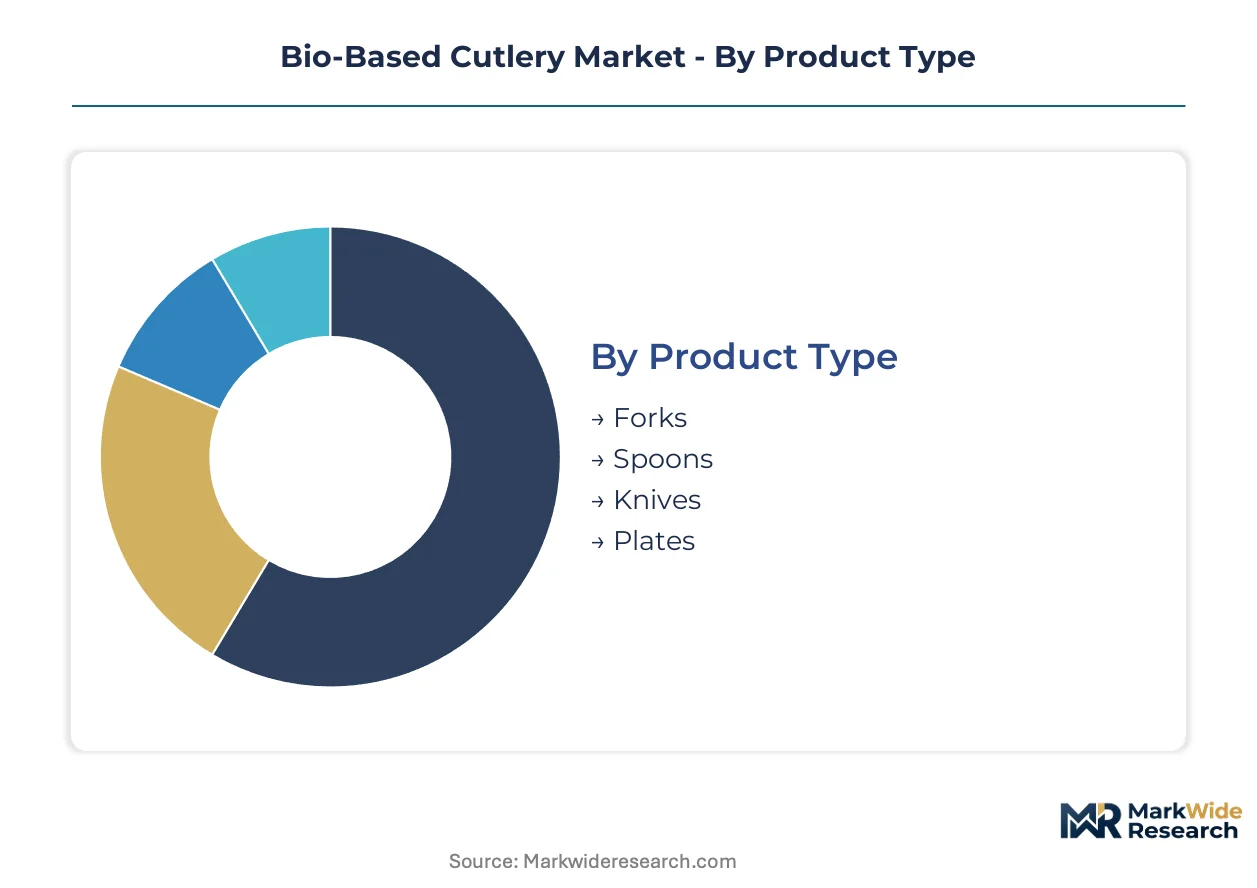
Segmentation in bio-based cutlery determines which certification pathways suppliers must navigate and where margin pools concentrate. Product type and material selection drive thermal performance requirements, while end-user and channel choices dictate packaging formats and compliance documentation intensity.
Product Type:
CPLA-based forks and spoons face the most stringent EFSA compostability documentation, while knives require additional blade-edge safety testing under FDA food-contact substance notifications.
- Forks:CPLA formulations dominate institutional procurement due to tine rigidity requirements. German airport catering contracts specify fork-first kit configurations, compressing supplier format flexibility.
- Spoons:Deep-bowl designs for soup applications demand heat-deflection temperatures above 80°C, locking in CPLA or bamboo composite selection. UK healthcare foodservice channels drive volume concentration for portion-controlled spoon packs.
- Knives:Serrated edges require modified mold tooling and separate safety certifications. Demand clusters in North American QSR chains with pre-wrapped cutlery mandates.
- Plates:Compartment designs for institutional trays face dimensional stability challenges in fiber-based materials.
Forks sit at the top of the volume ranking, with spoons climbing the fastest.
Material:
Cost tiers separate feedstock categories, with agricultural commodity exposure creating divergent margin predictability across supplier portfolios.
- CPLA:Crystallized PLA commands premium positioning through 85°C heat tolerance. Hot-beverage and soup applications in German contract catering anchor demand concentration.
- PLA:Standard formulations serve cold-food applications where thermal thresholds relax. Price-sensitive institutional buyers in India drive volume through BIS-certified domestic production.
- Bamboo:Fiber-compression molding scales fastest among Asian exporters. European cold-food qualification programs expand addressable market beyond thermal-limited use cases.
- Sugarcane:Bagasse-derived products compete on feedstock cost in tropical manufacturing clusters.
CPLA captures the dominant margin tier, while bamboo gains share fastest.
End User:
Customer type determines order frequency, batch size, and specification rigidity, with institutional buyers consolidating purchasing authority through modular kit contracts.
- Restaurants:Quick-service chains embed compostable specifications directly into supplier agreements. North American procurement mandates lock in multi-year material transitions.
- Catering Services:Contract operators in Germany and the UK specify pre-sorted kit configurations in tender documents. Operational efficiency metrics override material flexibility preferences.
- Food Trucks:Mobile operators prioritize lightweight, compact packaging for space-constrained storage.
- Households:Retail-packaged assortments face price competition from conventional plastic in supermarkets.
Restaurants anchor volume concentration, with catering services expanding most quickly.
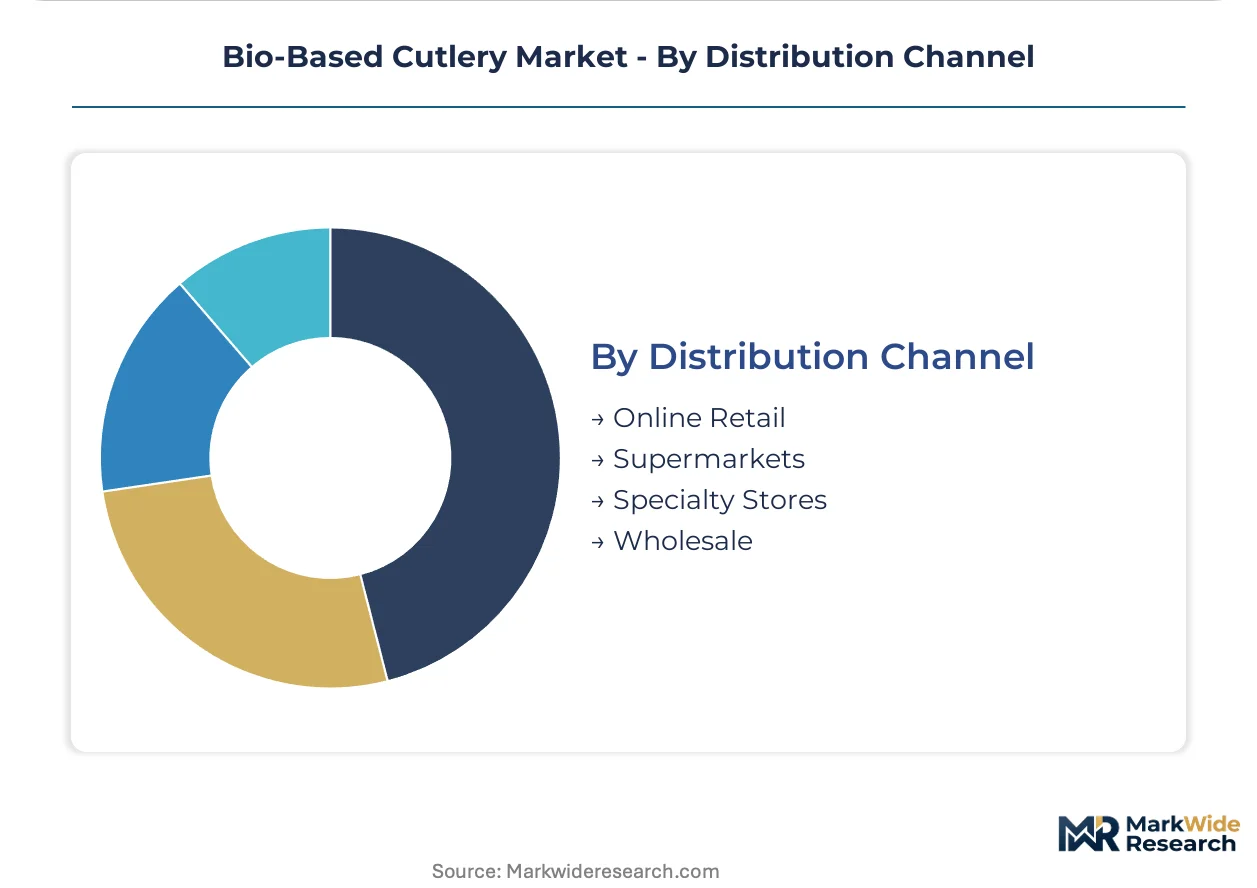
Distribution Channel:
Channel selection dictates packaging complexity and certification documentation reach, with wholesale and online retail creating divergent inventory risk profiles.
- Wholesale:Bulk pallet configurations serve institutional buyers with direct-to-kitchen delivery. German municipal composting networks support certified product premium pricing.
- Online Retail:E-commerce assortments require individual item labeling for consumer composting guidance. UK closed-loop partnership programs anchor brand differentiation.
- Supermarkets:Retail shelf placement demands competitive pricing against petroleum-derived alternatives.
- Specialty Stores:Eco-focused independents stock premium-tier certified products with full traceability documentation.
Wholesale channels dominate volume throughput, with online retail climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial-scale bio-based cutlery manufacturing first achieved commercial viability in European thermoforming clusters during the early 2000s, with German compounders pioneering CPLA crystallization protocols that enabled hot-food contact applications.
Germany
Municipal composting infrastructure density supports premium pricing for certified biodegradable cutlery in institutional foodservice procurement. The EU Single-Use Plastics Directive mandates material substitution across federal foodservice contracts. Bavaria's industrial corridor hosts concentrated thermoforming operations serving airport and healthcare catering channels.
United States
Quick-service restaurant chains embed compostable specifications directly into multi-year supplier agreements, locking in material transitions. FDA food-contact substance notifications govern additive migration limits for bio-based formulations. California's municipal composting mandates in the San Francisco Bay Area and Los Angeles metro create demand anchors for certified products.
United Kingdom
Closed-loop composting partnerships anchor brand differentiation in contract catering procurement. EFSA compostability standards determine product qualification for cross-border EU market access after Brexit. London's concentrated airport and corporate catering operations drive specification tightening for modular kit formats.
India
Price-sensitive institutional buyers drive volume through BIS-certified domestic PLA production. BIS certification requirements create divergent compliance thresholds from European standards, fragmenting supplier qualification costs. Maharashtra's industrial zones concentrate bagasse-derived manufacturing for tropical feedstock cost advantages.
China
Bamboo fiber compression molding scales fastest among Asian exporters targeting European cold-food qualification programs. GB standards and dual carbon goals shape domestic material substitution timelines. Zhejiang and Fujian provinces host concentrated fiber-composite manufacturing clusters serving export markets.
Bio-Based Cutlery Market Competitive Environment
The competitive structure tilts toward material-specialist compounders with integrated certification capabilities. Tiered concentration separates integrated European thermoformers from Asian fiber-composite exporters and North American distribution-focused operators. Strategic archetypes include CPLA crystallization specialists, closed-loop composting integrators, and bamboo fiber scale players. Capacity expansion in Asian manufacturing zones and strategic partnerships with municipal composting operators constitute the dominant competitive moves.
Within the European integrated compounder tier, Huhtamäki Oyj and Vegware Ltd. exemplify divergent market positioning. Huhtamäki Oyj occupies the thermoforming-dominant position leveraging CPLA expertise for kit assembly, while Vegware Ltd. anchors its presence through UK waste-stream integration. Pactiv Evergreen Inc. represents the North American scale-driven archetype with distribution infrastructure serving QSR procurement mandates.
| Leading Market Players |
|---|
| BioPak |
| Leafware LLC |
| Huhtamäki Oyj |
| Pactiv Evergreen Inc. |
| Anchor Packaging Inc. |
| Vegware Ltd. |
| Natur-Tec |
| Biodegradable Food Service, LLC |
| Biotrem |
| Others |
Value Chain & Pricing Dynamics
Captive CPLA crystallization capacity anchors both supply security and premium pricing power for European integrated compounders serving German airport catering and UK healthcare channels. This backward integration into compound formulation insulates margin pools from agricultural commodity swings while locking in certification documentation control.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified CPLA kits from BIS-compliant PLA and uncertified fiber alternatives. Price differentiation rests on compostability certification grade and heat-deflection performance tier. Cost compression in standard PLA is intensifying because Indian domestic manufacturers scale BIS-certified output. Price-sensitive institutional buyers in Maharashtra drive volume at economy tiers, while German contract catering absorbs premium CPLA pricing.
Supply Chain Analysis
Single-source vulnerability sits with Chinese bamboo fiber processors controlling compression-molding equipment for European export qualification. Geographic supply concentration clusters in Germany, China, and India. Raw material dependencies draw from industrial corn for PLA feedstock, bagasse for sugarcane derivatives, and bamboo pulp for fiber composites. Tariff exposure on Asian imports into Europe threatens margin stability. Distribution runs through wholesale pallet configurations to institutional buyers with direct-to-kitchen delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bio-based cutlery market compounds steadily as regulatory mandates eliminate conventional plastic alternatives across foodservice procurement channels.
For Market Incumbents: Lock in multi-year CPLA supply agreements with German compounders before capacity constraints tighten. Secure EFSA certification renewals ahead of REACH substance restriction updates that threaten additive reformulation costs. Deepen backward integration into thermoforming equipment to defend against Asian fiber-composite entrants scaling European cold-food qualification. For New Entrants and Emerging Players: Food truck operators represent an underserved buyer archetype with unmet demand for lightweight, compact kit formats. Penetrate UK airport mobile catering and North American festival foodservice where operational efficiency metrics relax thermal performance requirements. Pursue direct closed-loop composting partnerships to anchor brand differentiation against established wholesale distributors. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale converters lack capital for CPLA mold retooling and EFSA documentation overhead. Frame long-term viability around compounder-tier positioning with integrated certification capabilities. Target Asian bamboo fiber specialists with European qualification progress as acquisition candidates. Watch municipal composting capacity buildouts against regulatory ban timelines as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CPLA Crystallization Capacity Expansion | Huhtamäki Oyj leverages thermoforming expertise to capture German airport catering contract renewals. |
| Closed-Loop Composting Partnership | Vegware Ltd. anchors UK brand presence through waste-stream integration with municipal operators. |
| Bamboo Fiber Export Qualification | Zhejiang manufacturers scale compression-molding for European cold-food certification programs. |
| EFSA Certification Pathway Investment | Compounders defragment compliance costs to unlock cross-border market access post-Brexit. |
| Backward Integration into Feedstock | Indian domestic producers secure BIS certification through captive bagasse supply from Maharashtra. |
Study Parameters
Bottom-up foodservice procurement modeling reconciled against top-down thermoforming capacity tracking forms the analytical core of this study. Primary interviews with contract catering procurement directors, compounder technical R&D leads, municipal composting facility operators, and BIS certification auditors combined with secondary validation from EFSA substance notifications, BIS product registries, EU customs trade data, and airport catering tender documents. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map CPLA crystallization throughput, fiber-compression molding scale, and kit assembly capacity against QSR procurement mandates and institutional tender specifications across the analysis window. Segmentation dimensions include product type, material formulation, end-user channel, and geographic regulatory cluster. CAGRs derive from slope-intercept modeling of substitution timelines against composting infrastructure deployment curves.
Underlying measurement precision varies by segment; EFSA-certified CPLA kits carry tighter precision than emerging bamboo fiber alternatives where qualification timelines remain fluid. Forecasts reflect documented assumptions on regulatory enforcement consistency and municipal composting buildout pacing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
Sustainable Packaging Market
Sustainable Packaging
Middle East and Africa Eco-Friendly Packaging Market
Sustainable Packaging
Areca Plates Market
Sustainable Packaging
Compostable Food Trays Market
Sustainable Packaging
Zero Waste Packaging Market
Sustainable Packaging
Bagasse Tableware Products Market
Sustainable Packaging
Wheat Straw Cutlery Market
Sustainable Packaging
Eco Friendly Bottles Market
Sustainable Packaging
Plant Based Packaging Market
Sustainable Packaging
Green Packaging Market
Sustainable Packaging
Compostable Tableware Market
Sustainable Packaging
Japan Green Packaging Market
Sustainable Packaging
Global Paper Straw Market
Sustainable Packaging
GCC Green Packaging Market
Sustainable Packaging
Bagasse Bowls Market
Sustainable Packaging
Eco-Friendly Straw Market