
 Egypt Plastic Bottles Market | 2026-2036
Egypt Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Plastic Bottles Market Insights
rPET resin is decoupling virgin polymer economics in Egypt's packaging sector as recycled flake prices stabilize below naphtha-linked PET. Alpla Group leverages its captive preform capacity to supply multinational beverage clients across North Africa. Raya Plastics anchors the mid-tier segment through dedicated HDPE lines for household chemical distributors. NatPack competes on speed-to-market with localized mold fabrication serving personal care brands.
Egypt plastic bottles are hollow thermoplastic containers typically blow-molded from PET, HDPE, or LDPE resins with wall thicknesses calibrated between 0.25 mm and 1.5 mm depending on internal pressure and stacking load requirements; they function primarily as portable, lightweight, and chemically inert vessels for liquid and semi-liquid consumer and industrial goods. PET dominates beverage applications due to its clarity, gas barrier properties, and compatibility with carbonated soft drink filling pressures. HDPE sustains margin pools in household products and chemicals where opacity, chemical resistance, and post-consumer recyclability outweigh aesthetic demands. Small and medium sizes lead unit volumes across beverages and personal care, while extra-large formats occupy niche industrial and institutional channels with lower frequency but higher per-unit value.
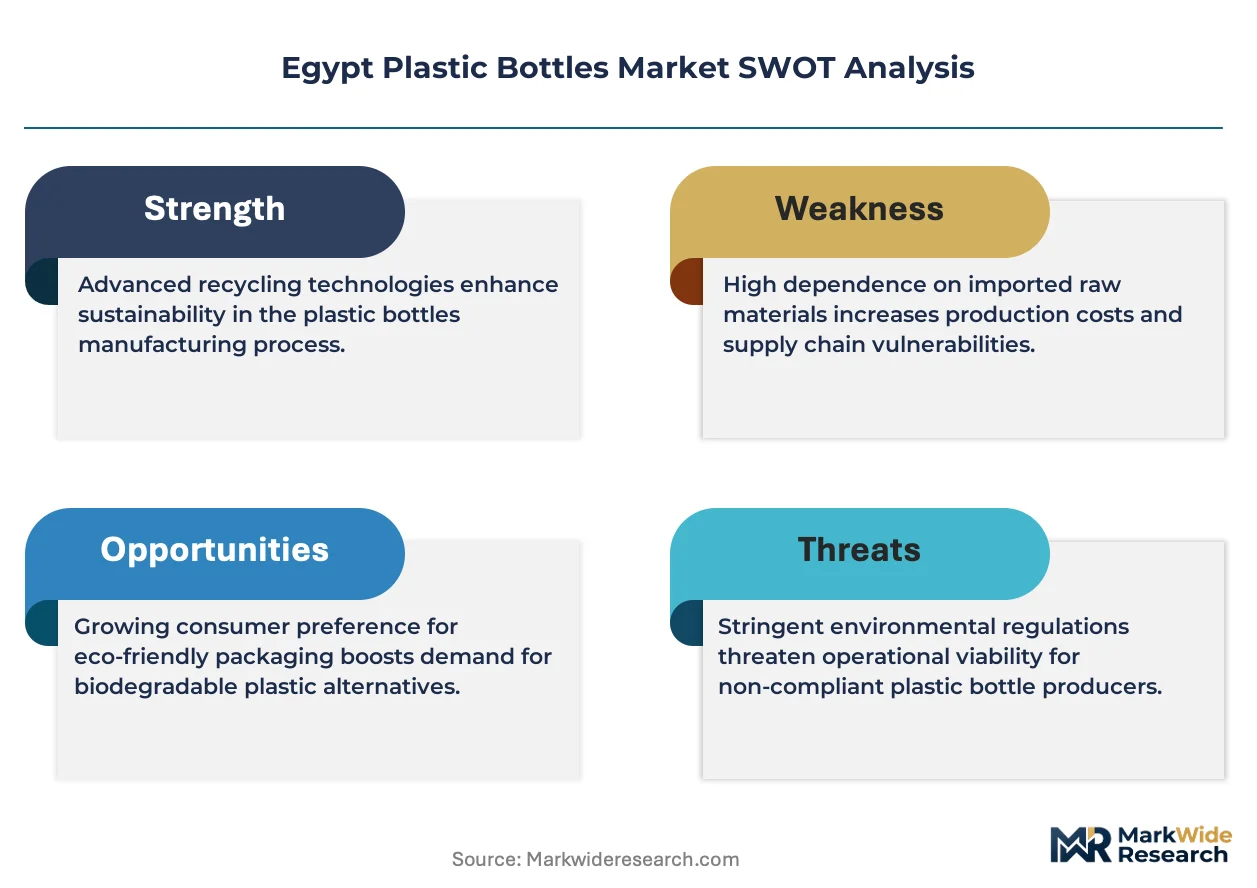
Egypt's Ministry of Environment enforces Law 202/2020 governing solid waste management, compelling producers to adopt extended producer responsibility frameworks and rPET content minimums in packaging sold domestically. The Egyptian Organization for Standardization and Quality (EOS) mandates migration testing and food-contact compliance certification under harmonized GB-equivalent protocols for imported resin and finished bottles. Stakeholders must monitor enforcement intensity in industrial zones outside Cairo and assess whether domestic flake purification capacity expands sufficiently to meet compliance thresholds without importing baled post-consumer material.
Market Dynamics
rPET flake purification capacity shortages are forcing Egyptian converters to import baled post-consumer material despite Law 202/2020's domestic content mandates, creating a structural tension between compliance costs and feedstock security.
Growth Catalysts
- Extended Producer Responsibility frameworks:Law 202/2020 compels brand owners to fund collection infrastructure, diverting investment toward bottle-to-bottle recycling systems in Greater Cairo's manufacturing corridor.
- Carbonated soft drink filling pressures:PET's gas barrier properties sustain demand from multinational beverage bottlers expanding bottling lines across Upper Egypt and the Delta region.
- Port-linked packaging zones:Alexandria's bonded warehousing and customs efficiencies attract export-oriented personal care brands seeking North African distribution hubs.
Market Restraints
- Naphtha-linked virgin PET volatility:Egyptian converters face margin compression when crude-derived feedstock prices spike above stabilized rPET flake benchmarks.
- Flake purification concentration:Domestic rPET food-grade capacity clusters in Cairo and Alexandria, leaving Upper Egypt processors dependent on long-haul logistics.
- HDPE opacity limitations:Household chemical distributors cannot substitute PET for premium cosmetic applications requiring visual clarity.
Strategic Opportunities
- Upper Egypt collection infrastructure:Underdeveloped post-consumer bale networks in Minya and Assiut governorates offer first-mover advantages for integrated recycler-processor joint ventures.
- Dual-color injection molding:Convergence of servo-electric blow molding with in-mold labeling enables premium personal care differentiation without secondary decoration.
- EOS food-contact compliance certification:Harmonized GB-equivalent protocols create export pathways for Egyptian converters into Sub-Saharan African markets lacking domestic certification capacity.
Industry Challenges
- Migration testing laboratory capacity:Bottlenecked EOS certification timelines delay new resin qualification, extending product development cycles for converters serving multinational clients.
- Legacy extrusion line reconfiguration:Retrofitting mechanical recycling flake handling systems into existing starlinger or erema-based purification trains demands specialized polymer engineering expertise scarce in the domestic labor pool.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Plastic Bottles Market |
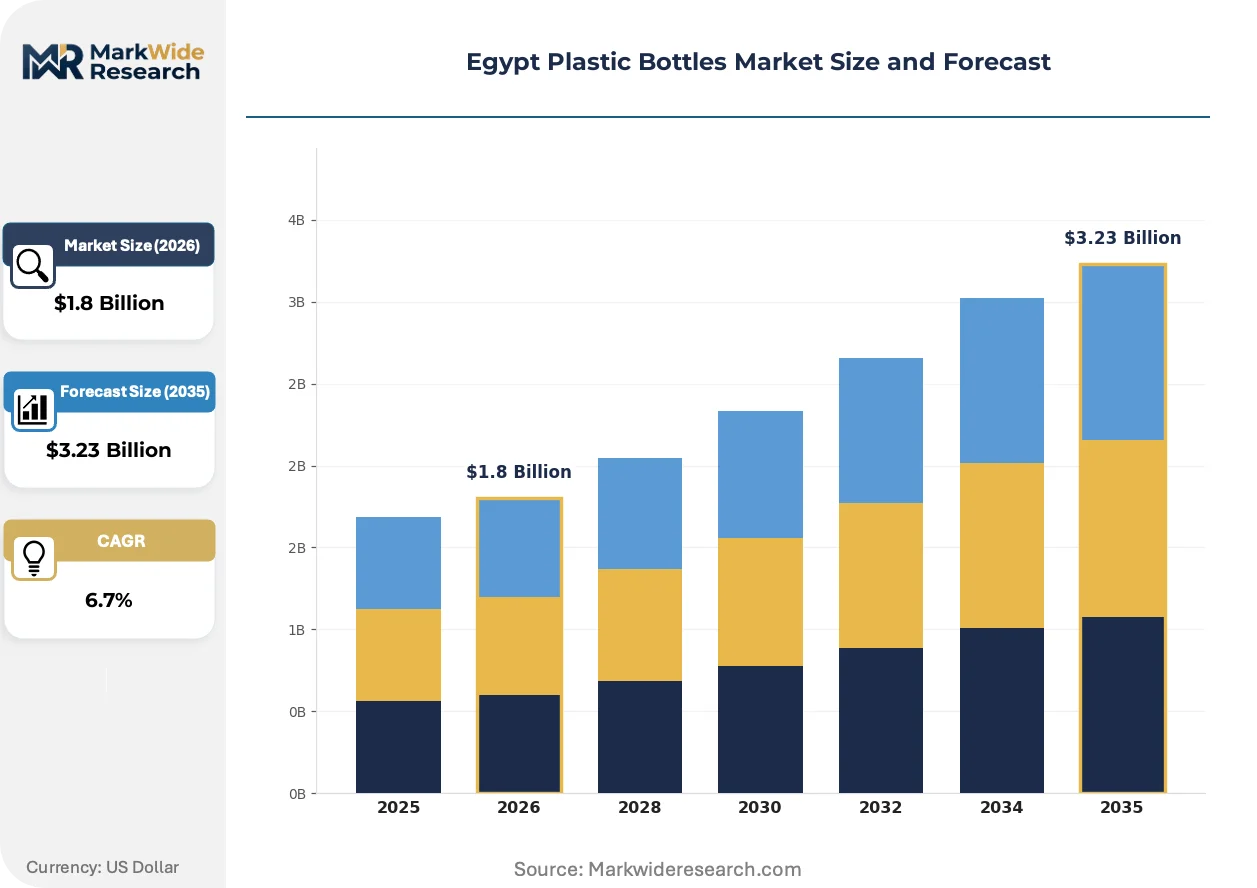
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: PET, HDPE, LDPE, PVC Application: Beverages, Personal Care, Household Products, Chemicals Size: Small, Medium, Large, Extra Large Closure Type: Screw Cap, Snap Cap, Flip Top, Others |
| Companies Covered | Alpla Group, Raya Plastics, NatPack, Master PET, New Delta Plastic, PET For Packaging Materials Egypt, Aquah Group, Hyma Plastic Group, Plastic Home Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Plastic Bottles Market Trends and Innovations
Active and intelligent packaging integration is compressing traditional commodity bottle margins while opening value-capture opportunities for converters capable of embedding sensor technologies and connected traceability.
Barrier-enhanced PET with plasma-deposited silicon oxide coatings is unifying carbonation retention performance with lightweighting targets. Beverage bottlers in Alexandria's port-linked zones are adopting these structures for export-bound carbonated soft drinks. The technology is unifying previously separate gas barrier and clarity specifications into single-layer bottle designs that reduce gram weight per unit.
Law 202/2020 enforcement intensity is tightening outside Cairo's industrial zones, with the Ministry of Environment deploying mobile inspection units to Delta region converters. Mid-tier processors face compliance cost escalation as extended producer responsibility fees scale with production volume. Household chemical distributors are responding by consolidating supplier bases toward converters with captive recycling certification.
Brand owners are compressing mold qualification timelines, demanding prototype-to-production cycles under eight weeks for seasonal personal care launches. Speed-to-market pressure favors converters with in-house mold fabrication like localized CNC machining clusters in 10th of Ramadan City. This behavioral shift is most visible in shampoo and conditioner segments where packaging refresh cycles now match fragrance formulation rotations.
Egypt Plastic Bottles Market Segmentation
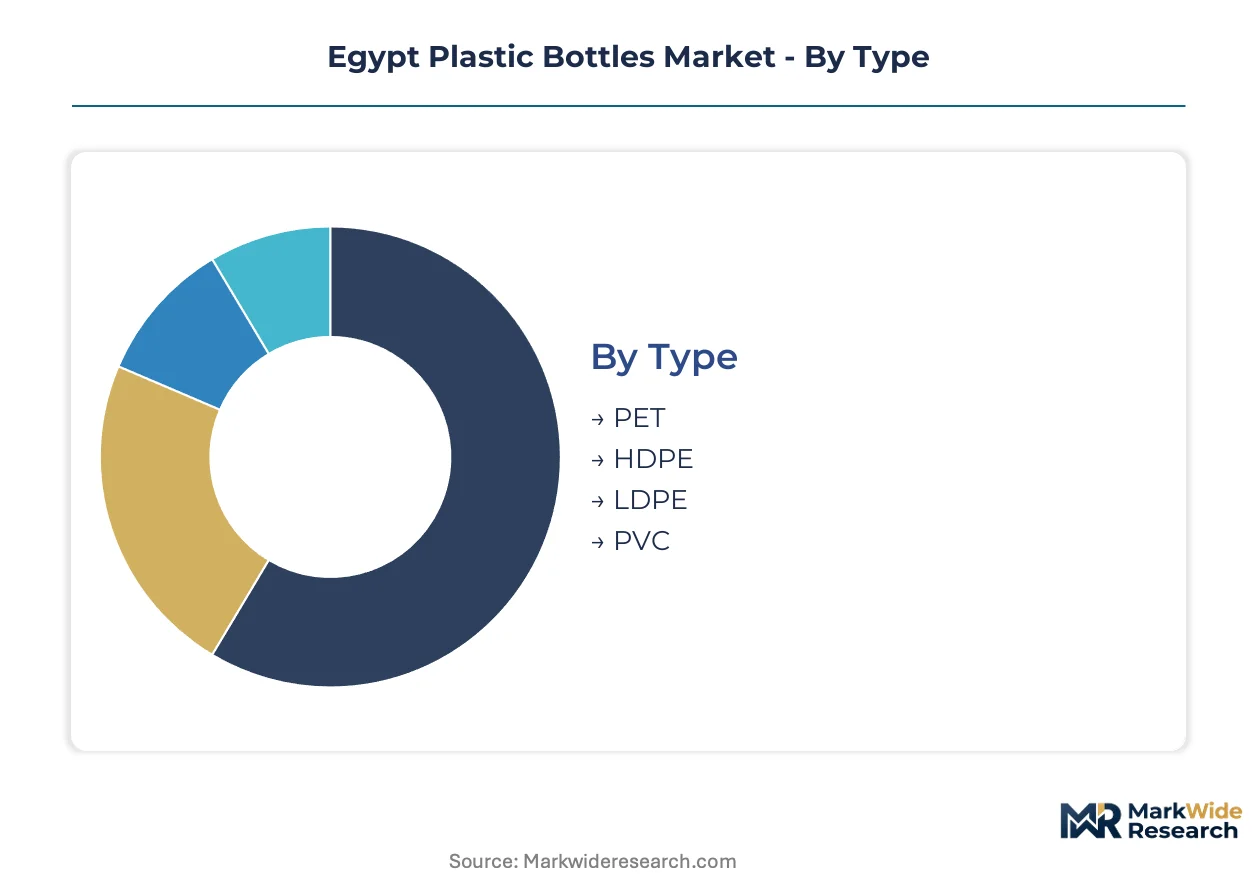
Resin chemistry, dimensional specifications, and closure mechanics create distinct margin pools across Egypt's packaging sector. Converters optimize line configurations around these segment boundaries to capture volume premiums in beverage bottling and technical specifications in chemical containment.
Type:
PET commands unit volume leadership while HDPE sustains margin concentration in specialized applications.
- PET:Polyethylene terephthalate delivers clarity and carbonation barrier performance for beverage bottlers. Demand concentrates in Greater Cairo's manufacturing corridor where multinational soft drink producers operate high-speed filling lines. The resin's compatibility with rPET flake integration aligns with Law 202/2020 compliance mandates.
- HDPE:High-density polyethylene provides opacity and chemical resistance for household products and industrial chemicals. Upper Egypt processors favor HDPE for bleach and detergent applications where visual clarity is secondary to structural integrity. Post-consumer recyclability sustains procurement preference among chemical distributors.
- LDPE:Low-density polyethylene serves squeeze applications and flexible packaging formats where conformability outweighs rigidity.
- PVC:Polyvinyl chloride occupies niche pharmaceutical and chemical containment segments requiring specific barrier properties.
Today's leader: PET. Tomorrow's challenger: HDPE.
Application:
End-use concentration in beverages generates scale economies while personal care demands speed-to-market flexibility.
- Beverages:Carbonated soft drinks, water, and juice bottling drive resin throughput across Alexandria's port-linked zones. PET's gas barrier properties sustain demand from multinational producers expanding Delta region capacity. Seasonal volume spikes require converters to maintain buffer inventory of preforms.
- Personal Care:Shampoo, conditioner, and lotion packaging demands rapid mold qualification cycles under eight weeks. Speed-to-market pressure favors converters with localized CNC machining in 10th of Ramadan City. Dual-color injection molding enables premium differentiation without secondary decoration.
- Household Products:Detergent and cleaning chemical containers prioritize HDPE opacity and chemical resistance over aesthetic specifications.
- Chemicals:Industrial and agricultural chemical containment requires specialized wall thickness calibration and UN certification compliance.
Beverages anchor current volume. Personal care is gaining share fastest.
Size:
Small and medium formats dominate unit economics while extra-large configurations capture per-unit value premiums.
- Small:Single-serve beverage and travel-size personal care formats maximize retail shelf density. Minya and Assiut governorates show expanding demand for portion-controlled household chemical packaging. Lightweighting targets concentrate development engineering on sub-500ml structures.
- Medium:Standard household and personal care volumes balance logistics efficiency with consumer handling convenience. Alexandria's export-oriented converters optimize pallet configurations around 500ml to 2L dimensional standards.
- Large:Family-size beverage and bulk household product formats reduce per-liter packaging cost for price-sensitive segments.
- Extra Large:Institutional and industrial refill containers occupy low-frequency, high-value channels with specialized stacking load requirements.
Medium sizes lead unit economics. Small formats are expanding most quickly.
Closure Type:
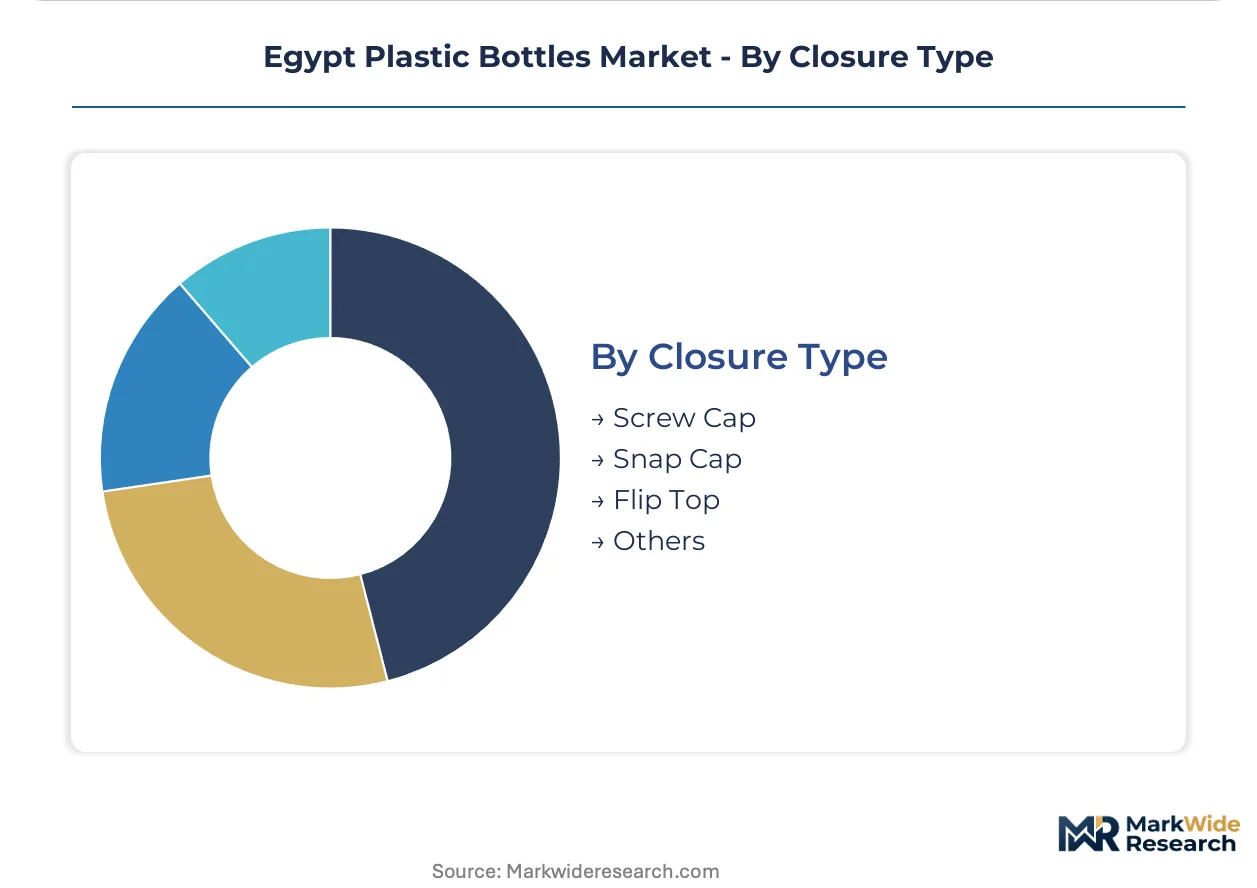
Functionality requirements separate commodity screw applications from premium dispensing configurations.
- Screw Cap:Standard threaded closures dominate beverage and chemical applications where resealability is primary. Cairo-based converters maintain captive cap molding to control supply security. Tamper-evident band integration is standard for food-contact compliance.
- Snap Cap:Push-fit closures serve single-serve beverage and sample-size personal care where opening convenience outweighs reseal demand.
- Flip Top:Hinged dispensing closures command premium positioning in shampoo and conditioner segments. Personal care brand owners specify flip-top configurations for bathroom-counter differentiation.
- Others:Pump dispensers, trigger sprayers, and specialized metering closures serve niche personal care and chemical application requirements.
Screw cap maintains volume leadership. Flip top is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Cairo's manufacturing corridor anchors Egyptian plastic bottle production, with Alexandria's port-linked packaging zones and Upper Egypt's emerging collection networks completing the national supply architecture. Sub-regional specialization concentrates resin conversion, beverage bottling, and recycling infrastructure across distinct geographic nodes.
Greater Cairo
Multinational beverage bottlers and captive preform operations cluster across Cairo, Giza, and Qalyubia governorates. Law 202/2020 enforcement intensity tightens compliance timelines for converters serving household chemical distributors. 10th of Ramadan City's CNC machining hubs enable rapid mold qualification cycles under eight weeks for personal care brands.
Alexandria and the Delta
Port-linked packaging zones leverage bonded warehousing efficiencies for export-oriented personal care brands targeting North African distribution. Barrier-enhanced PET with plasma-deposited silicon oxide coatings concentrates in Alexandria's bottling corridors for carbonated soft drink exports. The Ministry of Environment deploys mobile inspection units to Delta region converters, escalating extended producer responsibility fee collection.
Upper Egypt
Minya and Assiut governorates present underdeveloped post-consumer bale networks for integrated recycler-processor joint ventures. HDPE household chemical packaging dominates local processor configurations where visual clarity requirements remain secondary. Domestic rPET food-grade capacity gaps force Upper Egypt processors into long-haul logistics dependencies on Cairo and Alexandria purification clusters.
Suez Canal Zone
Free zone incentives attract resin import and re-export operations serving Red Sea shipping corridors. Industrial chemical containment applications concentrate in Port Said and Ismailia sub-regions requiring UN certification compliance. The zone's customs efficiencies support bulk HDPE procurement for chemical distributors operating across Sinai and eastern Delta networks.
Egypt Plastic Bottles Market Competitive Landscape
Global majors compete with regional champions across technology licensing and captive recycling certification dimensions. The vendor base stratifies into three tiers: multinational converters with integrated rPET purification, mid-tier domestic specialists with dedicated resin lines, and speed-to-market players with localized mold fabrication capabilities. Dominant competitive moves include strategic partnerships for flake supply security and capacity expansion into Upper Egypt collection infrastructure.
Among Austrian-headquartered industrial packaging specialists, Alpla Group exemplifies multinational scale archetypes with captive preform capacity serving North African beverage clients. Egyptian mid-tier specialists Raya Plastics and NatPack occupy distinct positioning vectors—Raya anchors household chemical distribution through dedicated HDPE configurations, while NatPack represents speed-to-market players with localized mold fabrication serving personal care brand refresh cycles. These three entities illustrate the competitive spectrum spanning global integration, resin specialization, and agile production.
| Leading Market Players |
|---|
| Alpla Group |
| Raya Plastics |
| NatPack |
| Master PET |
| New Delta Plastic |
| PET For Packaging Materials Egypt |
| Aquah Group |
| Hyma Plastic Group |
| Plastic Home Group |
| Others |
Pricing and Supply Chain Analysis
Polymer engineering expertise concentrated in Cairo and Alexandria governs labor-cost differentials that widen pricing-tier spreads between premium rPET-certified converters and commodity-grade processors serving Upper Egypt's household chemical distributors.
Pricing Analysis
Input-cost pass-through from naphtha-linked virgin PET volatility compresses margins for converters without captive flake purification. Pricing stratifies across premium, standard, and economy tiers based on rPET certification grade and volume scale. Cost compression in the standard tier is intensifying because Upper Egypt processors face long-haul logistics dependencies on Cairo-Alexandria purification clusters. Brand owners in the beverage segment demonstrate least price sensitivity, while household chemical distributors in Minya and Assiut governorates exhibit highest price sensitivity due to thin margin pools in bleach and detergent applications.
Supply Chain Analysis
Single-source vulnerability sits with European purification technology licensors supplying Cairo and Alexandria's rPET food-grade capacity. Raw material dependencies rest on Saudi Arabian and UAE resin imports, domestic naphtha derivatives from Alexandria's refining complex, and baled post-consumer flake from informal collection networks. Tariff exposure on European extrusion equipment escalates capital costs for capacity expansion. Distribution runs through bonded warehousing in Alexandria's port-linked zones for export-oriented personal care brands, with direct truckload delivery to Greater Cairo's manufacturing corridor for beverage bottlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's plastic bottles market reads as a late-cycle quality story, justified by beverage bottlers' accelerating demand-shift toward barrier-enhanced PET with plasma-deposited silicon oxide coatings for export-bound carbonated soft drinks.
For Market Incumbents: Deploy captive recycling certification as a defensive lever against Law 202/2020 compliance cost escalation. Alpla Group and Raya Plastics should consolidate supplier relationships with household chemical distributors seeking to avoid extended producer responsibility fee scaling. Backward integration into Upper Egypt collection infrastructure in Minya and Assiut governorates secures feedstock independence from Cairo-Alexandria purification clusters. For New Entrants and Emerging Players: The premium-economy price-point gap in personal care packaging offers white-space entry for speed-to-market specialists. Target underdeveloped post-consumer bale networks in Upper Egypt through integrated recycler-processor joint ventures. Pursue dual-color injection molding capabilities to serve shampoo and conditioner brands demanding sub-eight-week mold qualification cycles without secondary decoration investment. For Investors and Strategic Acquirers: Multinational beverage converters with North African export mandates are the most active acquirer in this space. The five-to-ten-year viability window favors targets with EOS food-contact compliance certification enabling Sub-Saharan African export pathways. Acquisition target archetype: mid-tier domestic specialists with dedicated HDPE lines and localized CNC machining clusters. Watch for inflection when domestic flake purification capacity expansion crosses threshold to eliminate baled post-consumer import dependencies.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Purification Capacity Expansion | EOS certification timelines bottleneck new resin qualification, rewarding early capacity builders in Greater Cairo. |
| Upper Egypt Collection Infrastructure | Integrated joint ventures in Minya and Assiut capture first-mover advantages in underdeveloped bale networks. |
| Barrier-Enhanced PET Technology Licensing | Plasma-deposited silicon oxide coatings unify gas barrier and lightweighting for Alexandria's export bottlers. |
| Dual-Color Injection Molding Adoption | 10th of Ramadan City CNC machining hubs enable premium personal care differentiation without secondary decoration. |
| Extended Producer Responsibility Compliance | Law 202/2020 enforcement intensity outside Cairo diverts investment toward bottle-to-bottle recycling systems. |
Research Methodology
Direct dialogue with plant managers at Cairo-Alexandria converters, procurement leads at multinational beverage bottlers, distribution channel partners in the Delta region, and technical R&D directors at rPET purification facilities grounded qualitative insights. Secondary validation drew from Egyptian Organization for Standardization and Quality certification records, Ministry of Environment enforcement disclosures, customs/trade data on resin imports, and SEC filings of multinational packaging parents. Bottom-up unit economics modeling triangulated with top-down market sizing across resin chemistry, application, and regional production hub dimensions.
Segmented outputs across the analysis window reflect discrete modeling of PET, HDPE, LDPE, and PVC resin chemistries; beverage, personal care, household products, and chemicals applications; and Greater Cairo, Alexandria-Delta, Upper Egypt, and Suez Canal Zone regional clusters. CAGRs were derived from elasticity-adjusted demand projections incorporating carbonated soft drink filling line expansion, Law 202/2020 compliance cost pass-through, and rPET flake price stabilization trajectories.
Caveats apply where Ministry of Environment enforcement intensity variations, naphtha price volatility spikes, or European purification equipment import tariff shifts could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Post-Consumer Recycled Plastic Packaging Market
Plastic Packaging
Plastic Liners Market
Plastic Packaging
Egypt Plastic Packaging Market
Plastic Packaging
Plastic Bottles and Containers Market
Plastic Packaging
Thailand Rigid Plastic Packaging Market
Plastic Packaging
Mexico Plastic Packaging Market
Plastic Packaging
PET Preforms Market
Plastic Packaging
Latin America Plastic Bottles Market
Plastic Packaging
Global Plastic Straps Market
Plastic Packaging
Vacuum Forming Plastic Market
Plastic Packaging
Clear Plastic Boxes Market
Plastic Packaging
Malaysia and Thailand Thermoformed Plastic Market
Plastic Packaging
Saudi Arabia Plastic Packaging Market
Plastic Packaging
Plastic Canister Market
Plastic Packaging
Global Single Use Plastic Packaging Market
Plastic Packaging
Middle East and Africa Single-Use Plastic Packaging Market