
 Saudi Arabia Plastic Packaging Market | 2026-2036
Saudi Arabia Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Plastic Packaging Market Outlook
Aftermarket recycling and reprocessing revenue is tilting toward domestic resin compounders as virgin polymer import costs fluctuate. Napco National leverages its integrated film-to-bag manufacturing footprint across Dammam and Jeddah to capture this margin pool. Takween Advanced Industries anchors its position through advanced polyethylene terephthalate sheet extrusion for thermoformed food trays. Zamil Plastic Industries Co. competes on scale in injection-molded industrial pails and drums for the petrochemical sector.
Saudi Arabia plastic packaging encompasses thermoformed, extruded, blow-molded, and injection-molded polymer structures typically ranging from 0.01 mm flexible films to 5 mm rigid containers, engineered to protect, preserve, and distribute consumer and industrial goods. Its primary commercial purpose centers on extending shelf stability for perishables while reducing transportation damage in high-temperature climates. Films dominate flexible food wrapping applications where barrier properties against oxygen and moisture determine material selection. Rigid containers lead in dairy and edible oil segments where stack strength and chemical resistance are non-negotiable. The biodegradable packaging type remains nascent but draws pilot investment as SFDA consults on compostability labeling standards.
SFDA polymer contact regulations, SASO technical regulations for plastic products, and GSO harmonized Gulf standards collectively govern resin grades, migration limits, and recyclate content claims across the Kingdom. These frameworks shape demand by disqualifying uncertified imports and incentivizing local testing laboratory partnerships. The EU Green Deal's extraterritorial carbon-border adjustments are beginning to influence Saudi exporters' packaging specifications for European-bound goods. Stakeholders must monitor whether Riyadh adopts extended producer responsibility mechanisms that would restructure collection infrastructure economics.
Market Dynamics
Saudi Arabia's plastic packaging sector is experiencing concentrated demand pressure along the Riyadh-Jeddah corridor, where mega-project construction and retail modernization are accelerating procurement cycles for both flexible films and rigid containers.
Growth Catalysts
- SFDA polymer contact-material rules:The Saudi Food and Drug Authority's updated compliance thresholds for imported resin formulations are disqualifying uncertified imports and redirecting procurement toward domestic testing laboratory partnerships.
- Cold-chain packaging procurement:Food and beverage processors are expanding temperature-controlled packaging volumes across the Kingdom to serve modern retail formats and quick-service restaurant networks.
- Dammam-Jeddah manufacturing corridor:Integrated film-to-bag production clusters are capturing margin pools from aftermarket recycling and reprocessing as virgin polymer import costs fluctuate.
Market Restraints
- Petrochemical feedstock volatility:Ethylene and propylene price swings from regional crackers in Jubail Industrial City transmit directly into polyethylene and polypropylene film cost structures.
- Import dependency for specialty resins:Barrier-grade ethylene vinyl alcohol and polyamide formulations concentrate supply risk with Asian and European compounders.
- Biodegradable performance limitations:Compostable polylactic acid and polyhydroxyalkanoate materials face heat-deflection and moisture-barrier constraints that limit adoption in ambient dairy applications.
Strategic Opportunities
- Eastern Province industrial zone expansion:Ras Al-Khair and Jubail petrochemical complexes offer captive feedstock access for backward-integrated packaging film production.
- SASO recyclate content verification:The Saudi Standards, Metrology and Quality Organization's emerging technical regulations for recycled polymer claims create first-mover positioning for domestic reprocessing infrastructure.
- Neom project construction logistics:Bulk industrial pails, drums, and intermediate bulk container demand from linear city infrastructure builds represents a multi-year procurement window.
Industry Challenges
- Migration testing laboratory capacity:SFDA compliance requires specific extractables and leachables protocols that strain available certified testing facilities in Riyadh and Jeddah.
- Multi-layer film delamination:Mechanical recycling of polyethylene-polyamide-ethylene vinyl alcohol laminates demands capital-intensive separation equipment that few domestic operators possess.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Plastic Packaging Market |
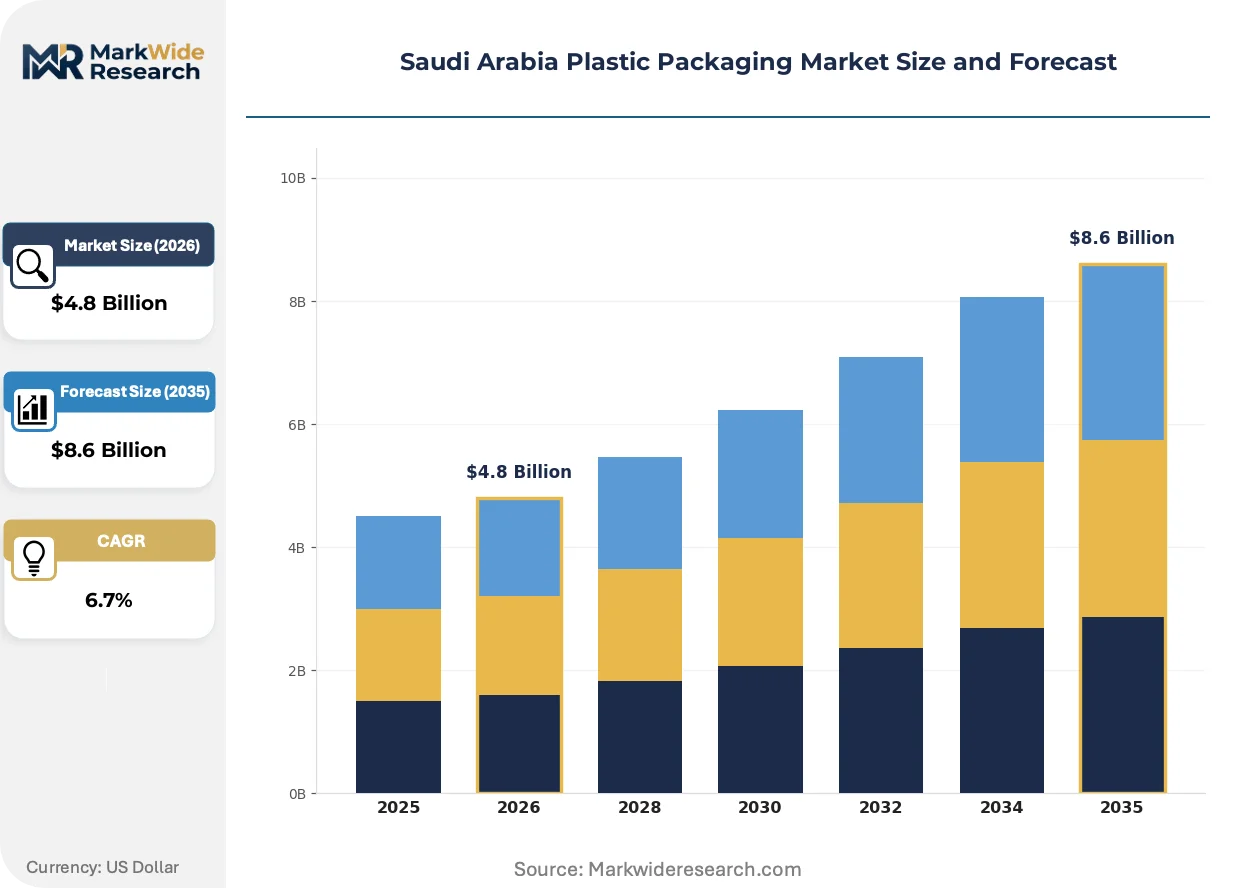
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Containers, Films, Bottles End Use Industry: Food & Beverage, Healthcare, Personal Care, Chemicals Form: Rigid, Flexible, Semi-Rigid, Blister Packaging Type: Single-Use, Reusable, Biodegradable, Multilayer |
| Companies Covered | Napco National, Takween Advanced Industries, National Plastic Factory, Arabian Plastic Industrial Company Limited, Zamil Plastic Industries Co., Sealed Air, Saudi Plastic Factory Co., Advanced Flexible Packaging Co., Obeikan Investment Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Plastic Packaging Market Strategic Shifts
Material science advances and regulatory tightening are converging to reshape specification standards across Saudi Arabia's packaging value chain, with particular intensity in food-contact and export-oriented segments.
Multi-layer coextrusion technology is hybridizing conventional polyethylene structures with bio-based barrier layers to meet emerging compostability benchmarks without sacrificing shelf-life performance. Dairy processors in the Central Region are piloting these formulations at commercial scale. The hybridizing approach is compressing the timeline for full petroleum-based material displacement in premium segments.
SFDA's polymer contact-material regulations are tightening migration limits for heavy metals and primary aromatic amines in imported resin grades. Domestic compounders are reformulating masterbatch additives to preempt disqualification. Thermoformed food tray manufacturers face the most immediate compliance recertification burden.
Consolidated buying by modern grocery chains is compressing supplier qualification cycles and unbundling technical service from material supply contracts. Traditional distributor networks in Jeddah and Dammam are losing share to direct mill relationships. Quick-service restaurant procurement teams are driving this pattern most aggressively.
Saudi Arabia Plastic Packaging Market Segmentation
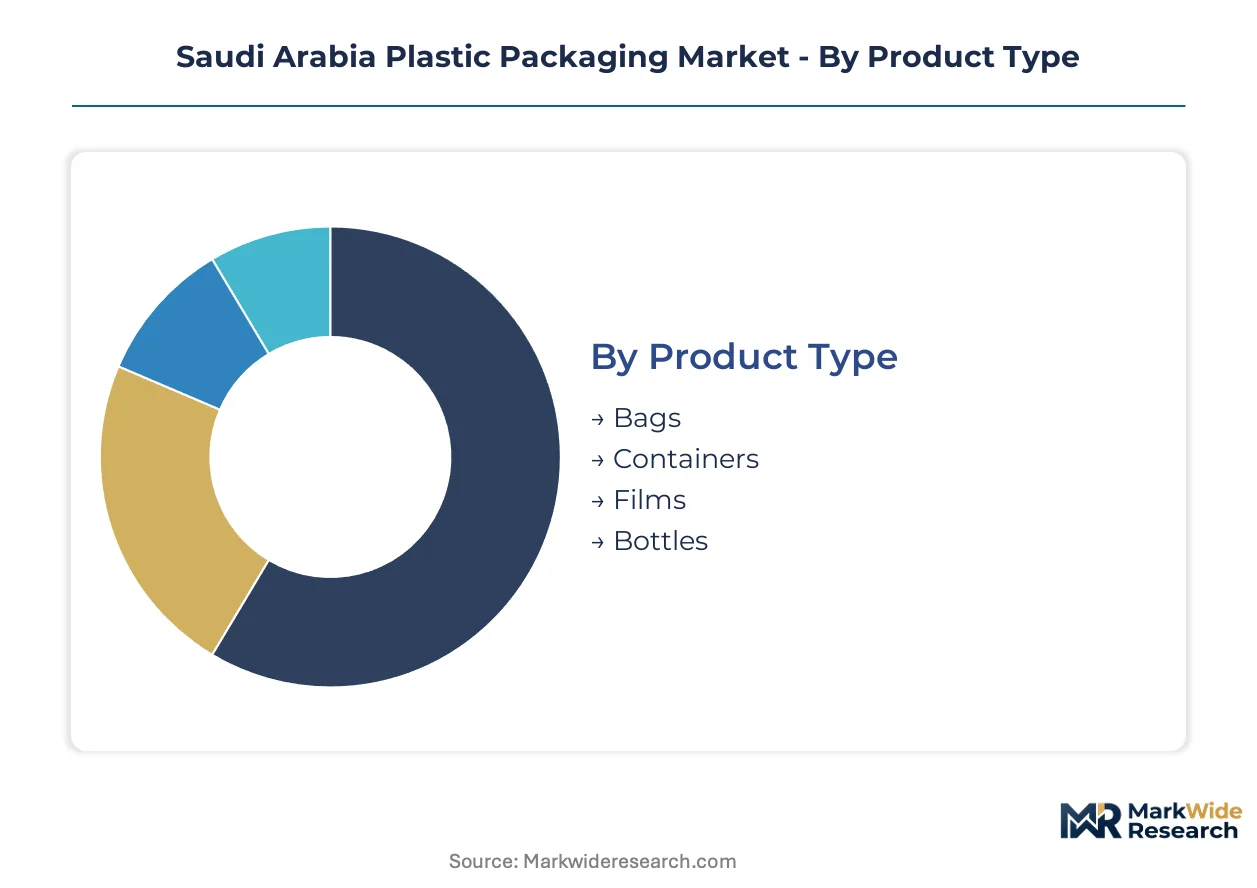
Segmentation in Saudi Arabia's plastic packaging market reveals how material specifications, regulatory compliance, and end-use performance requirements fragment procurement patterns across the Kingdom. Understanding these dimensions exposes where margin pools concentrate and where qualification barriers protect incumbent positions.
Product Type:
Cost tier differentiation across product categories determines resin grade selection, conversion technology investment, and customer switching economics.
- Bags:Polyethylene and polypropylene film structures dominate flexible retail and industrial applications. Demand concentrates in the Dammam-Jeddah corridor where integrated film-to-bag producers capture aftermarket recycling margins from fluctuating virgin polymer import costs.
- Films:Multi-layer coextruded barrier films ranging from 0.01 mm to 0.5 mm thickness serve food wrapping and protective packaging. Riyadh-based dairy processors are driving specification upgrades for oxygen and moisture barrier performance in ambient distribution.
- Containers:Injection-molded and thermoformed rigid structures provide stack strength for chemical and food applications.
- Bottles:Blow-molded polyethylene terephthalate and high-density polyethylene formats serve beverage and edible oil segments.
Bags command the established base. The steepest expansion runs through Films.
End Use Industry:
Application-specific compliance requirements create distinct qualification moats that reshape competitive positioning across customer verticals.
- Food & Beverage:SFDA polymer contact-material regulations impose migration limits for heavy metals and primary aromatic amines. Thermoformed tray manufacturers face immediate recertification burdens as the authority tightens thresholds for imported resin formulations.
- Chemicals:Industrial pails, drums, and intermediate bulk containers demand chemical resistance and UN certification for hazardous material transport. Neom project construction logistics are generating multi-year procurement windows for bulk packaging in the Eastern Province.
- Healthcare:Sterile barrier systems and pharmaceutical primary packaging require extractables and leachables testing protocols.
- Personal Care:Aesthetic surface finish and fragrance barrier properties drive material selection in cosmetics and hygiene applications.
Food & Beverage commands the established base. Chemicals shows the steepest expansion trajectory.
Form:
Volume throughput and capital intensity separate form categories, with rigid formats demanding higher fixed investment but capturing premium pricing in protected segments.
- Rigid:Thick-walled structures from 1 mm to 5 mm provide structural integrity for dairy and edible oil distribution. Stack strength requirements in high-temperature climates make rigid containers non-substitutable for ambient liquid storage.
- Flexible:Thin-gauge films and pouches reduce material weight and transportation cost. Quick-service restaurant procurement teams are compressing supplier qualification cycles and unbundling technical service from material supply contracts.
- Semi-Rigid:Thermoformed trays and clamshells balance protection with material efficiency.
- Blister:Form-fill-seal configurations serve unit-dose pharmaceutical and consumer goods applications.
Rigid commands the established base. Flexible gains share fastest through retail modernization.
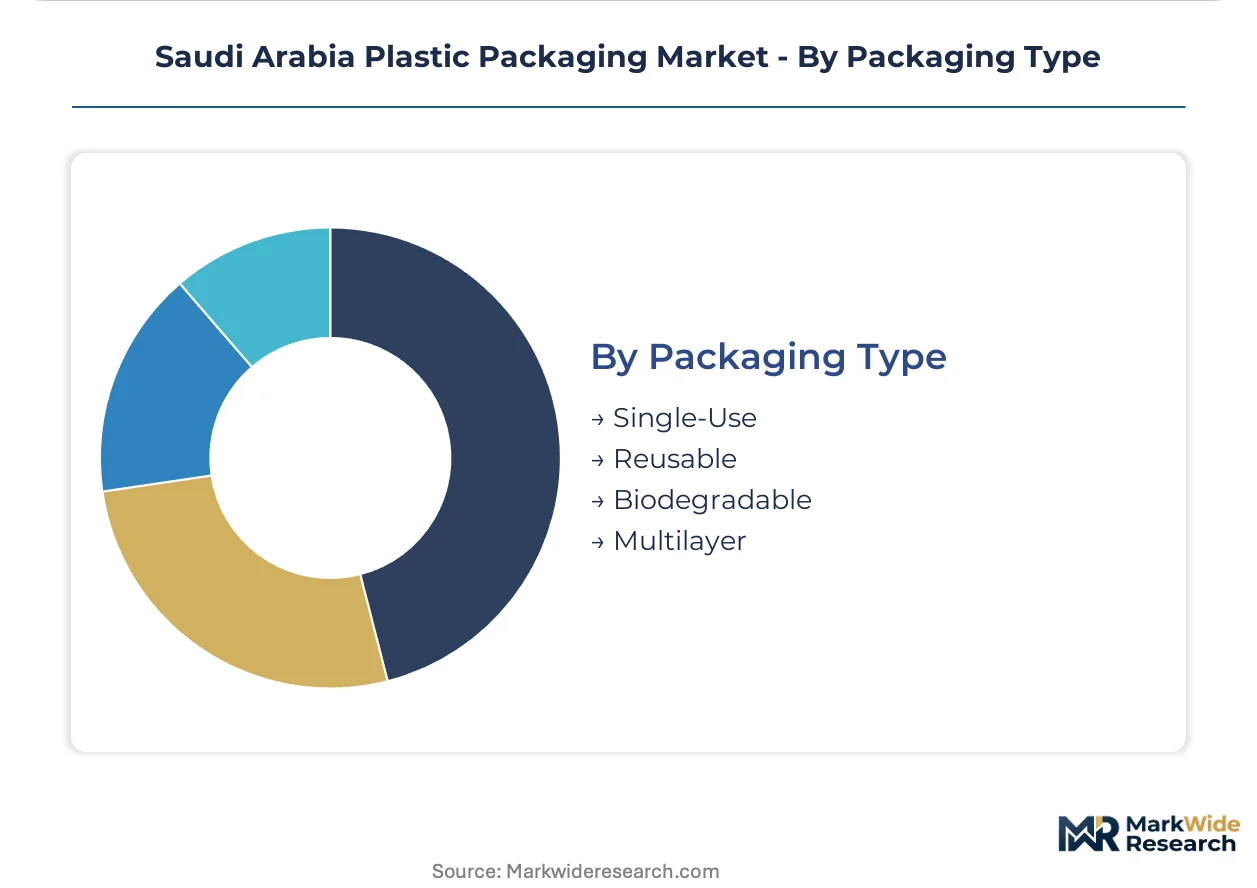
Packaging Type:
Customer type and sustainability positioning split procurement patterns, with regulatory pressure accelerating segmentation between conventional and next-generation formats.
- Single-Use:Conventional polyethylene and polypropylene formats serve cost-sensitive mass retail and foodservice applications. Modern grocery chain consolidation is redirecting volume toward direct mill relationships and away from traditional Jeddah and Dammam distributor networks.
- Multilayer:Coextruded polyethylene-polyamide-ethylene vinyl alcohol structures deliver barrier performance for extended shelf life. Mechanical recycling challenges from delamination strain domestic reprocessing capacity.
- Reusable:Returnable intermediate bulk containers and palletized systems serve closed-loop industrial logistics.
- Biodegradable:Polylactic acid and polyhydroxyalkanoate formulations face heat-deflection and moisture-barrier constraints that limit ambient dairy adoption. SFDA compostability labeling consultations are drawing pilot investment despite performance limitations.
Single-Use commands the established base. Multilayer climbs the fastest on barrier specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's regional consumption mix diverges sharply from neighboring Gulf economies, with Riyadh-Jeddah corridor demand concentrated in food-contact flexible films and Eastern Province procurement weighted toward industrial rigid containers for petrochemical logistics.
Riyadh
Central Region dairy processors drive specification upgrades for oxygen-barrier films in ambient distribution. SFDA polymer contact-material regulations impose immediate recertification burdens on thermoformed tray manufacturers sourcing imported resin grades. Riyadh-based testing laboratory partnerships are capturing compliance service revenue as migration protocol requirements tighten.
Eastern Province
Jubail Industrial City petrochemical complexes supply captive ethylene and propylene feedstock for backward-integrated film production. Ras Al-Khair construction logistics generate multi-year procurement windows for bulk industrial pails and intermediate bulk containers. Dammam manufacturing clusters capture aftermarket recycling margins from fluctuating virgin polymer import costs.
Western Region
Jeddah retail modernization accelerates flexible packaging procurement for quick-service restaurant networks and modern grocery chains. Traditional distributor networks lose share to direct mill relationships as consolidated buying compresses supplier qualification cycles. Red Sea port infrastructure positions the region for re-export packaging demand to African markets.
NEOM Northwest
Linear city construction generates sustained demand for bulk chemical-resistant containers and protective films in high-temperature climates. Giga-project logistics favor suppliers with integrated manufacturing footprints spanning Dammam-Jeddah corridors. Emerging compostability labeling consultations draw pilot investment despite biodegradable material performance constraints.
Saudi Arabia Plastic Packaging Market Competitive Environment
Capability concentration sits with integrated compounders possessing captive resin access; scale advantage sits with diversified converters operating multi-technology platforms. The vendor base organizes around three strategic archetypes: petrochemical-backed integrated producers, specialized food-contact compounders, and regional distribution-led converters. Dominant competitive moves include backward integration into resin compounding and geographic expansion along the Riyadh-Jeddah corridor.
Among Saudi-based integrated manufacturers, Napco National, Takween Advanced Industries, and Zamil Plastic Industries Co. exemplify distinct positioning archetypes. Napco National represents the integrated film-to-bag model with manufacturing presence across Dammam and Jeddah. Takween Advanced Industries anchors the advanced sheet extrusion segment for thermoformed applications. Zamil Plastic Industries Co. occupies the industrial rigid container tier serving petrochemical sector procurement.
| Leading Market Players |
|---|
| Napco National |
| Takween Advanced Industries |
| National Plastic Factory |
| Arabian Plastic Industrial Company Limited |
| Zamil Plastic Industries Co. |
| Sealed Air |
| Saudi Plastic Factory Co. |
| Advanced Flexible Packaging Co. |
| Obeikan Investment Group |
| Others |
Value Chain & Pricing Dynamics
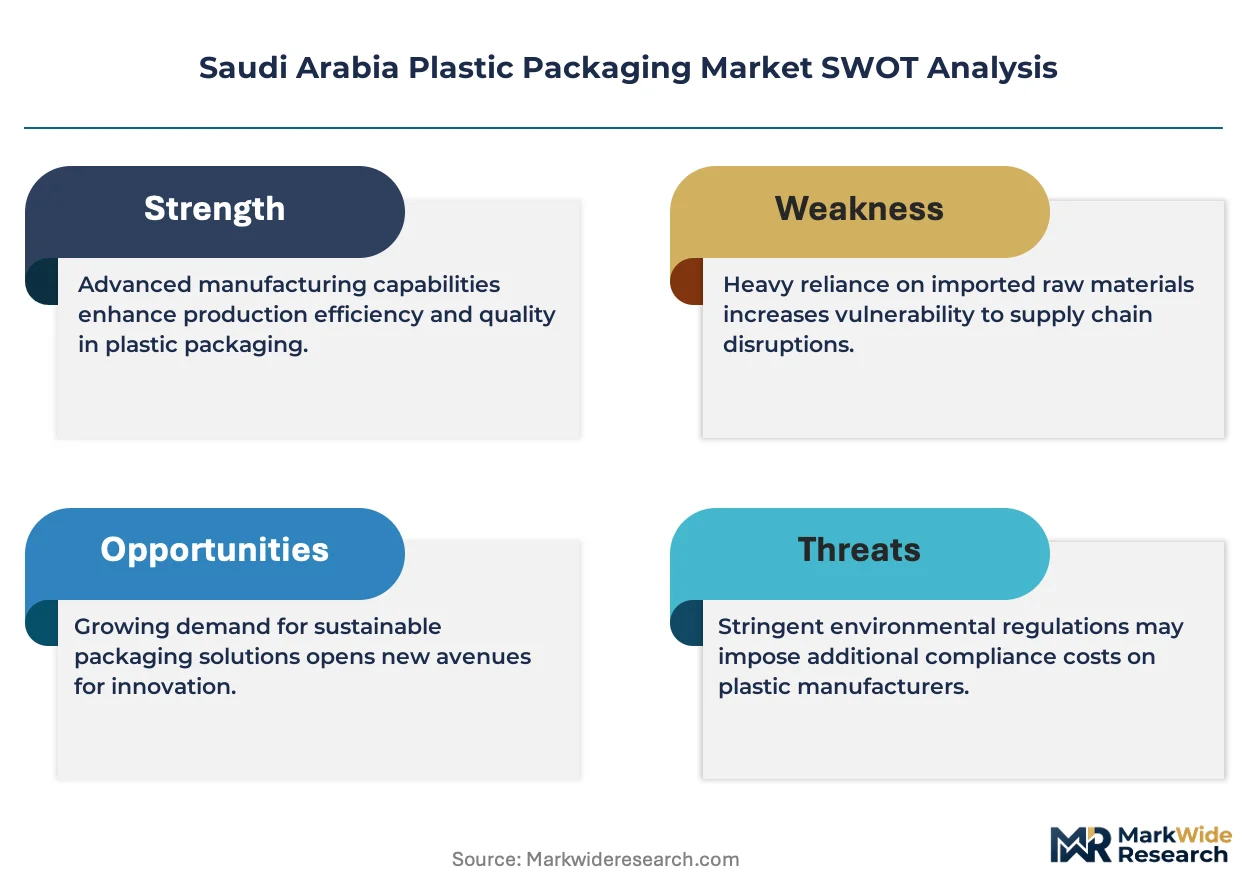
Undercapacity in SFDA-certified migration testing laboratories across Riyadh and Jeddah compresses supplier qualification timelines, granting domestic compounders pricing leverage over importers facing extended compliance delays. This utilization squeeze feeds directly into contract negotiation posture, with local resin formulators commanding premium positioning against Asian and European competitors.
Pricing Analysis
Long-term offtake agreements dominate procurement between integrated film producers and petrochemical sector buyers, while spot market exposure concentrates among smaller converters serving fragmented foodservice accounts. Three-tier pricing structure across premium, standard, and economy levels separates SFDA-certified food-contact grades from industrial pail formulations and generic polyethylene film. Cost compression in flexible packaging is intensifying because quick-service restaurant procurement teams are consolidating supplier panels and unbundling technical service. Food and beverage processors show the least price sensitivity given compliance recertification burdens, whereas commodity industrial drum buyers negotiate aggressively on volume.
Supply Chain Analysis
Export-control regimes on advanced barrier-grade ethylene vinyl alcohol and polyamide formulations limit resin flows from European and Japanese compounders into Saudi Arabia, concentrating specialty supply with South Korean and Singaporean sources. Domestic production draws from captive ethylene and propylene feedstock at Jubail Industrial City, while barrier film structures rest on imported ethylene vinyl alcohol, polyamide, and specialty masterbatch additives. Single-source vulnerability runs through Asian specialty resin compounders for oxygen-barrier dairy applications. Distribution runs through direct mill relationships with modern grocery chains, bypassing traditional Jeddah and Dammam distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's plastic packaging sector operates as a substitution defense against biodegradable material encroachment, as polylactic acid and polyhydroxyalkanoate performance limitations in high-temperature climates protect incumbent petroleum-based positions.
For Market Incumbents: Insulate food-contact certification moats by deepening backward integration into resin compounding at Ras Al-Khair and Jubail complexes, while expanding Riyadh-Jeddah laboratory partnerships to capture SFDA compliance service revenue from import-dependent competitors facing disqualification risk. For New Entrants and Emerging Players: Pursue biodegradable packaging pilot contracts with NEOM project logistics teams seeking compostability credentials for European-bound construction materials, leveraging the gap between labeling consultation momentum and material performance constraints in ambient dairy applications. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated film-to-bag manufacturers with captive feedstock access and multi-year petrochemical sector offtake agreements. Long-term viability centers on compounders positioned for SASO recyclate content verification infrastructure. Watch SFDA extended producer responsibility adoption as the signal forcing collection infrastructure economics restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive ethylene access at Jubail Industrial City insulates margin from import cost volatility. |
| SFDA Testing Laboratory Partnership | Riyadh-Jeddah certified facilities capture compliance service revenue from disqualified imports. |
| Multi-Layer Coextrusion Technology Investment | Hybrid bio-based barrier layers compress petroleum displacement timeline in premium dairy segments. |
| Direct Mill Relationship Expansion | Bypassing Dammam distributor networks aligns with quick-service restaurant procurement consolidation. |
| Recyclate Content Verification Infrastructure | SASO emerging standards create first-mover positioning for domestic reprocessing economics. |
Study Parameters
Cross-validation between primary interviews with resin procurement managers, thermoforming plant engineers, and SFDA regulatory affairs specialists anchors the qualitative findings against secondary validation through SASO technical regulation filings, Saudi Customs polymer trade data, and petrochemical sector capex disclosures. Bottom-up demand modeling triangulates against top-down value-chain analysis.
Calibration against historical polymer price elasticity and capacity utilization patterns at Jubail Industrial City refinements shapes the analytical framework across the analysis window. Segmentation dimensions include packaging form, end-use industry vertical, barrier performance tier, and regional production hub. CAGRs derive from trend extrapolation moderated by regulatory adoption curves and feedstock cost projection inputs.
Macroeconomic conditions sit as an overlay; deviation in ethylene-propylene spreads, SFDA enforcement intensity, or European carbon-border adjustment implementation would shift the trajectory. Material shifts in biodegradable material heat-deflection breakthroughs or extended producer responsibility mandate timing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Indonesia Plastic Food Tray Market
Plastic Packaging
Cast Films Market
Plastic Packaging
Italy Plastic Bottles Market
Plastic Packaging
Plastic Packaging Market
Plastic Packaging
Middle East and Africa Plastic Packaging Market
Plastic Packaging
Sugarcane Based PET Bottles Market
Plastic Packaging
Plastic Tubes Market
Plastic Packaging
Poland Plastic Bottles Market
Plastic Packaging
Europe Plastic Packaging Market
Plastic Packaging
Packaging Industry in South Africa Market
Plastic Packaging
CPET Trays Market
Plastic Packaging
Low Density Polyethylene (LDPE) Packaging Market
Plastic Packaging
PE Blow Molded Products Market
Plastic Packaging
PCR Bottles Market
Plastic Packaging
Asia-Pacific Plastic Bottles and Containers Market
Plastic Packaging
GCC PET Packaging Market