
 Plastic Battery Containers Market | 2026-2036
Plastic Battery Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Battery Containers Market Intelligence
China's polymer compounding corridor is reshaping supply dynamics for engineered battery housings. Graham Packaging Company leverages blow-molding scale to serve automotive OEMs with large-format lead acid enclosures. Greiner Packaging anchors European demand through injection-molded polypropylene lines certified for lithium-ion thermal runaway containment. BASF SE differentiates via flame-retardant ABS formulations that meet OEM material specifications without metal inserts.
Plastic battery containers are structural enclosures fabricated from thermoplastic resins—typically polypropylene, polyethylene, or ABS—designed to isolate electrochemical cells from mechanical stress, thermal excursion, and environmental ingress, with wall thicknesses and venting geometries tuned to cell chemistry. Injection molding dominates high-volume production for lithium-ion formats requiring dimensional precision and integrated cooling channels, while blow molding retains cost advantages for vented lead acid designs. Lead acid containers occupy mature replacement demand in automotive starter battery aftermarket channels, whereas lithium-ion housings capture margin pools tied to EV platform qualification cycles. Polypropylene leads material selection for its chemical resistance and weldability in thermal management assemblies.
EPA hazardous waste rules and NHTSA crashworthiness protocols in the United States, alongside REACH substance restrictions and EU Battery Regulation due diligence frameworks in Europe, are elevating recyclability and flame-retardant testing requirements for container suppliers. China's GB standards and MIIT new energy vehicle technical conditions mandate structural integrity thresholds that favor reinforced polymer grades over commodity plastics. Stakeholders must monitor evolving cell-to-pack architectures that may eliminate discrete container demand or shift specifications toward integrated structural battery housing resins.
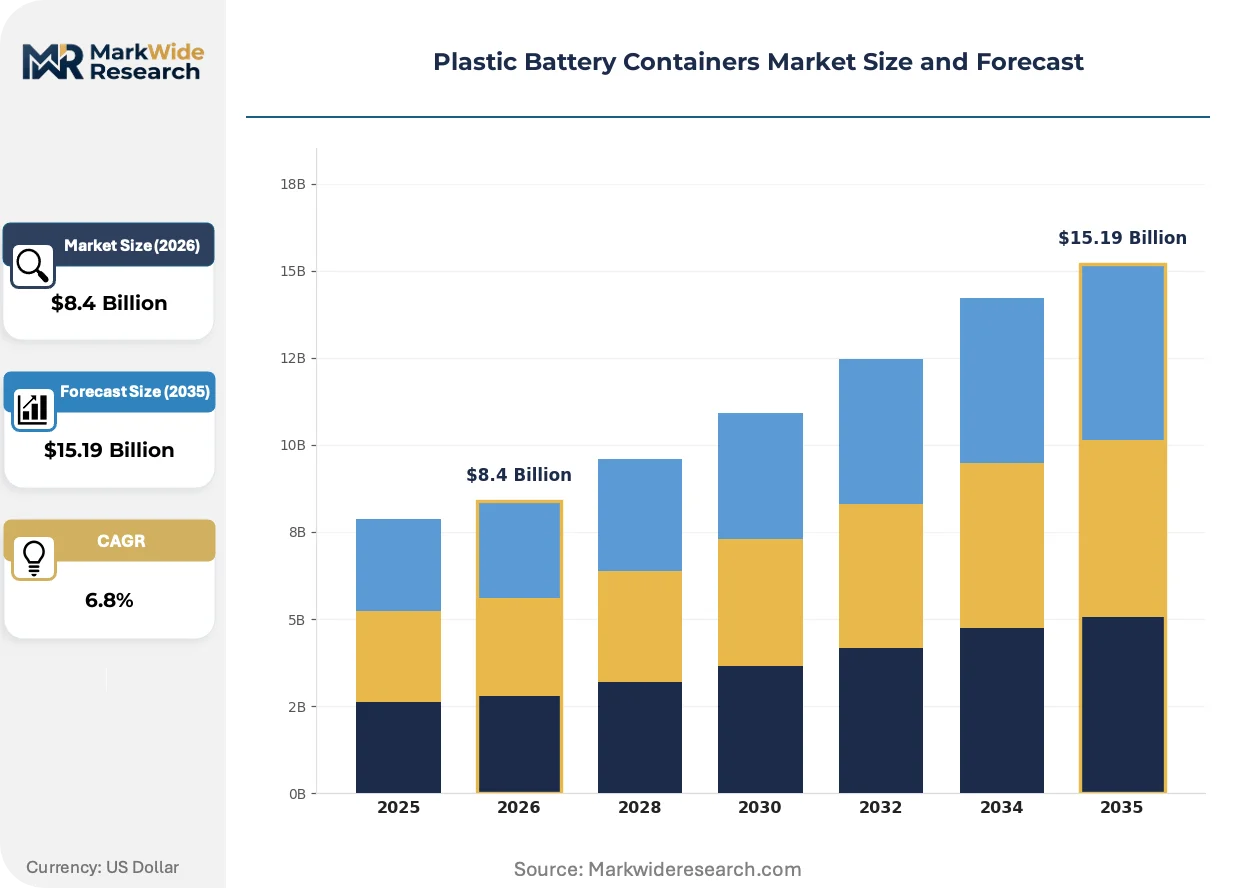
Market Dynamics
Cell-to-pack architectures are compressing discrete container demand as EV platforms integrate structural battery housings directly into chassis assemblies, forcing suppliers to pivot toward thermal management-integrated resin systems or risk disintermediation.
Growth Catalysts
- EU Battery Regulation due diligence:Mandatory recyclability and carbon footprint disclosure requirements are accelerating procurement of flame-retardant polypropylene grades certified for closed-loop recovery.
- China's MIIT new energy vehicle technical conditions:Structural integrity mandates favor reinforced polymer housings over commodity plastics in domestic EV production corridors.
- Lead acid aftermarket replacement cycles:Mature automotive starter battery channels sustain blow-molded polyethylene demand across independent repair networks and fleet maintenance operations.
Market Restraints
- Flame-retardant additive cost volatility:Phosphorus and halogen-based compound prices fluctuate with mining output and environmental compliance costs, squeezing compounder margins.
- Injection molding capacity concentration:High-precision lithium-ion housing production clusters in Germany and China create geographic supply vulnerability for qualified automotive programs.
- Metal housing substitution in heavy-duty applications:Steel and aluminum enclosures retain thermal runaway containment advantages in commercial vehicle and stationary storage formats above 100 kWh.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cell manufacturing:Domestic battery production incentives are attracting polymer compounding investments for localized housing supply to emerging gigafactory clusters.
- Solid-state battery thermal management convergence:Integration of phase-change materials within injection-molded channels opens premium specification tiers for next-generation cell formats.
- Direct OEM contracting models:Bypassing tiered automotive supplier hierarchies through platform-level qualification allows compounders to capture value from material specification ownership.
Industry Challenges
- Multi-standard certification timelines:Simultaneous UL 94 V-0, GB/T, and ECE R100 testing protocols extend product qualification cycles by 18-24 months for global automotive programs.
- Recyclate quality inconsistency:Post-consumer polypropylene feedstock variability complicates flame-retardant recompounding for battery-grade specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Battery Containers Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead Acid, Lithium-ion, Nickel Cadmium, Others End User: Automotive, Consumer Electronics, Telecommunications, Renewable Energy Material: Polyethylene, Polypropylene, ABS, PVC Manufacturing Stage: Injection Molding, Extrusion, Blow Molding, Thermoforming |
| Companies Covered | Graham Packaging Company, Greiner Packaging, Plastipak Holdings, Inc., LyondellBasell Industries N.V., BASF SE, ALPLA, Berry Global Inc., SABIC, Amcor Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Battery Containers Market Strategic Shifts & Innovations
Material science advances and regulatory tightening are converging to redefine performance benchmarks for electrochemical containment systems across mobility and stationary applications.
In-mold labeling with embedded thermal sensors is rendering obsolete post-assembly sensor mounting in premium EV battery housings. Automotive OEMs in Germany and South Korea are qualifying these smart-container prototypes for 2026 platform launches. The integration eliminates secondary adhesive bonding steps while enabling real-time cell monitoring through resin-embedded conductive traces.
REACH substance restrictions on halogenated flame retardants are compelling reformulation toward phosphorus-nitrogen synergists in European-bound polypropylene grades. Compounders must retest full material property suites under ECHA notification timelines. Battery producers serving EU markets are dual-sourcing legacy and next-generation formulations to manage transition risk.
Cell manufacturers are consolidating housing procurement under single-source material specifications rather than discrete component purchasing. Tier-1 automotive suppliers face margin compression as compounders negotiate directly with CATL, BYD, and LG Energy Solution for platform-level resin approvals. This disintermediation is most advanced in China's Yangtze River Delta battery corridor.
Plastic Battery Containers Market Segmentation
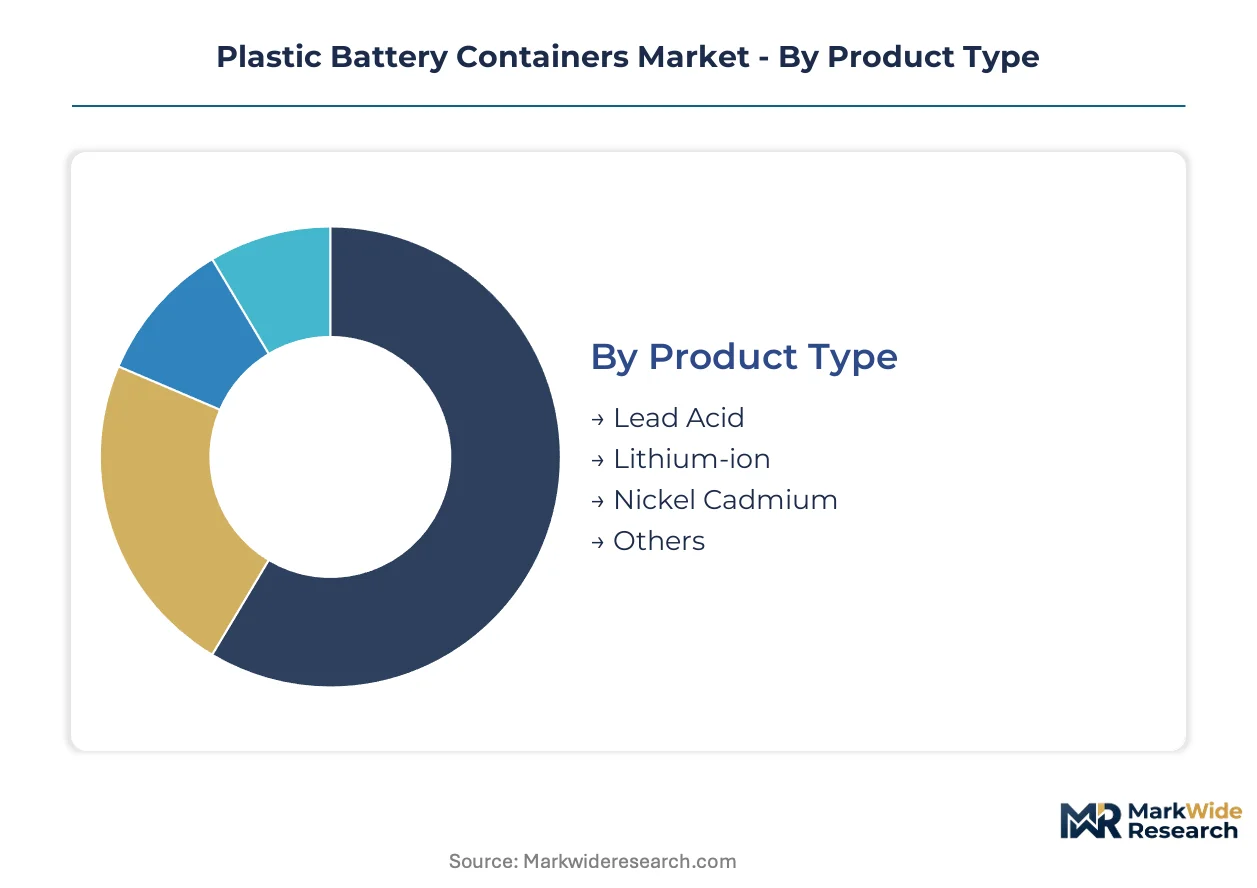
Segmentation in plastic battery containers reveals divergent procurement cycles across chemistries and manufacturing methods. Lead acid replacement channels turn inventory in months, while lithium-ion platform qualifications span years. Material selection and process technology determine which suppliers capture margin versus volume.
Product Type:
Lead acid containers cycle fastest through aftermarket channels, while lithium-ion qualifications lock in supply relationships for entire platform generations. Nickel cadmium retains niche military and aviation procurement with decade-long replacement horizons.
- Lead Acid:Blow-molded polyethylene enclosures dominate automotive starter battery aftermarket demand. Independent repair networks in the United States and Germany sustain high-volume procurement with limited specification variance. Replacement cycles compress inventory turns to under 90 days in mature markets.
- Lithium-ion:Injection-molded polypropylene and ABS housings require OEM platform qualification spanning 24-36 months. China's MIIT structural integrity mandates and NHTSA crashworthiness protocols in the United States elevate flame-retardant testing burdens. Cell-to-pack architectures threaten discrete container demand in premium EV segments.
- Nickel Cadmium:Specialized aviation and defense applications retain this chemistry despite environmental restrictions. REACH substance restrictions in Europe constrain new deployment outside exempted military procurement channels.
- Others:Emerging solid-state and sodium-ion formats drive experimental housing specifications. Phase-change material integration trials are underway in South Korean and Japanese pilot production lines.
Lead Acid dominates installed base. Lithium-ion is where expansion concentrates.
End User:
Automotive procurement stratifies across OEM platform supply and aftermarket replacement, while renewable energy installations concentrate demand in utility-scale procurement offices.
- Automotive:EV manufacturers in Germany and China specify thermal runaway containment grades with integrated cooling channels. Aftermarket starter battery demand flows through independent distributors with commodity polyethylene specifications.
- Consumer Electronics:Power tool and portable device manufacturers prioritize thin-wall injection molding for weight reduction. UL 94 V-0 certification gates access to North American retail channels.
- Telecommunications:Base station backup power in India and Southeast Asia sustains lead acid demand despite lithium-ion encroachment. Tower operators specify vented designs for tropical humidity exposure.
- Renewable Energy:Utility-scale solar and wind storage projects above 100 kWh favor metal housing alternatives for thermal containment. Sub-100 kWh residential installations drive reinforced polymer demand in California and Australian markets.
Automotive commands specification ownership. Renewable Energy is climbing the fastest for next-generation material trials.
Material:
Polypropylene captures volume leadership through weldability in thermal management assemblies, while ABS commands premium positioning in flame-retardant formulations.
- Polypropylene:Chemical resistance and ultrasonic weldability make this the default for lithium-ion cooling channel integration. REACH-compliant recyclate streams are qualifying for EU Battery Regulation closed-loop mandates.
- Polyethylene:Blow-molding compatibility and cost position sustain dominance in lead acid vented designs. Post-consumer recyclate variability complicates recompounding for battery-grade specifications.
- ABS:Flame-retardant grades without metal inserts meet OEM aesthetic and ignition resistance requirements. Phosphorus-nitrogen synergist reformulations are replacing halogenated legacy compounds under ECHA timelines.
- PVC:Declining share due to environmental scrutiny and recycling infrastructure gaps. Specialty cable-grade formulations persist in telecommunications backup power niches.
Polypropylene leads production volume. ABS secures the steepest expansion trajectory in premium EV specifications.
Manufacturing Stage:
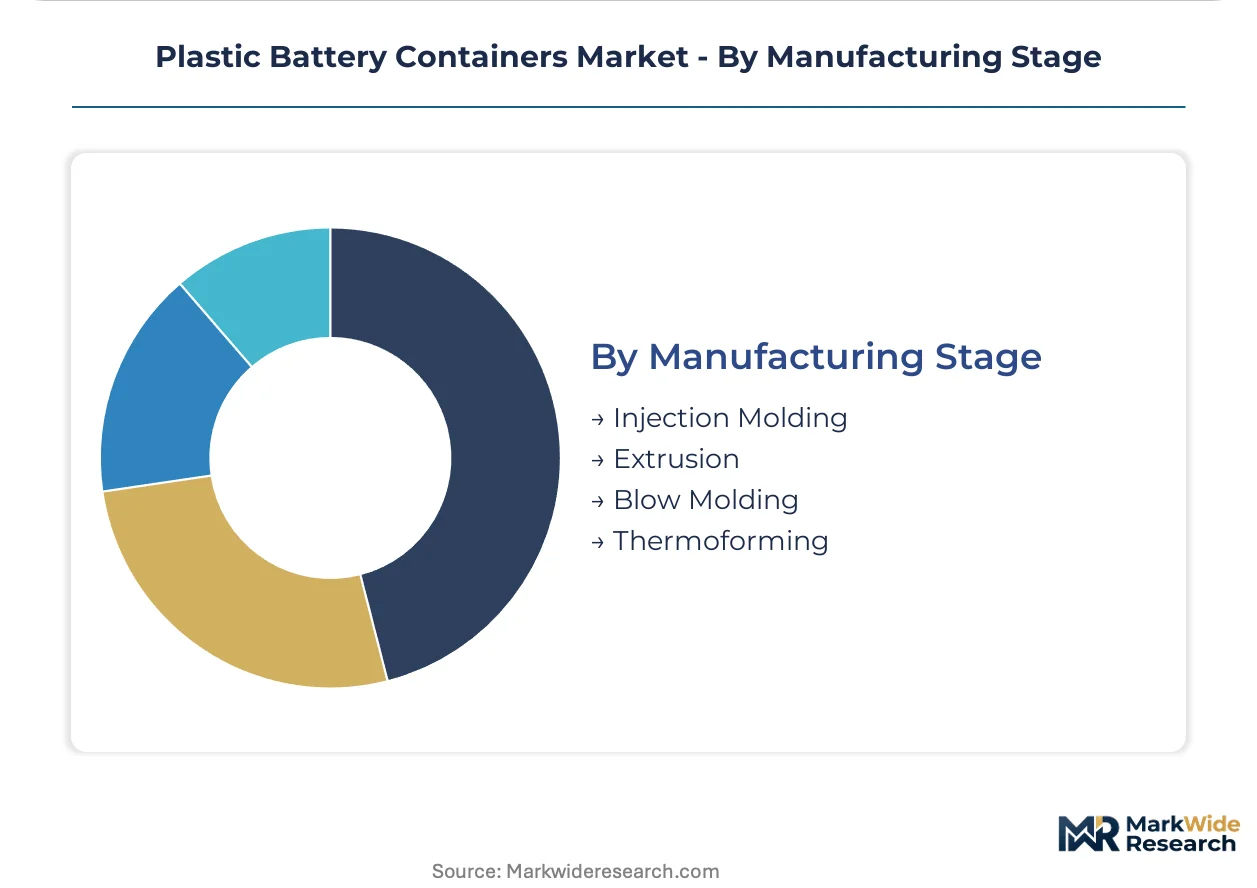
Injection molding concentrates in automotive corridor clusters, while blow molding retains geographic dispersion for aftermarket lead acid supply.
- Injection Molding:Dimensional precision enables integrated cooling channels and sensor mounting bosses for lithium-ion platforms. Capacity concentration in Germany and China's Yangtze River Delta creates supply vulnerability for qualified automotive programs.
- Blow Molding:Cost advantages persist for vented lead acid designs with simple cylindrical geometries. Graham Packaging Company and regional independents serve fragmented aftermarket demand across North America and Europe.
- Extrusion:Profile housings for prismatic cell arrays in stationary storage applications. Limited penetration outside Chinese and South Korean production corridors.
- Thermoforming:Thin-gauge prototypes and low-volume specialty formats. Tooling cost advantages suit pilot production and military specification development.
Injection Molding dominates value capture. Blow Molding retains the broadest geographic footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT structural integrity mandates anchor procurement dynamics in China, where battery gigafactory clusters concentrate housing demand. Germany's REACH and EU Battery Regulation frameworks elevate flame-retardant certification burdens. The United States balances NHTSA crashworthiness protocols against EPA hazardous waste rules. India attracts compounding investments through PLI scheme incentives. South Korea pilots phase-change material integration for next-generation formats.
China
CATL and BYD procurement drives injection-molded polypropylene specifications across the Yangtze River Delta corridor. MIIT new energy vehicle technical conditions mandate reinforced polymer grades over commodity plastics. Ningbo and Suzhou host qualified automotive programs serving domestic EV platform launches.
Germany
BMW and Volkswagen platform qualifications lock in supply relationships for lithium-ion thermal runaway containment grades. ECHA notification timelines compel phosphorus-nitrogen flame-retardant reformulation under REACH substance restrictions. Stuttgart and Munich anchor injection molding capacity serving premium EV specifications.
United States
Ford and GM expand procurement of large-format housings for electric truck platforms. NHTSA crashworthiness protocols intersect with EPA hazardous waste rules for recyclability disclosure. Detroit and South Carolina production corridors concentrate blow-molded lead acid aftermarket supply.
India
Reliance and Ola Electric gigafactory development attracts polymer compounding investments for localized housing supply. PLI scheme incentives for advanced chemistry cell manufacturing reduce import dependency. Gujarat and Tamil Nadu emerging clusters qualify flame-retardant grades for domestic platform integration.
South Korea
LG Energy Solution and Samsung SDI consolidate housing procurement under single-source material specifications. METI-aligned pilot programs test phase-change material integration within injection-molded cooling channels. Gyeonggi Province hosts smart-container prototypes embedding thermal sensors for 2026 launches.
Plastic Battery Containers Market Key Industry Players
Material compounders and packaging fabricators split the market along chemistry-specific qualification pathways. Consolidation concentrates around tier-1 automotive supplier hierarchies, though direct OEM contracting is disintermediating traditional channels. Three archetypes dominate: integrated resin suppliers with flame-retardant formulation ownership, blow-molding specialists serving aftermarket lead acid replacement, and injection-molding scale operators qualified for lithium-ion platform supply. Competitive moves center on capacity expansion in battery corridor clusters and strategic partnerships for recyclate stream certification.
Within the integrated resin supplier tier, BASF SE and SABIC exemplify compounders capturing value from material specification ownership in automotive programs. Among packaging fabricators, Graham Packaging Company represents blow-molding scale serving high-volume aftermarket channels. Greiner Packaging anchors European demand through injection-molded lines qualified for lithium-ion thermal management integration.
| Leading Market Players |
|---|
| Graham Packaging Company |
| Greiner Packaging |
| Plastipak Holdings, Inc. |
| LyondellBasell Industries N.V. |
| BASF SE |
| ALPLA |
| Berry Global Inc. |
| SABIC |
| Amcor Plc |
| Others |
Cost & Logistics Intelligence
Yangtze River Delta port congestion cost dynamics compress margins for injection-molded lithium-ion housing suppliers while amplifying price differentiation between qualified automotive grades and commodity aftermarket alternatives. Freight volatility from Ningbo and Shanghai feeds directly into procurement negotiations for flame-retardant polypropylene compounders serving CATL and BYD platform specifications.
Pricing Analysis
Geographic price spreads of 15-25% separate German automotive qualification tiers from Chinese domestic EV specifications. Three-tier pricing structure across premium, standard, and economy levels stratifies by UL 94 V-0 certification status and integrated cooling channel complexity. Cost compression in standard-grade polypropylene intensifies because REACH-compliant phosphorus-nitrogen flame-retardant reformulations carry additive premiums. Fleet maintenance operators in North American aftermarket channels exhibit highest price sensitivity, while German OEM platform engineers prioritize thermal runaway containment over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for battery housing compounders with cross-border automotive programs. Raw material sourcing draws from Saudi Arabian polypropylene feedstock, South Korean specialty additive packages, and German injection molding equipment. Single-source vulnerability concentrates in qualified Yangtze River Delta and Stuttgart production corridors where platform-specific tooling locks in supply relationships. Distribution runs through tier-1 automotive supplier hierarchies, though direct OEM contracting with CATL, BYD, and LG Energy Solution is disintermediating traditional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell-to-pack architecture fragmentation creates specialized niche opportunities for thermal management-integrated resin systems as discrete container demand compresses in premium EV segments. Platform-level material specification ownership now determines margin capture.
For Market Incumbents: Harden qualification pipelines against disintermediation by securing direct OEM platform approvals before tier-1 supplier consolidation completes. BASF SE and SABIC demonstrate defensive value capture through flame-retardant formulation ownership that tiered automotive suppliers cannot replicate. Capacity addition in India's Gujarat and Tamil Nadu corridors hedges geographic concentration risk in China and Germany. For New Entrants and Emerging Players: India's PLI scheme-advanced chemistry cell manufacturing corridors represent the most penetrable entry point for localized polymer compounding investments. Solid-state battery phase-change material integration trials in South Korean pilot lines offer second-mover specification influence without legacy platform lock-in. Go-to-market positioning should emphasize recyclate stream certification for EU Battery Regulation closed-loop mandates. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with underutilized injection molding capacity in battery corridor proximity. Five-to-ten-year viability hinges on cell-to-pack adoption velocity and structural battery housing resin substitution rates. Monitor ECHA notification timelines for phosphorus-nitrogen flame-retardant approvals as inflection indicator for European specification premium durability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flame-Retardant Additives | Compounders secure margin from phosphorus-nitrogen synergist formulation ownership under REACH timelines. |
| Capacity Expansion in Battery Corridor Clusters | Ningbo and Stuttgart proximity reduces freight exposure for qualified automotive platform supply. |
| Recyclate Stream Certification Investment | EU Battery Regulation closed-loop mandates create procurement preference for certified post-consumer polypropylene. |
| Direct OEM Platform Qualification | Bypassing tier-1 hierarchies captures value from material specification ownership with CATL and BYD. |
| Phase-Change Material Integration Partnership | South Korean pilot programs open premium specification tiers for next-generation solid-state formats. |
Research Approach
A standing panel of polymer compounding technical directors, automotive OEM platform engineers, tier-1 supplier procurement leads, and ECHA regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from MIIT new energy vehicle technical condition filings, REACH substance restriction notifications, UL certification databases, and customs trade data for polypropylene and ABS resin flows. Bottom-up segment sizing triangulated against top-down battery gigafactory capacity announcements.
Scenario-bracketing framed projections across cell-to-pack adoption velocity variants and flame-retardant reformulation cost pass-through assumptions. Segmentation dimensions modeled include battery chemistry type, manufacturing process technology, material grade tier, end-use application, and regional regulatory cluster. CAGRs derived from production volume build-ups correlated with OEM platform launch schedules and aftermarket replacement cycle patterns. Forecast inputs incorporated REACH recyclate mandate compliance timelines and NHTSA crashworthiness protocol evolution.
Practitioners should monitor ECHA notification delays, MIIT structural integrity mandate revisions, and solid-state battery pilot production scale-up for early signals of specification demand shifts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Transparent Plastic Packaging Market
Plastic Packaging
FFS Rigid Films Market
Plastic Packaging
Spain Plastic Bottles Market
Plastic Packaging
Corrugated Plastic Box Market
Plastic Packaging
Japan Plastic Bottles Market
Plastic Packaging
E-Commerce Plastic Packaging Market
Plastic Packaging
Egypt Plastic Bottles Market
Plastic Packaging
Reusable Plastic Water Bottles Market
Plastic Packaging
Plastic Cans Market
Plastic Packaging
Malaysia and Thailand Thermoformed Plastic Market
Plastic Packaging
Compostable Plastic Packaging Material Market
Plastic Packaging
Vietnam Plastic Bottles Market
Plastic Packaging
PE Blow Molded Products Market
Plastic Packaging
Plastic Corrugated Sheets Market
Plastic Packaging
Plastic Liners Market
Plastic Packaging
BOPP Tobacco Films Market