
 Global Eylea Market | 2026-2036
Global Eylea Market Size, Share, and Industry Trends Forecast 2026-2036
Global Eylea Market Foresight
Specialized eye hospitals is rotating toward higher patient throughput models as diabetic retinopathy cases multiply across developed economies. Regeneron Pharmaceuticals leverages its origination IP and manufacturing scale to anchor supply continuity for the reference biologic. Bayer AG competes through co-commercialization infrastructure across European markets. Roche Holding AG differentiates via its port delivery system technology in adjacent ophthalmology segments.
Eylea refers to aflibercept, a recombinant fusion protein comprising vascular endothelial growth factor binding domains fused to Fc portions of human immunoglobulin G1, administered via intravitreal injection to inhibit angiogenesis and vascular permeability. The therapy area segmentation shows diabetic retinopathy generating the fastest volume expansion as diabetes prevalence climbs, while age-related macular degeneration occupies the largest revenue pool due to higher per-patient treatment frequency. Eylea biosimilar entrants are concentrating margin pressure on the injectable vial format, whereas extended release formulations command premium positioning through reduced injection burden.
The FDA and EMA govern approval standards for ophthalmic biologics and biosimilars, with the FDA's interchangeable designation pathway shaping payer substitution policies. The EU's MDR and F-Gas Regulation affect device components and sterilization processes for pre-filled syringes. Japan's PMDA maintains distinct pharmacovigilance requirements that influence regional launch sequencing. Stakeholders must monitor biosimilar interchangeability rulings and extended-release formulation readouts to calibrate portfolio allocation between originator defense and next-generation development.
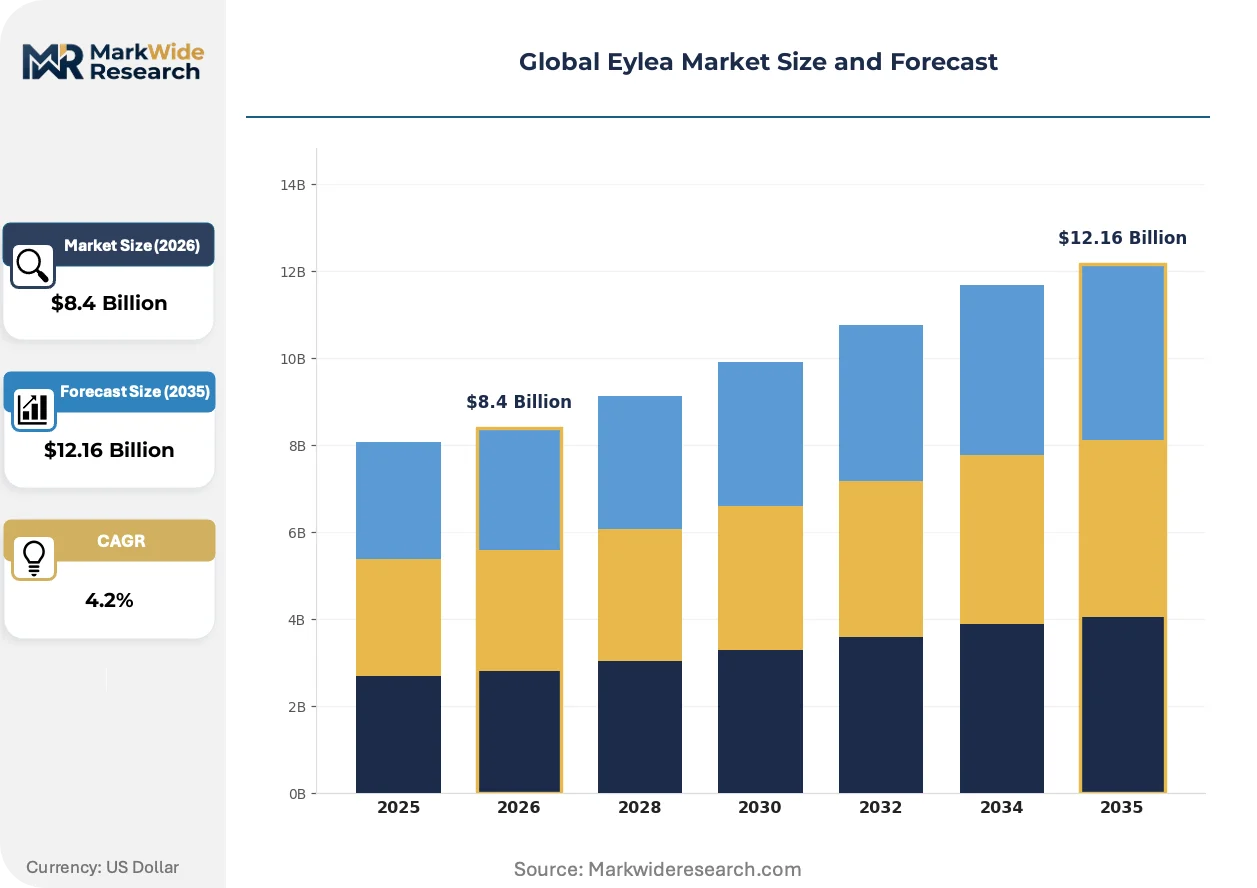
Market Dynamics
Biosimilar entry timelines governed by FDA interchangeability rulings and EMA centralized procedures are compressing originator exclusivity windows while redirecting R&D investment toward sustained-release delivery formats.
Growth Catalysts
- Diabetic retinopathy prevalence:Rising diabetes incidence across aging populations in the United States, Germany, and Japan generates expanding patient pools eligible for intravitreal anti-VEGF therapy.
- Extended-release formulation development:Port delivery system technology reduces injection frequency burden, improving adherence metrics and justifying premium positioning in reimbursement negotiations.
- FDA biosimilar pathway maturation:Interchangeability designation standards clarify substitution policies, accelerating payer acceptance of follow-on biologics in commercial formularies.
Market Restraints
- Biologics manufacturing concentration:Fill-finish capacity for ophthalmic injectables concentrates among a limited supplier base in Switzerland and Germany, creating single-source vulnerability.
- Reimbursement density asymmetry:Medicare coverage determination timelines in the United States delay commercial uptake of novel administration devices relative to vial formats.
- Intravitreal injection safety requirements:Endophthalmitis risk protocols mandate specialized training infrastructure, restricting administration to ophthalmic clinics and hospital-based retina specialists.
Strategic Opportunities
- Japan PMDA pharmacovigilance alignment:Streamlined adverse event reporting harmonization between FDA and Japanese regulators accelerates sequential launch timelines for sustained-release iterations.
- Home administration device development:Autoinjector platforms for patient self-administration address mobility constraints in rural United States markets and aging European demographics.
- Combination therapy protocols:Concurrent anti-VEGF and sustained-release corticosteroid regimens create protocol stickiness in diabetic macular edema treatment algorithms.
Industry Challenges
- Vitreoretinal surgeon training pipeline:Fellowship program capacity constraints in the United States limit the specialist workforce required for complex injection protocols and complication management.
- Cold chain integrity for pre-filled syringes:Temperature excursion validation requirements complicate distribution to secondary ophthalmic clinics in warmer climates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Eylea Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.16 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eylea Injectable, Eylea Pre-Filled Syringe, Eylea Biosimilar, Eylea Extended Release Therapy Area: Age-Related Macular Degeneration, Diabetic Retinopathy, Retinal Vein Occlusion, Macular Edema End User: Ophthalmic Clinics, Specialized Eye Hospitals, Diagnostic Centers, Research Institutes Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Sales |
| Companies Covered | Regeneron Pharmaceuticals Inc., Bayer AG, Roche Holding AG, Novartis AG, Pfizer Inc., Amgen Inc., Santen Pharmaceutical Co. Ltd., AbbVie Inc., Alcon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Eylea Market Shifts & Advancements
Delivery technology diversification is fragmenting the standard-of-care assumption that intravitreal injection frequency must remain fixed, enabling new competitive axes around patient convenience and healthcare system efficiency.
Sustained-release implant technology is fragmenting the traditional injection cadence model. Aflibercept polymeric depot formulations release therapeutic concentrations over four to six months. Retina specialists in academic medical centers are adopting these platforms for treatment-burdened patients. The technology is fragmenting volume concentration toward higher-complexity sites capable of implant placement and monitoring.
The EU MDR and F-Gas Regulation impose new sterilization validation requirements on pre-filled syringe components. Device manufacturers must demonstrate alternative sterilization methods for gas-dependent processes. Ophthalmic biologic sponsors with European manufacturing footprints are reformulating supply agreements to secure compliant component sourcing.
Patient switching behavior between anti-VEGF agents is compressing as real-world evidence databases mature. United States payers are deploying step-therapy algorithms that mandate documented failure on preferred agents. Retina practices are consolidating around protocol-driven treatment sequences rather than physician-directed selection, standardizing agent rotation patterns across metropolitan markets.
Global Eylea Market Segmentation
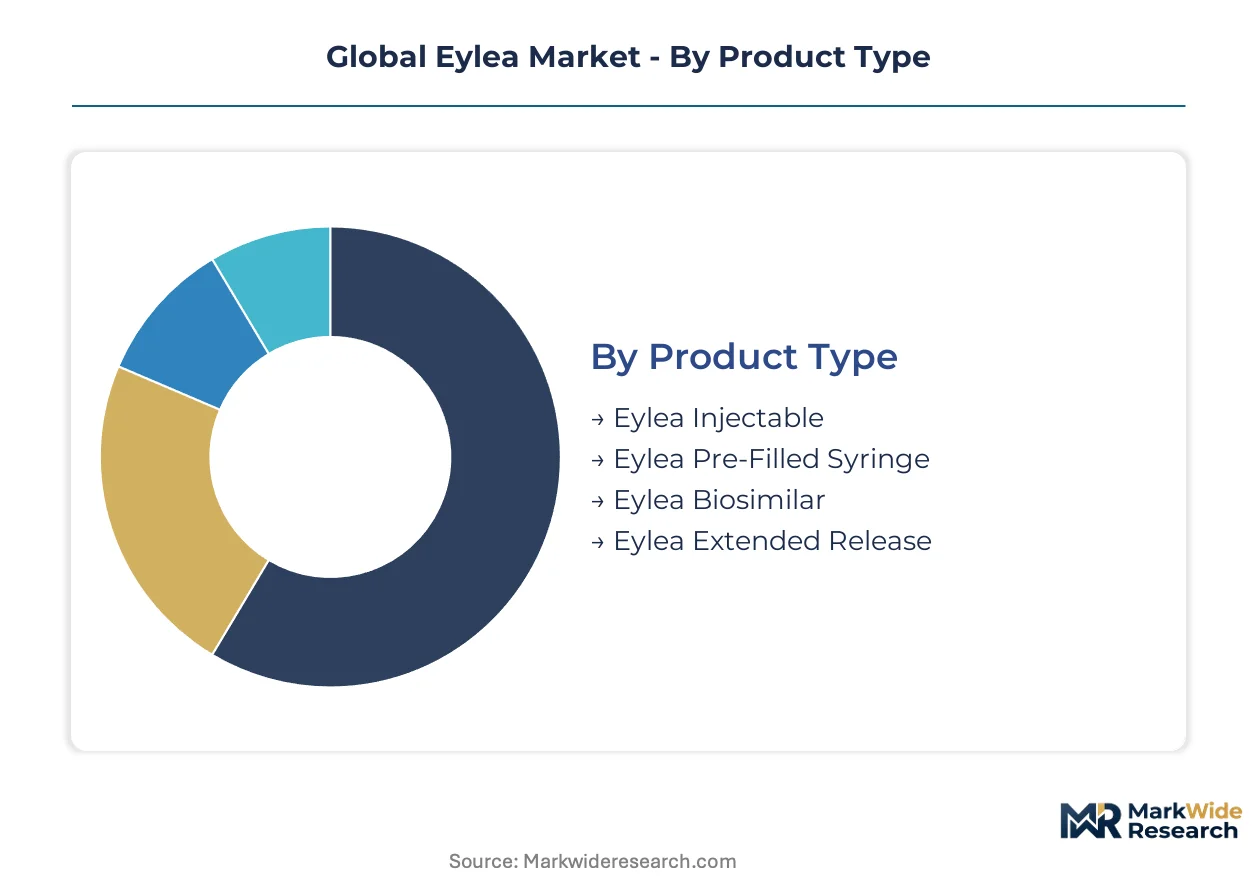
Eylea's market structure fragments across four dimensions that shape competitive positioning and margin capture. Product format differentiation determines reimbursement tier and manufacturing complexity. Therapy area concentration directs R&D investment toward sustained-release formulations.
Product Type:
FDA interchangeability rulings and EMA centralized procedures create divergent approval timelines across format categories.
- Eylea Injectable:The reference biologic in vial format requires cold chain distribution and specialized compounding. United States Medicare reimbursement density sustains volume concentration despite biosimilar pressure on net pricing.
- Eylea Pre-Filled Syringe:Unit-dose presentation reduces preparation time and contamination risk. German hospital procurement frameworks favor this format for outpatient retina clinics seeking throughput efficiency.
- Eylea Biosimilar:Follow-on biologics governed by FDA interchangeability standards and EMA biosimilar pathways. Payer formularies in United States commercial plans increasingly mandate step-therapy protocols.
- Eylea Extended Release:Polymeric depot formulations releasing therapeutic concentrations over four to six months. Japan's PMDA pharmacovigilance requirements influence sequential launch sequencing for implantable formats.
Established volume favors Eylea Injectable; emerging adoption favors Eylea Extended Release.
Therapy Area:
Patient pool expansion rates and injection frequency requirements create divergent revenue durability across indications.
- Age-Related Macular Degeneration:Chronic condition requiring indefinite maintenance therapy. United States, Germany, and Japan account for disproportionate volume due to aging demographics and reimbursement infrastructure.
- Diabetic Retinopathy:Rising diabetes prevalence across developed economies generates the steepest expansion trajectory for anti-VEGF eligible patients. Treatment protocols increasingly favor early intervention.
- Retinal Vein Occlusion:Acute presentation with defined treatment courses. Volume concentrates in academic medical centers with fellowship-trained vitreoretinal specialists.
- Macular Edema:Secondary indication with combination therapy potential. Protocol stickiness emerges from concurrent anti-VEGF and corticosteroid regimens in diabetic macular edema algorithms.
Revenue concentration sits with Age-Related Macular Degeneration; volume momentum shifts toward Diabetic Retinopathy.
End User:
Site-of-care economics and specialist workforce availability determine access patterns and administration technology preferences.
- Ophthalmic Clinics:Private practice retina specialists administer the majority of intravitreal injections. United States metropolitan markets show consolidation around protocol-driven treatment sequences.
- Specialized Eye Hospitals:Academic medical centers adopt sustained-release implants for treatment-burdened patients. Higher patient throughput models multiply across developed economies as diabetic retinopathy cases climb.
- Diagnostic Centers:Imaging and monitoring functions with limited therapeutic administration. Referral relationships with injection-capable sites shape patient flow.
- Research Institutes:Clinical trial enrollment and real-world evidence generation. Longitudinal databases inform payer step-therapy algorithm deployment.
Procedure volume concentrates in Ophthalmic Clinics; technology adoption leadership resides in Specialized Eye Hospitals.
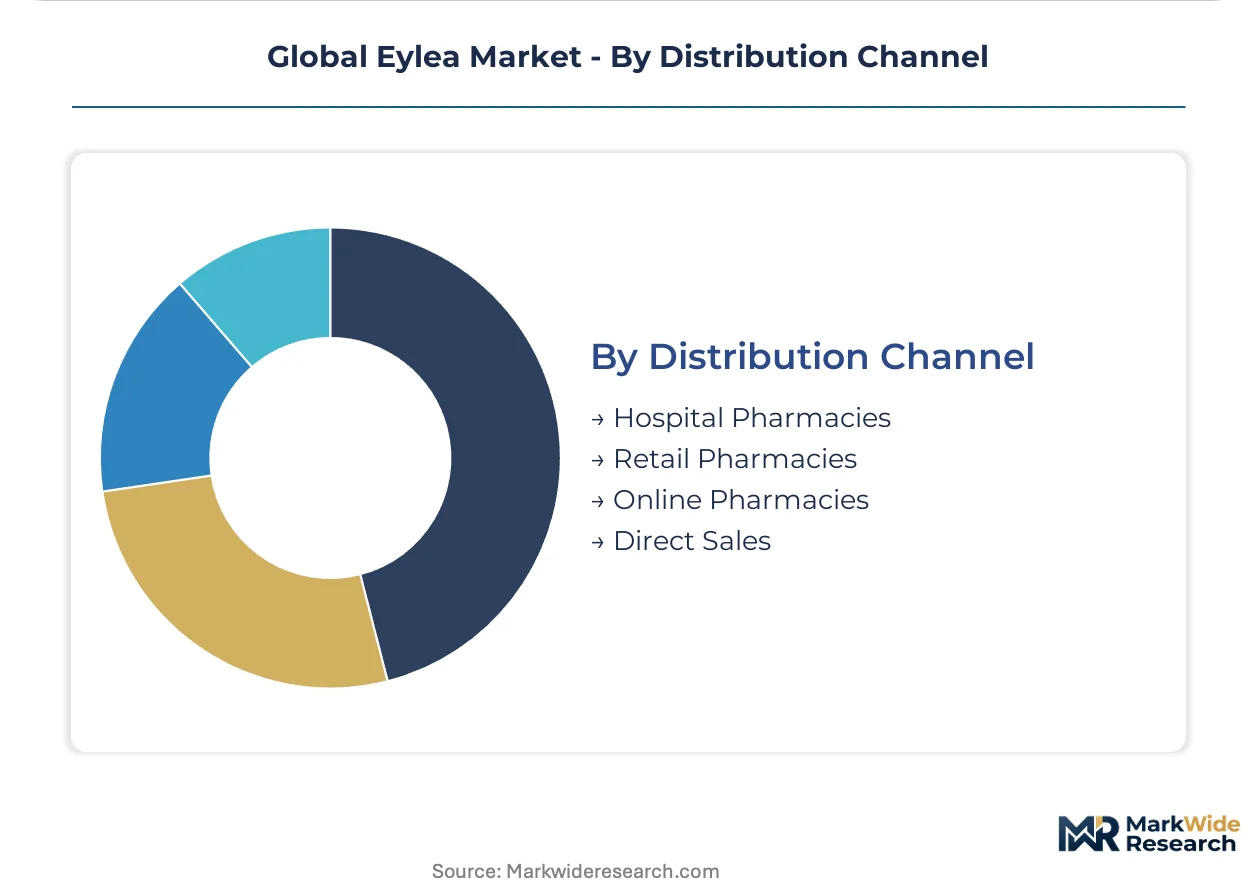
Distribution Channel:
Cold chain integrity requirements and temperature excursion validation shape channel viability for pre-filled syringe formats.
- Hospital Pharmacies:Integrated supply for inpatient and outpatient retina services. EU MDR sterilization validation requirements affect device component sourcing agreements.
- Retail Pharmacies:Limited penetration due to specialized handling and administration requirements. Patient self-administration remains restricted by intravitreal injection safety protocols.
- Online Pharmacies:Emerging for patient support programs and adherence tracking. Distribution to secondary ophthalmic clinics in warmer climates complicates temperature control.
- Direct Sales:Manufacturer-to-provider contracts for large-volume accounts. Switzerland and Germany fill-finish capacity concentration creates single-source vulnerability in this channel.
Institutional procurement dominates through Hospital Pharmacies; patient-facing access experiments through Online Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fill-finish capacity for ophthalmic biologics concentrates in Switzerland and Germany, creating single-source vulnerability for intravitreal injectables. Regulators in the United States, Japan, and key European markets govern approval standards that shape competitive entry timelines. Aging demographics and reimbursement density determine where volume expansion accelerates fastest.
United States
Medicare coverage determination timelines sustain demand concentration for vial formats despite biosimilar pressure on net pricing. The FDA's interchangeability designation pathway clarifies substitution policies for payer formularies. Retina specialists in metropolitan markets consolidate around protocol-driven treatment sequences.
Germany
Hospital procurement frameworks favor pre-filled syringe formats for outpatient retina clinics seeking throughput efficiency. The EU MDR and F-Gas Regulation impose sterilization validation requirements on device components. Manufacturing clusters in Baden-Württemberg and Bavaria anchor fill-finish operations for European supply.
Japan
Aging demographics generate expanding patient pools eligible for intravitreal anti-VEGF therapy. The PMDA maintains distinct pharmacovigilance requirements that influence sequential launch sequencing for implantable formats. Tokyo and Osaka academic medical centers adopt sustained-release platforms for treatment-burdened patients.
Switzerland
Specialized biologics manufacturing infrastructure supports cold chain distribution for ophthalmic injectables. Swissmedic governs approval standards for reference biologics and biosimilars entering European markets. Basel and Zürich industrial clusters concentrate sterile fill-finish capacity for global supply.
United Kingdom
NHS reimbursement frameworks prioritize cost-effectiveness in anti-VEGF therapy selection. The MHRA operates under retained EU MDR requirements for device component validation. London and Manchester retina centers participate in real-world evidence generation for payer algorithm deployment.
Global Eylea Market Competitive Landscape
Concentration sits with originator biologic sponsors possessing manufacturing scale and co-commercialization infrastructure. The market structure consolidates around three strategic archetypes: reference biologic originators defending exclusivity through formulation innovation, biosimilar entrants exploiting interchangeability pathways, and device-technology specialists differentiating via delivery system platforms. Dominant competitive moves include sustained-release formulation development and geographic co-commercialization partnerships.
Among originator-tier biopharmaceutical companies, Regeneron Pharmaceuticals Inc., Bayer AG, and Roche Holding AG occupy positions defined by origination IP, European market infrastructure, and port delivery system technology respectively. Regeneron Pharmaceuticals Inc. exemplifies the reference biologic archetype through its manufacturing scale advantages. Bayer AG represents the co-commercialization specialist model across European ophthalmology markets. Roche Holding AG anchors the device-differentiation vector with sustained-release platform investments.
| Leading Market Players |
|---|
| Regeneron Pharmaceuticals Inc. |
| Bayer AG |
| Roche Holding AG |
| Novartis AG |
| Pfizer Inc. |
| Amgen Inc. |
| Santen Pharmaceutical Co. Ltd. |
| AbbVie Inc. |
| Alcon Inc. |
| Others |
Supply & Pricing Matrix
Biosimilar substitution for intravitreal vial formats is compressing net pricing for reference biologics while simultaneously redirecting procurement volume toward pre-filled syringes and implantable depot formulations that command manufacturing premiums. This substitution dynamic concentrates fill-finish investment in Switzerland and Germany while fragmenting pricing power across administration technology tiers.
Pricing Analysis
Volume-discount tiering structures separate originator vial formats from biosimilar entrants and extended-release implants. Medicare reimbursement density in the United States sustains premium positioning for reference biologics despite biosimilar pressure on commercial formularies. Price differentiation rests on administration frequency burden and cold chain handling requirements. Ophthalmic clinics show highest price sensitivity to per-injection costs, while academic medical centers prioritize adherence metrics over unit economics.
Supply Chain Analysis
Switzerland and Germany anchor sterile fill-finish capacity for ophthalmic biologics through Basel and Baden-Württemberg manufacturing clusters. Active pharmaceutical ingredient production draws from Irish fermentation facilities and Singapore biologics parks. Single-source vulnerability concentrates in gas-dependent sterilization processes affected by EU F-Gas Regulation restrictions. Distribution runs through hospital pharmacy networks with direct manufacturer contracts for large-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around United States payer formularies and German hospital procurement frameworks, compressing vendor pricing autonomy through step-therapy mandates and volume aggregation.
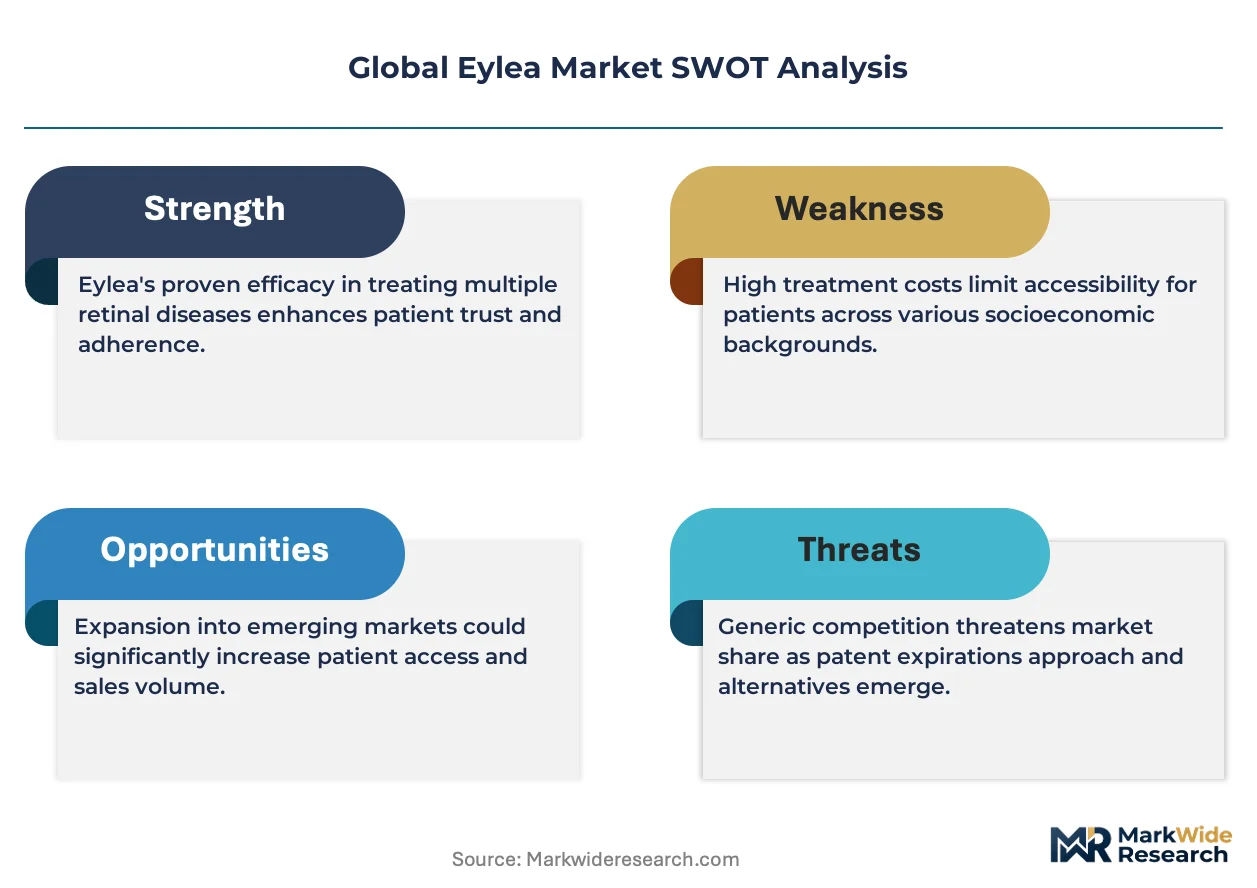
For Market Incumbents: Compound formulation innovation advantages through sustained-release platform investments that extend dosing intervals beyond biosimilar reach. Anchor manufacturing scale in Swiss and German fill-finish clusters to secure supply continuity against regulatory sterilization shifts. Prioritize FDA interchangeability defense through real-world evidence generation that reinforces protocol stickiness in retina specialist practices. For New Entrants and Emerging Players: FDA biosimilar fast-track pathways offer accelerated entry for vial-format follow-on biologics with demonstrated bioequivalence. Target United States commercial plans with step-therapy positioning that undercuts originator net pricing. Pursue European EMA centralized procedures to capture German hospital procurement volume through pre-filled syringe presentations. For Investors and Strategic Acquirers: The market sits at a biosimilar-entry phase that favors device-differentiation specialists over commodity biologic manufacturers. Long-term viability hinges on sustained-release technology ownership and geographic co-commercialization infrastructure. Watch FDA interchangeability rulings for Eylea biosimilars as the inflection signal for margin compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Release Formulation Development | Port delivery system technology reduces injection burden and commands premium reimbursement positioning. |
| FDA Interchangeability Pathway Navigation | Biosimilar substitution policies clarify payer formulary placement and accelerate commercial uptake. |
| European Manufacturing Footprint Expansion | EU MDR compliance for sterilization processes secures device component sourcing continuity. |
| Retina Specialist Training Partnership | Fellowship program alignment addresses workforce constraints limiting injection protocol expansion. |
| Japan PMDA Pharmacovigilance Alignment | Streamlined adverse event reporting accelerates sequential launch timelines for implantable formats. |
Research Methodology
Cross-validation between retina specialist interviews and payer formulary databases anchors the qualitative findings in documented access patterns. Primary fieldwork encompassed drug development executives at biologic sponsors, regulatory affairs leads navigating FDA and EMA pathways, formulary directors at United States commercial plans, hospital procurement managers in German outpatient clinics, and payer access specialists mapping step-therapy algorithms. Secondary validation drew from FDA biosimilar approval filings, EMA centralized procedure documentation, ClinicalTrials.gov enrollment records, and CMS Medicare reimbursement determinations. Bottom-up volume modeling triangulated against top-down market sizing across therapy areas and product formats.
Sensitivity analysis tested forecast outputs against variable biosimilar entry timing assumptions and sustained-release adoption curves across the projection horizon. The analytical framework segmented volume and value by product type, therapy area, end-user site of care, and distribution channel, with regional regulatory clusters as an overlay dimension. CAGRs derived from patient pool epidemiology, treatment frequency protocols, and pricing trajectory modeling. Forecast inputs incorporated diabetic retinopathy prevalence projections, vitreoretinal surgeon workforce expansion rates, and interchangeability designation timelines.
The analysis sits within stated boundaries; outcomes outside assumed biosimilar approval sequencing or sustained-release clinical readouts would require recalibration. Forecasts reflect documented assumptions about payer policy evolution and manufacturing capacity expansion. Recalibration cycles align with material shifts in FDA interchangeability rulings and extended-release formulation launch outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Short-Acting Insulin Market
Pharmaceuticals
Generic Pharmaceuticals Contract Manufacturing Market
Pharmaceuticals
Global Interleukin Inhibitors Market
Pharmaceuticals
Filgrastim Market
Pharmaceuticals
Global Antacids Market
Pharmaceuticals
Preeclampsia Therapeutics Market
Pharmaceuticals
Global Divalproex Sodium Market
Pharmaceuticals
Sinus Therapeutic Drugs Market
Pharmaceuticals
Global Histone Deacetylase Inhibitors Market
Pharmaceuticals
US Compounding Pharmacies Market
Pharmaceuticals
Global Prefilled Syringes Drug Molecules Market
Pharmaceuticals
Global Non-Alcoholic Fatty Liver Disease (NAFLD) Drug Market
Pharmaceuticals
Global Lyophilized Injectable Drugs Market
Pharmaceuticals
Dental Medication Market
Pharmaceuticals
Cerumenolytic Agents Market
Pharmaceuticals
Global Female Contraceptive Market