
 Europe Pharmaceutical Contract Sales Outsourcing (CSO) Market | 2026-2036
Europe Pharmaceutical Contract Sales Outsourcing (CSO) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pharmaceutical Contract Sales Outsourcing (CSO) Market Foresight
Germany's pharmaceutical corridor is reshaping how contract sales organizations deploy field teams across Central Europe. IQVIA Inc. leverages its pan-European data infrastructure to anchor multi-country launches for specialty therapeutics. Syneos Health Inc. competes through integrated commercialization platforms that span clinical-to-commercial handoffs. Ashfield Engage (Inizio) specializes in flexible staffing models that align sales force sizing with volatile pipeline cadences.
Pharmaceutical Contract Sales Outsourcing denotes the delegation of sales, marketing, and market access activities to third-party specialists who deploy trained representatives, digital engagement tools, and payer negotiation expertise on behalf of drug developers. These services operate under strict EMA pharmacovigilance protocols and country-specific transparency codes, functioning primarily to accelerate product uptake while containing fixed labor costs for sponsors. Field Sales occupies the largest revenue pool due to persistent physician-access requirements for novel therapies, while Market Access segments are expanding fastest as HTA negotiations grow more complex across EU member states. The Managed Services engagement model dominates among large pharmaceutical companies seeking long-term partnerships, whereas Project-Based Engagement captures emerging biotech firms with lumpy approval timelines.
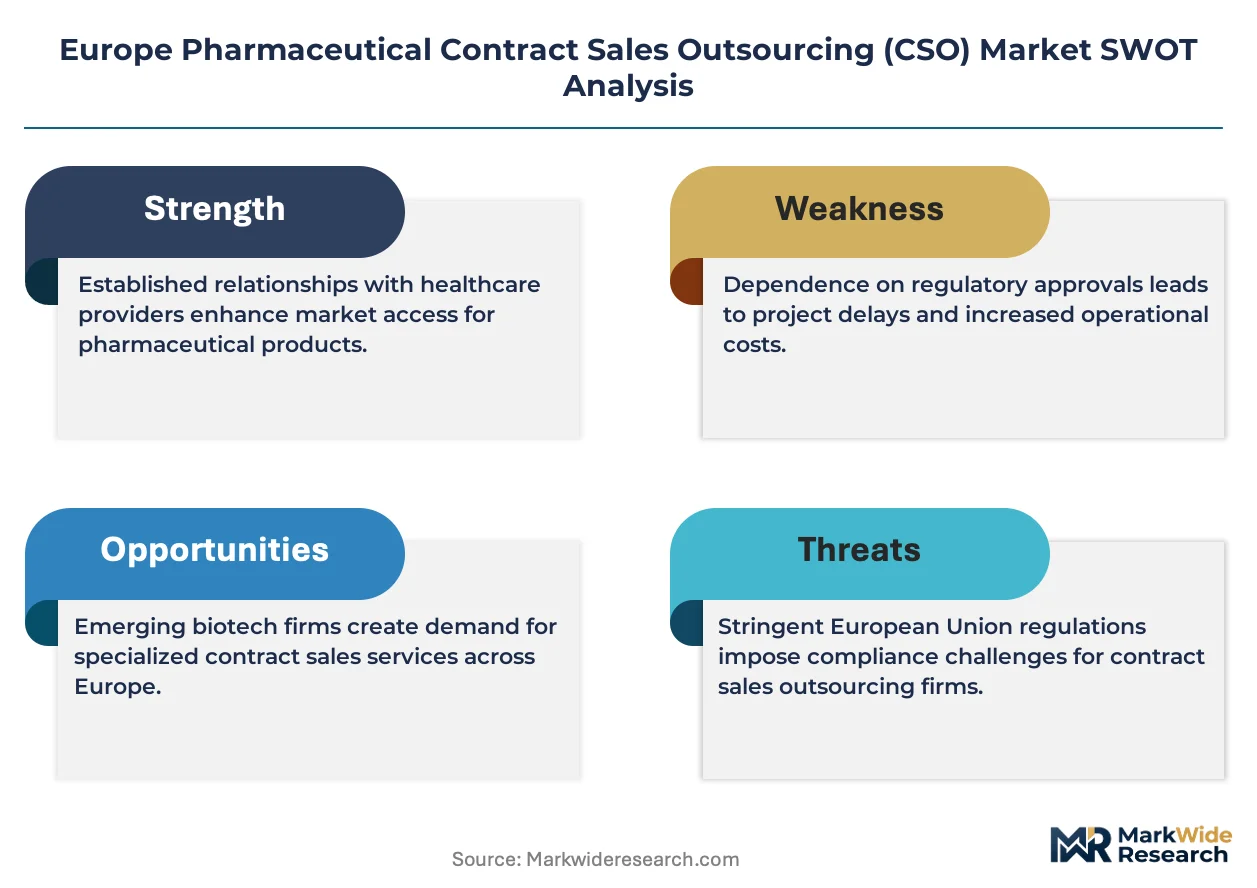
EMA's evolving guidance on digital promotion, combined with national transparency codes in France and the UK, forces CSOs to maintain dual compliance architectures across jurisdictions. The EU AI Act imposes new documentation burdens on algorithmic targeting tools used in physician engagement platforms, reshaping technology procurement decisions. Stakeholders must monitor how HTA convergence initiatives alter the skill mix required for successful payer negotiations.
Market Dynamics
The EU AI Act is collapsing traditional field-force deployment models across European pharmaceutical sales, compelling contract sales organizations to re-architect compliance infrastructure around algorithmic transparency requirements and dual-jurisdiction pharmacovigilance protocols.
Growth Catalysts
- EMA Pharmacovigilance Burden:Evolving post-market surveillance requirements from the European Medicines Agency raise fixed compliance costs for in-house teams, pushing specialty drug manufacturers toward outsourced sales partners with established regulatory infrastructure.
- HTA Complexity:Health technology assessment negotiations across Germany, France, and the UK demand specialized payer-access expertise that emerging biotech firms cannot build internally.
- Digital Health Pathways:The EU's accelerated authorization frameworks for technology-enabled therapeutics create demand for hybrid sales models combining field representatives with remote engagement platforms.
Market Restraints
- Cross-Border Compliance Friction:France's national transparency code and the UK's ABPI Code operate under divergent disclosure timelines, forcing CSOs to maintain redundant reporting systems for multi-country campaigns.
- AI Documentation Costs:The EU AI Act's algorithmic audit requirements impose capital-intensive validation burdens on physician-targeting platforms, compressing margins for technology-enabled service providers.
- Talent Pool Constraints:Germany's pharmaceutical corridor around Frankfurt and Heidelberg faces acute scarcity of representatives dual-qualified in scientific liaison and digital engagement tools.
Strategic Opportunities
- Central and Eastern Europe Expansion:Poland and Czech Republic represent underpenetrated markets where Western European CSOs can deploy proven payer-negotiation methodologies ahead of localized competitor formation.
- Real-World Evidence Integration:Convergence of EMA's DARWIN EU network with field-force data collection creates opportunity for CSOs to offer differentiated value through outcomes-linked contracting.
- Modular Service Unbundling:Project-based engagement models targeting emerging biotechs with lumpy approval timelines allow flexible capacity allocation without long-term fixed commitments.
Industry Challenges
- Pharmacovigilance Training Lag:Field representatives require continuous certification under EudraVigilance protocols, creating operational drag as pipeline cadences accelerate.
- Legacy CRM Integration:Sponsor systems built on pre-digital architectures resist seamless data handoff to CSO-operated engagement platforms, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pharmaceutical Contract Sales Outsourcing (CSO) Market |
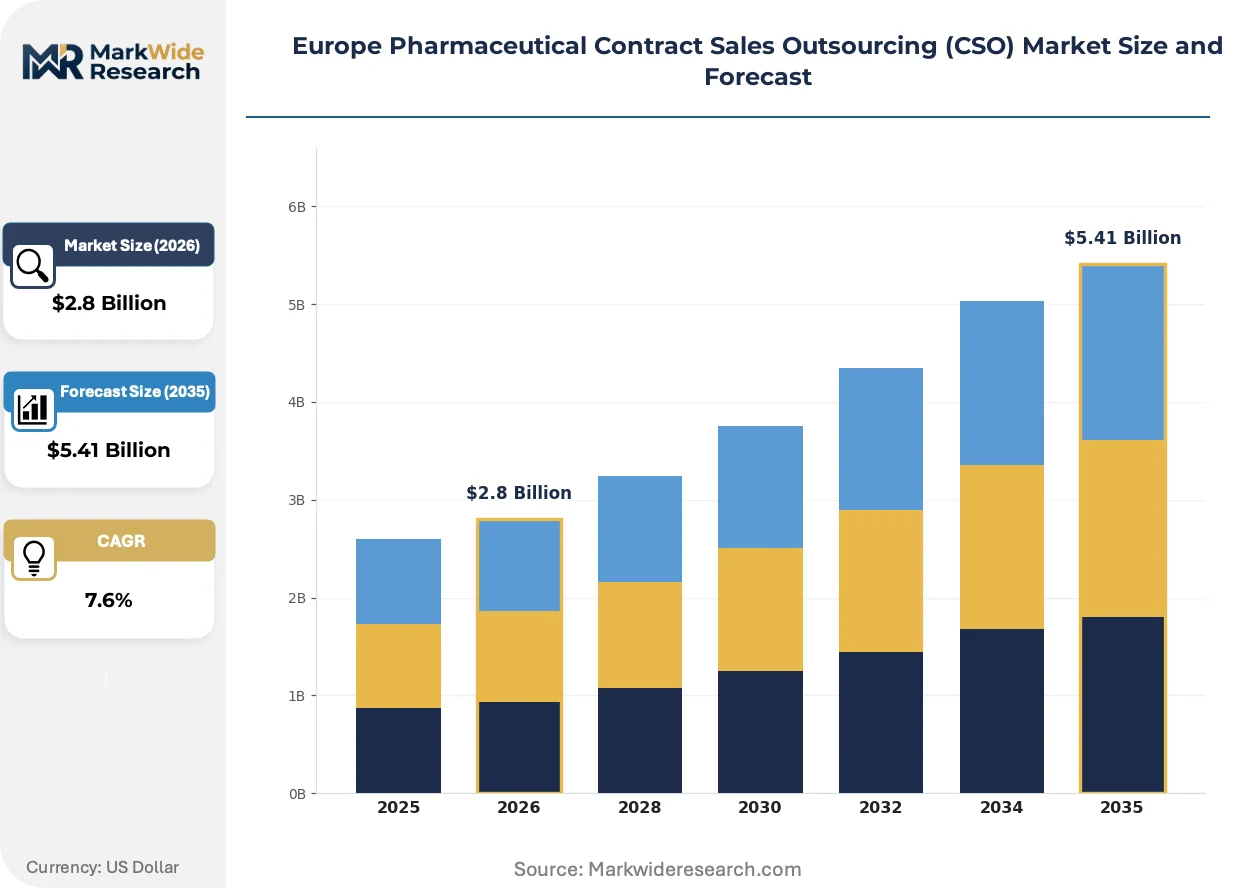
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Field Sales, Tele-sales, Promotional Services, Market Access End User: Pharmaceutical Companies, Biotechnology Firms, Medical Device Manufacturers, Contract Research Organizations Engagement Model: Managed Services, Dedicated Teams, Project-Based Engagement, Staffing Solutions Market Segment: Chronic Diseases, Specialty Drugs, Over-the-Counter, Generic Products |
| Companies Covered | IQVIA Inc., Syneos Health Inc., Parexel International Corporation, ICON plc, EVERSANA, Ashfield Engage (Inizio), Amplity Health, Uniphar Group, PHOENIX Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pharmaceutical Contract Sales Outsourcing (CSO) Market Shifts & Advancements
Technology-enabled sales architectures are displacing traditional field-force hierarchies across European pharmaceutical commercialization, with artificial intelligence and remote engagement tools compressing the cost structure of physician access while regulatory frameworks reshape permissible deployment models.
AI-driven physician targeting platforms are collapsing the cost-per-contact economics of traditional field sales by algorithmically prioritizing high-propensity prescribers and automating routine engagement touchpoints. Mid-sized biotech sponsors across Germany and the Netherlands are adopting these tools at accelerated pace, replacing static territory assignments with dynamic, data-driven call planning. The structural consequence is a compression of representative headcount requirements for mature therapeutic categories, reallocating human capital toward complex scientific exchange.
EMA's evolving guidance on digital promotion, coupled with the EU AI Act's risk-classification framework for algorithmic decision systems, is forcing CSOs to document training data provenance and model performance metrics for physician-engagement algorithms. This regulatory overlay raises barriers to entry for technology-light competitors while favoring established players with dedicated compliance infrastructure. France and Germany exhibit the steepest compliance ramp, as national regulators layer additional transparency requirements atop EU baseline obligations.
Biotech procurement patterns are fragmenting across engagement-model preferences, with emerging sponsors favoring modular, project-based contracts over traditional managed-service arrangements. This shift disintermediates long-term partnership structures in favor of capacity-on-demand pricing, particularly visible among UK-based venture-backed firms with unpredictable approval timelines. The consequence is a bifurcation in CSO capability investment, with some vendors deepening flexible staffing infrastructure while others defend integrated platform positions.
Europe Pharmaceutical Contract Sales Outsourcing (CSO) Market Segmentation
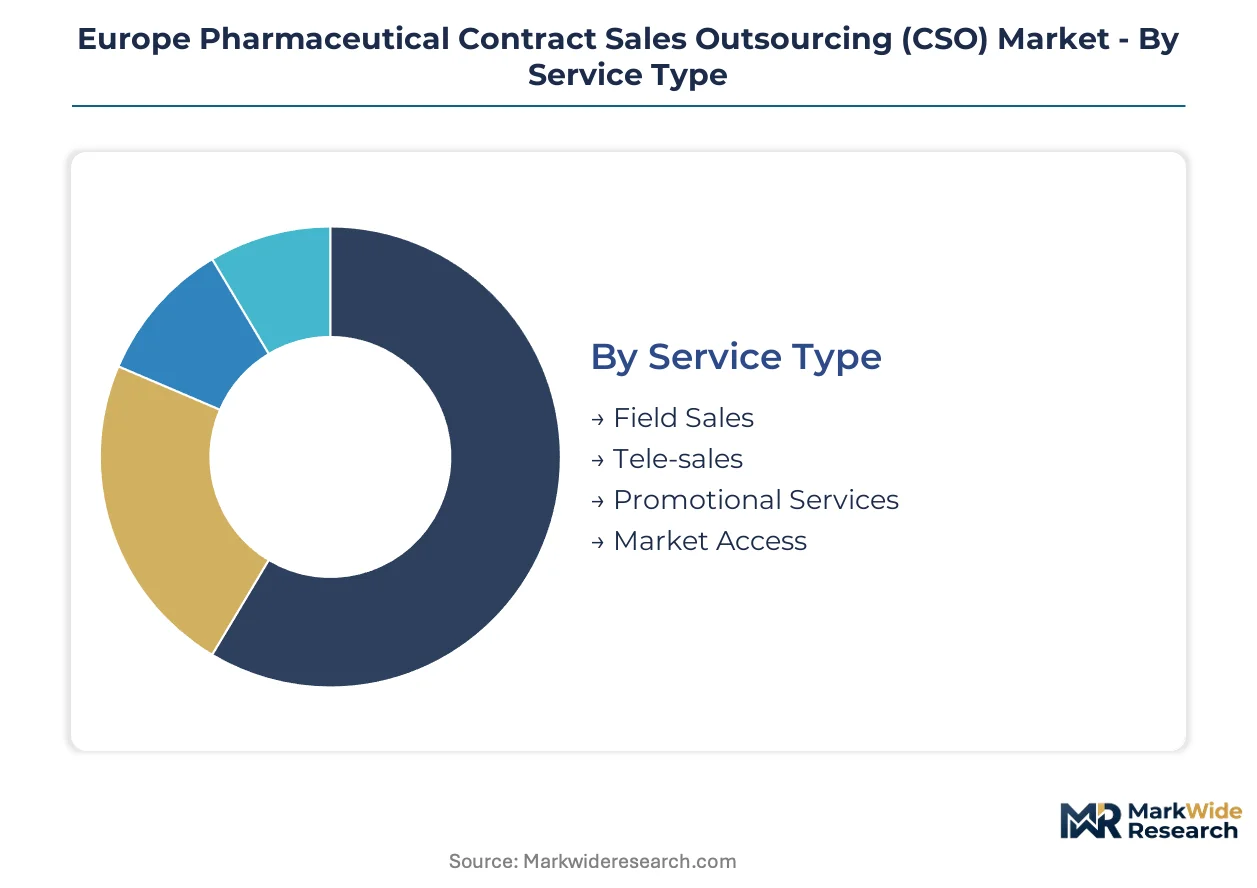
CSO procurement patterns across Europe fragment sharply by therapeutic complexity and regulatory exposure, with sponsors selecting service architectures that match pipeline volatility and EMA compliance burdens. Segmentation reveals where contract sales organizations must build differentiated capabilities versus commoditized capacity.
Service Type:
After-sales service intensity varies dramatically across service modalities, with field-deployed representatives requiring continuous EudraVigilance certification and real-time adverse event reporting infrastructure that tele-sales platforms handle through automated workflows.
- Field Sales:Deploys medically trained representatives for face-to-face physician engagement, requiring territory-level pharmacovigilance protocols and sample-handling logistics. Demand concentrates in Germany's pharmaceutical corridor around Frankfurt, driven by specialty drug launches needing scientific liaison depth that remote channels cannot replicate.
- Tele-sales:Leverages centralized calling infrastructure for routine prescription maintenance and pharmacy replenishment, slashing cost-per-contact versus field deployment. France and the Netherlands show fastest adoption where remote detailing permissions align with national transparency codes.
- Promotional Services:Encompasses congress presence, peer-to-peer education, and digital campaign execution with regulatory review layers.
- Market Access:Delivers HTA submission support, payer negotiation, and pricing strategy for national reimbursement.
By volume, Field Sales leads. By growth pace, Market Access is expanding most quickly.
End User:
Customer procurement sophistication spans from global pharmaceutical procurement teams running competitive tenders to venture-backed biotechs purchasing modular capacity.
- Pharmaceutical Companies:Large sponsors demand integrated platforms spanning clinical-to-commercial handoffs, with multi-year managed service contracts anchoring CSO revenue stability. Germany-based mid-cap firms increasingly unbundle services, buying standalone market access or field-force overflow capacity.
- Biotechnology Firms:Emerging sponsors with lumpy approval timelines favor project-based engagement without fixed commitments, particularly visible among UK venture-backed companies.
- Medical Device Manufacturers:Requires CSOs with dual competency in drug-device combination products and MDR compliance.
- Contract Research Organizations:Purchases CSO services for sponsor-requested commercialization extensions beyond clinical trial completion.
Pharmaceutical Companies anchor contract value. Biotechnology Firms drive fastest expansion in project-based procurement.
Engagement Model:
Pricing structures stratify by commitment duration and exclusivity, with managed services commanding premium rates for dedicated team allocation versus transactional staffing markups.
- Managed Services:Long-term partnerships embedding CSO teams within sponsor commercial operations, with shared KPIs and outcomes-linked compensation. Large pharmaceutical companies across France and Germany dominate this segment, seeking regulatory risk transfer and fixed-cost predictability.
- Dedicated Teams:Exclusive representative allocation for single-sponsor deployment without full operational integration.
- Project-Based Engagement:Modular contracts for launch preparation, indication expansion, or geographic market entry, capturing emerging biotech demand for flexible capacity.
- Staffing Solutions:Transactional placement of individual representatives without strategic service overlay.
Managed Services holds revenue concentration. Project-Based Engagement climbs the fastest as biotech procurement fragments.
Market Segment:
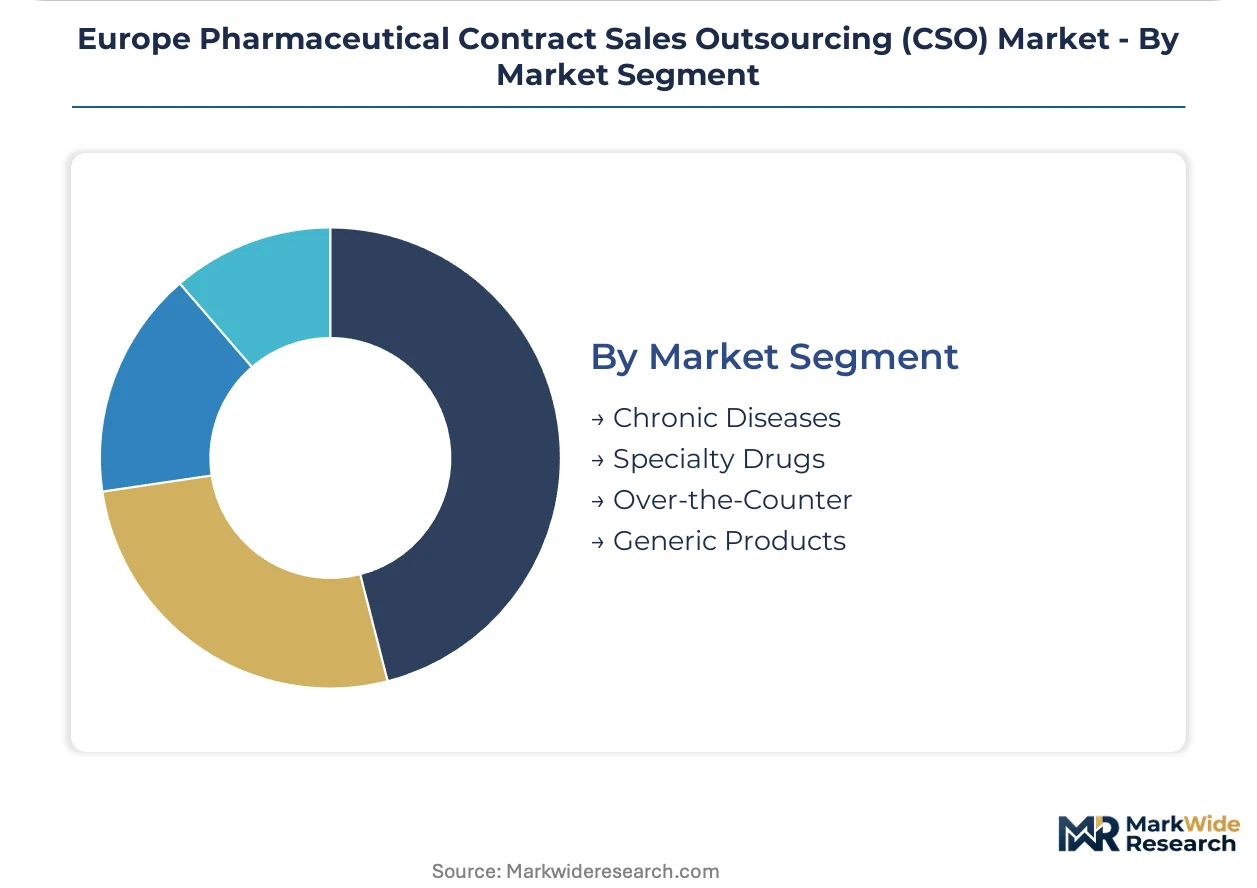
Therapeutic category dictates sales force scientific depth, with specialty drugs requiring PhD-qualified medical science liaisons and chronic disease portfolios deploying larger but less credentialed teams.
- Specialty Drugs:Targets complex therapeutics in oncology, rare disease, and immunology requiring scientific exchange depth and payer navigation expertise. Demand clusters in Germany's dense biotech ecosystem around Heidelberg, where EMA proximity accelerates regulatory-intense launches.
- Chronic Diseases:Covers diabetes, cardiovascular, and respiratory maintenance medications with high-volume, lower-margin sales economics.
- Over-the-Counter:Emphasizes pharmacy channel management and consumer marketing rather than physician detailing.
- Generic Products:Focuses on price-competitive tender participation and volume retention against branded erosion.
Chronic Diseases dominates representative headcount. Specialty Drugs shows steepest expansion trajectory on pricing power and HTA complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main corridor's high-speed rail network and Frankfurt Airport cargo terminals anchor Germany's pharmaceutical logistics dominance across Central Europe. This infrastructure underwrites rapid field-force deployment for EMA-regulated product launches.
Germany
Specialty drug manufacturers in the Frankfurt-Heidelberg corridor drive demand for scientifically credentialed sales teams. The country's national pharmaceutical regulator, the Federal Institute for Drugs and Medical Devices (BfArM), enforces strict transparency requirements under the Arzneimittelmarkt-Neuordnungsgesetz (AMNOG) framework. Bavaria's Munich biotech cluster concentrates emerging sponsor headquarters seeking modular CSO capacity.
France
Paris-based pharmaceutical procurement teams favor long-term managed service partnerships for chronic disease portfolios. The National Agency for Food, Environmental and Occupational Health Safety (ANSES) and the National Commission on Informatics and Liberty (CNIL) impose dual compliance layers on digital physician engagement. The Lyon-Saint-Étienne corridor hosts mid-cap firms unbundling services into standalone market access contracts.
United Kingdom
Venture-backed biotechs in London and Cambridge favor project-based engagement without fixed commitments. The Association of the British Pharmaceutical Industry (ABPI) Code operates under disclosure timelines divergent from EU baseline requirements. The Golden Triangle research cluster generates lumpy approval pipelines demanding flexible staffing models.
Netherlands
Tele-sales adoption accelerates in Amsterdam and Rotterdam where remote detailing permissions align with national transparency frameworks. The Dutch Medicines Evaluation Board (CBG-MEB) maintains pharmacovigilance protocols compatible with centralized calling infrastructure. The Leiden bio-science park concentrates gene therapy sponsors purchasing hybrid field-remote deployment.
Poland
Western European CSOs deploy proven payer-negotiation methodologies ahead of localized competitor formation. The Office for Registration of Medicinal Products, Medical Devices and Biocidal Products enforces EMA-aligned post-market surveillance. Warsaw and Kraków emerge as cost-competitive hubs for overflow capacity serving German sponsor demand.
Europe Pharmaceutical Contract Sales Outsourcing (CSO) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in discrete service modules. The vendor base stratifies between consolidated multi-service conglomerates and niche staffing boutiques. Three archetypes dominate: pan-European data infrastructure operators, flexible staffing model specialists, and integrated clinical-to-commercial handoff providers. Competitive moves concentrate on M&A for regulatory compliance capabilities and technology licensing for AI-enabled physician targeting.
Within the platform integrator tier, IQVIA Inc. and Syneos Health Inc. occupy positions exemplifying scale-driven infrastructure deployment. Ashfield Engage (Inizio) represents the flexible staffing archetype, anchoring project-based procurement patterns among emerging biotech sponsors. These three entities collectively illustrate how CSO competitive positioning fragments across engagement-model preferences rather than geographic coverage alone.
| Leading Market Players |
|---|
| IQVIA Inc. |
| Syneos Health Inc. |
| Parexel International Corporation |
| ICON plc |
| EVERSANA |
| Ashfield Engage (Inizio) |
| Amplity Health |
| Uniphar Group |
| PHOENIX Group |
| Others |
Supply & Pricing Matrix
Undercapacity in Germany's pharmaceutical corridor around Frankfurt and Heidelberg is tightening capacity allocation decisions for contract sales organizations, compressing margins on standardized field-force deployments while elevating pricing power for scientifically credentialed teams serving EMA-regulated specialty launches.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across European pharmaceutical contract sales outsourcing, with algorithmic audit compliance costs stratifying providers into premium-mid-economy pricing differentiation based on documentation infrastructure depth. Managed services contracts anchored to large pharmaceutical sponsors command rate premiums for dedicated team allocation and regulatory risk transfer, while project-based engagements for emerging biotechs exhibit acute price sensitivity due to unpredictable approval timelines and venture capital constraints. Pricing pressure stems from the EU AI Act's capital-intensive validation burdens on physician-targeting platforms, forcing technology-enabled providers to absorb compliance costs or surrender margin.
Supply Chain Analysis
Tariff exposure between the United Kingdom and European Union member states dominates supply chain risk architecture for multi-country CSO campaigns, compelling redundant compliance infrastructure investments. Talent sourcing concentrates in Germany, France, and the Netherlands, where medically trained representatives with dual qualifications in scientific liaison and digital engagement tools remain scarce. The service delivery model rests on pan-European data infrastructure operated by platform integrators, with distribution running through centralized tele-sales hubs in Amsterdam and Rotterdam alongside territory-based field deployment anchored to Germany's Rhine-Main logistics network.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's pharmaceutical contract sales outsourcing market sits in early-cycle expansion, with EMA pharmacovigilance burden and HTA complexity accelerating sponsor reliance on outsourced regulatory infrastructure ahead of in-house buildout.
For Market Incumbents: Pre-empt modular service unbundling by deepening flexible staffing infrastructure targeting UK venture-backed biotechs with lumpy approval timelines, while defending integrated platform positions through AI-enabled physician targeting capabilities that satisfy EU AI Act documentation requirements. Consolidate regulatory compliance capabilities via targeted capability acquisitions in France and Germany where national transparency codes layer atop EU baseline obligations.
For New Entrants and Emerging Players: Central and Eastern European markets, particularly Poland and the Czech Republic, represent the most penetrable entry point for Western European CSO methodologies ahead of localized competitor formation. Deploy proven payer-negotiation frameworks from Germany's AMNOG environment into Warsaw and Kraków, capturing cost-competitive overflow capacity demand from German mid-cap sponsors seeking geographic diversification without regulatory complexity multiplication.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because EMA pharmacovigilance convergence and HTA negotiation specialization create durable competitive moats around compliance infrastructure investments. Target acquisition profiles emphasizing EudraVigilance-certified training platforms and real-world evidence integration capabilities. Monitor DARWIN EU network convergence with field-force data collection as the signal for outcomes-linked contracting inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Compliance Infrastructure Investment | EU AI Act documentation capabilities separate premium-tier providers from commoditized staffing competitors in Germany. |
| Real-World Evidence Integration | DARWIN EU network convergence enables differentiated outcomes-linked contracting for EMA-regulated specialty launches. |
| Central and Eastern Europe Expansion | Poland and Czech Republic deployment captures underpenetrated demand before localized CSO competitor formation accelerates. |
| Modular Service Unbundling | Project-based engagement models align capacity allocation with UK venture-backed biotech procurement fragmentation patterns. |
| Pharmacovigilance Training Platform Development | EudraVigilance certification infrastructure addresses operational drag from accelerating pipeline cadences across Frankfurt-Heidelberg corridor. |
Research Methodology
A spread of perspectives from commercial operations executives at specialty drug manufacturers, regulatory affairs leads navigating EMA pharmacovigilance protocols, payer access specialists managing HTA submissions, and CSO procurement directors converged on the working assumptions underlying this analysis. Secondary validation drew from EMA submission databases, national transparency code filings in France and the UK, ClinicalTrials.gov launch timelines, and formulary access records. Bottom-up service demand modeling triangulated against top-down pharmaceutical R&D pipeline projections across the analysis window.
Demand-supply balance framing anchored the forecast framework, with segmentation across service type, engagement model, therapeutic category, and regional regulatory cluster modeled throughout the projection horizon. CAGRs derived from sponsor spending patterns on outsourced commercialization, weighted by pipeline stage distribution and EMA approval velocity. Industry-specific inputs included EudraVigilance certification lag times and AMNOG negotiation cycle durations.
Practitioners should monitor EMA guidance evolution on digital promotion, EU AI Act enforcement patterns, and HTA convergence initiative progress for early signals requiring forecast revision. Regulatory timeline acceleration or pharmacovigilance burden reduction could materially alter outsourcing elasticity assumptions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Ebola Virus Vaccine Market
Pharmaceuticals
Levofloxacin Lactate Injection Market
Pharmaceuticals
Global Thin Film Drugs Market
Pharmaceuticals
Prescription Stimulants Market
Pharmaceuticals
Canine Dilated Cardiomyopathy Drugs Market
Pharmaceuticals
GLP-1 Receptor Agonist Market
Pharmaceuticals
Vutrisiran Market
Pharmaceuticals
India Over-The-Counter Drugs (OTC) Market
Pharmaceuticals
Global Gout Therapeutics Market
Pharmaceuticals
Celiac Disease Drugs Market
Pharmaceuticals
Simvastatin Market
Pharmaceuticals
Metastatic Cancer Treatment Drug Market
Pharmaceuticals
Acne Drugs Market
Pharmaceuticals
Middle East and Africa Anti-Fungal Agents Market
Pharmaceuticals
Global Anticoagulant Reversal Drugs Market
Pharmaceuticals
Hyperphosphatemia Drugs Market