
 Global Inhaled Antibiotics Market | 2026-2036
Global Inhaled Antibiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Inhaled Antibiotics Market Foresight
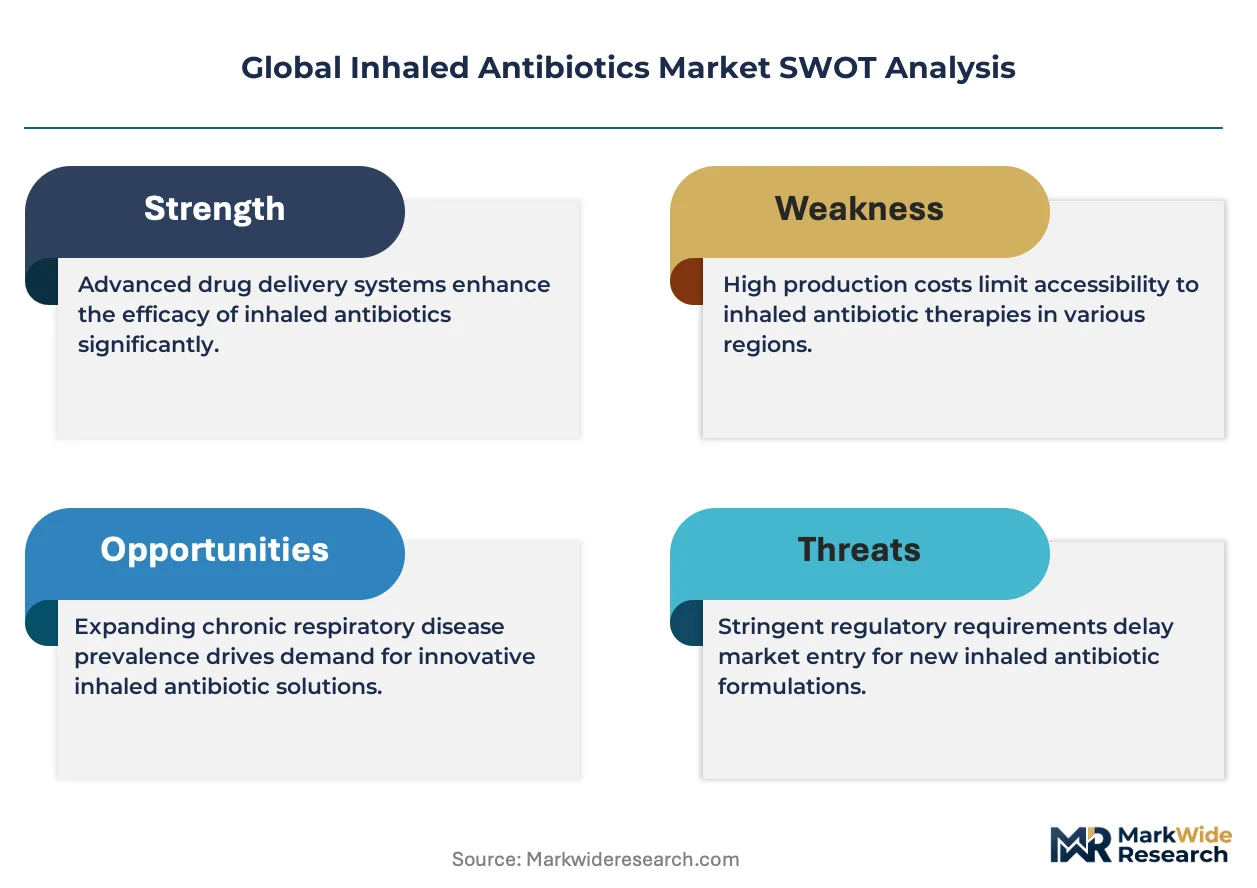
CE marking under the EU Medical Device Regulation (MDR) is collapsing the field of device-drug combination suppliers eligible to serve European patients. Novartis AG leverages its integrated inhaled therapy platform to sustain leadership across nebulized antibiotic formulations. Insmed Incorporated anchors its position through specialization in liposomal amikacin delivery for refractory infections. Chiesi Farmaceutici SpA competes on geographic dominance in Southern European respiratory markets.
Inhaled antibiotics constitute pharmaceutical agents formulated for pulmonary deposition via aerosolized or powdered delivery systems, typically requiring particle size distributions between 1 and 5 micrometers to achieve optimal alveolar penetration. These therapies serve primarily to treat drug-resistant bacterial infections in patients with compromised lung architecture or mechanical ventilation dependence. Tobramycin dominates current revenue pools due to established clinical protocols in cystic fibrosis management, while liposomal formulations represent the fastest-growing product class as manufacturers seek enhanced local drug retention and reduced systemic toxicity. Dry powder inhalers command premium positioning in homecare settings, whereas nebulizer-based delivery retains structural importance in intensive care applications where ventilator compatibility governs purchasing decisions.
The FDA's orphan drug program and EMA's pediatric investigation plans jointly shape development priorities, incentivizing sponsors to pursue narrow indications with extended market exclusivity provisions. The European F-Gas Regulation constrains propellant choices for metered-dose inhaler platforms, redirecting formulation investment toward dry powder and soft mist alternatives. Stakeholders must monitor evolving pharmacopeial standards for inhaled product characterization, as harmonization between USP and EP methodologies will determine which manufacturers can streamline multi-jurisdictional filings without redundant clinical bridging studies.
Market Dynamics
Particle engineering for targeted alveolar deposition is decomposing traditional formulation approaches, as manufacturers abandon simple micronization in favor of engineered porous structures and lipid encapsulation systems that extend pulmonary residence time.
Growth Catalysts
- Orphan drug exclusivity frameworks:The FDA's orphan drug designation pathway and EMA's pediatric investigation plans accelerate development timelines for rare respiratory indications, compressing regulatory review periods for sponsors targeting refractory infections.
- Cystic fibrosis center expansion:Specialized respiratory care infrastructure in the United States concentrates patient access to nebulized and dry powder antibiotic therapies, creating predictable demand corridors for device-drug combination suppliers.
- Mechanical ventilation protocols:Intensive care units in Germany and Japan standardize inhaled antibiotic prophylaxis for ventilator-associated pneumonia, embedding aerosolized delivery into critical care workflows.
Market Restraints
- Propellant supply constraints:The European F-Gas Regulation restricts hydrofluorocarbon availability for metered-dose inhaler platforms, forcing reformulation investment toward dry powder and soft mist alternatives with higher development costs.
- Device-drug combination complexity:CE marking under the EU Medical Device Regulation collapses the supplier field eligible to serve European patients, as smaller manufacturers lack resources for clinical performance documentation.
- Systemic toxicity substitution risk:Intravenous antibiotic protocols retain preference in many hospital formularies due to established reimbursement codes and nursing familiarity, limiting inhaled therapy penetration.
Strategic Opportunities
- Homecare delivery channel expansion:Dry powder inhaler platforms command premium positioning in United States homecare settings where patient self-administration reduces hospital readmission costs and payer burden.
- Pharmacopeial harmonization:Convergence between USP and EP methodologies for inhaled product characterization enables streamlined multi-jurisdictional filings without redundant clinical bridging studies for qualified sponsors.
- Non-CF bronchiectasis applications:Refractory non-tuberculous mycobacterial infections represent an underpenetrated indication where liposomal amikacin formulations demonstrate clinical differentiation from standard-of-care.
Industry Challenges
- Aerosol physics talent scarcity:Formulation scientists with combined expertise in pulmonary deposition modeling and pharmaceutical manufacturing process design command premium compensation, constraining R&D scaling for mid-cap developers.
- Legacy nebulizer integration friction:Intensive care procurement committees face capital allocation conflicts between ventilator-compatible nebulizer systems and emerging vibrating mesh technologies with incompatible cleaning protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Inhaled Antibiotics Market |
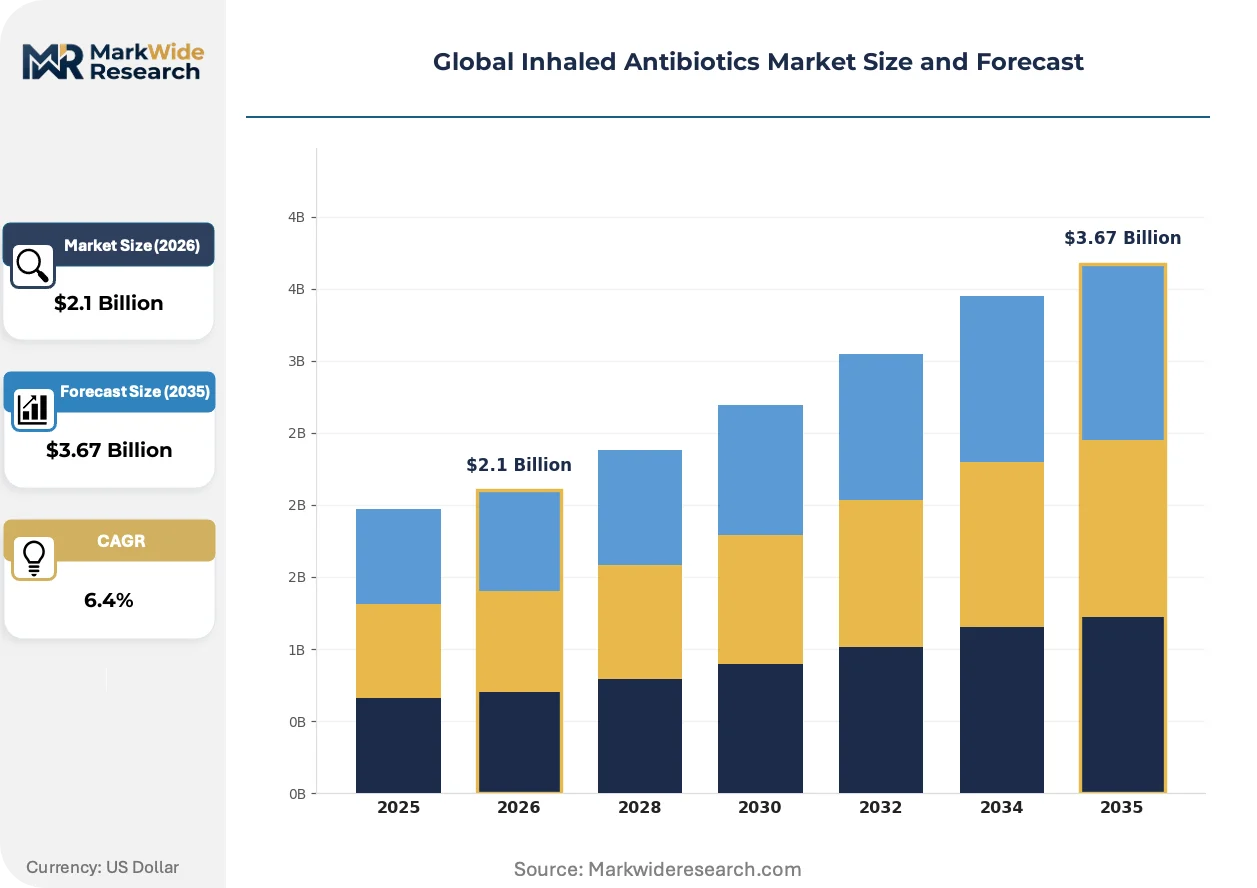
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tobramycin, Colistin, Aztreonam, Levofloxacin, Amikacin Application: Cystic Fibrosis, Bronchiectasis, Hospital-Acquired Pneumonia, Ventilator-Associated Pneumonia, Chronic Obstructive Pulmonary Disorder End User: Specialty Clinics, Respiratory Care Centers, Ambulatory Surgery Centers, Homecare Providers, Pulmonary Rehabilitation Centers Delivery Mode: Dry Powder Inhalers, Nebulizers, Metered-Dose Inhalers, Soft Mist Inhalers, Intratracheal Instillation |
| Companies Covered | Novartis AG, Gilead Sciences Inc, Insmed Incorporated, Chiesi Farmaceutici SpA, Teva Pharmaceutical Industries Ltd, Bayer AG, Grifols SA, Hikma Pharmaceuticals PLC, Lupin Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Inhaled Antibiotics Market Shifts & Advancements
Lipid-based encapsulation technologies and adaptive device platforms are actively restructuring competitive advantage in inhaled antibiotic development, rewarding integrated capabilities over pure-play pharmaceutical or device specialization.
Engineered porous particle technology is decomposing conventional spray-dried lactose formulations by enabling high drug loading with improved aerodynamic performance. Cystic fibrosis treatment centers in the United States and United Kingdom adopt these platforms for tobramycin delivery at accelerating pace. The technology is compressing manufacturing batch complexity while extending patent protection horizons for reformulated legacy molecules.
REACH and RoHS compliance requirements in Europe are constraining excipient selection and device material composition for combination products. Manufacturers face reformulation costs or supply chain requalification when legacy plasticizers or stabilizers lose authorization. Dry powder inhaler categories face the steepest adaptation burden due to polymer-dependent reservoir and blister designs.
Hospital pharmacy committees now unbundle device procurement from drug supply contracts, reversing historical bundling arrangements that locked institutions into single-source combinations. This pattern disrupts traditional device-drug pairing strategies and elevates standalone device performance metrics in purchasing evaluations. The United States acute care segment exhibits this shift most visibly, with group purchasing organizations rewriting contract templates to separate component sourcing.
Global Inhaled Antibiotics Market Segmentation
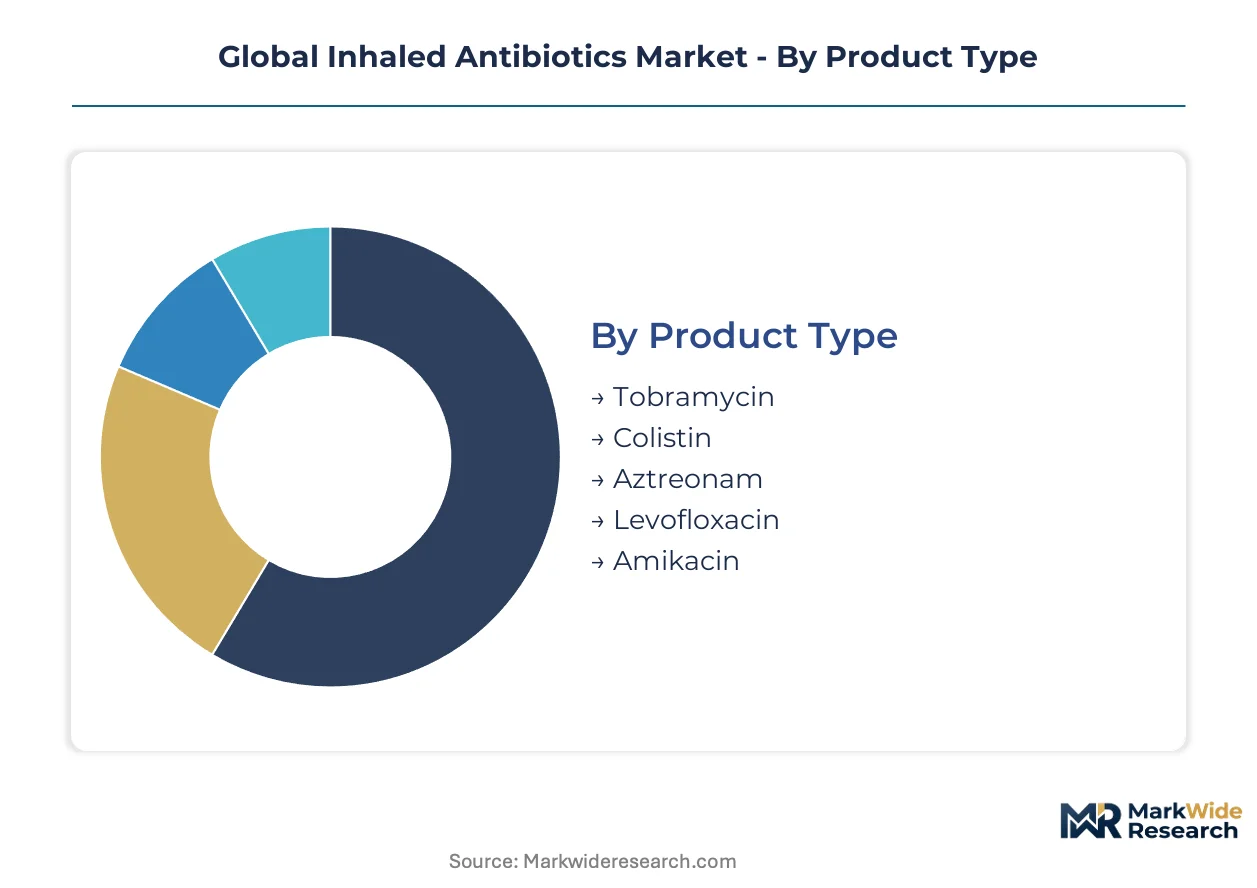
Segmentation in inhaled antibiotics reveals divergent commercial pathways: hospital procurement committees prioritize ventilator-compatible nebulizer systems, while homecare channels favor dry powder platforms that reduce nursing supervision costs. Understanding these channel dynamics enables manufacturers to align formulation investments with reimbursement realities across acute and chronic care settings.
Product Type:
Channel-mix patterns vary sharply across antibiotic classes, with legacy molecules flowing through established hospital formularies while liposomal formulations capture specialty pharmacy dispensing.
- Tobramycin:Aminoglycoside antibiotic formulated for aerosolized delivery via nebulizer or dry powder systems, achieving alveolar deposition through optimized particle size distribution. Demand concentrates in United States cystic fibrosis centers where established clinical protocols and payer familiarity sustain formulary placement. FDA orphan drug exclusivity reinforces manufacturer commitment to this segment despite generic competition pressure.
- Amikacin:Liposomal encapsulation technologies enable extended pulmonary residence time and reduced systemic toxicity compared to intravenous administration. Growth concentrates in refractory non-tuberculous mycobacterial infections where standard-of-care fails, with Insmed Incorporated's liposomal formulation anchoring specialty pharmacy distribution in North American and European markets. EMA pediatric investigation plans accelerate development timelines for rare indication expansion.
- Colistin:Polymyxin antibiotic reserved for multidrug-resistant Gram-negative infections in intensive care settings, delivered via nebulizer for ventilator-associated pneumonia prophylaxis.
- Aztreonam:Monobactam antibiotic targeting Pseudomonas aeruginosa in cystic fibrosis patients with tobramycin intolerance or resistance.
- Levofloxacin:Fluoroquinolone antibiotic with broad-spectrum coverage, primarily deployed in bronchiectasis exacerbations through nebulized delivery.
By volume, tobramycin leads due to decades of clinical protocol embedding. By growth pace, liposomal amikacin formulations are gaining share fastest through orphan indication expansion.
Application:
Cost-tier stratification separates acute infection management reimbursed through DRG codes from chronic disease maintenance funded via specialty pharmacy benefits.
- Cystic Fibrosis:Genetic disorder producing thick mucus accumulation and chronic bacterial colonization requiring lifelong antibiotic suppression. United States treatment centers concentrate patient volume and drive nebulizer system standardization, with Medicaid and commercial payer contracts locking in predictable reimbursement corridors for device-drug combinations.
- Ventilator-Associated Pneumonia:Nosocomial infection developing in mechanically ventilated patients, targeted by inhaled prophylaxis protocols in German and Japanese intensive care units. Procurement committees in these markets prioritize ventilator-compatible nebulizer systems with validated cleaning protocols, embedding aerosolized antibiotics into critical care workflows.
- Bronchiectasis:Irreversible bronchial dilation with chronic infection risk, representing an expanding indication as non-CF populations gain diagnostic recognition.
- Hospital-Acquired Pneumonia:Infection developing after hospital admission, addressed through combination intravenous and inhaled antibiotic protocols in high-acuity settings.
- Chronic Obstructive Pulmonary Disorder:Progressive airflow limitation with acute exacerbation risk, where inhaled antibiotics remain investigational for bacterial colonization management.
Cystic fibrosis generates the highest per-patient revenue due to chronic administration requirements. Ventilator-associated pneumonia applications are expanding most quickly as European and Asian critical care units adopt prophylactic protocols.
End User:
Customer-type concentration shapes device performance requirements, with institutional purchasers prioritizing capital durability and homecare channels emphasizing patient self-administration simplicity.
- Homecare Providers:Post-acute and chronic care settings where patients self-administer dry powder antibiotic therapies under remote nursing supervision. United States Medicare home health benefit structures and commercial payer readmission reduction programs concentrate demand here, with group purchasing organizations unbundling device from drug procurement to enable standalone inhaler selection.
- Respiratory Care Centers:Specialized facilities integrating diagnostic, therapeutic, and rehabilitation services for complex pulmonary conditions. These centers in the United Kingdom and Germany standardize nebulizer platform selection across patient cohorts, creating volume concentration for compatible antibiotic formulations.
- Specialty Clinics:Physician practices focused on cystic fibrosis or bronchiectasis management, prescribing nebulized and dry powder therapies.
- Ambulatory Surgery Centers:Outpatient facilities with limited inhaled antibiotic deployment for perioperative prophylaxis.
- Pulmonary Rehabilitation Centers:Therapy-focused facilities where inhaled antibiotics support exercise tolerance improvement in chronic lung disease.
Respiratory care centers dominate institutional volume through protocol standardization. Homecare providers are climbing the fastest as reimbursement shifts toward outpatient chronic disease management.
Delivery Mode:
Maturity-stage differentiation separates established nebulizer platforms with extensive clinical validation from emerging soft mist technologies seeking market entry.
- Dry Powder Inhalers:Breath-actuated devices delivering micronized antibiotic particles without propellant, enabling patient self-administration in homecare settings. United States cystic fibrosis patients favor these systems for portability and reduced cleaning burden compared to nebulizers, with premium pricing sustained through patent-protected device designs and formulary preference.
- Nebulizers:Jet and vibrating mesh systems generating aerosolized drug for passive inhalation, retaining structural importance in intensive care applications. German and Japanese hospital procurement specifications prioritize ventilator circuit compatibility and validated disinfection protocols, locking in supplier relationships for device-drug combinations.
- Soft Mist Inhalers:Propellant-free mechanical systems producing slow-moving aerosol clouds with reduced hand-breath coordination requirements.
- Metered-Dose Inhalers:Pressurized systems facing European F-Gas Regulation constraints on hydrofluorocarbon propellant availability.
- Intratracheal Instillation:Direct airway administration reserved for salvage therapy in mechanically ventilated patients with refractory infections.
Nebulizers retain volume leadership through intensive care protocol embedding. Dry powder inhalers show the steepest expansion trajectory as homecare channels gain reimbursement priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure underwrites Europe's distribution dominance for temperature-sensitive inhaled therapies, while direct air links from Basel and Frankfurt anchor Swiss-German manufacturing corridors.
United States
Cystic fibrosis treatment centers in Boston and Minneapolis concentrate patient volume and drive nebulizer system standardization. The FDA's orphan drug designation pathway compresses regulatory review timelines for sponsors targeting refractory respiratory infections. Medicaid and commercial payer contracts in these metropolitan clusters lock in predictable reimbursement corridors for device-drug combinations.
Germany
Intensive care units in Munich and Heidelberg standardize inhaled antibiotic prophylaxis for ventilator-associated pneumonia, embedding aerosolized delivery into critical care workflows. The EU Medical Device Regulation's CE marking requirements filter device-drug combination suppliers eligible to serve European patients. The Rhine-Main pharmaceutical cluster around Frankfurt sustains formulation expertise for liposomal encapsulation technologies.
United Kingdom
Specialized respiratory care infrastructure in London and Manchester concentrates demand for dry powder antibiotic therapies in homecare settings. The MHRA's post-Brexit regulatory autonomy enables streamlined approval pathways for novel inhaler platforms. The Cambridge-Oxford life sciences corridor attracts particle engineering talent for engineered porous structure development.
Japan
Mechanical ventilation protocols in Tokyo and Osaka hospitals drive nebulizer system procurement with validated cleaning requirements. The PMDA's sakigake designation system accelerates review timelines for innovative inhaled therapies targeting unmet respiratory needs. The Kansai region's medical device manufacturing base supplies vibrating mesh technologies for intensive care applications.
Switzerland
Basel's pharmaceutical innovation ecosystem anchors integrated inhaled therapy platform development across nebulized and dry powder formulations. Swissmedic's alignment with EMA standards enables concurrent European market access strategies. The Lake Geneva region concentrates aerosol physics research talent commanding premium compensation for pulmonary deposition modeling expertise.
Global Inhaled Antibiotics Market Competitive Landscape
Listed leaders compete with private specialists across integrated platform capabilities, with publicly traded pharmaceutical conglomerates leveraging cross-therapeutic respiratory expertise against focused private developers. The field organizes around three archetypes: diversified conglomerates with inhaled therapy divisions, specialty pharmaceutical firms concentrating on orphan respiratory indications, and generic manufacturers seeking differentiation through device-drug combinations. Consolidation pressure intensifies as CE marking requirements under EU MDR collapse the supplier field, while strategic partnerships between device engineers and formulation scientists accelerate liposomal encapsulation development timelines.
Among diversified pharmaceutical conglomerates, Novartis AG and Gilead Sciences Inc occupy positions exemplifying integrated inhaled therapy platform strategies, while Insmed Incorporated represents the specialist archetype concentrating on liposomal amikacin delivery for refractory infections. Chiesi Farmaceutici SpA anchors geographic dominance patterns in Southern European respiratory markets, with Teva Pharmaceutical Industries Ltd exemplifying generic manufacturer evolution toward device-drug combination differentiation.
| Leading Market Players |
|---|
| Novartis AG |
| Gilead Sciences Inc |
| Insmed Incorporated |
| Chiesi Farmaceutici SpA |
| Teva Pharmaceutical Industries Ltd |
| Bayer AG |
| Grifols SA |
| Hikma Pharmaceuticals PLC |
| Lupin Ltd |
| Others |
Supply & Pricing Matrix
Liposomal encapsulation replacing conventional micronization is redrawing active pharmaceutical ingredient sourcing maps and compressing formulation premiums as manufacturers absorb higher excipient costs against reduced systemic toxicity value propositions.
Pricing Analysis
Volume-discount tiering structures separate cystic fibrosis center procurement contracts from specialty pharmacy dispensing arrangements. Pricing stratifies across orphan-designated liposomal formulations, standard nebulized antibiotics, and generic dry powder alternatives. Cost compression in the nebulizer segment is intensifying because hospital pharmacy committees now unbundle device from drug procurement. Homecare dry powder platforms exhibit the lowest price sensitivity due to Medicare readmission reduction program alignment.
Supply Chain Analysis
Switzerland and Germany anchor liposomal formulation expertise and device engineering capabilities for integrated inhaled therapy platforms. Supply chains draw from Indian API manufacturers for aminoglycoside antibiotics, Italian excipient suppliers for lipid encapsulation systems, and Japanese vibrating mesh component fabricators. Single-source vulnerability concentrates in hydrofluorocarbon propellant supply chains facing EU F-Gas Regulation constraints. Distribution runs through Rotterdam's pharmaceutical cold chain infrastructure for temperature-sensitive biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The inhaled antibiotics market is recovering from cyclical patent cliff pressures as orphan drug exclusivity frameworks reset development economics for refractory infection indications.
For Market Incumbents: Compound device-drug combination capabilities through backward integration into particle engineering talent pools. Lock in cystic fibrosis center formulary placement through ventilator-compatible nebulizer system standardization. Absorb emerging soft mist technology threats by acquiring vibrating mesh platform specialists before CE marking requirements filter smaller competitors from European procurement channels. For New Entrants and Emerging Players: Anchor in non-CF bronchiectasis applications where diagnostic recognition is expanding the addressable patient pool beyond established cystic fibrosis centers. Target refractory non-tuberculous mycobacterial infections as the most penetrable indication where liposomal amikacin formulations demonstrate clinical differentiation. Pursue specialty pharmacy distribution partnerships to bypass hospital formulary committee gatekeeping. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed specialty pharmaceutical firms holding orphan respiratory indications. Long-term viability hinges on regulatory exclusivity durability rather than manufacturing scale advantages. Monitor FDA pediatric investigation plan submission velocity as the inflection indicator for pipeline quality and management execution capability.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA's pathway compresses review timelines and extends market exclusivity for refractory infection sponsors. |
| CE Marking Pathway Completion | EU MDR compliance filters device-drug combination suppliers eligible to serve European patients. |
| Particle Engineering Talent Acquisition | Scarce formulation scientists with pulmonary deposition expertise command premium compensation packages. |
| Specialty Pharmacy Distribution Partnership | Channel alignment bypasses hospital formulary committees and captures homecare reimbursement flows. |
| Reimbursement Strategy Development | Medicaid and commercial payer contracts lock in predictable access corridors for device-drug combinations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA orphan drug filings, EMA pediatric investigation plans, ClinicalTrials.gov protocol registries, and hospital GPO contract databases. Interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists informed demand-side assumptions. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored volume and value estimates.
Segmentation dimensions modeled include antibiotic class, delivery mode, application indication, and regional regulatory cluster across the projection horizon. CAGRs were derived from indication-specific patient growth trajectories and pricing elasticity assumptions. Forecast inputs incorporated cystic fibrosis center expansion rates, ventilator-associated pneumonia protocol adoption curves, and orphan drug exclusivity expiration schedules.
Material uncertainties — regulatory pathway delays, propellant supply disruptions, and pharmacopeial standard divergence — sit outside the modeled envelope. Forecasts reflect assumptions about reimbursement stability and clinical protocol embedding velocity. Recalibration cycles align with material shifts in FDA review timelines and EMA MDR enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Vero Cell Rabies Vaccine Market
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market
Pharmaceuticals
Global Anthrax Vaccine Market
Pharmaceuticals
North America Over the Counter Drugs Market
Pharmaceuticals
Anticonvulsants Market
Pharmaceuticals
Anti-Inflammatory Biologics Market
Pharmaceuticals
Global Eylea Market
Pharmaceuticals
Middle East and Africa Anti-Fungal Agents Market
Pharmaceuticals
Traveler's Diarrhea Treatment Market
Pharmaceuticals
Secondary Myelofibrosis Therapeutics Market
Pharmaceuticals
Pharmaceutical Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Short-Acting Insulin Market
Pharmaceuticals
Depression Drugs Market
Pharmaceuticals
Global Caspofungin Market
Pharmaceuticals
Anti-Radiation Drugs Market
Pharmaceuticals
Global Endometriosis Drugs Market