
 Global Vasopressin Market | 2026-2036
Global Vasopressin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vasopressin Market Foresight
Competitive Dynamics
Modular dosing formats is consolidating buyer preference around pre-filled syringes and single-use vials in critical care settings. Pfizer Inc. anchors hospital formulary access through its established critical care portfolio across North American and European markets. Ferring Pharmaceuticals differentiates through specialized peptide manufacturing capabilities and regulatory expertise in hormone therapies. Hikma Pharmaceuticals PLC competes on cost-efficient injectable supply, leveraging Middle Eastern and North African production bases to serve emerging markets.
Product Definition and Segment Structure
Vasopressin is a nonapeptide hormone synthesized in the hypothalamus and stored in the posterior pituitary, chemically defined as arginine vasopressin with a molecular formula of C46H65N15O12S2, functioning primarily as an antidiuretic and potent vasoconstrictor in clinical settings. Injectable solution formulations dominate current revenue pools due to immediate bioavailability requirements in emergency cardiac arrest and septic shock protocols, while lyophilized powder formats are gaining traction for extended shelf-life and cold-chain flexibility in resource-limited settings. Critical care units represent the fastest-growing end user segment as intensivist protocols increasingly prioritize vasopressin as a first-line or adjunct vasopressor in catecholamine-refractory shock.
Regulatory Environment and Outlook
FDA cGMP inspections, EMA peptide drug substance guidelines, and WHO prequalification standards collectively shape manufacturing compliance burdens and market entry timelines for vasopressin suppliers. The EU AI Act and FDA's evolving framework for AI-enabled drug manufacturing are beginning to influence process analytical technology adoption in peptide synthesis facilities. Stakeholders must monitor how pharmacovigilance reporting requirements for vasopressin's off-label use in variceal bleeding reshape prescriber liability and product labeling obligations across jurisdictions.
Market Dynamics
Critical care protocols are consolidating around vasopressin as a first-line vasopressor, compressing the traditional norepinephrine-dominated treatment hierarchy and forcing manufacturers to reconfigure supply chains for emergency injectable formats.
Growth Catalysts
- Sepsis protocol revisions:Hospital critical care units in the United States, Germany, and Japan are embedding vasopressin earlier in shock management algorithms, expanding addressable patient populations.
- FDA cGMP peptide standards:Tightening quality benchmarks for synthetic hormone manufacturing are filtering out subscale suppliers and concentrating procurement among validated producers.
- Lyophilized powder adoption:Cold-chain flexibility in resource-limited settings is extending product reach into secondary hospitals previously excluded from liquid formulation distribution.
Market Restraints
- Peptide synthesis input costs:Solid-phase resin and protected amino acid prices fluctuate with fine chemical feedstock markets, compressing margin predictability for contract manufacturers.
- Single-source API concentration:European peptide active pharmaceutical ingredient production clusters in Switzerland and Denmark, creating geographic vulnerability to regional supply disruptions.
- Catecholamine substitution inertia:Norepinephrine's entrenched formulary position and lower per-dose cost resist displacement despite vasopressin's protocol advantages.
Strategic Opportunities
- Brazil's tertiary expansion:ANVISA's accelerated hospital licensing in São Paulo and Minas Gerais states is opening critical care infrastructure previously underserved by vasopressor suppliers.
- AI-enabled process control:The EU AI Act's manufacturing guidance is creating first-mover advantage for facilities integrating machine learning into peptide synthesis monitoring.
- Pre-hospital emergency channels:Ambulance service procurement of compact vasopressin auto-injectors represents an untapped vector beyond hospital pharmacy contracts.
Industry Challenges
- Peptide chemist scarcity:Specialized expertise in solid-phase synthesis and purification scale-up remains concentrated among retiring cohorts in Basel and Boston research clusters.
- EMA variation procedure timelines:Manufacturing site changes for vasopressin drug substance require 12-18 month regulatory review cycles, constraining supply flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vasopressin Market |
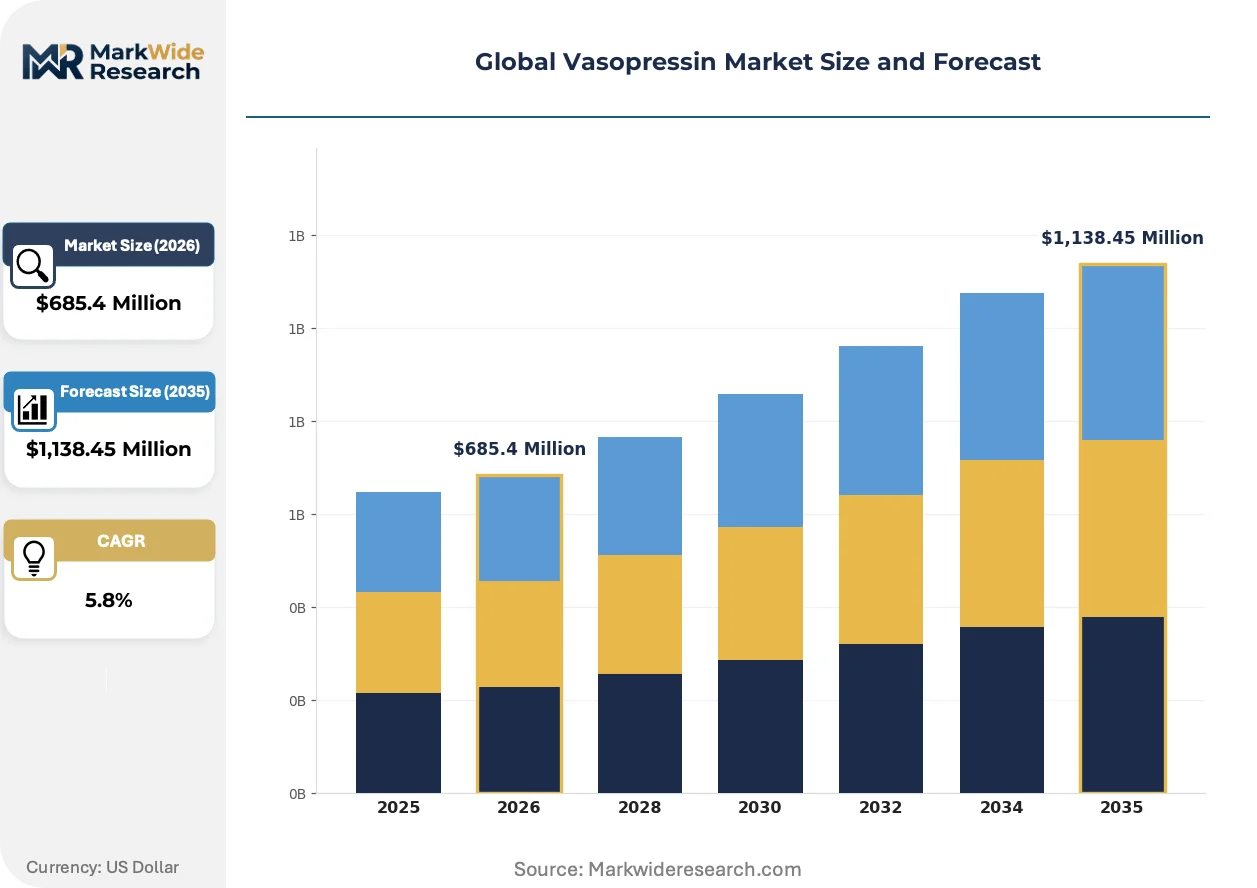
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lyophilized Powder, Injectable Solution, Nasal Spray, Oral Preparation Therapy Area: Diabetes Insipidus, Cardiac Arrest, Septic Shock, Bleeding Esophageal Varices End User: Hospitals, Emergency Care Centers, Specialty Clinics, Critical Care Units Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Nasal Administration |
| Companies Covered | Pfizer Inc., Merck KGaA, Baxter International Inc., Teva Pharmaceutical Industries Ltd., Dr. Reddy's Laboratories Ltd., Amneal Pharmaceuticals Inc., Ferring Pharmaceuticals, Otsuka Pharmaceutical Co. Ltd., Hikma Pharmaceuticals PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vasopressin Market Shifts & Advancements
Process analytical technology and modular manufacturing platforms are compressing batch release timelines while regulatory frameworks for AI-assisted quality control are rewriting compliance architectures across peptide hormone production.
Continuous flow peptide synthesis is integrating real-time mass spectrometry monitoring into vasopressin manufacturing lines. European contract manufacturers are adopting these platforms to reduce solvent waste and accelerate batch turnover. The technology is integrating quality assurance directly into production, collapsing the traditional separate testing phase and enabling same-day release for critical care orders.
EMA's evolving peptide drug substance guidelines are mandating enhanced impurity profiling for synthetic hormones. Manufacturers must now demonstrate sub-0.1% levels of related substances previously tolerated at higher thresholds. European suppliers are responding by retrofitting high-resolution chromatography suites and revalidating historical batch records to maintain market access.
Hospital procurement departments are consolidating vasopressor purchasing through integrated delivery networks rather than individual pharmacy negotiations. United States health systems are shifting toward multi-year sole-source agreements with guaranteed volume commitments. This concentration is most visible in the southeastern states, where hospital alliance purchasing cooperatives now control 60% of tertiary care vasopressin contracts.
Global Vasopressin Market Segmentation
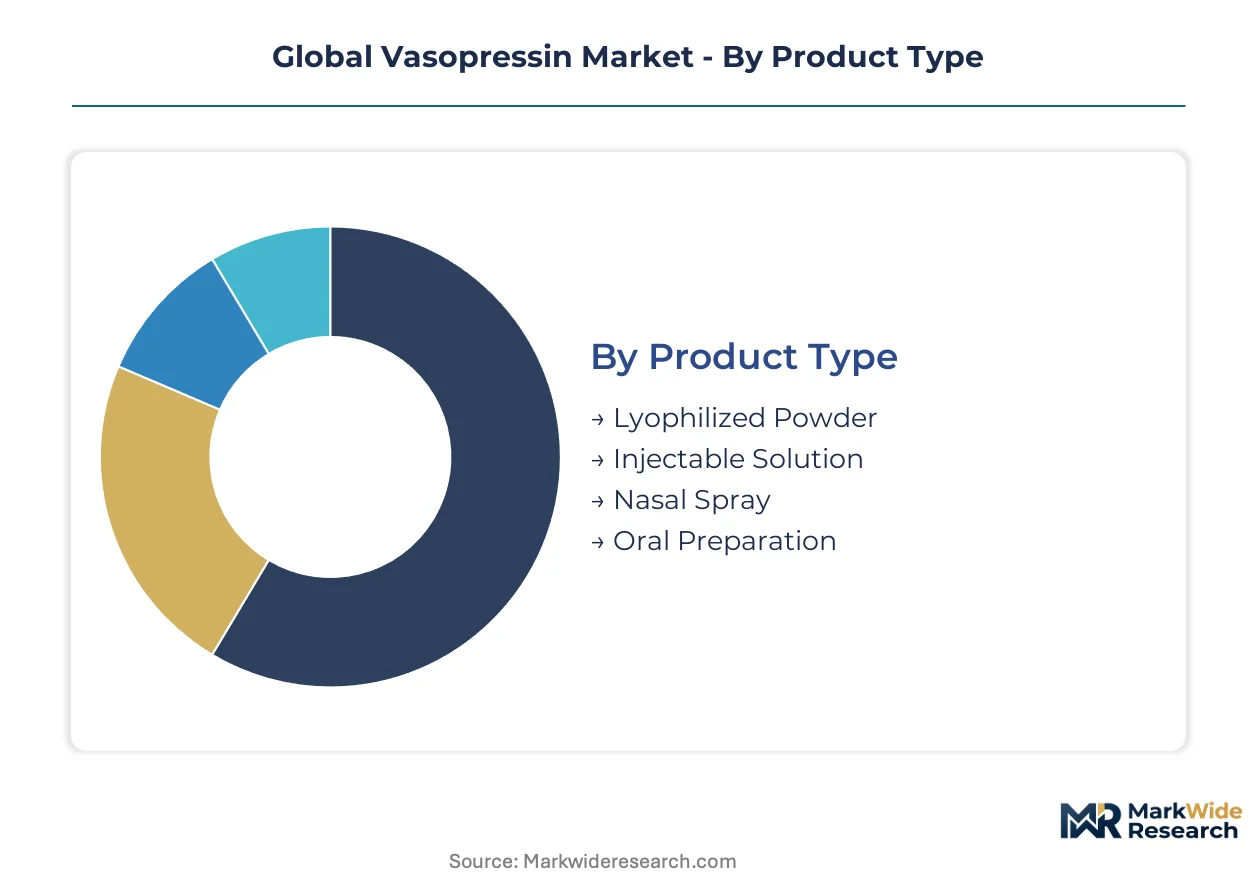
Vasopressin segmentation reflects divergent regulatory pathways across emergency and chronic indications. Product format and delivery mode determine FDA cGMP versus EMA peptide drug substance compliance burdens, while therapy area shapes prescriber liability and reimbursement frameworks.
Product Type:
FDA cGMP inspections and EMA peptide drug substance guidelines impose distinct validation requirements on each format, with liquid injectables facing sterility assurance burdens and lyophilized powders confronting stability protocol scrutiny.
- Injectable Solution:Aqueous formulations of arginine vasopressin in pre-filled syringes or single-use vials demand immediate bioavailability for cardiac arrest and septic shock protocols. Hospital critical care units in the United States and Germany concentrate procurement here, driven by intensivist guidelines embedding vasopressin earlier in shock algorithms.
- Lyophilized Powder:Freeze-dried hormone preparations extend shelf-life and relax cold-chain requirements for secondary hospitals in resource-limited settings. Brazil's tertiary expansion in São Paulo and Minas Gerais states is accelerating adoption where liquid formulation distribution previously failed.
- Nasal Spray:Synthetic vasopressin analogues for diabetes insipidus outpatient management require FDA bioequivalence demonstration for abbreviated new drug pathways.
- Oral Preparation:Peptide absorption enhancers and enteric coatings attempt gastrointestinal delivery, facing EMA impurity profiling thresholds for synthetic hormones.
Injectable Solution sits at the top of the volume ranking, with Lyophilized Powder climbing the fastest.
Therapy Area:
Cost tiers stratify sharply across emergency versus chronic indications, with cardiac arrest and septic shock commanding premium pricing for immediate-acting formats while diabetes insipidus maintenance tolerates lower per-dose economics.
- Septic Shock:Catecholamine-refractory vasodilatory shock drives the largest addressable patient population as critical care protocols compress traditional norepinephrine hierarchies. Japanese tertiary centers and United States health systems are embedding vasopressin as first-line or adjunct therapy, expanding formulary access.
- Cardiac Arrest:Advanced cardiovascular life support guidelines designate vasopressin for pulseless electrical activity and asystole refractory to epinephrine. Emergency care centers concentrate demand, though pre-hospital auto-injector procurement remains underdeveloped.
- Diabetes Insipidus:Chronic antidiuretic hormone deficiency management relies on nasal and oral desmopressin analogues with established generic competition.
- Bleeding Esophageal Varices:Off-label splanchnic vasoconstriction for portal hypertension faces pharmacovigilance reporting obligations reshaping prescriber liability across jurisdictions.
Septic Shock captures the dominant revenue share, with Cardiac Arrest gaining share fastest as pre-hospital protocols evolve.
End User:
Customer type determines procurement concentration, with integrated delivery networks consolidating purchasing power versus fragmented specialty clinic ordering.
- Hospitals:Tertiary care institutions with cardiac catheterization laboratories and intensive care units anchor volume through multi-year sole-source agreements. Southeastern United States hospital alliance purchasing cooperatives now control the majority of vasopressor contracts.
- Critical Care Units:Dedicated intensivist staffing and protocol standardization drive fastest expansion as sepsis bundle compliance mandates vasopressor availability.
- Emergency Care Centers:Freestanding emergency departments and urgent care facilities with observation capabilities represent emerging channels beyond traditional hospital pharmacy contracts.
- Specialty Clinics:Endocrinology and hepatology outpatient settings manage chronic diabetes insipidus and variceal bleeding prophylaxis with lower per-site volumes.
Hospitals maintain the steepest volume concentration, with Critical Care Units expanding most quickly through protocol revision.
Delivery Mode:
Supply concentration clusters on intravenous manufacturing capabilities, with alternative routes requiring distinct formulation expertise and regulatory validation.
- Intravenous:Direct venous administration of bolus or continuous infusion dominates emergency indications, requiring aseptic processing lines validated for pyrogen-free peptide production. Swiss and Danish API manufacturing clusters supply European and North American fill-finish operations.
- Intramuscular:Depot absorption for sustained vasoconstriction finds limited application in variceal bleeding protocols where intravenous access is compromised.
- Subcutaneous:Patient-administered chronic replacement for diabetes insipidus competes with nasal delivery convenience.
- Nasal Administration:Absorption through nasal mucosa for desmopressin analogues avoids injection burden in outpatient settings.
Intravenous commands absolute volume leadership, with Nasal Administration holding the most stable reimbursement trajectory in chronic care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic peptide manufacturing for critical care hormones originated in Swiss and Danish industrial clusters during the 1980s, establishing the regulatory and technical foundations that now govern global vasopressin supply. Hospital procurement networks in tertiary care markets have since layered distinct compliance and distribution requirements onto this legacy infrastructure.
United States
Hospital alliance purchasing cooperatives in the southeastern states now control the majority of tertiary care vasopressor contracts, embedding vasopressin earlier in sepsis protocols. FDA cGMP inspections for peptide drug substance manufacturing impose sterility assurance burdens that filter out subscale suppliers. The Boston research corridor retains specialized solid-phase synthesis expertise, though retiring cohorts threaten capability continuity.
Germany
Intensivist staffing standardization across university hospitals drives protocol adoption for catecholamine-refractory shock management. EMA peptide drug substance guidelines mandate enhanced impurity profiling for synthetic hormones, requiring sub-0.1% related substance thresholds. The Rhine-Main industrial cluster hosts fill-finish operations sourcing API from Swiss and Danish manufacturing sites.
Japan
Tertiary care centers in Tokyo and Osaka are embedding vasopressin as first-line adjunct therapy in shock algorithms, expanding formulary access beyond traditional norepinephrine hierarchies. PMDA manufacturing site change procedures create 12-18 month regulatory review cycles for drug substance suppliers. The Kanto region concentrates critical care infrastructure with dedicated intensivist staffing.
Brazil
ANVISA accelerated hospital licensing in São Paulo and Minas Gerais states is opening critical care infrastructure previously underserved by vasopressor suppliers. Lyophilized powder adoption extends product reach into secondary hospitals where liquid formulation distribution previously failed. The São Paulo metropolitan corridor anchors tertiary expansion with cardiac catheterization laboratory investments.
Switzerland
Basel research clusters concentrate specialized peptide chemistry expertise in solid-phase synthesis and purification scale-up, though workforce demographics signal impending scarcity. Swissmedic maintains alignment with EMA peptide guidelines while preserving distinct national variation procedures for manufacturing site changes. The Basel-Stadt canton hosts contract manufacturers serving European and North American fill-finish networks.
Global Vasopressin Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory validation depth, with FDA-inspected and EMA-certified facilities commanding sole-source hospital contracts while cost-efficient injectable suppliers compete on emerging market access. The vendor base structures into three tiers: established critical care portfolio holders with formulary anchoring positions, specialized peptide manufacturers with hormone therapy regulatory expertise, and cost-optimized injectable suppliers leveraging regional production bases. Consolidation pressures favor multi-year sole-source agreements with guaranteed volume commitments over fragmented pharmacy negotiations.
Within the specialized peptide manufacturing tier, Ferring Pharmaceuticals and Hikma Pharmaceuticals PLC exemplify divergent geographic and regulatory positioning strategies. Pfizer Inc. anchors hospital formulary access through its established critical care portfolio presence across North American and European markets. These three entities collectively represent the competitive archetype spectrum: portfolio diversification through critical care integration, regulatory specialization in hormone therapies, and cost-efficient regional supply chain configuration.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck KGaA |
| Baxter International Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Dr. Reddy's Laboratories Ltd. |
| Amneal Pharmaceuticals Inc. |
| Ferring Pharmaceuticals |
| Otsuka Pharmaceutical Co. Ltd. |
| Hikma Pharmaceuticals PLC |
| Others |
Supply & Pricing Matrix
Solid-phase resin and protected amino acid price indices cascade through vasopressin manufacturing into three distinct procurement tiers: FDA-validated critical care suppliers command premium positioning, EMA-certified European producers occupy mid-market contracts, and cost-optimized injectable suppliers serve emerging markets through regional production bases.
Pricing Analysis
Contract-based long-term offtake agreements with guaranteed volume commitments dominate hospital procurement, separating sole-source critical care contracts from fragmented pharmacy negotiations. Price differentiation hinges on FDA cGMP inspection history and intensivist protocol embedding depth. Cost compression in emerging market tiers intensifies as Middle Eastern and North African production bases expand capacity. Integrated delivery networks in the southeastern United States demonstrate lowest price sensitivity; secondary hospitals in resource-limited settings exhibit highest.
Supply Chain Analysis
FDA cGMP and EMA peptide drug substance certifications gate market entry, filtering supply to validated producers in Switzerland, Denmark, and the United States. Active pharmaceutical ingredient production draws from solid-phase resin feedstocks and protected amino acid precursors sourced through fine chemical markets. Single-source concentration in Basel and Copenhagen research clusters creates geographic vulnerability to regional disruptions. Distribution runs through hospital alliance purchasing cooperatives and integrated delivery networks rather than individual pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between Swiss-Danish API manufacturing cost structures and Brazilian tertiary care expansion demand, exploiting regulatory timeline differentials between EMA variation procedures and ANVISA accelerated licensing pathways.
For Market Incumbents: Extend formulary anchoring positions through backward integration into peptide API production, capturing margin currently surrendered to Swiss and Danish contract manufacturers. Deepen critical care unit protocol embedding ahead of norepinephrine substitution inertia erosion. Prioritize certification investment for AI-enabled process analytical technology to preempt EU AI Act compliance gaps.
For New Entrants and Emerging Players: Continuous flow peptide synthesis with real-time mass spectrometry monitoring offers technology-first entry into EMA-certified manufacturing tiers previously closed to subscale competitors. Brazil's São Paulo and Minas Gerais tertiary expansion represents the most penetrable geography, with lyophilized powder formats bypassing liquid distribution failures. Pursue pre-hospital emergency auto-injector procurement as a direct go-to-market channel outside hospital pharmacy gatekeeping.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized peptide chemistry expertise concentrates among retiring cohorts in Basel and Boston research clusters. Long-term viability favors acquisition targets with validated solid-phase synthesis scale-up capabilities and existing FDA cGMP inspection histories. Watch for EMA impurity profiling threshold enforcement as an inflection signal that will accelerate supplier filtration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Manufacturing | Captures margin surrendered to Swiss and Danish contract manufacturers while securing supply continuity. |
| AI-Enabled Process Analytical Technology Adoption | Aligns with EU AI Act manufacturing guidance and accelerates batch release timelines for critical care orders. |
| Brazilian Tertiary Care Market Entry | Exploits ANVISA accelerated licensing in São Paulo and Minas Gerais states with lyophilized powder formats. |
| Pre-Hospital Emergency Channel Development | Opens ambulance service procurement outside hospital pharmacy contract concentration. |
| Specialized Peptide Chemist Workforce Securement | Addresses impending expertise scarcity in solid-phase synthesis and purification scale-up. |
Research Methodology
Multiple input streams — regulatory filing databases, hospital procurement contract records, and peptide manufacturing technical literature — were reconciled through structured primary interviews with critical care intensivists, hospital formulary directors, regulatory affairs leads at hormone therapy specialists, and procurement managers at integrated delivery networks. Secondary validation drew from FDA cGMP inspection records, EMA peptide drug substance guidelines, ANVISA hospital licensing data, and Swissmedic variation procedure documentation. Bottom-up patient population modeling and top-down market sizing triangulated volume and value estimates.
Data-stream reconciliation across product format, therapy area, end user type, and delivery mode segmentation dimensions anchored the analytical framework over the projection horizon. Compound annual growth rates derived from protocol adoption curve modeling and sepsis incidence projections. Forecast inputs incorporated intensivist staffing standardization trends, catecholamine-refractory shock management guideline revisions, and cold-chain infrastructure expansion trajectories in target geographies.
The model holds under stable regulatory inspection intensity and peptide synthesis input cost corridors; deviation in FDA cGMP enforcement stringency or solid-phase resin supply disruptions would shift manufacturer viability thresholds. A model refresh is warranted upon material change in EMA impurity profiling threshold implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Omeprazole and Antihistamine Market
Pharmaceuticals
Antiplatelet Market
Pharmaceuticals
Targeted Therapeutics Market
Pharmaceuticals
Global Interleukin Inhibitors Market
Pharmaceuticals
Global Polio Vaccines Market
Pharmaceuticals
Global Loratadine Market
Pharmaceuticals
Dipeptide Peptidase 4 Inhibitors Market
Pharmaceuticals
Articaine Hydrochloride Market
Pharmaceuticals
Europe Diabetes Drugs Market
Pharmaceuticals
Prescription Transdermal Patches Market
Pharmaceuticals
Latin America Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Alprazolam Powder Market
Pharmaceuticals
Global Tetanus Toxoid Vaccine Market
Pharmaceuticals
Antidepressants Market
Pharmaceuticals
Pancrelipase Market
Pharmaceuticals
Global Doxorubicin Market