
 Plaque Disclosing Aids Market | 2026-2036
Plaque Disclosing Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Plaque Disclosing Aids Market Analytics
The buyer base for plaque disclosing aids is broadening beyond dental professionals into parent-led home care segments and school wellness coordinators. Procter & Gamble leverages its retail shelf presence to anchor consumer-facing tablet formats in mass-market channels. GC Europe N.V. competes through specialized dental supply relationships that sustain professional-grade gel penetration across European clinics. Sunstar Suisse S.A. differentiates via orthodontic-focused positioning that controls practitioner recommendation flows.
Plaque disclosing aids comprise color-reactive formulations—typically erythrosine, fluorescein, or two-tone dye systems at concentrations between 0.5% and 2.0%—that visually demarcate accumulated biofilm on tooth surfaces to guide brushing behavior or professional cleaning. Tablet formats dominate volume through low unit cost and extended shelf stability, while rinse applications capture faster expansion among pediatric and geriatric users seeking reduced application complexity. Dental clinics represent the mature margin pool where professional authentication commands pricing premiums, whereas home care channels show structural growth as direct-to-consumer subscription models reshape replenishment patterns.
The FDA's OTC monograph framework governs active ingredient safety and labeling claims for U.S. home-use products, while the EU Medical Device Regulation classifies certain professional disclosing systems as Class I devices requiring CE conformity assessment. Japan's PMDA maintains distinct cosmetic-drug boundaries that shape import eligibility for dye-based formulations. Stakeholders must monitor evolving classification thresholds that could resegment channel access requirements between professional and consumer tiers.
Market Dynamics
School-based pediatric dental programs are restructuring procurement channels for plaque disclosing aids, shifting volume from dental supply distributors toward institutional purchasing frameworks that prioritize tablet formats and bulk rinse packaging.
Growth Catalysts
- Germany's statutory dental insurance funds:Preventive care reimbursements for professional-grade disclosing aids sustain clinic demand and normalize patient exposure to biofilm visualization protocols.
- Two-tone dye systems:Advanced formulations distinguishing mature from immature plaque improve brushing instruction outcomes, driving replacement rates in orthodontic and periodontal practices.
- Direct-to-consumer subscription models:Home care replenishment automation captures parent-led segments seeking consistent supply without retail friction.
Market Restraints
- Erythrosine supply concentration:Synthetic dye production clusters in Asian chemical manufacturing hubs, exposing formulators to input cost volatility and qualification delays.
- FDA OTC monograph compliance:Active ingredient safety documentation and labeling claim restrictions extend product development timelines for U.S. home-use entrants.
- Fluorescein-based substitutes:Alternative biofilm visualization methods in professional settings threaten tablet format volume in high-margin clinic channels.
Strategic Opportunities
- Japan's PMDA cosmetic-drug boundary clarity:Import eligibility frameworks for dye-based formulations create first-mover advantages for compliant entrants in Asia-Pacific's aging-consumer market.
- Orthodontic patient retention protocols:Fixed-appliance maintenance programs integrate disclosing aids into long-term compliance monitoring, expanding recurring revenue pools.
- EU MDR Class I device pathway:CE conformity assessment for professional systems enables premium positioning through clinical authentication claims.
Industry Challenges
- Formulation stability expertise:Dye concentration maintenance across shelf life requires specialized chemistry talent scarce in mid-tier manufacturers.
- Dual-channel certification complexity:Professional and consumer tier products demand divergent quality management systems, straining operational bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plaque Disclosing Aids Market |
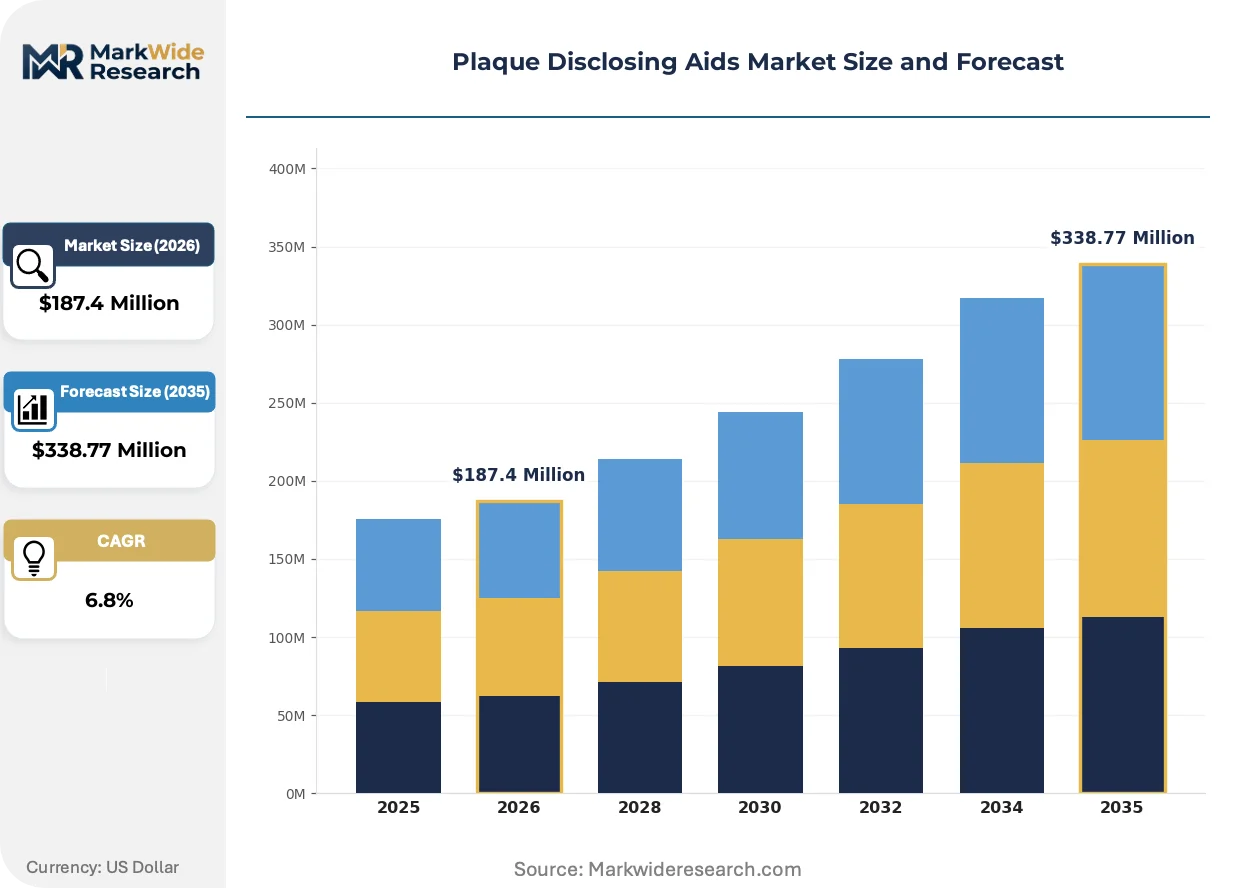
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Rinses, Gels, Sprays Application: Dental Clinics, Home Care, Orthodontics, Educational Institutions Distribution Channel: Online Stores, Pharmacies, Dental Supply Stores, Supermarkets End User: Children, Adults, Seniors, Dental Professionals |
| Companies Covered | Procter & Gamble, GC Europe N.V., Boots Company PLC, Sunstar Suisse S.A., TePe Oral Hygiene Products Ltd, Colgate-Palmolive, Young Dental, Periogen, Patterson Dental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plaque Disclosing Aids Market Evolving Landscape
Digital integration and formulation science are converging to transform how plaque visualization reaches end users, compressing the gap between professional diagnosis and home-based self-monitoring.
Smartphone-compatible fluorescence detection is decentralizing biofilm assessment from clinic-bound devices to consumer handheld hardware. Orthodontic practices are piloting patient-owned UV-LED accessories that pair with app-based brushing coaching. This technology is decentralizing practitioner control over diagnostic interpretation while creating data streams for remote compliance monitoring.
The EU Medical Device Regulation's 2021 implementation tightened classification thresholds for professional disclosing systems, triggering reformulation investments across European dental supply chains. Manufacturers serving German and French markets now segregate production lines to isolate CE-marked professional gels from consumer-tier tablets. Clinic-facing portfolios absorb compliance costs through pricing premiums, while home-use channels face margin compression from additional conformity documentation.
Parent-led subscription procurement is displacing pharmacy-based replenishment in North American home care segments. Direct fulfillment models bypass retail shelf-space constraints and capture usage-pattern data that informs personalized refill timing. This behavioral shift concentrates most visibly in U.S. suburban markets where pediatric dental referrals increasingly bundle disclosing tablets with post-appointment home care instructions.
Plaque Disclosing Aids Market Segmentation
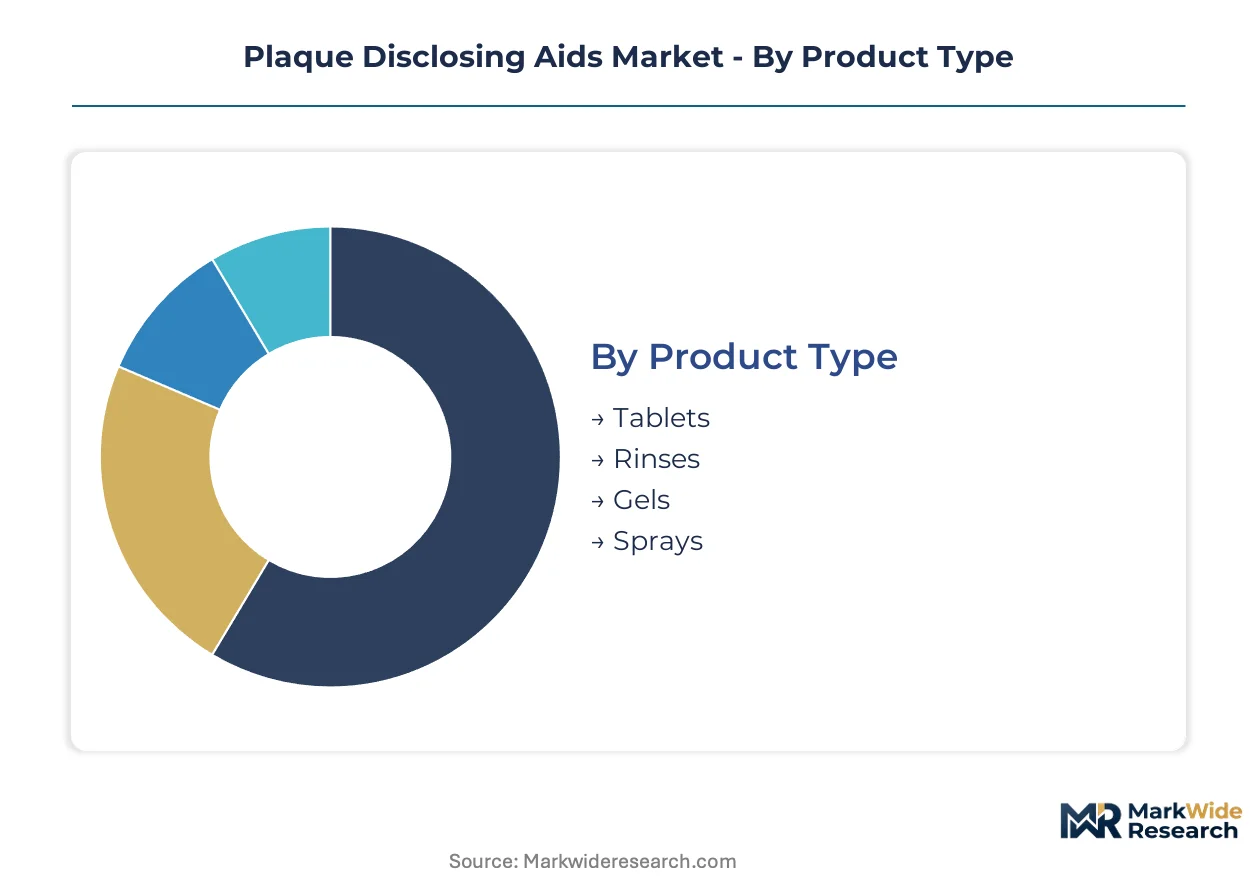
Segmentation in plaque disclosing aids reveals how formulation formats and channel access determine pricing power and user compliance. Each dimension exposes distinct margin structures and regulatory exposure that shape competitive positioning.
Product Type:
Supply concentration in erythrosine dye manufacturing clusters favors tablet production economies, while gel formulations require specialized stability expertise that limits qualified suppliers.
- Tablets:Compressed dye matrices at 0.5-2.0% erythrosine concentration offer 24-month shelf stability and lowest unit economics. School procurement programs in Germany and institutional purchasing frameworks in the United States drive volume concentration here, though margin compression intensifies from bulk pricing demands.
- Rinses:Aqueous formulations reduce application complexity for pediatric and geriatric users, capturing faster expansion in home care channels. Japan's PMDA cosmetic-drug boundary clarity creates import eligibility hurdles that compliant entrants can leverage for premium positioning.
- Gels:Viscous professional-grade systems require CE conformity assessment under EU MDR Class I device pathways, enabling clinical authentication premiums in German and French clinics.
- Sprays:Aerosolized delivery formats occupy niche positioning for orthodontic compliance monitoring, with limited manufacturer base due to propellant regulatory complexity.
Today's leader: Tablets. Tomorrow's challenger: Rinses.
Application:
Cost tier separation between professional authentication and consumer self-monitoring creates divergent quality management requirements that strain operational bandwidth.
- Dental Clinics:Professional-grade systems command pricing premiums through clinical validation and reimbursement integration. Germany's statutory dental insurance funds sustain demand normalization for biofilm visualization protocols.
- Home Care:Direct-to-consumer subscription models reshape replenishment patterns, concentrating parent-led segments in U.S. suburban markets where pediatric referrals bundle tablets with post-appointment instructions.
- Orthodontics:Fixed-appliance maintenance programs integrate disclosing aids into long-term compliance monitoring, with patient-owned UV-LED accessories piloting in practices seeking remote monitoring data streams.
- Educational Institutions:School-based pediatric dental programs shift procurement from dental supply distributors toward institutional frameworks prioritizing bulk packaging and tablet formats.
Orthodontics gains share fastest through recurring revenue integration; home care climbs steepest via subscription automation.
Distribution Channel:
Volume concentration in dental supply relationships sustains professional-grade penetration, while digital channels capture behavioral data that informs personalized refill timing.
- Online Stores:Direct fulfillment models bypass retail shelf-space constraints and capture usage-pattern analytics, with parent-led subscription procurement displacing pharmacy replenishment in North America.
- Pharmacies:Mass-market tablet accessibility anchors consumer-facing formats, though margin pressure mounts from retail slotting fee structures.
- Dental Supply Stores:Specialized relationships sustain professional-grade gel penetration across European clinics, with GC Europe N.V. competing through channel exclusivity arrangements.
- Supermarkets:Low-engagement impulse purchases concentrate in tablet formats with prominent shelf positioning from Procter & Gamble's retail presence.
Channel control tilts toward online stores; dental supply stores defend professional authentication value.
End User:
Customer type maturity varies sharply, with pediatric segments showing structural growth from school program integration while senior users drive rinse format simplicity preferences.
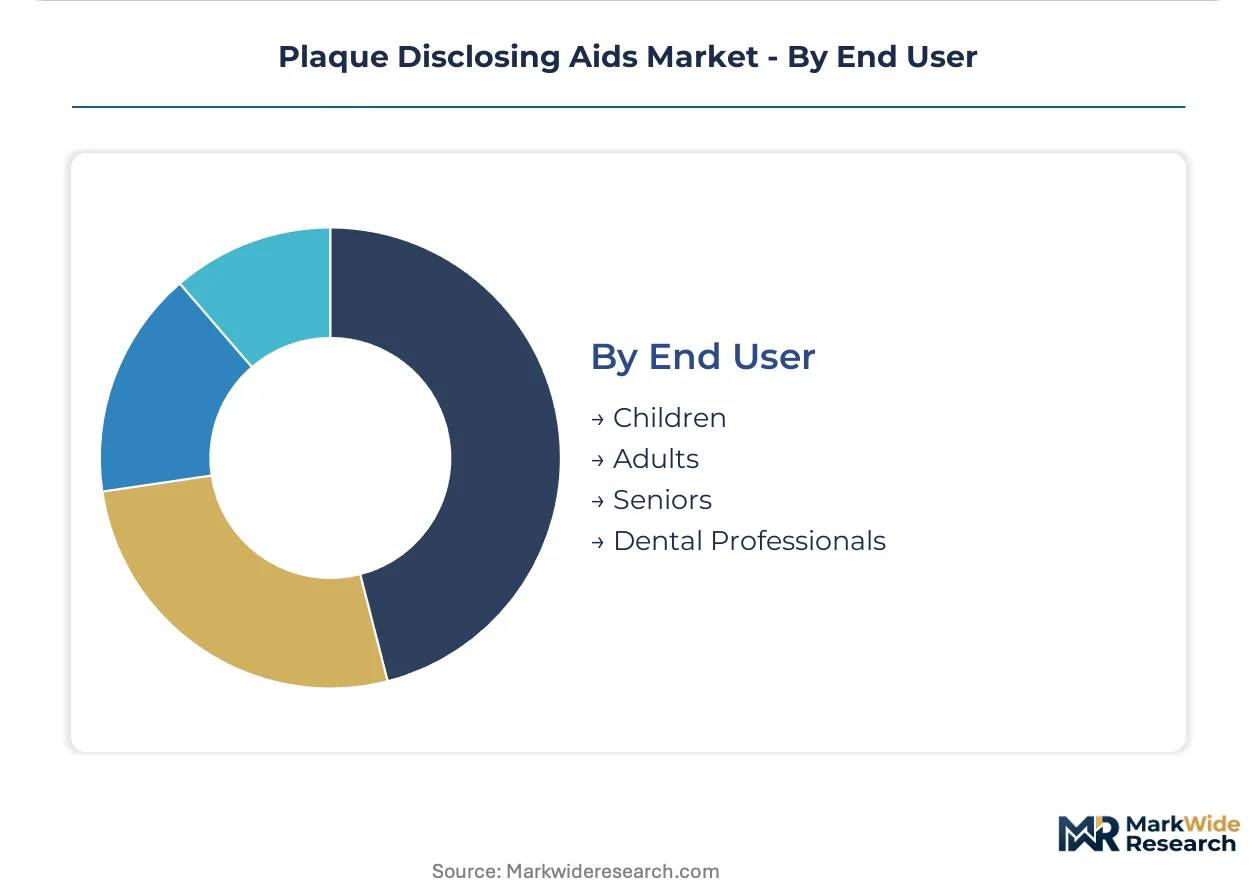
- Children:School-based program exposure normalizes biofilm visualization habits early, creating lifetime user conversion pathways through institutional procurement channels.
- Adults:Orthodontic patient retention protocols and periodontal maintenance programs sustain replacement demand for two-tone dye systems distinguishing mature from immature plaque.
- Seniors:Reduced manual dexterity drives preference for rinse applications over tablet manipulation, with Japan's aging-consumer market presenting first-mover opportunities for compliant dye formulations.
- Dental Professionals:Practitioner recommendation flows control category entry points, with Sunstar Suisse S.A. differentiating through orthodontic-focused positioning that channels professional authority.
Children represent the installed base foundation; seniors offer the steepest expansion trajectory through demographic tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's statutory insurance reimbursements normalize professional-grade disclosing aid usage, while Japan's aging demographics accelerate rinse-format demand through reduced-dexterity preferences. The United States anchors direct-to-consumer subscription growth, with institutional procurement patterns diverging sharply across these three markets.
United States
Pediatric dental referrals in suburban markets bundle disclosing tablets with post-appointment home care instructions, normalizing parent-led procurement. The FDA's OTC monograph framework governs active ingredient safety documentation and labeling claims for home-use entrants. Greater Boston's dental technology cluster pilots smartphone-compatible fluorescence detection systems for remote compliance monitoring.
Germany
Statutory dental insurance funds sustain clinic demand through preventive care reimbursements for professional-grade disclosing aids. The EU Medical Device Regulation's Class I device pathway requires CE conformity assessment for professional gel systems, enabling authentication premiums. Bavaria's dental supply chains absorb compliance costs through segregated production lines isolating CE-marked professional gels from consumer-tier tablets.
Japan
Senior users drive rinse application preferences due to reduced manual dexterity requirements in fixed-appliance maintenance. METI and PMDA maintain distinct cosmetic-drug boundaries that shape import eligibility for dye-based formulations. The Kanto region around Tokyo presents first-mover advantages for compliant entrants targeting Asia-Pacific's aging-consumer market with simplified application formats.
United Kingdom
School-based pediatric dental programs shift procurement from dental supply distributors toward institutional purchasing frameworks prioritizing bulk tablet packaging. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR transition timelines for professional system classifications. London's health technology procurement hubs pilot orthodontic patient retention protocols integrating disclosing aids into long-term compliance monitoring.
India
Expanding private dental clinic networks in metropolitan areas create demand for professional-grade visualization protocols among emerging middle-class patients. CDSCO's pharmaceutical-cosmetic classification boundaries for dye-based formulations remain under development, creating regulatory navigation complexity. Maharashtra's Mumbai-Pune pharmaceutical manufacturing corridor attracts formulation investments targeting price-sensitive tablet production for institutional procurement channels.
Plaque Disclosing Aids Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across channel tiers, with consumer packaged goods majors leveraging retail shelf presence against dental supply specialists defending professional authentication value. The vendor base separates into three strategic archetypes: mass-market consumer brands, professional-grade specialists, and orthodontic-focused niche players. Consolidation pressure concentrates among mid-tier manufacturers lacking formulation stability expertise. Competitive moves center on direct-to-consumer subscription automation and CE conformity investments for EU MDR compliance.
Among diversified consumer packaged goods majors, Procter & Gamble and Colgate-Palmolive exemplify mass-market archetypes with retail channel anchoring. GC Europe N.V. and Sunstar Suisse S.A. occupy professional-grade specialist positions through dental supply relationship control. These named entities represent the spectrum from consumer-facing tablet volume to clinic-facing gel premiums, with each archetype defending distinct margin pools against cross-tier encroachment.
| Leading Market Players |
|---|
| Procter & Gamble |
| GC Europe N.V. |
| Boots Company PLC |
| Sunstar Suisse S.A. |
| TePe Oral Hygiene Products Ltd |
| Colgate-Palmolive |
| Young Dental |
| Periogen |
| Patterson Dental |
| Others |
Value Network & Pricing Analysis
Erythrosine dye spot prices in Asian chemical manufacturing hubs cascade through formulation tiers, compressing margins on consumer-grade tablets while professional gel systems absorb cost volatility through CE-marked authentication premiums in German clinics.
Pricing Analysis
Capacity additions in China's synthetic dye corridor are reshaping price floors for erythrosine-dependent tablet production, though professional-grade gel systems maintain premium-mid-economy pricing differentiation through EU MDR Class I device certification. Price differentiation hinges on clinical validation depth and reimbursement integration, with German statutory insurance coverage insulating clinic-facing tiers from parent-led home care segments where subscription automation intensifies cost compression. Pricing pressure stems from bulk institutional procurement in school-based programs, squeezing standard-tier tablet margins while premium orthodontic gels defend value through fixed-appliance maintenance bundling.
Supply Chain Analysis
Single-source vulnerability sits with erythrosine production concentrated in Chinese and Indian chemical manufacturing corridors, where dye concentration stability expertise remains scarce outside specialized European formulators. Raw material dependencies center on erythrosine, fluorescein alternatives, and two-tone dye system precursors, with formulation chemistry talent anchoring supply security in Bavaria's dental supply chains. Supply chain risk manifests as regulatory qualification delays when Asian dye batches fail FDA OTC monograph documentation standards. Distribution runs through dental supply relationships for professional gels, while direct-to-consumer subscription models bypass retail slotting constraints for home care tablets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Japan's aging-consumer rinse demand and Germany's reimbursement-anchored clinic premiums, exploiting the PMDA cosmetic-drug boundary clarity gap against EU MDR compliance burdens.
For Market Incumbents: Hedge against fluorescein-based substitute technologies in professional channels by deepening backward integration into dye synthesis partnerships in Maharashtra's pharmaceutical corridor, while segregating CE-marked production lines to isolate authentication premiums from consumer-tier margin erosion. For New Entrants and Emerging Players: Begin with Japan's Kanto region rinse applications, where PMDA import eligibility hurdles create defensive moats for compliant first-movers targeting senior dexterity limitations, leveraging direct-to-consumer subscription automation to bypass entrenched dental supply relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier manufacturers possessing formulation stability expertise but lacking dual-channel certification infrastructure, as orthodontic patient retention protocols extend recurring revenue visibility across the analysis window. The inflection signal to watch is smartphone-compatible fluorescence detection adoption rates in Greater Boston's dental technology cluster.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR Class I device classification enables premium positioning in German clinic channels. |
| Direct-to-Consumer Subscription Launch | Bypasses pharmacy slotting fees while capturing usage-pattern data from parent-led segments. |
| Backward Integration into Dye Synthesis | Reduces exposure to erythrosine supply concentration in Asian chemical manufacturing hubs. |
| Orthodontic Practice Partnership | Integrates disclosing aids into fixed-appliance maintenance protocols for recurring revenue. |
| PMDA Import Eligibility Compliance | Unlocks first-mover positioning in Japan's aging-consumer rinse market. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dental supply procurement managers, pediatric program coordinators, orthodontic practice administrators, and formulation chemistry directors with secondary validation from FDA OTC monograph filings, EU MDR conformity assessment databases, PMDA cosmetic-drug classification rulings, and German statutory insurance reimbursement schedules. Bottom-up volume triangulation across tablet, rinse, gel, and spray formats converged with top-down value estimates from dental supply distributor revenue disclosures.
Segment-weighting approaches applied differential growth assumptions across product type, application, distribution channel, and end user dimensions, with CAGRs derived from elasticity modeling of reimbursement policy changes and substitution threat curves. Industry-specific forecast inputs included school-based procurement pipeline tracking in the United Kingdom and orthodontic patient retention protocol adoption rates in U.S. suburban markets.
Caveats apply where FDA OTC monograph revisions or EU MDR classification threshold adjustments could materially shift the outlook for home-use versus professional-tier channel access. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
GCC Dental Implants Market
Dental Devices
Asia-Pacific Dental Lab Market
Dental Devices
Middle East and Africa Dental Lab Market
Dental Devices
Dental Microsurgery Market
Dental Devices
Dental Rapid Prototyping Systems Market
Dental Devices
Argentina Dental Devices Market
Dental Devices
Global Dental Laboratory Welders Market
Dental Devices
Digital Dental Cameras Market
Dental Devices
Dental Scalers Market
Dental Devices
Dental 3D Scanners Market
Dental Devices
Dental Liners and Bases Market
Dental Devices
Glenoid Fossa Prosthesis Market
Dental Devices
Intraoral Dental Scanner Market
Dental Devices
Chile Dental Devices Market
Dental Devices
Dental Diagnostic and Surgical Market
Dental Devices
Dental Anaesthetic Market