
 Plaque Disclosing Market | 2026-2036
Plaque Disclosing Market Size, Share, and Industry Trends Forecast 2026-2036
Plaque Disclosing Market Analysis
Dental hygienist workforce expansion across community college programs is rotating professional-grade plaque disclosing uptake toward preventive care settings. Sunstar Suisse S.A. leverages its periodontal specialty heritage to anchor professional channel dominance in European dental practices. Young Dental sustains manufacturing scale across disposable applicator formats that dental clinics favor for single-patient workflows. Procter & Gamble competes through retail shelf presence and consumer brand recognition in mass-market oral care aisles.
Plaque disclosing agents are colorimetric formulations—typically erythrosine, fluorescein, or two-tone dye systems—that bind to dental biofilm and render it visible under natural or UV light for oral hygiene assessment and patient education. Tablet formats dissolve in saliva to bathe all tooth surfaces, while gel formulations permit targeted application with brushes or syringes for precise plaque mapping. Gels and tablets lead product type revenue due to established reimbursement codes in professional settings, though rinse formats show faster growth in pediatric and geriatric home care where compliance simplicity matters. Personal care and professional dental applications capture the deepest margin pools, with educational segments expanding through dental school curriculum mandates.
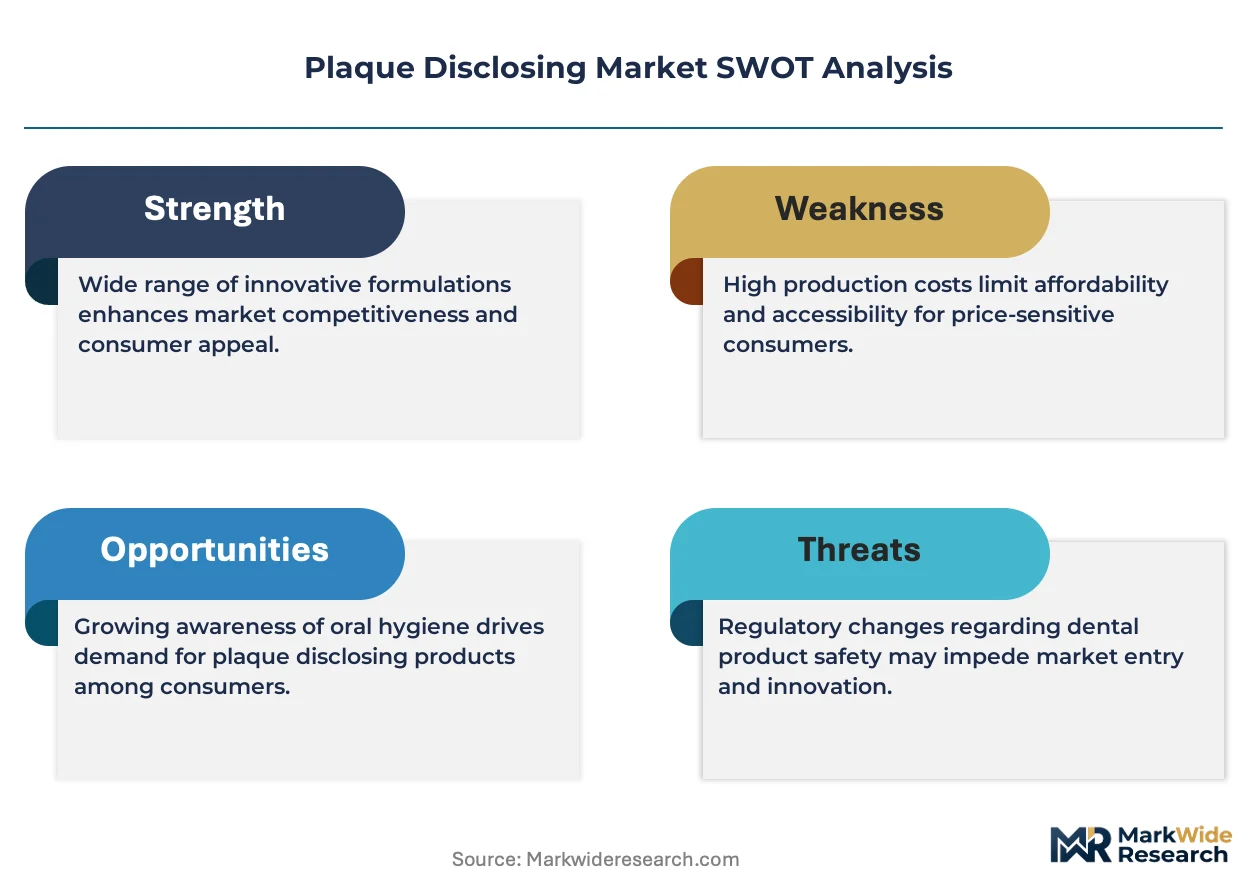
FDA over-the-counter monograph requirements govern dye safety and concentration limits for U.S. consumer products, while the EU Medical Device Regulation classifies certain professional disclosing systems as Class I devices subject to CE marking and post-market surveillance. Japan's Ministry of Economy, Trade and Industry (METI) and Pharmaceutical and Medical Devices Agency (PMDA) coordinate standards for dye-containing oral care imports, creating compliance complexity for multinational suppliers. Stakeholders must monitor whether preventive dental benefits expansion in national health schemes converts reimbursement eligibility into mandatory product specification standards.
Market Dynamics
Community college dental hygienist programs are expanding across the United States, rotating professional-grade plaque disclosing uptake toward preventive care settings and away from specialized periodontal practices. This workforce pipeline shift concentrates demand in reimbursable prophylaxis sessions rather than out-of-pocket specialty visits.
Growth Catalysts
- Germany's statutory dental prevention programs:Insurer-reimbursed prophylaxis sessions routinely incorporate plaque visualization tools, embedding disclosing products into standard care protocols.
- FDA over-the-counter monograph framework:Updated oral care ingredient pathways streamline formulation approvals for consumer-grade dye systems, accelerating retail market entry.
- Tablet dissolution chemistry:Saliva-activated colorimetric binding enables complete oral cavity coverage without clinician assistance, supporting home care compliance.
Market Restraints
- Erythrosine supply concentration:Synthetic dye production clusters in Asian chemical manufacturing hubs, exposing formulators to input volatility and trade friction.
- EU Medical Device Regulation classification:Professional disclosing systems face Class I device requirements with CE marking and post-market surveillance, extending compliance timelines.
- Visual plaque assessment alternatives:Intraoral cameras and fluorescence-based biofilm detection systems offer comparable educational value without consumable dye dependency.
Strategic Opportunities
- Pediatric home care segments:Rinse formats with simplified compliance protocols address caregiver preference for low-friction oral hygiene routines in children's dentistry.
- Japan's METI-PMDA coordination:Streamlined import standards for dye-containing oral care products reduce regulatory fragmentation for multinational suppliers entering Asian markets.
- Educational curriculum mandates:Dental school requirements for hands-on plaque visualization training institutionalize product adoption before professional practice entry.
Industry Challenges
- Dual regulatory pathway navigation:Manufacturers must simultaneously satisfy FDA cosmetic-dye limits and EU medical device quality management systems, fragmenting product development resources.
- Single-patient workflow integration:Disposable applicator formats demanded by infection control protocols compress margin structures and require continuous manufacturing scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plaque Disclosing Market |
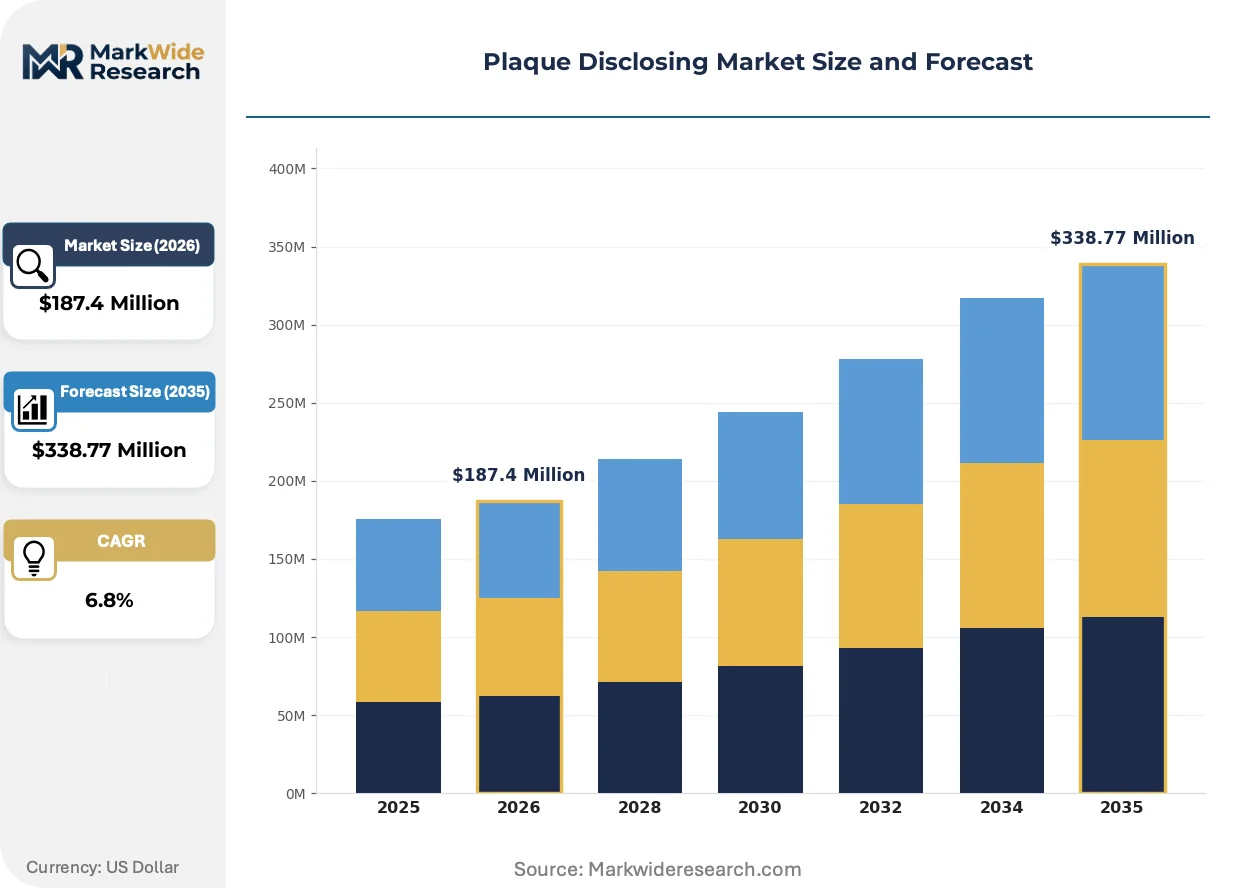
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Gels, Rinses, Stickers Application: Personal Care, Professional Dental, Educational, Clinical Research End User: Consumers, Dental Clinics, Hospitals, Schools Distribution Channel: Online Stores, Pharmacies, Dental Supply Distributors, Retail Outlets |
| Companies Covered | Sunstar Suisse S.A., Young Dental, Procter & Gamble, Johnson & Johnson, Dentsply Sirona Inc., GC Europe N.V., TePe Oral Hygiene Products Ltd, Colgate-Palmolive Company, Boots Company PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plaque Disclosing Market Emerging Trajectories
Fluorescent dye systems are actively reshaping competitive positioning across professional and consumer channels, with UV-activated visualization displacing natural-light-dependent formulations in premium segments.
Two-tone dye chemistry is supplanting single-color plaque disclosing in North American dental schools. The dual-stain approach distinguishes mature biofilm from newer deposits, enabling more precise patient coaching. Academic clinics are adopting this technology fastest, compressing demand for legacy erythrosine-only formulations and forcing manufacturers to reformulate core SKUs.
Japan's Pharmaceutical and Medical Devices Agency tightened dye concentration reporting requirements for oral care imports in coordination with METI standards harmonization. This regulatory convergence is elevating documentation burdens for multinational suppliers. European manufacturers with established quality management systems are capturing share from smaller exporters lacking compliance infrastructure.
Direct-to-consumer subscription models are disrupting traditional pharmacy and dental supply house distribution for home-use tablet formats. Millennial and Gen Z buyers prefer automated replenishment over retail shelf purchasing. This channel rotation is most visible in United States urban markets where dental deserts limit professional point-of-sale access.
Plaque Disclosing Market Segmentation
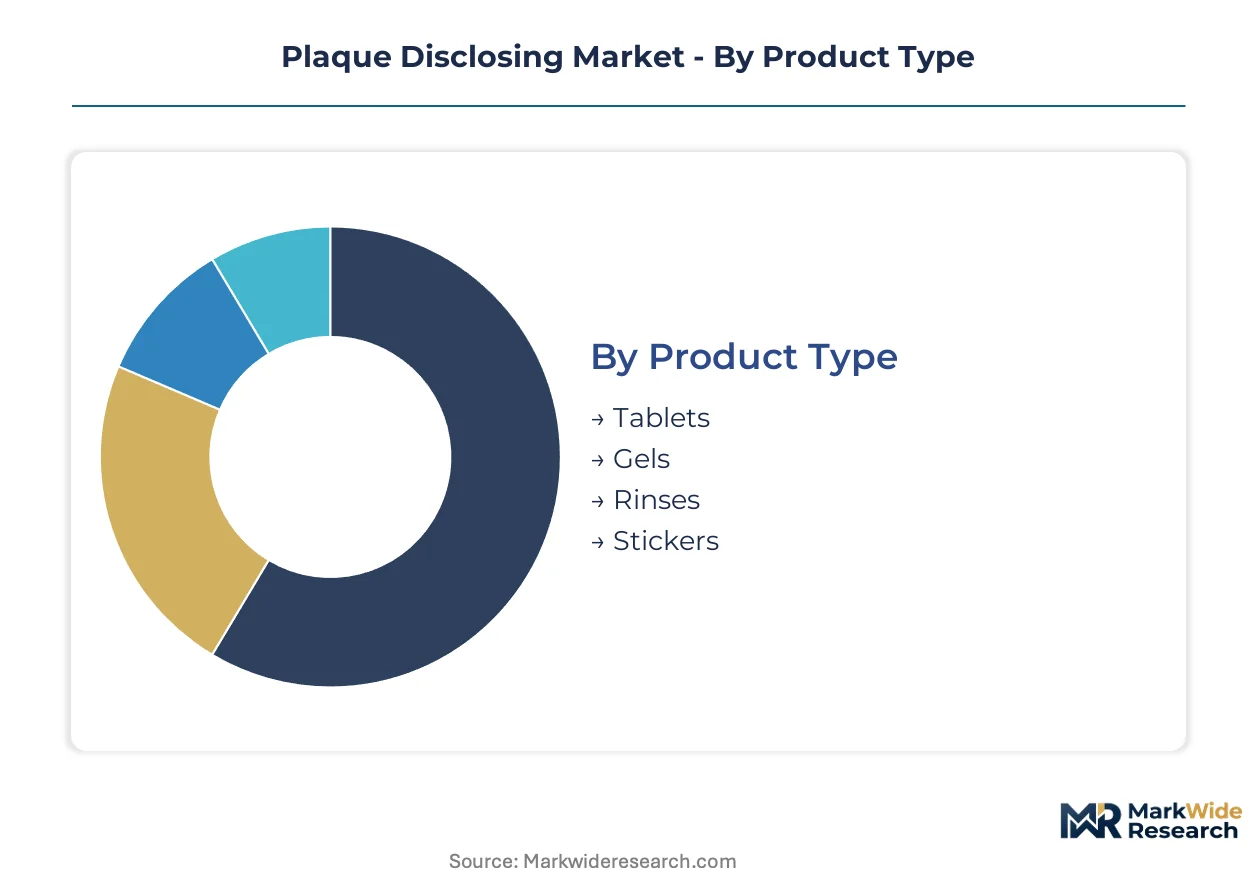
Plaque disclosing formulations span multiple delivery formats and use environments, each carrying distinct regulatory obligations and margin structures. Segment boundaries increasingly blur as professional-grade products migrate toward direct-to-consumer channels and educational mandates institutionalize specific formats.
Product Type:
Domestic manufacturing concentrates on tablet and gel formats serving North American and European professional channels, while Asian chemical hubs supply erythrosine and fluorescein intermediates for export-led rinse production.
- Tablets:Saliva-activated dye systems dissolve to bathe complete oral cavities without clinician assistance. Demand clusters in Germany's statutory prevention programs where insurer-reimbursed prophylaxis sessions mandate standardized visualization protocols. Supply chains source erythrosine predominantly from Chinese and Indian dye manufacturers, exposing formulators to input volatility.
- Gels:Viscous formulations permit targeted brush or syringe application for precise plaque mapping in periodontal assessments. Dental clinics in the United States favor single-patient disposable applicators to satisfy infection control requirements, compressing margin structures through continuous manufacturing scale demands.
- Rinses:Liquid formats address pediatric and geriatric home care where compliance simplicity outweighs coverage completeness.
- Stickers:Adhesive disclosing strips serve niche educational demonstrations and temporary visualization needs.
Tablets command the established base in professional reimbursement environments. The steepest expansion runs through rinse formats gaining traction in pediatric home care segments.
Application:
Cost tier differentiation separates premium professional systems from mass-market consumer offerings, with educational applications occupying a mid-tier position sustained by curriculum procurement budgets.
- Personal Care:Home-use tablet and rinse formats target individual oral hygiene monitoring without clinical supervision. Direct-to-consumer subscription models are displacing pharmacy distribution in United States urban markets where dental deserts limit professional point-of-sale access.
- Professional Dental:Clinical-grade gel and tablet systems integrate into reimbursable prophylaxis workflows. Two-tone dye chemistry is displacing single-color formulations in North American dental schools, forcing manufacturers to reformulate core SKUs toward dual-stain approaches that distinguish mature from newer biofilm deposits.
- Educational:Dental school curriculum mandates for hands-on plaque visualization training institutionalize product adoption before professional practice entry.
- Clinical Research:Standardized disclosing protocols support biofilm quantification studies and oral care product efficacy trials.
Professional dental applications anchor revenue concentration through established reimbursement codes. Educational segments are climbing the fastest as training program expansion widens institutional procurement pipelines.
End User:
Volume concentration tilts toward dental clinics processing high-throughput preventive appointments, while consumer and school segments show divergent procurement patterns between retail and institutional channels.
- Consumers:Individual purchasers select tablet and rinse formats through retail and online channels, with millennial and Gen Z buyers preferring automated subscription replenishment over shelf purchasing.
- Dental Clinics:Outpatient facilities drive bulk procurement of gel and tablet formats for single-patient workflows. Community college dental hygienist program expansion across the United States is rotating professional-grade uptake toward preventive care settings.
- Hospitals:Inpatient dental departments and surgical suites employ disclosing agents for pre-operative oral assessment.
- Schools:Public health dental programs and educational institutions incorporate visualization tools into children's oral hygiene instruction.
Dental clinics maintain the volume base through reimbursable session throughput. Schools are expanding most quickly as public health prevention programs widen classroom-based dental education.
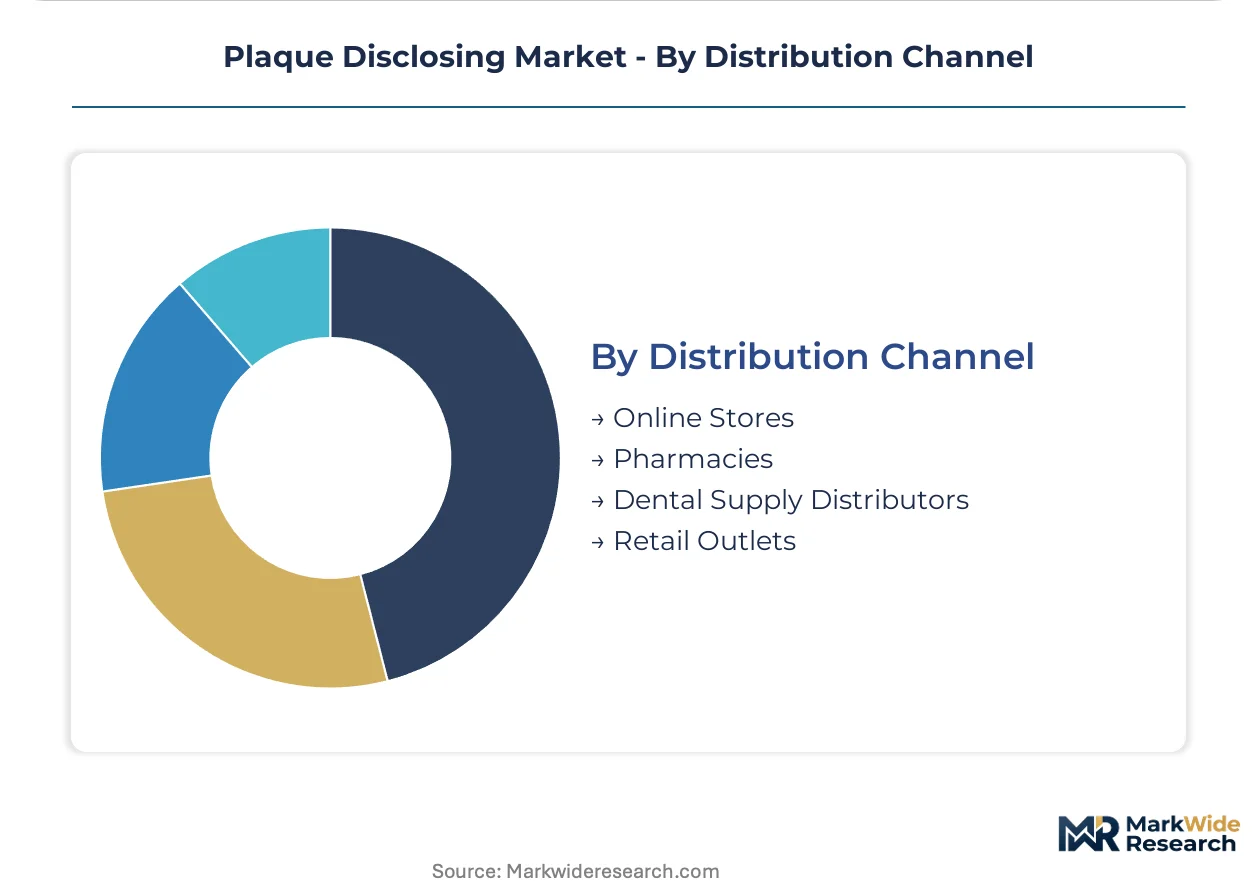
Distribution Channel:
Customer type fragmentation separates institutional procurement through supply distributors from individual purchasing via retail and digital channels, with margin structures varying sharply across route-to-market configurations.
- Online Stores:E-commerce platforms and direct-to-consumer subscriptions capture millennial and Gen Z buyers seeking automated replenishment. This channel rotation is most visible in United States urban markets with limited professional point-of-sale density.
- Pharmacies:Traditional retail pharmacy chains stock consumer-grade tablet formats for over-the-counter purchase, competing with digital channels for convenience-oriented buyers.
- Dental Supply Distributors:Professional channel intermediaries serve clinic and hospital procurement with bulk gel and tablet formats, maintaining relationships through infection control product bundling.
- Retail Outlets:Mass-market oral care aisles in supermarkets and big-box stores compete on shelf presence and brand recognition.
Dental supply distributors command the professional procurement base. Online stores are gaining share fastest as subscription models disrupt traditional pharmacy purchasing patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA over-the-counter monograph requirements govern dye safety and concentration limits for U.S. consumer products, while the EU Medical Device Regulation classifies certain professional disclosing systems as Class I devices subject to CE marking and post-market surveillance.
United States
Community college dental hygienist programs are expanding across the country, rotating professional-grade plaque disclosing uptake toward preventive care settings. FDA's updated over-the-counter monograph framework for oral care ingredients is reshaping formulation pathways for consumer-grade dye systems. Manufacturing scale concentrates in disposable applicator formats that dental clinics favor for single-patient workflows.
Germany
Statutory dental prevention programs drive insurer-reimbursed prophylaxis sessions that routinely incorporate plaque visualization tools. EU Medical Device Regulation classifies professional disclosing systems as Class I devices with CE marking requirements. The statutory prevention program embeds disclosing products into standard care protocols across outpatient dental facilities.
Japan
METI and PMDA coordinate standards for dye-containing oral care imports, creating compliance complexity for multinational suppliers entering Asian markets. Tightened dye concentration reporting requirements elevate documentation burdens for foreign exporters. Quality management systems from established European manufacturers are capturing share from smaller suppliers lacking compliance infrastructure.
United Kingdom
Public health dental programs incorporate visualization tools into children's oral hygiene instruction across schools. CE marking requirements under EU Medical Device Regulation continue to influence post-Brexit regulatory alignment discussions. Educational curriculum mandates for hands-on plaque visualization training institutionalize product adoption before professional practice entry.
China
Synthetic dye production clusters in chemical manufacturing hubs, exposing formulators to input volatility and trade friction. National standards for dye-containing oral care products are evolving alongside import regulatory frameworks. Production concentration in erythrosine and fluorescein intermediates supplies export-led manufacturing for global formulators.
Plaque Disclosing Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the plaque disclosing market structure. Multinational consumer health conglomerates leverage retail shelf presence and brand recognition in mass-market oral care aisles, while periodontal specialty manufacturers anchor professional channel dominance through dental practice relationships. Strategic archetypes separate mass-market consumer players from professional-grade specialists and private-label dental supply manufacturers. Competitive moves concentrate on portfolio diversification across tablet, gel, and rinse formats alongside geographic expansion into reimbursable prevention program markets.
Within the professional specialty tier, Sunstar Suisse S.A. and Young Dental occupy positions reflecting periodontal heritage and manufacturing scale respectively. Sunstar Suisse S.A. exemplifies the European professional channel anchor, while Young Dental represents North American production concentration in disposable formats. Procter & Gamble sits within the consumer health conglomerate archetype, competing through retail distribution density and household brand equity in over-the-counter oral care segments.
| Leading Market Players |
|---|
| Sunstar Suisse S.A. |
| Young Dental |
| Procter & Gamble |
| Johnson & Johnson |
| Dentsply Sirona Inc. |
| GC Europe N.V. |
| TePe Oral Hygiene Products Ltd |
| Colgate-Palmolive Company |
| Boots Company PLC |
| Others |
Supply Flow & Price Mechanics
Fluorescent dye chemistry displacing erythrosine-only formulations is redrawing supply geography toward European quality-management-certified producers while compressing margin structures for Asian dye-dependent formulators. This substitution simultaneously elevates documentation burdens under Japan's METI-PMDA coordination and creates pricing power for manufacturers with captive fluorescein production capabilities.
Pricing Analysis
Geographic price spreads widen between German statutory prevention program reimbursements and United States direct-to-consumer subscription tiers. Three-tier pricing structure across professional-grade gels, standard tablets, and economy rinse formats separates clinical certification levels from retail accessibility. Cost compression in disposable applicator manufacturing runs through infection control protocol mandates that dental clinics enforce. Pediatric home care segments exhibit highest price sensitivity, while periodontal specialty practices absorb premium two-tone dye system costs without volume elasticity.
Supply Chain Analysis
Inventory lead times extend for erythrosine-dependent formulators facing documentation requirements under Japan's tightened PMDA reporting standards. Synthetic dye production clusters in China and India, while finished tablet and gel manufacturing concentrates in the United States and Germany. Supply chains draw from fluorescein intermediates, viscous gel bases, and disposable applicator plastics. Single-source vulnerability concentrates in Chinese erythrosine manufacturing hubs exposed to trade friction. Distribution runs through dental supply distributors bundling infection control products alongside professional-grade disclosing systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plaque disclosing markets function as service-attach opportunities where subscription replenishment models and educational curriculum mandates generate recurring revenue layers expanding faster than hardware-only tablet sales. Direct-to-consumer automation and institutional procurement pipelines now outpace traditional pharmacy channel growth.
For Market Incumbents: Consolidate manufacturing scale in disposable applicator formats to defend against private-label dental supply competitors compressing margin structures. Secure backward integration into fluorescein production to reduce dependency on Chinese erythrosine supply volatility. CE marking investment under EU Medical Device Regulation creates defensive moats against smaller exporters lacking quality management infrastructure. For New Entrants and Emerging Players: Lead with rinse format development targeting pediatric home care segments where compliance simplicity outweighs clinical precision requirements. Japan's METI-PMDA coordination barriers filter out undercapitalized competitors, creating white-space for quality-system-compliant entrants. Direct-to-consumer subscription acquisition costs run lower than dental supply distributor slotting fees in United States urban dental deserts. For Investors and Strategic Acquirers: The market sits at a professional-consumer convergence phase that favors periodontal heritage specialists with dental practice relationship networks. Five-to-ten year viability hinges on reimbursement code expansion in national health prevention schemes. Watch for statutory dental prevention program adoption in Asia-Pacific markets as inflection signal for geographic demand rotation.| Strategic Initiative | Industry Significance |
|---|---|
| Two-Tone Dye Reformulation | North American dental school curriculum mandates force SKU migration toward dual-stain chemistry. |
| Direct-to-Consumer Subscription Launch | Millennial and Gen Z buyer preference for automated replenishment displaces pharmacy shelf purchasing. |
| CE Marking Pathway Investment | EU Medical Device Regulation classification elevates compliance barriers against non-quality-system competitors. |
| Backward Integration into Fluorescein | Captive dye production reduces exposure to Asian erythrosine supply concentration and trade friction. |
| Educational Curriculum Partnership | Dental school hands-on training mandates institutionalize product adoption before professional practice entry. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA monograph filings, EU Medical Device Regulation guidance documents, and German statutory prevention program reimbursement schedules. Dental hygienist program directors, periodontal practice managers, dental supply distributor procurement leads, and GPO contracts managers provided operational perspective. Secondary validation drew from customs trade data, SEC 10-K oral care segment disclosures, and hospital procurement database extracts. Bottom-up demand modeling triangulated against top-down market sizing across tablet, gel, and rinse format segments.
Segmentation dimensions modeled span product type chemistry, application environment, end-user procurement channel, and geographic regulatory cluster. Volume and value outputs across the projection horizon reflect patient session throughput in reimbursable prophylaxis settings, community college training program expansion rates, and direct-to-consumer subscription adoption curves. CAGRs derived from segment-level growth rate reconciliation against macro oral care expenditure trends. Forecast inputs incorporated dye substitution dynamics and infection control protocol evolution.
The analysis sits within stated boundaries; outcomes outside FDA monograph stability, EU MDR enforcement continuity, or German statutory prevention program funding levels would require recalibration. Forecasts reflect documented assumptions about reimbursement code permanence and dye supply chain configuration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Supplies
Dental Consumables Market
Dental Supplies
Dental Caries Treatment Market
Dental Supplies
Fissure Sealants Market
Dental Supplies
Dental Preventive Supplies Market
Dental Supplies
Global Hotel Dental Kits Market
Dental Supplies
Global Dental Suture Market
Dental Supplies
Endodontic Supplies Market
Dental Supplies
Orthodontic Consumables Market
Dental Supplies
Orthodontic Supplies Market