
 Carica Papaya Seed Oil Market | 2026-2036
Carica Papaya Seed Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Carica Papaya Seed Oil Market Analysis
Market Context
The gap between cold-pressed organic grades and solvent-extracted commodity volumes is broadening across supply contracts. Parchem Fine & Specialty Chemicals leverages its distribution network to anchor premium pharmaceutical-grade supply in North America. Grenera Nutrients Private Limited dominates organic certification coverage across Indian export channels. Botanical Beauty competes through direct-to-consumer positioning in specialty skincare formulations.
Technical Profile and Segment Structure
Carica papaya seed oil is a fixed oil expressed from dried seeds of Carica papaya L., typically containing 60-75% oleic acid and notable papain enzyme residues, valued for its keratolytic and moisturizing properties in topical applications. The organic oil segment sustains margin premiums through ECOCERT and USDA NOP compliance, while refined oil occupies volume leadership in mass-market cosmetics. Pharmaceutical applications lead growth trajectory due to wound-healing and antimicrobial research, whereas dietary supplements remain a smaller, emerging channel constrained by novel food status reviews in multiple jurisdictions.
Regulatory Environment and Outlook
EMA guidelines on herbal medicinal products, FDA cosmetic ingredient safety requirements, and FSSAI functional food classifications collectively shape market access pathways and labeling obligations for papaya seed oil. REACH registration in Europe and BIS quality standards in India further segment export eligibility by purity grade and contaminant thresholds. Stakeholders must monitor evolving novel food approvals and organic equivalence agreements between major importing regions to anticipate supply chain reconfigurations.
Market Dynamics
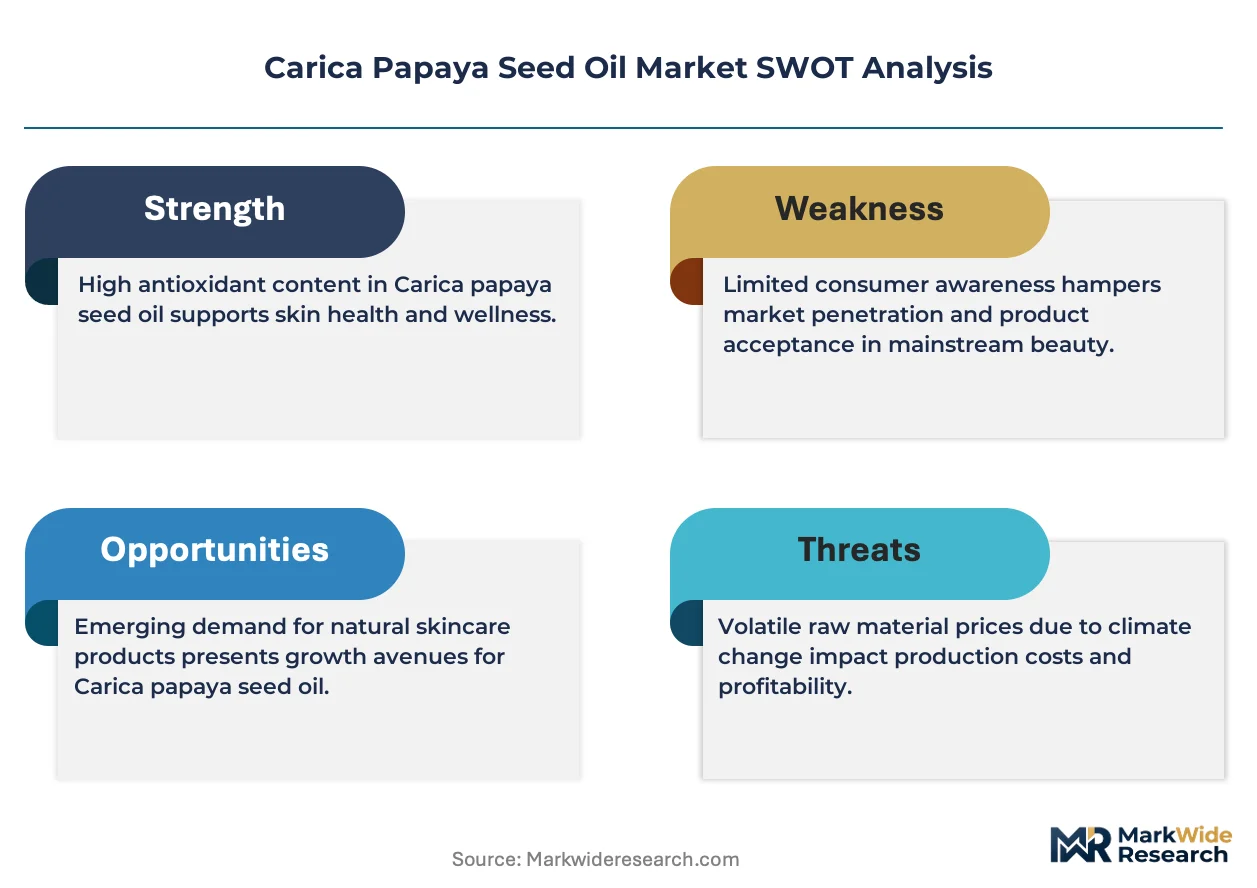
The Carica Papaya Seed Oil Market is bifurcating around cold-pressed organic extraction versus solvent-extracted commodity grades, with certification requirements from ECOCERT and USDA NOP compressing margins for non-compliant processors while rewarding premium positioning.
Growth Catalysts
- EMA guidelines on herbal medicinal products:These standards are accelerating pharmaceutical-grade qualification pathways across European Union member states, expanding high-margin therapeutic applications for papaya seed oil.
- Wound-healing research:Clinical studies validating papain enzyme activity are pulling investment into pharmaceutical formulations targeting dermatological and post-surgical care segments.
- Kerala and Tamil Nadu clusters:Concentrated Ayurvedic processing infrastructure in these Indian states is enabling integrated supply chains from seed collection to certified organic export.
Market Restraints
- Seed supply volatility:Papaya fruit processing waste constitutes the primary feedstock, tying oil output to seasonal fruit harvests and fresh produce market fluctuations.
- Novel food status reviews:EFSA and multiple national regulators have not completed safety assessments for dietary supplement applications, blocking oral consumption channels.
- Substitution by marula and baobab oils:These established African-origin oils compete for identical cosmetic emollient positioning with stronger existing supply chains.
Strategic Opportunities
- FSSAI functional food classification pathway:Successful navigation of India's food safety framework would unlock domestic nutraceutical demand from Ayurvedic wellness consumers.
- Supercritical CO2 extraction convergence:Combining this solvent-free technology with enzymatic pre-treatment is enabling higher papain retention for therapeutic-grade products.
- Direct-to-consumer subscription channels:Specialty skincare brands are bypassing traditional cosmetic ingredient distributors to capture margin through recurring revenue models.
Industry Challenges
- Organic certification timelines:ECOCERT and USDA NOP conversion periods require three-year field histories, constraining rapid supply expansion for certified grades.
- Papain activity standardization:Inconsistent enzyme potency across batches complicates pharmaceutical formulation consistency and dossier preparation for regulatory submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carica Papaya Seed Oil Market |
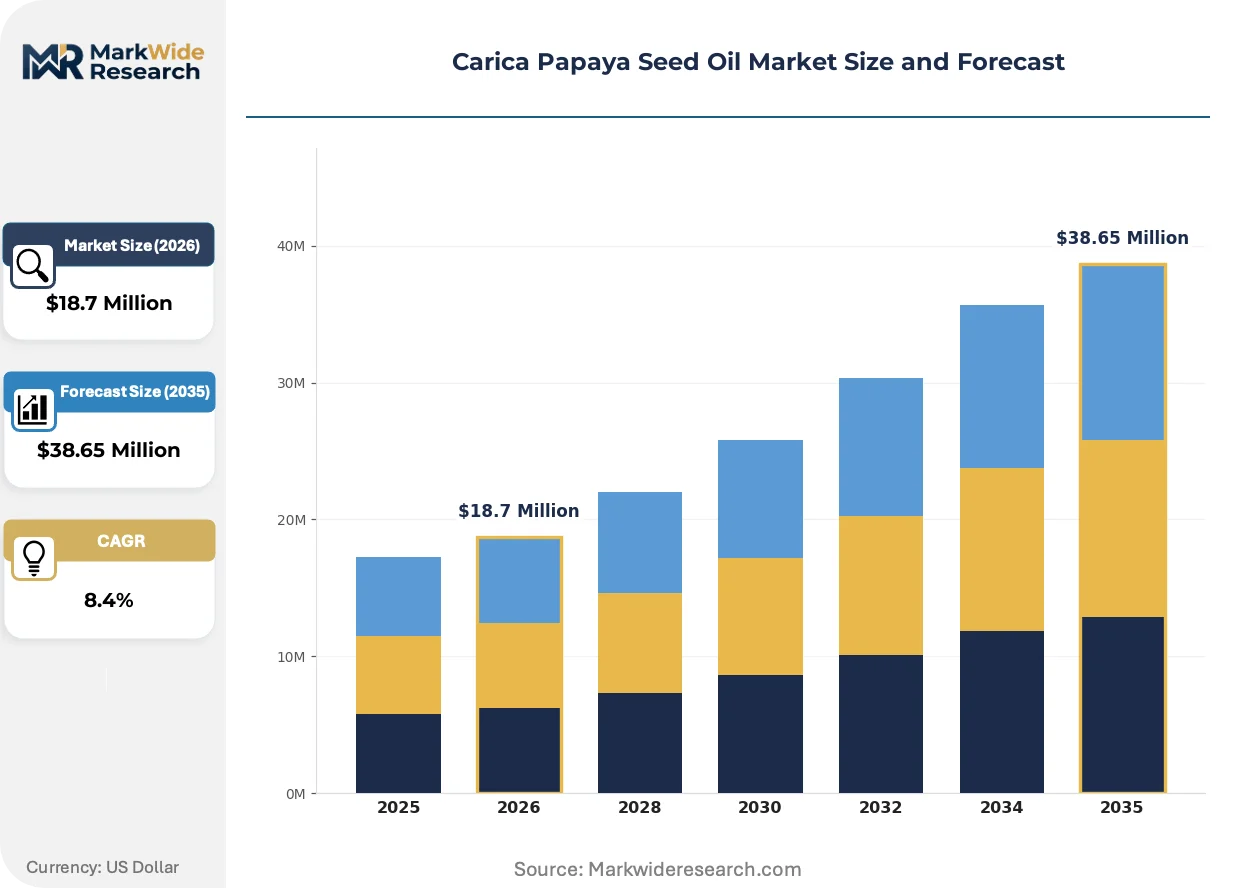
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $38.65 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Oil, Crude Oil, Organic Oil, Non-Organic Oil Application: Cosmetics, Food Industry, Pharmaceuticals, Dietary Supplements End User: Healthcare Providers, Cosmetic Manufacturers, Food Processors, Nutritional Companies Distribution Channel: Online Retail, Wholesale, Specialty Stores, Supermarkets |
| Companies Covered | Parchem Fine & Specialty Chemicals, Lotus Garden Botanicals, Grenera Nutrients Private Limited, Suyash Herbs Exports Private Limited, R K Products, Botanical Beauty, Cosmark Pty Ltd, Augustus Oils Limited, Katyani Exports, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carica Papaya Seed Oil Market Emerging Trajectories
Formulation science and extraction technology are converging to reposition papaya seed oil from commodity cosmetic ingredient to targeted therapeutic agent, with regulatory navigation and channel restructuring determining competitive outcomes.
Supercritical CO2 extraction systems are rewriting the technical economics of papaya seed oil production. This solvent-free technology preserves heat-sensitive papain enzymes while eliminating hexane residue concerns. Pharmaceutical contract manufacturers in Germany and Switzerland are adopting these systems to meet EMA quality standards. The structural consequence is compressing traditional cold-press processors into lower-margin cosmetic grades unless they upgrade capital equipment.
REACH registration requirements in Europe are tightening contaminant thresholds for imported botanical oils. ECHA's updated guidance on substance evaluation is forcing exporters to implement comprehensive pesticide residue testing and supply chain documentation. Indian processors targeting European pharmaceutical customers are responding by integrating in-house analytical laboratories and backward integration into certified organic papaya orchards.
Ingredient buyers are consolidating supplier relationships around vertically integrated processors with multi-certification coverage. Large cosmetic formulators are reducing vendor counts from regional distributors to direct contracts with extraction facilities holding simultaneous ECOCERT, USDA NOP, and ISO 22000 credentials. This concentration is most visible in North American clean beauty brands, where procurement teams prioritize audit transparency and batch-level traceability over price competition.
Carica Papaya Seed Oil Market Segmentation
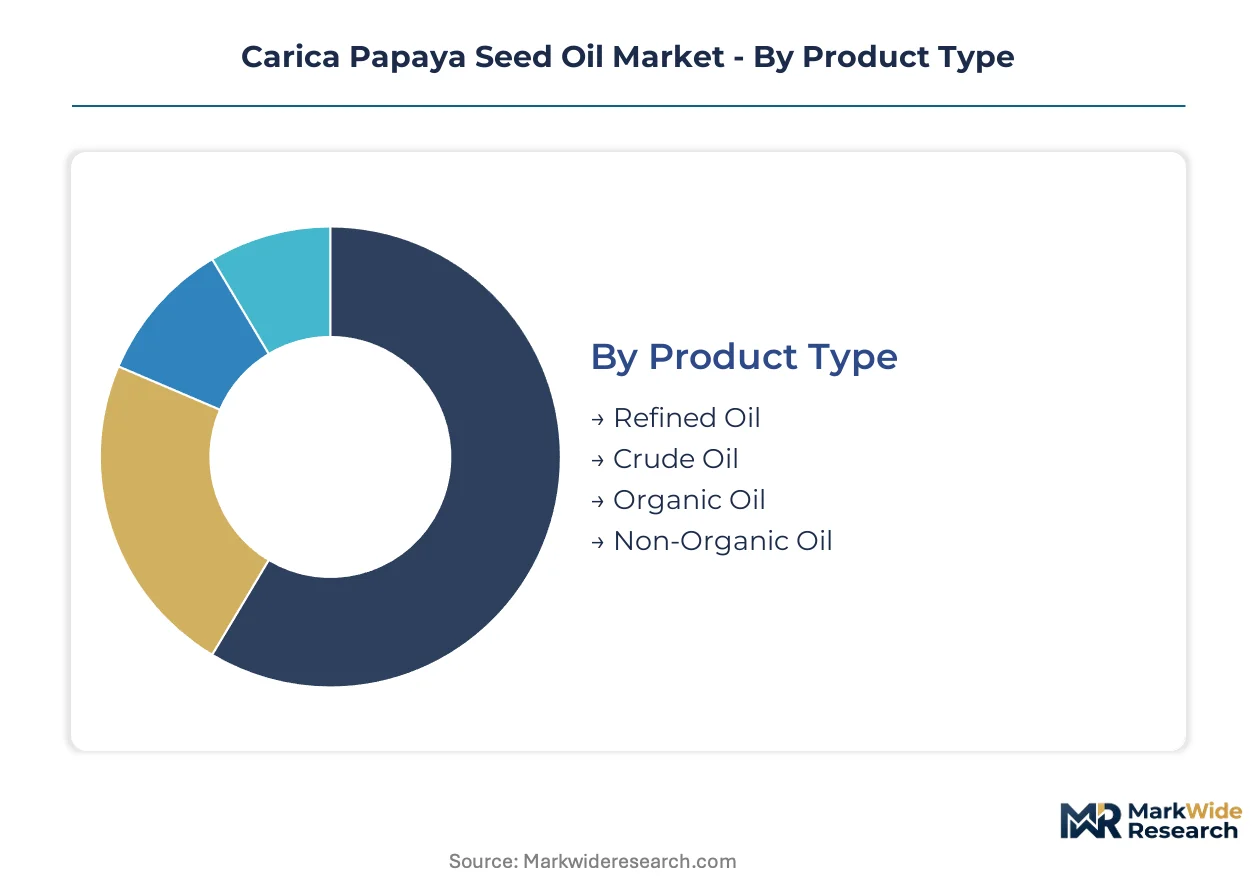
Segmentation in the Carica Papaya Seed Oil Market tracks how extraction method, purity certification, and end-use specifications fragment pricing power and regulatory compliance burdens across supply tiers. Buyers with pharmaceutical or organic cosmetic requirements face fundamentally different supplier qualification criteria than mass-market formulators.
Product Type:
Supply concentration around Kerala and Tamil Nadu processing clusters creates divergent availability profiles for each extraction and certification grade.
- Organic Oil:Cold-pressed from certified orchards meeting ECOCERT or USDA NOP standards, commanding margin premiums through three-year conversion timelines and pesticide residue documentation. Demand concentrates in North American clean beauty brands and European pharmaceutical contract manufacturers where REACH registration and EMA quality standards apply.
- Refined Oil:Solvent-extracted or physically refined to remove odor, color, and papain enzyme residues, occupying volume leadership in mass-market cosmetic emulsions and personal care products. Indian exporters target Southeast Asian cosmetic manufacturers with BIS-compliant refined grades for cost-sensitive formulation.
- Crude Oil:Unfiltered cold-pressed output retaining maximum papain activity for therapeutic applications, typically sold through Ayurvedic processing channels in Kerala before secondary refining or direct pharmaceutical use.
- Non-Organic Oil:Conventionally cultivated feedstock without certification coverage, supplying commodity cosmetic and industrial applications where price competition with marula and baobab oils constrains margin.
Today's leader: Refined Oil. Tomorrow's challenger: Organic Oil.
Application:
End-use specifications determine whether papain enzyme retention or complete protein removal drives processing economics and regulatory pathway selection.
- Pharmaceuticals:Wound-healing and antimicrobial formulations leverage papain's keratolytic activity, with EMA herbal medicinal product guidelines and FDA cosmetic ingredient safety requirements shaping dossier preparation and clinical validation investment.
- Cosmetics:Emollient and exfoliant applications in skincare, haircare, and sun care products represent the established volume base, with supercritical CO2 extraction gaining share among German and Swiss contract manufacturers serving premium positioning.
- Food Industry:Novel food status reviews by EFSA and national regulators block oral consumption channels in Europe, while FSSAI functional food classification in India offers a potential domestic pathway for Ayurvedic wellness positioning.
- Dietary Supplements:Capsule and softgel applications remain constrained by incomplete safety assessments, with growth contingent on regulatory clearance in multiple jurisdictions.
Cosmetics generates current revenue concentration. Pharmaceuticals climbs fastest on therapeutic validation.
End User:
Procurement sophistication varies dramatically across buyer categories, from pharmaceutical GMP compliance to direct-to-consumer brand agility.
- Cosmetic Manufacturers:Large formulators consolidate vendor relationships around vertically integrated processors with multi-certification coverage, prioritizing batch-level traceability over price in North American clean beauty procurement.
- Healthcare Providers:Hospital systems and dermatology clinics sourcing topical therapeutic products require standardized papain potency documentation and sterile manufacturing conditions.
- Nutritional Companies:Supplement brands await novel food approvals to activate oral consumption channels, currently limited to topical or non-food positioning.
- Food Processors:Edible oil applications face regulatory barriers in major import markets, constraining commercial development despite traditional use in some origin regions.
Cosmetic Manufacturers dominate contract volume. Healthcare Providers offer steepest expansion trajectory on clinical validation.
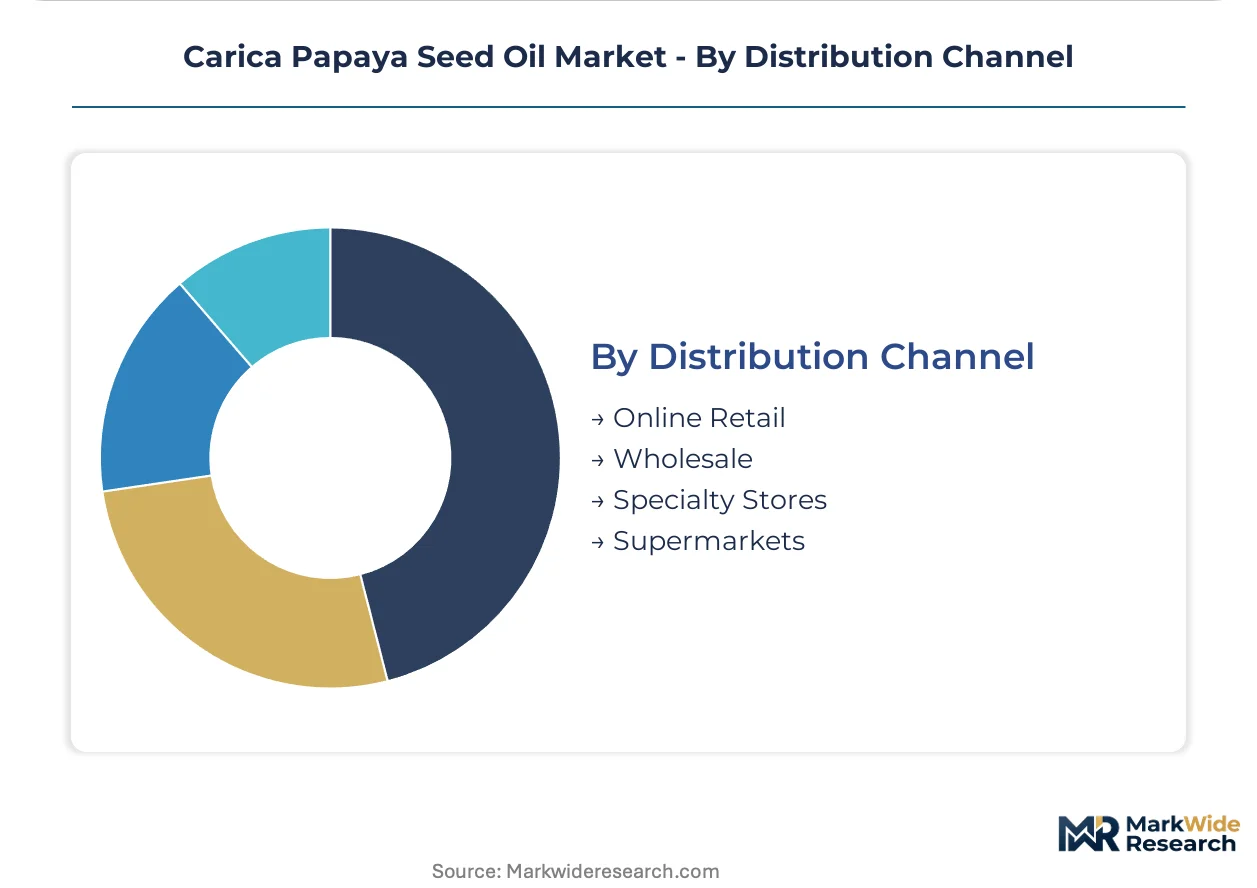
Distribution Channel:
Channel selection reflects buyer scale, certification requirements, and the trade-off between procurement efficiency and margin capture.
- Wholesale:Bulk supply contracts to cosmetic and pharmaceutical manufacturers anchor volume throughput, with direct relationships replacing regional distributors as buyers consolidate supplier bases.
- Online Retail:Direct-to-consumer subscription channels enable specialty skincare brands to bypass traditional ingredient distributors and capture recurring revenue through clean beauty positioning.
- Specialty Stores:Ayurvedic and natural product retailers in India and diaspora markets move certified organic grades to wellness-focused consumers.
- Supermarkets:Mass-market retail presence remains limited by shelf-space competition with established cosmetic oils and regulatory labeling constraints.
Wholesale commands current flow. Online Retail gains fastest on brand disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India commands raw material sourcing through Kerala and Tamil Nadu processing clusters, while Germany dominates pharmaceutical-grade extraction technology adoption among European contract manufacturers.
India
Kerala and Tamil Nadu anchor integrated supply chains from seed collection to certified organic export, serving Ayurvedic wellness brands and international cosmetic formulators. FSSAI functional food classification pathways offer domestic nutraceutical expansion potential. Coimbatore and Kochi processing facilities concentrate supercritical CO2 extraction investment for therapeutic-grade output.
Germany
Pharmaceutical contract manufacturers in Bavaria and Baden-Württemberg drive demand for papain-retentive grades targeting wound-healing applications. EMA herbal medicinal product guidelines accelerate dossier preparation for topical therapeutic positioning. Frankfurt and Stuttgart extraction facilities adopt enzymatic pre-treatment convergence to meet REACH contaminant thresholds.
United States
Clean beauty procurement teams in California and New York prioritize multi-certification coverage and batch-level traceability over price competition. FDA cosmetic ingredient safety requirements shape labeling obligations for papaya-derived actives. Los Angeles and Brooklyn direct-to-consumer brands bypass traditional distributors through subscription revenue models.
Switzerland
Swissmedic quality standards attract premium pharmaceutical positioning for dermatological and post-surgical care segments. Geneva and Basel contract manufacturers source supercritical CO2-extracted grades with standardized papain potency documentation. Alpine processing facilities integrate in-house analytical laboratories for pesticide residue compliance.
France
ECOCERT certification demand from Paris-based cosmetic formulators compresses margins for non-compliant Indian exporters. ANSM guidance on topical herbal products influences formulation development for pharmacy-channel distribution. Grasse and Lyon specialty chemical distributors consolidate supplier relationships around vertically integrated processors.
Carica Papaya Seed Oil Market Vendor Landscape
Top-tier vendors anchor pharmaceutical-grade supply chains, while mid-tier processors compete on organic certification coverage and regional distribution reach. The vendor base stratifies across extraction technology tiers, with supercritical CO2 operators commanding premium positioning against conventional cold-press facilities. Three archetypes dominate: vertically integrated Indian exporters with multi-certification coverage, North American specialty distributors with direct-to-consumer channel access, and European pharmaceutical contract manufacturers with GMP compliance infrastructure. Competitive moves concentrate on backward integration into certified organic orchards and technology licensing for enzyme retention processes.
Among Indian integrated processors, Grenera Nutrients Private Limited and Suyash Herbs Exports Private Limited exemplify the multi-certification archetype spanning ECOCERT, USDA NOP, and ISO 22000 credentials. Parchem Fine & Specialty Chemicals occupies a position in North American pharmaceutical-grade distribution, while Augustus Oils Limited represents European sourcing specialization for therapeutic applications.
| Leading Market Players |
|---|
| Parchem Fine & Specialty Chemicals |
| Lotus Garden Botanicals |
| Grenera Nutrients Private Limited |
| Suyash Herbs Exports Private Limited |
| R K Products |
| Botanical Beauty |
| Cosmark Pty Ltd |
| Augustus Oils Limited |
| Katyani Exports |
| Others |
Supply Flow & Price Mechanics
Backward integration into certified organic orchards anchors supply security and pricing power for processors serving pharmaceutical and clean beauty channels. Kerala and Tamil Nadu processors leverage captive feedstock to compress conversion timelines and defend margin premiums against solvent-extracted commodity competition.
Pricing Analysis
Capacity additions in Tamil Nadu are reshaping price floors for refined grades while organic cold-pressed tiers sustain premiums. Three-tier pricing structure across pharmaceutical-grade, certified organic, and commodity refined levels reflects ECOCERT compliance costs and papain standardization investments. Pricing pressure stems from marula and baobab oil substitution in mass-market cosmetics. Mass-market cosmetic formulators exhibit highest price sensitivity; pharmaceutical contract manufacturers prioritize batch traceability over unit cost.
Supply Chain Analysis
Freight cost differentials between Indian coastal ports and European pharmaceutical hubs influence processor location decisions for export-oriented facilities. Raw material sourcing concentrates in India, with secondary processing nodes in Germany and Switzerland for EMA-compliant therapeutic grades. Feedstock draws from seasonal papaya fruit processing waste, tethering oil output to harvest cycles. Single-source vulnerability runs through Kerala monsoon-dependent collection networks. Distribution runs through direct bulk contracts consolidating regional distributor bypass.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Indian processing cost advantages meet European regulatory premium capture, with FSSAI functional food clearance offering domestic margin expansion unavailable to export-only competitors.
For Market Incumbents: Deepen supercritical CO2 extraction capacity in Coimbatore and Kochi to meet Swissmedic and EMA quality standards. Secure multi-certification coverage spanning ECOCERT, USDA NOP, and ISO 22000 to defend against backward-integrated Ayurvedic brands. Anchor long-term offtake with North American clean beauty procurement teams prioritizing audit transparency over spot pricing.
For New Entrants and Emerging Players: Hospital systems and dermatology clinics sourcing standardized topical therapeutics represent an underserved buyer archetype with concentrated contract potential. Target wound-healing and post-surgical care segments where papain potency documentation commands premium positioning. Pursue supercritical CO2 technology licensing from German equipment vendors to bypass capital-intensive cold-press infrastructure.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier Indian processors with organic certification gaps because ECOCERT conversion timelines create acquisition windows before three-year field histories mature. Target facilities with existing BIS compliance and Kerala/Tamil Nadu geographic concentration. Watch for EFSA novel food approval signals as inflection indicators for dietary supplement channel activation.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Scale-Up | Enables EMA-compliant therapeutic-grade output for German and Swiss contract manufacturers. |
| Backward Integration into Certified Orchards | Compresses ECOCERT conversion timelines and secures pesticide residue documentation for REACH compliance. |
| FSSAI Functional Food Classification Pursuit | Unlocks domestic nutraceutical demand from Ayurvedic wellness consumers in India. |
| Direct-to-Consumer Subscription Launch | Captures recurring revenue through clean beauty positioning bypassing traditional distributors. |
| Multi-Certification Coverage Investment | Meets procurement consolidation trends among North American cosmetic formulators requiring audit transparency. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement included extraction facility managers in Kerala and Tamil Nadu, procurement leads at North American clean beauty brands, regulatory affairs specialists navigating EMA herbal medicinal product guidelines, and pharmaceutical contract manufacturing executives in Germany and Switzerland. Secondary validation drew from customs trade data, BIS quality standard filings, ECOCERT and USDA NOP certification registries, and ECHA REACH registration databases. Bottom-up volume modeling from processor capacity and top-down demand estimation from end-use consumption patterns were cross-referenced for triangulation.
Segment-weighting approaches applied differential growth assumptions across extraction method, certification grade, and end-use application dimensions. The analytical framework modeled organic oil, refined oil, crude oil, and non-oil grades; pharmaceutical, cosmetic, food industry, and dietary supplement applications; and wholesale, online retail, specialty store, and supermarket channels throughout the projection horizon. CAGRs were derived from historical trajectory analysis and regulatory pathway timing. Forecast inputs included EFSA novel food review status, FSSAI classification progression, and supercritical CO2 technology adoption rates among European contract manufacturers.
Underlying measurement precision varies by segment; pharmaceutical and organic cosmetic tiers carry tighter precision than commodity refined grades due to concentrated buyer visibility and certification documentation requirements. Forecasts reflect documented assumptions about regulatory clearance timelines and technology adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
High Protein Flour Market
Ingredients
Low-Fat Cocoa Powder Market
Ingredients
Beetroot Powder Market
Ingredients
Bread Flour Market
Ingredients
2'-Fucosyllactose (2'-FL) Market
Ingredients
Savory Ingredients Market
Ingredients
Global Yeast Market
Ingredients
PHO Oils Market
Ingredients
Fish Feed Ingredients Market
Ingredients
Potato Peel Powder Market
Ingredients
Global Infant Nutrition Ingredients Market
Ingredients
Ahiflower Oil Market
Ingredients
South America Algae Omega-3 Ingredients Market
Ingredients
Sunflower Protein Market
Ingredients
Sprouted Brown Rice Protein Market
Ingredients
Egg Membrane Powder Market