
 Global DNA/RNA Extraction Kit Market | 2026-2036
Global DNA/RNA Extraction Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Global DNA/RNA Extraction Kit Market Foresight
Automated magnetic bead extraction is narrowing the performance gap between manual and high-throughput workflows in clinical and research settings. Thermo Fisher Scientific leverages its integrated instrument-reagent ecosystem to sustain platform loyalty across diagnostic laboratories. QIAGEN anchors its position through silica membrane chemistry leadership and companion diagnostic partnerships. Promega Corporation differentiates via enzymatic lysis innovations tailored for challenging sample matrices.
DNA/RNA extraction kits comprise buffered reagent systems—typically containing chaotropic salts, detergents, and proteinases—designed to lyse cells, stabilize nucleic acids, and remove contaminants for downstream PCR, sequencing, or hybridization applications. Silica membrane technology dominates routine diagnostic volumes due to cost efficiency and protocol familiarity, while magnetic particle technology captures the fastest expansion as laboratories automate sample-to-answer pipelines. Research institutes represent the deepest end-user segment for manual kit consumption, whereas contract research organizations drive demand for scalable, GMP-compliant extraction platforms.
FDA oversight of laboratory-developed tests and EPA guidelines for nucleic acid-based environmental monitoring shape product validation requirements in the United States. EMA's In Vitro Diagnostic Regulation and REACH chemical compliance standards govern kit composition and performance claims across European markets. ISO 13485 quality management certification has become a baseline threshold for supplier qualification in regulated diagnostic procurement. Stakeholders must monitor evolving harmonization between FDA and EMA nucleic acid test standards to anticipate cross-border product registration burdens.
Market Dynamics
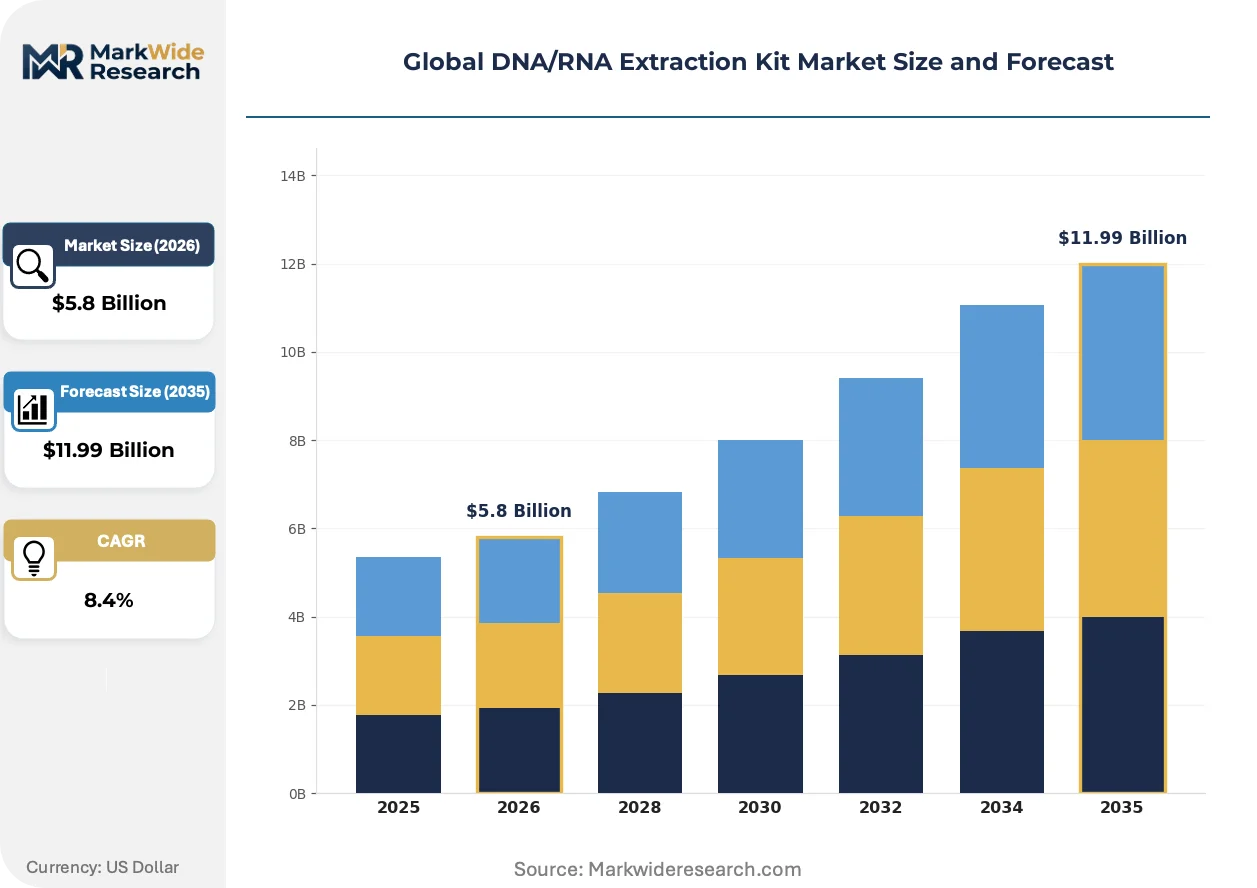
Magnetic bead automation is compressing protocol timelines in clinical laboratories while silica membrane chemistry retains cost dominance in research settings, creating a bifurcated technology landscape where extraction method selection increasingly depends on throughput requirements rather than sample type alone.
Growth Catalysts
- IVDR implementation deadlines:European diagnostic laboratories are accelerating nucleic acid test validation workflows ahead of EMA enforcement milestones, driving kit standardization and quality documentation investments.
- Point-of-care molecular diagnostics:Miniaturized extraction modules are penetrating infectious disease screening programs in India and Brazil where decentralized testing infrastructure is expanding.
- Environmental nucleic acid surveillance:EPA guidelines for waterborne pathogen monitoring are mandating standardized extraction protocols across municipal testing facilities in the United States.
Market Restraints
- Chaotropic salt cost volatility:Guanidine hydrochloride supply disruptions from Chinese chemical manufacturers are compressing reagent margins and forcing formulation adjustments.
- Magnetic particle supply concentration:Surface-modified iron oxide bead production clusters in Germany and Japan, exposing buyers to single-source risks during trade friction periods.
- Cross-contamination in automated systems:Carryover between high-titer and low-titer samples in liquid handling robotics limits confidence in ultra-sensitive oncology applications.
Strategic Opportunities
- Cell-free DNA extraction from liquid biopsies:Oncology companion diagnostic pipelines in South Korea and Singapore are creating demand for specialized low-input protocols.
- CRISPR-based nucleic acid enrichment:Targeted depletion of human background sequences is hybridizing with traditional extraction workflows to improve pathogen detection sensitivity.
- ISO 13485-certified contract manufacturing:Diagnostic kit developers are outsourcing GMP production to specialized European facilities to accelerate regulatory submissions.
Industry Challenges
- Automation protocol validation timelines:FDA 510(k) clearance for instrument-reagent combinations extends development cycles by 18-24 months versus manual kit submissions.
- Multi-omics sample preparation convergence:Simultaneous DNA, RNA, and protein extraction from single biopsies demands reagent compatibility matrices that strain quality control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global DNA/RNA Extraction Kit Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spin Column Kits, Magnetic Bead Kits, Liquid-Liquid Extraction Kits, Filter Plate Kits, Vacuum Manifold Kits Application: Molecular Diagnostics, Genetic Research, Forensic Analysis, Agricultural Biotechnology, Veterinary Science End User: Research Institutes, Pharmacies, Diagnostic Laboratories, Academic Institutions, Contract Research Organizations Technology: Silica Membrane Technology, Magnetic Particle Technology, Enzymatic Digestion, Automated Systems, Manual Extraction |
| Companies Covered | Thermo Fisher Scientific, QIAGEN, F. Hoffmann-La Roche, Promega Corporation, Agilent Technologies, Bio-Rad Laboratories, Danaher, Merck, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global DNA/RNA Extraction Kit Market Shifts & Advancements
Extraction technology is fragmenting into throughput-optimized and sample-optimized branches, with automation hardware and chemistry kits increasingly sold as integrated ecosystems rather than interchangeable components.
Lyophilized reagent formats are hybridizing with microfluidic cartridge architectures to enable ambient-temperature distribution of complete extraction workflows. Tropical disease programs in sub-Saharan Africa are piloting these systems where cold chain infrastructure remains unreliable. The format shift is compressing per-test logistics costs while demanding new manufacturing investments in precision dispensing and desiccant packaging.
EMA's In Vitro Diagnostic Regulation is mandating clinical evidence packages for extraction kits used in licensed diagnostic procedures. Manufacturers serving European markets are restructuring quality management systems to capture real-world performance data across multiple hospital sites. The compliance burden is favoring larger kit suppliers with dedicated regulatory affairs teams over specialty reagent houses.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer relationships in United States hospital networks. Academic medical centers in Boston, Houston, and San Francisco are negotiating multi-year extraction kit contracts bundled with sequencing service agreements. The purchasing model shift is compressing vendor margins while locking in volume commitments that disadvantage smaller kit developers.
Global DNA/RNA Extraction Kit Market Segmentation
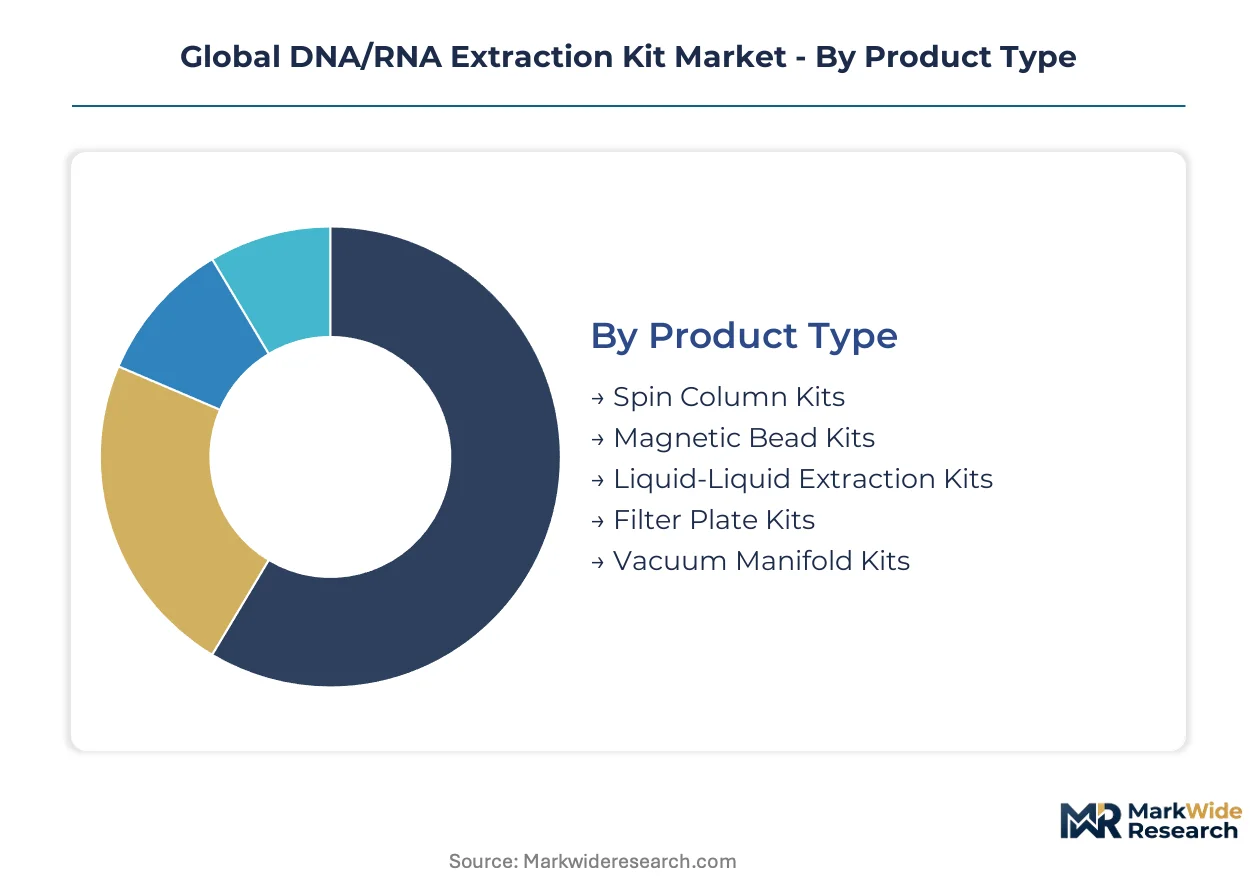
Extraction kit segmentation reveals divergent procurement cycles across product architectures, with automation-ready formats turning over faster than legacy manual systems. Application-driven demand concentrates in regulated diagnostics where validation timelines stretch replacement schedules, while research end-users cycle through formats more rapidly based on protocol evolution.
Product Type:
Cycle times vary dramatically across extraction architectures, with automated magnetic formats refreshing every 18-24 months versus 4-6 year replacement horizons for manual column systems.
- Spin Column Kits:Silica membrane chemistry packaged in centrifuge-compatible cartridges dominates routine diagnostic volumes due to cost efficiency and protocol familiarity. United States hospital laboratories in Boston and Houston maintain substantial inventory positions, though procurement is consolidating through group purchasing organizations that compress vendor margins.
- Magnetic Bead Kits:Surface-modified iron oxide particles enable walk-away automation in high-throughput settings across Germany and China. Clinical diagnostic laboratories in these markets are displacing manual methods as regulatory frameworks tighten around molecular assay validation standards.
- Liquid-Liquid Extraction Kits:Phenol-chloroform phase separation persists in specialized research protocols requiring ultra-high molecular weight DNA recovery.
- Filter Plate Kits:96-well format silica membranes serve mid-throughput screening operations in contract research organizations.
- Vacuum Manifold Kits:Multi-sample parallel processing architecture retains niche positioning in forensic laboratories processing batch evidence samples.
Spin column formats anchor the volume base while magnetic bead kits gain share at the steepest rate.
Application:
Cost tier stratification separates premium-priced companion diagnostic workflows from economy-scale agricultural screening programs.
- Molecular Diagnostics:FDA-cleared and EMA-IVDR compliant extraction protocols command premium positioning in infectious disease and oncology testing. South Korea and Singapore laboratories are driving specialized low-input cell-free DNA workflows for liquid biopsy applications.
- Genetic Research:Academic institutions in San Francisco and research institutes across Germany represent the deepest consumption base for manual kit formats with flexible protocol customization.
- Forensic Analysis:Standardized DNA profiling protocols in United States federal and state laboratories mandate chain-of-custody compatible extraction systems.
- Agricultural Biotechnology:Crop genotyping and seed quality testing in Brazil and India deploy high-volume, cost-optimized extraction formats.
- Veterinary Science:Point-of-care molecular diagnostics for livestock and companion animals are expanding in decentralized testing infrastructure across India and Brazil.
Molecular diagnostics commands the premium tier while agricultural biotechnology anchors economy-scale procurement volumes.
End User:
Customer type determines purchasing authority structure, with consolidated hospital networks exercising procurement leverage unavailable to fragmented academic buyers.
- Research Institutes:Manual kit consumption concentrates here with protocol flexibility prioritized over throughput. German Max Planck institutes and United States National Institutes of Health facilities maintain diverse format inventories.
- Diagnostic Laboratories:High-throughput automated platforms dominate in United States clinical reference labs facing ISO 13485 certification requirements and FDA oversight of laboratory-developed tests.
- Pharmacies:Emerging point-of-care molecular testing in Brazil and India is creating demand for miniaturized extraction modules.
- Academic Institutions:Budget-constrained procurement favors economy-tier spin column formats with educational pricing structures.
- Contract Research Organizations:GMP-compliant extraction platforms with scalable batch documentation serve pharmaceutical client audit requirements.
Diagnostic laboratories concentrate platform investment while contract research organizations are expanding most quickly as outsourcing accelerates.
Technology:
Supply concentration in surface-modified bead manufacturing creates sourcing risk exposure distinct from commodity silica membrane supply chains.
- Silica Membrane Technology:Chaotropic salt-mediated nucleic acid binding to glass fiber matrices retains cost dominance in research settings. QIAGEN's chemistry leadership anchors this segment through companion diagnostic partnerships.
- Magnetic Particle Technology:Iron oxide core-shell architectures with carboxyl or silica surface functionalization enable automated liquid handling integration. Production clusters in Germany and Japan expose buyers to single-source risks during trade friction periods.
- Enzymatic Digestion:Proteinase K and lyticase formulations tailored for challenging sample matrices differentiate specialty suppliers.
- Automated Systems:Integrated instrument-reagent ecosystems from Thermo Fisher Scientific sustain platform loyalty through protocol lock-in.
- Manual Extraction:Open-format reagent systems retain positioning in resource-limited settings and protocol development workflows.
Silica membrane technology anchors installed base volumes while magnetic particle systems are climbing the fastest as automation penetrates clinical workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German magnetic bead manufacturers export surface-modified iron oxide particles to clinical diagnostic laboratories across the United States and China, establishing a critical supply corridor for automated extraction workflows.
United States
FDA oversight of laboratory-developed tests and EPA guidelines for waterborne pathogen monitoring are tightening nucleic acid assay validation requirements. Academic medical centers in Boston and Houston are consolidating procurement through group purchasing organizations that bundle extraction kits with sequencing service agreements. Clinical reference laboratories face ISO 13485 certification mandates that favor established kit suppliers with dedicated regulatory affairs teams.
Germany
EMA's In Vitro Diagnostic Regulation is mandating clinical evidence packages for extraction kits used in licensed diagnostic procedures. Max Planck institutes across the country maintain diverse format inventories for research applications with flexible protocol customization. Surface-modified bead production clusters in German industrial centers expose buyers to single-source risks during trade friction periods.
China
NMPA regulatory frameworks are tightening around molecular assay validation standards for clinical diagnostic laboratories. Manufacturing of chaotropic salts including guanidine hydrochloride concentrates in Chinese chemical production hubs, creating supply disruption vulnerabilities that compress reagent margins. High-throughput automation adoption is accelerating in Beijing and Shanghai hospital networks.
India
Point-of-care molecular diagnostics for infectious disease screening are expanding through decentralized testing infrastructure in sub-Saharan Africa and domestic veterinary applications. CDSCO regulatory pathways for nucleic acid test kits are evolving alongside BIS quality standards for diagnostic reagents. Tropical disease programs are piloting lyophilized reagent formats with microfluidic cartridges where cold chain infrastructure remains unreliable.
South Korea
Oncology companion diagnostic pipelines are creating specialized demand for low-input cell-free DNA extraction protocols from liquid biopsies. MFDS regulatory requirements for nucleic acid-based cancer diagnostics are shaping kit validation timelines for domestic biotechnology firms. Seoul-based diagnostic developers are outsourcing GMP production to specialized European contract manufacturing facilities.
Global DNA/RNA Extraction Kit Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure where integrated instrument-reagent ecosystems sustain platform loyalty while chemistry-focused suppliers defend membrane and bead technology positions. The vendor base organizes around three archetypes: diversified life science conglomerates with automation hardware portfolios, nucleic acid purification specialists with membrane chemistry leadership, and enzymatic reagent innovators targeting challenging sample matrices. Dominant competitive moves include strategic partnerships between kit manufacturers and sequencing platform developers, plus geographic expansion through ISO 13485-certified contract manufacturing arrangements.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher exemplify channel-controlling strategies through integrated instrument-reagent ecosystems. Among chemistry specialists, QIAGEN occupies a position representing silica membrane leadership, while Promega Corporation exemplifies enzymatic lysis innovation for complex sample types. These three anchors illustrate how competitive positioning fragments between platform lock-in architectures and open-format reagent flexibility.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| QIAGEN |
| F. Hoffmann-La Roche |
| Promega Corporation |
| Agilent Technologies |
| Bio-Rad Laboratories |
| Danaher |
| Merck |
| PerkinElmer |
| Others |
Supply & Pricing Matrix
Jiangsu province's chaotropic salt manufacturing clusters exert outsized leverage over global reagent pricing, with guanidine hydrochloride production volatility transmitting directly into kit margin compression across downstream diagnostic markets.
Pricing Analysis
Magnetic bead extraction systems command 40-60% premiums over silica membrane equivalents, while lyophilized formats sit at emerging price points between established tiers. Pricing stratifies across premium-certified diagnostic protocols, standard research-grade formats, and economy-scale agricultural screening tiers. Cost compression in economy segments intensifies as Brazilian and Indian buyers consolidate procurement through agricultural cooperatives. Academic institutions exhibit highest price sensitivity due to budget-constrained grant funding, whereas ISO 13485-certified diagnostic laboratories prioritize validation documentation over per-unit cost.
Supply Chain Analysis
Export control regimes limiting surface-modified nanoparticle technology flows constrain German and Japanese bead manufacturers' expansion into Chinese clinical markets. Supply concentrates in Germany for precision surface chemistry, Japan for iron oxide core production, and China for chaotropic salt synthesis. Raw material dependencies center on guanidine hydrochloride, proteinase K enzymes, and medical-grade silica fibers. Single-source vulnerability in surface-modified bead production exposes buyers to trade friction disruptions. Distribution runs through diagnostic group purchasing organizations in the United States, direct manufacturer relationships in German research institutes, and government tender systems in Brazil and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat environment where regulatory entrenchment—specifically ISO 13485 certification and FDA 510(k) instrument-reagent combination clearances—erects formidable barriers against new kit suppliers.
For Market Incumbents: Entrench platform loyalty through backward integration into magnetic particle surface chemistry production, eliminating German and Japanese single-source dependencies. Deepen companion diagnostic partnerships with oncology sequencing platform developers to lock in extraction protocol specifications. Capacity addition in low-cost chaotropic salt manufacturing regions defends margin position against Chinese supply disruption threats. For New Entrants and Emerging Players: Build out specialized low-input cell-free DNA extraction capabilities targeting South Korean and Singaporean liquid biopsy laboratories, where regulatory pathways remain less consolidated than United States or European markets. Veterinary point-of-care diagnostics in decentralized Indian and Brazilian infrastructure represents the most penetrable segment. Go-to-market positioning through ISO 13485-certified European contract manufacturing accelerates regulatory credibility without captive production investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors enzymatic lysis innovators with differentiated sample matrix capabilities over commodity silica membrane suppliers facing automation displacement. Long-term viability over the next decade hinges on CRISPR enrichment hybridization and multi-omics convergence readiness. Acquisition target archetype: specialty reagent houses with validated challenging-sample protocols and existing MFDS or CDSCO regulatory filings. Signal to watch: FDA guidance on liquid biopsy companion diagnostic extraction validation standards.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Unlocks diagnostic laboratory procurement eligibility under tightening EMA IVDR enforcement. |
| Magnetic Bead Surface Chemistry Acquisition | Captures German precision manufacturing capabilities to reduce single-source supply risk. |
| Lyophilized Format Development | Enables ambient-temperature distribution for tropical disease programs lacking cold chain infrastructure. |
| Companion Diagnostic Partnership | Locks in extraction protocol specifications with oncology sequencing platform developers. |
| Point-of-Care Microfluidic Integration | Penetrates decentralized testing infrastructure in Indian and Brazilian veterinary markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearances, EMA IVDR technical documentation, and ISO 13485 certification databases. Primary interviews engaged diagnostic laboratory directors, GPO contracts managers, regulatory affairs specialists at kit manufacturers, and biomedical engineers at academic medical centers. Secondary validation drew from EPA environmental monitoring guidelines, NMPA regulatory filings, and customs trade data on chaotropic salt imports. Bottom-up demand modeling across end-user segments triangulated against top-down market sizing from instrument installation bases.
Forecast inputs span product architecture turnover cycles, automation penetration curves in clinical versus research settings, and regulatory validation timeline compressions. Segmentation dimensions include extraction technology type, application workflow complexity, end-user purchasing authority structure, and regional regulatory framework clusters. CAGRs derive from installed base expansion rates and per-laboratory consumption intensity shifts across the projection horizon. Industry-specific inputs incorporate companion diagnostic pipeline progression and liquid biopsy clinical adoption trajectories.
Stress conditions across chaotropic salt supply disruptions, trade friction escalation in magnetic particle exports, and IVDR enforcement timeline accelerations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding automation adoption curves and regulatory harmonization progress. Material shifts in FDA guidance on extraction kit standalone classification or REACH chemical restriction expansions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
ELISA POT Assay Kits Market
Biotechnology Equipment
Global Life Sciences Tools Market
Biotechnology Equipment
Automated Colony Picking Systems Market
Biotechnology Equipment
Cryopreservation Freezer Market
Biotechnology Equipment
Cell Disruption Market
Biotechnology Equipment
Balanced Salt Solution for Cell Culture Market
Biotechnology Equipment
Global Bioprocess Analyzers Market
Biotechnology Equipment
Lab Automation in Bioanalysis Market
Biotechnology Equipment
Biochemistry Analyzers Market
Biotechnology Equipment
Airlift Bioreactors Market
Biotechnology Equipment
Fluidized-Bed Bioreactors Market
Biotechnology Equipment
Global Plant Cell Culture Equipment Market
Biotechnology Equipment
Automated Cell Culture Systems Market
Biotechnology Equipment
Latin America Protein Purification and Isolation Market
Biotechnology Equipment
Bioprocessing Systems Market
Biotechnology Equipment
Real-Time Bioprocess Raman Analyzer Market