
 Spain Gene Editing Market | 2026-2036
Spain Gene Editing Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Gene Editing Market Insights
Buyer concentration among Spanish pharmaceutical companies is consolidating as mid-sized firms merge R&D budgets to afford CRISPR infrastructure. Thermo Fisher Scientific leverages its distribution network to supply reagent kits across Iberian research hubs. Merck KGaA anchors its position through synthetic biology partnerships with Barcelona-based institutions. Horizon Discovery Group Plc competes by specializing in cell-line engineering services tailored to Spanish regulatory requirements.
Gene editing encompasses programmable nuclease systems that introduce site-specific DNA modifications, with CRISPR-Cas9 guiding RNA directing double-strand breaks at precise genomic loci for knockout or knock-in applications. CRISPR dominates product type revenue due to licensing accessibility and protocol standardization, while TALEN retains share in therapeutic contexts requiring higher specificity. Research applications absorb the largest end-user spend, though therapeutics is expanding fastest as AEMPS streamlines advanced therapy medicinal product pathways.
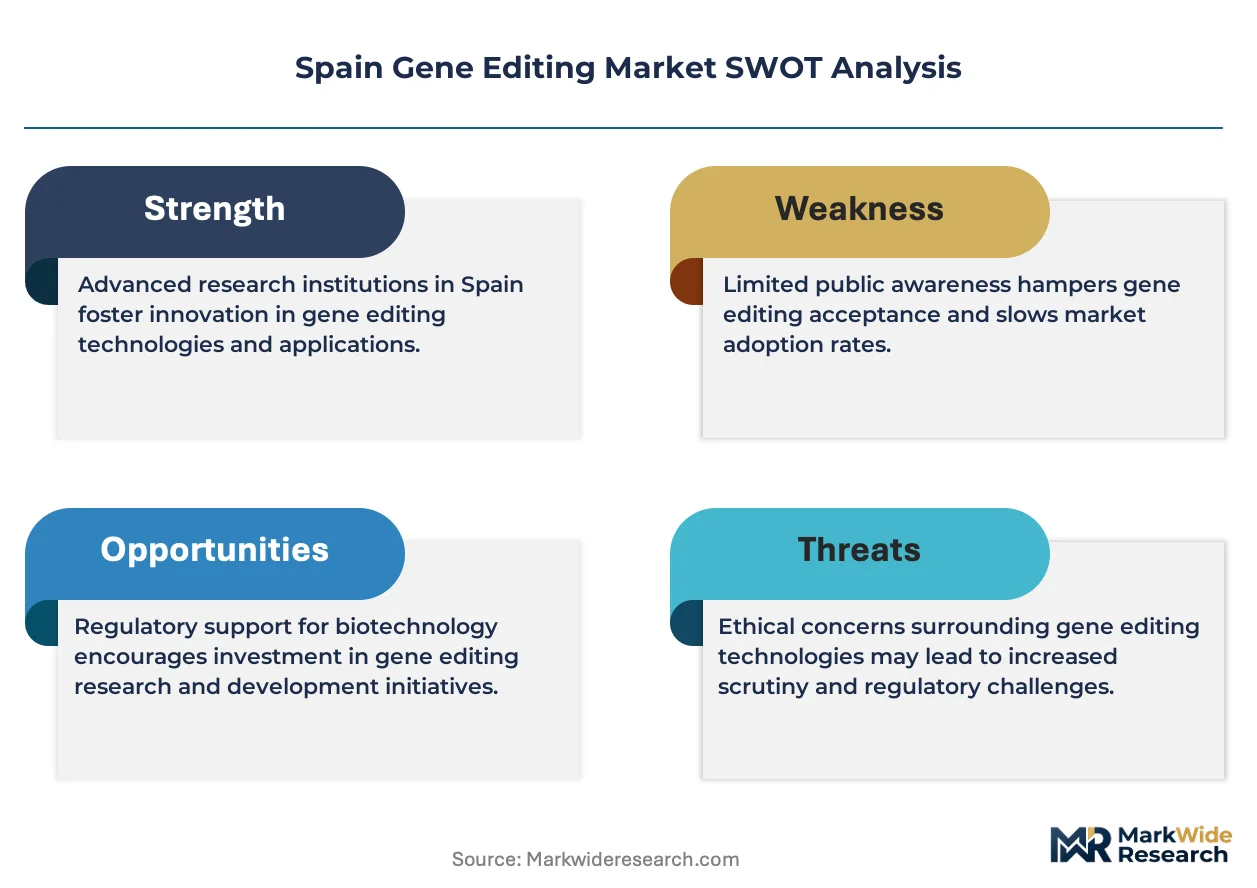
AEMPS and the Spanish National Institute of Health Carlos III coordinate gene therapy trial approvals, enforcing Good Clinical Practice standards that filter out under-resourced applicants. The European Medicines Agency's centralized marketing authorization for gene therapies creates a dual compliance layer that Spanish developers must navigate before commercialization. Stakeholders should monitor how AEMPS interprets the EU Clinical Trials Regulation for site-specific protocol amendments.
Market Dynamics
Spanish pharmaceutical consolidation is compressing buyer pools while AEMPS tightens gene therapy trial protocols, forcing CRISPR infrastructure investments toward fewer, better-capitalized research consortia in Barcelona and Madrid.
Growth Catalysts
- Advanced Therapy Medicinal Product pathways:AEMPS streamlining of ATMP approvals accelerates therapeutic CRISPR trials by reducing protocol amendment cycles for Spanish developers.
- Barcelona biomedical cluster concentration:Co-location of academic labs, CROs, and biotech startups generates knowledge spillovers that lower CRISPR protocol development costs.
- Base editing maturation:Cytosine and adenine base editors are expanding addressable disease targets beyond double-strand break limitations in hematologic applications.
Market Restraints
- Guide RNA synthesis cost volatility:Dependence on specialized oligonucleotide suppliers exposes Spanish labs to input price swings that strain mid-tier R&D budgets.
- Delivery vector manufacturing bottleneck:AAV and lentiviral vector production concentrates among three European CDMOs, creating queue delays for Spanish gene therapy sponsors.
- Off-target editing liability:Persistent technical limitations in predicting CRISPR-Cas9 off-target effects elevate clinical trial insurance premiums and regulatory scrutiny.
Strategic Opportunities
- Andalusian agricultural genomics:Olive and vineyard breeding programs in southern Spain remain underpenetrated for CRISPR-based trait editing despite EU exemption for certain plant applications.
- EU Green Deal biomanufacturing incentives:Horizon Europe funding streams for sustainable bioproduction create capital access for Spanish synthetic biology ventures integrating gene editing.
- Prime editing convergence with AI:Machine learning-guided pegRNA design is opening precision medicine applications previously unreachable with first-generation CRISPR systems.
Industry Challenges
- Bioinformatics specialist scarcity:Spanish universities produce insufficient computational biologists capable of guide RNA design and off-target prediction, forcing salary inflation for retained talent.
- GMP facility capex requirements:Cell and gene therapy manufacturing suites demand capital commitments that exceed mid-sized Spanish biotech balance sheet capacity without venture syndication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Gene Editing Market |
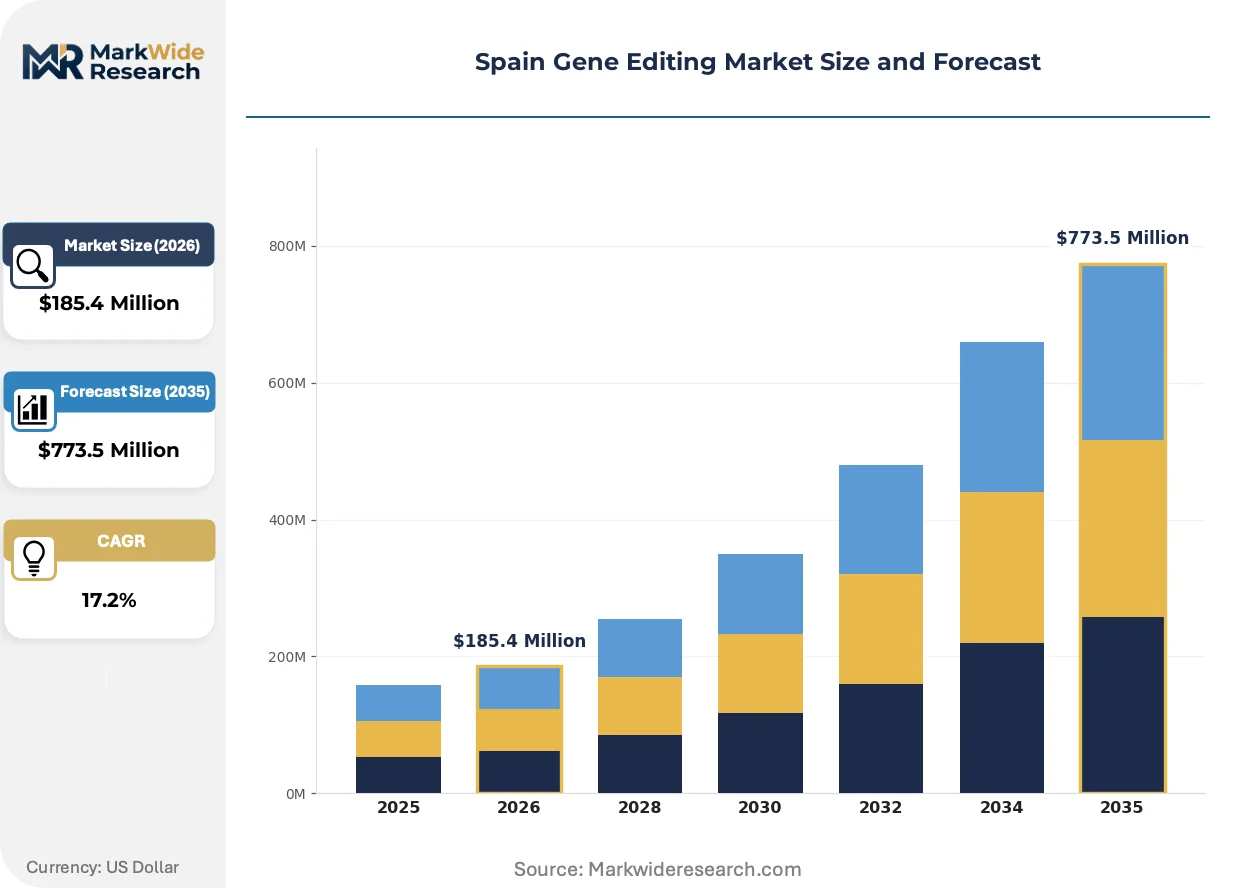
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $773.5 Million |
| CAGR (2026 – 2036) | 17.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CRISPR, ZFN, TALEN, Antisense Oligonucleotides Application: Research, Therapeutics, Agriculture, Industrial Biotechnology End User: Pharmaceutical Companies, Research Institutions, Biotechnology Firms, Academic Labs Technology: Gene Synthesis, Genome Editing, Recombinant DNA Technology, Gene Delivery |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Horizon Discovery Group Plc, Genscript Biotech Corporation, Cellectis S.A., CRISPR Therapeutics AG, Konexio Biotech, Lonza Group Ltd, New England Biolabs, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Gene Editing Market Trends and Innovations
Gene editing workflows in Spain are fragmenting into specialized service layers, with research institutions outsourcing vector production and analytical validation while retaining intellectual property control internally.
CRISPR-Cas12 and Cas13 systems are modularizing diagnostic and therapeutic applications beyond genome editing into nucleic acid detection and transcriptome modulation. Spanish infectious disease research programs are adopting these variants for point-of-care pathogen identification. The structural consequence is a compression of assay development timelines from months to weeks as modular CRISPR components integrate with standard qPCR infrastructure.
EMA centralized marketing authorization for gene therapies is creating dual compliance obligations that Spanish developers must satisfy before AEMPS will grant national trial site approval. This regulatory layering extends preclinical-to-clinic transition timelines. Therapeutic developers with Barcelona headquarters are responding by embedding regulatory affairs specialists earlier in discovery programs.
Spanish pharmaceutical procurement is consolidating reagent purchasing through preferred supplier agreements rather than project-by-project acquisition. Academic core facilities and mid-sized biotechs are ceding vendor selection authority to centralized purchasing committees. This concentration is most visible in Madrid's health research institutes, where Thermo Fisher and Merck KGaA have secured multi-year CRISPR kit supply contracts.
Spain Gene Editing Market Segmentation
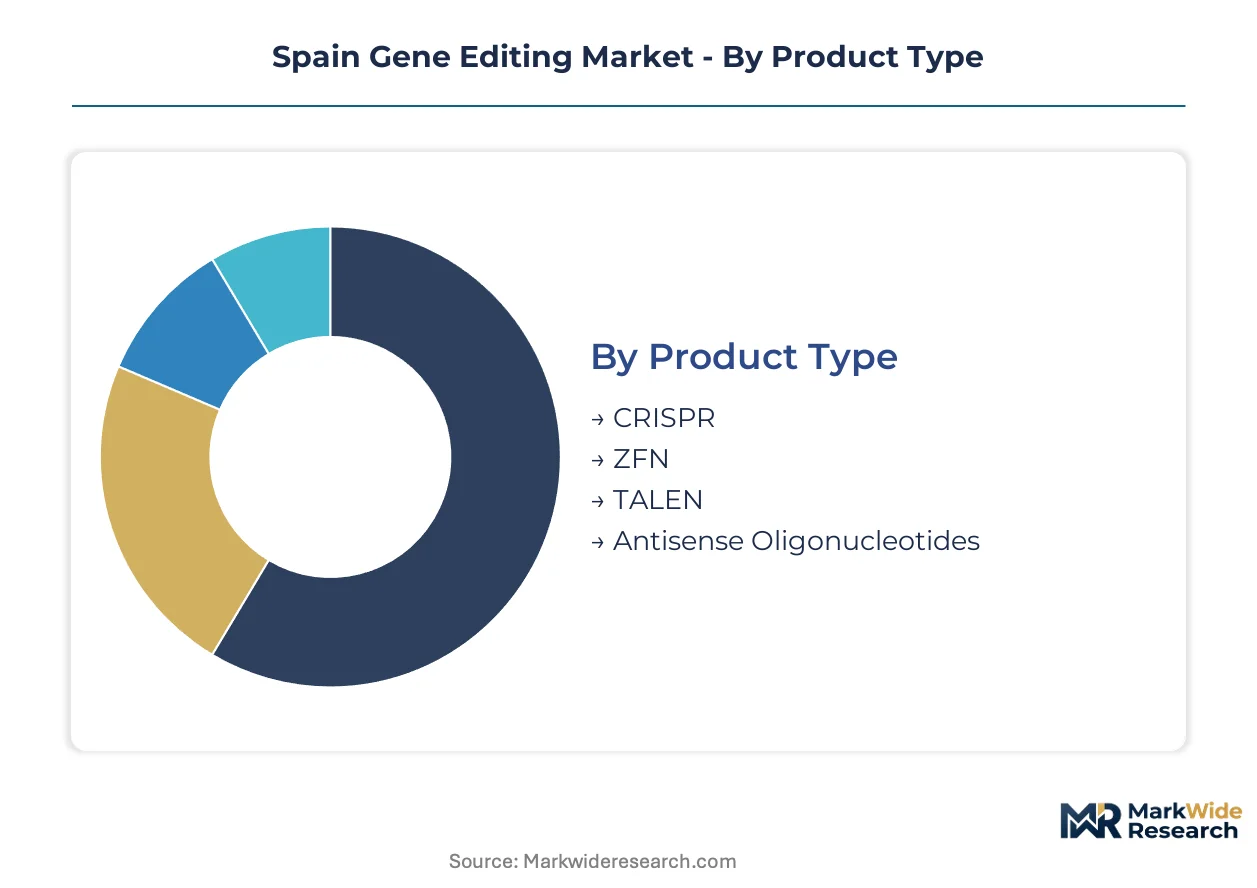
Gene editing market segmentation in Spain reflects divergent regulatory pathways and capital intensity requirements across therapeutic, agricultural, and industrial applications. AEMPS oversight tiers create distinct compliance burdens that reshape procurement patterns and vendor selection criteria for each segment category.
Product Type:
CRISPR and TALEN face divergent AEMPS classification pathways, with CRISPR-based therapeutics requiring advanced therapy medicinal product designation while TALEN applications often proceed under modified biologic frameworks.
- CRISPR:RNA-guided programmable nuclease systems enabling precise double-strand breaks with minimal design iteration. Spanish pharmaceutical companies concentrate demand in Barcelona and Madrid for hematologic and oncology targets, constrained by EMA centralized marketing authorization timelines. CRISPR sits at the top of the volume ranking, with base editing variants climbing the fastest.
- TALEN:Transcription activator-like effector nucleases offering reduced off-target profiles through protein-DNA recognition domains. Demand clusters among Madrid-based gene therapy developers pursuing regulatory pathways for monogenic disorders where specificity premiums justify higher synthesis costs.
- ZFN:Zinc finger nuclease platforms retain niche positioning in legacy agricultural trait programs and industrial strain engineering where established protocols reduce validation overhead.
- Antisense Oligonucleotides:Single-stranded nucleic acid therapeutics modulating gene expression through mRNA targeting, deployed across Spanish rare disease research networks with distinct CDMO sourcing requirements from nuclease-based systems.
CRISPR commands the largest procurement volumes, with antisense oligonucleotides gaining share fastest as AEMPS streamlines oligonucleotide therapeutic pathways.
Application:
Application segmentation tracks capital deployment patterns, with therapeutics demanding GMP facility investments that exceed mid-tier Spanish biotech balance sheet capacity.
- Research:Preclinical discovery workflows consuming reagent kits, synthetic guide RNA, and analytical validation services. Spanish academic core facilities and CROs in Barcelona's biomedical cluster drive procurement concentration, supported by Horizon Europe funding streams for fundamental genome biology.
- Therapeutics:Clinical-stage gene editing interventions requiring vector manufacturing partnerships and AEMPS trial site approvals. Spanish developers face queue delays at European CDMOs for AAV and lentiviral production, compressing program timelines.
- Agriculture:Crop trait editing for olive, vineyard, and cereal breeding programs in Andalusia and Castilla-La Mancha, operating under EU exemptions for certain plant applications that reduce regulatory friction.
- Industrial Biotechnology:Microbial strain engineering for enzyme production and sustainable biomanufacturing, aligned with EU Green Deal bioproduction incentives targeting Spanish synthetic biology ventures.
Research applications absorb the largest end-user spend, with therapeutics expanding most quickly as AEMPS advances ATMP pathway refinements.
End User:
End user concentration reflects R&D budget consolidation, with mid-sized Spanish pharmaceutical firms merging procurement functions to achieve CRISPR infrastructure scale.
- Pharmaceutical Companies:Integrated drug developers with internal gene therapy pipelines and regulatory affairs capabilities. Spanish mid-caps are consolidating through preferred supplier agreements with Thermo Fisher and Merck KGaA for multi-year reagent commitments.
- Research Institutions:National health research institutes and Carlos III network facilities with centralized purchasing committees. Madrid's health research institutes have ceded vendor selection authority to procurement committees, compressing supplier margins.
- Biotechnology Firms:Venture-backed startups co-located in Barcelona's biomedical cluster, outsourcing vector production and analytical validation while retaining IP control.
- Academic Labs:University core facilities with fragmented purchasing patterns and sensitivity to guide RNA synthesis cost volatility.
Pharmaceutical companies dominate procurement volumes, with biotechnology firms climbing fastest as Barcelona cluster density attracts venture syndication.
Technology:
Technology segmentation maps to supply chain specialization, with gene delivery manufacturing bottlenecks creating queue delays for Spanish sponsors.
- Gene Synthesis:De novo DNA construction services supporting guide RNA template production and donor template generation. Spanish labs depend on specialized oligonucleotide suppliers with volatile pricing structures.
- Genome Editing:Programmable nuclease platforms and base editing systems constituting the core therapeutic modality. Barcelona-based institutions drive protocol development through synthetic biology partnerships with Merck KGaA.
- Recombinant DNA Technology:Molecular cloning and vector construction workflows underlying plasmid production for viral packaging.
- Gene Delivery:Viral vector manufacturing and non-viral delivery system development, concentrated among three European CDMOs with queue delays extending Spanish trial initiation timelines.
Genome editing represents the largest technology category, with gene delivery gaining share fastest as AAV manufacturing capacity constraints ease.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish gene editing talent concentrates in Barcelona's biomedical corridor and Madrid's health research institutes, with AEMPS regulatory expertise anchoring southern Europe's clinical trial infrastructure.
Madrid
The capital hosts Carlos III network facilities and centralized purchasing committees that consolidate reagent procurement across national health institutes. AEMPS headquarters enforces Good Clinical Practice standards that filter gene therapy applicants. Madrid's health research institutes have ceded vendor selection authority to procurement committees, compressing supplier margins for CRISPR kit providers.
Catalonia
Barcelona's biomedical cluster generates knowledge spillovers between academic labs, CROs, and venture-backed biotech startups co-located in the city. The regional concentration attracts Horizon Europe funding streams for fundamental genome biology research. Synthetic biology partnerships with multinational reagent suppliers anchor protocol development capabilities in the metropolitan area.
Basque Country
Industrial biotechnology applications concentrate in northern Spain where microbial strain engineering serves enzyme production and sustainable biomanufacturing. EU Green Deal bioproduction incentives create capital access for regional synthetic biology ventures. San Sebastián and Bilbao host contract research organizations supporting vector production outsourcing from Barcelona-based therapeutic developers.
Andalusia
Agricultural genomics programs in southern Spain target olive and vineyard breeding applications under EU exemptions for certain plant applications. The region remains underpenetrated for CRISPR-based trait editing despite favorable regulatory treatment. Sevilla and Málaga research stations coordinate with Madrid-based regulatory affairs specialists for field trial approvals.
Valencia
The eastern coastal region supports marine biotechnology applications and alternative delivery vector research distinct from Barcelona's therapeutic focus. Regional universities produce bioinformatics specialists that Madrid and Barcelona employers recruit aggressively. Valencia's lower cost structure attracts satellite R&D facilities from multinational pharmaceutical companies.
Spain Gene Editing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the Spanish gene editing supply landscape. The market exhibits tiered concentration with multinational life science tools providers anchoring reagent supply and boutique cell-line engineering services occupying regulatory compliance niches. Three strategic archetypes dominate: scale-driven reagent manufacturers, synthetic biology platform licensors, and regulatory-specialized service providers. Competitive dynamics center on preferred supplier agreements locking in multi-year procurement commitments and synthetic biology partnerships embedding vendors within Barcelona research institutions.
Among diversified life science conglomerates, Thermo Fisher Scientific and Merck KGaA represent the scale-driven archetype through Iberian distribution networks and institutional partnership programs. Horizon Discovery Group Plc occupies a position exemplifying the regulatory-specialized service tier, with its cell-line engineering focus tailored to Spanish AEMPS requirements. These three companies anchor distinct competitive positions without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Horizon Discovery Group Plc |
| Genscript Biotech Corporation |
| Cellectis S.A. |
| CRISPR Therapeutics AG |
| Konexio Biotech |
| Lonza Group Ltd |
| New England Biolabs |
| Others |
Pricing and Supply Chain Analysis
Captive vector manufacturing partnerships in Barcelona and Madrid anchor supply positions for Spanish gene therapy developers while compressing reagent procurement margins through multi-year preferred supplier agreements. Thermo Fisher and Merck KGaA leverage synthetic biology partnerships to lock in pricing power across Iberian research hubs, forcing mid-tier biotechs into consolidated purchasing pools.
Pricing Analysis
Capacity additions in Germany and Switzerland are reshaping price floors for AAV and lentiviral vector manufacturing, though queue delays persist. Project-based pricing dominates therapeutic applications, with GMP-grade reagent tiers differentiating on AEMPS certification status and vector quality grade. Cost compression in research-grade CRISPR kits intensifies as Madrid health institutes centralize procurement, while pharmaceutical companies show lowest price sensitivity due to ATMP pathway timelines.
Supply Chain Analysis
Specialized bioinformatics talent scarcity in Spanish manufacturing geographies constrains guide RNA design capacity expansion. Supply concentrates in Germany, Switzerland, and the United States for viral vector production, with Spanish labs drawing from specialized oligonucleotide suppliers in these markets. Single-source vulnerability runs through European CDMO queues for AAV manufacturing. Distribution runs through Thermo Fisher's Iberian logistics network and Merck KGaA's institutional partnership channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Spanish gene editing hinges on base editing maturation reducing validation cycle costs and AEMPS streamlining ATMP pathways that compress time-to-revenue for therapeutic developers.
For Market Incumbents: Cement preferred supplier status through multi-year CRISPR kit contracts with Madrid's centralized purchasing committees. Deepen synthetic biology partnerships with Barcelona academic institutions to anchor protocol development capabilities. Defend against emerging CDMO competition by securing captive AAV manufacturing slots at European facilities before queue delays worsen. For New Entrants and Emerging Players: EU Green Deal bioproduction incentives in Spain open a window for synthetic biology ventures targeting Andalusian agricultural genomics. Target olive and vineyard breeding programs where CRISPR trait editing remains underpenetrated despite regulatory exemptions. Pursue service-based entry through cell-line engineering partnerships with Barcelona biotech startups lacking internal GMP capabilities. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-sized Spanish pharmaceutical firms lack balance sheet capacity for GMP facility capex without venture syndication. Five-to-ten year viability favors regulatory-specialized service providers with AEMPS compliance track records. Watch for inflection when AEMPS publishes site-specific protocol amendment guidance under EU Clinical Trials Regulation.| Strategic Initiative | Industry Significance |
|---|---|
| ATMP Pathway Navigation | AEMPS streamlined approvals accelerate therapeutic CRISPR trials by reducing amendment cycles. |
| Base Editing Platform Licensing | Cytosine and adenine base editors expand addressable disease targets beyond double-strand break limitations. |
| CDMO Queue Securement | Early AAV manufacturing slot reservations prevent trial initiation delays at European viral vector facilities. |
| Bioinformatics Talent Acquisition | Computational biologist recruitment from Valencia universities offsets Spanish specialist scarcity. |
| Agricultural Genomics Partnership | Andalusian olive breeding programs offer CRISPR entry under favorable EU plant application exemptions. |
Research Methodology
Direct dialogue with gene therapy development executives, regulatory affairs specialists at AEMPS, Barcelona CRO operations directors, and Madrid health institute procurement managers grounded the qualitative foundation. Secondary validation drew from EMA centralized marketing authorization filings, AEMPS clinical trial registry data, Horizon Europe funding disclosures, and Spanish pharmaceutical consolidation announcements. Bottom-up reagent demand estimates triangulated against top-down therapeutic pipeline valuations.
Top-down market sizing segmented by product type, application, end user, and technology across the analysis window, with CAGRs derived from therapeutic pipeline progression rates and research funding trajectories. Modeled dimensions included hematologic versus oncology target categories, GMP versus research-grade quality tiers, and Barcelona-Madrid versus secondary regional demand clusters. Forecast inputs incorporated AEMPS ATMP pathway refinement timelines and EU Green Deal biomanufacturing incentive disbursement schedules.
Revisions become necessary when AEMPS issues contradictory protocol amendment guidance, EMA centralized authorization timelines extend unexpectedly, or CDMO queue delays exceed modeled assumptions. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
CAS9 Technology Market
Gene Editing & CRISPR
Genetic Engineering Market
Gene Editing & CRISPR
Klinefelter Syndrome Therapeutics Market
Gene Editing & CRISPR
Global CRISPR and Cas Genes Market
Gene Editing & CRISPR
Gene Editing Off-Target Effect Detection Test Systems Market
Gene Editing & CRISPR
Genome Engineering Market
Gene Editing & CRISPR
Gene Editing Market
Gene Editing & CRISPR
North America Gene Synthesis Market
Gene Editing & CRISPR
UK Gene Editing Market
Gene Editing & CRISPR
Knock Out Mouse Model Market
Gene Editing & CRISPR
Gene Editing Tools Market
Gene Editing & CRISPR
Rare NGR1 Fusion Market
Gene Editing & CRISPR
Global Recombinant DNA (Rdna) Technology Market
Gene Editing & CRISPR
Base Editing Market
Gene Editing & CRISPR
France Gene Editing Market
Gene Editing & CRISPR
Global Plant Breeding and CRISPR Plant Market